
 Functional Polymer Market | 2026-2036
Functional Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Polymer Market Intelligence
Chinese production capacity expansion in specialty copolymers is tilting the competitive landscape toward regional self-sufficiency. BASF SE leverages its extensive R&D infrastructure to develop novel biodegradable polymers. Evonik Industries AG specializes in high-performance polymers for niche applications like medical devices and coatings. DuPont de Nemours, Inc. anchors its market position through a broad portfolio of thermoplastic elastomers.
Functional polymers are macromolecules engineered with specific reactive groups along their backbone or as pendant groups. This deliberate chemical modification imparts unique thermal, electrical, optical, or biological properties not found in conventional commodity plastics. Within polymer types, conductive polymers and biodegradable polymers represent the fastest-growing categories, driven by electronics and packaging end-use sectors, respectively. Emulsion polymerization remains a dominant technology for producing polymers used in coatings and adhesives due to its process control and environmental advantages.
Regulatory frameworks such as the European Union's REACH and the US EPA's Toxic Substances Control Act (TSCA) govern chemical safety and market access. Concurrently, standards from the International Organization for Standardization (ISO) on biodegradability, like ISO 14855, influence product design and material selection. Navigating the evolving definitions of sustainability and circularity across these diverse regulatory regimes is the central strategic challenge for manufacturers.
Market Dynamics
The functional polymer market is defined by the dual pressure for higher-performance materials from sectors like electronics and stringent sustainability mandates, such as China's dual carbon goals. This conflict drives innovation in conductivity, mechanical properties, and end-of-life circularity.
Growth Catalysts
- Electronics Sector Demand:The need for advanced conductive polymers in flexible displays and wearable technology creates a strong pull for materials with specific electrical properties.
- Sustainability Policies:Frameworks like the EU Green Deal accelerate R&D and adoption of biodegradable polymers, particularly in single-use packaging applications.
- Process Technology:Emulsion polymerization offers superior control, enabling production of sophisticated water-based polymers for high-value coatings and adhesives.
Market Restraints
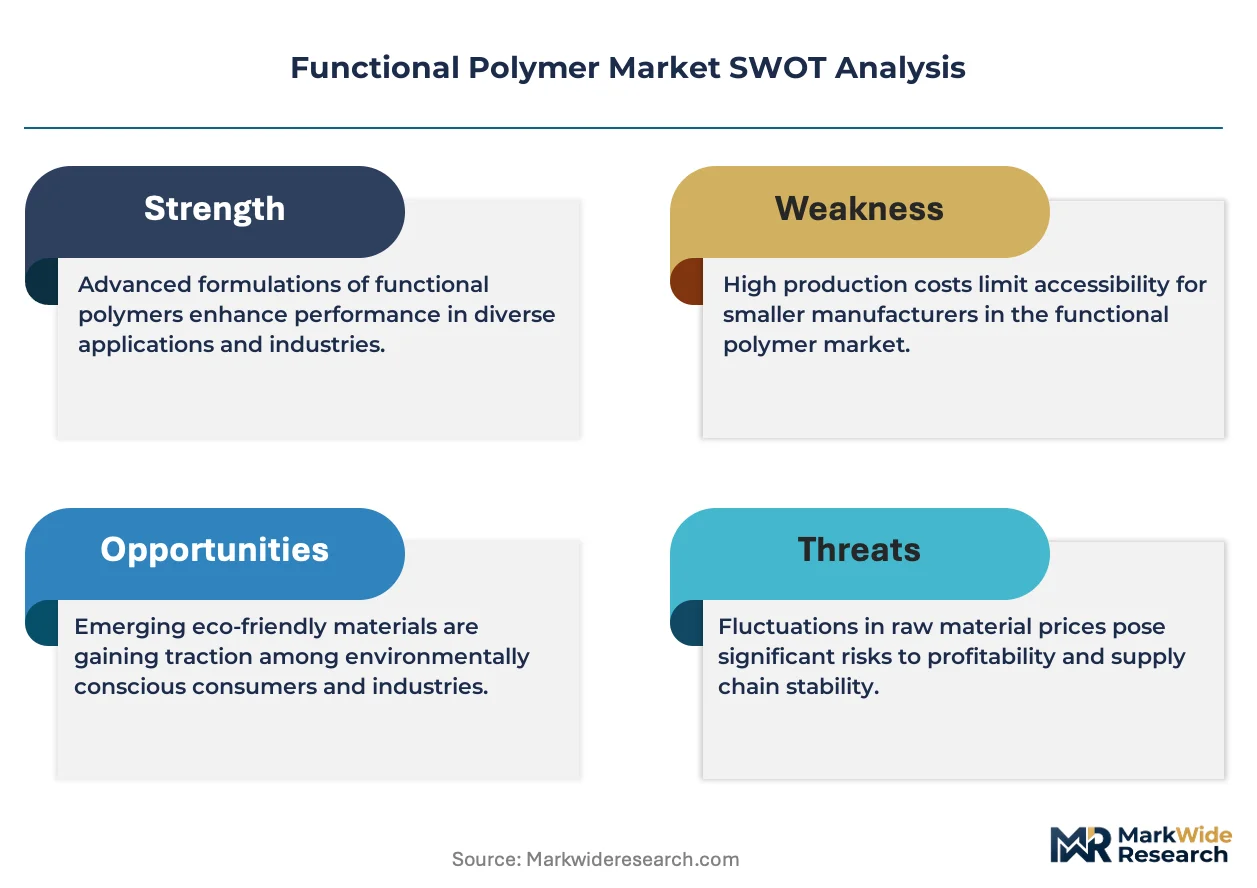
- Feedstock Volatility:Price fluctuations in petrochemical feedstocks, the primary raw material for many polymers, directly impact production costs and compress margins.
- Performance Trade-offs:Biodegradable polymers often exhibit lower mechanical strength or thermal stability, limiting use in demanding engineering applications.
- Regulatory Fragmentation:Divergent chemical safety regulations like the EU's REACH and the US TSCA create complex compliance pathways and increase time-to-market.
Strategic Opportunities
- Medical Device Polymers:High-performance, biocompatible polymers for drug-eluting stents, medical implants, and advanced wound care systems present a significant value opportunity.
- Self-Healing Materials:Formulating polymers with self-repair capabilities can extend the service life of components in high-stress sectors like aerospace and automotive.
- Bio-based Monomers:Using bio-based feedstocks to produce monomers for specialty copolymers opens pathways for creating sustainable materials that meet performance goals.
Industry Challenges
- Certification Complexity:Navigating lengthy and costly certification processes for biodegradability under standards like ISO 14855 delays product launches and market entry for new sustainable materials.
- Capital Investment:The construction of new specialty copolymer production facilities requires significant capital expenditure to achieve the scale and technological capability needed for regional self-sufficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Polymer Market |
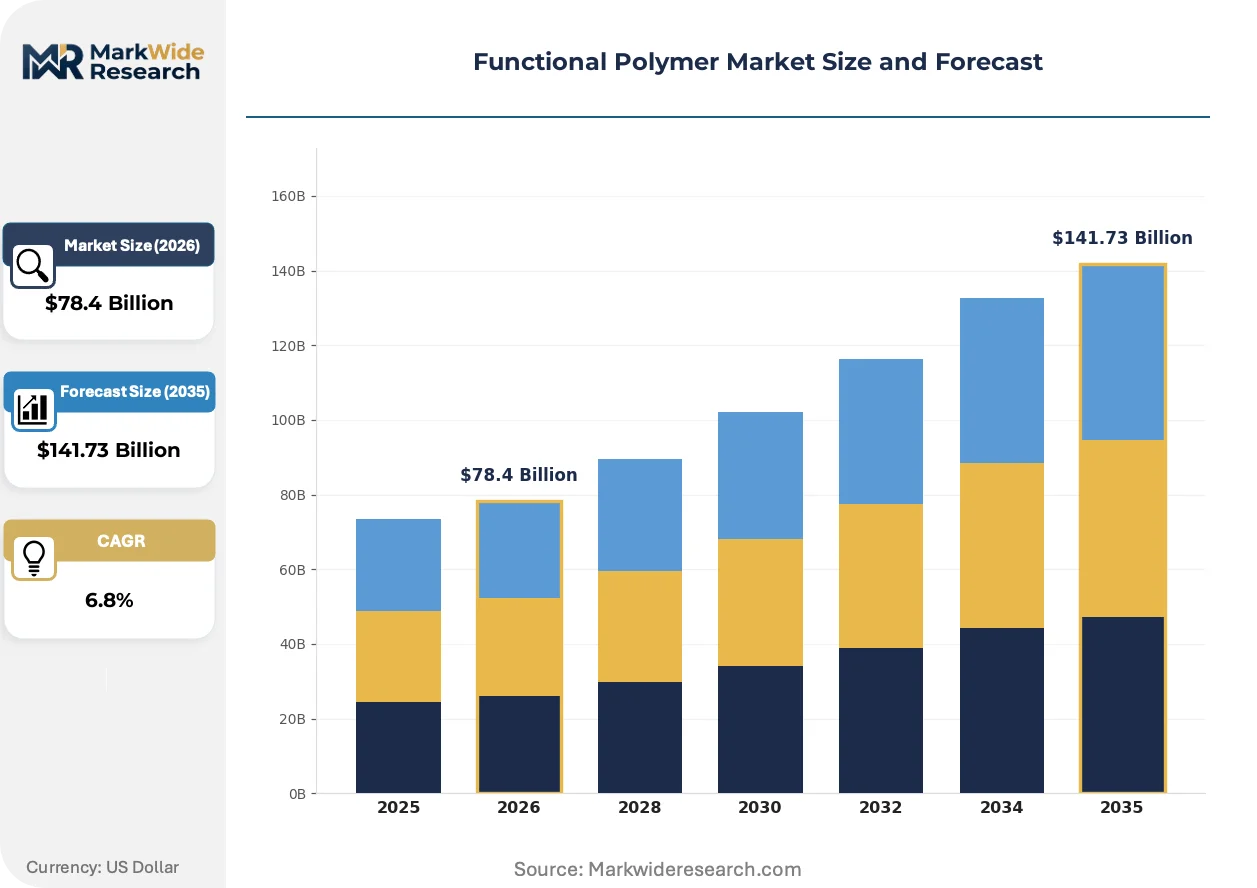
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Polymer Type: Conductive Polymers, Biodegradable Polymers, Specialty Copolymers, Thermoplastic Elastomers, Photoresponsive Polymers End Use Industry: Electronics Manufacturing, Packaging Solutions, Textile Fabrication, Agriculture Supplies, Water Treatment Technology: Emulsion Polymerization, Suspension Polymerization, Bulk Polymerization, Solution Polymerization, Plasma Polymerization Application: Adhesives, Coatings, Sensors, Drug Delivery, Lubricants, Sealants |
| Companies Covered | BASF SE, Evonik Industries AG, DuPont de Nemours, Inc., Covestro AG, SABIC, Solvay S.A., ADEKA Corporation, Tosoh Corporation, Nippon Shokubai Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Polymer Market Strategic Shifts & Innovations
Material science's convergence with computational modeling is accelerating the development of application-specific functional polymers. This allows for faster design-test cycles, enabling formulators to meet precise performance criteria driven by sustainability and miniaturization demands.
Smart polymers, which respond to external stimuli like temperature or pH, are gaining traction. The biomedical sector is a primary adopter for targeted drug delivery and tissue engineering scaffolds. This technology is hybridizing material science with active sensing, creating components that can both provide structure and dynamically react to their environment.
The European Union's Green Deal framework is forcing a systemic reevaluation of polymer lifecycles. It sets ambitious targets for recycled content and recyclability, directly impacting material design. The packaging industry is most affected, investing heavily in monomaterial solutions and chemical recycling to comply with these emerging circular economy mandates.
Specification based on life-cycle assessment (LCA) data is becoming a key procurement criterion, moving beyond just cost and performance. This shift disrupts traditional sales cycles based on technical data sheets, favoring suppliers who provide transparent environmental product declarations. This trend is most visible in Europe's construction and automotive industries, driven by corporate reporting mandates like the CSRD.
Functional Polymer Market Segmentation
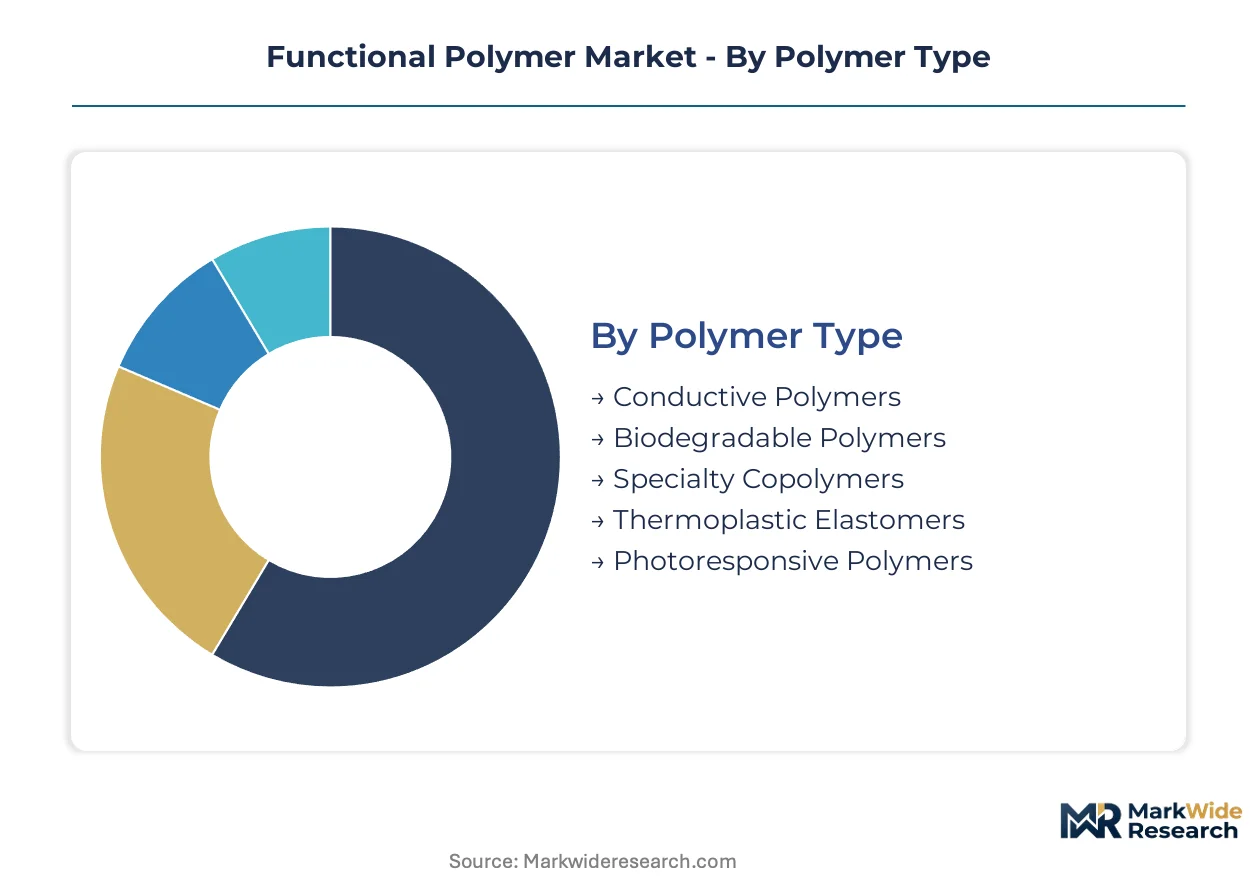
Understanding the functional polymer market through detailed segmentation reveals distinct growth trajectories and competitive dynamics across various material types and end-use sectors. Manufacturers strategically align their product portfolios to address the specific performance requirements and regulatory pressures within each segment. This granular view highlights areas of innovation and established demand.
Polymer Type:
The functional polymer market exhibits a varied maturity spectrum, with some polymer types well-established while others are emerging for specialized uses.
- Conductive Polymers:These macromolecules feature delocalized electrons, enabling electrical conductivity along their backbone. Demand from electronics manufacturing is concentrating on these materials for flexible displays and advanced sensors.
- Biodegradable Polymers:Engineered to decompose naturally through microbial action, these polymers address environmental concerns. Packaging solutions, particularly single-use applications, drive significant adoption due to sustainability policies.
- Specialty Copolymers:These polymers combine two or more different monomers, yielding tailored properties for specific industrial requirements.
- Thermoplastic Elastomers:Materials that possess both thermoplastic and elastomeric properties offer flexibility and processability for various products.
- Photoresponsive Polymers:These polymers undergo reversible changes in their structure or properties when exposed to light stimuli.
Conductive Polymers retains volume leadership; Biodegradable Polymers holds the steepest expansion curve.
End Use Industry:
End-use industries dictate the performance specifications and volume requirements for functional polymers.
- Electronics Manufacturing:This sector requires polymers with precise electrical, thermal, and mechanical properties for components like advanced conductive films and encapsulants. The need for flexible displays and wearable technology creates strong pull for these materials.
- Packaging Solutions:The packaging industry demands polymers offering barrier properties, mechanical strength, and increasingly, biodegradability for various containers and films. Sustainability policies like the EU Green Deal accelerate adoption of new biodegradable alternatives.
- Textile Fabrication:Functional polymers impart enhanced durability, water repellency, or flame resistance to specialized fabrics.
- Agriculture Supplies:Polymers are used in controlled-release fertilizers, mulching films, and protective coatings for seeds.
- Water Treatment:This industry utilizes polymers as flocculants, coagulants, and membrane materials for purification processes.
Electronics Manufacturing drives innovation in high-performance materials, while Packaging Solutions represents a significant volume opportunity.
Technology:
Polymerization technologies define the production scalability, cost-efficiency, and material properties achievable for functional polymers.
- Emulsion Polymerization:This technique involves polymerizing monomers in an aqueous medium stabilized by surfactants, producing high molecular weight polymers with controlled particle size. It remains a dominant technology for producing polymers used in coatings and adhesives due to its process control advantages.
- Suspension Polymerization:Monomers are dispersed as droplets in a non-solvent, forming polymer beads or pearls with good heat transfer characteristics. This method is favored for producing PVC and ion-exchange resins.
- Bulk Polymerization:Monomers are polymerized directly without solvent or diluent, offering high purity products but challenges in heat dissipation.
- Solution Polymerization:Monomers are dissolved in a solvent during polymerization, which aids in heat removal and viscosity control.
- Plasma Polymerization:This advanced technique uses a plasma environment to deposit thin polymer films with unique surface properties.
Emulsion Polymerization maintains its central role in water-based systems, while Plasma Polymerization offers specialized surface modification capabilities.
Application:
Diverse applications leverage the specific reactive groups and tailored properties of functional polymers to enhance product performance.
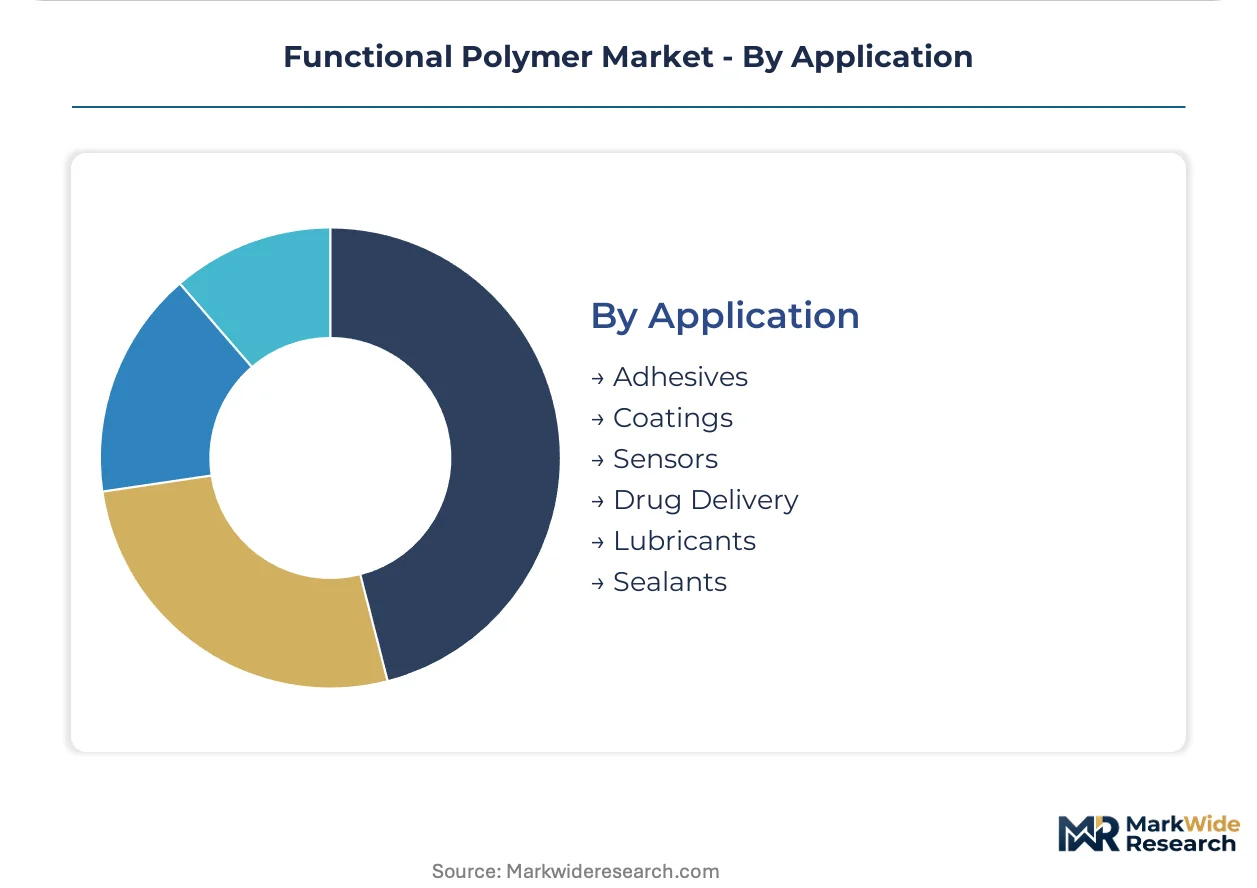
- Adhesives:Functional polymers provide superior bonding strength, flexibility, and environmental resistance in various adhesive formulations. Their use is critical in construction, automotive, and electronics assembly for durable connections.
- Coatings:Polymers in coatings offer protective barriers, aesthetic appeal, and specialized functionalities like anti-corrosion or self-cleaning properties. Emulsion polymerization enables sophisticated water-based coatings for high-value surfaces.
- Sensors:Functional polymers act as active elements in sensors, responding to chemical, physical, or biological stimuli.
- Drug Delivery:Biocompatible polymers enable controlled release mechanisms for pharmaceuticals and targeted therapeutic agents.
- Lubricants:Polymers enhance viscosity, reduce friction, and improve thermal stability in advanced lubricant formulations.
- Sealants:Functional polymers provide elastic, durable seals against moisture, chemicals, and environmental factors in construction and automotive.
Adhesives and Coatings drive substantial volume requirements, while Sensors and Drug Delivery lead innovation in functional specificity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global functional polymer market demonstrates distinct consumption-mix differentials across major economies, with some regions prioritizing high-performance electronics materials while others focus on sustainable packaging solutions. China’s dual carbon goals necessitate a strong emphasis on advanced polymer solutions across multiple industries, driving significant domestic demand. European Union policies like the Green Deal accelerate the adoption of biodegradable alternatives, particularly in consumer-facing sectors.
China
Electronics manufacturing and automotive sectors drive demand for specialty copolymers and conductive polymers in China. The national dual carbon goals under the Ministry of Ecology and Environment (MEE) accelerate the development of advanced polymer solutions. Production capacity expansion in the Yangtze River Delta region supports regional self-sufficiency for various functional polymer types.
United States
The United States market emphasizes high-performance polymers for aerospace, medical devices, and advanced electronics applications. The US Environmental Protection Agency's (EPA) Toxic Substances Control Act (TSCA) governs chemical safety and market access for new polymer formulations. Silicon Valley and research hubs in Massachusetts concentrate on novel material development, particularly for smart polymers and bio-based monomers.
Germany
Germany leads in the development and application of functional polymers for high-value industrial coatings and engineering plastics. The European Union's REACH regulation dictates strict compliance for chemical substances, influencing polymer design and manufacturing processes. Major chemical companies like BASF SE and Evonik Industries AG, headquartered in the Rhine-Main region, leverage extensive R&D for novel biodegradable polymers.
Japan
Advanced electronics, automotive components, and specialized packaging drive demand for functional polymers in Japan. The Ministry of Economy, Trade and Industry (METI) supports initiatives for material innovation and circular economy principles. Industrial clusters around Tokyo and Osaka focus on developing photoresponsive polymers and high-durability thermoplastic elastomers for niche applications.
India
Demand in India focuses on packaging solutions and agricultural supplies, with an emerging interest in sustainable and biodegradable polymers. The Bureau of Indian Standards (BIS) sets quality and environmental performance benchmarks for polymer products. Manufacturing hubs in Gujarat and Maharashtra are increasing production capacity for specialty copolymers to meet domestic industrial requirements.
Functional Polymer Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a dynamic competitive environment in the functional polymer market. Large integrated chemical producers leverage extensive R&D infrastructure and diversified portfolios. Specialist material science companies focus on high-performance niche applications. Strategic partnerships and capacity expansion are dominant competitive moves among these players.
On the premium-tier vector, BASF SE represents a global leader, anchoring its position through extensive research and development in novel biodegradable polymers. Evonik Industries AG exemplifies specialization, focusing on high-performance polymers for niche applications such as medical devices and coatings. DuPont de Nemours, Inc. sits within the diversified materials segment, maintaining its market position through a broad portfolio of thermoplastic elastomers and specialty copolymers.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| DuPont de Nemours, Inc. |
| Covestro AG |
| SABIC |
| Solvay S.A. |
| ADEKA Corporation |
| Tosoh Corporation |
| Nippon Shokubai Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Suez Canal shipping lanes, a critical global logistics corridor, influence functional polymer cost dynamics, linking supply concentration from East Asia to downstream price differentiation in Europe and North America.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing for bulk functional polymers, while specialty grades often trade on a spot market basis. Price differentiation stems from performance certification, such as ISO 14855 for biodegradability, and the level of customization required for specific end-use applications. Pricing softness reflects intense competition in commodity polymer grades, though high-performance conductive polymers command a premium. Electronics manufacturers exhibit lower price sensitivity for mission-critical materials, while packaging solution providers are highly sensitive to cost variations in high-volume biodegradable polymers.
Supply Chain Analysis
Major chemical producers like BASF SE and Evonik Industries AG hold significant contract manufacturing capacity for specialty polymers, particularly in Germany. Geographic supply concentration for functional polymers centers on China, Germany, and the United States. The industry relies heavily on petrochemical feedstocks, such as ethylene and propylene, alongside a growing reliance on bio-based monomers. Commodity price volatility for these petrochemicals presents a significant structural risk. Distribution runs through direct sales channels for large industrial clients, supplemented by specialized distributors serving niche application segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The functional polymer market represents a high-growth disruption, fundamentally reshaped by the EU Green Deal's sustainability mandates and the rapid advancements in flexible electronics.
For Market Incumbents: Entrench core market positions by diversifying feedstock sources, mitigating dependency on volatile petrochemicals. Invest in advanced process technologies like emulsion polymerization to enhance product quality and control. Counter the threat from emerging biodegradable alternatives through targeted R&D in high-performance bio-based polymers. Pursue strategic partnerships to expand capacity in specialty copolymers, particularly in regions like the Yangtze River Delta, supporting self-sufficiency goals.
For New Entrants and Emerging Players: Bio-based polymer formulations for sustainable packaging represent a penetrable entry point, especially for small-to-medium enterprises seeking eco-friendly solutions. Target niche applications in medical devices requiring biocompatible polymers with specific functionalities. Focus on rapid certification pathways for new biodegradable materials under standards like ISO 14855. A go-to-market angle emphasizing transparent life-cycle assessment data can attract procurement-conscious buyers.
For Investors and Strategic Acquirers: Niche technology developers specializing in advanced bio-based monomers or smart polymers present attractive acquisition targets. The functional polymer market offers strong long-term viability, driven by its essential role in electronics innovation and the global shift towards sustainability. A signal to watch for inflection is the commercialization of cost-effective chemical recycling technologies for mixed polymer waste streams.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion: Specialty Copolymers | Enhances regional self-sufficiency and meets demand from diverse industrial sectors. |
| Green Manufacturing Transition: Bio-based Feedstock Integration | Reduces reliance on petrochemicals and aligns with global sustainability objectives. |
| Joint Venture: Advanced Conductive Polymers | Accelerates innovation for flexible displays and next-generation electronic components. |
| Long-term Supply Agreement: Sustainable Packaging Materials | Secures market share in a high-volume segment driven by environmental mandates. |
| R&D Investment: Self-Healing Polymer Formulations | Extends product lifespan and reduces maintenance in high-stress engineering applications. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary data from reputable market intelligence sources anchors the qualitative findings. This study engaged polymer scientists, procurement managers from electronics and packaging firms, regulatory affairs specialists, and end-use product developers. Secondary sources included chemical industry reports, patent databases, academic journals, and government environmental policy documents, ensuring a comprehensive data foundation for bottom-up and top-down triangulation.
Calibrating historical data trends with future technological adoption curves forms the core of the analytical framework across the analysis window. The model integrates segmentation across polymer type, end-use industry, technology, application, and regional regulatory landscape. Compound annual growth rates were derived from a blend of historical market trends and projected innovation rates. Key forecast inputs included raw material price forecasts and electronics sector growth projections.
Macroeconomic conditions sit as an overlay; deviation in global economic growth or geopolitical stability would shift the trajectory of the market. Forecasts reflect assumptions documented through extensive research. Unforeseen regulatory shifts or rapid technological obsolescence in key end-use sectors could revise projections. Cross-checking against external market indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Phthalimide Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Serine Market
Functional Chemicals
Global Adiponitrile Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
Glutamine Market
Functional Chemicals
Tartrazine Market
Functional Chemicals
Thymolphthalein Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
Carbomer Market
Functional Chemicals
Global Peptide Synthesis Market
Functional Chemicals
Isophthaloyl Chloride Market
Functional Chemicals
Europe Formic Acid Market
Functional Chemicals
Global L-Arginine Market