
 Global Tert-Amylbenzene Market | 2026-2036
Global Tert-Amylbenzene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tert-Amylbenzene Market Intelligence
Continuous flow reactor technology is reconfiguring how tert-amylbenzene derivatives are synthesized at scale. Solvay S.A. leverages its European fluorochemical infrastructure to sustain captive precursor supply for high-purity grades. Vinati Organics anchors South Asian demand through specialized aromatic production at its Maharashtra facilities. ExxonMobil Corporation competes on feedstock integration, drawing C5 streams from its Baton Rouge refinery complex.
Tert-amylbenzene is a branched alkylbenzene with the formula C11H16, typically produced via Friedel-Crafts alkylation of benzene with amylene isomers and used primarily as a specialty solvent and chemical intermediate in pharmaceutical and agrochemical synthesis. Purified grades command premium positioning due to stringent residual olefin specifications required for active ingredient manufacturing, while technical grades serve broader solvent applications where color stability matters less than cost. The chemical intermediates application segment leads volume absorption as downstream producers seek controlled boiling-point solvents for Grignard and organolithium reactions.
EPA NESHAP standards and REACH Annex XVII restrictions on volatile aromatic content are forcing reformulation of coating systems that historically relied on uncontrolled solvent blends. China's MEE emission permits and India's CEA hazardous chemical handling rules add compliance layers for import-dependent formulators. Stakeholders must monitor how dual carbon targets in Beijing and Brussels redirect petrochemical feedstock allocations toward lower-aromatic alternative chemistries.
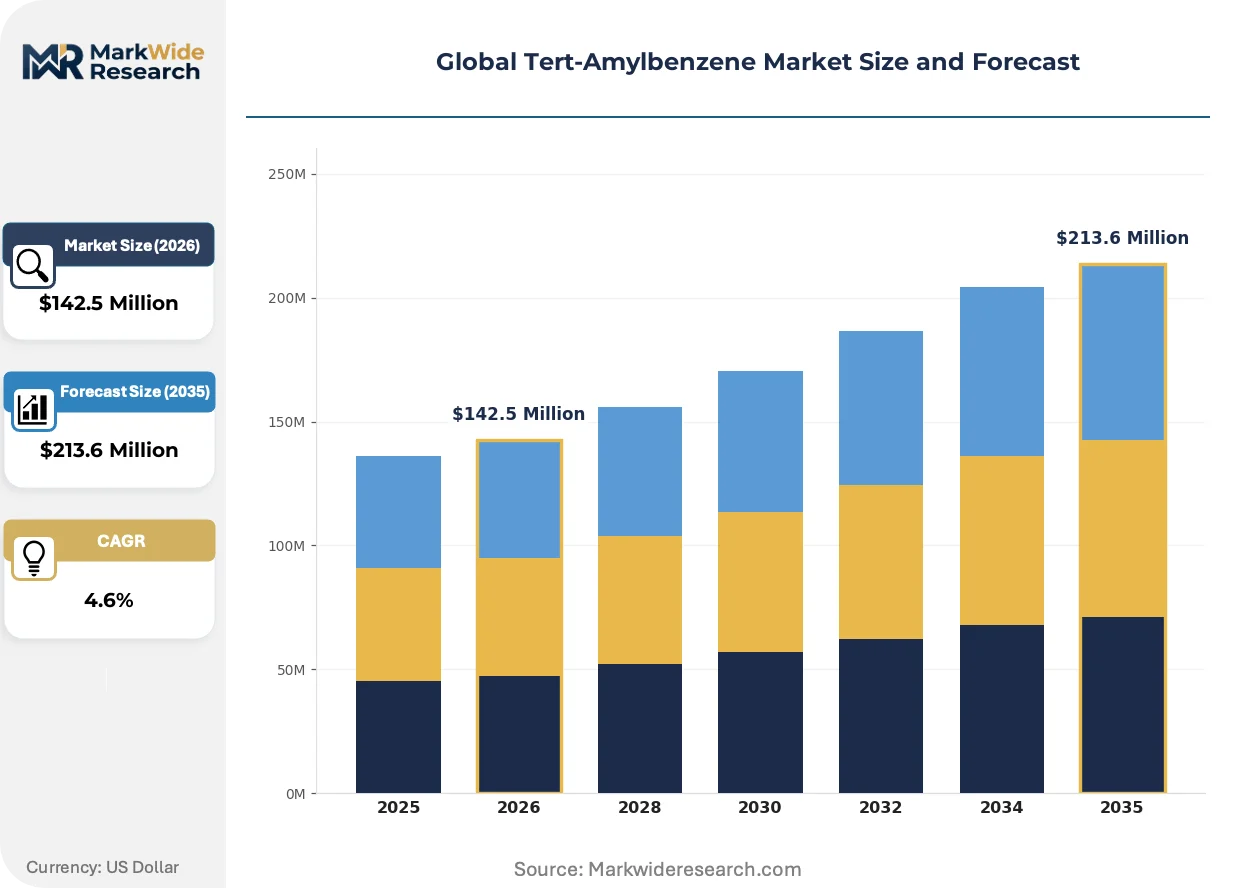
Market Dynamics
Continuous flow reactor technology is compressing batch-cycle times for tert-amylbenzene derivatives while REACH Annex XVII and EPA NESHAP standards tighten residual olefin specifications, forcing capital retooling across European and North American production assets.
Growth Catalysts
- Agrochemical synthesis demand:Specialty chemical manufacturers in India and China are expanding technical-grade purchases for pyrethroid and herbicide intermediate production.
- REACH compliance premium:Purified grades with sub-50 ppm residual olefin content command positioning in pharmaceutical solvent applications.
- Shanghai-Gujarat corridor concentration:East Asian manufacturing clusters are absorbing volume through integrated aromatic supply chains.
Market Restraints
- Amylene feedstock volatility:C5 stream availability fluctuates with refinery operating rates, compressing margin stability for non-integrated producers.
- Supplier concentration risk:Captive supply from integrated petrochemical complexes limits third-party market access.
- Bio-based solvent substitution:Terpene-derived alternatives are displacing technical-grade material in coating applications.
Strategic Opportunities
- Grignard reaction solvents:Organolithium chemistry expansion in contract manufacturing creates specification-grade demand.
- India PLI scheme alignment:Domestic aromatic intermediate production incentives support import substitution for agrochemical formulators.
- EPA solvent emission rules:Reformulation mandates for coating systems open technical-grade volume in compliant blend formulations.
Industry Challenges
- Flow chemistry engineering talent:Shortage of process intensification specialists delays continuous reactor commissioning timelines.
- Dual certification burden:Simultaneous REACH registration and EPA PMN filing extends product qualification cycles.
- Legacy batch asset stranding:Depreciated stainless-steel reactor networks face write-down pressure against modular replacement economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tert-Amylbenzene Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $213.6 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isomer A, Isomer B, Purified Grade, Technical Grade Application: Solvent Industry, Chemical Intermediates, Specialty Chemicals, Additive Manufacturing End User Industry: Pharmaceutical Manufacturers, Agrochemical Producers, Paints & Coatings, Consumer Goods OEMs Packaging Type: Drums, Bulk Containers, Intermediate Bulk Containers, Flexible Packaging |
| Companies Covered | TCI Chemicals, Alfa Aesar (Thermo Fisher Scientific), Solvay S.A., ExxonMobil Corporation, Frontier Scientific Inc., Vinati Organics, Sigma-Aldrich (Merck KGaA), Eastman Chemical Company, Jiujiang Pro High Technology Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tert-Amylbenzene Market Strategic Shifts & Innovations
Process intensification and regulatory chemistry are restructuring how tert-amylbenzene grades are specified, produced, and qualified across pharmaceutical and agrochemical value chains.
Microchannel reactor architecture is enabling precise temperature control for Friedel-Crafts alkylation with reduced catalyst loading. Pharmaceutical contract manufacturers in Switzerland and Germany are adopting these systems for GMP-grade production. Conventional stirred-tank batch processing is rendering obsolete for high-purity applications where residual olefin specifications must hold below 20 ppm.
REACH Annex XVII restrictions on volatile aromatic content are forcing coating formulators to document solvent blend compositions. Industrial finish producers in Italy and Spain are reformulating alkyd systems to reduce uncontrolled aromatic fractions. Technical-grade tert-amylbenzene with documented purity certificates is capturing volume from uncharacterized commodity solvent blends.
Specification-driven procurement now dominates active ingredient manufacturing, with pharmaceutical buyers requiring batch-specific residual olefin certificates. Contract research organizations in Massachusetts and Basel are consolidating supplier lists to pre-qualified producers with dedicated analytical capabilities. This shift concentrates volume among three to four European and Indian manufacturers with captive gas chromatography protocols.
Global Tert-Amylbenzene Market Segmentation
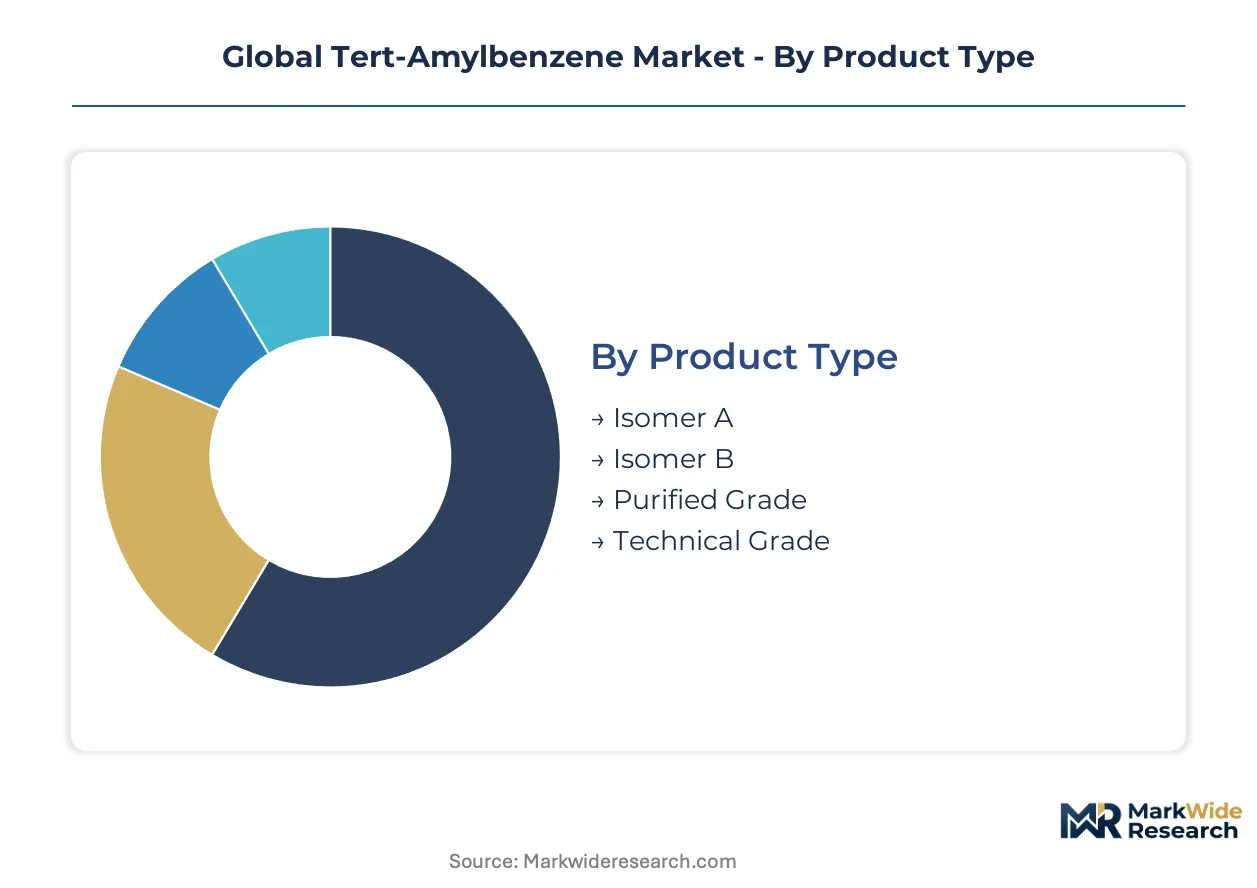
Tert-amylbenzene specifications diverge sharply across end-use requirements, with pharmaceutical and agrochemical buyers imposing distinct purity thresholds that reshape supplier economics. Segmentation reveals how technical-grade volume competes against purified-grade premiums, while packaging and logistics configurations respond to regional manufacturing cluster densities.
Product Type:
Mature commodity grades anchor baseline volume, while emerging high-purity specifications capture expanding pharmaceutical contract manufacturing demand.
- Purified Grade:Sub-50 ppm residual olefin content meets REACH Annex XVII pharmaceutical solvent standards. Demand concentrates in Swiss and German GMP facilities where batch-specific certificates are mandatory for Grignard reaction solvents.
- Technical Grade:Standard Friedel-Crafts alkylation output serves agrochemical intermediate synthesis. Gujarat and Maharashtra formulators absorb volume through India PLI scheme-aligned domestic aromatic production.
- Isomer A:Controlled branching pattern suits coating applications requiring predictable evaporation profiles.
- Isomer B:Alternative isomeric distribution finds niche use in specialty additive formulations.
Purified grade handles the majority of throughput; technical grade is the fastest mover on share.
Application:
Cost tier differentiation separates specification-driven pharmaceutical demand from price-sensitive industrial solvent procurement.
- Chemical Intermediates:Dominant volume absorption occurs in organolithium and Grignard reaction media. Massachusetts and Basel contract research organizations consolidate supplier lists to pre-qualified European and Indian manufacturers with captive gas chromatography protocols.
- Solvent Industry:Technical-grade material enters coating reformulations responding to EPA NESHAP emission mandates. Italian and Spanish alkyd system producers document blend compositions to satisfy REACH volatile aromatic restrictions.
- Specialty Chemicals:Custom synthesis applications require documented isomer ratios for reproducibility.
- Additive Manufacturing:Emerging specification development for photopolymer resin formulations.
Chemical intermediates commands the dominant revenue position; specialty chemicals is climbing the fastest on application share.
End User Industry:
Customer type fragmentation splits between validated pharmaceutical supply chains and cost-optimized agrochemical procurement.
- Pharmaceutical Manufacturers:Active ingredient producers require residual olefin certificates below 20 ppm. Continuous flow reactor adoption in Switzerland and Germany renders conventional batch processing obsolete for GMP-grade supply.
- Agrochemical Producers:Pyrethroid and herbicide intermediate synthesis drives technical-grade volume. Shanghai corridor manufacturers expand purchases through integrated aromatic supply chain proximity.
- Paints & Coatings:Reformulation mandates under EPA solvent emission rules open compliant blend opportunities.
- Consumer Goods OEMs:Fragrance and personal care applications impose odor and color stability specifications.
Agrochemical producers absorb the greatest tonnage; pharmaceutical manufacturers are gaining share fastest on value terms.
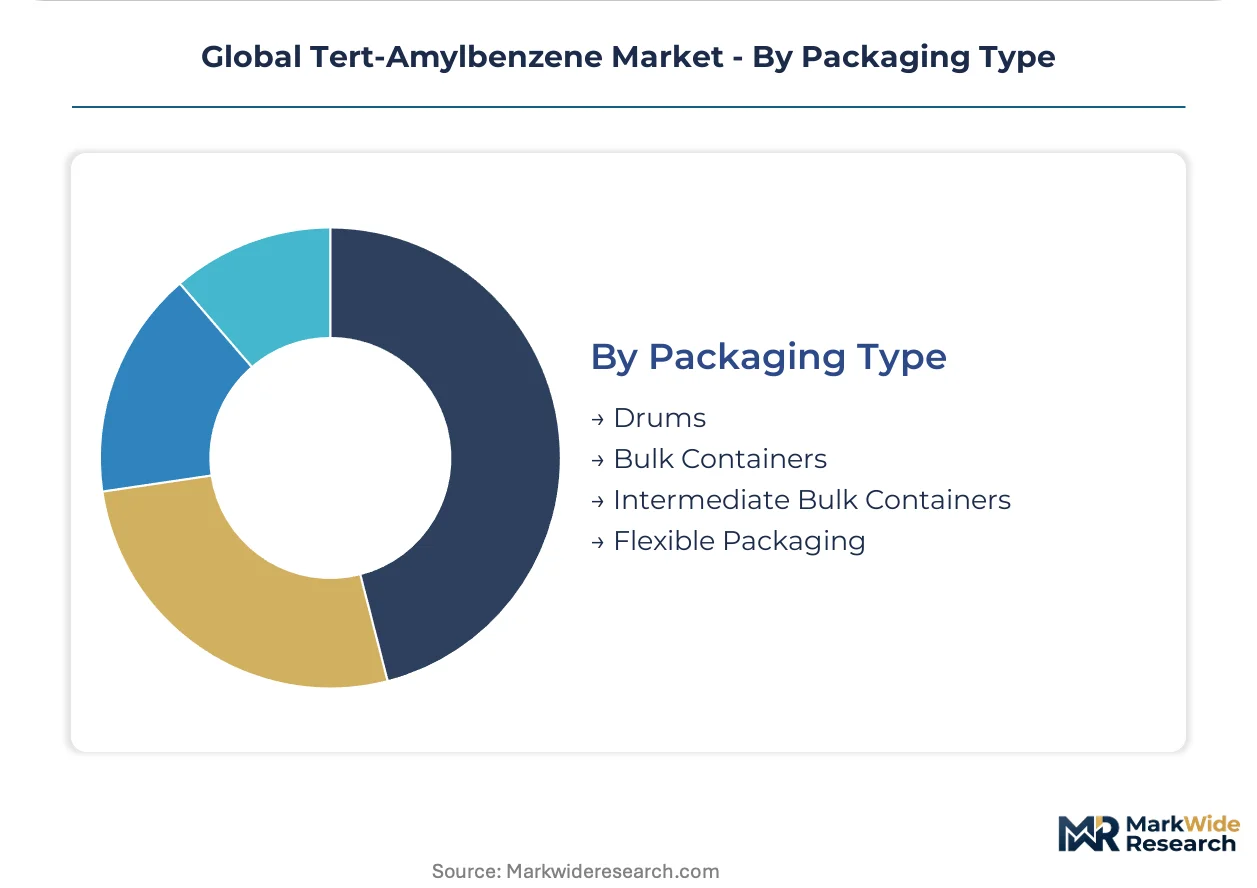
Packaging Type:
Supply concentration in East Asian manufacturing corridors dictates logistics configuration preferences.
- Bulk Containers:Integrated petrochemical complexes around Baton Rouge and Baton Rouge refinery networks favor direct pipeline and tanker transfer. Captive C5 stream access enables margin stability unavailable to non-integrated distributors.
- Intermediate Bulk Containers:Gujarat and Maharashtra chemical corridors prefer 1,000-liter totes for just-in-time agrochemical formulator delivery. CEA hazardous chemical handling rules govern transfer protocols.
- Drums:Standard 200-liter steel packaging serves mid-volume pharmaceutical and specialty chemical procurement.
- Flexible Packaging:Niche adoption for low-volume, high-frequency specialty chemical shipments.
Bulk containers handle the majority of throughput; intermediate bulk containers are expanding most quickly on format share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian and Chinese manufacturers export technical-grade tert-amylbenzene to European pharmaceutical formulators, creating a triangular trade flow governed by divergent regulatory timelines. This corridor concentrates volume absorption in East Asian chemical clusters while European buyers impose REACH-certified purity thresholds.
China
Shanghai corridor manufacturers absorb the greatest agrochemical intermediate volume through integrated aromatic supply chains. MEE emission permits now require documented residual olefin content below 100 ppm for coating solvent applications. Dual carbon targets in Beijing redirect petrochemical feedstock allocations toward lower-aromatic alternative chemistries, compressing technical-grade margins.
India
Gujarat and Maharashtra formulators drive technical-grade demand for pyrethroid and herbicide synthesis under PLI scheme-aligned domestic production incentives. CEA hazardous chemical handling rules govern intermediate bulk container transfer protocols for just-in-time delivery. The India PLI scheme supports import substitution for agrochemical formulators seeking captive aromatic intermediate supply.
United States
Baton Rouge refinery complexes leverage captive C5 stream access to sustain margin stability unavailable to non-integrated distributors. EPA NESHAP standards and evolving solvent emission rules tighten residual olefin specifications, forcing coating system reformulation. Gulf Coast petrochemical infrastructure anchors technical-grade production for domestic agrochemical and coating applications.
Germany
Pharmaceutical contract manufacturers in Basel-adjacent facilities demand sub-20 ppm residual olefin certificates for Grignard reaction solvents. REACH Annex XVII restrictions on volatile aromatic content force industrial finish producers to document blend compositions. Continuous flow reactor adoption renders conventional batch processing obsolete for GMP-grade supply qualification.
Switzerland
Swiss GMP facilities consolidate supplier lists to pre-qualified producers with dedicated gas chromatography protocols for batch-specific certification. Swissmedic pharmaceutical standards align with REACH pharmaceutical solvent requirements, creating dual compliance burdens. Contract research organizations in Basel anchor specification-grade demand for organolithium chemistry expansion.
Global Tert-Amylbenzene Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered purity specifications and captive feedstock access. The vendor base organizes around three strategic archetypes: integrated petrochemical complexes with refinery-derived C5 streams, specialty aromatic manufacturers with dedicated alkylation assets, and laboratory chemical distributors serving specification-driven pharmaceutical procurement. Dominant competitive moves include backward integration into amylene feedstock and modular continuous reactor licensing for GMP-grade qualification.
Within the integrated petrochemical tier, Solvay S.A. and ExxonMobil Corporation exemplify channel-controlling positioning through captive precursor supply and refinery network access respectively. Among South Asian specialty aromatic producers, Vinati Organics occupies a position representing Maharashtra-based dedicated production for regional agrochemical formulators. These three anchors illustrate how feedstock integration and geographic concentration shape competitive differentiation across technical and purified grade segments.
| Leading Market Players |
|---|
| TCI Chemicals |
| Alfa Aesar (Thermo Fisher Scientific) |
| Solvay S.A. |
| ExxonMobil Corporation |
| Frontier Scientific Inc. |
| Vinati Organics |
| Sigma-Aldrich (Merck KGaA) |
| Eastman Chemical Company |
| Jiujiang Pro High Technology Materials |
| Others |
Cost & Logistics Intelligence
Undercapacity in European continuous flow reactor installations compresses margin stability for purified-grade suppliers while forcing technical-grade producers toward spot-market amylene sourcing. This utilization asymmetry rewards integrated Baton Rouge and Shanghai corridor manufacturers with captive feedstock buffers against C5 stream volatility.
Pricing Analysis
Batch-to-continuous technology-generation pricing gaps separate legacy stainless-steel reactor output from microchannel-derived GMP-grade premiums. Three-tier pricing structure across pharmaceutical-certified, technical-grade, and uncharacterized solvent tiers reflects residual olefin certification costs and REACH documentation burdens. Cost compression in technical-grade material intensifies because bio-based terpene alternatives displace coating applications. Agrochemical formulators in Gujarat exhibit highest price sensitivity; Swiss GMP facilities accept premium positioning for sub-20 ppm certificates.
Supply Chain Analysis
Upstream amylene availability rests on refinery operating rates at Baton Rouge, Rotterdam, and Singapore cracking complexes. C5 stream supply draws from fluid catalytic cracker byproduct recovery, shale naphtha fractionation, and dedicated steam cracker optimization. Single-source vulnerability concentrates around integrated petrochemical gatekeepers controlling pipeline transfer infrastructure. Distribution runs through intermediate bulk container networks serving Maharashtra just-in-time delivery and bulk tanker shipments anchoring Gulf Coast technical-grade volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmaceutical contract manufacturers consolidating supplier lists to three pre-qualified European and Indian producers with captive gas chromatography protocols.
For Market Incumbents: Harden qualification barriers by investing in continuous flow reactor licensing for REACH-EPA dual certification and securing captive C5 stream arrangements at Baton Rouge or Rotterdam refinery networks. Bio-based solvent substitution in coating applications threatens technical-grade margin pools; defend through backward integration into amylene recovery units. For New Entrants and Emerging Players: Pursue white-space positioning in India PLI scheme-aligned domestic aromatic intermediate production for agrochemical formulators seeking import substitution. The most penetrable segment is technical-grade supply to Gujarat and Maharashtra corridors lacking integrated refinery access. A modular continuous reactor licensing model accelerates GMP-grade qualification without legacy batch asset stranding. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous flow reactor commissioning and dual REACH-EPA certification pathways. Long-term viability favors acquisition targets with captive analytical capabilities and pre-qualified pharmaceutical supplier status rather than commodity technical-grade exposure. Watch for EPA solvent emission rule finalization as inflection signal for compliant blend formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amylene Feedstock | Captive C5 stream access at Baton Rouge or Rotterdam insulates margin stability against refinery rate volatility. |
| Continuous Flow Reactor Licensing | Modular microchannel systems enable GMP-grade qualification without legacy stainless-steel asset write-downs. |
| Dual Certification Investment | Simultaneous REACH registration and EPA PMN filing extends pharmaceutical supplier list consolidation benefits. |
| India PLI Scheme Alignment | Domestic aromatic intermediate production incentives support import substitution for Gujarat agrochemical formulators. |
| Long-term Supply Agreement | Contracted offtake with Swiss and German GMP facilities locks in specification-grade volume against spot-market volatility. |
Research Approach
Operator-level perspectives from plant managers at alkylation facilities, procurement leads at pharmaceutical contract manufacturers, distribution channel partners in Gujarat and Maharashtra, and technical R&D directors at specialty aromatic producers anchored the qualitative base. Primary interview insights combined with secondary validation from customs and trade data, Cefic sector reports, SEC 10-K filings, and EPA regulatory dockets. Bottom-up capacity modeling and top-down demand triangulation cross-checked segment-level outputs.
Scenario-bracketing framed analytical approach across the projection horizon, with low-case assumptions around bio-based solvent substitution velocity and high-case assumptions around organolithium chemistry expansion in contract manufacturing. Segmentation dimensions modeled include grade tier, end-use industry, packaging format, and regional production hub. CAGRs derived from production capacity buildout timelines and downstream absorption elasticity estimates, with specific inputs from MEE emission permit issuance rates and India PLI scheme disbursement trajectories.
Sensitivities concentrate around dual carbon target enforcement in Beijing redirecting petrochemical feedstock allocations and EPA NESHAP standard finalization timelines. Forecasts reflect documented assumptions on continuous flow reactor adoption rates and REACH-EPA regulatory convergence patterns. Cross-checking against Cefic aromatic solvent trade flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Soy-Based Chemical Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
Europe Formic Acid Market
Functional Chemicals
2-Propylheptanol Market
Functional Chemicals
Threonine Acids Market
Functional Chemicals
Paraben Market
Functional Chemicals
Chlorobutanol Market
Functional Chemicals
Ortho Phthalic Aldehyde Market
Functional Chemicals
Amino Acids Market
Functional Chemicals
Furan Dicarboxylic Methyl Ester (FDME) Market
Functional Chemicals
Transfluthrin Market
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
Carbomer Market
Functional Chemicals
Ortho-Phthalaldehyde Market
Functional Chemicals
US Potassium Methylate Market
Functional Chemicals
Urea Formaldehyde Market