
 Aluminum Foil Containers Market | 2026-2036
Aluminum Foil Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Foil Containers Market Analysis
Ready-to-eat meal programs in institutional food service is recalibrating bulk purchasing patterns for aluminum foil containers across North American and European contract catering. Reynolds Consumer Products leverages extensive retail shelf presence and national distribution networks to sustain volume leadership in the United States consumer segment. Novelis anchors upstream supply security through its recycled aluminum sheet operations, while Contital specializes in European-format container designs for bakery and airline catering channels.
Aluminum foil containers are formed from rolled aluminum alloy sheets, typically 35–150 micrometers thick, through mechanical stamping or folding processes to create moisture-resistant, thermally conductive vessels for food handling and preparation. The disposable containers category dominates current shipment volumes due to institutional food service procurement scale, though coated containers command premium positioning where acidic or high-fat food contact demands enhanced barrier performance. Within end users, food service channels concentrate the largest absolute demand, while food processing applications are expanding fastest as ready-meal manufacturers adopt inline filling and sealing compatibility.
The FDA regulates aluminum food-contact substances under 21 CFR 177.1390, establishing compositional limits and extraction testing protocols that directly shape product formulations for U.S.-bound containers. The EU F-Gas Regulation and REACH compliance requirements influence coating chemistry selections and manufacturing site qualifications for European market access. Stakeholders must monitor evolving extended producer responsibility frameworks and recycled content mandates, as these mechanisms will increasingly determine which production configurations and material sourcing strategies maintain commercial viability across priority markets.
Market Dynamics
The EU's Single-Use Plastics Directive is forcing food service operators across Europe to eliminate polystyrene and polypropylene alternatives, redirecting procurement budgets toward aluminum foil containers with established recycling infrastructure. This regulatory compression is reshaping competitive positioning as manufacturers with European coating certifications capture volume previously held by plastic converters.
Growth Catalysts
- EU Single-Use Plastics Directive:The ban on expanded polystyrene food containers in EU member states is redirecting institutional catering procurement toward aluminum alternatives with proven circularity credentials.
- Ready-to-eat meal programs:Contract catering operators in North American healthcare and education sectors are standardizing aluminum foil containers for hot-meal distribution due to thermal retention and stackability advantages.
- Recycled aluminum sheet supply:Novelis and other rolling mills are expanding post-consumer scrap processing capacity, lowering embodied carbon in container-grade aluminum and satisfying ESG procurement criteria.
Market Restraints
- Primary aluminum price volatility:LME aluminum pricing swings above USD 2,600 per tonne compress container manufacturer margins and complicate annual contract negotiations with food service distributors.
- Coating chemistry constraints:REACH compliance requirements for epoxy-phenolic and polyester coatings limit formulation flexibility and extend new product qualification timelines by 8-14 months.
- Rigid plastic substitution in cold applications:Polypropylene containers retain cost advantages for refrigerated prepared salads and deli items where thermal conductivity is not required.
Strategic Opportunities
- India domestic food delivery expansion:Swiggy and Zomato's cloud kitchen networks are adopting aluminum containers for biryani and curry delivery, creating demand for compartmentalized regional formats.
- Extended Producer Responsibility frameworks:France's Citeo and Germany's ZSVR systems are creating preferential procurement channels for containers with verified recycled content above 50 percent.
- Smart packaging convergence:Integration of RFID temperature-logging tags with aluminum lids is enabling cold-chain verification for pharmaceutical meal programs and airline catering.
Industry Challenges
- Coating technician scarcity:Qualified formulators familiar with FDA 21 CFR 177.1390 and REACH-compliant coating systems command premium wages, constraining European and North American plant expansion.
- Legacy stamping equipment retooling:Mechanical press lines designed for 50-micron gauges require USD 2-4 million upgrades to handle 80-150 micron recycled-content alloys with work-hardening variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Foil Containers Market |
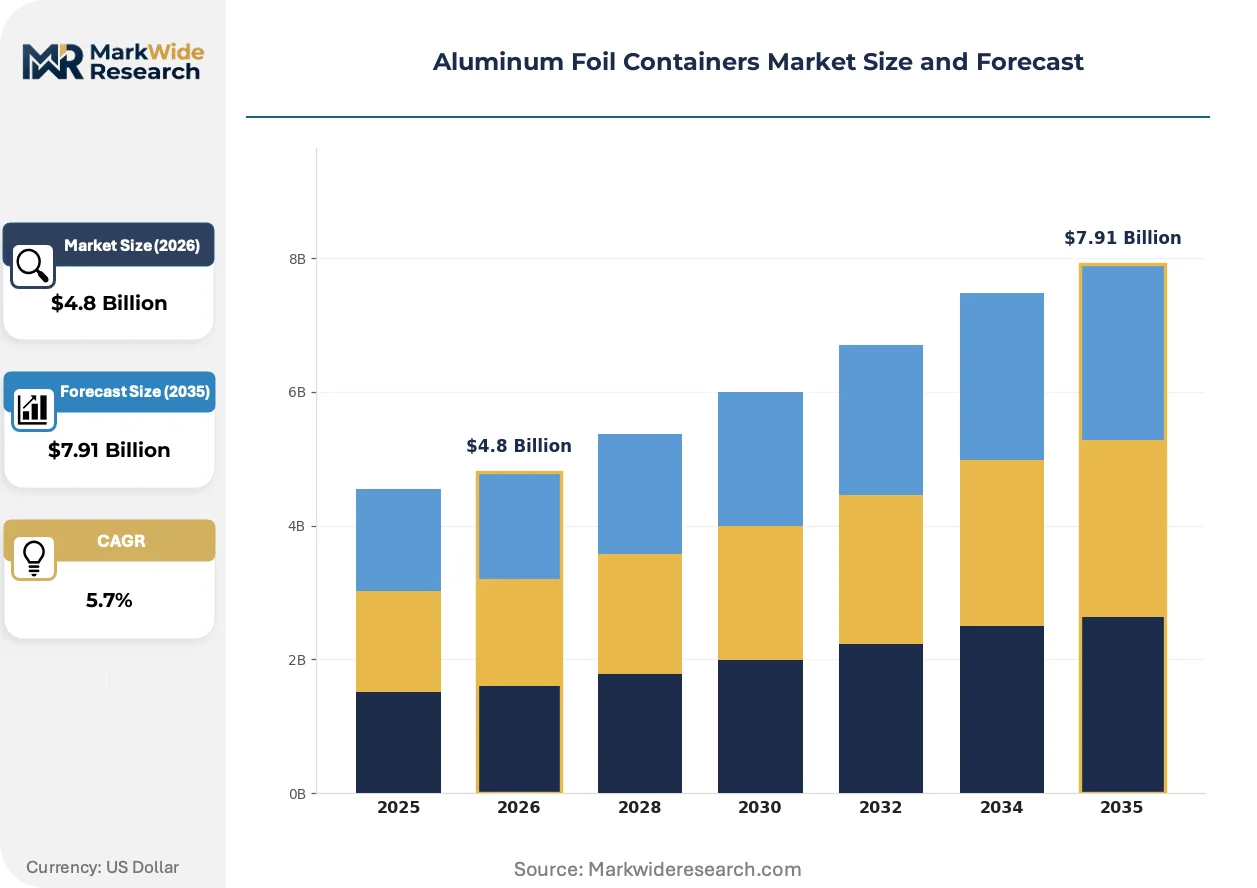
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Containers, Reusable Containers, Coated Containers, Non-Coated Containers End User: Food Service, Retail, Food Processing, Catering Services Application: Packaging, Cooking, Baking, Heating Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Reynolds Consumer Products, Contital, Pactiv Evergreen, Novelis, Handi-foil of America, D & W Fine Pack, Hulamin Containers, Trinidad Benham Corporation, Penny Plate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Foil Containers Market Emerging Trajectories
Active coating technologies and inline forming-sealing systems are compressing the traditional separation between container manufacturing and food packing operations. These convergences are enabling new service models where converters participate directly in supply chain optimization rather than remaining discrete component suppliers.
Barrier coating systems incorporating ceramic-reinforced polyester layers are unifying grease resistance and microwave compatibility in a single application process. Ready-meal manufacturers in Germany and the Netherlands are specifying these coatings for dual-ovenable product lines. The technology is unifying what previously required separate container SKUs for conventional and microwave ovens, reducing distributor inventory complexity.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer coatings from European food-contact applications by 2026. Aluminum foil container producers are accelerating qualification of silicone-modified polyester alternatives. Bakery and high-fat snack segments in France and Italy are most affected, with reformulation timelines compressed to maintain retailer shelf placement.
Direct procurement relationships between container converters and national food service distributors are displacing regional broker networks in North American institutional channels. Aramark and Compass Group are consolidating supplier panels to 3-5 approved converters with national logistics coverage. The shift is most visible in the United States K-12 and healthcare verticals, where procurement standardization reduces SKU proliferation and simplifies sustainability reporting.
Aluminum Foil Containers Market Segmentation
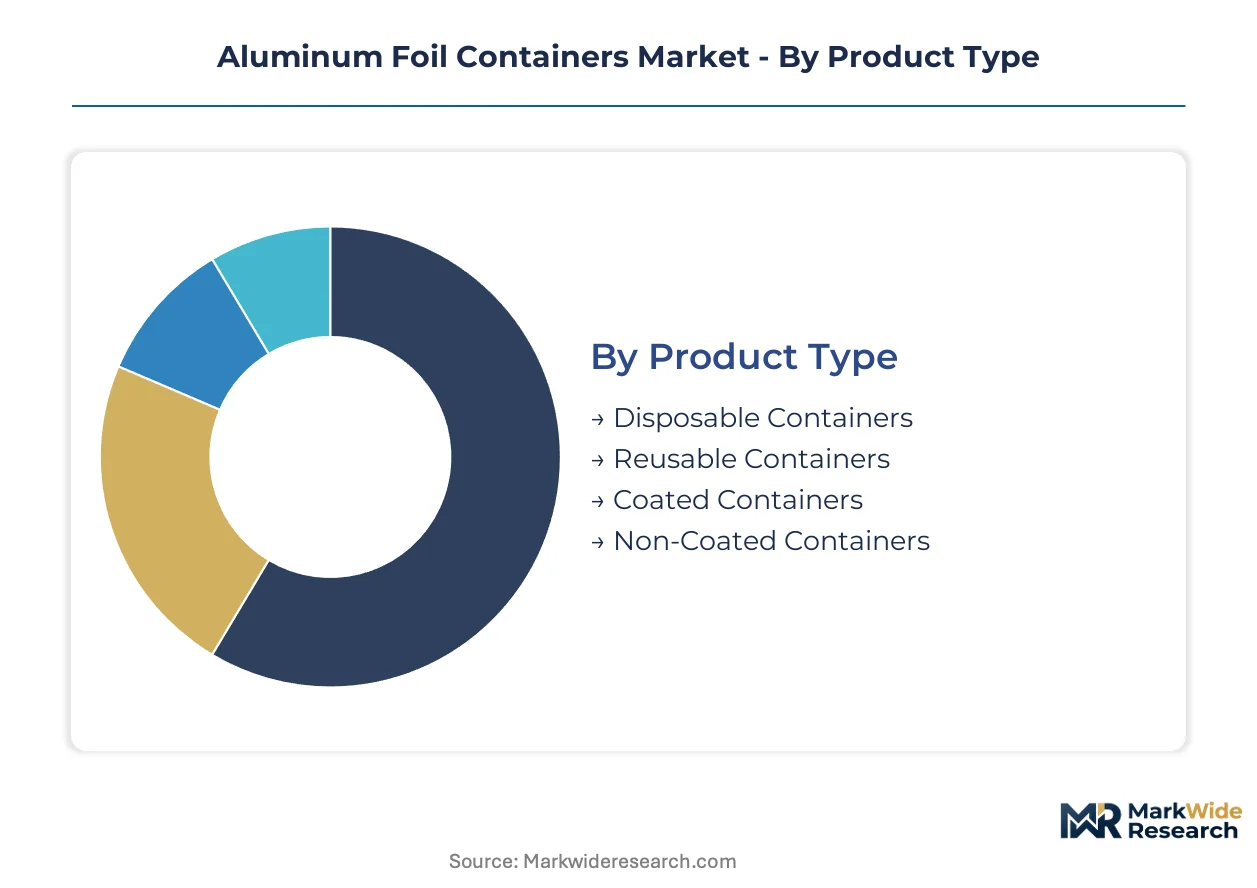
Aluminum foil container procurement patterns diverge sharply across institutional buyers, retail consumers, and food manufacturers, with each segment imposing distinct specifications on gauge thickness, coating chemistry, and format geometry. Understanding these segment boundaries clarifies where converter investments in coating capacity versus stamping automation generate differential returns.
Product Type:
Buyers select product types based on intended use frequency, food acidity, and end-of-life handling requirements, with coating decisions dominating total cost of ownership calculations for high-acid applications.
- Disposable Containers:Formed from 35–80 micrometer aluminum alloy sheets through progressive die stamping, these single-use vessels dominate institutional procurement volumes. Demand concentrates in North American K-12 and healthcare contract catering, where stackability and thermal retention properties reduce meal distribution labor costs. Volume sits with disposable containers; growth tilts toward coated variants as acidic ready-meal formulations expand.
- Coated Containers:Epoxy-phenolic or polyester barrier layers applied through roll-coating or spray deposition prevent aluminum ion migration into acidic or high-fat foods. German and Dutch ready-meal manufacturers specify ceramic-reinforced polyester coatings for dual-ovenable product lines, unifying conventional and microwave compatibility in single SKUs.
- Reusable Containers:Heavy-gauge 100–150 micrometer constructions with reinforced rims withstand 50+ wash cycles in commercial dishwashing systems. European airline catering operators deploy these for premium cabin service to reduce per-flight material costs.
- Non-Coated Containers:Bare aluminum surfaces suit dry baked goods and neutral pH foods where barrier performance is unnecessary, offering lowest unit cost for high-volume bakery channels.
Coating investments determine margin capture; uncoated volume sustains baseline plant utilization.
End User:
End-user segments separate by procurement scale, with institutional buyers negotiating annual contracts against spot-market purchasing patterns in retail channels.
- Food Service:Contract catering operators and quick-service restaurants specify format-standardized containers for inventory simplification. Aramark and Compass Group consolidated North American supplier panels to 3–5 approved converters with national logistics coverage, compressing regional broker networks.
- Food Processing:Inline filling and sealing compatibility requirements drive specification of flange geometries and lid-seal surfaces. Ready-meal manufacturers in Germany and the Netherlands are expanding fastest as production lines integrate forming-sealing systems.
- Catering Services:Event and mobile catering operators prioritize compartmentalized formats for menu separation and transport stability.
- Retail:Consumer-packaged formats through supermarkets and online retail emphasize aesthetic finishing and multi-pack configurations for household storage convenience.
Institutional procurement concentrates absolute volume; food processing applications expand most quickly through automation integration.
Application:
Application selection follows thermal requirements and equipment compatibility, with microwave-safe specifications increasingly mandatory across premium positioning.
- Packaging:Primary containment for prepared meals, baked goods, and deli items with modified atmosphere compatibility. France and Italy bakery segments drive specification of fluoropolymer-free coatings under REACH Annex XVII restrictions.
- Heating:Direct flame and oven exposure applications demand alloy compositions with thermal conductivity above 200 W/m·K for even heat distribution.
- Cooking:Grilling and roasting formats with vented lids for moisture release, specified by cloud kitchen operators in India for biryani and curry delivery.
- Baking:Shallow-gauge constructions with non-stick interior surfaces for cake and pastry production, where dimensional stability prevents warping at 200°C+ temperatures.
Packaging commands shipment volume; heating applications gain specification share as dual-ovenable coatings proliferate.
Distribution Channel:
Channel selection reflects buyer scale and delivery velocity requirements, with wholesale maintaining cost advantage for pallet-scale procurement.
- Wholesale:Food service distributors and institutional procurement platforms aggregate container volumes with national logistics networks. Reynolds Consumer Products leverages extensive distribution infrastructure to sustain volume leadership in United States consumer and institutional segments.
- Supermarkets:Retail shelf presence requires branded multi-pack configurations with consumer-facing sustainability messaging.
- Online Retail:Direct-to-consumer and small-business procurement through e-commerce platforms, growing fastest in India domestic food delivery expansion.
- Specialty Stores:Restaurant supply and bakery equipment retailers serving independent operators with format-specific inventory.
Wholesale channels dominate institutional volume; online retail climbs fastest as cloud kitchen procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters in India and Southeast Asia absorb rising export volumes while North American and European markets prioritize domestic procurement from certified converters. This production-consumption divide shapes regional investment patterns.
United States
Contract catering operators in healthcare and education sectors standardize aluminum foil containers for hot-meal distribution. FDA regulates aluminum food-contact substances under 21 CFR 177.1390, establishing compositional limits and extraction testing protocols. Reynolds Consumer Products leverages extensive retail shelf presence and national distribution networks to sustain volume leadership.
Germany
Ready-meal manufacturers specify ceramic-reinforced polyester coatings for dual-ovenable product lines unifying conventional and microwave compatibility. The EU F-Gas Regulation and REACH compliance requirements influence coating chemistry selections and manufacturing site qualifications. Novelis anchors upstream supply security through recycled aluminum sheet operations serving container-grade demand.
India
Swiggy and Zomato's cloud kitchen networks adopt aluminum containers for biryani and curry delivery, creating demand for compartmentalized regional formats. BIS standards govern food-contact materials alongside FSSAI regulations for packaged food distribution. Manufacturing clusters in Gujarat and Maharashtra absorb rising shares of export-oriented container production.
France
Bakery and high-fat snack segments accelerate qualification of silicone-modified polyester alternatives as REACH Annex XVII eliminates fluoropolymer coatings by 2026. France's Citeo extended producer responsibility system creates preferential procurement channels for containers with verified recycled content above 50 percent. Contital specializes in European-format container designs for bakery and airline catering channels.
Netherlands
Food processing applications expand fastest as ready-meal manufacturers adopt inline filling and sealing compatibility with flange-standardized containers. ECHA oversees REACH compliance for coating chemistries entering European food-contact applications. Rotterdam and Amsterdam logistics corridors concentrate distribution infrastructure for Benelux institutional procurement.
Aluminum Foil Containers Market Vendor Landscape
Top-tier vendors anchor national distribution and retail shelf presence, while mid-tier specialists capture premium niches through coating certifications and format specialization. The vendor base separates into integrated aluminum rolling operations, dedicated container converters, and hybrid players with backward sheet supply. Three archetypes dominate: scale-driven mass-market suppliers, coating-certified premium specialists, and regional export-oriented fabricators. Competitive moves concentrate on strategic partnerships with food service distributors and capacity expansion in recycled-content alloy processing.
Among North American consumer-product incumbents, Reynolds Consumer Products and Pactiv Evergreen occupy positions exemplifying scale-driven distribution leverage. Contital represents the European-format specialization archetype. Novelis anchors the integrated upstream tier through captive recycled aluminum sheet supply. These three names illustrate how competitive positioning separates by supply chain control depth rather than container manufacturing scale alone.
| Leading Market Players |
|---|
| Reynolds Consumer Products |
| Contital |
| Pactiv Evergreen |
| Novelis |
| Handi-foil of America |
| D & W Fine Pack |
| Hulamin Containers |
| Trinidad Benham Corporation |
| Penny Plate |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists in North American food service distribution have consolidated procurement panels to 3-5 approved converters, compressing margin capture for mid-tier container manufacturers while amplifying volume leverage for scale leaders. This ownership concentration reshapes pricing discipline as distributors demand multi-year contract stability against volatile LME aluminum inputs.
Pricing Analysis
Margin tightening in institutional tiers reflects consolidated buyer power as Aramark and Compass Group standardize national supplier panels. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-coated dual-ovenable formats from bare disposable containers and reusable airline-grade constructions. Cost-down pressure on standard-grade disposable containers accelerates because Indian and Southeast Asian export-oriented fabricators absorb volume at thinner margin structures. Food service channels exhibit highest price sensitivity due to annual contract negotiations against spot aluminum indices, while food processing buyers prioritize coating certification premiums over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European ready-meal manufacturers mandate qualification of both Novelis-recycled and primary aluminum sheet suppliers to mitigate alloy variability risks. Supply concentrates in India, Germany, and the United States for container-grade rolling capacity, with Gujarat and Maharashtra manufacturing clusters absorbing rising export volumes. Raw material dependencies center on post-consumer scrap aluminum, epoxy-phenolic coating resins, and ceramic-reinforced polyester barrier layers. Tariff exposure on Chinese aluminum semi-finished products is reshaping procurement geography as buyers pivot toward Indian and European mill sources. Distribution runs through national food service distributors with pallet-scale logistics networks, displacing regional broker intermediaries in North American institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container converters face a vertical-integration race as coating certification and recycled-content alloy supply emerge as decisive competitive moats. Players capturing upstream sheet supply or downstream direct-procurement relationships with institutional buyers will consolidate margin capture.
For Market Incumbents: Anchor coating chemistry expertise as a defensive barrier against REACH Annex XVII compliance deadlines eliminating fluoropolymer alternatives by 2026. Invest in ceramic-reinforced polyester qualification timelines to maintain shelf placement with French and Italian bakery segments. Defend against Indian export-oriented fabricators by locking multi-year direct procurement contracts with Aramark and Compass Group before contract renewal cycles compress regional broker networks entirely.
For New Entrants and Emerging Players: Capture cloud kitchen procurement digitization in India as Swiggy and Zomato's biryani and curry delivery networks expand compartmentalized regional format demand. Target food processing applications in Germany and the Netherlands where inline filling and sealing compatibility requirements create specification barriers for incumbent disposable-focused converters. Enter through coating certification partnerships with established European converters lacking REACH-compliant formulation capacity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier coating-certified specialists in European markets facing technician scarcity and extended qualification timelines. Long-term viability over a five-to-ten-year window hinges on recycled-content alloy processing capabilities as France's Citeo and Germany's ZSVR extended producer responsibility systems create preferential procurement channels. Monitor LME aluminum price volatility as the primary inflection signal for margin compression triggers and distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Sheet Supply | Novelis anchors container-grade demand security through captive post-consumer scrap processing capacity expansion. |
| Coating Chemistry Certification Investment | REACH-compliant silicone-modified polyester qualification maintains European bakery segment shelf placement against 2026 deadlines. |
| Direct Procurement Relationship Establishment | Aramark and Compass Group panel consolidation rewards national logistics coverage with multi-year contract stability. |
| Regional Format Specialization | Contital captures European airline and bakery channel premiums through geometry-optimized container designs. |
| Smart Packaging Convergence | RFID temperature-logging integration with aluminum lids enables pharmaceutical meal program cold-chain verification. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across container converter plant managers, food service procurement directors, coating chemistry formulators, and rolling mill technical sales leads. FDA 21 CFR 177.1390 documentation, ECHA REACH Annex XVII restriction timelines, and EU F-Gas Regulation compliance databases provided regulatory boundary conditions. Aluminum Association shipment statistics and national customs trade flows supplied volume calibration points. Bottom-up segment modeling triangulated against top-down macroeconomic demand drivers.
Granularity-level modeling operated at product type, end user, application, and distribution channel intersections, with additional dimensioning by coating chemistry certification tier and recycled-content alloy specification. CAGRs derived from regression-based demand elasticity analysis against food service employment indices, ready-meal production capacity expansion, and regulatory substitution timelines. Forecast inputs incorporated EU Single-Use Plastics Directive implementation pace, cloud kitchen network expansion rates in India, and extended producer responsibility framework adoption across European member states.
The model holds under stable LME aluminum price corridors and gradual REACH compliance phase-in schedules; deviation in primary metal volatility or accelerated fluoropolymer coating bans would shift volume trajectories materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Screw Top Lids Market
Containers
Container Liner Market
Containers
ISO Container Market
Containers
Composite Ibcs System Market
Containers
Thermoformed Containers Market
Containers
Global Food Containers Market
Containers
Takeout Containers Market
Containers
Spout Containers Market
Containers
Edible Oil Cans Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Oblong Container Market
Containers
Container Mouth Inner Seal Market
Containers
HDPE Containers Market
Containers
Concentrate Containers Market
Containers
Vacuum Formed Tray Market
Containers
PET Hinged Containers Market