
 Edible Oil Cans Market | 2026-2036
Edible Oil Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Oil Cans Market Foresight
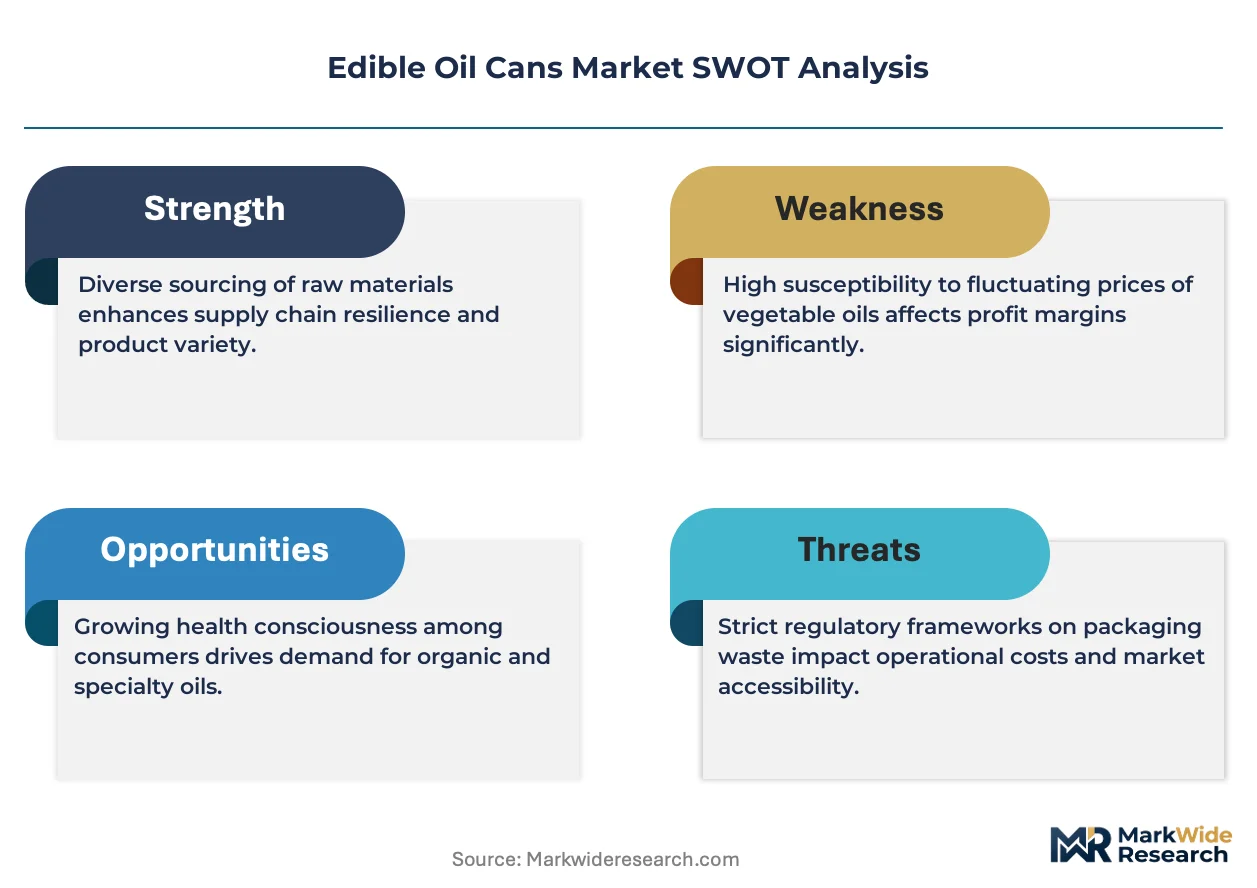
REACH compliance is repositioning material selection across European supply chains, raising compliance costs for non-EU exporters. Sidel S.A. leverages blow-molding automation to dominate high-speed canning lines for edible oils. Ball Corporation anchors North American metal can supply through captive aluminum sourcing and continuous casting investments. Kian Joo Can Factory Berhad competes across ASEAN markets with integrated tinplate printing and forming operations.
Edible oil cans are rigid primary containers, typically fabricated from tinplate, aluminum, or food-grade polymers, engineered to prevent oxidation, light degradation, and moisture ingress across shelf lives exceeding twelve months. Metal cans remain dominant in institutional channels where puncture resistance and stackability matter, while pouches represent the fastest-growing packaging type as flexible barrier films displace rigid formats in e-commerce and single-serve hospitality segments. Plastic bottles occupy the margin-rich premium retail tier where clarity and ergonomic handling drive consumer preference.
EU F-Gas Regulation and REACH restrict certain polymer additives and propellants used in can lining formulations, forcing reformulation investments among Asian exporters serving European buyers. China's SAMR enforces GB standards for food-contact substances that diverge from FDA and EFSA thresholds, creating dual-certification burdens for multinational suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and material-specific recycling quotas that will determine which packaging substrates retain channel access across major import jurisdictions.
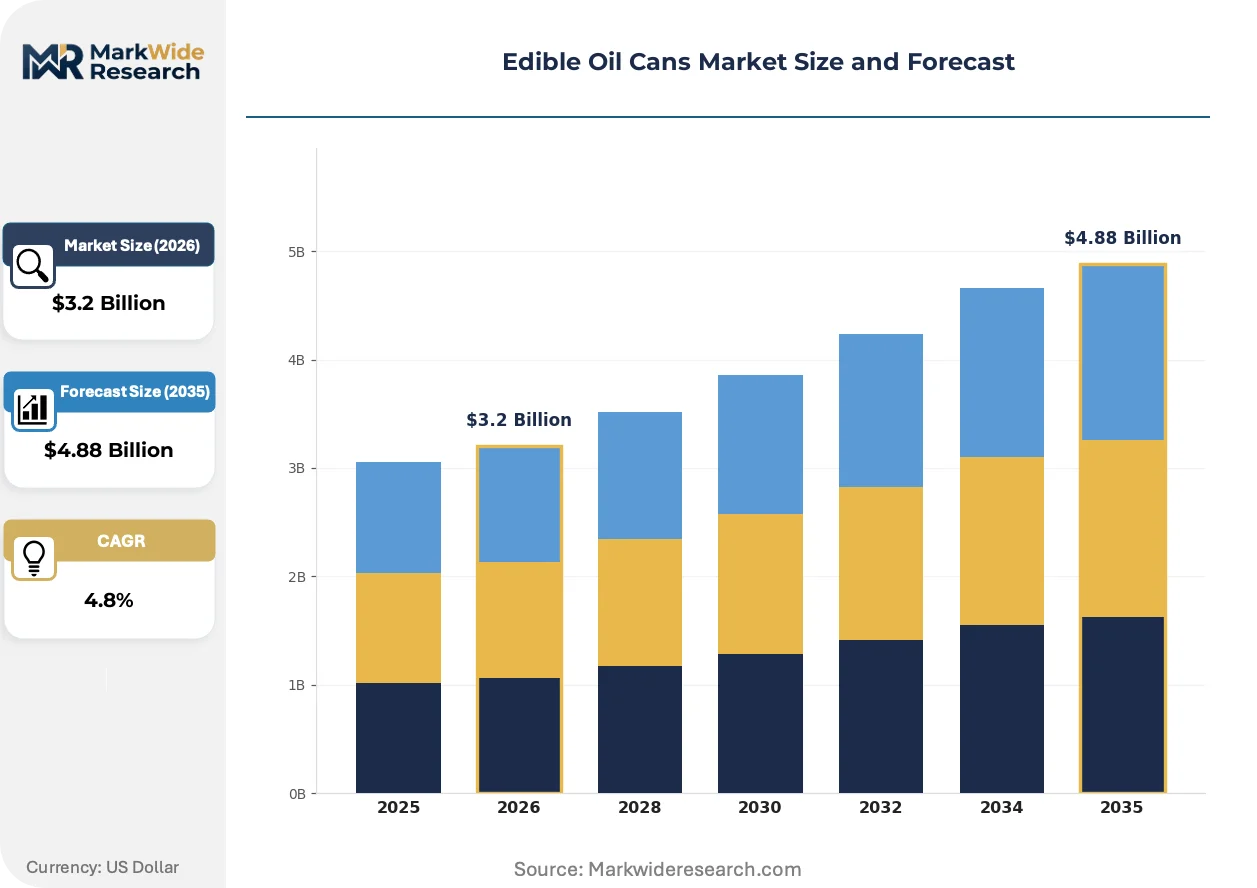
Market Dynamics
Metal-to-plastic substrate transitions are compressing legacy tinplate demand as China's GB standards and dual carbon goals force recyclability redesigns across Southeast Asian manufacturing clusters.
Growth Catalysts
- GB Standards Compliance:China's SAMR enforcement of food-contact material rules is accelerating certified packaging adoption by export-oriented canners in Vietnam and Indonesia.
- E-commerce Penetration:Single-serve flexible pouches are capturing hospitality and direct-to-consumer channels where rigid cans face last-mile damage rates.
- REACH-Driven Reformulation:EU F-Gas Regulation and polymer additive restrictions are forcing Asian suppliers to invest in compliant lining chemistries to retain European market access.
Market Restraints
- Aluminum Price Volatility:Captive smelter capacity concentration in specific geographies exposes canners to input cost swings that compress margin buffers.
- Technical Barrier Limitations:Oxygen transmission rates in bio-based polymers still exceed metal can performance thresholds for shelf lives beyond eighteen months.
- Regulatory Divergence Friction:Dual-certification burdens across FDA, EFSA, and GB standards lengthen product approval cycles and raise compliance overhead.
Strategic Opportunities
- Underpenetrated Rural India:Branded packaged oil penetration remains below urban tiers, creating white space for region-optimized can sizes and price points.
- Extended Producer Responsibility Tailwinds:EU packaging waste directives and material-specific recycling quotas favor mono-material plastic designs over multi-layer laminates.
- Digital Printing Convergence:Combination of UV-curable inks and high-speed forming lines enables micro-batch customization for seasonal and private-label campaigns.
Industry Challenges
- Barrier Coating Expertise Gap:Shortage of polymer chemists familiar with food-contact epoxy alternatives is slowing BPA-non-intent lining transitions.
- Legacy Equipment Stranding:Three-piece tinplate lines face accelerated obsolescence as two-piece aluminum and blow-molded plastic capacities scale.
- Cross-Border Certification Timelines:Divergent testing protocols between China's NMPA and EU EFSA create parallel approval tracks that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Oil Cans Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $4.88 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oil, Olive Oil, Sunflower Oil, Canola Oil Packaging Type: Metal Cans, Plastic Bottles, Glass Jars, Pouches End User: Household, Restaurants, Food Processing, Catering Distribution Channel: Supermarkets, Online Retail, Wholesalers, Specialty Stores |
| Companies Covered | Sidel S.A., Western Cans Pvt. Ltd., Parekhplast India Limited, Kian Joo Can Factory Berhad, Yee Lee Corporation Bhd group, Daeryuk Can Co., Ltd., Koogan Plastics (Pty) Ltd, Johore Tin Berhad (JTB), Ball Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Oil Cans Market Shifts & Advancements
Blow-molding automation and digital printing integration are compressing batch economics and enabling mass customization. Regulatory divergence between major import jurisdictions is fragmenting material specifications. Demand concentration in Southeast Asian manufacturing hubs is reshaping supplier location decisions.
High-speed blow-molding lines with integrated barrier layer co-extrusion are automating the shift from metal to polymer containers for mid-shelf edible oils. Regional canners in Vietnam and Thailand are adopting these systems to serve export markets requiring lighter freight costs. The technology is automating throughput gains that previously required multiple tinplate forming stations.
EU F-Gas Regulation restrictions on certain propellants and polymer additives are forcing reformulation of internal can linings and sealants. Asian exporters serving European buyers must now certify alternative epoxy-phenolic systems or lose channel access. Flexible pouch suppliers are capturing share in single-serve segments where rigid metal compliance costs prove prohibitive.
Foodservice buyers are consolidating procurement around suppliers offering combined rigid-flexible portfolios with unified quality certification. Traditional metal can specialists face disintermediation unless they add pouch or bottle formats. This pattern concentrates most visibly in China's institutional catering sector, where SAMR traceability requirements favor integrated packaging vendors over single-format suppliers.
Edible Oil Cans Market Segmentation
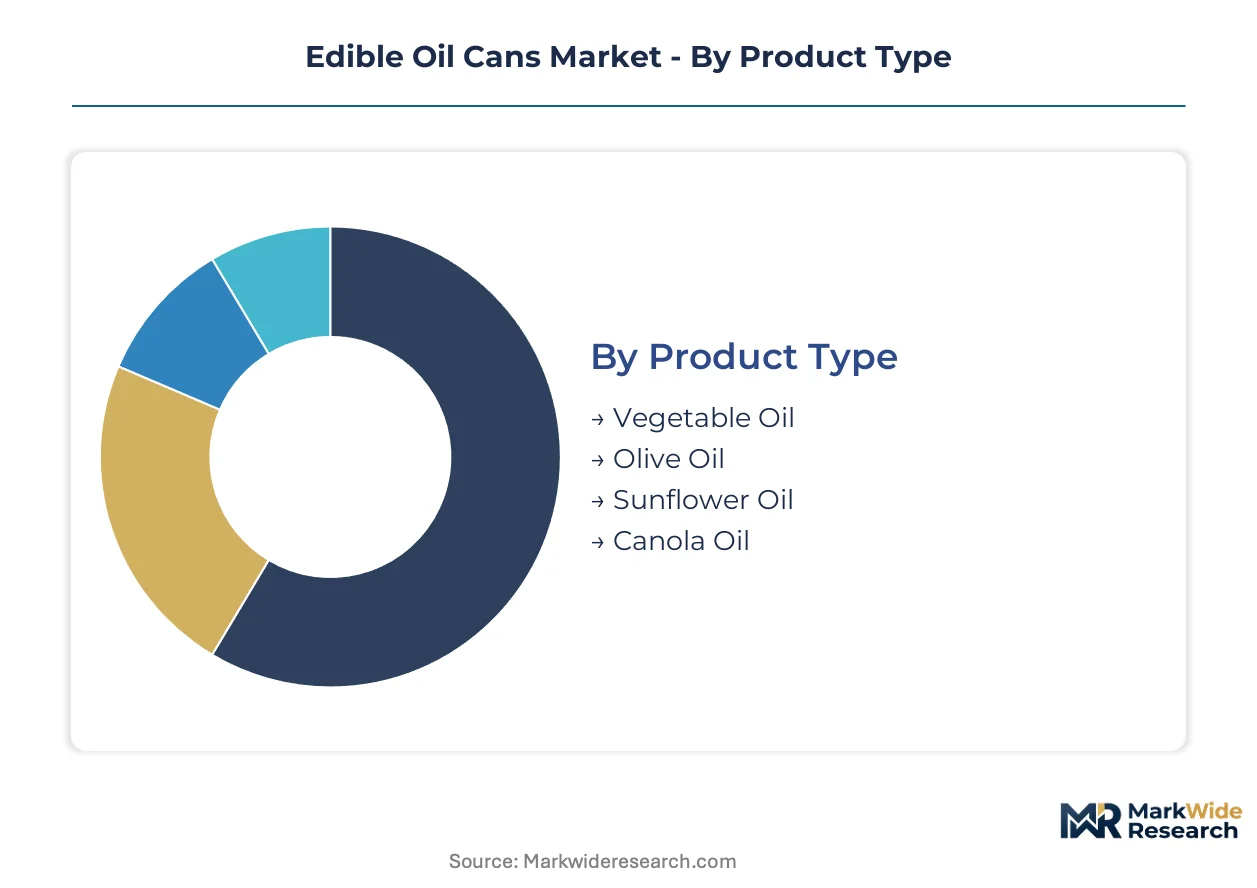
Edible oil packaging specifications diverge sharply across consumption contexts, with shelf-life requirements and handling intensity dictating substrate selection. Material transitions in Southeast Asian manufacturing clusters are fragmenting legacy segment boundaries as regulatory compliance costs reshape channel economics.
Product Type:
Upgrade cycles in edible oil packaging correlate directly with oil oxidation sensitivity and premium positioning strategies across retail tiers.
- Vegetable Oil:Palm and soybean oil variants dominate institutional procurement volumes where metal can puncture resistance outweighs freight cost premiums. Southeast Asian canners in Vietnam and Indonesia concentrate production capacity here to serve China's import demand under tightening GB standards compliance.
- Olive Oil:Extra virgin grades require UV-blocking glass or tinplate configurations to prevent photo-oxidation of polyphenol compounds. Italian and Spanish exporters maintain metal can preferences for foodservice bulk formats despite rising polymer alternatives in retail.
- Sunflower Oil:High-linoleic varieties drive flexible pouch adoption in Eastern European markets where price elasticity shapes consumer choice.
- Canola Oil:North American supply chains favor two-piece aluminum cans for export grades targeting Japanese food processing buyers.
Vegetable oil sits at the top of the volume ranking, with olive oil climbing the fastest as Mediterranean diet penetration expands in Asian middle-class segments.
Packaging Type:
Cost tier stratification determines substrate selection, with freight density and regulatory compliance burden separating premium from economy positioning.
- Metal Cans:Three-piece tinplate and two-piece aluminum formats deliver eighteen-plus month shelf stability through oxygen transmission rates below 0.1 cc per square meter daily. China's dual carbon goals are accelerating metal-to-plastic transitions in domestic canning lines despite institutional buyer preference for stackability.
- Plastic Bottles:Blow-molded PET with multilayer EVOH barriers captures premium retail tiers where clarity and ergonomic handling drive consumer preference. Sidel S.A. automation deployments in Thailand and Vietnam are compressing per-unit economics for mid-shelf edible oils.
- Glass Jars:Olive oil specialty segments retain glass for perceived quality signaling, though breakage rates constrain e-commerce penetration.
- Pouches:Spouted flexible formats with metallized film barriers represent the steepest expansion trajectory as single-serve hospitality and direct-to-consumer channels displace rigid formats.
Metal cans retain volume leadership in institutional channels, with pouches gaining share fastest where last-mile damage tolerance matters.
End User:
Application intensity separates segments, with handling frequency and storage duration dictating puncture resistance requirements.
- Household:Branded packaged oil adoption accelerates in emerging economies as food safety standards tighten and consumers shift from loose oil purchases.
- Restaurants:High-turnover foodservice operations prioritize five-liter metal can formats with integrated pouring spouts for kitchen efficiency.
- Food Processing:Industrial buyers specify bulk tote configurations with nitrogen flushing compatibility for subsequent repackaging operations.
- Catering:Event and institutional catering consolidates procurement around suppliers offering combined rigid-flexible portfolios with unified SAMR traceability certification in China.
Household consumption anchors segment volume, with food processing expanding most quickly as Southeast Asian manufacturing clusters scale export-oriented canning capacity.
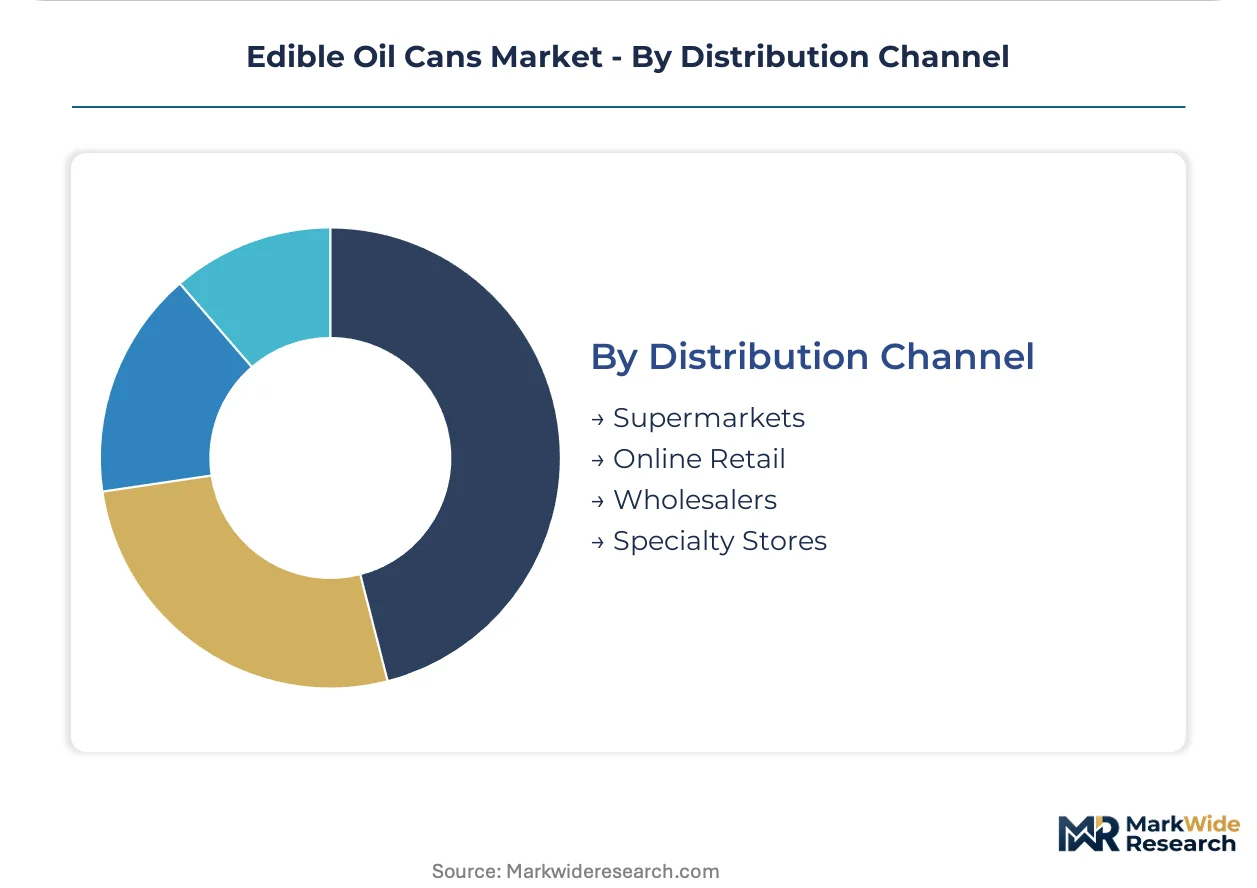
Distribution Channel:
Customer type and purchase frequency determine channel infrastructure investment, with inventory velocity and spoilage risk shaping format selection.
- Supermarkets:Modern trade formats in India and Indonesia drive region-optimized can sizes as branded packaged oil penetration penetrates below-urban tiers.
- Online Retail:E-commerce penetration favors pouch and bottle formats where rigid can damage rates in last-mile logistics compress margins.
- Wholesalers:Cash-and-carry formats serving independent restaurants concentrate metal can volumes through palletized procurement efficiency.
- Specialty Stores:Gourmet and organic oil segments command glass and premium tinplate configurations with digital printing customization for seasonal campaigns.
Supermarkets maintain volume dominance, with online retail climbing fastest as direct-to-consumer packaging formats displace traditional can specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metal can fabrication for edible oils traces its industrial lineage to early twentieth-century tinplate rolling mills in the United Kingdom and subsequent mass-production scaling in the American Midwest. Contemporary manufacturing geography reflects this heritage while shifting toward Southeast Asian export platforms and Chinese domestic capacity.
China
Domestic edible oil consumption drives massive canning demand as urban households abandon loose oil purchases. SAMR enforcement of GB standards for food-contact materials forces dual-certification investments from export-oriented suppliers. Manufacturing clusters in Guangdong and Zhejiang provinces are converting legacy tinplate lines to blow-molded PET systems to meet dual carbon goals.
United States
Institutional foodservice buyers anchor metal can volumes through palletized procurement of five-liter formats. FDA food-contact substance notifications govern internal lining chemistries for domestic and export grades. Chicago and Baltimore maintain heritage canning infrastructure serving North American soybean and canola oil supply chains.
Vietnam
Export-oriented canning capacity is scaling rapidly to serve Chinese import demand under tightening GB compliance requirements. Regional suppliers invest in Sidel S.A. blow-molding automation to capture mid-shelf edible oil contracts. Manufacturing parks outside Ho Chi Minh City concentrate new polymer forming investments.
Indonesia
Palm oil processing dominance creates downstream canning demand for both domestic consumption and re-export. National food safety agency regulations align partially with GB standards to facilitate China-bound shipments. Batam and Surabaya host expanding metal-to-plastic conversion projects serving ASEAN trade flows.
India
Branded packaged oil penetration in rural tiers lags urban centers, creating white space for region-optimized can sizes. FSSAI enforcement of food-contact material rules is tightening loose oil distribution channels. Manufacturing clusters in Maharashtra and Gujarat are scaling tinplate and polymer forming capacity simultaneously.
Edible Oil Cans Market Competitive Landscape
The competitive structure tilts toward integrated packaging specialists with captive material sourcing and high-speed forming automation. Tier-one positions concentrate among European blow-molding equipment licensors and North American aluminum can fabricators with captive smelter relationships. Three strategic archetypes dominate: automation-integrated system suppliers, metal can specialists with backward aluminum control, and ASEAN-based integrated tinplate printers. Capacity expansion and portfolio diversification into flexible formats represent the dominant competitive moves as rigid can demand fragments.
Among the named fabricators, Sidel S.A. and Ball Corporation occupy positions at the automation-licensor and metal-can ends of the technology spectrum respectively, while Kian Joo Can Factory Berhad anchors the ASEAN integrated tinplate archetype. These three represent distinct strategic postures without implying specific market share claims. Western Cans Pvt. Ltd. and Parekhplast India Limited sit within the South Asian supplier tier where regional scale and import-substitution dynamics shape positioning. Daeryuk Can Co., Ltd. exemplifies Korean specialized metal forming capabilities serving export-oriented oil processors.
| Leading Market Players |
|---|
| Sidel S.A. |
| Western Cans Pvt. Ltd. |
| Parekhplast India Limited |
| Kian Joo Can Factory Berhad |
| Yee Lee Corporation Bhd group |
| Daeryuk Can Co., Ltd. |
| Koogan Plastics (Pty) Ltd |
| Johore Tin Berhad (JTB) |
| Ball Corporation |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap canners across Vietnam and Indonesia anchor regional supply discipline through generational control of tinplate printing and forming assets, insulating pricing from short-term commodity swings while China's SAMR enforcement of GB standards forces compliance-driven cost pass-throughs to export buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments edible oil cans by barrier performance and certification grade. Premium PET bottles with EVOH co-extrusion command handling premiums for ergonomic clarity, while institutional metal cans compete on palletized freight density. Cost compression in mid-shelf polymer formats is intensifying because Sidel S.A. automation deployments in Thailand compress per-unit economics. Food processing buyers exhibit least price sensitivity due to nitrogen-flushing compatibility requirements, whereas rural Indian household segments drive volume through region-optimized can sizes at economy entry points.
Supply Chain Analysis
China's dual carbon goals and local-content preferences for domestic blow-molding equipment are reshaping sourcing patterns across Southeast Asian manufacturing clusters. Raw material flows draw from Indonesian palm oil processing, Vietnamese polymer resin imports, and Chinese tinplate rolling capacity. Single-source vulnerability concentrates in aluminum smelter geography, exposing canners to input cost volatility when captive supply concentrates in specific geographies. Distribution runs through palletized wholesale channels serving institutional foodservice buyers, with e-commerce direct-to-consumer flows fragmenting toward flexible pouch specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edible oil cans function as a stable compounder anchored by irreversible food safety regulation tightening across emerging economies, with household branded-packaging adoption creating predictable replacement demand.
For Market Incumbents: Lock in backward integration into aluminum smelter relationships or captive PET resin supply to defend margin buffers against input volatility. Prioritize GB standards certification investments to maintain China export access as SAMR enforcement tightens. Accelerate flexible pouch format additions before foodservice buyers complete procurement consolidation around unified rigid-flexible portfolios. For New Entrants and Emerging Players: E-commerce fulfillment partners represent the fastest channel to scale, bypassing entrenched wholesale relationships controlled by legacy metal can specialists. Target rural Indian household segments with region-optimized can sizes below one-liter capacity where branded penetration lags urban tiers. Lead with digital printing-enabled micro-batch customization for seasonal private-label campaigns to differentiate from high-volume incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among ASEAN integrated tinplate printers with dormant polymer conversion capability. The five-to-ten year viability window favors suppliers with demonstrated cross-certification across FDA, EFSA, and GB standards regimes. Watch for accelerated metal-to-plastic conversion announcements from Chinese manufacturing clusters as the inflection signal for substrate shift momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Layer Co-Extrusion Scale-Up | High-speed PET lines with EVOH barriers displace tinplate in mid-shelf edible oils across Vietnam and Thailand. |
| GB Standards Dual Certification | SAMR-compliant lining chemistries preserve China channel access for export-oriented ASEAN canners. |
| Flexible Pouch Format Addition | Spouted metallized film configurations capture single-serve hospitality demand with lower compliance burden than metal. |
| Digital Printing Integration | UV-curable ink systems enable micro-batch seasonal campaigns for private-label edible oil brands. |
| Captive Aluminum Smelter Relationship | Backward integration into primary metal supply insulates margin buffers against LME price volatility. |
Research Methodology
Coverage spans China, Vietnam, Indonesia, India, and the United States, with primary inputs from each market combining interviews with canner operations directors, polymer chemists specializing in food-contact barriers, retail category buyers, and foodservice procurement managers. Secondary validation draws from SAMR GB standard filings, FDA food-contact substance notifications, ASEAN customs trade databases, and SEC 10-K disclosures from listed packaging fabricators. Bottom-up capacity assessments triangulate against top-down consumption estimates.
Rate-of-change decomposition separates volume growth from value mix shifts across the projection horizon. Segmentation dimensions include oil type sensitivity, packaging substrate, end-user application intensity, and channel format. CAGRs derive from installed capacity trajectories, regulatory compliance cost curves, and substitution elasticity between metal and polymer formats. Forecast inputs incorporate SAMR enforcement intensity timelines and EU F-Gas Regulation amendment pathways.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum price volatility, bio-based polymer barrier breakthroughs, and divergence between FDA and GB testing protocols. A small set of named triggers warrants ongoing watch: China's dual carbon goal acceleration, REACH polymer additive list expansions, and rural Indian FSSAI enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Snap-Lock Container Market
Containers
Lever Lid Cans Market
Containers
Shipping Container Liners Market
Containers
Global Flexitanks Market
Containers
Metal IBC Market
Containers
Lift-Off Lid Box Market
Containers
ISO Container Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
Concentrate Containers Market
Containers
Thermoformed Containers Market
Containers
Spout Containers Market
Containers
Wooden Barrels Market
Containers
Container Mouth Inner Seal Market
Containers
Cubitainer Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Americas Container Technology Market