
 Vacuum Formed Tray Market | 2026-2036
Vacuum Formed Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Formed Tray Market Analytics
EU MDR is shifting the cost-of-entry calculus for vacuum formed tray suppliers serving European medical device clients. Placon Corporation leverages captive thermoforming capacity and ISO 11607 certification to sustain sterile packaging leadership across North American hospital supply chains. T.O. Plastics anchors its position through deep specialization in thin-gauge PET trays for electronics OEMs. Bardes Plastics competes on custom tool-less forming capabilities that reduce prototyping lead times for medical device startups.
Vacuum formed trays are thermoformed plastic containers produced by heating a polymer sheet and drawing it over a mold via vacuum pressure, typically achieving wall thicknesses between 0.010 and 0.080 inches depending on draw ratio and material gauge. These trays function primarily as protective shipping platforms, retail display units, and sterile barrier systems across industrial and consumer supply chains. PET Trays command structural priority in food packaging due to clarity and recyclability tailwinds, while PP Trays represent the fastest-expanding material category in medical applications driven by steam sterilization compatibility and elevated temperature resistance. The Electronics application segment remains margin-diluted by commoditized Asian supply, whereas Medical Packaging concentrates value through validation-intensive cleanroom production requirements.
FDA sterilization validation protocols and EU MDR technical documentation requirements shape product development timelines and testing expenditures for tray manufacturers targeting regulated healthcare markets. ISO 11607 and ASTM F2097 establish baseline performance criteria for sterile barrier integrity and seal strength that determine market access eligibility. REACH restrictions on phthalate plasticizers in PVC formulations redirect formulation R&D toward PET and PP alternatives across European supply chains. Stakeholders must monitor evolving extended producer responsibility frameworks in California and the EU, as recycled content mandates will force material specification changes before the forecast horizon closes.
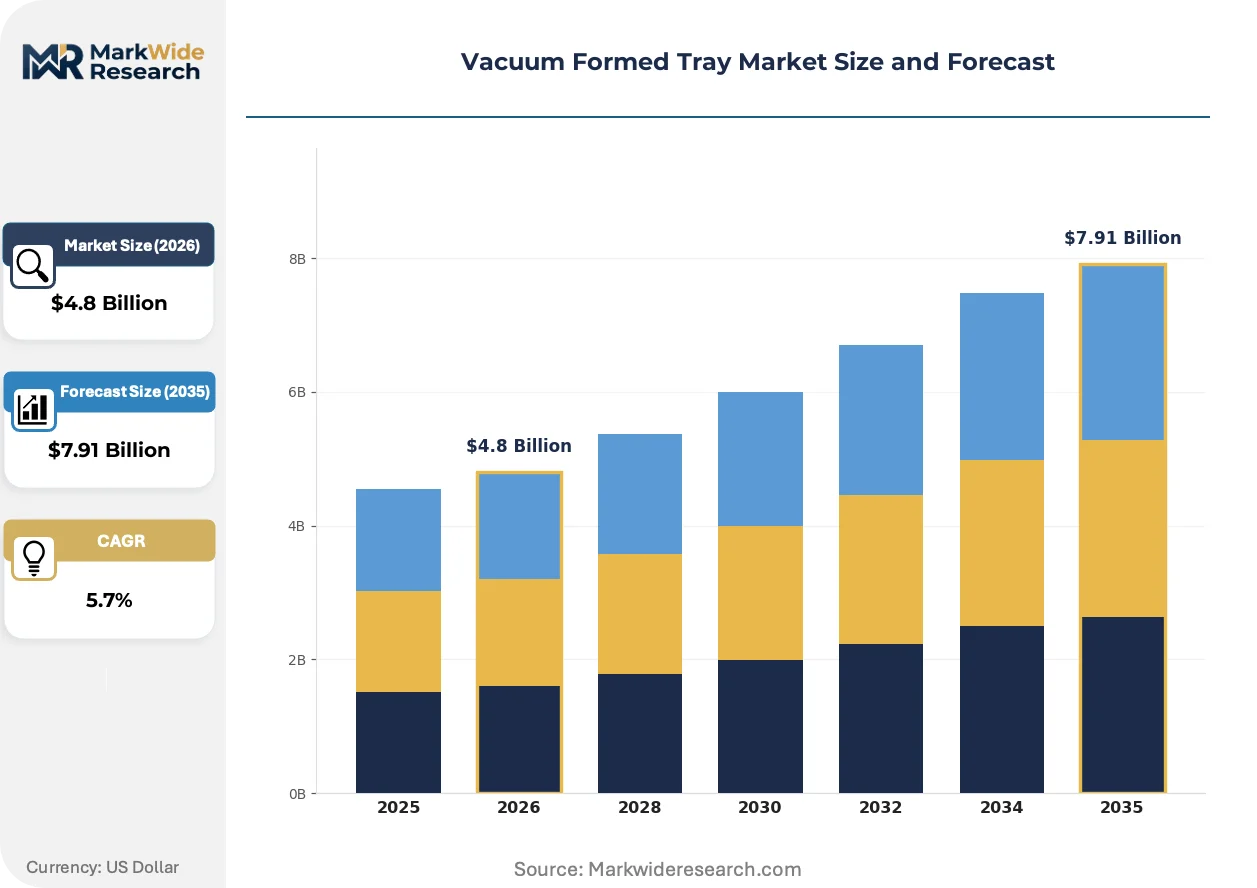
Market Dynamics
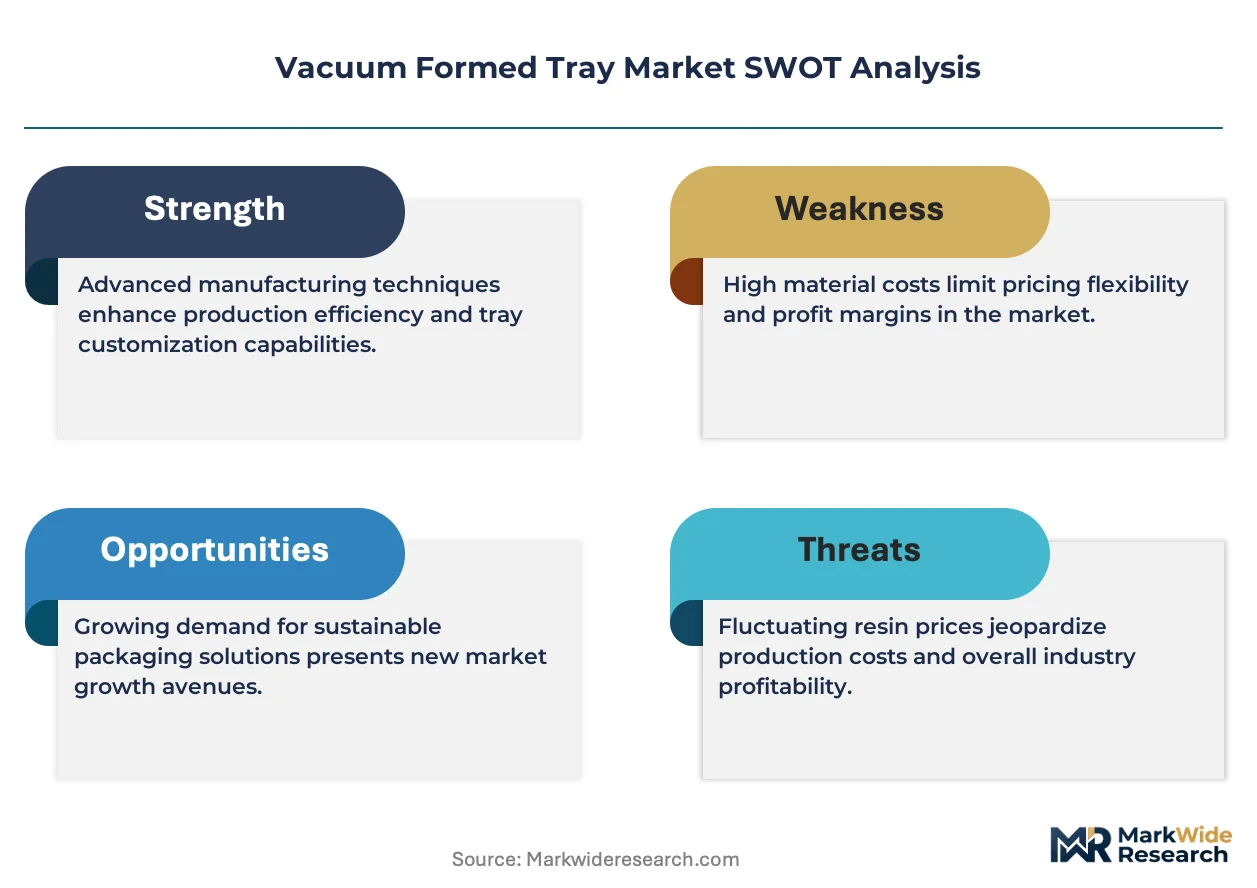
Sterile barrier validation requirements under FDA and EU MDR are compressing supplier qualification timelines while elevating capital thresholds for tray manufacturers serving medical device OEMs. This regulatory tightening is consolidating production capacity among ISO 11607-certified thermoformers with cleanroom infrastructure.
Growth Catalysts
- Steam sterilization compatibility:Polypropylene trays enable autoclave processing at 134°C, satisfying central sterilization departments in German and US hospital systems that have phased out ethylene oxide alternatives.
- REACH phthalate restrictions:ECHA's 2023 plasticizer limitations on PVC formulations are redirecting European medical packaging procurement toward PET and PP tray substrates with validated extractables profiles.
- Tuttlingen cluster expansion:Germany's surgical instrument manufacturing corridor around Tuttlingen is generating concentrated demand for validated sterile barrier systems from regional thermoforming suppliers.
Market Restraints
- Petrochemical input volatility:Virgin PET and PP resin prices track naphtha and propylene feedstock swings, compressing gross margins for thin-gauge thermoformers without backward integration into resin compounding.
- Asian supply commoditization:Electronics-grade vacuum formed trays face price erosion from Chinese and Vietnamese producers with lower labor and environmental compliance costs.
- Validation timeline friction:FDA 510(k) sterilization validation protocols require 18-24 month qualification cycles for new tray designs, freezing out speculative capacity additions.
Strategic Opportunities
- Post-consumer recycled content mandates:California's SB 54 extended producer responsibility framework will force rPET incorporation in food-contact trays by 2030, rewarding early movers with validated mechanical recycling streams.
- Tool-less forming for prototyping:Medical device startups require rapid design iteration for custom surgical kits, creating white space for thermoformers with CNC-routed aluminum tooling and 72-hour prototype turnaround.
- RFID-integrated traceability:Converging UHF RFID inlay insertion with thermoforming lines enables unit-level sterilization load tracking, differentiating suppliers for orthopedic implant OEMs.
Industry Challenges
- Cleanroom technician scarcity:ISO Class 7-8 production environments require specialized aseptic handling certification that remains concentrated in established medical device manufacturing regions.
- Legacy ERP integration:Validated manufacturing execution systems for FDA 21 CFR Part 11 compliance create friction when merging acquired thermoforming assets with consolidated corporate platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Formed Tray Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PS Trays, PVC Trays, PET Trays, PP Trays Application: Food Packaging, Medical Packaging, Electronics, Consumer Goods End User: Food Service, Healthcare, Retail, E-Commerce Material: Polyethylene, Polystyrene, Polypropylene, Others |
| Companies Covered | Plastiform, Placon Corporation, T.O. Plastics, Tray-Pak Corporation, Bardes Plastics, Reflex Packaging, Innovative Plastec, Tekni-Pak, Plastic Ingenuity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Formed Tray Market Evolving Landscape
Material science advances and regulatory digitization are compressing product development cycles while elevating performance specifications for vacuum formed trays across sterile barrier and sustainable packaging applications.
Multi-layer coextruded PET/EVOH/PE structures are consolidating moisture and oxygen barrier performance in pharmaceutical blister trays, displacing conventional PVC/PVdC laminations. Oncology drug manufacturers in Switzerland and Massachusetts are qualifying these substrates for humidity-sensitive oral solid dose packaging. The shift is consolidating procurement among thermoformers with captive coextrusion capacity and validated adhesive lamination processes.
EU MDR's Unique Device Identification mandates are forcing serialization integration into sterile barrier tray designs before 2026 compliance deadlines. Medical device manufacturers must embed Data Matrix codes at the point of thermoforming rather than post-process labeling. German and Irish orthopedic implant suppliers are most affected, redesigning tray cavities to accommodate laser-marked lidstock alignment with minimal seal area sacrifice.
Hospital supply chain consolidation is compressing vendor managed inventory programs into direct-to-sterile-processing-department distribution. Large US health systems including HCA and CommonSpirit are bypassing distributor warehouses for Class II device trays, requiring thermoformers to maintain regional finished goods buffers with EDI-triggered replenishment. The model concentrates volume among suppliers with multi-site US manufacturing footprints and validated cold chain documentation.
Vacuum Formed Tray Market Segmentation
Vacuum formed tray manufacturers face divergent technical specifications across end-use verticals, with medical and food applications imposing incompatible sterilization and barrier requirements. Material selection and gauge thickness decisions cascade through tooling investments, cleanroom infrastructure, and regulatory validation pathways.
Product Type:
Supply concentration among ISO 11607-certified thermoformers favors substrates with validated sterile barrier performance, while commodity electronics applications fragment across lower-specification producers.
- PET Trays:Amorphous polyester sheets deliver optical clarity and moisture barrier performance critical for pharmaceutical blister packs and fresh produce display. German oncology drug manufacturers and Swiss packaging converters concentrate procurement among suppliers with captive coextrusion lines and validated adhesive lamination. REACH phthalate restrictions redirect European medical procurement toward PET substrates with documented extractables profiles.
- PP Trays:Semi-crystalline polypropylene withstands autoclave temperatures to 134°C, enabling steam sterilization workflows that German and US hospital systems favor over ethylene oxide alternatives. Central sterilization departments in Tuttlingen's surgical instrument corridor generate concentrated demand for validated PP sterile barrier systems.
- PS Trays:Crystal and high-impact polystyrene variants serve cost-sensitive electronics cushioning and retail display applications where clarity-to-cost ratios dominate specification.
- PVC Trays:Plasticized formulations face ECHA restrictions on phthalate content, compressing European medical market access and redirecting R&D toward copolyester alternatives.
Today's leader: PET Trays. Tomorrow's challenger: PP Trays.
Application:
Margin structures diverge sharply between validation-intensive healthcare segments and price-commoditized industrial applications.
- Medical Packaging:Sterile barrier systems require ISO Class 7-8 cleanroom production, FDA 510(k) sterilization validation, and EU MDR technical documentation. German orthopedic implant OEMs and Irish medical device suppliers drive specification intensity through Unique Device Identification mandates and Data Matrix serialization integration.
- Food Packaging:California's SB 54 extended producer responsibility framework will mandate post-consumer recycled content thresholds by 2030, rewarding thermoformers with validated rPET mechanical recycling streams and closed-loop collection partnerships.
- Electronics:Thin-gauge ESD-safe trays for semiconductor and component shipping face margin compression from Vietnamese and Chinese producers with lower environmental compliance and labor costs.
- Consumer Goods:Retail display and promotional packaging applications prioritize rapid tooling turnaround and short-run flexibility over material performance specifications.
Medical Packaging commands premium pricing through validation barriers. Food Packaging faces steepest regulatory transformation.
End User:
Customer procurement sophistication ranges from EDI-triggered vendor managed inventory programs to spot-market commodity purchasing.
- Healthcare:Hospital supply chain consolidation at HCA and CommonSpirit compresses distribution tiers, requiring direct-to-sterile-processing-department logistics with regional finished goods buffers and validated cold chain documentation.
- Food Service:National restaurant chains and institutional catering operations specify clarity, stackability, and microwave safety in grab-and-go and prepared meal applications.
- Retail:Mass merchandisers and grocery chains balance shelf appeal against unit economics in produce, bakery, and deli tray procurement.
- E-Commerce:Protective shipping trays for fragile goods must integrate with automated fulfillment center handling systems and last-mile damage reduction protocols.
Healthcare leads specification complexity. E-Commerce offers volume scaling potential.
Material:
Resin selection determines processing window, sterilization compatibility, and regulatory compliance trajectory across regional frameworks.
- Polypropylene:Steam sterilization compatibility and elevated temperature resistance position this material for central sterilization department workflows in German and US hospital systems phasing out ethylene oxide.
- Polyethylene:LDPE and HDPE variants serve cost-driven industrial cushioning and secondary packaging applications with lower performance thresholds.
- Polystyrene:Amorphous structure enables thermoforming clarity at reduced gauge thickness for retail display and electronics applications.
- Others:Bio-based PLA and cellulose pulp hybrid formulations address emerging single-use plastic restrictions in French and Italian food service markets.
Polypropylene anchors medical validation pipelines. Bio-based alternatives gain regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermoforming engineers and ISO 11607-certified technicians concentrate in Germany's medical technology corridor, the US Great Lakes manufacturing belt, and Switzerland's precision packaging sector. This talent distribution shapes where validated sterile barrier production scales fastest.
United States
FDA 510(k) sterilization validation requirements and hospital supply chain consolidation at HCA and CommonSpirit drive demand for ISO Class 7-8 cleanroom capacity. The Midwest manufacturing belt around Wisconsin and Minnesota anchors thermoforming production for medical device OEMs, with regional finished goods buffers supporting direct-to-sterile-processing-department distribution models.
Germany
EU MDR technical documentation mandates and Unique Device Identification serialization requirements compress supplier qualification timelines. The Tuttlingen surgical instrument cluster generates concentrated demand for validated PP sterile barrier systems, with regional thermoformers investing in steam sterilization-compatible tray designs for central sterilization departments phasing out ethylene oxide.
Switzerland
Swissmedic oncology drug packaging regulations and humidity-sensitive oral solid dose requirements accelerate multi-layer coextruded PET/EVOH/PE adoption. Basel and Zurich packaging converters concentrate procurement among thermoformers with captive coextrusion lines, displacing conventional PVC/PVdC laminations in pharmaceutical blister applications.
China
NMPA medical device registration requirements and domestic hospital procurement reform reshape sterile barrier demand. Yangtze River Delta electronics manufacturers drive thin-gauge ESD-safe tray consumption, though price competition from Vietnamese producers compresses margins in commoditized semiconductor shipping applications.
India
CDSCO medical device rules and phased implementation of quality management system requirements elevate compliance thresholds for tray suppliers. Maharashtra and Gujarat pharmaceutical packaging hubs generate demand for cost-optimized sterile barriers, with domestic thermoformers scaling ISO 11607-certified capacity to serve export-oriented injectables manufacturers.
Vacuum Formed Tray Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market segments. The vendor base stratifies between ISO 11607-certified medical specialists with cleanroom infrastructure and commodity electronics-grade producers facing Asian price pressure. Three archetypes dominate: captive thermoformers with backward resin integration, custom tool-less prototyping shops, and multi-site regional suppliers with EDI-enabled vendor managed inventory programs. Competitive moves concentrate on M&A consolidation of validated cleanroom assets and geographic expansion to support direct-to-hospital distribution models.
Among US-based fabricators, Placon Corporation and T.O. Plastics occupy distinct positioning archetypes. Placon exemplifies the captive capacity model with thermoforming operations scaled to serve North American hospital supply chains. T.O. Plastics represents thin-gauge specialization for electronics OEMs. Bardes Plastics anchors the custom rapid-prototyping tier, serving medical device startups with compressed design iteration cycles.
| Leading Market Players |
|---|
| Plastiform |
| Placon Corporation |
| T.O. Plastics |
| Tray-Pak Corporation |
| Bardes Plastics |
| Reflex Packaging |
| Innovative Plastec |
| Tekni-Pak |
| Plastic Ingenuity |
| Others |
Value Network & Pricing Analysis
Naphtha and propylene feedstock indices cascade through virgin PET and PP resin costs into three distinct pricing tiers for vacuum formed tray procurement. Medical device OEMs absorb premium positioning for ISO 11607-certified cleanroom production, while electronics buyers face relentless cost compression from Asian suppliers with lower compliance burdens.
Pricing Analysis
Tool-less prototyping services and high-volume production contracts split the market into unbundled and bundled service models. Three-tier pricing structure separates validated sterile barrier systems from standard industrial trays and commodity electronics cushioning, with certification grade and cleanroom infrastructure as primary differentiation drivers. Cost compression in electronics-grade segments intensifies because Vietnamese producers undercut on labor and environmental compliance. Hospital supply chains show lowest price sensitivity due to regulatory validation lock-in, while consumer electronics OEMs negotiate aggressively on unit economics.
Supply Chain Analysis
Direct-to-sterile-processing-department channels handle hyperscale health system demand from HCA and CommonSpirit, bypassing traditional distributor tiers. Resin compounding concentrates in Germany, the United States, and China, with thermoforming production anchored in the US Great Lakes belt and Germany's Tuttlingen corridor. Raw material flows draw from naphtha crackers, propylene derivatives, and post-consumer rPET streams. Single-source vulnerability around ISO Class 7-8 cleanroom technician pools in established medical device regions creates qualification bottlenecks. Distribution runs through EDI-triggered vendor managed inventory programs for healthcare, spot-market procurement for electronics, and closed-loop collection partnerships for food-grade rPET.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through steam sterilization-compatible PP tray adoption, as German and US hospital systems phase out ethylene oxide and absorb premium pricing for validated alternatives.
For Market Incumbents: Acquire captive coextrusion capacity to consolidate barrier film integration and displace PVC/PVdC laminations in pharmaceutical blister applications. Defend against Asian price erosion by embedding RFID traceability and serialization compliance into tray designs for orthopedic implant OEMs facing EU MDR deadlines. Expand multi-site US manufacturing footprints to support direct-to-hospital distribution models with regional finished goods buffers.
For New Entrants and Emerging Players: California's SB 54 extended producer responsibility framework opens a window for rPET-focused thermoformers with validated mechanical recycling streams and food-contact compliance. Target medical device startups in surgical instrument corridors with 72-hour prototype turnaround using CNC-routed aluminum tooling. Pursue tool-less forming specialization that compresses design iteration cycles for custom surgical kits.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap thermoformers holding ISO 11607 certification and cleanroom infrastructure in underserved US regions. Long-term viability hinges on regulatory validation moats widening as FDA 510(k) timelines extend and EU MDR technical documentation burdens intensify. Watch for inflection when hospital supply chain consolidation accelerates direct-to-sterile-processing-department procurement mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11607 Certification Investment | Validates sterile barrier performance for FDA 510(k) submissions and EU MDR compliance. |
| Captive Coextrusion Capacity Addition | Enables multi-layer PET/EVOH/PE structures for humidity-sensitive oncology drug packaging. |
| Post-Consumer rPET Stream Development | Positions suppliers for California SB 54 recycled content mandates by 2030. |
| RFID-Integrated Traceability Deployment | Differentiates tray suppliers for orthopedic implant OEMs requiring unit-level sterilization tracking. |
| Tool-Less Rapid Prototyping Capability | Captures medical device startup demand with compressed design iteration cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand estimates for vacuum formed tray applications. Primary discussions with thermoforming plant managers, medical device procurement leads at German orthopedic OEMs, hospital supply chain directors at US health systems, and pharmaceutical packaging converters informed capacity and specification trends. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, customs trade data for PET and PP resin flows, and hospital GPO contract disclosures. Bottom-up production capacity tallies triangulated against top-down end-use consumption models.
Historical reference periods anchored volume and value trajectories across the projection horizon, with growth rates derived from segment-specific demand elasticity and regulatory compliance cost curves. Segmentation dimensions modeled include material substrate, sterilization compatibility tier, end-use vertical, cleanroom certification status, and geographic production cluster. Forecast inputs incorporated steam sterilization adoption curves in German and US hospital systems, REACH phthalate restriction implementation timelines, and extended producer responsibility framework phase-ins.
Revisions become necessary when resin feedstock volatility exceeds historical bands, cleanroom technician availability constraints tighten, or regulatory validation timelines shift materially. Forecasts reflect documented assumptions regarding hospital supply chain consolidation pace and rPET mechanical recycling yield improvements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Light Resistant Containers Market
Containers
Foldable Steel Containers Market
Containers
Pinch Grip Jars Market
Containers
Americas Container Technology Market
Containers
Club Store Packaging Tray Market
Containers
Wooden Barrels Market
Containers
Cylindrical Cans Market
Containers
Lever Lid Tinplate Containers Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Die Cut Display Container Market
Containers
PET Containers Market
Containers
Single Wall Jars Market
Containers
Hinged Lid Tins Market
Containers
Wooden Crates Market
Containers
Aluminum Foil Containers Market
Containers
Foam Containers Market