
 Container Liner Market | 2026-2036
Container Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Container Liner Market Analysis
Licensed mariner availability is bifurcating fleet deployment strategies across major carriers. MSC leverages its Geneva-based network to sustain officer training pipelines across Mediterranean and West African routes. Maersk anchors its Copenhagen operations with integrated cadet academies in Denmark and Singapore. CMA CGM differentiates through French maritime school partnerships that secure deck officer supply for its expanding transpacific services.
Container liners are flexible barrier inserts designed to line the interior of standard shipping containers, typically fabricated from multi-layer polyethylene or woven polypropylene with load ratings exceeding 20 metric tons to prevent cargo contamination during ocean transit. The primary industrial purpose centers on converting dry bulk containers into single-use liquid or powder transport systems without dedicated tank infrastructure. Polyethylene formulations dominate installed base economics due to chemical resistance and heat-sealing compatibility, while polypropylene variants capture pharmaceutical end users demanding higher tensile strength for active ingredient shipments. Custom liners command premium positioning in the chemicals segment where UN-certified hazardous material configurations require engineered venting and discharge port geometries.
The International Maritime Organization's SOLAS container weight verification mandate shapes liner specification requirements by enforcing verified gross mass documentation that indirectly governs fill optimization protocols. EU REACH compliance and the EU Green Deal's FuelEU Maritime initiative collectively pressure liner material sourcing toward recyclable substrates and reduced carbon intensity in production logistics. China's SAMR national standards for food-contact materials dictate import acceptance criteria for liners serving the food and beverage export channel. Stakeholders must monitor evolving bio-based polymer certification pathways and port authority digitization requirements that will determine competitive access to priority trade lanes.
Market Dynamics
The EU Green Deal's FuelEU Maritime initiative is compressing vessel deployment timelines while forcing liner manufacturers toward low-carbon substrate certification, creating simultaneous demand pull and compliance cost pressure across chemical and food-grade segments.
Growth Catalysts
- Bulk Chemical Logistics Expansion:German and Indian chemical manufacturers are extending multi-year contracts for powder and liquid bulk transport, converting standard dry containers into single-use tank systems without dedicated infrastructure investment.
- REACH-Driven Material Upgrades:EU REACH compliance requirements for hazardous cargo documentation are accelerating adoption of UN-certified liner configurations with engineered venting and discharge geometries in the chemicals segment.
- Asia-Pacific Manufacturing Corridor:Vietnam's export processing zones are absorbing liner volumes for agricultural commodity and processed food shipments, driven by EU and US import demand.
Market Restraints
- Petrochemical Feedstock Volatility:Multi-layer polyethylene and woven polypropylene production costs fluctuate with crude oil derivatives, compressing margin stability for liner fabricators without long-term resin contracts.
- Licensed Mariner Supply Concentration:Officer training pipeline bottlenecks in Mediterranean and West African routes limit fleet expansion velocity for carriers deploying liner-compatible container assets.
- SAMR Certification Friction:China's national standards for food-contact materials create import acceptance delays for non-domestic liner manufacturers serving the food and beverage export channel.
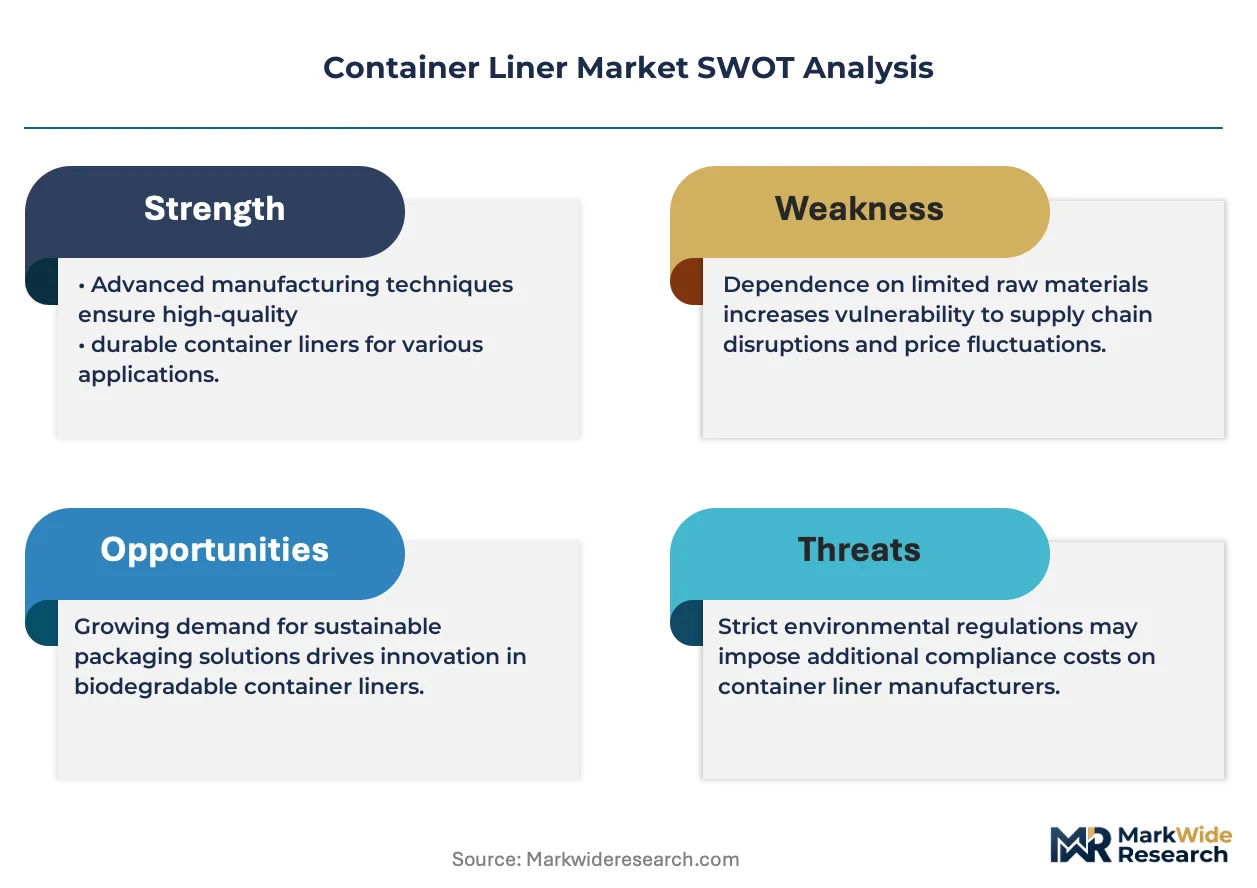
Strategic Opportunities
- Recyclable Substrate Development:Bio-based polymer certification pathways under EU circular economy frameworks offer premium positioning for liner producers able to document carbon intensity reduction in production logistics.
- Pharmaceutical Active Ingredient Transport:Polypropylene variants with higher tensile strength specifications are capturing demand from pharmaceutical end users for temperature-sensitive active ingredient shipments requiring enhanced barrier properties.
- Port Authority Digitization:Verified gross mass documentation requirements under SOLAS are creating integrated service opportunities for liner suppliers offering fill optimization software alongside physical products.
Industry Challenges
- Cadet Academy Capacity Constraints:Integrated officer training programs in Denmark and Singapore face enrollment limitations that restrict carrier fleet scaling and liner deployment velocity.
- Dual Certification Timeline Compression:Simultaneous EU REACH and China SAMR compliance documentation extends product development cycles for hazardous material and food-contact liner configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Container Liner Market |
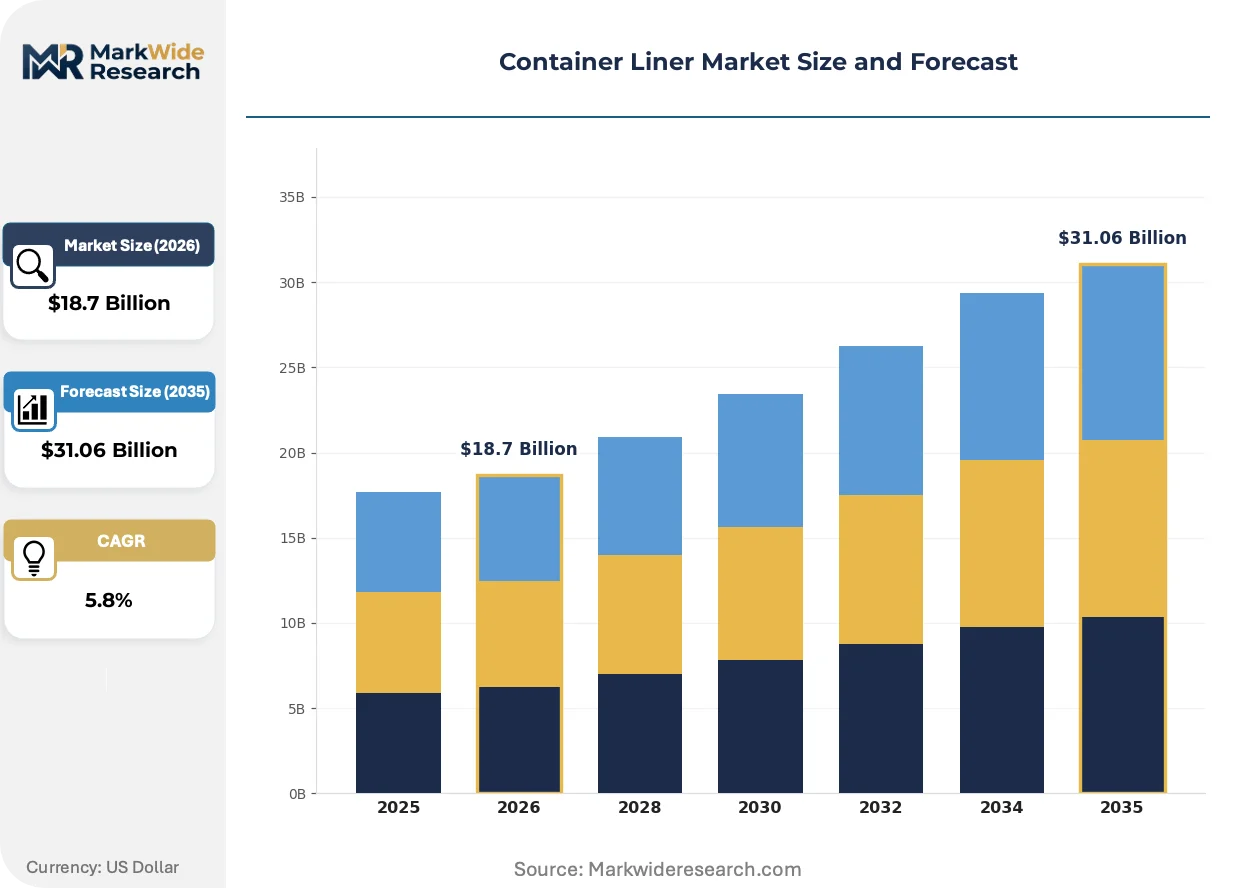
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Liners, FIBC Liners, Roll Liners, Custom Liners Material: Polyethylene, Polypropylene, Paper, Non-Woven Fabrics End User: Agriculture, Food & Beverage, Chemicals, Pharmaceuticals Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Mediterranean Shipping Company (MSC), Maersk, CMA CGM, COSCO Shipping Lines, Hapag-Lloyd, Ocean Network Express, Evergreen Marine, Yang Ming Marine Transport, HMM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Container Liner Market Emerging Trajectories
Material science advances and regulatory digitization are converging to redefine competitive differentiation in liner manufacturing, with sustainability credentials and smart documentation capabilities displacing traditional price-based procurement.
Multi-layer co-extruded polyethylene formulations with embedded RFID tracking layers are fragmenting the commodity liner segment by enabling real-time cargo condition monitoring. Pharmaceutical and high-value chemical shippers in Rotterdam and Singapore are specifying these configurations for temperature-sensitive loads. The technology is compressing differentiation timelines as standard barrier liners face displacement from sensor-integrated alternatives within premium segments.
The EU Green Deal's emissions trading requirements for maritime logistics are tightening vessel specifications that indirectly govern liner fill optimization protocols. FuelEU Maritime mandates are pushing carriers toward slow-steaming routes that extend transit times and increase demand for enhanced moisture barrier properties. Chemical manufacturers in Antwerp and Hamburg are responding by specifying custom venting geometries that accommodate longer ocean legs without cargo degradation.
Buyer consolidation among multinational chemical distributors is compressing procurement cycles and unbundling after-sales technical support from unit pricing. Large contract holders in the Rhine-Ruhr and Gujarat industrial corridors are centralizing liner sourcing through integrated logistics providers rather than direct manufacturer relationships. This pattern is most visible in hazardous material segments where UN certification management and documentation compliance are being outsourced to third-party logistics operators.
Container Liner Market Segmentation
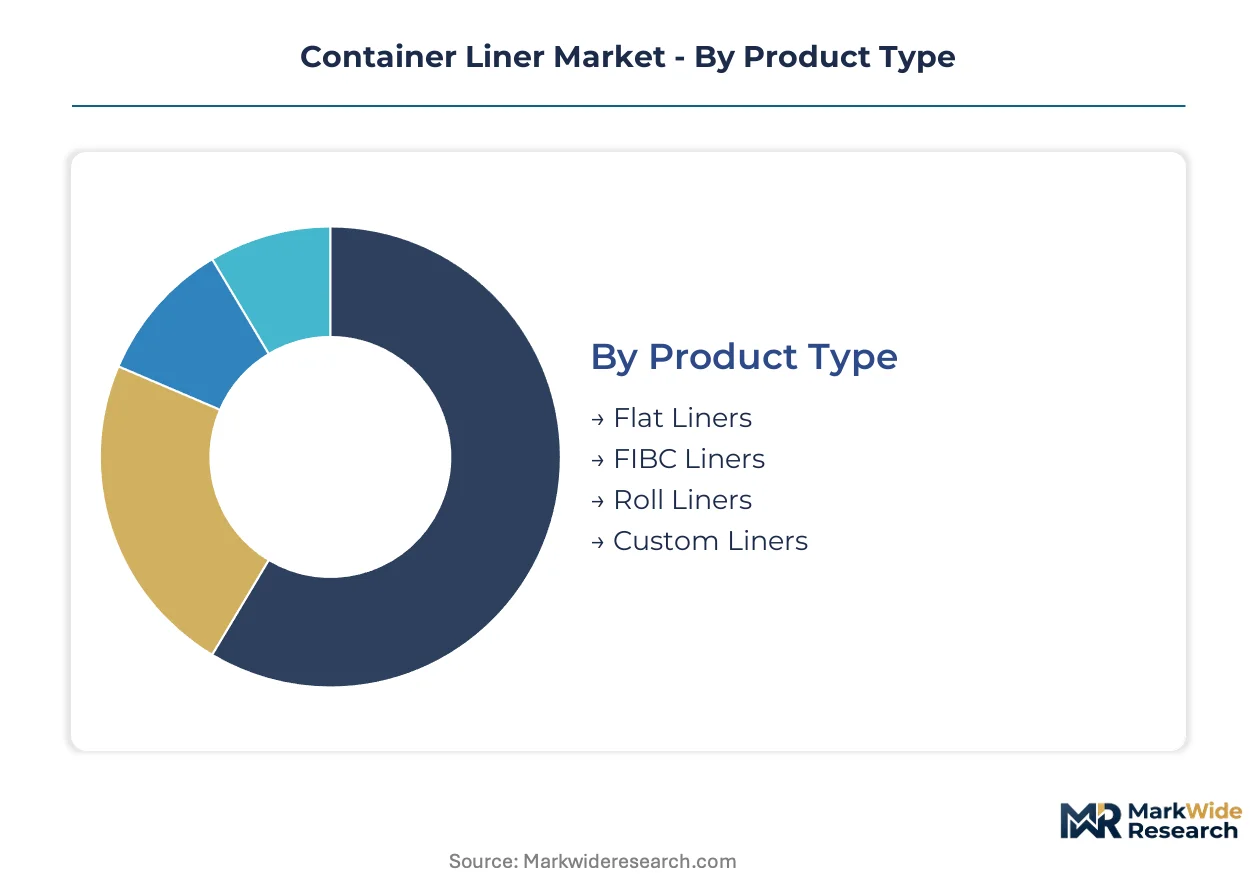
Container liner procurement patterns diverge sharply across material grades and end-use certifications, with chemical and pharmaceutical buyers commanding premium configurations while agricultural volume runs on commodity specifications. Segmentation discipline separates margin-accretive custom fabrication from standardized bulk supply.
Product Type:
Custom liners concentrate margin pools through UN-certified hazardous material engineering, while flat liners anchor volume throughput in agricultural commodity flows.
- Flat Liners:Single-layer polyethylene or polypropylene sheets designed for dry bulk agricultural commodities such as grains, seeds, and feed supplements. Demand clusters in Vietnam's export processing zones for rice and coffee shipments bound for EU markets, with SAMR food-contact compliance requirements dictating substrate selection for China-bound exports.
- Custom Liners:Engineered multi-layer configurations with specified venting geometries, discharge port placements, and UN-certified hazardous material ratings for chemical and active pharmaceutical ingredient transport. German chemical manufacturers in the Rhine-Ruhr corridor specify these for REACH-compliant powder and liquid bulk movements, with FuelEU Maritime slow-steaming routes driving enhanced moisture barrier specifications.
- FIBC Liners:Flexible intermediate bulk container inserts for semi-bulk handling of industrial minerals and construction aggregates.
- Roll Liners:Continuous spooled formats for automated filling operations in high-volume food processing facilities.
Custom liners hold installed capacity. Flat liners are rotating up the share rankings.
Material:
Polyethylene formulations dominate installed base economics through heat-sealing compatibility and chemical resistance, while bio-based polymer pathways are climbing the certification ladder under EU circular economy frameworks.
- Polyethylene:Multi-layer co-extruded formulations comprising the majority of chemical and food-grade liner deployments, with embedded RFID tracking layers now specified by Rotterdam and Singapore pharmaceutical distributors for temperature-sensitive cargo monitoring. REACH compliance documentation and recyclable substrate certification are compressing differentiation timelines as standard barrier grades face displacement.
- Polypropylene:Woven and non-woven variants capturing pharmaceutical end users demanding higher tensile strength for active ingredient shipments requiring enhanced barrier properties against moisture and oxygen ingress. India's CDSCO pharmaceutical export requirements and EU EMA good distribution practice standards are tightening material traceability protocols.
- Paper:Kraft and coated grades for food-contact applications with limited moisture exposure.
- Non-Woven Fabrics:Spunbond polypropylene for breathable agricultural commodity protection.
Polyethylene dominates current procurement volumes. Polypropylene is climbing the fastest on pharmaceutical certification requirements.
End User:
Chemical manufacturers generate the steepest margin premiums through UN-certified hazardous material configurations, while food and beverage buyers impose the most stringent multi-jurisdiction compliance burdens.
- Chemicals:German and Indian manufacturers extending multi-year contracts for powder and liquid bulk transport, converting standard dry containers into single-use tank systems without dedicated infrastructure investment. EU REACH hazardous cargo documentation and engineered venting geometries are accelerating specification upgrades, with Antwerp and Hamburg shippers responding to FuelEU Maritime slow-steaming mandates through enhanced moisture barrier requirements.
- Pharmaceuticals:Temperature-sensitive active ingredient shipments requiring polypropylene tensile strength specifications, embedded RFID condition monitoring, and dual EU-China certification pathways. Rotterdam and Singapore distribution hubs are centralizing sourcing through integrated logistics providers capable of managing UN certification and documentation compliance.
- Agriculture:Grain, seed, and feed supplement movements through Vietnam's export processing zones.
- Food & Beverage:Processed food and beverage exports facing China SAMR import acceptance friction for non-domestic manufacturers.
Chemicals holds installed capacity. Pharmaceuticals is rotating up the share rankings.
Distribution Channel:
Direct sales relationships capture the highest-margin custom liner contracts, while distributor networks are consolidating procurement for commodity-grade agricultural specifications.
- Direct Sales:Manufacturer relationships with multinational chemical distributors in the Rhine-Ruhr and Gujarat industrial corridors, unbundling after-sales technical support from unit pricing and centralizing UN certification management. Large contract holders are outsourcing hazardous material documentation compliance to integrated logistics providers rather than maintaining direct manufacturer relationships.
- Distributors:Third-party logistics operators capturing consolidated liner sourcing for agricultural and standard food-grade segments, with buyer compression among multinational distributors shortening procurement cycles and compressing margin transparency.
- Online Sales:Digital procurement platforms for standardized flat liner and roll liner specifications.
- Retailers:Limited presence in small-volume agricultural and construction end uses.
Direct sales holds installed capacity. Distributors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR food-contact certification requirements in China anchor Asia-Pacific liner procurement compliance frameworks, while EU REACH and FuelEU Maritime directives reshape European specification standards. Industrial clusters in Germany, India, Vietnam, and the Netherlands concentrate demand for chemical-grade and food-grade liner configurations.
Germany
Rhine-Ruhr chemical manufacturers extend multi-year bulk transport contracts for powder and liquid movements. EU REACH hazardous cargo documentation mandates engineered venting geometries in custom liner specifications. Antwerp and Hamburg shippers respond to FuelEU Maritime slow-steaming routes through enhanced moisture barrier requirements for extended ocean legs.
China
Export processing zones absorb agricultural commodity liner volumes for rice and coffee shipments bound for EU markets. SAMR national standards for food-contact materials dictate import acceptance criteria for liners serving the food and beverage export channel. Yangtze River Delta manufacturing corridors centralize sourcing decisions for multinational distributors.
India
Gujarat industrial corridor chemical manufacturers convert standard dry containers into single-use tank systems without dedicated infrastructure investment. CDSCO pharmaceutical export requirements tighten material traceability protocols for polypropylene liner variants. Mumbai and Ahmedabad distribution hubs consolidate procurement through integrated logistics providers.
Vietnam
Export processing zones drive liner absorption for agricultural commodity and processed food shipments. EU import demand for coffee and rice shipments shapes specification requirements for moisture barrier properties. Ho Chi Minh City logistics clusters concentrate sourcing relationships with multinational chemical distributors.
Netherlands
Rotterdam pharmaceutical distributors specify multi-layer co-extruded polyethylene formulations with embedded RFID tracking layers for temperature-sensitive cargo monitoring. EU circular economy frameworks pressure liner material sourcing toward recyclable substrates. Randstad logistics operators centralize UN certification management and documentation compliance outsourcing.
Container Liner Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the container liner market, with integrated carriers and specialized fabricators occupying distinct competitive positions. The vendor base consolidates around three strategic tiers: Mediterranean-based integrated carriers with Geneva training networks, Copenhagen-anchored operators with cadet academy pipelines, and French maritime school partnerships securing transpacific officer supply. Dominant competitive moves include strategic fleet deployment optimization and integrated logistics service bundling that unbundles after-sales technical support from unit pricing.
Among the carrier archetypes, Mediterranean Shipping Company (MSC), Maersk, and CMA CGM represent the integrated operator tier that shapes liner-compatible container asset deployment. MSC leverages its Geneva-based network to sustain officer training pipelines across Mediterranean and West African routes. Maersk anchors Copenhagen operations with integrated cadet academies in Denmark and Singapore. CMA CGM occupies a position within French maritime school partnerships that secure deck officer supply for expanding transpacific services. These carriers exemplify how licensed mariner availability bifurcates fleet deployment strategies and indirectly governs liner fill optimization protocols through vessel specification requirements.
| Leading Market Players |
|---|
| Mediterranean Shipping Company (MSC) |
| Maersk |
| CMA CGM |
| COSCO Shipping Lines |
| Hapag-Lloyd |
| Ocean Network Express |
| Evergreen Marine |
| Yang Ming Marine Transport |
| HMM |
| Others |
Supply Flow & Price Mechanics
Polyethylene-to-polypropylene substitution in pharmaceutical-grade liners simultaneously shifts supply geography toward Indian and Chinese woven fabricators and compresses pricing economics for commodity multi-layer formulations. This material pivot concentrates procurement leverage with CDSCO-certified manufacturers while eroding margins for standard chemical-grade producers locked into conventional co-extrusion capacity.
Pricing Analysis
Price spreads between Rotterdam and Ho Chi Minh City distribution points reflect FuelEU Maritime compliance cost absorption and SAMR certification friction for China-bound food-grade shipments. Three-tier pricing structure across UN-certified hazardous configurations, REACH-compliant industrial grades, and commodity agricultural specifications governs contract negotiations, with chemical manufacturers in the Rhine-Ruhr corridor least sensitive due to bundled technical support requirements. Price differentiation stems from embedded RFID tracking layers and dual EU-China certification documentation. Cost compression in standard polyethylene flat liners is intensifying because of petrochemical feedstock volatility and buyer consolidation among multinational distributors.
Supply Chain Analysis
Strategic stockpiling of resin inventories dominates liner fabricator behavior, contrasting with just-in-time preferences among pharmaceutical distributors managing temperature-sensitive active ingredient shipments. Manufacturing concentrates in China, India, and Germany, with Yangtze River Delta facilities feeding food-grade export demand and Gujarat woven polypropylene suppliers serving CDSCO-regulated pharmaceutical channels. Raw material dependencies center on crude oil derivatives for polyethylene co-extrusion, polypropylene resin for pharmaceutical tensile specifications, and bio-based polymer feedstocks for EU circular economy certification. Single-source vulnerability runs through concentrated Mediterranean officer training pipelines that govern fleet deployment velocity for liner-compatible container assets. Distribution runs through integrated logistics providers consolidating procurement for hazardous material segments while direct manufacturer relationships persist in custom engineered configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The container liner market functions as a service-attach opportunity where fill optimization software and UN certification management expand faster than physical liner unit sales. Technical support bundling and documentation compliance outsourcing now command premium positioning over commodity substrate supply.
For Market Incumbents: Compound defensive positioning through backward integration into bio-based polymer certification pathways and captive supply of REACH-compliant engineered venting geometries. Secure cadet academy pipeline partnerships in Copenhagen and Singapore to offset licensed mariner supply concentration threatening fleet deployment velocity. Invest in RFID-embedded co-extrusion capacity to preempt pharmaceutical distributor procurement consolidation.
For New Entrants and Emerging Players: Lead with recyclable substrate development targeting EU Green Deal circular economy frameworks where incumbent polyethylene fabricators face carbon intensity compliance gaps. Penetrate Vietnam's export processing zones for agricultural commodity liners through SAMR pre-certification partnerships with Yangtze River Delta logistics operators. Pursue direct-to-chemical-manufacturer relationships in the Gujarat industrial corridor bypassing consolidated distributor networks.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated logistics providers with certification management capabilities over standalone fabricators. Five-to-ten year viability hinges on FuelEU Maritime slow-steaming route proliferation extending transit times and moisture barrier specification upgrades. Target acquisition archetypes include polypropylene specialists with CDSCO traceability protocols and embedded RFID technology layers. Watch for bio-based polymer cost parity thresholds as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Polymer Supply | Captures EU circular economy certification premiums ahead of REACH substrate mandates. |
| RFID-Enabled Co-extrusion Capacity Expansion | Secures Rotterdam pharmaceutical distributor specifications for temperature-sensitive cargo monitoring. |
| Cadet Academy Partnership Investment | Offsets Mediterranean and West African licensed mariner supply concentration constraining fleet velocity. |
| Dual EU-China Certification Documentation Service | Compresses product development timelines for hazardous material and food-contact liner configurations. |
| Fill Optimization Software Development | Captures SOLAS verified gross mass documentation requirements as integrated service revenue layer. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with liner procurement managers at German chemical manufacturers, integrated logistics operators in Rotterdam and Singapore, and vessel operations directors at Mediterranean and Copenhagen-anchored carriers; and secondary validation through customs trade data, EU REACH registration databases, SAMR food-contact material filings, and SEC disclosures from listed container shipping operators. Bottom-up triangulation against top-down macroeconomic freight indices anchored volume and value estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning material grade tiers, end-use industry certification requirements, distribution channel structure, and regional regulatory cluster alignment. CAGRs derived from elasticity-adjusted freight volume correlations and liner penetration rate assumptions tied to FuelEU Maritime slow-steaming route proliferation. Industry-specific forecast inputs incorporated petrochemical feedstock price volatility indices and officer training pipeline enrollment capacity constraints.
Underlying assumptions cover sustained EU Green Deal implementation trajectory and Asia-Pacific manufacturing corridor export growth, with deviation risk concentrated in SAMR certification timeline delays and licensed mariner supply bottlenecks. Forecasts reflect these conditions with sensitivity to bio-based polymer cost parity achievement. Revision becomes warranted when FuelEU Maritime compliance cost absorption crosses thresholds triggering carrier fleet restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Food Grade Stainless Steel Container Market
Containers
Cubitainer Market
Containers
HDPE Bottles Market
Containers
Reconditioned IBC Market
Containers
Straight Sided Glass Jar Market
Containers
EPS Shippers Market
Containers
Soup Containers Market
Containers
Collapsible Crate Market
Containers
Foldable Container Market
Containers
Stackable Container Market
Containers
Twist Up Stick Container Market
Containers
Lab Storage Container Market
Containers
Thin Wall Containers Market
Containers
Child-Resistant Containers Market
Containers
Multi Cavity Tray Market
Containers
Wooden Crates Market