
 Composite Ibcs System Market | 2026-2036
Composite Ibcs System Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Ibcs System Market Outlook
Asset-light leasing models for composite IBC fleets is narrowing the capital barrier for mid-tier logistics providers. SCHÜTZ GmbH & Co. KGaA leverages its European manufacturing footprint to sustain long-term rental contracts with chemical multinationals. Mauser Packaging Solutions anchors North American demand through refurbishment networks that extend container life cycles. Greif Inc. differentiates via steel-composite hybrid designs that compete on drop-test performance in hazardous material transport.
A composite IBC system combines polymer liners, steel or aluminum cages, and composite outer shells to store and transport bulk liquids and powders typically ranging from 275 to 330 gallons. The design prioritizes stackability, chemical resistance, and collapsibility for return logistics in continuous industrial supply chains. Rigid IBC configurations dominate current volume due to their established UN certification paths for dangerous goods, while flexible IBC formats are gaining share in food-grade and agricultural applications where weight reduction drives freight economics. Hybrid IBC designs, blending collapsible frames with rigid bases, concentrate margin pools in pharmaceutical cold-chain logistics where temperature stability commands premium positioning.
EPA hazardous waste container standards and UN Model Regulations on dangerous goods transport shape product design requirements for composite IBC systems sold into North American and European chemical markets. FDA food contact material rules and EU REACH substance restrictions further filter which resin formulations and barrier coatings qualify for food, beverage, and pharmaceutical end uses. Stakeholders must monitor evolving extended producer responsibility frameworks in Germany and California, as these jurisdictions test deposit-return mechanisms that could restructure ownership models across the IBC value chain.
Market Dynamics
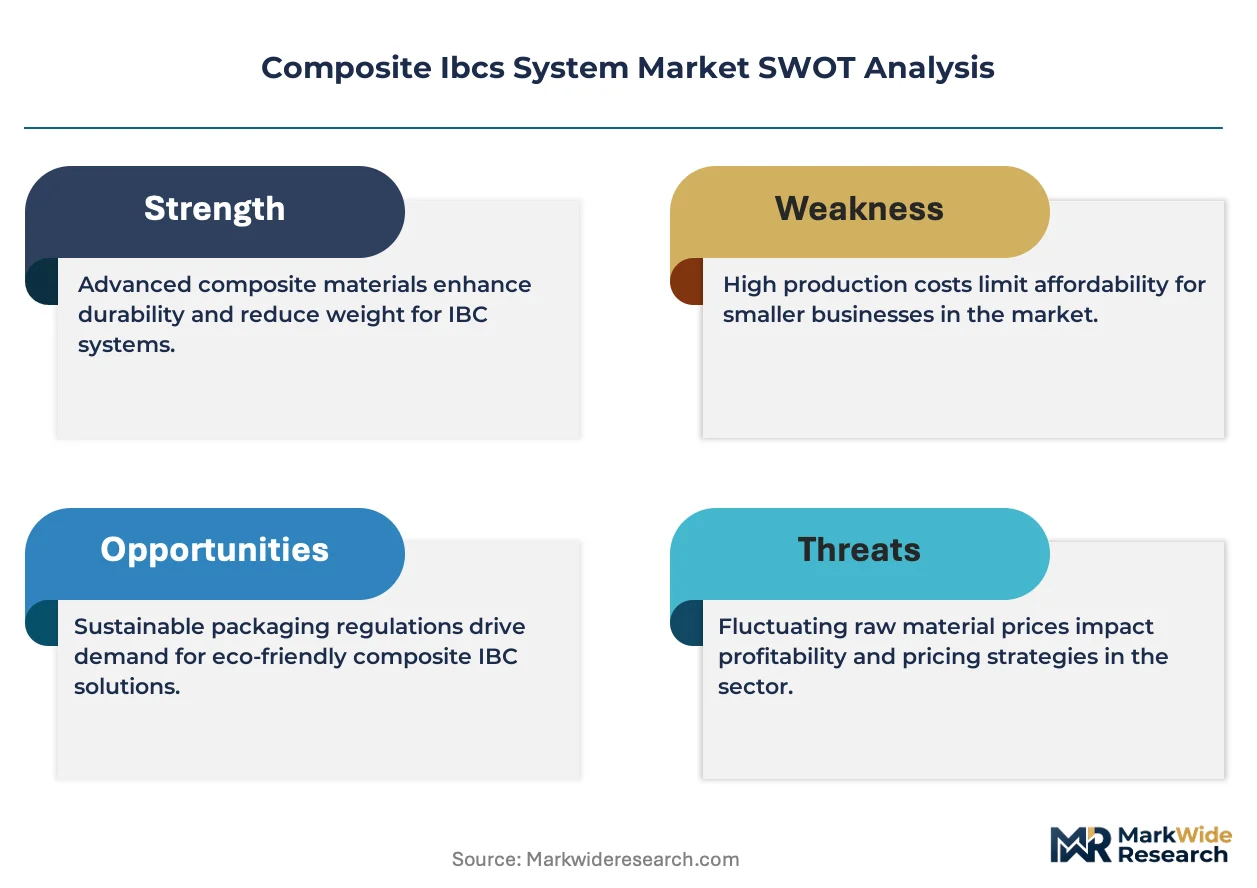
Asset-light leasing models for composite IBC fleets are compressing capital requirements for mid-tier logistics providers, while EU REACH material compliance rules and EPA container regulations reshape ownership structures across chemical supply chains.
Growth Catalysts
- EU REACH substance restrictions:Chemical manufacturers in Germany and the United States are expanding reusable bulk packaging programs to meet material compliance rules, accelerating fleet turnover toward certified composite systems.
- Food-grade composite IBC leasing networks:North American industrial corridors are witnessing displacement of single-use steel drums as food processors adopt closed-loop container pooling for liquid ingredients and edible oils.
- UN Model Regulations certification paths:Rigid IBC configurations with established dangerous goods approvals are capturing hazardous material transport volumes previously handled by uncertified alternatives.
Market Restraints
- Polymer resin cost volatility:Fluctuations in high-density polyethylene and polypropylene feedstock prices compress margins for liner manufacturers serving price-sensitive agricultural chemical segments.
- Steel cage supply concentration:Galvanized steel cage fabrication concentrates in Chinese and Indian metalworking clusters, exposing European and North American IBC assemblers to tariff and shipping cost shocks.
- Flexible IBC technical limitations:UN certification gaps for flexible intermediate bulk containers in hazardous goods transport restrict their penetration of chemical markets despite freight weight advantages.
Strategic Opportunities
- Pharmaceutical cold-chain logistics:Hybrid IBC designs blending collapsible frames with rigid bases command premium positioning where temperature stability requirements outstrip standard container capabilities.
- California extended producer responsibility frameworks:Deposit-return mechanism pilots in Germany and California could restructure ownership models, creating first-mover advantages for leasing-network operators with refurbishment infrastructure.
- RFID-enabled fleet tracking convergence:Integration of polymer liner barrier technology with IoT sensor networks opens outcome-based pricing models for chemical manufacturers seeking real-time container location and condition data.
Industry Challenges
- UN certification timeline compression:Dangerous goods testing protocols for new composite formulations require 12-18 month approval cycles, delaying product launches and freezing R&D pipelines.
- Legacy steel drum integration friction:Food and beverage manufacturers face capital-intensive facility modifications to accommodate composite IBC handling equipment incompatible with existing drum-filling lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Ibcs System Market |
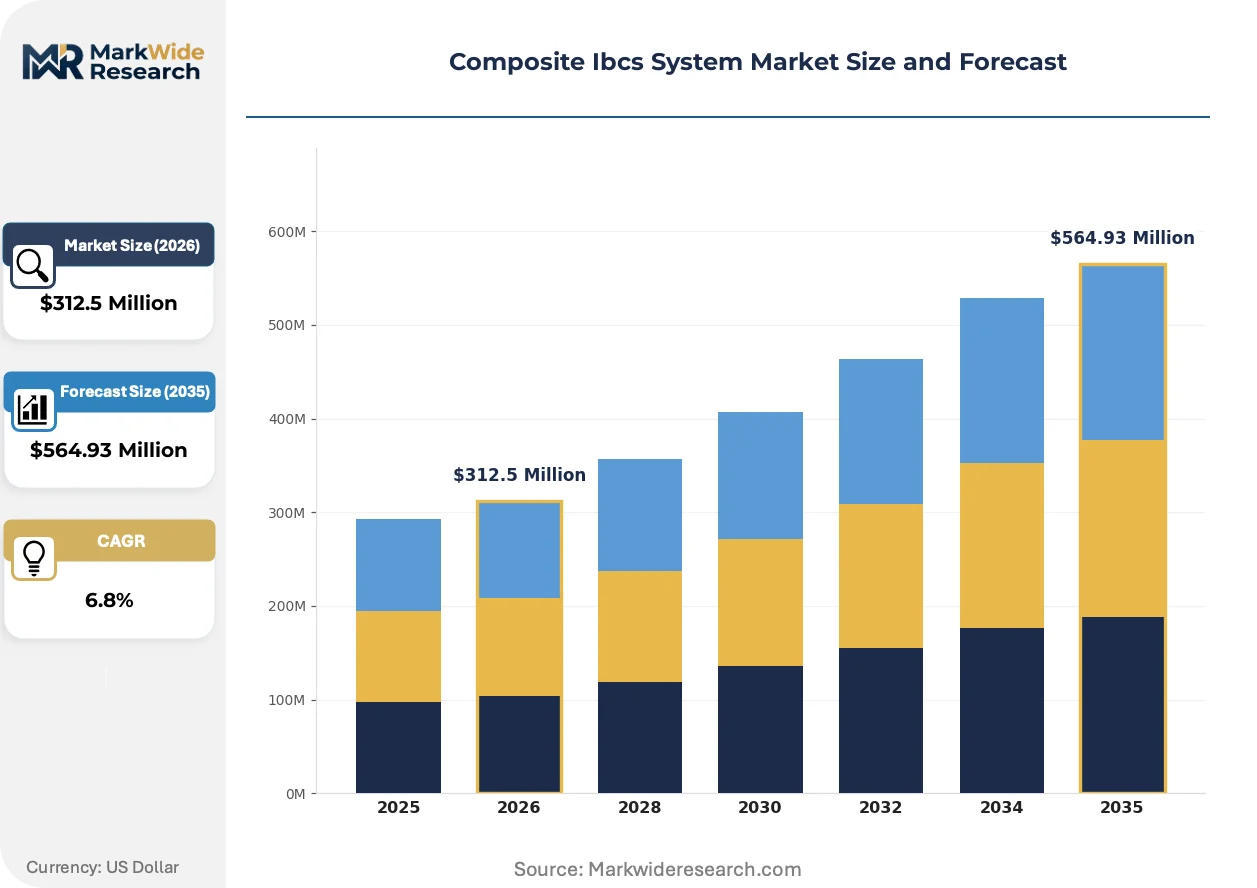
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible IBC, Rigid IBC, Hybrid IBC, Collapsible IBC End User: Chemicals, Food & Beverage, Pharmaceuticals, Agriculture Material: Plastic, Steel, Aluminum, Composites Distribution Channel: Online, Direct Sales, Retail, Distributors |
| Companies Covered | SCHÜTZ GmbH & Co. KGaA, Mauser Packaging Solutions, Greif Inc., Time Technoplast Ltd., Hoover CS, Berry Global Inc., Snyder Industries, Brambles Ltd, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Ibcs System Market Strategic Shifts
Barrier-coated polymer liners and RFID-enabled fleet tracking are compressing inspection cycles and enabling predictive maintenance models across chemical and food-grade container pools.
Multi-layer co-extruded polymer liners with ethylene vinyl alcohol barrier layers are rendering obsolete single-wall high-density polyethylene constructions in oxygen-sensitive food and pharmaceutical applications. Specialty chemical manufacturers in Switzerland and the Netherlands are specifying these constructions for vitamin and additive transport. The technology is rendering obsolete annual liner replacement schedules through extended service life certification.
EU Green Deal packaging waste directives are mandating minimum recycled content thresholds for plastic transport packaging sold into member states. Composite IBC producers are reformulating outer shell resins to incorporate post-industrial regrind without compromising UN drop-test performance. German chemical distributors are responding by consolidating purchasing with suppliers holding EMAS environmental management certification.
Outcome-based container service contracts are displacing unit-sale purchasing in North American food ingredient supply chains. Large-scale bakery and dairy processors are unbundling container ownership from logistics services, paying per-use fees that include washing, inspection, and reverse logistics. This shift concentrates procurement authority with three national leasing networks operating USDA-inspected wash facilities.
Composite Ibcs System Market Segmentation
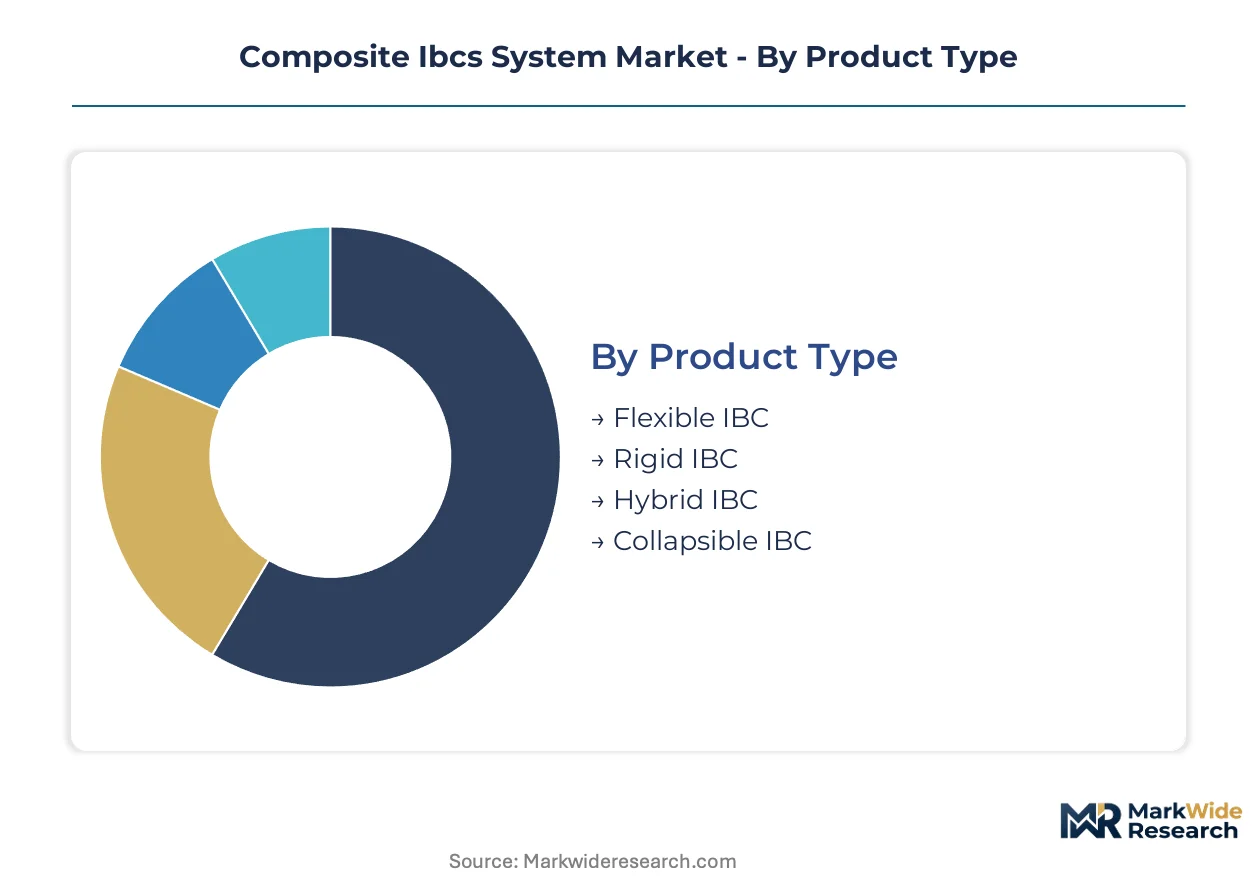
Composite IBC system segmentation reveals how container design, material construction, and channel economics fragment purchasing authority across chemical, food, and pharmaceutical supply chains. Understanding these splits exposes where leasing networks concentrate fleet investment versus where direct sales retain margin.
Product Type:
Cost tier differentiation separates capital-intensive rigid configurations from collapsible formats optimized for return freight economics.
- Rigid IBC:Steel or aluminum cages encase polymer liners in fixed-wall constructions certified under UN Model Regulations for dangerous goods transport. Chemical manufacturers in Germany and the United States specify these for solvent and acid handling where drop-test performance governs liability exposure.
- Hybrid IBC:Blends collapsible polymer frames with rigid base structures to balance stackability with empty-container compression. Pharmaceutical cold-chain logistics in Switzerland and the Netherlands command premium positioning for temperature-stable vaccine transport where standard containers fail.
- Flexible IBC:Woven polypropylene or polyethylene constructions reduce tare weight for agricultural chemical and food-grade powder handling where freight cost dominates total logistics spend.
- Collapsible IBC:Foldable sidewall designs cut return shipping volume by 70 percent for food ingredient pooling networks operating across North American industrial corridors.
Rigid IBC commands the established base. The steepest expansion runs through Hybrid IBC.
End User:
Application severity drives material specification divergence, with hazardous chemical transport imposing certification barriers that food and agricultural segments escape.
- Chemicals:Acid, solvent, and specialty chemical handling requires UN-certified constructions with ethylene vinyl alcohol barrier liners. EU REACH substance restrictions and EPA container regulations force fleet turnover toward reusable composite systems in German and US manufacturing clusters.
- Food & Beverage:Liquid ingredient and edible oil transport demands FDA food contact material compliance plus USDA-inspected wash protocols. North American bakery and dairy processors are unbundling container ownership from logistics services through per-use leasing contracts.
- Pharmaceuticals:Vitamin, additive, and vaccine transport specifies multi-layer co-extruded liners with oxygen barriers. Swiss and Dutch manufacturers lead specification of extended service life certifications that eliminate annual liner replacement.
- Agriculture:Fertilizer and pesticide handling tolerates single-wall polyethylene constructions where polymer resin cost volatility compresses margins for price-sensitive growers.
Chemicals anchors procurement volume. Food & Beverage is climbing the fastest as steel drum displacement accelerates.
Material:
Supply concentration for steel cage fabrication in Chinese and Indian metalworking clusters exposes assemblers to tariff shocks, reshaping material sourcing strategy.
- Plastic:High-density polyethylene and polypropylene liners dominate food-grade and agricultural applications where chemical resistance and cleanability outweigh structural load requirements. EU Green Deal packaging waste directives are mandating minimum recycled content thresholds for outer shell resins.
- Steel:Galvanized cage constructions provide UN-certified drop-test performance for hazardous material transport. German chemical distributors are consolidating purchasing with EMAS-certified suppliers to meet environmental management requirements.
- Aluminum:Lightweight cage alternatives reduce tare weight for air freight and premium logistics segments where transport cost per kilogram governs mode selection.
- Composites:Glass-reinforced polymer outer shells blend chemical resistance with impact durability for pharmaceutical and specialty chemical applications requiring extended service intervals.
Plastic captures volume leadership. Composites are gaining share fastest in premium pharmaceutical cold-chain positioning.
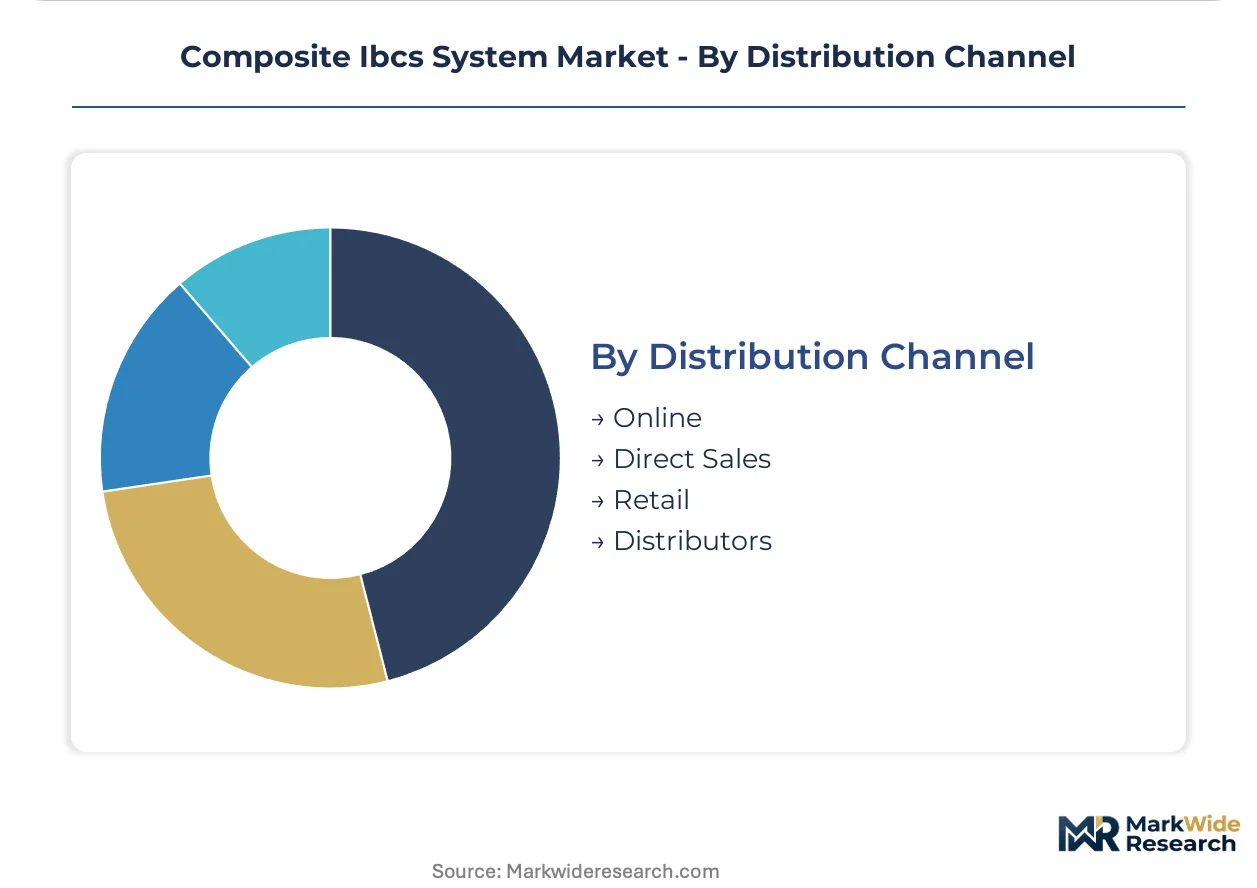
Distribution Channel:
Customer scale and purchase frequency determine whether container procurement flows through direct manufacturer relationships or intermediated distributor networks.
- Direct Sales:Long-term rental contracts with chemical multinationals and national food processors bypass channel margin. SCHÜTZ GmbH & Co. KGaA leverages its European manufacturing footprint to sustain these relationships.
- Distributors:Regional chemical and agricultural supply houses aggregate fragmented demand from mid-tier processors lacking fleet scale for direct negotiation. Mauser Packaging Solutions anchors North American refurbishment networks through this channel.
- Online:E-procurement platforms serve spot purchasing for replacement liners and accessories where standard specifications eliminate technical consultation.
- Retail:Limited to small-volume agricultural and food service applications where single-unit purchases bypass leasing economics entirely.
Direct Sales holds the revenue base. Distributors are expanding fastest as mid-tier logistics providers compress capital barriers through asset-light leasing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH substance restrictions and EPA container regulations are restructuring fleet ownership patterns across chemical manufacturing corridors. Germany and the United States are expanding reusable bulk packaging programs under compliance mandates. Food-grade composite IBC leasing networks are displacing single-use steel drums in North American industrial clusters.
United States
EPA hazardous waste container standards govern dangerous goods transport certification for rigid IBC configurations. Food processors in the Midwest industrial corridor are unbundling container ownership through per-use leasing contracts with USDA-inspected wash facilities. Chicago and Detroit chemical distributors are consolidating procurement with suppliers meeting extended producer responsibility frameworks.
Germany
EU REACH material compliance rules accelerate fleet turnover toward certified composite systems among specialty chemical manufacturers. EMAS environmental management certification filters supplier selection for outer shell resin formulations incorporating post-industrial regrind. The Rhine-Ruhr industrial basin anchors refurbishment network investment for closed-loop container pooling.
China
GB standards for dangerous goods packaging shape UN certification paths for steel cage and polymer liner assemblies. Polymer resin cost volatility compresses margins for agricultural chemical segments in Shandong and Jiangsu manufacturing clusters. NMPA regulations on pharmaceutical transport packaging drive specification of multi-layer co-extruded barrier liners.
Switzerland
Swissmedic pharmaceutical transport requirements command premium positioning for hybrid IBC designs with temperature stability certification. Vitamin and additive manufacturers in Basel specify extended service life certifications that eliminate annual liner replacement schedules. The Swiss chemical corridor leads adoption of RFID-enabled fleet tracking for real-time container condition monitoring.
Netherlands
EU Green Deal packaging waste directives mandate minimum recycled content thresholds for plastic transport packaging sold into member states. Rotterdam chemical distributors are consolidating purchasing with EMAS-certified suppliers for outer shell resin formulations. The Port of Rotterdam logistics hub concentrates food-grade composite IBC leasing network operations for edible oil transport.
Composite Ibcs System Market Competitive Environment
Channel-controlling players compete with product-specialist players across three structural tiers. Leasing-network operators with refurbishment infrastructure occupy the premium tier, capturing long-term rental contracts through asset-light service models. Manufacturing-scale assemblers with captive steel cage supply sit in the mid-tier, optimizing unit economics on volume production. Regional distributors aggregate fragmented agricultural and mid-tier chemical demand through spot purchasing relationships. M&A activity concentrates among leasing-network operators acquiring wash facility assets, while technology licensing agreements proliferate around RFID-enabled fleet tracking systems.
Within the European manufacturing tier, SCHÜTZ GmbH & Co. KGaA exemplifies the long-term rental contract archetype anchored to continental production footprints. Mauser Packaging Solutions occupies a position among North American refurbishment-network operators extending container life cycles through distributor-channel relationships. Greif Inc. represents the hybrid-design specialist archetype competing on drop-test performance differentiation in hazardous material transport segments.
| Leading Market Players |
|---|
| SCHÜTZ GmbH & Co. KGaA |
| Mauser Packaging Solutions |
| Greif Inc. |
| Time Technoplast Ltd. |
| Hoover CS |
| Berry Global Inc. |
| Snyder Industries |
| Brambles Ltd |
| DS Smith |
| Others |
Value Chain & Pricing Dynamics
Steel cage supply concentration in Chinese and Indian metalworking clusters exposes European and North American IBC assemblers to tariff and shipping cost shocks, compressing margins for mid-tier producers while amplifying pricing power for vertically integrated manufacturers with captive cage fabrication. This risk vector widens spreads between premium UN-certified rigid configurations and price-sensitive agricultural segments, while reshaping sourcing strategies toward regional steel suppliers and alternative cage materials.
Pricing Analysis
Certification level under UN Model Regulations and FDA food contact standards creates the primary spread between premium hazardous-material constructions and economy agricultural tiers. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by barrier liner technology, steel gauge, and refurbishment service bundling. Cost compression in agricultural segments is intensifying because polymer resin feedstock volatility transfers directly to single-wall polyethylene constructions. Food processors and pharmaceutical manufacturers exhibit lowest price sensitivity, prioritizing compliance documentation and temperature stability over unit cost.
Supply Chain Analysis
High-density polyethylene and polypropylene resin feedstocks draw from petrochemical complexes concentrated in the United States, China, and the Middle East, with polymer liner fabrication anchored in German and US manufacturing corridors. Galvanized steel cage supply rests on metalworking clusters in China and India, while aluminum alternatives source from Canadian and Australian smelters. Single-source vulnerability concentrates in Chinese steel cage exports exposed to tariff escalation. Distribution runs through direct manufacturer relationships for chemical multinationals and national leasing networks, with regional distributors serving fragmented agricultural demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three national food-grade leasing networks operating USDA-inspected wash facilities, consolidating procurement authority and compressing channel margins for container manufacturers without refurbishment infrastructure.
For Market Incumbents: Harden certification moats around UN Model Regulations and FDA food contact compliance to defend against emerging Asian manufacturers with lower-cost steel cage supply. Deepen backward integration into polymer liner extrusion to capture margin from resin volatility, while expanding refurbishment network density in the Midwest industrial corridor to lock in per-use leasing contracts with bakery and dairy processors. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical cold-chain logistics where hybrid IBC designs command premium positioning and incumbent capacity is constrained. Target Swiss and Dutch vitamin manufacturers specifying extended service life certifications, leveraging temperature stability requirements as a technical barrier to volume leaders focused on commodity chemical segments. For Investors and Strategic Acquirers: Refurbishment-network operators with USDA-inspected facilities and RFID-enabled fleet tracking infrastructure represent the most defensible acquisition archetype in a market shifting toward outcome-based service contracts. Monitor California extended producer responsibility framework implementation as the inflection signal for deposit-return mechanism adoption that would restructure ownership models and concentrate value in leasing-network operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Liner Extrusion | Captures margin from HDPE resin volatility while securing FDA-compliant food-grade supply for leasing networks. |
| Refurbishment Network Expansion | Extends container life cycles and anchors per-use pricing models with USDA-inspected wash facilities in North American corridors. |
| RFID-Enabled Fleet Tracking Deployment | Opens outcome-based contracts with chemical manufacturers seeking real-time location and condition data. |
| Hybrid IBC Design Development | Commands premium positioning in Swiss and Dutch pharmaceutical cold-chain logistics where temperature stability governs selection. |
| EMAS Environmental Certification Investment | Filters supplier selection for German chemical distributors consolidating purchasing under EU Green Deal recycled content mandates. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from packaging manufacturers, EU REACH substance restriction databases, and UN dangerous goods transport records. Primary interviews engaged plant managers at chemical manufacturing facilities, procurement leads at food processors, distribution channel partners in agricultural supply, and technical R&D directors at liner extrusion operations. Bottom-up volume estimates triangulate against top-down market sizing derived from production capacity disclosures and fleet utilization metrics reported by leasing-network operators.
Forecast inputs include polymer resin price indices, steel cage fabrication capacity by geography, UN certification approval timelines, and regulatory implementation schedules for extended producer responsibility frameworks. Segmentation modeling spans product type, end-use industry, material construction, and distribution channel, with regional clusters further split by regulatory jurisdiction. CAGRs derive from regression analysis against historical fleet turnover rates and substitution patterns from steel drums to composite IBC systems across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing, trade tariff levels, or freight shipping costs would shift the trajectory of manufacturing cost structures and regional competitiveness. Cross-checking against customs import data for steel cage assemblies and polymer liner shipments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Intermediate Bulk Container Liner Market
Containers
Essential Oil Containers Market
Containers
Sample Containers Market
Containers
Straight Sided Glass Jar Market
Containers
Oblong Container Market
Containers
PET Hinged Containers Market
Containers
PET Containers Market
Containers
North America Insulated Shipping Containers Market
Containers
Global Multi Pack Carriers Market
Containers
Global Styrene Compartment Boxes Market
Containers
Child-Resistant Containers Market
Containers
Food Grade Stainless Steel Container Market
Containers
HDPE Containers Market
Containers
Half Height Containers Market
Containers
Durable Insulated Containers Market
Containers
Wooden Barrels Market