
 Thermoformed Containers Market | 2026-2036
Thermoformed Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoformed Containers Market Outlook
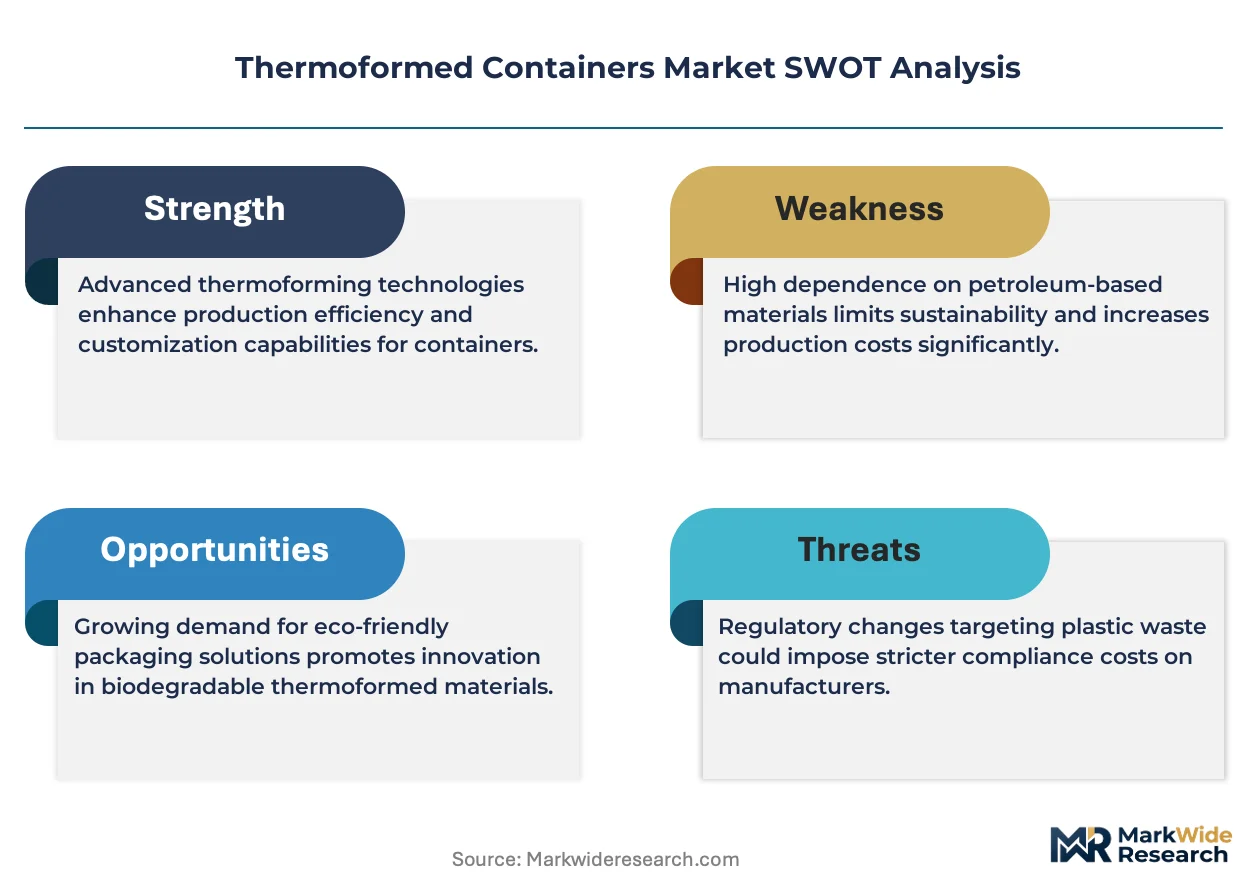
EU REACH compliance is realigning the cost-of-entry calculus for new thermoformed container producers, forcing reformulation investments that favor well-capitalized incumbents. Pactiv LLC leverages captive resin sourcing and integrated sheet extrusion to sustain margin stability under volatile polymer pricing. Dart Container Corporation anchors North American foodservice demand through proprietary mold design capabilities and high-volume manufacturing scale. Amcor plc differentiates via multi-layer barrier technology leadership and global pharmaceutical-grade certification.
Thermoformed containers are rigid or semi-rigid packaging structures produced by heating thermoplastic sheets and forming them over molds via vacuum or pressure, typically yielding wall thicknesses from 0.005 to 0.060 inches for applications requiring structural integrity at low unit weight. The process serves primary industrial purposes across food preservation, sterile medical distribution, and sensitive electronics protection where cost-per-unit and customization speed outweigh injection molding capital intensity. Clamshells and trays dominate current volume, with clamshells capturing premium produce and retail-ready protein segments where tamper-evidence and shelf visibility command price premiums. PET material grades are expanding fastest as brand owners and retailers mandate post-consumer recycled content thresholds that polystyrene struggles to satisfy.
FDA food contact regulations, EU EFSA migration limits, and EPA resin production emissions standards collectively shape permissible material inputs, additive packages, and end-of-life labeling claims across the value chain. These frameworks elevate compliance costs but simultaneously create defensible positions for producers with certified recycling streams and documented chain-of-custody protocols. Stakeholders must monitor evolving extended producer responsibility schemes and recycled content mandates to anticipate which material-platform investments will retain competitive validity.
Market Dynamics
EU REACH compliance is realigning the cost-of-entry calculus for new thermoformed container producers, forcing reformulation investments that favor well-capitalized incumbents with certified recycling streams and documented chain-of-custody protocols.
Growth Catalysts
- EU Single-Use Plastics Directive:The mandate for recycled content thresholds is accelerating material transitions toward rPET and bio-based alternatives across food packaging applications.
- Quick-service restaurant chains:These foodservice operators are expanding thermoformed container procurement for grab-and-go formats, driving volume concentration in disposable rigid packaging.
- Multi-layer barrier technology:Advances in co-extrusion and adhesive lamination are extending shelf life for sensitive proteins, opening premium segments previously served by glass or metal.
Market Restraints
- Polymer price volatility:Virgin PET and polystyrene resin costs fluctuate with crude oil indices, compressing margins for converters without captive resin sourcing or long-term supply contracts.
- German packaging waste regulations:Extended producer responsibility schemes in this key demand cluster impose compliance burdens that smaller producers struggle to absorb.
- Polystyrene substitution ceiling:Technical limitations in achieving equivalent clarity and barrier performance with recycled content are constraining material transitions in certain cold-chain applications.
Strategic Opportunities
- Pharmaceutical-grade certification:EMA and FDA sterile packaging requirements for medical device distribution represent an underpenetrated vertical with pricing premiums above foodservice norms.
- Electronics protection segments:Thermoformed ESD-safe trays for semiconductor and component shipping offer growth as supply chains reshore sensitive manufacturing.
- Digital printing integration:Convergence of thermoforming with in-mold labeling and direct-to-shape decoration enables brand owners to eliminate secondary labeling operations.
Industry Challenges
- Tooling engineer scarcity:Mold design and CNC programming expertise for complex multi-cavity tooling is concentrating at a handful of specialized job shops, extending new product development timelines.
- Recycled content verification:Mass-balance accounting and third-party certification for post-consumer rPET streams require dedicated quality infrastructure that mid-tier converters lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoformed Containers Market |
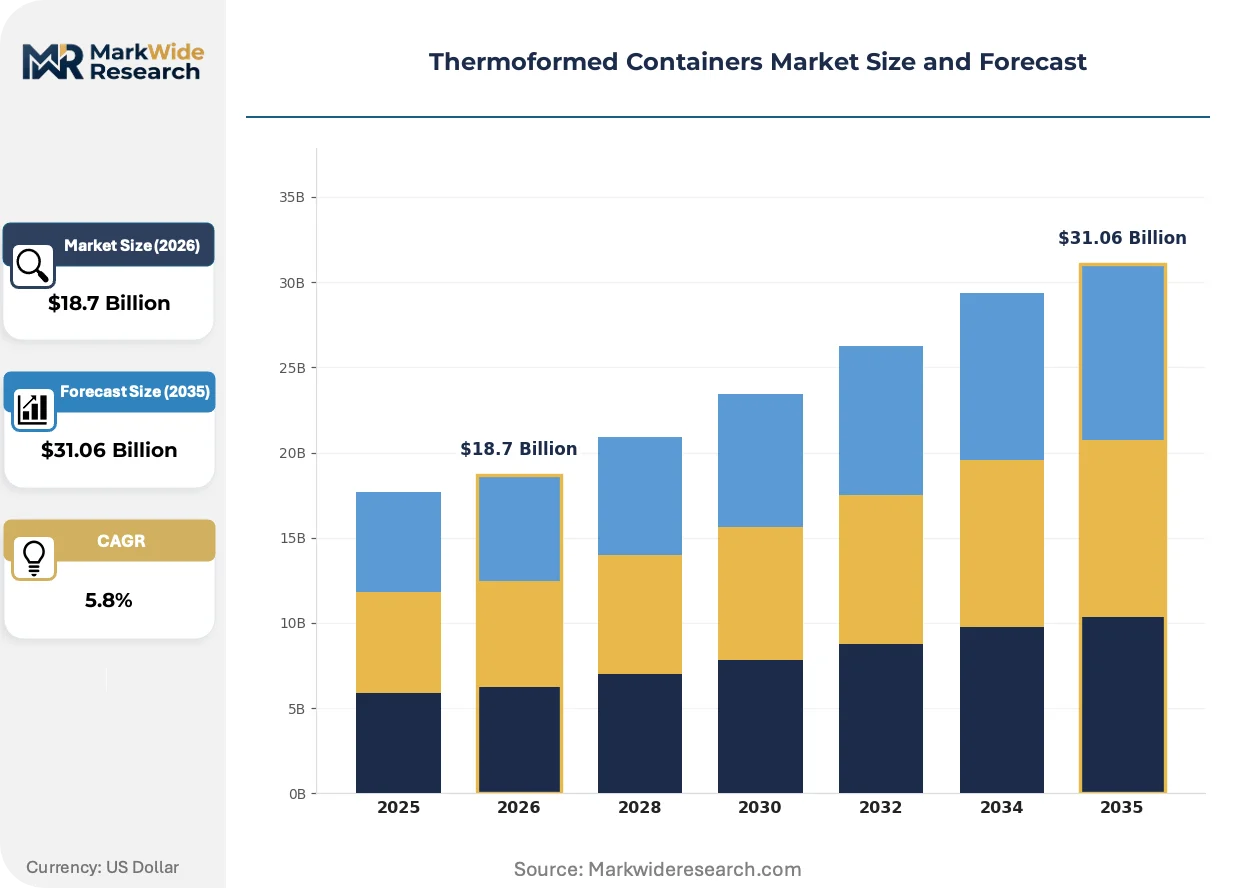
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Clamshells, Trays, Lids Material: Polyethylene, Polypropylene, Polystyrene, PET Application: Food Packaging, Medical Supplies, Electronics, Consumer Goods End User: Food Industry, Healthcare, Retail, Manufacturing |
| Companies Covered | Pactiv LLC, Dart Container Corporation, Amcor plc, Berry Global Inc., Anchor Packaging, Sonoco Products Company, Huhtamaki Oyj, Sealed Air Corporation, Placon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoformed Containers Market Strategic Shifts
Material science advances and regulatory stringency are compressing the viable technology set for thermoformed containers, privileging platforms that satisfy both performance specifications and end-of-life accountability requirements.
Mono-material PET structures with built-in oxygen scavenger layers are overtaking multi-material laminates in fresh protein packaging. Retailers and brand owners in Germany and France are specifying these formats to meet EU recyclability labeling mandates. The shift is compressing demand for ethylene vinyl alcohol coextrusions that complicate mechanical recycling streams.
REACH substance restrictions on phthalate plasticizers and certain stabilizers are forcing reformulation of legacy PVC and polystyrene grades used in medical and food-contact applications. Compounders serving the thermoforming industry are accelerating bio-based plasticizer development. Medical device distributors in the US and EU are qualifying alternative material platforms ahead of anticipated FDA and EFSA migration limit updates.
Quick-service restaurant procurement departments are consolidating supplier bases and demanding direct mill-to-converter chain-of-custody documentation for recycled content claims. This buying-pattern compression is disintermediating distributors who cannot provide batch-level certification. The phenomenon is most visible in US coastal markets where municipal composting infrastructure and corporate sustainability targets intersect.
Thermoformed Containers Market Segmentation
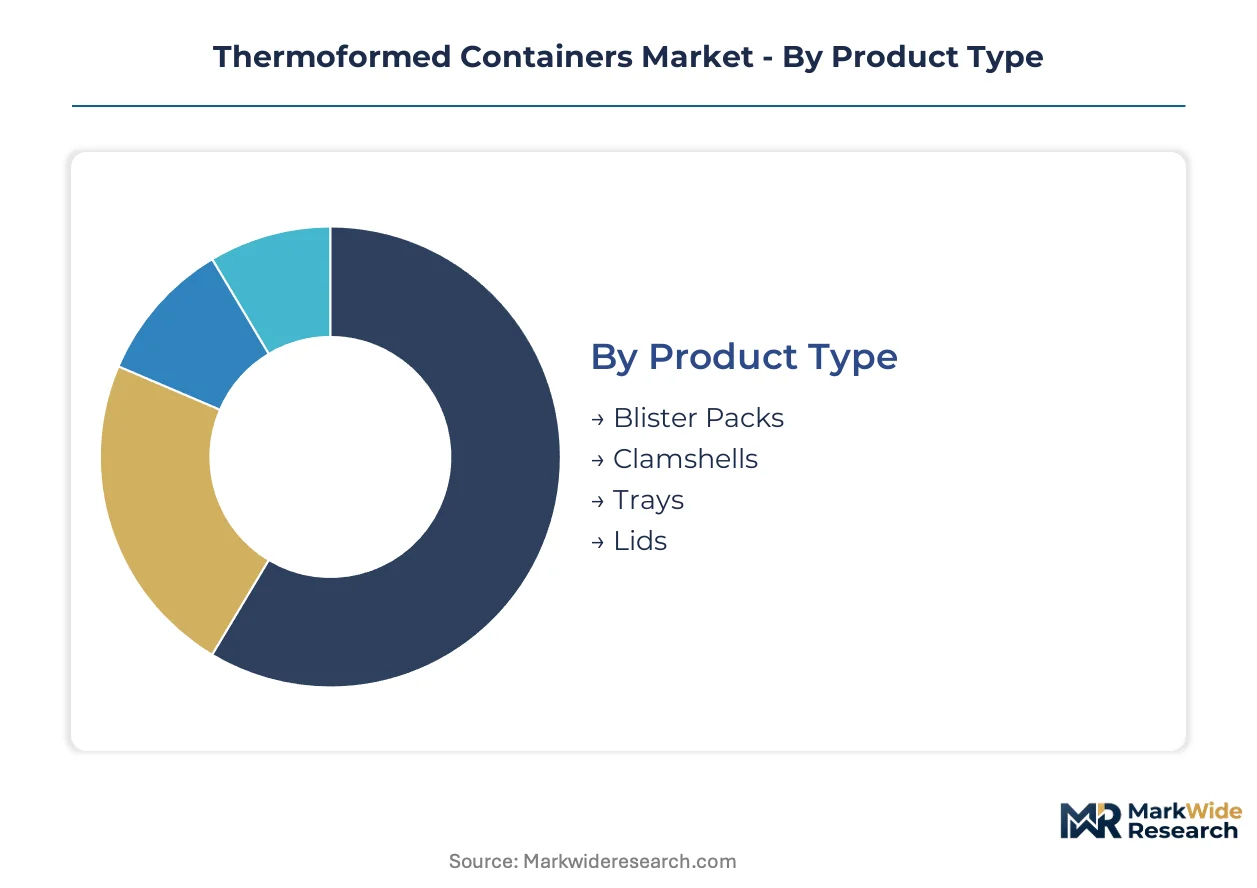
Thermoformed container producers face divergent technical specifications across end-use verticals, with food packaging demanding oxygen barrier performance while medical applications prioritize sterile integrity. Material-platform investments and mold design capabilities must align to specific segment requirements rather than generic volume production.
Product Type:
Replacement cycles for legacy injection-molded packaging are accelerating thermoformed format adoption as brand owners seek lighter-weight alternatives with faster tooling turnaround.
- Clamshells:These hinged, tamper-evident structures integrate living hinges and snap closures for retail-ready produce and protein display. Quick-service restaurant chains in Germany and France are specifying clamshell formats for grab-and-go salads and sandwiches to meet EU Single-Use Plastics Directive recyclability mandates.
- Trays:Shallow, structural platforms with formed cavities for product nesting and stacking strength dominate institutional foodservice and medical kit packaging. Healthcare distributors in the US are transitioning from polystyrene to PET tray formats to satisfy FDA food contact migration limits and hospital sustainability procurement criteria.
- Blister Packs:Clear, formable cavities sealed to printed backing cards provide unit-dose protection for pharmaceuticals and small electronics.
- Lids:Thermoformed covers with peripheral sealing flanges complete tray systems for modified atmosphere packaging applications.
Trays sit at the top of the volume ranking, with clamshells climbing the fastest as retail-ready formats displace bulk packaging in fresh food segments.
Material:
Cost tier stratification separates commodity resin grades from certified recycled content streams that command procurement premiums.
- PET:Amorphous and crystallizable grades deliver clarity, barrier performance, and compatibility with post-consumer recycled content streams. EU EFSA migration limits and retailer recycled content thresholds are concentrating demand growth in Germany, where food processors require documented chain-of-custody certification for rPET incorporation.
- Polystyrene:General-purpose and high-impact grades offer low material cost and excellent thermoforming response for cold-chain dairy and deli applications. Technical limitations in achieving equivalent clarity with recycled content are constraining transitions in certain medical and food-contact segments where FDA regulations permit legacy formulations.
- Polypropylene:Oriented and cast grades provide heat resistance for microwaveable and hot-fill applications.
- Polyethylene:Low-density and linear low-density grades serve flexible lid and shallow tray formats with moderate barrier requirements.
PET leads absolute volume, with bio-based alternatives gaining share fastest as REACH substance restrictions accelerate material platform transitions.
Application:
Customer type concentration shapes margin profiles, with pharmaceutical-grade certification enabling pricing premiums above commodity foodservice norms.
- Food Packaging:Modified atmosphere and vacuum-skin formats extend shelf life for fresh proteins, produce, and prepared meals. Quick-service restaurant procurement consolidation in US coastal markets is demanding direct mill-to-converter chain-of-custody documentation for recycled content claims.
- Medical Supplies:Sterile barrier systems for device distribution require EMA and FDA compliance with documented validation protocols. Underpenetration relative to glass and metal alternatives creates expansion opportunity as supply chains reshore sensitive manufacturing.
- Electronics:ESD-safe thermoformed trays protect semiconductors and components during shipping and handling.
- Consumer Goods:Visible packaging for cosmetics, hardware, and household products prioritizes shelf presence and theft deterrence.
Food Packaging dominates shipment value, with Medical Supplies expanding most quickly as regulatory certification barriers limit competitive entry.
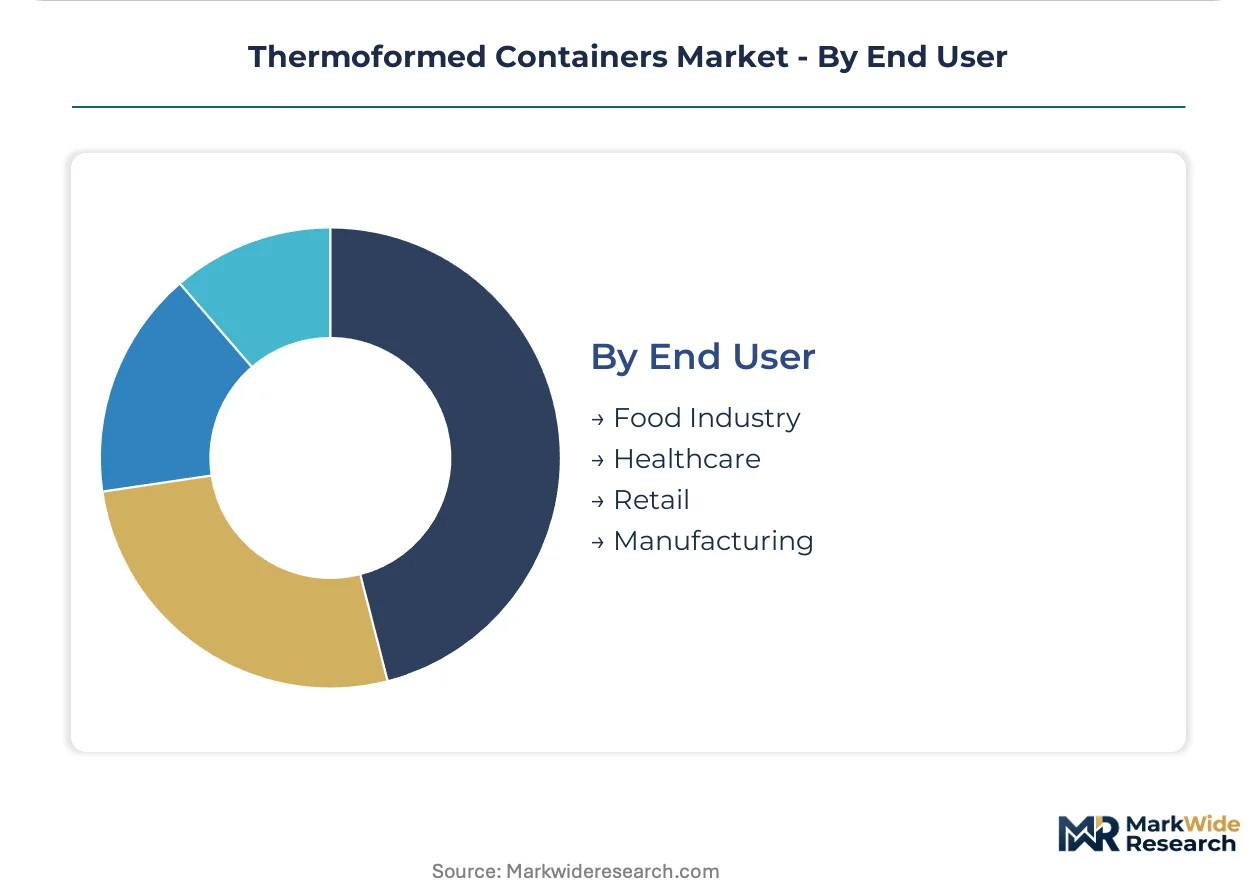
End User:
Supply concentration among integrated converters with captive sheet extrusion distinguishes volume tiers from specialty producers serving certified segments.
- Food Industry:Processors, distributors, and foodservice operators specify format, material, and barrier performance to match distribution chain requirements. Extended producer responsibility schemes in Germany impose compliance burdens that favor well-capitalized incumbents with certified recycling infrastructure.
- Healthcare:Hospital systems, medical device manufacturers, and pharmaceutical distributors mandate sterile integrity and migration-compliant material inputs. FDA and EMA packaging regulations elevate quality infrastructure requirements that mid-tier converters struggle to satisfy.
- Retail:Supermarket chains and mass merchandisers drive standardization toward mono-material recyclable formats.
- Manufacturing:Industrial component producers utilize thermoformed dunnage and work-in-process trays for factory-floor logistics.
The Food Industry anchors demand volume, with Healthcare posting the steepest expansion trajectory as sterile packaging requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermoforming expertise concentrates in regions with mature plastics processing infrastructure and stringent packaging regulations that reward technical compliance capabilities.
Germany
Food processing clusters around Munich and Hamburg drive demand for rPET-certified thermoformed trays. ECHA REACH substance restrictions force reformulation investments that favor producers with documented chain-of-custody protocols. The Rhine-Ruhr industrial corridor hosts integrated converters combining captive sheet extrusion with high-volume thermoforming operations.
United States
Quick-service restaurant procurement consolidation in California and New York Metro demands direct mill-to-converter certification for recycled content claims. FDA food contact migration limits and EPA resin production emissions standards shape permissible material inputs. The Midwest manufacturing belt around Chicago anchors thermoformed container production for foodservice and medical distribution.
China
Electronics manufacturing reshoring in the Yangtze River Delta and Pearl River Delta generates demand for ESD-safe thermoformed trays. SAMR packaging standards and GB quality certifications elevate compliance requirements for export-oriented producers. Shenzhen and Suzhou industrial zones concentrate mold fabrication and CNC programming capabilities for complex multi-cavity tooling.
France
Retail-ready protein packaging specifications from Carrefour and Intermarché drive adoption of mono-material PET clamshells. ANSM medical device packaging regulations and EU EFSA migration limits constrain material platform choices. The Île-de-France region around Paris hosts pharmaceutical distributors qualifying alternative material platforms ahead of anticipated regulatory updates.
India
FSSAI food safety standards and rising quick-service restaurant penetration in Mumbai and Bangalore expand thermoformed container procurement. BIS certification requirements for food-contact materials create entry barriers for unqualified imports. The Gujarat industrial corridor hosts emerging converters serving domestic food processors and export markets.
Thermoformed Containers Market Competitive Environment
The competitive structure tilts toward integrated converters with captive resin sourcing and certified recycling infrastructure. Tiered differentiation separates premium barrier-technology specialists from commodity volume producers. Three archetypes dominate: integrated resin-to-container operators, multi-layer barrier technology leaders, and regional foodservice-focused fabricators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as producers secure rPET supply agreements and pharmaceutical-grade certification.
Among North American integrated operators, Pactiv LLC and Dart Container Corporation exemplify the scale-driven archetype with upstream control over sheet extrusion. Amcor plc occupies a position representing multi-layer barrier technology leadership and global certification breadth. These three anchors illustrate how capital intensity and regulatory compliance capabilities stratify competitive positioning across foodservice, medical, and electronics protection segments.
| Leading Market Players |
|---|
| Pactiv LLC |
| Dart Container Corporation |
| Amcor plc |
| Berry Global Inc. |
| Anchor Packaging |
| Sonoco Products Company |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| Placon Corporation |
| Others |
Value Chain & Pricing Dynamics
Mono-material PET platform transitions are compressing converter margins while simultaneously concentrating supply among integrated resin-to-container operators with captive sheet extrusion capabilities. This technology shift rewards producers in Germany and the US Midwest who have secured long-term rPET supply agreements ahead of EU EFSA migration limit enforcement.
Pricing Analysis
Container pricing splits between bundled and unbundled service models. Three-tier pricing structure across pharmaceutical-grade certified, foodservice-standard, and commodity economy levels reflects certification burden and barrier complexity. Pricing pressure stems from polymer price volatility tied to crude oil indices, compressing margins for converters without captive resin sourcing. Quick-service restaurant chains exhibit highest price sensitivity through consolidated procurement, while pharmaceutical distributors accept premium pricing for EMA-validated sterile barrier systems.
Supply Chain Analysis
Virgin PET and rPET pellet supply rests on integrated resin producers in the US, Germany, and China. Key inputs include thermoforming-grade sheet extrusion, multi-cavity aluminum molds, and oxygen scavenger additive packages. Single-source vulnerability concentrates in specialized mold fabrication shops around Shenzhen and Chicago. Distribution runs through direct mill-to-converter channels for certified recycled content claims, bypassing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoformed container production operates as a geographic-arbitrage play where EU REACH compliance costs in Germany create margin expansion opportunities for US-based exporters serving coastal quick-service restaurant markets.
For Market Incumbents: Lock in rPET supply agreements with documented chain-of-custody certification ahead of EU Single-Use Plastics Directive enforcement. Expand captive sheet extrusion capacity in the US Midwest to defend margin position against polymer price volatility. Prioritize pharmaceutical-grade EMA certification to access pricing premiums above foodservice norms. For New Entrants and Emerging Players: Launch via direct-to-food-processor distribution models in India and Southeast Asia where BIS and FSSAI certification requirements create entry barriers for unqualified imports. Target medical supplies segments in France and Germany where sterile packaging validation protocols limit competitive density. Pursue digital printing integration partnerships to eliminate secondary labeling operations for brand owners. For Investors and Strategic Acquirers: Roll-up economics work for regional foodservice fabricators with underinvested rPET conversion capabilities because EU extended producer responsibility schemes are accelerating consolidation. Focus acquisition screening on mid-tier converters with certified recycling infrastructure and mold design engineering benches. Watch EU EFSA migration limit updates as the inflection trigger for material platform transition speed.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Supply Agreement | Secures post-consumer recycled content streams ahead of EU Single-Use Plastics Directive thresholds. |
| Pharmaceutical-Grade Certification | Enables EMA and FDA sterile packaging qualification for medical device distribution premiums. |
| Captive Sheet Extrusion Expansion | Insulates margin stability from virgin PET price volatility through backward integration. |
| Digital Printing Integration | Eliminates secondary labeling costs for quick-service restaurant brand owners via direct-to-shape decoration. |
| Mold Design Engineering Acquisition | Addresses tooling engineer scarcity constraining new product development timelines. |
Study Parameters
Multiple input streams — executive interviews with thermoforming plant managers, procurement leads at quick-service restaurant chains, pharmaceutical packaging engineers, and distribution channel partners — were reconciled against secondary validation from FDA food contact filings, EU EFSA migration limit updates, SEC 10-K disclosures by integrated converters, and customs trade data on PET resin flows. Bottom-up volume modeling across clamshell, tray, and blister pack formats was triangulated with top-down market sizing.
Historical capacity utilization patterns were cross-referenced against panel input from resin producers and sheet extrusion operators to anchor growth projections across the analysis window. Segmentation dimensions modeled include product type, material grade tier, application vertical, and regional regulatory cluster. CAGRs were derived from iterative convergence between demand-side procurement forecasts and supply-side capacity expansion announcements, with specific weighting for EU REACH reformulation timelines and US EPA resin emissions standards.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt polymer price spikes or accelerated EU recycled content mandate implementation. Projections reflect assumptions on rPET availability scaling and mold fabrication lead time stability. A small set of triggers — EFSA migration limit updates, extended producer responsibility scheme expansions, and quick-service restaurant procurement consolidation announcements — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Foldable Steel Containers Market
Containers
Thin Wall Plastic Containers Market
Containers
Jug Shipper Market
Containers
Stainless Steel Cask Market
Containers
Screw Top Pails Market
Containers
ISO Ocean Containers Market
Containers
Pinch Grip Jars Market
Containers
Cubitainer Market
Containers
Multi Cavity Tray Market
Containers
Cups and Lids Market
Containers
HDPE Containers Market
Containers
Packaging Bins Market
Containers
Twist Up Stick Container Market
Containers
Essential Oil Containers Market
Containers
Concentrate Containers Market
Containers
Stackable Plastic Trays Market