
 Spout Containers Market | 2026-2036
Spout Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Spout Containers Market Analytics
Aftermarket service revenue for spout container tooling and retrofit line integration is tilting toward specialized engineering partners rather than original equipment manufacturers. Amcor plc leverages its integrated film-to-pouch manufacturing network across multiple continents to sustain cost advantages in high-volume squeeze pouch contracts. Berry Global anchors its position through backward integration into specialty polyethylene resins, while Mondi Group competes on fiber-based barrier substrates that target paperization mandates in European retail channels.
Spout containers are single- or multi-layer packaging vessels featuring an integrated dispensing aperture, typically constructed from laminated films, blow-molded plastics, or composite substrates with oxygen and moisture barrier properties, designed for controlled product dispensing and resealability in consumer and industrial applications. Stand-up pouches with screw-cap closures dominate value contribution due to premium positioning in adult nutrition and portable beverage segments, while flexible containers are capturing the fastest volume growth as brands convert from rigid formats to reduce shipping cube and shelf footprint. Plastic remains the baseline material by tonnage, though composite substrates command superior margins by satisfying dual-recyclability claims and extended shelf-life requirements.
The FDA governs food-contact substance notifications for spout container materials in the United States, while the EU's REACH and PPWR frameworks restrict certain plasticizers and mandate recyclability targets that reshape material selection across European supply chains. China's SAMR enforces GB standards for composite packaging safety that affect import specifications and domestic production licensing. Stakeholders must monitor how diverging extended producer responsibility implementations across these jurisdictions alter total cost of ownership calculations and regional sourcing strategies.
Market Dynamics
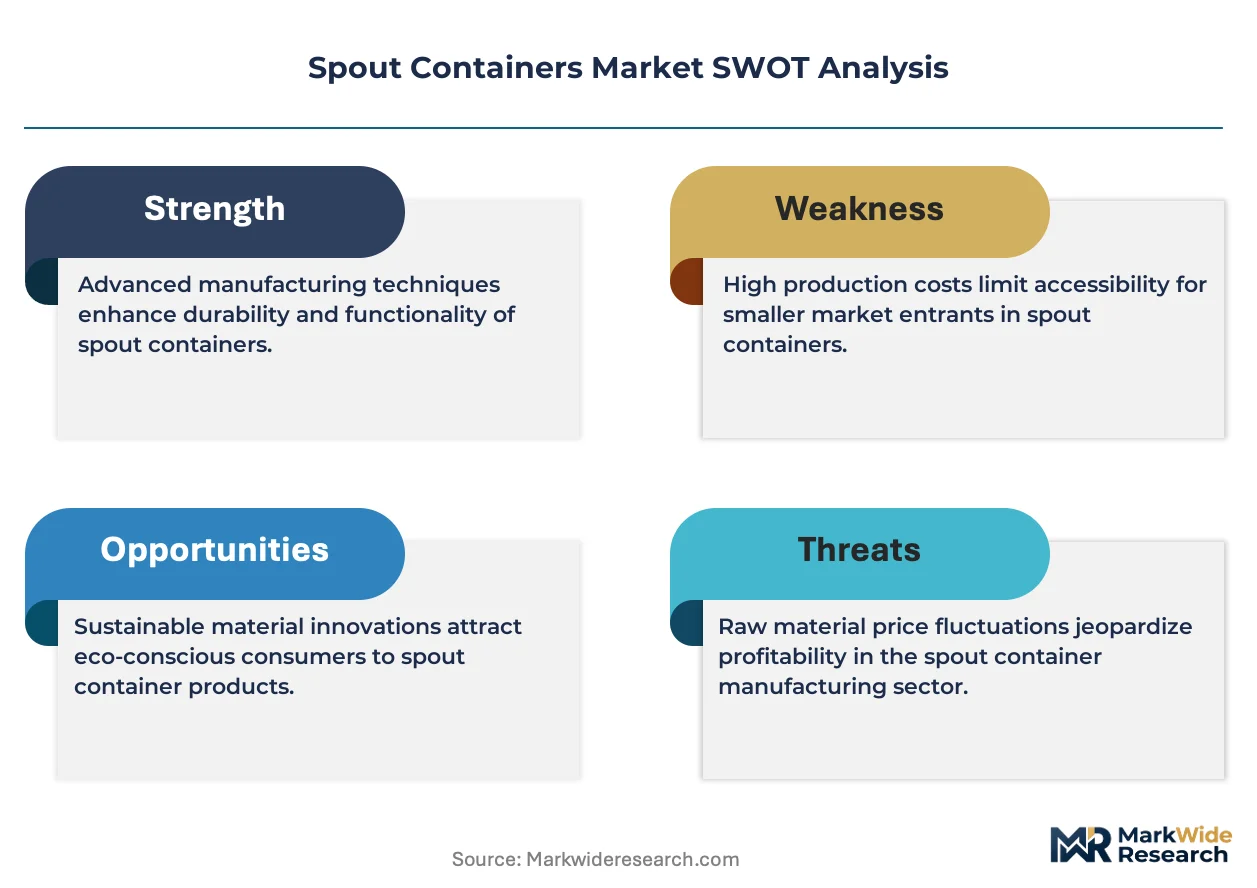
Extended producer responsibility frameworks are forcing material recertification across European supply chains, compressing converter margins while accelerating substrate innovation cycles in food-contact applications.
Growth Catalysts
- Baby food and toddler nutrition:Stand-up pouches with screw-cap closures capture premium positioning as parents prioritize portability and resealability for on-the-go feeding occasions.
- REACH and PPWR compliance:European recyclability mandates drive demand for composite substrates that satisfy dual-recyclability claims and extended shelf-life specifications.
- Flexible container conversion:Brands across adult nutrition and portable beverage segments replace rigid formats to reduce shipping cube and shelf footprint.
Market Restraints
- Specialty polyethylene resin concentration:Backward integration by dominant packaging conglomerates limits independent converter access to barrier-grade materials.
- Fiber-based barrier substrate cost premiums:Mondi Group's paperization-focused products command 15-30% price deltas versus conventional plastic laminates.
- SAMR licensing timelines:China's GB standards for composite packaging safety extend domestic production approval cycles by 8-14 months versus historical baselines.
Strategic Opportunities
- Adult nutrition white space:Protein powder and meal-replacement brands in Germany and France underutilize spouted stand-up pouches versus ready-to-drink formats.
- Retrofit line integration services:Aftermarket tooling revenue tilts toward specialized engineering partners capable of legacy equipment modification.
- IRA clean packaging incentives:US bio-based substrate developers access federal tax credits for renewable feedstock conversion in food-contact applications.
Industry Challenges
- Barrier film metallization expertise:Vacuum deposition technicians with oxygen transmission rate optimization experience command 40% wage premiums in flexible packaging hubs.
- Multi-jurisdiction notification complexity:FDA food-contact substance submissions require parallel EFSA dossier preparation for brands serving transatlantic retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spout Containers Market |
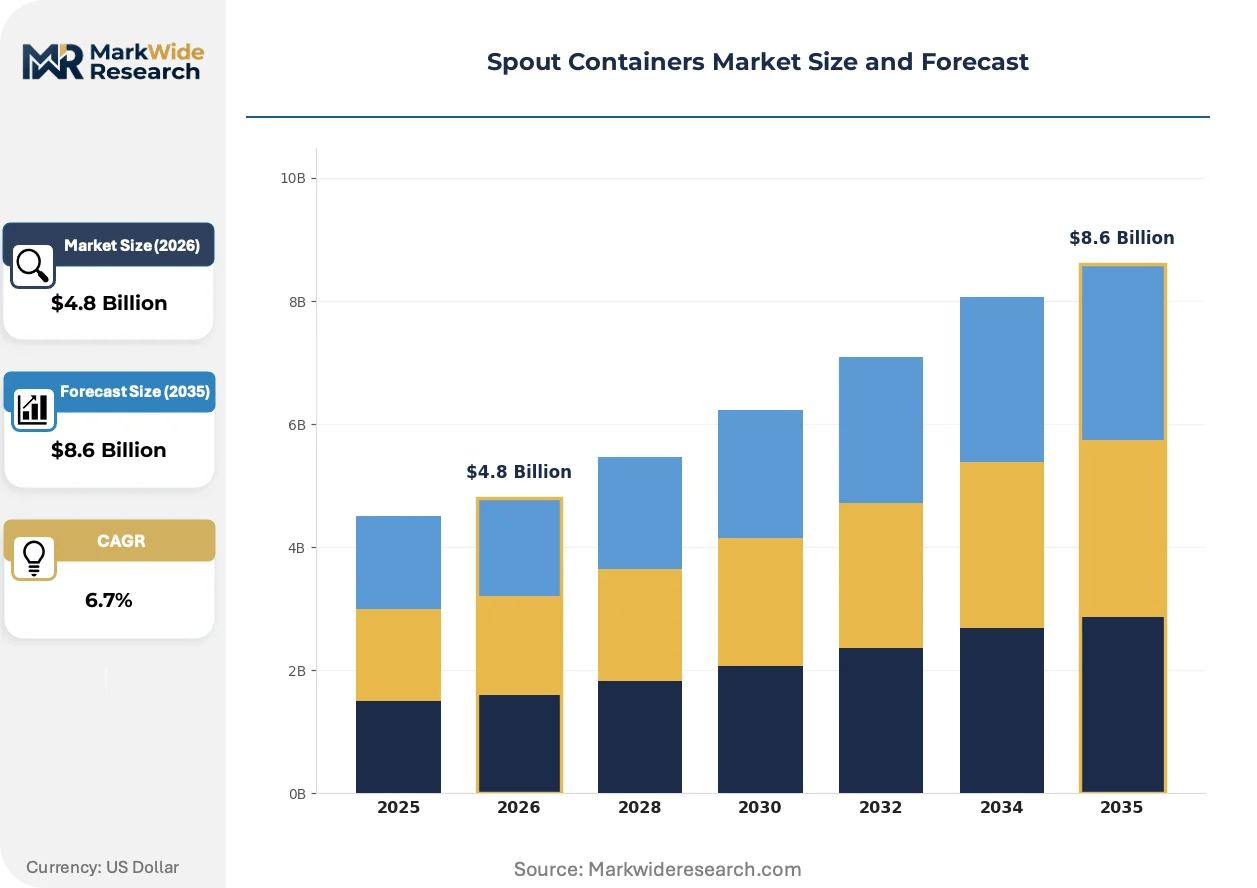
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Squeeze Pouches, Stand-up Pouches, Rigid Containers, Flexible Containers Material: Plastic, Glass, Metal, Composite Closure Type: Screw Cap, Flip-top Cap, Snap Cap, Pull-tab End Use Industry: Food & Beverage, Personal Care, Household Products, Industrial |
| Companies Covered | Amcor plc, Berry Global, Mondi Group, AptarGroup Inc., Guala Pack S.p.A., Glenroy Inc., Constantia Flexibles, ProAmpac, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spout Containers Market Evolving Landscape
Material science convergence with regulatory compliance automation is compressing product development cycles while fragmenting supplier relationships across specialized substrate and equipment tiers.
Barrier substrate technology is hybridizing oxygen-scavenging polymers with cellulose fiber matrices to create thermoformable structures that maintain 12-month shelf stability. Premium pet food brands in Italy and Spain pilot these materials for gravure-printed stand-up pouches. The convergence is hybridizing equipment requirements, forcing converters to source dual-capacity laminators capable of both solventless adhesive and extrusion coating.
EU Packaging and Packaging Waste Regulation enforcement timelines are compressing recyclability certification deadlines for laminated structures. European retail chains now mandate third-party verification of mono-material claims before shelf placement. Adult nutrition brands sourcing from Chinese converters face expedited audit requirements to maintain EU market access.
Brand procurement teams are unbundling spout container specifications from legacy converter relationships, issuing discrete RFQs for substrate, spout fitment, and filling equipment. This disintermediation fragments supplier accountability while concentrating specification authority with retail private-label managers. The shift is most visible in US club store channels where squeeze pouch volumes concentrate among three national buyers.
Spout Containers Market Segmentation
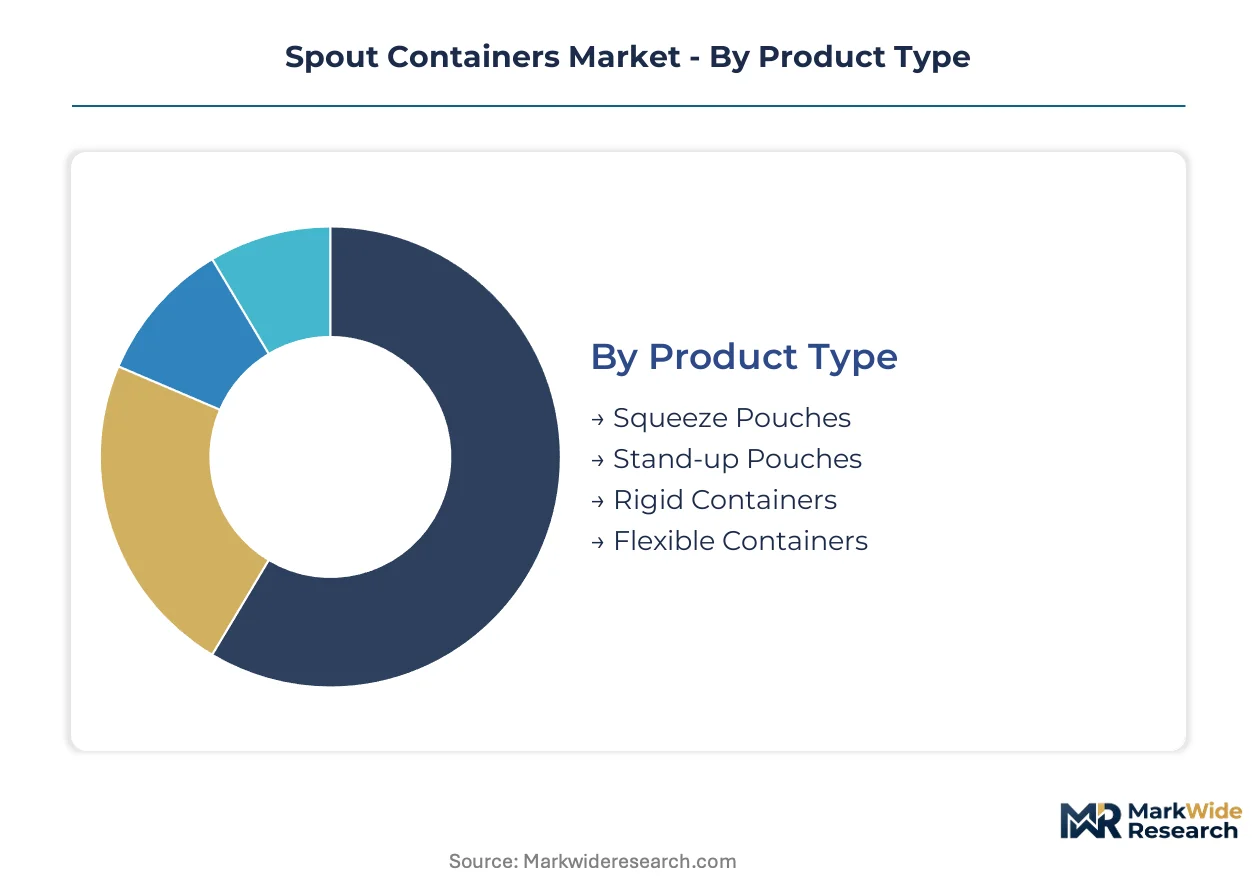
Spout container segmentation reveals how material compliance, dispensing mechanics, and end-use shelf requirements fragment manufacturing capabilities across converter tiers. Product format selection directly determines barrier engineering complexity and regulatory notification pathways.
Product Type:
Mature formats dominate installed converter capacity while emerging structures reshape capital deployment priorities.
- Squeeze Pouches:Multi-layer laminated films with integrated spout fitments enable controlled viscous product dispensing for adult nutrition and condiment applications. German and French protein powder brands underutilize this format versus ready-to-drink alternatives, creating white-space opportunity. Squeeze pouches handle the majority of throughput; flexible containers are the fastest mover on share.
- Stand-up Pouches:Gusseted bottom structures with screw-cap closures provide premium shelf presence and resealability for baby food and portable beverage segments. Chinese domestic converters are scaling production for regional food brands seeking reduced shipping cube.
- Rigid Containers:Blow-molded or injection-molded structures with attached dispensing apertures serve industrial lubricant and concentrated household chemical applications requiring stack strength.
- Flexible Containers:Pillow or gusseted formats with fitment seals capture fastest volume growth as brands convert from rigid formats to minimize shelf footprint and freight cost.
Stand-up pouches command premium positioning; flexible containers are climbing the fastest on volume contribution.
Material:
Cost tier stratification separates commodity tonnage from certified barrier substrates commanding margin premiums.
- Plastic:Polyethylene and polypropylene laminates form the baseline material by tonnage, with specialty barrier grades concentrated among backward-integrated conglomerates limiting independent converter access.
- Glass:Borosilicate and soda-lime structures serve premium personal care and pharmaceutical applications requiring inert contact surfaces and optical clarity for brand differentiation.
- Metal:Aluminum and tinplate containers with threaded apertures target industrial adhesive and specialty chemical segments demanding puncture resistance and light protection.
- Composite:Hybrid cellulose fiber matrices with oxygen-scavenging polymers satisfy EU PPWR dual-recyclability claims and extended shelf-life specifications, commanding 15-30% price deltas versus conventional plastic laminates.
Plastic moves the most volume; composite substrates gain share fastest on regulatory tailwinds.
Closure Type:
Application-driven torque and reseal requirements segment tooling specialization across converter equipment bases.
- Screw Cap:Threaded polyethylene or polypropylene closures with induction seals provide tamper evidence and repeated resealability for baby food and adult nutrition on-the-go consumption occasions.
- Flip-top Cap:Hinged polyethylene structures enable single-handed dispensing for personal care and household product applications prioritizing convenience.
- Snap Cap:Friction-fit closures with audible engagement feedback serve single-serve beverage and condiment portions where resealability is secondary to opening confirmation.
- Pull-tab:Frangible membrane structures with integral tear strips target industrial and agricultural chemical applications requiring hermetic integrity until point-of-use.
Screw caps anchor premium positioning; flip-top configurations are expanding most quickly in personal care conversion.
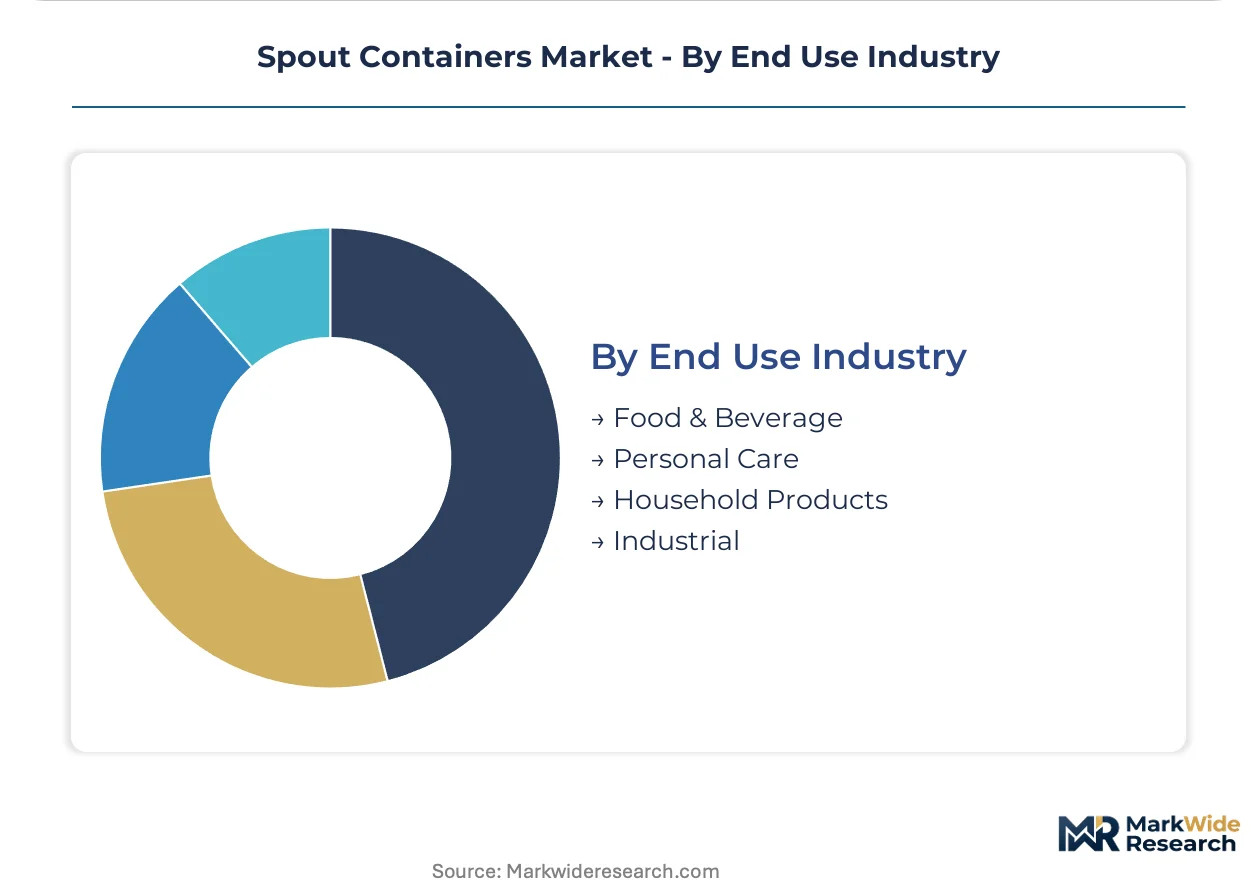
End Use Industry:
Customer type divergence separates food-contact regulatory complexity from industrial specification tolerance.
- Food & Beverage:FDA food-contact substance notifications and parallel EFSA dossier requirements govern laminated structures for baby food, adult nutrition, and portable beverage segments. EU retail chains mandate third-party mono-material verification before shelf placement.
- Personal Care:Cosmetic and hygiene product brands prioritize dispensing precision and aesthetic surface finish, with unbundled RFQs for substrate, fitment, and filling equipment fragmenting supplier accountability.
- Household Products:Concentrated detergent and cleaning chemical applications demand chemical compatibility and child-resistant closure integration.
- Industrial:Lubricant, adhesive, and agricultural chemical specifications prioritize puncture resistance and UV stability over barrier sophistication.
Food and beverage commands specification authority; personal care is gaining share fastest on unbundled procurement trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys spout containers predominantly for regional food brand conversion to flexible formats, while Germany and France concentrate demand in adult nutrition premium positioning, and the United States splits volume between baby food portability and industrial chemical dispensing.
United States
Baby food brands and adult nutrition suppliers drive squeeze pouch volume through club store channels where three national buyers concentrate procurement authority. FDA food-contact substance notifications govern laminated structure approvals, with parallel EFSA dossier preparation required for transatlantic retail distribution. Midwest flexible packaging hubs around Chicago and Milwaukee host vacuum deposition technicians commanding wage premiums for oxygen transmission rate optimization expertise.
Germany
Protein powder and meal-replacement brands underutilize spouted stand-up pouches versus ready-to-drink alternatives, creating identifiable white-space opportunity for format conversion. EU REACH and PPWR frameworks restrict specific plasticizers and mandate recyclability targets that reshape material selection across converter supply chains. Bavaria and Baden-Württemberg anchor barrier film metallization capacity serving gravure-printed pouch specifications for premium pet food brands.
China
Domestic flexible packaging converters scale production of spouted stand-up pouches for regional food brands seeking reduced shipping cube and shelf footprint advantages. SAMR enforces GB standards for composite packaging safety that extend domestic production approval cycles by 8-14 months versus historical baselines. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou concentrate fitment assembly and pouch forming equipment capacity.
France
Adult nutrition brands pilot hybrid cellulose fiber matrices with oxygen-scavenging polymers for 12-month shelf stability in gravure-printed stand-up pouches. EU PPWR enforcement timelines compress recyclability certification deadlines for laminated structures entering retail distribution. Auvergne-Rhône-Alpes and Île-de-France host retail private-label managers unbundling spout container specifications from legacy converter relationships.
Italy
Premium pet food brands pilot thermoformable barrier substrates for gravure-printed stand-up pouches requiring dual-capacity laminators capable of solventless adhesive and extrusion coating. EFSA dossier requirements parallel FDA submissions for brands serving transatlantic retail channels. Northern industrial districts around Milan and Bologna concentrate converter capacity for food-contact barrier engineering.
Spout Containers Market Competitive Landscape
Capability concentration sits with specialized engineering partners capable of legacy equipment modification and barrier film metallization expertise; scale advantage sits with backward-integrated conglomerates controlling specialty polyethylene resin supply. The market structures around three archetypes: integrated film-to-pouch manufacturers, resin-backward-integrated packaging conglomerates, and fiber-based barrier substrate specialists. Dominant competitive moves include strategic partnerships for aftermarket tooling revenue capture and portfolio diversification into composite substrates satisfying dual-recyclability claims.
Within the integrated manufacturing tier, Amcor plc exemplifies multi-continent film-to-pouch network positioning, while Berry Global represents resin-backward-integrated conglomerate structure. Mondi Group occupies the fiber-based barrier substrate specialist archetype targeting paperization mandates. These three anchors illustrate how geographic coverage, upstream material control, and regulatory-responsive substrate innovation define competitive positioning in spout container supply.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Mondi Group |
| AptarGroup Inc. |
| Guala Pack S.p.A. |
| Glenroy Inc. |
| Constantia Flexibles |
| ProAmpac |
| Sonoco Products Company |
| Others |
Value Network & Pricing Analysis
Tariff exposure on specialty polyethylene resins and oxygen-scavenging polymers determines both pricing tier spreads and supply chain configuration across converter tiers. The EU's PPWR compliance deadlines and China's SAMR licensing extensions compress margins while fragmenting procurement authority toward retail private-label managers.
Pricing Analysis
Long-term offtake contracts dominate high-volume squeeze pouch agreements with club store buyers, while spot purchasing governs specialty composite substrate lots for premium pet food applications. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified barrier laminates from uncertified commodity grades and fiber-based paperization alternatives. Cost compression in standard-tier polyethylene laminates is intensifying because backward-integrated conglomerates limit independent converter access to barrier-grade materials. Brand procurement teams at mass retailers exhibit highest price sensitivity, whereas premium adult nutrition brands prioritize dual-recyclability certification over unit cost.
Supply Chain Analysis
Export-control scrutiny on vacuum deposition equipment and metallization expertise limits barrier film technology flows to Chinese and Southeast Asian converters. Manufacturing gravity centers on Germany and Italy for gravure-printed pouch specifications, China for fitment assembly and pouch forming equipment, and the United States for Midwest flexible packaging hubs. Raw material flows draw from Saudi Arabian polyethylene feedstocks, South Korean oxygen-scavenging polymer additives, and Nordic cellulose fiber matrices. Single-source vulnerability concentrates in vacuum deposition technician labor pools commanding wage premiums. Distribution runs through converter-direct relationships with retail private-label managers, bypassing traditional packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier film metallization expertise and legacy equipment modification capability constitute the critical asset gap separating viable competitors from margin-compressed commodity players. The market rewards specialized engineering partners over scale-driven resin integrators.
For Market Incumbents: Harden defensive positions through captive supply of specialty polyethylene resins and accelerated certification investment for EU PPWR dual-recyclability claims. Threats from fiber-based substrate specialists like Mondi Group displace plastic laminate share in European retail channels. Priority levers include backward integration into oxygen-scavenging polymer supply and capacity addition in Bavaria for gravure-printed pouch metallization. For New Entrants and Emerging Players: German and French adult nutrition white space offers the most penetrable geographic underpenetration, as protein powder brands underutilize spouted stand-up pouches versus ready-to-drink alternatives. Target retrofit line integration services for legacy equipment modification, where aftermarket tooling revenue tilts toward specialized engineering partners. A direct-to-converter sales model bypassing legacy distributor relationships captures unbundled procurement trends. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors fiber-based barrier substrate specialists and equipment-modification engineering partners over commodity resin-integrated conglomerates. Long-term viability across the next decade hinges on dual-recyclability certification depth and retrofit service capability. Acquisition targets should demonstrate vacuum deposition expertise and solventless adhesive laminator dual-capacity. The signal to watch is EU retail chain third-party mono-material verification mandates accelerating beyond current PPWR timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Substrate Certification | EU PPWR dual-recyclability claims command 15-30% price premiums over conventional laminates. |
| Retrofit Line Integration Services | Aftermarket tooling revenue tilts toward specialized engineering partners capable of legacy equipment modification. |
| Backward Integration into Specialty Resins | Captive polyethylene supply limits independent converter access and sustains margin position. |
| Gravure-Printed Pouch Capacity Expansion | Premium pet food brands in Italy and Spain pilot hybrid cellulose fiber matrices for 12-month shelf stability. |
| Regional Converter Partnerships | Chinese domestic flexible packaging converters scale spouted stand-up pouch production for regional food brands. |
Research Methodology
A spread of perspectives from flexible packaging plant managers, retail private-label procurement directors, barrier film R&D specialists, and vacuum deposition equipment engineers converged on the working assumptions governing material substitution timelines and regulatory compliance costs. Primary fieldwork combined structured interviews with secondary validation against EU PPWR implementation documents, FDA food-contact substance notification databases, SAMR GB standard filings, and trade flow records for specialty polyethylene resins. Bottom-up capacity assessments triangulated against top-down demand modeling across baby food, adult nutrition, and portable beverage end-use segments.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product format, material compliance tier, closure torque specification, and regional regulatory cluster. Modeled variables included converter capacity utilization by equipment type, fitment assembly labor cost differentials, and barrier film metallization yield rates. CAGRs derived from regression analysis of historical volume trajectories adjusted for PPWR enforcement acceleration and SAMR licensing timeline extensions.
Practitioners should monitor EU retail chain third-party verification mandates, SAMR approval cycle fluctuations, and specialty resin tariff schedule adjustments for early signals of forecast deviation. Material shifts in extended producer responsibility implementation timelines or breakthroughs in mono-material barrier performance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Global Styrene Compartment Boxes Market
Containers
Concentrate Containers Market
Containers
2 Piece Cans Market
Containers
Takeout Containers Market
Containers
HDPE Containers Market
Containers
Wooden Barrels Market
Containers
Jars Market
Containers
Bulk Containers Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Disposable Lids Market
Containers
North America Insulated Shipping Containers Market
Containers
Hinged Lid Compostable Container Market
Containers
Container Mouth Inner Seal Market
Containers
Feeder Containers Market
Containers
Stack and Nest Containers Market
Containers
Packer Bottle Market