
 Vented Caps Market | 2026-2036
Vented Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Vented Caps Market Analytics
Membrane filtration integration is fragmenting traditional vented cap architectures into multi-layer breathable barrier systems. Corning Incorporated leverages its materials science heritage to dominate laboratory-grade vented closures with controlled porosity specifications. W. L. Gore & Associates anchors premium membrane technology through proprietary expanded polytetrafluoroethylene barriers that sustain differential pressure ratings across pharmaceutical applications. SABEU GmbH & Co. KG specializes in customized venting solutions for European chemical packaging, competing on rapid tooling turnaround and regional regulatory alignment.
Vented caps are pressure-equalizing closures incorporating hydrophobic membrane filters or porous substrates that permit gas exchange while blocking liquid and particulate ingress, typically manufactured through injection molding with subsequent membrane welding or insert placement. Their primary commercial purpose spans sterile pharmaceutical containment, volatile chemical storage, and agricultural formulation packaging where thermal expansion or gas evolution risks container deformation or seal breach. Screw-on caps occupy the largest volume position across pharmaceutical and chemical applications due to established cGMP compatibility and torque-verifiable sealing integrity. Plastic material formulations lead unit economics, though composite constructions incorporating fluoropolymer membranes command margin concentration in biologic drug packaging where USP Class VI and ISO 10993 compliance are mandatory. Snap-on configurations represent the fastest-growing product category in single-use diagnostic and point-of-care device segments where assembly automation drives throughput requirements.
The FDA enforces container closure system integrity standards under USP <1207> that directly shape vented cap validation protocols for sterile drug products, while the EPA's 40 CFR pesticide container regulations mandate venting performance for agricultural chemical packaging to prevent rupture during temperature cycling. REACH and the EU MDR impose additional material migration and biocompatibility testing burdens on suppliers targeting European pharmaceutical and medical device end markets. Stakeholders must monitor evolving regulatory convergence between pharmaceutical packaging integrity standards and circular economy packaging directives, as these frameworks will determine which membrane technologies and material platforms retain market access across major economies.
Market Dynamics
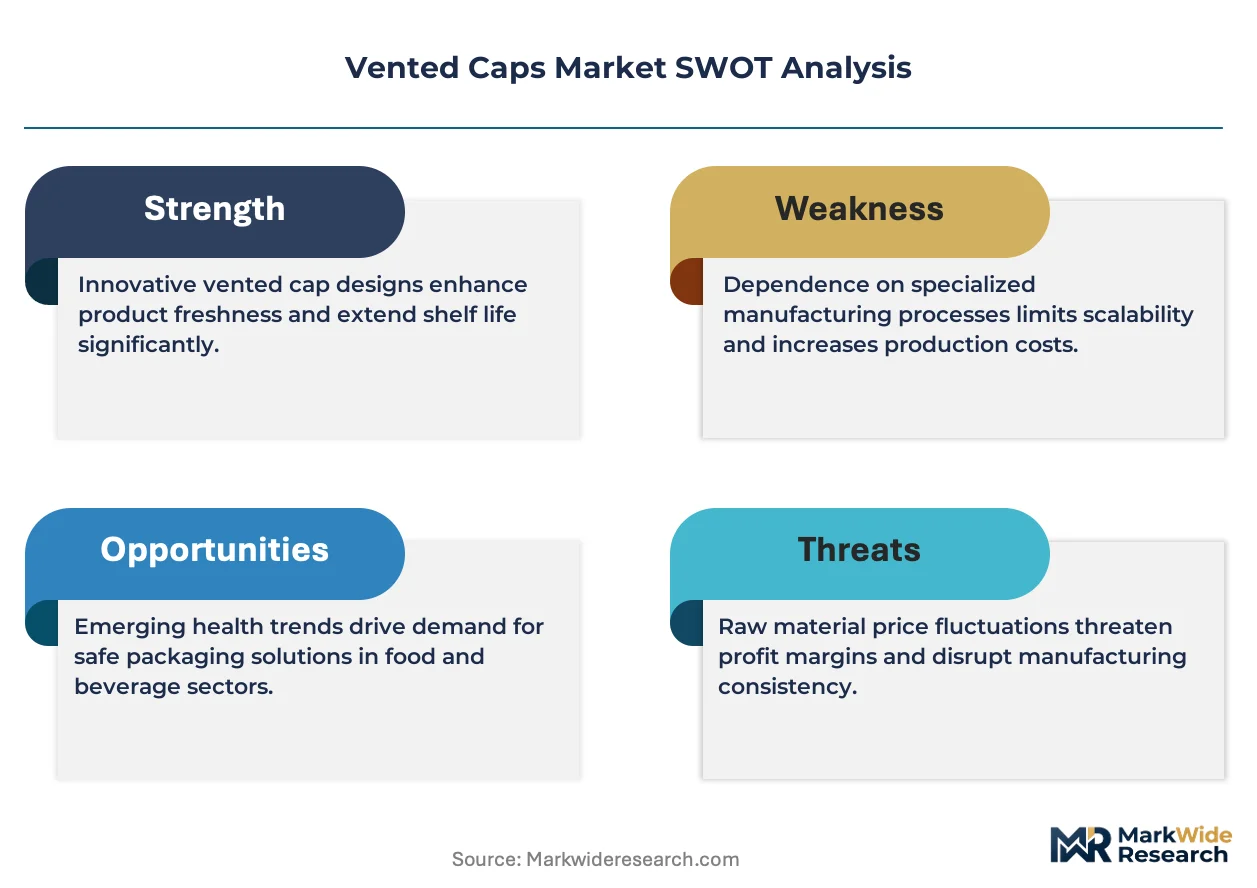
Membrane welding automation is compressing production cycle times while simultaneously tightening quality tolerances for hydrophobic barrier integration, forcing mid-tier suppliers to retool or exit pharmaceutical-grade segments.
Growth Catalysts
- Biologic drug proliferation:Cell and gene therapy pipelines require sterile gas exchange at cryogenic temperatures, pulling vented cap demand into cold-chain logistics networks.
- EPA 40 CFR pesticide container mandates:Temperature cycling performance requirements for agricultural chemical packaging prevent rupture incidents and sustain replacement demand.
- Injection molding precision advances:Multi-cavity tooling with in-mold membrane placement cuts unit costs for high-volume diagnostic applications.
Market Restraints
- Fluoropolymer membrane cost volatility:PTFE and ePTFE feedstock prices swing with semiconductor and industrial demand cycles, squeezing margin on premium pharmaceutical grades.
- German supplier concentration:SABEU GmbH & Co. KG and regional filtration specialists anchor European supply, creating single-source vulnerability for just-in-time pharmaceutical packaging lines.
- Metal-to-plastic substitution limits:Corrosive chemical segments still specify metal closures for extreme pH environments, capping plastic vented cap penetration in industrial solvents.
Strategic Opportunities
- India pharmaceutical packaging expansion:CDSCO manufacturing quality upgrades and export-oriented production incentives create demand for USP Class VI compliant vented closures.
- Point-of-care diagnostic automation:Snap-on vented cap formats integrate with robotic assembly lines for rapid test cartridge production.
- EU MDR biocompatibility alignment:ISO 10993 testing harmonization across European medical device markets reduces certification duplication for membrane suppliers.
Industry Challenges
- Cleanroom membrane welding technician scarcity:Specialized operators who maintain ISO 14644 Class 7 environments command premium wages and limit production scaling.
- Dual certification timeline compression:Simultaneous FDA USP <1207> and EMA Annex 1 validation for sterile barrier systems extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vented Caps Market |
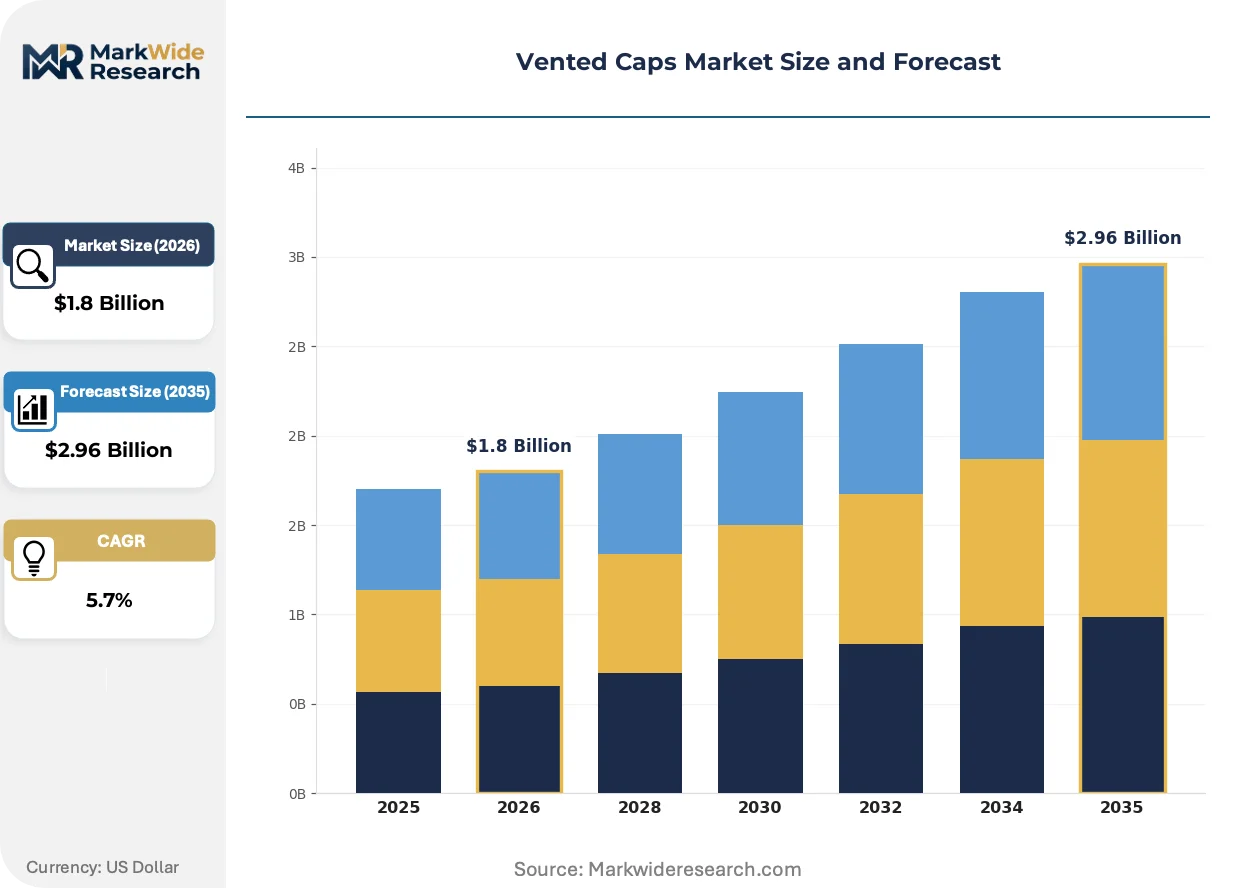
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snap-on Caps, Screw-on Caps, Flip Caps, Push-fit Caps Material: Plastic, Metal, Rubber, Composite Application: Pharmaceuticals, Food & Beverage, Chemicals, Agriculture End User: Manufacturers, Distributors, Retailers, Consumers |
| Companies Covered | Cole-Parmer Instrument Company, StockCap, Corning Incorporated, SABEU GmbH & Co. KG, CP Lab Safety, W. L. Gore & Associates, Merck Group, Kaufman Container Company, Filtration Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vented Caps Market Evolving Landscape
Digital process control layers are overlaying physical membrane manufacturing, generating real-time porosity validation data that downstream pharmaceutical buyers now mandate for batch release documentation.
Multi-layer breathable barrier architectures are virtualizing traditional single-membrane vented cap designs. Biologic drug manufacturers in the United States and Germany are specifying these stacked configurations for monoclonal antibody containers. This technology is virtualizing quality assurance workflows by embedding sensor-readable porosity signatures directly into membrane welds.
REACH SVHC candidate list expansion is forcing material requalification across European pharmaceutical packaging supply chains. ECHA substance of very high concern notifications now cover several plasticizer classes common in cap sealing gaskets. Suppliers serving EMA-regulated markets are accelerating bio-based elastomer development to preempt authorization requirements.
Contract packaging organizations are consolidating vented cap specifications across multiple drug programs to capture volume pricing. Large pharmaceutical CDMOs in Switzerland and Singapore are pushing membrane suppliers toward platform designs that serve both clinical and commercial phases. This specification rationalization concentrates procurement power with buyers who can commit to multi-year membrane film orders.
Vented Caps Market Segmentation
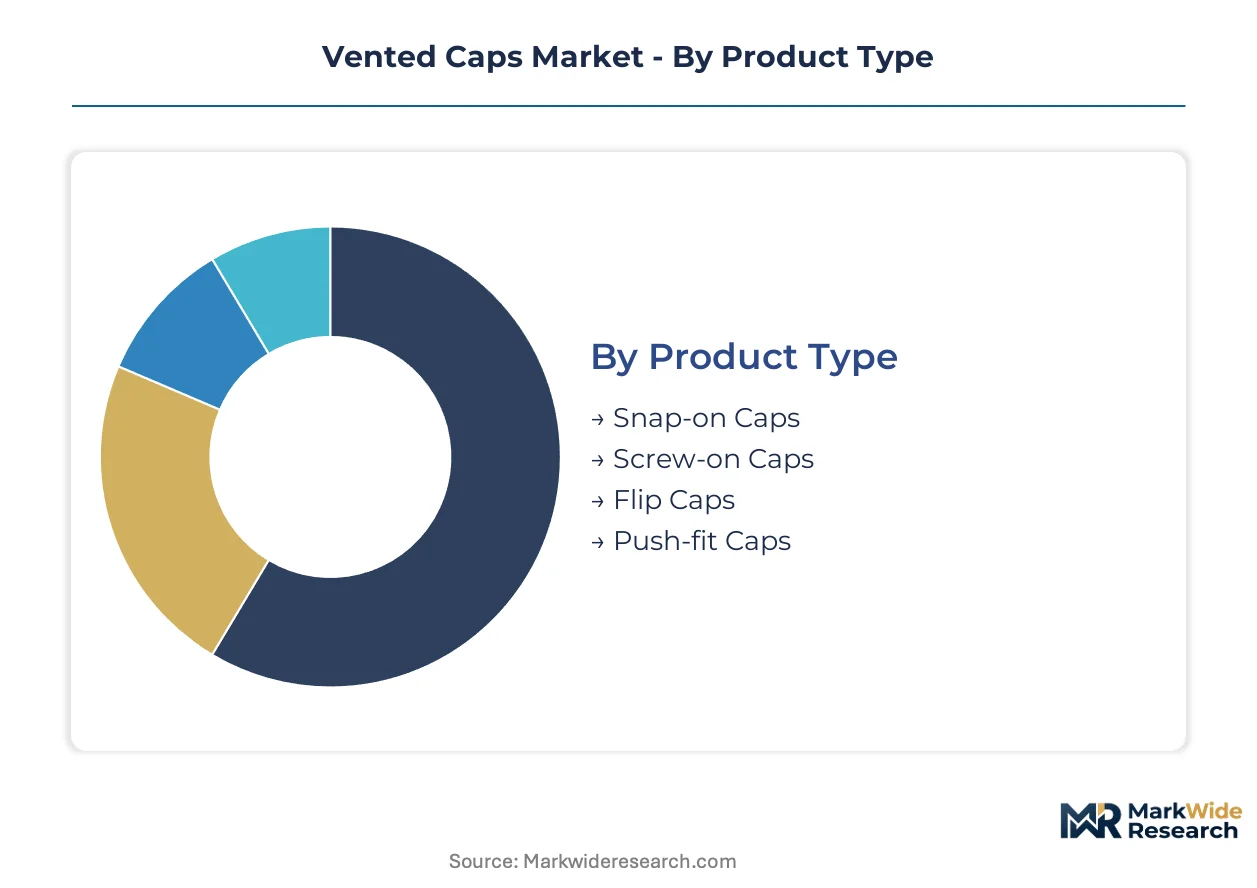
Vented cap procurement cycles vary dramatically across product architectures and end-use certifications. Segment-level turnover rates directly dictate inventory strategies and supplier qualification timelines for pharmaceutical packaging buyers.
Product Type:
Screw-on caps rotate through procurement cycles slowest due to multi-year validation lock-in, while snap-on formats refresh specifications quarterly to match diagnostic device iteration.
- Screw-on Caps:Threaded closure systems with torque-verifiable sealing meet cGMP documentation requirements for sterile drug containment. Pharmaceutical manufacturers in Germany and the United States specify these for biologic storage vials where seal integrity failures trigger batch recalls. Validation timelines extending 18-24 months cement incumbent supplier relationships.
- Snap-on Caps:Interference-fit designs enable robotic assembly at throughput rates exceeding 400 units per minute. Point-of-care diagnostic producers in Singapore and Switzerland drive specification turnover as test cartridge form factors shrink. CDMO procurement teams refresh vendor pools every 90-120 days to capture molding innovation.
- Flip Caps:Hinged single-motion opening suits consumer-facing pharmaceutical packaging where elderly patient compliance is prioritized.
- Push-fit Caps:Friction-based retention serves low-cost agricultural chemical containers where temperature cycling demands exceed consumer handling requirements.
Screw-on caps anchor the volume base while snap-on caps gain share at the steepest rate.
Material:
Raw material selection stratifies margin profiles, with fluoropolymer composites commanding certification premiums that commodity plastics cannot access.
- Plastic:Polypropylene and polyethylene formulations dominate unit economics through multi-cavity injection molding. REACH SVHC screening now excludes phthalate plasticizers common in legacy gasket compounds, forcing European suppliers toward bio-based elastomer alternatives. CDSCO import inspections for Indian pharmaceutical packaging increasingly flag non-compliant plasticizer residuals.
- Composite:Laminated constructions embedding expanded PTFE membranes achieve USP Class VI and ISO 10993 biocompatibility ratings mandatory for monoclonal antibody containment. W. L. Gore & Associates and Corning Incorporated control membrane supply for these premium tiers, with spot pricing indexed to semiconductor industry PTFE demand cycles.
- Metal:Aluminum and stainless steel closures retain specification in corrosive solvent packaging where pH extremes degrade polymer seals.
- Rubber:Bromobutyl and chlorobutyl formulations serve legacy pharmaceutical vial applications where gas permeability specifications predate membrane integration.
Plastic formulations capture the widest unit deployment while composite constructions expand most quickly in biologic drug packaging.
Application:
Regulatory burden intensity separates application tiers, with pharmaceutical validation protocols consuming 3-5x the qualification resources of agricultural packaging.
- Pharmaceuticals:Sterile barrier systems under FDA USP <1207> and EMA Annex 1 mandate container closure integrity testing at cryogenic temperatures. Cell and gene therapy cold-chain logistics in the United States and Germany now specify vented caps for liquid nitrogen vapor phase storage, pulling membrane suppliers into -150°C performance validation.
- Chemicals:EPA 40 CFR pesticide container regulations mandate venting performance to prevent rupture during temperature cycling. Agricultural formulation packagers in the United States face replacement demand cycles tied to seasonal application windows and container reuse inspection schedules.
- Agriculture:Fertilizer and herbicide packaging specifications concentrate in regions with high mechanized farming density.
- Food & Beverage:Fermentation gas release applications in craft brewing and kombucha production drive breathable closure demand with minimal regulatory overhead.
Pharmaceuticals anchors the value concentration while chemicals sustains replacement-driven volume.
End User:
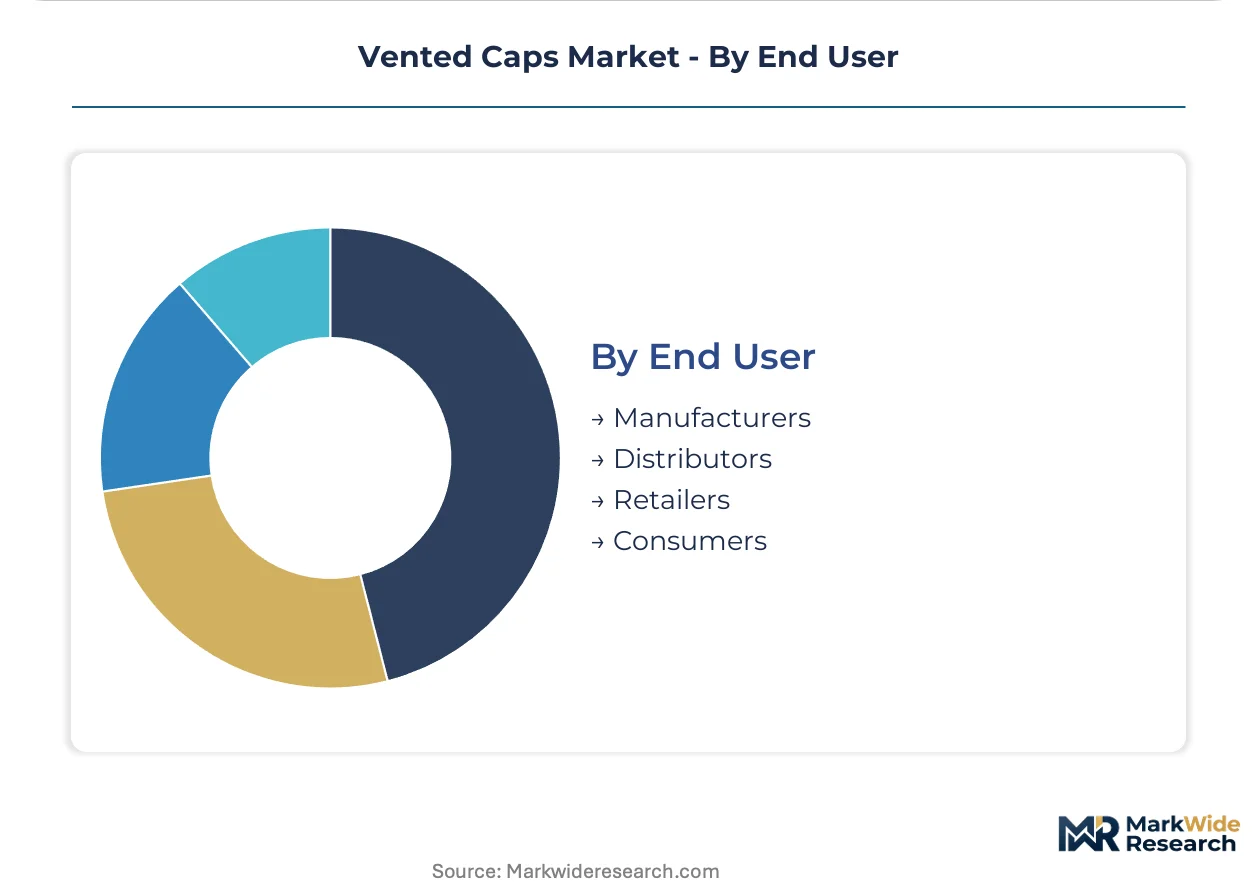
Buyer sophistication and technical specification authority determine segment profitability, with direct manufacturers capturing margin that distributor intermediaries compress.
- Manufacturers:Pharmaceutical and chemical companies with in-house packaging engineering teams issue detailed membrane porosity specifications and audit supplier cleanrooms directly. Multi-year supply agreements with volume commitments secure preferential pricing and dedicated production slots during feedstock shortages.
- Distributors:Industrial packaging wholesalers aggregate fragmented agricultural and food processing demand, standardizing on generic vented cap specifications that sacrifice performance for inventory breadth.
- Retailers:Home improvement and agricultural supply chains specify private-label vented closures for consumer chemical repackaging.
- Consumers:Direct purchases concentrate in homebrewing and specialty chemical storage niches with minimal quality verification.
Manufacturers anchor the specification authority while distributors expand reach into price-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German membrane specialists export vented closure systems to pharmaceutical packaging lines across the United States and Switzerland, while Indian CDMOs import USP Class VI certified components for biologic drug export programs.
United States
Cell and gene therapy cold-chain logistics drive vented cap specification for cryogenic storage vessels. FDA USP <1207> container closure integrity standards mandate validation protocols that extend supplier qualification timelines. Boston-Cambridge biotech clusters and North Carolina Research Triangle pharmaceutical manufacturing anchor domestic demand concentration.
Germany
SABEU GmbH & Co. KG and specialized filtration component producers anchor European supply chains for chemical and pharmaceutical packaging. REACH SVHC candidate list expansion forces material requalification across plasticizer-dependent gasket compounds. Baden-Württemberg industrial corridors concentrate precision membrane welding automation investments.
Switzerland
Contract packaging organizations consolidate vented cap specifications across multiple drug programs to capture volume pricing from membrane suppliers. Swissmedic medical device regulations align with EU MDR biocompatibility testing frameworks. Basel pharmaceutical CDMO clusters drive platform design standardization for clinical-to-commercial phase transitions.
India
CDSCO manufacturing quality upgrades and export-oriented production incentives create demand for USP Class VI compliant vented closures in biologic drug packaging. Maharashtra and Gujarat pharmaceutical manufacturing zones expand sterile barrier system procurement for regulated export markets. CDSCO import inspections increasingly flag non-compliant plasticizer residuals in legacy gasket materials.
Singapore
Point-of-care diagnostic automation pulls snap-on vented cap formats into robotic assembly lines for rapid test cartridge production. Regional headquarters for global pharmaceutical CDMOs concentrate specification authority for Asia-Pacific clinical trial material packaging. Biomedical manufacturing clusters in Tuas and one-north drive quarterly vendor pool refresh cycles.
Vented Caps Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered certification segments. The vendor base organizes around membrane technology ownership, injection molding scale, and regulatory validation depth. Three archetypes dominate: integrated materials science conglomerates with proprietary fluoropolymer platforms, regional precision molding specialists with rapid tooling turnaround, and diversified laboratory supply distributors with broad SKU breadth. Competitive moves concentrate on multi-year supply agreement locking and cleanroom membrane welding technician recruitment.
Within the integrated materials tier, Corning Incorporated and W. L. Gore & Associates exemplify archetype leaders. SABEU GmbH & Co. KG represents the regional specialist model with European regulatory alignment capabilities. These three anchors demonstrate how membrane technology control, geographic proximity to pharmaceutical clusters, and validation depth separate premium-tier suppliers from commodity molding competitors.
| Leading Market Players |
|---|
| Cole-Parmer Instrument Company |
| StockCap |
| Corning Incorporated |
| SABEU GmbH & Co. KG |
| CP Lab Safety |
| W. L. Gore & Associates |
| Merck Group |
| Kaufman Container Company |
| Filtration Group Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in German precision membrane welding facilities is compressing lead times for pharmaceutical-grade vented caps while simultaneously eroding pricing power among mid-tier European suppliers. This utilization dynamic forces suppliers toward either premium certification investments or commodity volume plays, bifurcating the competitive landscape.
Pricing Analysis
Single-layer membrane pricing faces sustained compression against multi-layer breathable barrier premiums that biologic drug manufacturers now specify for cryogenic applications. Three-tier pricing structure across premium fluoropolymer composites, standard polypropylene formulations, and economy agricultural grades anchors the market. Cost compression in standard tiers intensifies because Indian CDMOs are consolidating procurement across multiple drug programs. Agricultural chemical packagers exhibit highest price sensitivity due to seasonal demand cycles, while cell therapy developers accept premium positioning for USP Class VI validated systems.
Supply Chain Analysis
Contract manufacturing concentrates among German precision molding specialists and Swiss CDMO packaging lines that control cleanroom membrane welding capacity. Geographic supply centers on Germany, Switzerland, and the United States for pharmaceutical grades, with India and China feeding agricultural and industrial segments. Raw material dependencies rest on expanded PTFE feedstock from semiconductor industry suppliers, polypropylene resin from petrochemical complexes, and bio-based elastomer alternatives for REACH-compliant gaskets. Single-source vulnerability in fluoropolymer membrane supply creates structural risk for biologic drug packaging lines. Distribution runs through direct manufacturer relationships for pharmaceutical tiers and industrial distributors for agricultural applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom membrane welding technician scarcity is constraining production scaling across pharmaceutical-grade segments, creating durable competitive moats for suppliers with established training pipelines and certification depth.
For Market Incumbents: Pre-empt Indian pharmaceutical packaging expansion by establishing local cleanroom facilities before CDSCO import inspection protocols harden. Secure multi-year membrane film commitments from W. L. Gore & Associates or Corning Incorporated to defend against fluoropolymer feedstock volatility. Backward integration into membrane manufacturing equipment represents the critical lever for margin protection against emerging Asian molding competitors. For New Entrants and Emerging Players: India's Maharashtra and Gujarat pharmaceutical zones offer the most penetrable geography for USP Class VI compliant vented closure supply, given CDSCO quality upgrades and export-oriented production incentives. Point-of-care diagnostic automation in Singapore presents adjacent white-space with quarterly vendor refresh cycles and lower validation barriers than pharmaceutical sterile barriers. Target robotic assembly integration capabilities as the decisive go-to-market angle for snap-on format penetration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-layer membrane welding automation as pharmaceutical buyers mandate digital process control layers for batch release documentation. Long-term viability favors platform suppliers serving both clinical and commercial phases with standardized specifications. Acquisition targets should display cleanroom technician training infrastructure and existing FDA USP <1207> validation depth. Watch for EPA 40 CFR enforcement intensity as the inflection signal for agricultural chemical packaging replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Membrane Welding Automation | Compresses production cycles while tightening hydrophobic barrier quality tolerances for pharmaceutical grades. |
| Multi-Layer Barrier Platform Standardization | Enables CDMOs to consolidate specifications across clinical and commercial drug programs for volume pricing. |
| India Manufacturing Quality Certification | Positions suppliers for CDSCO export-oriented production incentives and biologic drug packaging demand. |
| Bio-Based Elastomer Material Transition | Preempts REACH SVHC authorization requirements for plasticizer-dependent gasket compounds in European markets. |
| Cryogenic Performance Validation Investment | Secures specification for cell and gene therapy cold-chain logistics in Boston-Cambridge and North Carolina clusters. |
Research Methodology
A standing panel of pharmaceutical packaging engineers, CDMO procurement directors, membrane welding technicians, and regulatory affairs specialists provided ongoing calibration across primary interview rounds and secondary validation. FDA USP <1207> filings, EMA Annex 1 guidance documents, EPA 40 CFR pesticide container regulations, and REACH SVHC candidate list updates anchored secondary source triangulation. Bottom-up segment sizing across product types, materials, and applications converged with top-down market reconciliation.
Scenario-bracketing around regulatory enforcement intensity, fluoropolymer feedstock volatility, and biologic drug pipeline expansion shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include closure architecture, material certification tier, application regulatory burden, end-user specification authority, and regional manufacturing cluster. CAGRs derived from elasticity-adjusted demand curves incorporating membrane welding automation diffusion rates and pharmaceutical cold-chain logistics expansion.
Practitioners should monitor EPA enforcement patterns, ECHA SVHC list expansion timing, and semiconductor industry PTFE demand cycles for early signals of forecast revision. Quarterly review of CDSCO import inspection protocols, cleanroom technician wage inflation, and multi-year supply agreement announcement frequency is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Non-Aerosol Overcaps Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
Disc Top Caps Market
Caps and Closures
Buttress Closures Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
Germany Plastic Caps and Closures Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market
Caps and Closures
China Plastic Caps and Closures Market
Caps and Closures
Lug Caps Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Cork Stoppers Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Push Pull Closure Market