
 PVC Packing Straps Market | 2026-2036
PVC Packing Straps Market Size, Share, and Industry Trends Forecast 2026-2036
PVC Packing Straps Market Analytics
Asset-light leasing models for strapping equipment is narrowing the capital barrier for mid-sized logistics providers entering automated packaging. Teufelberger Stralsund GmbH leverages its coastal German manufacturing base to sustain just-in-time supply for Baltic Sea freight corridors. Polychem Corporation anchors North American demand through captive resin sourcing and proprietary extrusion tooling. FROMM Group competes across Europe and Asia with a rental-heavy service model that bundles equipment, consumables, and technical support.
PVC packing straps are extruded polyvinyl chloride bands, typically 1–4 mm thick, engineered for tensile retention and weather resistance during transit and storage. The material's chlorine content and plasticizer load determine flexibility ratings and recyclability profiles under regional waste frameworks. Heavy-duty flat straps dominate volume in manufacturing and palletizing applications where break strength and machine compatibility command premium positioning. Corner protectors represent a faster-growing niche as e-commerce shippers adopt damage-prevention protocols for fragile goods. Round straps retain share in bundling applications where hand-tooling and low-cost deployment remain priorities.
REACH and RoHS frameworks in Europe restrict phthalate plasticizers and heavy-metal stabilizers in PVC consumer-facing packaging, pushing compounders toward calcium-zinc or organic stabilizer systems. BIS certification in India mandates minimum tensile strength and elongation thresholds for straps used in export cargo, filtering out informal producers. OSHA guidelines in the US govern manual strapping workstation ergonomics, indirectly favoring automated tensioning systems. Stakeholders must monitor how extended producer responsibility schemes in the EU and state-level plastic waste rules in India reshape material recovery economics and virgin resin premiums.
Market Dynamics
Automated palletizing infrastructure in export manufacturing hubs is compressing lead times and forcing compounders to certify straps for high-speed tensioning systems. REACH phthalate restrictions and BIS tensile mandates are simultaneously narrowing the supplier base while opening premium positioning for compliant producers.
Growth Catalysts
- REACH compliance migration:German logistics operators now specify calcium-zinc stabilized straps for Baltic Sea freight corridors, filtering informal suppliers and consolidating procurement with certified compounders.
- Cross-border e-commerce scaling:Fulfillment infrastructure buildouts in Vietnam and Mexico are generating machine-grade strap demand for automated export packaging lines.
- Corner protector adoption:Damage-prevention protocols for fragile goods are expanding strap-plus-accessory bundling in e-commerce shipper procurement specifications.
Market Restraints
- Resin cost volatility:PVC pellet prices fluctuate with chlorine-alkali capacity utilization, squeezing margin stability for extrusion-dependent producers without captive resin sourcing.
- Substitution pressure:Polypropylene strapping gains share in light-duty bundling where hand-tooling and lower break strength requirements dominate.
- Plasticizer regulatory friction:RoHS heavy-metal restrictions in European consumer-facing applications force reformulation cycles that extend product development timelines.
Strategic Opportunities
- Asset-light equipment leasing:Bundled rental models for strapping machinery and consumables lower capital barriers for mid-sized logistics providers entering automated packaging.
- Extended producer responsibility tailwinds:EU waste framework revisions are creating closed-loop recovery economics that favor producers with established recycling partnerships.
- India export cargo certification:BIS-mandated minimum elongation thresholds for export straps are filtering informal competition and opening premium positioning for tested compounds.
Industry Challenges
- Extrusion tooling capex intensity:Proprietary die configurations for heavy-duty flat straps require significant upfront investment, limiting mid-tier expansion.
- Multi-jurisdiction certification timelines:Simultaneous REACH, RoHS, and BIS compliance documentation extends product launch cycles and strains regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC Packing Straps Market |
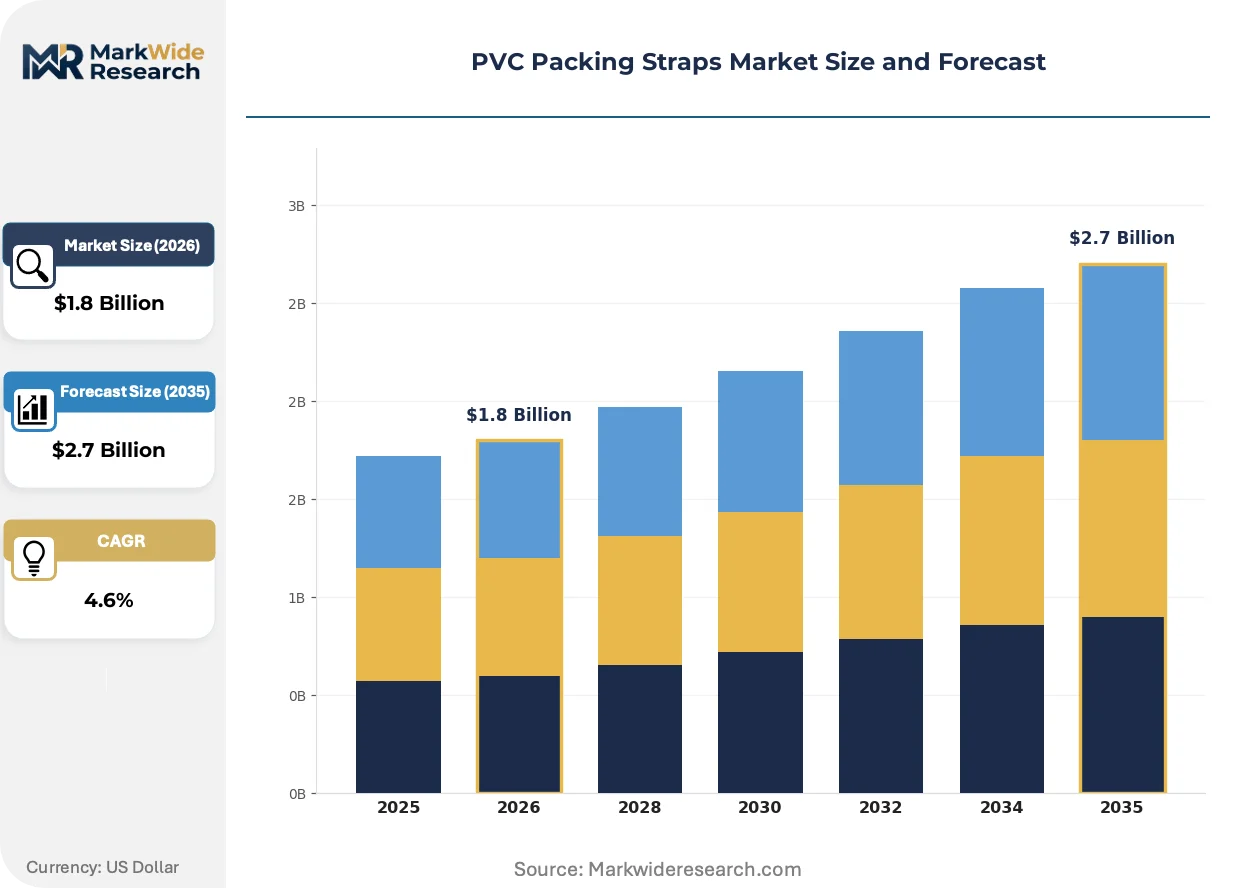
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Straps, Round Straps, Corner Protectors, Heavy-Duty Straps End User: Manufacturing, Warehousing, Retail, Logistics Application: Packaging, Bundling, Shipping, Palletizing Thickness: 1 mm, 2 mm, 3 mm, 4 mm |
| Companies Covered | Teufelberger Stralsund GmbH, Cyklop International, FROMM Group, Auto Strap India, CONSENT L.L.C, Polychem Corporation, Crown Holdings Inc., Mosca GmbH, DuBose Strapping Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC Packing Straps Market Evolving Landscape
Material science advances and procurement model reinvention are compressing the traditional specification cycle between compounders and end-users. Three developments are restructuring competitive positioning.
Co-extruded multi-layer strap construction is hybridizing rigid core layers with flexible outer skins to achieve machine compatibility without sacrificing weather resistance. High-volume palletizing operations in Germany and China are adopting these constructions for automated lines running at elevated tension speeds. The technology is hybridizing performance specifications that previously required separate product lines.
REACH Annex XVII restrictions on phthalate plasticizers are forcing compounders toward calcium-zinc and organic stabilizer systems. The industrial consequence is elevated raw material costs and reformulation validation requirements for European market access. Consumer-facing packaging applications face the steepest compliance burden, with many producers exiting decorative and retail-grade straps entirely.
Leasing-based procurement for strapping equipment is displacing capital purchase models among mid-sized logistics operators. Equipment-consumables bundling disrupts traditional distributor relationships and concentrates supplier power with vertically integrated compounders. This pattern is most visible in India, where rental penetration is accelerating among third-party logistics providers scaling for export manufacturing contracts.
PVC Packing Straps Market Segmentation
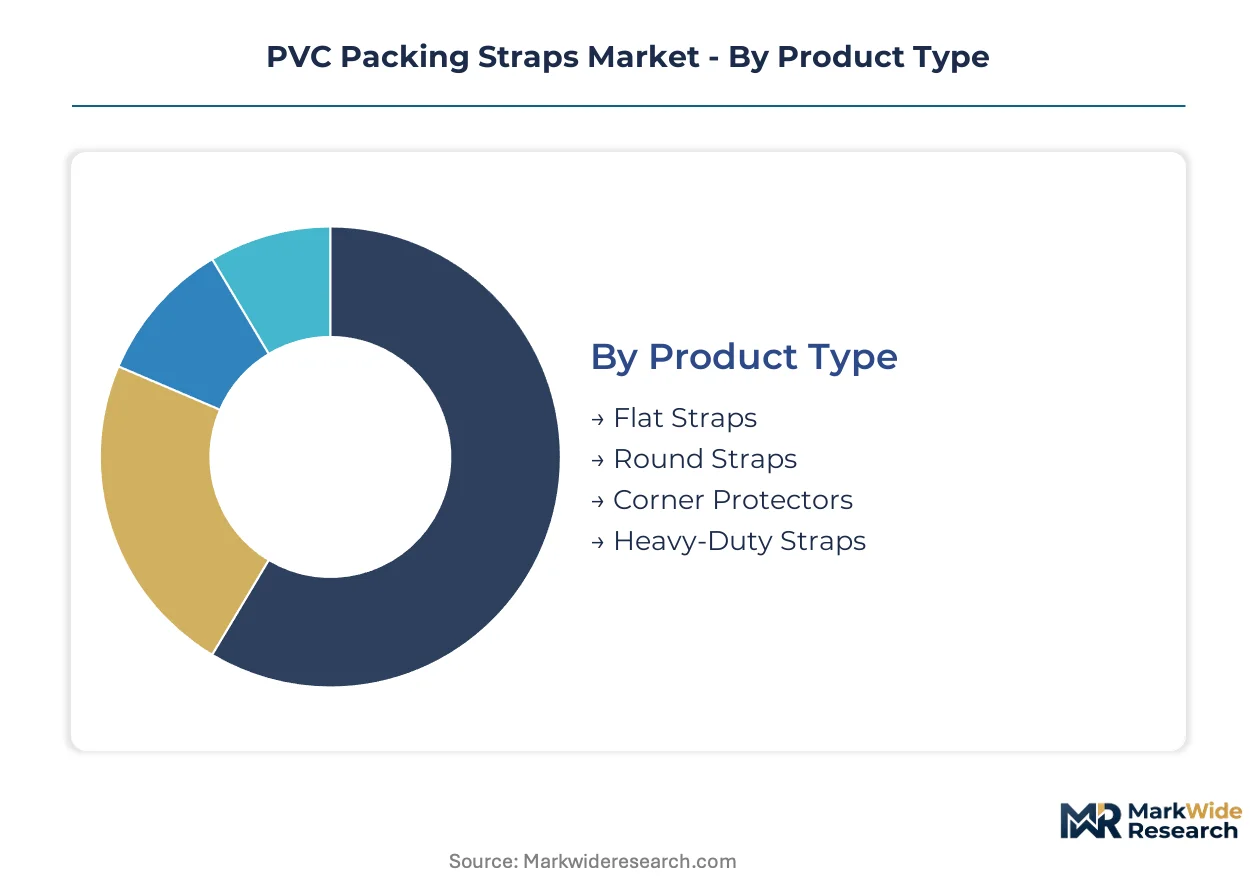
Segmentation in the PVC packing straps market reflects divergent performance requirements across automated machinery, manual tooling, and damage-prevention protocols. Procurement specifications vary sharply between export manufacturing hubs and domestic distribution networks, forcing compounders to maintain parallel certification tracks.
Product Type:
Extrusion configurations span rigid load-bearing cores to flexible outer skins, each commanding distinct tooling investments and resin formulations.
- Flat Straps:These extruded bands feature rectangular cross-sections optimized for automated tensioning heads in high-speed palletizing lines. German logistics operators along Baltic Sea freight corridors now specify calcium-zinc stabilized flat straps to satisfy REACH Annex XVII phthalate restrictions, filtering informal suppliers and consolidating procurement with certified compounders.
- Heavy-Duty Straps:Engineered for break strength exceeding standard grades, these constructions incorporate higher plasticizer loads and thicker gauge dimensions. Demand concentrates in Vietnam and Mexico where export manufacturing hubs are scaling automated packaging infrastructure for cross-border e-commerce fulfillment.
- Round Straps:Circular cross-section profiles retain dominance in hand-tooling applications where low-cost deployment and manual tensioning remain operational priorities for smaller warehousing operations.
- Corner Protectors:Accessory-grade components that prevent edge compression damage during transit. E-commerce shippers in India are adopting these for fragile goods protocols, expanding strap-plus-accessory bundling in procurement specifications.
The dominant share belongs to Flat Straps, while Corner Protectors are gaining share fastest.
End User:
Customer scale determines whether procurement flows through capital purchase or leased equipment-consumables bundling.
- Manufacturing:Export-oriented production facilities in China and Mexico generate machine-grade strap demand for automated export packaging lines, with specifications tightening around BIS and REACH compliance documentation.
- Logistics:Third-party providers in India are accelerating rental penetration for strapping equipment, lowering capital barriers for mid-sized operators scaling for export manufacturing contracts.
- Warehousing:Regional distribution centers favor hand-compatible strap formats with lower break strength thresholds, where polypropylene substitution pressure is most acute.
- Retail:Consumer-facing applications face the steepest RoHS heavy-metal compliance burden, with many producers exiting decorative and retail-grade straps entirely.
Manufacturing commands the largest procurement volumes, though Logistics is expanding most quickly through asset-light leasing adoption.
Application:
Functional use cases dictate tension speed compatibility and weather resistance specifications.
- Palletizing:Automated line integration requires straps certified for elevated tension speeds without slippage or breakage, driving co-extruded multi-layer construction adoption in Germany and China.
- Packaging:Export cargo specifications mandate minimum elongation thresholds under BIS certification, filtering informal competition and opening premium positioning for tested compounds.
- Bundling:Hand-tooling applications prioritize flexibility and low-cost deployment, retaining round strap formats despite polypropylene encroachment in lighter-duty segments.
- Shipping:Weather resistance specifications dominate for ocean freight exposure, with chloride content and stabilizer systems determining recyclability profiles under EU extended producer responsibility frameworks.
Palletizing generates the highest value per meter, while Packaging is climbing the fastest on export cargo certification requirements.
Thickness:
Gauge selection correlates directly with break strength requirements and machinery compatibility.
- 2 mm:The workhorse specification for general manufacturing and warehousing applications, balancing cost efficiency with adequate tensile retention for standard pallet loads.
- 4 mm:Heavy-duty construction for automated high-tension systems in export manufacturing, where proprietary die configurations require significant upfront extrusion tooling investment.
- 1 mm:Light-duty bundling for retail and hand-tooling applications, most vulnerable to polypropylene substitution in cost-sensitive procurement.
- 3 mm:Intermediate specification serving mixed manual and semi-automated environments, common in mid-sized logistics providers transitioning to leased equipment models.
The 2 mm specification holds the dominant position, though 4 mm is expanding most quickly on automated infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics operators in Germany and India drive procurement volume, while export manufacturing hubs in Vietnam, China, and Mexico generate machine-grade strap demand for automated packaging infrastructure.
Germany
Teufelberger Stralsund leverages its coastal manufacturing base for just-in-time supply to Baltic Sea freight corridors. ECHA REACH Annex XVII phthalate restrictions filter informal suppliers and consolidate procurement with calcium-zinc certified compounders. Hamburg and Bremen logistics clusters specify heavy-duty flat straps for automated palletizing lines serving Scandinavian export routes.
India
Third-party logistics providers accelerate rental penetration for strapping equipment to lower capital barriers for mid-sized operators scaling export contracts. BIS certification mandates minimum tensile strength and elongation thresholds for export cargo straps, filtering informal producers from formal procurement channels. Maharashtra and Gujarat manufacturing belts generate concentrated demand for machine-grade straps in pharmaceutical and textile export packaging.
Vietnam
Cross-border e-commerce fulfillment infrastructure buildouts drive machine-grade strap adoption for automated export packaging lines. The country's national standards body enforces material specifications for chloride-based packaging materials in cargo bound for EU and US markets. Ho Chi Minh City and Binh Duong industrial zones concentrate new automated palletizing installations serving electronics and footwear exporters.
China
Co-extruded multi-layer strap construction gains adoption in high-volume palletizing operations running at elevated tension speeds. MIIT and GB standards govern plasticizer content and recyclability profiles for packaging materials in domestic and export applications. Yangtze River Delta manufacturing clusters integrate certified straps into automated lines serving cross-border e-commerce fulfillment.
Mexico
Nearshoring manufacturing expansion generates demand for heavy-duty straps in automotive and electronics export packaging. The country's federal consumer protection agency monitors material specifications for transit packaging under harmonized North American trade frameworks. Baja California and Nuevo León industrial corridors scale automated strapping infrastructure for US-bound cargo consolidation.
PVC Packing Straps Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates procurement power with vertically integrated compounders and equipment bundlers. The vendor base stratifies between resin-integrated extruders with captive supply chains and regional fabricators dependent on spot resin markets. Two dominant archetypes emerge: coastal logistics-anchored manufacturers with just-in-time delivery capabilities, and rental-service bundlers combining equipment leasing with consumable supply. Competitive moves center on extrusion tooling capacity expansion and asset-light equipment leasing partnerships that displace capital purchase models.
Among German coastal manufacturers, Teufelberger Stralsund GmbH exemplifies the logistics-anchored archetype with its Baltic Sea positioning. FROMM Group occupies the rental-bundler tier across European and Asian markets. Polychem Corporation represents the North American resin-integrated model with captive sourcing structures. These three players illustrate the strategic divergence between geography-captive supply, service-bundled procurement, and upstream material control that defines competitive positioning in this market.
| Leading Market Players |
|---|
| Teufelberger Stralsund GmbH |
| Cyklop International |
| FROMM Group |
| Auto Strap India |
| CONSENT L.L.C |
| Polychem Corporation |
| Crown Holdings Inc. |
| Mosca GmbH |
| DuBose Strapping Inc. |
| Others |
Value Network & Pricing Analysis
Baltic Sea freight corridors channel PVC strap cost dynamics through a supply base concentrated in coastal German manufacturing and resin-integrated North American producers, with downstream price differentiation tracking certification tier rather than geography alone.
Pricing Analysis
Cost-plus contracts with chlorine-alkali indexation dominate procurement between compounders and logistics operators, insulating certified producers from resin volatility while squeezing spot-dependent regional fabricators. Three-tier pricing structure across REACH-compliant premium, BIS-certified standard, and informal economy grades separates machine-grade palletizing straps from hand-tooling round formats. Cost compression in the economy tier intensifies as polypropylene substitution accelerates in light-duty bundling. Mid-sized logistics providers exhibit highest price sensitivity, while export manufacturers prioritize certification compliance over unit cost.
Supply Chain Analysis
Export-control regimes on extrusion die technology limit tooling flows to India and Vietnam, constraining local capacity buildouts and preserving German and Chinese equipment dominance. Resin supply concentrates in Germany, China, and the US Gulf Coast, with PVC pellet sourcing tethered to chlorine-alkali capacity utilization at integrated petrochemical complexes. Single-source vulnerability runs through proprietary die configurations for heavy-duty flat straps. Distribution runs through equipment-consumables bundlers displacing traditional distributor networks, particularly in Indian third-party logistics markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-leasing bundling is reconstituting PVC strap procurement as a platform economy, with interoperability between strapping machinery and consumable supply creating winner-take-most dynamics among vertically integrated compounders.
For Market Incumbents: Harden certification moats by accelerating calcium-zinc stabilizer validation for REACH Annex XVII compliance before reformulation cycles complete. Anchor Baltic Sea and Yangtze River Delta logistics clusters with captive resin sourcing to defend margin position against polypropylene substitution in light-duty segments. Priority rests on extrusion tooling capacity expansion in Vietnam and Mexico before BIS and local standards mature.
For New Entrants and Emerging Players: Pursue corner protector and accessory-grade white space in Indian e-commerce fulfillment, where damage-prevention protocol adoption outpaces certified strap supply. Target Maharashtra and Gujarat pharmaceutical export belts with rental-equipment partnerships that bypass capital barriers for mid-sized logistics operators. Go-to-market leverage centers on BIS pre-certification of tested compounds before incumbent documentation cycles conclude.
For Investors and Strategic Acquirers: EU extended producer responsibility revisions reshape the acquisition landscape toward compounders with established mechanical recycling partnerships and closed-loop recovery economics. Long-term viability favors resin-integrated extruders with coastal logistics positioning over regional fabricators exposed to spot resin markets. Signal to monitor: BIS elongation threshold enforcement intensity in Indian export cargo channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Captive PVC pellet supply insulates Teufelberger Stralsund and Polychem from chlorine-alkali volatility. |
| Equipment-Consumables Bundling Expansion | FROMM Group's rental-heavy model concentrates procurement power with vertically integrated compounders in India. |
| REACH-Compliant Reformulation Investment | Calcium-zinc stabilizer migration filters informal suppliers and opens premium positioning for certified compounders. |
| Coastal Manufacturing Footprint Extension | Just-in-time supply capabilities for Baltic Sea and Yangtze River Delta freight corridors defend logistics-anchored market share. |
| Recycling Partnership Development | Closed-loop recovery economics under EU extended producer responsibility favor early movers in mechanical recycling infrastructure. |
Research Methodology
A spread of perspectives from extrusion plant managers, logistics procurement leads at third-party providers, distribution channel partners, and regulatory affairs directors at compounders converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, BIS certification records, ECHA REACH registration databases, and SEC filings from resin-integrated producers. Bottom-up strap volume estimates by thickness grade and end-use application triangulated against top-down petrochemical capacity assessments.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeling spanning product type, end user archetype, application function, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume projections incorporating machine-grade strap adoption curves in Vietnam and Mexico. Industry-specific forecast inputs included chlorine-alkali capacity utilization rates and automated palletizing infrastructure installation timelines.
Sensitivities concentrate around BIS enforcement intensity in India, REACH Annex XVII amendment timing, and polypropylene substitution elasticity in light-duty bundling. Forecasts reflect documented assumptions on regulatory compliance migration rates and equipment-leasing penetration curves. Material shifts in EU extended producer responsibility implementation scope or USMCA rules-of-origin reinterpretation for nearshored Mexican manufacturing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Child Resistant Zipper Market
Packaging Materials
Packaging Primers Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Global Thin Wall Packaging Market
Packaging Materials
Laminated Tubes Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Textile Packaging Market
Packaging Materials
Card Films Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Africa Packaging Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
Europe Consumer Packaging Market