
 Pallet Corner Boards Market | 2026-2036
Pallet Corner Boards Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Corner Boards Market Analytics
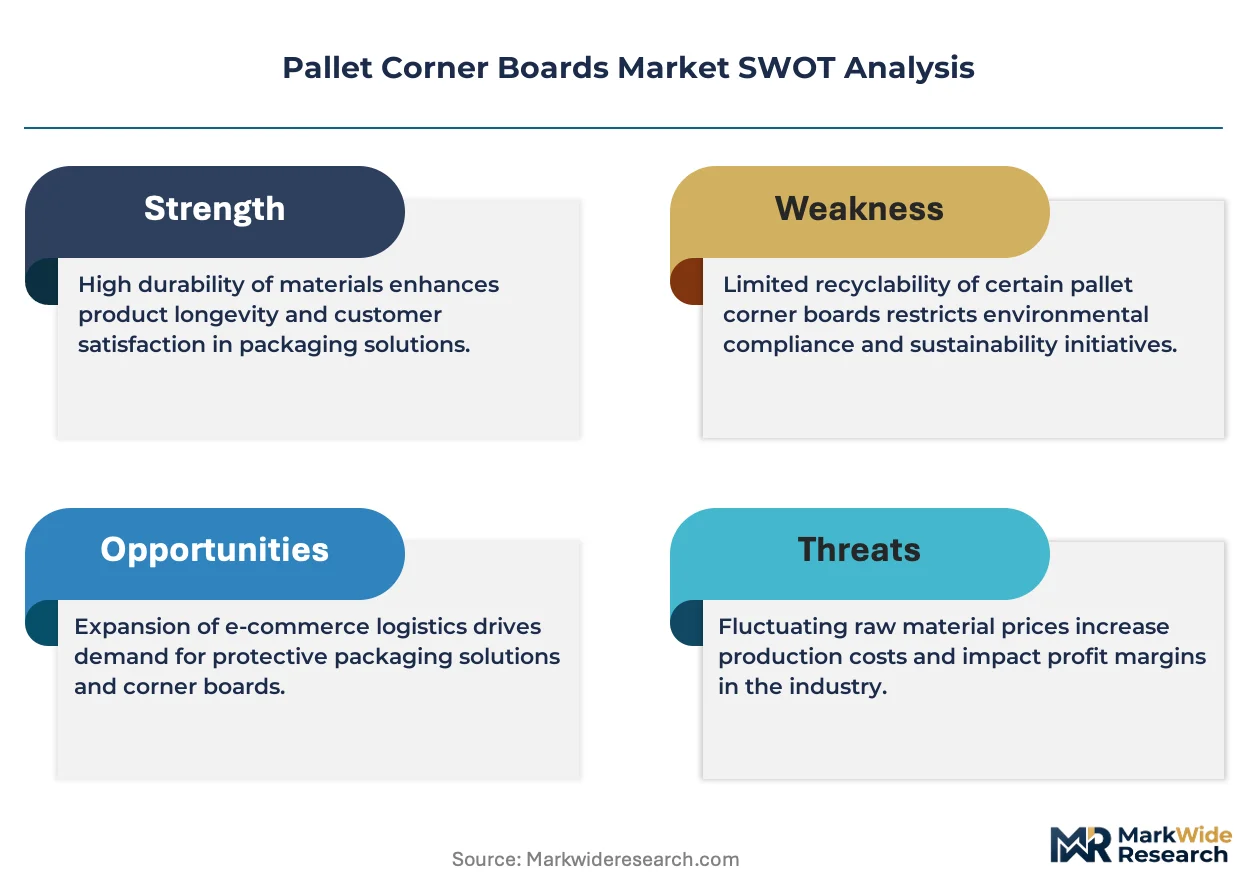
REACH compliance is hardening the cost-of-entry calculus for European pallet corner board suppliers, forcing reformulation of adhesives and surface treatments. Georgia-Pacific LLC leverages its integrated pulp-to-board supply chain to absorb these input cost shifts. Smurfit Kappa Group sustains competitive pressure through its specialized corrugated corner board operations across Benelux plants. Mondi Group anchors its position via kraftliner-based corner boards engineered for moisture resistance in food logistics.
Pallet corner boards are rigid L-shaped or U-shaped protective profiles, typically manufactured from laminated paperboard, solid fiberboard, or extruded plastic, with calipers ranging from 2mm to 10mm and leg lengths from 50mm to 120mm; they shield palletized edges from strapping damage, impact, and compression during transit and warehouse handling. Wood corner boards retain volume leadership in heavy-load shipping applications where crush resistance above 500 psi remains essential, though plastic and composite alternatives are gaining share in electronics and automotive export lanes where weight reduction and moisture immunity command premium positioning. The export application segment carries elevated margin pools due to ISPM-15 phytosanitary certification requirements for wood-based shipping materials.
EPA guidelines on recycled content in federal procurement, ECHA substance restrictions under REACH Annex XVII, and FDA indirect food contact regulations each reshape formulation choices and customer qualification timelines for corner board manufacturers serving regulated end users. The EU Green Deal packaging recyclability targets are accelerating fiber-based substitution away from plastic corner profiles in retail distribution networks. Stakeholders must monitor evolving Extended Producer Responsibility fee structures, as these will determine whether multi-trip plastic corner boards or single-use fiber alternatives deliver lower total cost of ownership across contract logistics operations.
Market Dynamics
EU Packaging and Packaging Waste Regulation enforcement is tightening material traceability mandates, forcing pallet corner board suppliers to requalify adhesive formulations and surface treatments across reusable transport packaging fleets. REACH Annex XVII substance restrictions compound this pressure by prohibiting specific chemistries in fiberboard lamination processes.
Growth Catalysts
- Cold-chain logistics expansion:Food processing operators are mandating corner board specifications that maintain load stability compliance through temperature cycling from frozen distribution centers to retail backrooms.
- REACH reformulation deadlines:ECHA substance restrictions on formaldehyde-based resins are accelerating adoption of bio-based adhesive alternatives in kraftliner corner board manufacturing.
- Automotive inbound standardization:German OEMs are consolidating supplier qualification lists around unified corner board caliper and leg-length specifications across Just-in-Sequence delivery networks.
Market Restraints
- Pulp price volatility:Northern bleached softwood kraft pulp contracts exhibit cyclical swings that compress margins for integrated paperboard corner board producers without captive timber holdings.
- ISPM-15 certification friction:Wood corner board exporters face inspection bottlenecks at ports of entry where phytosanitary compliance documentation triggers customs delays and demurrage costs.
- Plastic profile substitution ceiling:Fiber-based alternatives hit performance limits above 70% relative humidity in uncontrolled warehouse environments, preserving polypropylene corner board demand in tropical logistics lanes.
Strategic Opportunities
- Extended Producer Responsibility alignment:EU Green Deal packaging recyclability targets create first-mover advantage for suppliers offering closed-loop fiber collection programs paired with multi-trip plastic corner board leasing models.
- Moisture-resistant kraftliner formulations:Food logistics operators in Benelux distribution corridors are specifying wax-alternative barrier coatings that maintain edge crush performance through refrigerated supply chains.
- Electronics export lane specialization:Semiconductor and consumer electronics shippers in South Korea are adopting lightweight composite corner profiles that reduce dimensional weight charges in air freight billing.
Industry Challenges
- Adhesive chemist talent scarcity:Formulation specialists capable of balancing REACH compliance with bond strength requirements command premium compensation in European pulp-to-board integrated operations.
- Multi-jurisdiction certification timelines:Suppliers serving both FDA indirect food contact and EFSA material migration limits must maintain parallel testing protocols that extend product launch cycles by quarters.
- Legacy strapping equipment compatibility:Automated stretch-wrapping lines in contract logistics warehouses require corner board leg-length tolerances within millimeter bands that strain extrusion and laminating process controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Corner Boards Market |
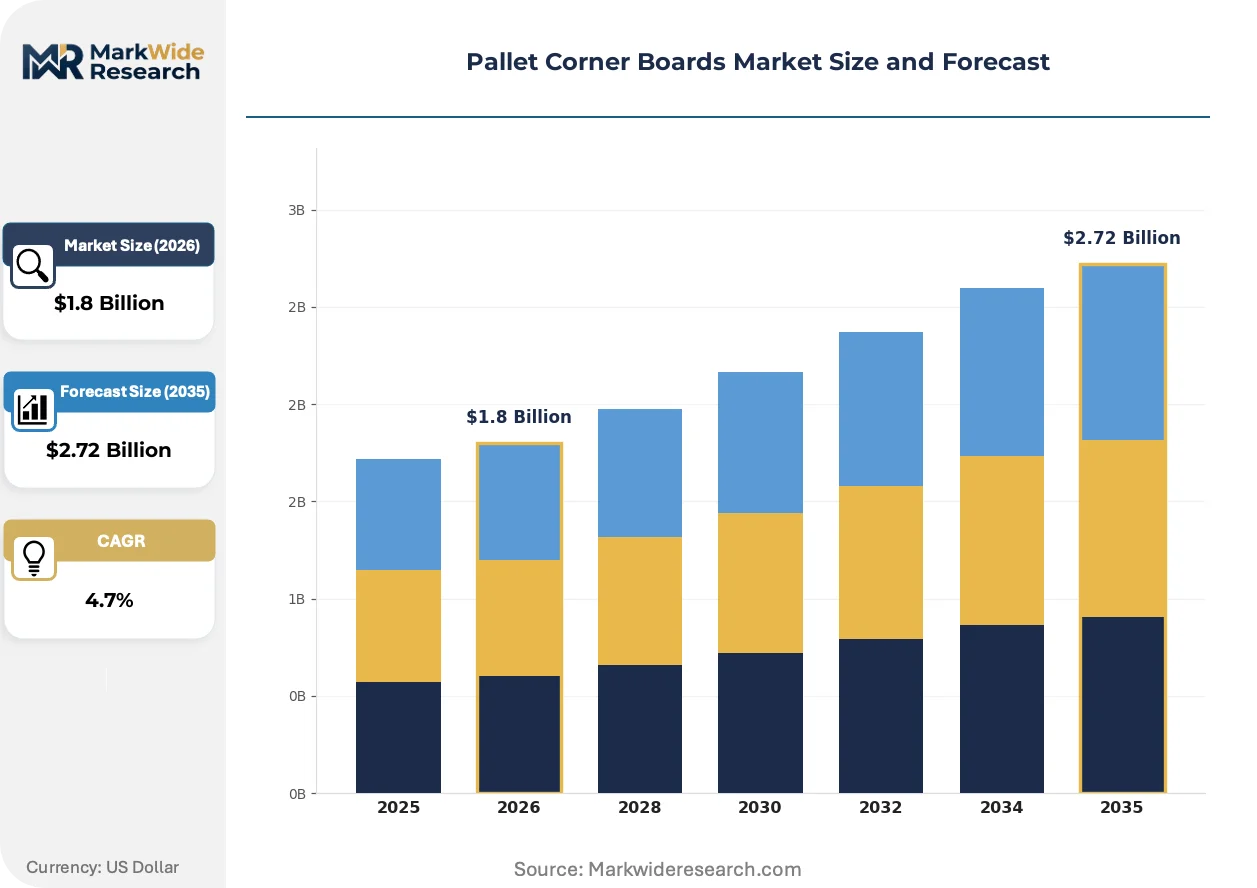
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Plastic, Metal, Composite End User: Retail, Automotive, Food Processing, Electronics Application: Shipping, Storage, Export, Distribution Packaging Type: Cardboard, Stretch Film, Shrink Wrap, Others |
| Companies Covered | Signode Industrial Group, Smurfit Kappa Group, Georgia-Pacific LLC, Sonoco Products Company, Cascades Inc., Mondi Group, DS Smith Plc, Packaging Corporation of America, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Corner Boards Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to reshape corner board specifications across temperature-controlled and export-heavy logistics corridors. Suppliers are repositioning around barrier performance and circularity credentials rather than commodity cost positioning.
Recycled-content paperboard formulations incorporating post-consumer fiber streams are absorbing moisture-resistance requirements previously met by plastic alternatives. Cold-chain operators in dairy and produce distribution are specifying these profiles for secondary packaging layers where condensation exposure is intermittent rather than sustained. The technology is absorbing market share from polypropylene in European retail distribution networks where EU Green Deal recyclability targets favor fiber-based solutions.
EPA recycled content guidelines for federal procurement are tightening domestic sourcing requirements for wood and paper-based shipping materials. Federal supply schedules now mandate minimum post-consumer fiber percentages that disqualify virgin pulp corner boards from defense and civilian agency contracts. Suppliers with integrated recycling streams in the southeastern United States are capturing qualification advantages in this channel.
Buyer consolidation among third-party logistics providers is compressing supplier qualification cycles and unbundling after-sales technical service from unit pricing. Large contract logistics operators in Germany and the Netherlands are deploying centralized procurement platforms that standardize corner board specifications across multi-site warehouse networks. This pattern concentrates volume with suppliers capable of delivering consistent caliper tolerances at scale across regional distribution footprints.
Pallet Corner Boards Market Segmentation
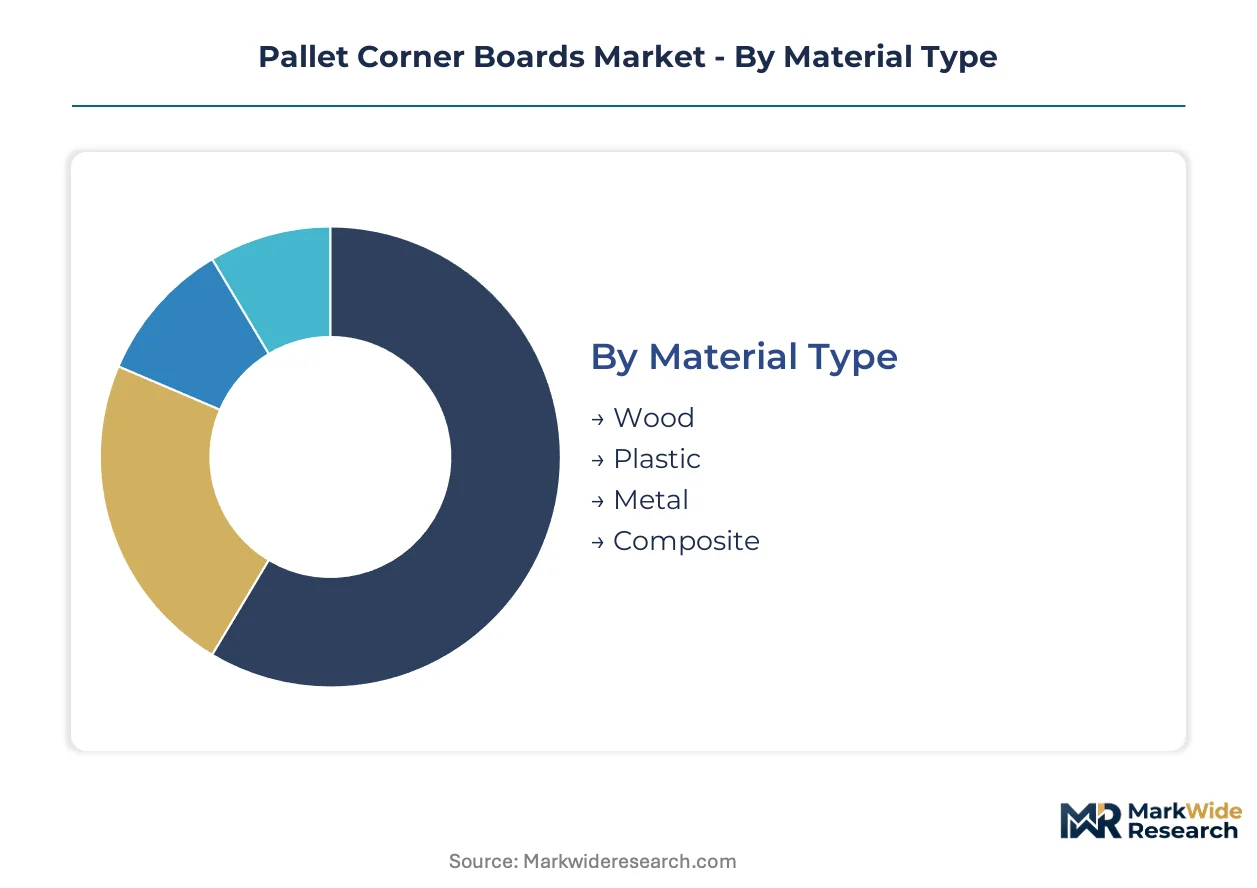
Corner board specification varies sharply by load weight, environmental exposure, and regulatory jurisdiction. Buyers select material and profile geometry based on strapping tension requirements, humidity conditions, and phytosanitary certification needs.
Material Type:
Cost tier and performance ceiling drive material selection, with crush resistance and moisture immunity commanding premium positioning.
- Wood:Solid wood corner boards deliver crush resistance above 500 psi through dense hardwood laminates or finger-jointed pine. German automotive OEMs standardize wood profiles for Just-in-Sequence inbound supply chains where load stability failures trigger line-stop penalties.
- Plastic:Extruded polypropylene and high-density polyethylene profiles offer complete moisture immunity and consistent caliper tolerances within millimeter bands. Cold-chain logistics operators in Benelux dairy distribution specify plastic corner boards where condensation exposure exceeds 70% relative humidity.
- Metal:Steel and aluminum corner profiles serve extreme heavy-load applications in machinery and industrial equipment shipping. These profiles withstand strapping tensions that fracture fiberboard alternatives.
- Composite:Hybrid formulations combining kraftliner facings with plastic cores reduce dimensional weight for air freight billing. South Korean electronics exporters specify these profiles for semiconductor shipments.
Wood leads on scale; composite leads on momentum.
End User:
Application intensity and qualification rigor vary by sector, with food contact compliance and export certification creating divergent buyer requirements.
- Retail:Mass merchandisers and grocery chains specify recycled-content fiberboard corner boards for store-ready pallet displays. EPA recycled content guidelines for federal procurement are tightening domestic sourcing requirements that favor integrated recycling streams in the southeastern United States.
- Automotive:Tier suppliers face unified caliper and leg-length specifications across German OEM delivery networks. Load stability compliance failures trigger line-stop penalties that dwarf corner board unit costs.
- Food Processing:Dairy and produce distributors mandate moisture-resistant formulations that maintain edge crush performance through refrigerated supply chains. FDA indirect food contact regulations and EFSA material migration limits require parallel testing protocols.
- Electronics:Semiconductor and consumer electronics shippers prioritize lightweight profiles that reduce dimensional weight charges. ISPM-15 phytosanitary certification requirements for wood-based materials drive substitution toward plastic and composite alternatives.
Automotive leads on specification rigor; food processing leads on regulatory-driven reformulation.
Application:
Transit distance and handling frequency determine profile durability requirements and certification needs.
- Shipping:Long-haul freight corridors demand corner boards that withstand repeated forklift impact and automated stretch-wrapping tension. Wood profiles retain dominance in domestic heavy-load lanes.
- Storage:Warehouse racking applications prioritize vertical load distribution and stack stability over impact resistance. Standard caliper specifications suffice for controlled indoor environments.
- Export:International lanes carry elevated margin pools due to ISPM-15 phytosanitary certification requirements. Inspection bottlenecks at ports of entry trigger customs delays that favor pre-certified suppliers.
- Distribution:Multi-stop delivery networks require corner boards that tolerate temperature cycling from frozen distribution centers to retail backrooms. Cold-chain operators specify barrier-coated fiberboard or plastic alternatives.
Export leads on margin capture; distribution leads on volume expansion.
Packaging Type:
Secondary packaging integration determines corner board leg-length tolerances and surface friction requirements.
- Cardboard:Corrugated shrouds and full overwraps require corner boards with compatible crush characteristics and adhesive bonding surfaces. Smurfit Kappa Group specializes in integrated corrugated corner board systems.
- Stretch Film:Automated wrapping lines demand precise leg-length tolerances within millimeter bands to prevent film puncture and load rotation. Mondi Group engineers kraftliner-based profiles for high-speed equipment compatibility.
- Shrink Wrap:Heat-activated films require corner boards with thermal stability and low-friction surfaces that prevent film adhesion during tunnel passage.
- Others:Strapping-only and banding applications use narrow-profile corner boards designed for steel or polyester strap channels.
Stretch film leads on equipment integration; cardboard leads on sustainability positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized adhesive chemists and pulp-to-board process engineers concentrate in Germany and the Benelux corridor, anchoring European formulation capabilities for REACH-compliant corner board production.
United States
Defense and civilian agency procurement through federal supply schedules drives specification rigor for recycled-content corner boards. EPA guidelines on post-consumer fiber percentages now disqualify virgin pulp alternatives from federal contracts. Integrated recycling streams in Georgia and the Carolinas capture qualification advantages for domestic pulp-to-board producers.
Germany
Automotive OEMs standardize corner board caliper and leg-length specifications across Just-in-Sequence delivery networks. KBA vehicle certification protocols indirectly pressure inbound packaging consistency to prevent line-stop penalties. Stuttgart and Wolfsburg industrial clusters consolidate supplier qualification lists around unified dimensional tolerances.
Netherlands
Dairy and produce distributors in Rotterdam-Antwerp corridor mandate moisture-resistant formulations for refrigerated supply chains. EFSA material migration limits require parallel testing protocols alongside FDA standards for exporters serving dual jurisdictions. Cold-chain operators specify barrier-coated fiberboard where condensation exposure remains intermittent.
China
Electronics exporters in Shenzhen and Dongguan adopt lightweight composite corner profiles to reduce dimensional weight charges in air freight billing. GB standards for packaging materials tighten quality consistency requirements for cross-border e-commerce shipments. Yangtze River Delta manufacturers scale composite formulations for semiconductor and consumer electronics lanes.
South Korea
Semiconductor shippers in Seoul Capital Area and Busan-Ulsan corridor prioritize composite corner boards for moisture immunity and weight reduction. MFDS food contact regulations shape barrier coating specifications for agricultural export packaging. Daegu-Gyeongbuk logistics hubs standardize composite profiles for temperature-sensitive electronics distribution.
Pallet Corner Boards Market Competitive Landscape
The competitive structure tilts toward integrated pulp-to-board conglomerates with captive timber holdings and specialized corrugated operations. Tier-one suppliers absorb input cost volatility through backward integration into kraftliner production, while mid-scale specialists compete on equipment compatibility and regional service density. Three archetypes dominate: vertically integrated paperboard producers, corrugated packaging specialists with corner board divisions, and plastics extruders pivoting toward composite formulations. Consolidation proceeds through asset acquisitions in Benelux and capacity expansion in southeastern United States recycling corridors.
Within the integrated conglomerate tier, Georgia-Pacific LLC and WestRock Company exemplify scale-driven positioning through captive pulp supply chains. Smurfit Kappa Group and Mondi Group occupy specialist positions anchored in European corrugated and kraftliner operations. These four represent divergent strategic postures: North American vertical integration against European formulation specialization.
| Leading Market Players |
|---|
| Signode Industrial Group |
| Smurfit Kappa Group |
| Georgia-Pacific LLC |
| Sonoco Products Company |
| Cascades Inc. |
| Mondi Group |
| DS Smith Plc |
| Packaging Corporation of America |
| WestRock Company |
| Others |
Value Network & Pricing Analysis
Northern bleached softwood kraft pulp contract volatility cascades through pallet corner board supply chains, compressing margins for non-integrated producers while amplifying pricing power for conglomerates with captive timber holdings across Georgia and the Carolinas. This input cost dynamic stratifies the market into three distinct tiers: premium moisture-resistant kraftliner formulations for cold-chain logistics, standard recycled-content fiberboard for retail distribution, and economy-grade wood profiles for domestic heavy-load shipping.
Pricing Analysis
Buyer consolidation among third-party logistics providers is unbundling after-sales technical service from unit pricing, forcing suppliers to compete on pure equipment compatibility and caliper tolerance consistency. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—REACH-compliant adhesive formulations command 15-25% premiums over conventional alternatives. Cost compression in the standard tier is intensifying because large German automotive OEMs are consolidating supplier qualification lists around unified dimensional specifications. Mass merchandisers exhibit highest price sensitivity due to thin retail margins, while cold-chain operators demonstrate lowest sensitivity given compliance failure costs that dwarf packaging unit economics.
Supply Chain Analysis
Reverse-logistics flows for reusable plastic corner boards are creating closed-loop collection programs in Benelux dairy distribution networks, where multi-trip leasing models compete against single-use fiber alternatives on total cost-of-ownership metrics. Manufacturing concentration centers on Germany, the United States, and China, with specialized adhesive chemists and pulp-to-board process engineers anchoring European formulation capabilities. Raw material sourcing draws from Northern bleached softwood kraft pulp, post-consumer recycled fiber streams, and bio-based adhesive alternatives. Single-source vulnerability persists for REACH-compliant adhesive formulations where ECHA substance restrictions have eliminated multiple legacy chemistries. Distribution runs through centralized procurement platforms operated by large contract logistics operators in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pallet corner boards function as a stable compounder anchored by regulatory-driven material reformulation cycles that perpetually refresh supplier qualification requirements and sustain incumbent pricing power.
For Market Incumbents: Anticipate REACH Annex XVII expansion by accelerating bio-based adhesive R&D partnerships and locking in multi-year kraftliner supply agreements before pulp price cyclicality intensifies. Defensive consolidation should prioritize corrugated specialists in Benelux with established EFSA material migration testing protocols, as these capabilities represent scarce qualifications that new entrants cannot replicate quickly. Capacity addition in southeastern United States recycling corridors captures EPA federal procurement advantages. For New Entrants and Emerging Players: E-commerce packaging procurement platforms offer the most penetrable entry vector, bypassing entrenched relationships with automotive OEMs and cold-chain operators. Target South Korean electronics export lanes where lightweight composite corner profiles face minimal incumbent saturation and air freight dimensional weight savings justify premium positioning. A technical service-heavy go-to-market approach—embedding formulation specialists at shipper sites—differentiates against commodity fiberboard suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs have stranded mid-scale producers without backward integration into pulp supply or specialized testing infrastructure. The five-to-ten year viability window favors integrated conglomerates with captive timber holdings and regional recycling stream control. Acquisition target archetype: corrugated packaging specialists with established corner board divisions and existing EFSA/FDA dual-qualification protocols. The signal to watch is Extended Producer Responsibility fee structure finalization in EU member states, which will determine whether fiber or plastic corner boards achieve lower total cost-of-ownership in contract logistics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraftliner Production | Georgia-Pacific absorbs pulp price volatility through captive supply chains in southeastern United States. |
| REACH-Compliant Adhesive Reformulation | Smurfit Kappa Group maintains European market access as ECHA restrictions eliminate legacy resin chemistries. |
| Moisture-Resistant Barrier Coating Development | Mondi Group captures cold-chain specifications in Benelux dairy distribution through wax-alternative formulations. |
| Multi-Trip Plastic Corner Board Leasing | Closed-loop collection programs align with EU Green Deal recyclability targets and EPR fee optimization. |
| Composite Profile Air Freight Specialization | South Korean electronics exporters reduce dimensional weight charges through lightweight hybrid formulations. |
Research Methodology
Bottom-up food processing and automotive demand modeling reconciled against top-down pulp-to-board capacity tracking forms the analytical core of this study. Primary interviews with procurement managers at third-party logistics providers, adhesive formulation specialists at integrated paperboard producers, regulatory affairs leads at packaging manufacturers, and equipment engineers at automated stretch-wrapping OEMs were cross-validated against secondary sources including ECHA substance restriction databases, EPA recycled content procurement guidelines, SEC 10-K filings of publicly traded packaging conglomerates, and customs trade data for wood-based shipping materials.
Input-output matrices mapping kraftliner production volumes to corner board caliper specifications across material type, end-use sector, and application intensity generated segment-level demand estimates over the projection horizon. Segmentation dimensions modeled include material substrate, load weight tier, environmental exposure condition, and regulatory jurisdiction cluster. CAGRs were derived from trend extrapolation of qualification cycle frequencies and substitution elasticity between fiber and plastic alternatives. Industry-specific forecast inputs incorporated REACH reformulation deadline compliance rates and ISPM-15 certification inspection bottleneck severity at major ports.
The model assumes a particular technology adoption path; alternative pathways for bio-based adhesive scale-up or composite extrusion cost reduction would alter the outlook for material substitution timelines. Forecasts reflect assumptions regarding regulatory enforcement consistency and pulp price cyclicality persistence. Practitioners should monitor ECHA Annex XVII expansion proposals, EU EPR fee structure finalization, and federal procurement guideline updates for early signals of qualification requirement shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
Europe Pallet Wrapping Machine Market
Pallets Packaging
Pallet Packaging Market
Pallets Packaging
Pallet Wraps Market
Pallets Packaging
Corrugated Pallets Market
Pallets Packaging
Pallet Labeler Market
Pallets Packaging
Europe Pallet Market
Pallets Packaging
Disposable Plastic Pallet Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
Indonesia Pallets Market
Pallets Packaging
Middle East Pallets Market
Pallets Packaging
Empty Fruit Bunch Pallets Market
Pallets Packaging
Wooden Pallet Collars Market
Pallets Packaging
Paper Pallet Market