
 Concentrate Containers Market | 2026-2036
Concentrate Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Concentrate Containers Market Outlook
California's concentrate processor network is repositioning toward higher-volume packaging formats as extraction yields improve. Berry Global Inc. leverages its thermoforming scale to supply child-resistant containers across the Southwest. Amcor plc sustains barrier film expertise that extends shelf stability for terpene-sensitive concentrates. Kush Bottles anchors direct distribution through cannabis-specific wholesale channels that bypass conventional packaging brokers.
Concentrate containers are purpose-built receptacles engineered from FDA-compliant polypropylene or borosilicate glass with hermetic sealing interfaces to prevent oxidation and preserve cannabinoid potency. These units serve the legal cannabis industry's need for compliant storage, transport, and retail presentation of extracted oils, waxes, and shatter. Glass jars dominate premium solventless segments where visual product inspection drives purchasing decisions, while polyethylene bottles capture volume in hydrocarbon extraction categories where opacity supports UV protection. Tamper-evident closure systems command margin premiums as state regulators tighten chain-of-custody documentation requirements.
FDA food-contact substance notifications and CPSC child-resistant packaging standards create dual compliance thresholds that filter out commodity suppliers lacking testing infrastructure. EPA guidelines on volatile organic compound emissions from packaging manufacturing facilities add environmental compliance layers in production-heavy states. Stakeholders must monitor evolving state cannabis agency rules on labeling, batch tracking, and minimum packaging opacity as these specifications directly dictate material selection and mold investment cycles.
Market Dynamics
State-level cannabis legalization cascades across the United States, forcing concentrate processors to retool packaging lines for child-resistant compliance while extraction yields climb and SKU proliferation accelerates container format diversification.
Growth Catalysts
- Hydrocarbon extraction expansion:Butane and propane extraction methods in Colorado and Michigan drive demand for opaque polyethylene bottles that block UV degradation of terpene-rich concentrates.
- CPSC child-resistant mandates:Federal packaging standards compel dispensaries to source certified containers, eliminating uncertified commodity suppliers from approved vendor lists.
- Solventless premium segmentation:Rosin and ice-water hash processors in California favor borosilicate glass jars with hermetic seals to showcase product clarity and preserve volatile aromatic compounds.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings squeeze converter margins, particularly for mid-tier thermoformers lacking long-term resin hedging contracts.
- Testing infrastructure concentration:FDA food-contact notification capabilities cluster with large multi-site converters, excluding regional molders from premium concentrate container contracts.
- Glass logistics fragility:Borosilicate jar breakage rates during interstate transport elevate insurance and replacement costs for solventless distributors.
Strategic Opportunities
- Illinois processor buildout:Limited-license cannabis markets in the Midwest present first-mover container supply contracts as extraction capacity comes online.
- Terpenes preservation coatings:Barrier film innovations that extend shelf stability for oxidation-sensitive live resin formats command pricing premiums from craft processors.
- Direct-to-processor distribution:Bypassing conventional packaging brokers through cannabis-specific wholesale channels reduces lead times for urgent SKU launches.
Industry Challenges
- Child-resistant certification timelines:CPSC protocol testing cycles extend six to nine months, delaying new container launches past seasonal concentrate demand peaks.
- Mold capital intensity:Custom tamper-evident closure systems require dedicated injection tooling investments that strain converter balance sheets during state regulatory transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concentrate Containers Market |
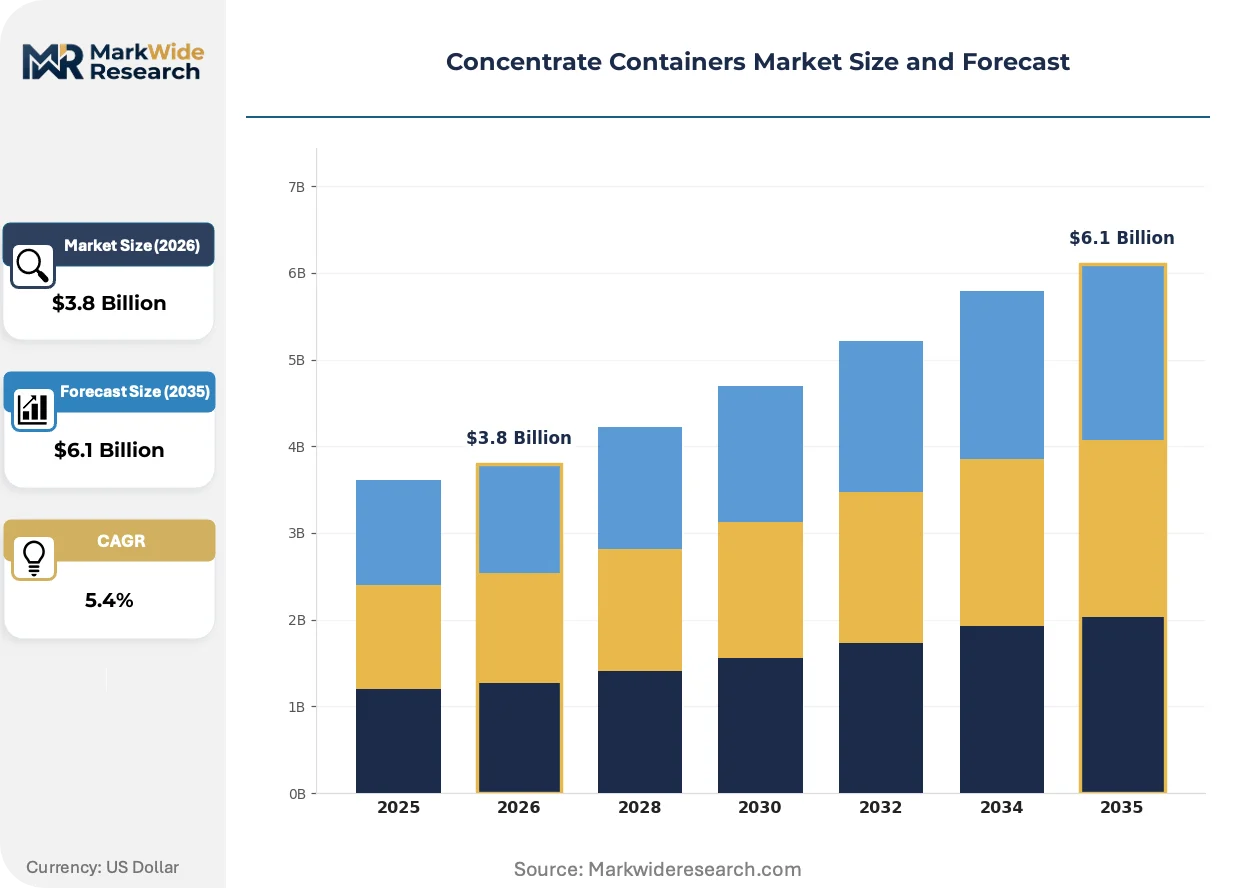
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bottles, Glass Jars, Metal Cans, Flexible Pouches Capacity: Small (100-500ml), Medium (500ml-1L), Large (1-5L), Extra Large (5L+) Material: Polyethylene, Polypropylene, Glass, Aluminum Closure Type: Screw Caps, Snap Caps, Flip Tops, Tamper Evident |
| Companies Covered | Marijuana Packaging, Kush Bottles, Cannaline, Smoke Weed, KushMart, Gem Packaging, Berry Global Inc., Amcor plc, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concentrate Containers Market Strategic Shifts
Automation and regulatory precision reshape how concentrate containers are specified, produced, and distributed. Material science advances collide with evolving compliance mandates to redefine competitive differentiation.
Inline vision inspection systems are automating defect detection in child-resistant closure assembly, cutting manual quality labor from converter operations. Large-scale thermoformers in California deploy these systems to maintain CPSC certification consistency across high-volume polypropylene runs. The technology is automating quality assurance staffing models that previously consumed fifteen to twenty percent of plant headcount.
California's Department of Cannabis Control tightened batch tracking and chain-of-custody documentation requirements for concentrate packaging in 2023. Dispensaries now demand tamper-evident features with serialized QR codes linking to state traceability databases. Hydrocarbon processors face the steepest compliance burden, retrofitting inventory systems to capture container-level lineage data.
Processor procurement teams consolidate vendor relationships from twelve to fifteen suppliers down to three or four full-service converters. Live resin and sauce manufacturers in Michigan prioritize partners offering in-house design, mold fabrication, and regulatory documentation under single contracts. This consolidation concentrates volume with vertically integrated packaging suppliers who control resin sourcing through captive compounding operations.
Concentrate Containers Market Segmentation
Concentrate container specifications cascade from extraction method requirements through retail compliance mandates. Each segmentation dimension carries distinct certification burdens that filter supplier capabilities and reshape procurement patterns across state-legal cannabis markets.
Product Type:
FDA food-contact notifications and CPSC child-resistant certification requirements apply unevenly across container formats, with some segments demanding dual testing protocols while others navigate single-agency pathways.
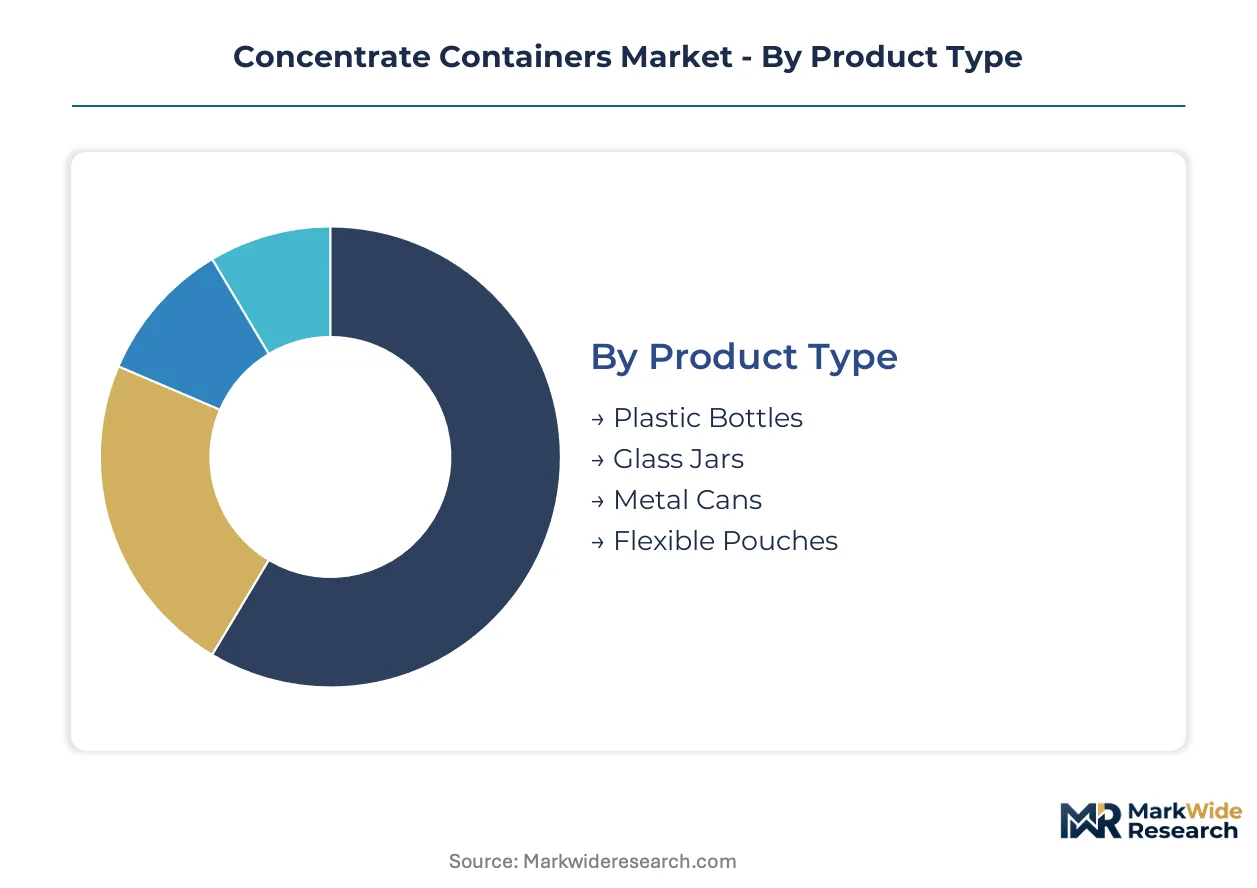
- Plastic Bottles:Opaque polyethylene constructions dominate hydrocarbon extraction categories where UV blocking preserves terpene potency. Michigan and Colorado processors specify these for live resin and sauce formats where oxidation sensitivity demands barrier protection. Child-resistant certification cycles for polyethylene closures run six to nine months, eliminating suppliers lacking dedicated testing infrastructure.
- Glass Jars:Borosilicate constructions with hermetic sealing interfaces serve California's solventless premium segment. Rosin and ice-water hash processors favor visual product inspection capabilities that drive purchasing decisions at dispensary counters. Interstate logistics elevate replacement costs due to breakage rates during transport.
- Metal Cans:Aluminum formats with internal liners address niche solventless applications requiring complete light exclusion.
- Flexible Pouches:Multi-layer barrier films capture emerging disposable vape cartridge pre-fill segments in Illinois buildout markets.
Plastic bottles sit at the top of the volume ranking, with flexible pouches climbing the fastest as disposable format adoption accelerates.
Capacity:
Format selection tracks directly against extraction batch economics and dispensary inventory turnover velocity, with smaller capacities commanding per-unit premiums that compress at volume tiers.
- Small (100-500ml):Single-serve and sample formats dominate California craft processor portfolios where SKU proliferation strategies target connoisseur segmentation. These capacities carry the highest per-milliliter packaging cost burden, pressuring margin structures for boutique operators.
- Medium (500ml-1L):Standard retail units balance shelf presence with inventory efficiency across Colorado dispensary networks. This tier captures the broadest processor adoption as extraction yields stabilize and wholesale packaging standardizes.
- Large (1-5L):Bulk storage formats serve processor-to-processor B2B transfers in Michigan's vertically integrated supply chains.
- Extra Large (5L+):Industrial totes address raw extract accumulation prior to final packaging conversion.
Medium capacities anchor current procurement volumes, though small formats are expanding most quickly as craft segmentation deepens.
Material:
Resin selection determines compliance pathway complexity, with petroleum-derived polymers facing distinct regulatory scrutiny versus inorganic alternatives.
- Polyethylene:HDPE and LDPE grades dominate hydrocarbon extraction packaging where opacity and chemical resistance prove essential. Feedstock price volatility squeezes converter margins, particularly for mid-tier thermoformers lacking long-term hedging contracts.
- Polypropylene:Thermoformed constructions serve child-resistant compliance requirements across Southwest processor networks. Berry Global leverages multi-site compounding scale to stabilize resin access for high-volume contracts.
- Glass:Borosilicate and soda-lime variants split across premium and economy solventless positioning.
- Aluminum:Lightweight metal formats address specific light-sensitive extract categories with secondary liner requirements.
Polyethylene maintains volume leadership, while glass is gaining share fastest as solventless premiumization accelerates in California.
Closure Type:
Child-resistant functionality and chain-of-custody documentation requirements elevate closure specification complexity beyond commodity hardware selection.
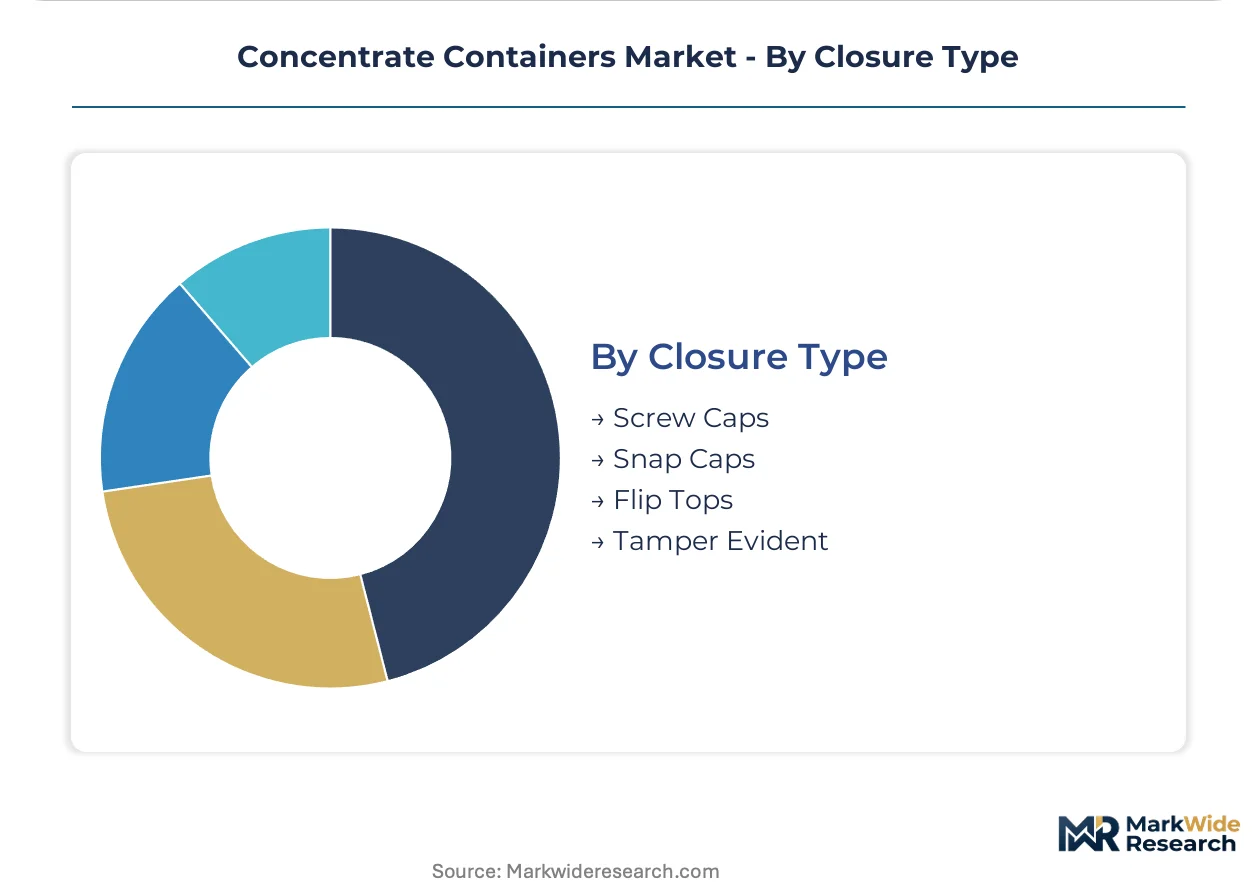
- Screw Caps:Threaded polyethylene and polypropylene constructions dominate CPSC-certified applications where push-and-turn mechanisms satisfy federal mandates. California's Department of Cannabis Control requires these for all retail-facing concentrate packaging.
- Snap Caps:Press-fit designs serve non-child-resistant B2B transfer applications where regulatory burden relaxes.
- Flip Tops:Hinged constructions address convenience positioning in adult-use markets with modified child-resistant protocols.
- Tamper Evident:Break-band and shrink-sleeve systems command margin premiums as state regulators tighten batch tracking requirements. Serialized QR code integration now links individual containers to state traceability databases.
Screw caps hold the top volume position, with tamper evident systems showing the steepest expansion trajectory as documentation mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics concentrate concentrate container manufacturing in jurisdictions with lower compliance-cost burdens, while state-level cannabis legalization patterns dictate demand geography. Production migrates toward regions with established polymer processing infrastructure and favorable permitting regimes.
United States
California's Department of Cannabis Control mandates serialized QR codes linking containers to state traceability databases, tightening documentation requirements for hydrocarbon processors. FDA food-contact notifications and CPSC child-resistant certification create dual compliance thresholds that filter out commodity suppliers. Los Angeles and Oakland extraction clusters drive premium borosilicate glass demand for solventless rosin presentation.
Canada
Health Canada cannabis regulations standardize child-resistant packaging across federal and provincial markets, reducing regulatory fragmentation versus US state-by-state variance. British Columbia and Ontario concentrate processors favor polyethylene bottles with barrier properties for live resin oxidation protection. Vancouver's extraction equipment manufacturing base supports adjacent container supply chain development.
Germany
BfArM medical cannabis licensing creates container demand for pharmaceutical-grade extract distribution through pharmacy channels. EU MDR and REACH compliance requirements elevate material certification burdens for polypropylene suppliers. Berlin's emerging cannabis processing pilot programs test hermetic sealing specifications for imported concentrate stability.
Netherlands
Office of Medicinal Cannabis regulations govern container specifications for domestic medical extract distribution and export qualification. Rotterdam's polymer logistics hub facilitates resin access for European thermoformers serving cannabis packaging contracts. Amsterdam coffee shop regulatory tolerance creates parallel demand for non-medical concentrate storage formats.
Australia
TGA medical cannabis framework mandates child-resistant packaging with batch-level documentation for concentrate products through authorized prescriber channels. Victoria and New South Wales extraction facility buildouts drive container procurement as domestic processing capacity scales. Melbourne's pharmaceutical packaging converter base adapts FDA-compliant polypropylene lines for cannabis-specific contracts.
Concentrate Containers Market Competitive Environment
United States producers anchor one tier; European specialists hold certification-advantaged positions in medical-regulated markets. The vendor base splits between multi-site polymer converters with captive compounding operations and regional molders serving single-state cannabis markets. Three archetypes dominate: vertically integrated resin-to-container suppliers, cannabis-dedicated distributors with direct processor relationships, and diversified packaging conglomerates leveraging barrier film expertise. Competitive moves center on CPSC certification pre-positioning ahead of state legalization waves and mold-fabrication capacity expansion to capture SKU proliferation demand.
Within the cannabis-dedicated distribution tier, Kush Bottles and Marijuana Packaging exemplify direct-to-processor channel strategies that bypass conventional packaging brokers. Among diversified industrial converters, Berry Global Inc. and Amcor plc occupy positions anchored by multi-site thermoforming scale and barrier film technology portfolios. These named entities represent archetype endpoints rather than exhaustive market coverage, with additional competition emerging from regional molders and emerging cannabis-specific packaging ventures.
| Leading Market Players |
|---|
| Marijuana Packaging |
| Kush Bottles |
| Cannaline |
| Smoke Weed |
| KushMart |
| Gem Packaging |
| Berry Global Inc. |
| Amcor plc |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
Processor procurement consolidation from twelve to fifteen suppliers down to three or four full-service converters forces mid-tier thermoformers to absorb resin volatility or surrender volume to vertically integrated competitors with captive compounding operations.
Pricing Analysis
Distributor margin compression runs through cannabis-specific wholesale channels as direct-to-processor distribution bypasses conventional packaging brokers. Three-tier pricing structure across premium, standard, and economy levels separates CPSC-certified child-resistant containers with serialized QR codes from uncertified commodity alternatives. Pricing pressure stems from polypropylene feedstock volatility squeezing converter margins, particularly for mid-tier thermoformers lacking long-term hedging contracts. Craft processors in California's solventless segment show least price sensitivity, while hydrocarbon extraction operations in Michigan prioritize per-unit cost minimization.
Supply Chain Analysis
Reverse-logistics flows for borosilicate glass jars elevate replacement costs as breakage rates during interstate transport trigger insurance claims and inventory replenishment cycles. Manufacturing concentration centers on the United States, Canada, and Germany where FDA, Health Canada, and BfArM compliance infrastructures filter supplier participation. Raw material dependencies draw from petroleum-derived polypropylene resins, borosilicate glass feedstock, and aluminum sheet stock. Single-source vulnerability sits with CPSC-certified child-resistant closure testing facilities where six-to-nine-month certification cycles create bottlenecks. Distribution runs through cannabis-dedicated wholesale channels that bypass conventional packaging brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate with converters who achieve backward integration into resin compounding and capture premium-tier positioning through CPSC certification pre-positioning ahead of state legalization waves.
For Market Incumbents: Cement CPSC certification consistency across multi-site thermoforming operations to defend against emerging regional molders lacking testing infrastructure. Add captive compounding capacity in California or Michigan to neutralize polypropylene resin volatility. Channel control through cannabis-specific wholesale relationships protects against distributor margin compression. For New Entrants and Emerging Players: Begin with Illinois processor buildout markets where limited-license cannabis frameworks present first-mover container supply contracts as extraction capacity comes online. Target flexible pouch formats for disposable vape cartridge pre-fill segments where barrier film innovation commands pricing premiums. Go-to-market angle should emphasize in-house design, mold fabrication, and regulatory documentation under single contracts. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated resin-to-container suppliers who control compounding operations and maintain CPSC certification across multiple state markets. Five-to-ten-year viability favors converters with mold-fabrication capacity expansion to capture SKU proliferation demand. Monitor state cannabis agency rule changes on labeling, batch tracking, and minimum packaging opacity as inflection indicators for material selection and mold investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| CPSC Certification Pre-Positioning | FDA and CPSC dual compliance thresholds filter out commodity suppliers lacking testing infrastructure. |
| Backward Integration into Resin Compounding | Captive polypropylene supply stabilizes margins against feedstock volatility squeezing mid-tier thermoformers. |
| Mold Fabrication Capacity Expansion | Custom tamper-evident closure tooling captures SKU proliferation demand from live resin and sauce manufacturers. |
| Direct-to-Processor Distribution | Cannabis-specific wholesale channels bypass conventional packaging brokers and reduce lead times. |
| Barrier Film Innovation | Terpenes preservation coatings command pricing premiums from craft processors for oxidation-sensitive live resin formats. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with concentrate processors, packaging procurement managers, thermoforming plant operators, and regulatory compliance officers with secondary validation against FDA food-contact substance notifications, CPSC certification databases, state cannabis agency rule filings, and customs trade records. Bottom-up volume estimates from processor packaging line configurations triangulated against top-down resin consumption patterns across the analysis window.
Historical reference periods anchored the forecast framework to extraction yield improvements, state legalization cascades, and SKU proliferation rates observed across prior regulatory transitions. Segmentation dimensions modeled include product type, capacity tier, material grade, and closure certification level alongside extraction method requirements and retail compliance mandates. CAGRs derived from processor capacity buildout pipelines and dispensary density projections incorporated polypropylene resin price trajectory assumptions and child-resistant certification timeline constraints.
Several conditions sit outside the modeled scope, including federal cannabis rescheduling decisions, interstate commerce authorization, and breakthrough material substitutions displacing polypropylene or borosilicate glass. Forecasts reflect assumptions around state-level legalization continuity and CPSC protocol stability. Practitioners should monitor EPA volatile organic compound emission guideline revisions and state traceability database integration requirements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Container Coating Market
Containers
2 Piece Cans Market
Containers
Multi-Layer Blow Molded Containers Market
Containers
Container Stacking Machine Market
Containers
Pinch Grip Jars Market
Containers
Container Market
Containers
Cylindrical Cans Market
Containers
Die Cut Display Container Market
Containers
Screw Top Lids Market
Containers
PVC Container Market
Containers
Dispensing Jug Market
Containers
Foam Hinged Take-Out Containers Market
Containers
Flexible Water Tanks Market
Containers
Popcorn Containers Market
Containers
Disposable Cups and Lids Market
Containers
Twist Up Stick Container Market