
 Takeout Containers Market | 2026-2036
Takeout Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Takeout Containers Market Outlook
A wide capital-intensity gap between integrated converters and specialty players is rotating strategic investment toward automated thermoforming and pulp-molding lines. Pactiv Evergreen leverages its North American manufacturing footprint to sustain cost advantages in foam and paperboard categories. Amcor PLC anchors global film and barrier technology leadership, competing across multi-material flexible formats. Graphic Packaging International specializes in coated paperboard solutions, dominating quick-service restaurant supply contracts through direct mill-to-restaurant logistics.
Takeout containers are engineered food-contact vessels manufactured from plastic resins, paperboard substrates, expanded polystyrene, or aluminum sheet, designed to maintain thermal stability, leak resistance, and stackability during transport from foodservice operator to consumer. Production methods span injection molding, thermoforming, folded carton gluing, and die-cut foam shaping, with barrier coatings applied to paper grades for grease and moisture control. Plastic clamshells retain the largest volume share across fast-casual chains, though molded fiber bowls are capturing premium positioning as compostable certification becomes a procurement filter. Aluminum trays occupy a defensible niche in oven-ready and catering applications where reheating compatibility commands price premiums over disposable alternatives.
The FDA regulates food-contact substance compliance under 21 CFR, while the EPA tracks per- and polyfluoroalkyl substance phaseouts affecting grease-resistant coatings; in Europe, EFSA and REACH jointly constrain additive chemistries and recyclability claims for single-use items. These frameworks are tightening material specifications, forcing converters to validate alternative barrier systems or forfeit institutional and chain-restaurant contracts. Stakeholders must monitor evolving state-by-state packaging EPR legislation and third-party compostability certification requirements to avoid stranded inventory and locked-out market segments.
Market Dynamics
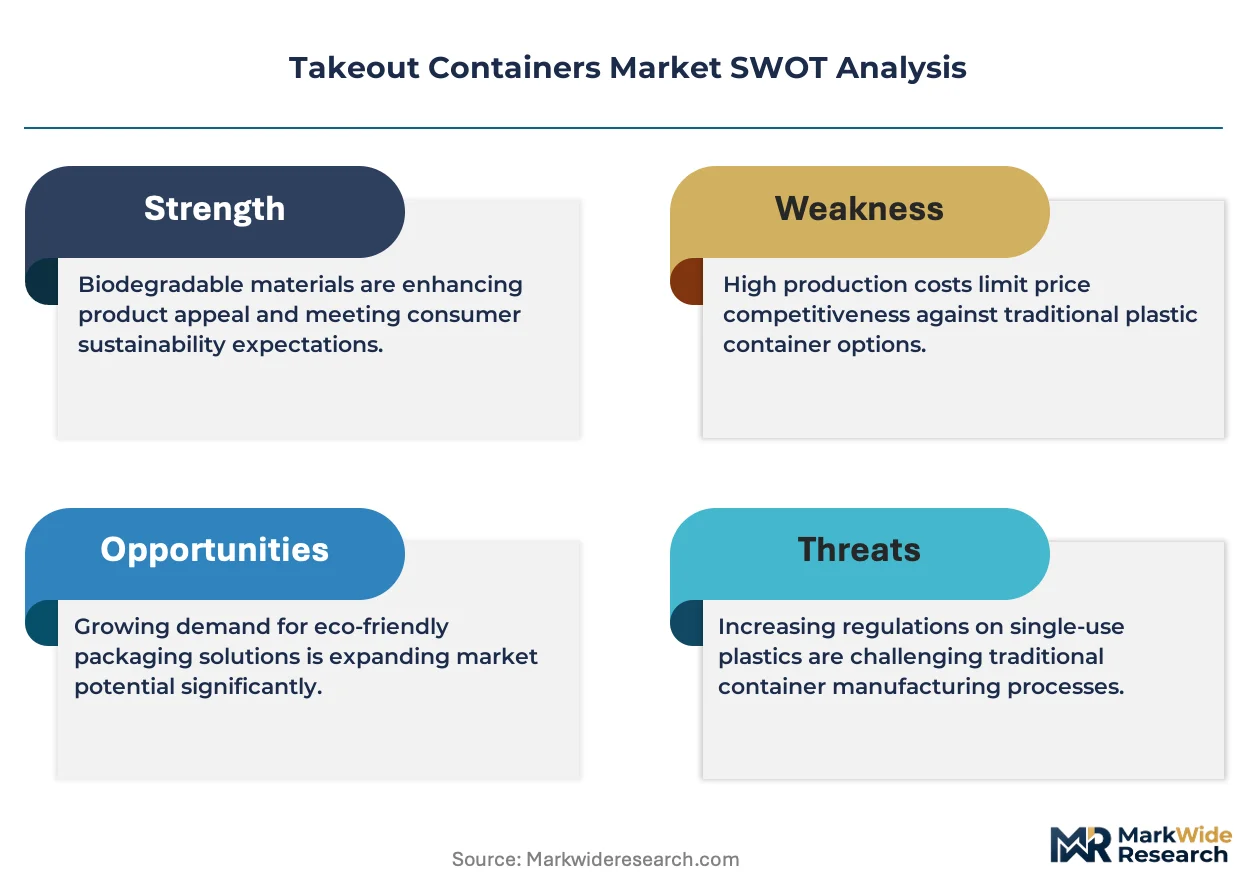
Material substitution mandates from California, New York, and the EU Single-Use Plastics Directive are compressing foam and conventional plastic formats while expanding pulp-molding and barrier-coated paperboard capacity investments.
Growth Catalysts
- EU Single-Use Plastics Directive:Bans on expanded polystyrene foodware accelerate converter retooling toward molded fiber and compostable alternatives across quick-service restaurant supply chains.
- Cloud kitchen proliferation:Third-party delivery platforms in urban United States and China corridors multiply container throughput per outlet, expanding total addressable volume for multi-material formats.
- Barrier coating advances:PFAS-free grease-resistant chemistries enable paperboard substitution in hot-food applications previously locked to plastic clamshells.
Market Restraints
- Pulp fiber cost volatility:Bleached kraft and recycled fiber input swings compress margin stability for molded fiber specialists lacking long-term supply contracts.
- Thermoforming equipment concentration:Automated high-speed lines cluster among integrated North American converters, limiting specialty player scale-up speed.
- Aluminum tray substitution ceiling:Oven-ready reheating compatibility limits displacement by microwave-incompatible fiber alternatives in catering segments.
Strategic Opportunities
- German institutional procurement:Federal catering contracts now mandate EN 13432 compostability certification, creating premium positioning for validated fiber bowl suppliers.
- Smart packaging convergence:QR-code traceability and temperature-indicating inks integrate with standard container formats for cold-chain verification.
- Direct mill-to-restaurant logistics:Coated paperboard producers bypass distributor tiers to capture quick-service restaurant volume through dedicated fleet contracts.
Industry Challenges
- PFAS phaseout compliance timeline:EPA testing protocols for 21 CFR food-contact substances delay alternative barrier validation, risking contract forfeiture.
- Pulp-molding technical talent scarcity:Wet-pressing process engineering expertise concentrates among legacy European and Japanese equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Takeout Containers Market |
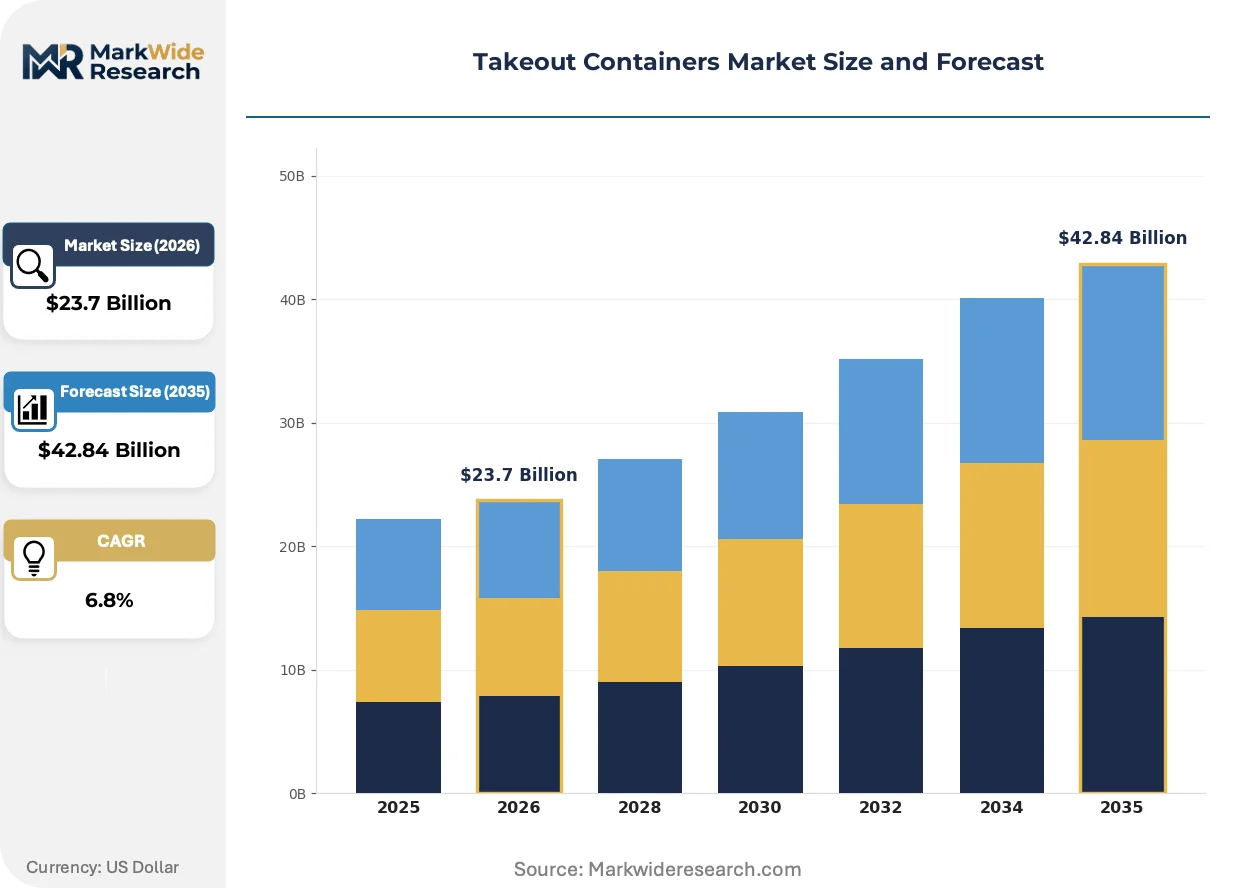
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Foam, Aluminum Product Type: Clamshells, Bowls, Plates, Trays End User: Restaurants, Cafes, Food Delivery Services, Catering Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Pactiv Evergreen, Sealed Air, Amcor PLC, Sumkoka, Sonoco, WestRock Company, Berry Global Group, Ball Corporation, Graphic Packaging International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Takeout Containers Market Strategic Shifts
Active material innovation and regulatory chemistry constraints are reconfiguring converter R&D priorities and procurement qualification standards across foodservice supply tiers.
Molded fiber with PFAS-free grease-resistant coatings is supplanting conventional plastic clamshells in fast-casual hot-food segments. Chains in California and New York procurement corridors adopt these formats at accelerated pace to preempt state-level foam bans. This substitution compresses virgin polypropylene demand while expanding pulp-molding line utilization rates among integrated paperboard converters.
REACH and EFSA joint constraints on additive chemistries and recyclability claims tighten specification windows for single-use food-contact items in European markets. Converters must validate alternative barrier systems through extended migration testing protocols or forfeit institutional contract eligibility. Quick-service restaurant supply chains respond by consolidating supplier bases toward vertically integrated players with in-house testing laboratories.
Cloud kitchen operators now specify container performance through outcome-based durability metrics rather than material type alone. Third-party delivery platforms in United States urban corridors track spillage and temperature retention data, redirecting volume toward multi-material flexible formats with superior transport stability. This behavioral pivot concentrates procurement influence among platform aggregators rather than individual restaurant operators.
Takeout Containers Market Segmentation
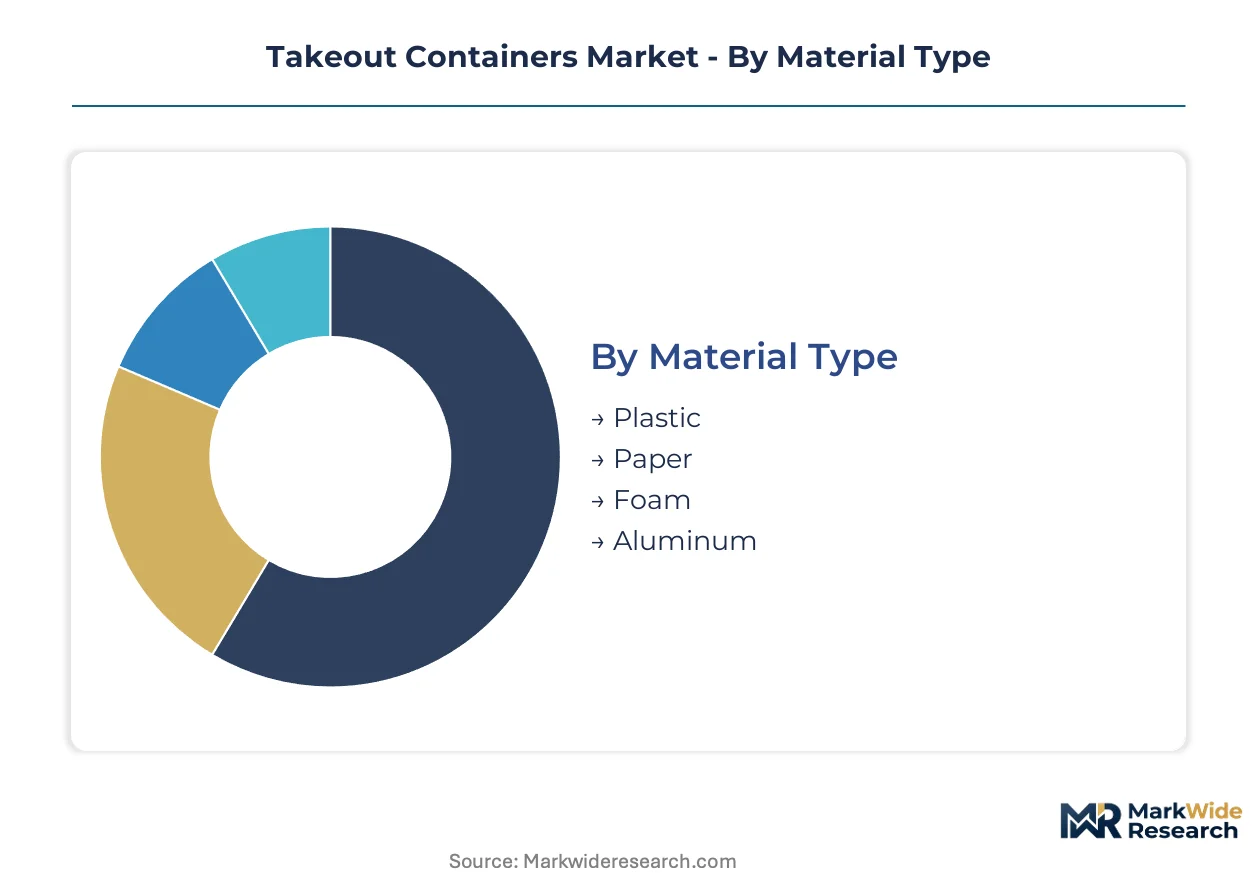
Takeout container procurement flows through distinct channel hierarchies that reshape volume allocation by material and format. Restaurant chains, cloud kitchens, and institutional buyers each impose specification filters that segment supply tiers by performance certification, thermal stability, and compostability validation.
Material Type:
Channel mix varies sharply by substrate: quick-service restaurant chains source plastic and paperboard through direct mill contracts, while independent operators rely on distributor tiers for foam and aluminum.
- Plastic:Polypropylene and PET clamshells dominate fast-casual throughput in United States urban corridors. California and New York state-level bans on expanded polystyrene are compressing virgin polypropylene demand even as total plastic volume holds.
- Paper:Barrier-coated kraft and molded fiber formats capture premium positioning through EN 13432 and BPI compostability certification. German federal catering contracts now mandate these specifications, rotating procurement toward validated European suppliers.
- Foam:Expanded polystyrene retains residual share in cost-sensitive independent pizzerias and small-town distributors. EU Single-Use Plastics Directive enforcement is accelerating phaseout timelines across member states.
- Aluminum:Oven-ready trays occupy defensible niches in catering and institutional reheating applications where microwave-incompatible fiber alternatives fail. Price premiums over disposables persist in airport and hospital contract segments.
Plastic dominates installed base. Paper is where expansion concentrates.
Product Type:
Format selection tracks application temperature and transport duration: hot-food segments prioritize clamshell thermal retention, while bowl formats capture cold-chain and compostable positioning.
- Clamshells:Hinged-lid plastic and fiber formats lock in heat for fried and grilled items across third-party delivery platforms. United States cloud kitchen operators specify these for spillage reduction in urban last-mile corridors.
- Bowls:Round-bottom molded fiber and plastic containers serve grain bowls, salads, and noodle applications where sauce containment matters. PFAS-free grease-resistant coatings are unlocking paperboard substitution in hot-soup segments previously plastic-locked.
- Plates:Flat paperboard and foam formats concentrate in barbecue, buffet, and casual dining takeout. Cost per unit remains the primary procurement filter for independent operators in distributor-dependent channels.
- Trays:Compartmentalized aluminum and plastic formats serve airline, hospital, and corporate catering with portion control requirements. Reheating compatibility limits fiber displacement in oven-ready specifications.
Clamshells anchor current volume share. Bowls are climbing the fastest as fast-casual formats proliferate.
End User:
Customer scale determines specification stringency: national chains enforce compostability mandates, while fragmented independents prioritize unit economics.
- Restaurants:Quick-service and fast-casual chains in United States, China, and Germany corridors consolidate procurement toward integrated converters with in-house testing laboratories. Direct mill-to-restaurant logistics bypass distributor markups for high-volume accounts.
- Cafes:Coffee-forward and bakery formats emphasize cup and clamshell compatibility with branding real estate. Smaller average order values sustain distributor channel dependence.
- Food Delivery Services:Platform aggregators in United States and China urban corridors now specify outcome-based durability metrics rather than material type alone. Spillage and temperature retention data redirect volume toward multi-material flexible formats.
- Catering:Institutional and event segments demand oven-ready reheating compatibility that preserves aluminum tray share. Federal and corporate contract tiers impose EN 13432 or BPI certification where fiber alternatives qualify.
Restaurants command the largest procurement volume. Food delivery services are gaining share fastest as platform economics reshape container throughput.
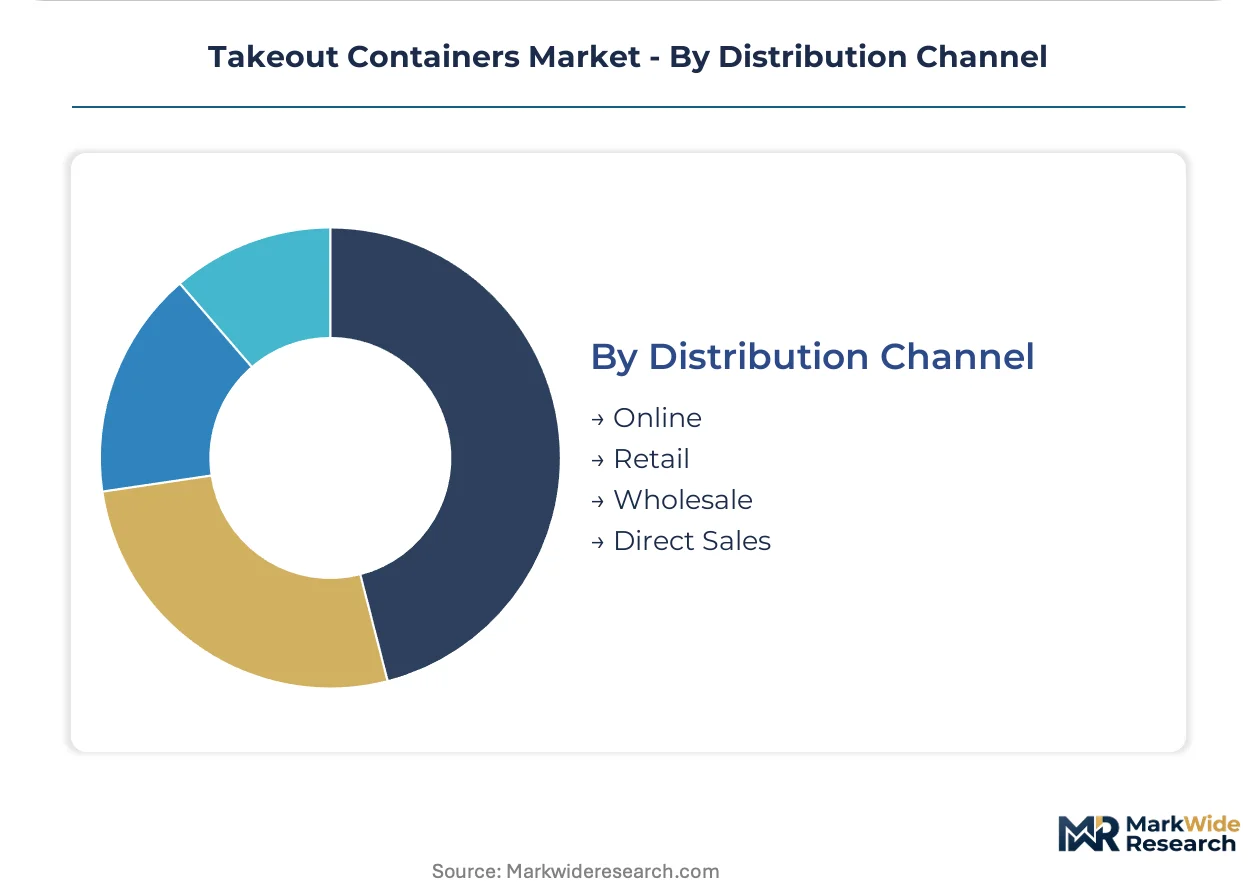
Distribution Channel:
Channel structure stratifies by customer scale and geographic concentration: direct sales capture national accounts, while retail and online serve fragmented independents.
- Online:E-procurement platforms aggregate independent restaurants and small chains in United States and European corridors. SKU breadth and rapid replenishment offset per-unit premiums over wholesale tiers.
- Retail:Cash-and-carry and big-box formats serve micro-operators with immediate pickup requirements. Stock-keeping unit proliferation compresses shelf space for specialty compostable formats.
- Wholesale:Broadline distributors maintain inventory depth across plastic, paper, and foam categories for mixed-operator customer bases. Consolidation among United States foodservice distributors is narrowing supplier access for mid-tier converters.
- Direct Sales:Integrated paperboard and plastic converters deploy dedicated fleet contracts to quick-service restaurant chains. Bypassing distributor tiers captures margin and locks in volume commitments.
Direct sales anchor the highest-margin relationships. Online channels are expanding most quickly as procurement digitization penetrates independent segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate low price elasticity as sustainability certifications become procurement gatekeepers, while operators in India and Southeast Asia remain highly sensitive to unit cost. This demand-elasticity contrast shapes regional capacity investment patterns and material substitution timelines.
United States
Cloud kitchen proliferation across New York, Los Angeles, and Chicago corridors multiplies container throughput per outlet. California and New York state-level bans on expanded polystyrene compress foam demand while accelerating pulp-molding line investments. The EPA's PFAS phaseout timeline under 21 CFR food-contact substance rules delays alternative barrier validation for paperboard converters.
China
Third-party delivery platforms in Shanghai, Beijing, and Shenzhen urban corridors specify outcome-based durability metrics rather than material type alone. The country's dual carbon goals constrain virgin plastic resin approvals for single-use foodware. Yangtze River Delta manufacturing clusters concentrate automated thermoforming capacity for export-oriented quick-service restaurant supply chains.
Germany
Federal catering contracts now mandate EN 13432 compostability certification, creating premium positioning for validated fiber bowl suppliers. EFSA and REACH joint constraints on additive chemistries tighten specification windows for imported single-use items. Bavaria and North Rhine-Westphalia host integrated paperboard converters with in-house testing laboratories serving institutional accounts.
India
Food delivery platform expansion in Mumbai, Delhi-NCR, and Bangalore corridors drives multi-material flexible format demand for spillage reduction. FSSAI food-contact substance regulations lag European stringency, preserving cost-driven foam and conventional plastic share among independent operators. Gujarat and Maharashtra industrial zones concentrate imported thermoforming equipment for mid-tier converter scale-up.
Japan
Quick-service restaurant chains in Tokyo, Osaka, and Nagoya corridors consolidate procurement toward vertically integrated converters with captive pulp supply. METI guidance on plastic resource circulation accelerates molded fiber R&D investment among domestic equipment suppliers. Kanto and Kansai manufacturing basins retain wet-pressing process engineering expertise concentrated among legacy Japanese machinery providers.
Takeout Containers Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the takeout containers market. Integrated North American converters with captive resin and fiber supply dominate cost-efficient foam and paperboard categories, while specialty players with in-house barrier coating laboratories capture premium positioning in compostable formats. Three archetypes define competitive structure: vertically integrated giants with mill-to-restaurant logistics, regional specialists with equipment-locked process expertise, and platform-integrated suppliers serving cloud kitchen aggregators. Dominant competitive moves include backward integration into pulp molding capacity and strategic partnerships with third-party delivery platforms for outcome-based specification contracts.
Among North American integrated converters, Pactiv Evergreen and Graphic Packaging International exemplify the scale-driven archetype with dedicated fleet contracts bypassing distributor tiers. Amcor PLC anchors the multi-material flexible format segment through global film and barrier technology positioning. These three companies represent distinct competitive vectors: captive manufacturing footprint, direct logistics relationships, and cross-material technology leadership.
| Leading Market Players |
|---|
| Pactiv Evergreen |
| Sealed Air |
| Amcor PLC |
| Sumkoka |
| Sonoco |
| WestRock Company |
| Berry Global Group |
| Ball Corporation |
| Graphic Packaging International |
| Others |
Value Chain & Pricing Dynamics
EN 13432 compostability certification gates both supplier qualification and price differentiation across European institutional procurement corridors. Buyers in Germany and the United States demonstrate low price elasticity as sustainability mandates harden into contract requirements, while operators in India and Southeast Asia remain highly sensitive to unit economics.
Pricing Analysis
After-sales service contracts for logistics optimization and inventory management drive lifetime value for integrated converters with dedicated fleet arrangements. Three-tier pricing structure across premium, standard, and economy levels separates EN 13432-certified fiber bowls from conventional plastic clamshells and residual foam formats. Price differentiation rests on certification grade and volume scale, with national quick-service restaurant chains locking in multi-year commitments. Cost compression in the standard tier is intensifying as pulp fiber input volatility squeezes molded fiber specialists lacking long-term supply contracts. Independent operators in distributor-dependent channels exhibit the highest price sensitivity, while institutional buyers in Germany and California accept premiums for validated compostable formats.
Supply Chain Analysis
Yangtze River Delta manufacturing clusters concentrate automated thermoforming capacity for export-oriented quick-service restaurant supply chains. Raw material flows draw from bleached kraft pulp suppliers in the United States and Brazil, virgin polypropylene resin producers in the Gulf Coast, and recycled fiber processors in European Nordic regions. Single-source vulnerability concentrates in wet-pressing process equipment supplied by legacy Japanese and European machinery providers. Distribution runs through direct mill-to-restaurant fleet contracts for national chains, broadline distributor tiers for mixed-operator bases, and e-procurement platforms aggregating independent restaurants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Takeout container demand follows cyclical recovery patterns tied to foodservice foot traffic and delivery platform expansion. Cloud kitchen proliferation and third-party delivery growth serve as the named cyclical driver restoring throughput volumes.
For Market Incumbents: Consolidate supplier relationships around vertically integrated converters with captive pulp supply and in-house testing laboratories to defend against PFAS phaseout compliance risks. Lock in long-term fiber supply contracts to buffer against pulp input volatility compressing margin stability. Prioritize capacity addition in Yangtze River Delta and Bavaria manufacturing clusters to anchor regional cost positions.
For New Entrants and Emerging Players: Lead with PFAS-free grease-resistant coating technology to capture premium positioning in California and New York procurement corridors where state-level bans accelerate material substitution. Target cloud kitchen operators in United States urban corridors specifying outcome-based durability metrics rather than material type alone. Deploy platform-integrated supply partnerships with third-party delivery aggregators as the go-to-market angle.
For Investors and Strategic Acquirers: EPA's PFAS phaseout timeline under 21 CFR food-contact substance rules reshapes the acquisition landscape toward converters with validated alternative barrier systems. Five-to-ten year viability favors specialty players with in-house coating laboratories and EN 13432 certification infrastructure over commodity foam converters facing stranded asset risk. The signal to watch is state-by-state packaging EPR legislation progression as an inflection indicator for accelerated consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Molding Capacity | Captive fiber supply secures margin stability against bleached kraft volatility for integrated converters. |
| PFAS-Free Barrier Coating R&D Investment | Validated alternative chemistries unlock paperboard substitution in hot-food segments previously plastic-locked. |
| Direct Mill-to-Restaurant Logistics Contracts | Dedicated fleet arrangements bypass distributor markups and lock in volume commitments from national chains. |
| Platform Partnerships for Outcome-Based Specifications | Third-party delivery aggregators redirect procurement influence toward multi-material flexible formats with superior transport stability. |
| EN 13432 Certification Infrastructure Buildout | Compostability validation secures eligibility for German federal catering contracts and premium institutional positioning. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foodservice procurement directors, converter plant managers, third-party delivery platform supply chain leads, and distributor category buyers. Secondary validation drew from FDA 21 CFR food-contact substance filings, EPA PFAS regulatory dockets, EU EFSA and REACH guidance documents, and trade data tracking pulp and resin input flows. Bottom-up volume estimates from material-grade production data were triangulated against top-down spending patterns from foodservice operator procurement disclosures.
Across the analysis window, the forecasting framework modeled demand trajectories by material type, product format, end-user segment, and distribution channel structure. Segmentation dimensions included plastic resin grade, paperboard barrier coating technology, clamshell versus bowl versus tray formats, and cloud kitchen versus traditional restaurant procurement patterns. CAGRs were derived from regression analysis against foodservice outlet expansion, delivery platform transaction growth, and regulatory phaseout timelines. Industry-specific inputs incorporated thermoforming line capacity utilization rates and pulp-molding equipment installation pipelines.
The analysis sits within stated boundaries; outcomes outside sustained cloud kitchen proliferation, accelerated PFAS regulatory enforcement, or stable pulp fiber supply conditions would require recalibration. Practitioners should keep alternative scenarios live as state-level packaging EPR legislation and third-party compostability certification requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Sanitary Cans Market
Containers
Algeria Container Glass Market
Containers
Disposable Lids Market
Containers
Metal Crates Market
Containers
Jug Shipper Market
Containers
Wide Mouth Jars Market
Containers
Container Coating Market
Containers
Global Container Monitoring Market
Containers
Sandwich Containers Market
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Containerboard Market
Containers
Pocket Containers Market
Containers
Snap-Lock Container Market
Containers
Screw Top Jar Market
Containers
Club Store Packaging Tray Market
Containers
Pinch Grip Jars Market