
 Light Density Polyethylene (LDPE) Bottles Market | 2026-2036
Light Density Polyethylene (LDPE) Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Light Density Polyethylene (LDPE) Bottles Market Foresight
Personal care brands are unwinding historical reliance on rigid HDPE formats in favor of flexible LDPE squeeze bottles for lotions, shampoos, and travel-size toiletries. Berry Global Inc. leverages its broad thermoforming footprint to supply multi-layer LDPE solutions across North American personal care accounts. Amcor Plc sustains global conversion capabilities that anchor its position in pharmaceutical-grade LDPE packaging with enhanced barrier properties. ALPLA Group specializes in injection-blow-molded LDPE designs that dominate European cosmetics packaging channels through dedicated beauty-sector facilities.
Light density polyethylene bottles are extrusion- or blow-molded containers manufactured from branched polyethylene resin with density ranging from 0.910 to 0.940 g/cm³, valued for flexibility, stress-crack resistance, and moisture barrier performance in squeezable and collapsible formats. Round bottles occupy the largest product-type position due to universal compatibility with capping machinery and established filling-line infrastructure across cosmetics and household sectors. The food and beverage end-user segment registers the fastest structural expansion as condiment and sauce brands adopt LDPE squeeze formats to replace glass and rigid alternatives. Small-size LDPE bottles concentrate margin pools in travel-retail and sample-dispensing channels where premium unit economics offset lower volumes.
FDA food-contact notification requirements govern LDPE resin purity and additive migration limits for U.S. food and pharmaceutical packaging applications, while EU REACH and MDR frameworks impose substance-of-very-high-concern screening on colorants and stabilizers used in European medical and cosmetic bottles. India's BIS certification mandates and FSSAI packaging safety standards are tightening compliance thresholds for imported LDPE resin and finished containers entering domestic food and personal care supply chains. Stakeholders must monitor evolving extended-producer-responsibility frameworks and recycled-content mandates across multiple jurisdictions to align capital allocation with compliance-driven material transitions.
Market Dynamics
Squeeze-format personal care packaging is compressing rigid HDPE demand as brands prioritize collapsible LDPE bottles for consumer convenience and shelf differentiation.
Growth Catalysts
- EU REACH migration limits:Tightening substance-of-very-high-concern screening is accelerating compliant LDPE resin qualification for cosmetics and pharmaceutical channels.
- India cosmetics manufacturing:Domestic production scale-up in Maharashtra and Gujarat is concentrating procurement demand for injection-blow-molded LDPE bottles.
- Food-contact squeeze formats:Condiment brands are converting glass and rigid containers to LDPE alternatives for portion control and reduced breakage.
Market Restraints
- Ethylene feedstock volatility:Crude-linked naphtha pricing transmits directly to LDPE resin costs, compressing converter margins during upstream spikes.
- Recycled-content technical ceiling:Mechanical recycling of LDPE produces odor and color inconsistency that limits food-contact and cosmetic applications.
- Polypropylene substitution:Clarified PP resins with improved clarity and stiffness are capturing premium personal care segments previously served by LDPE.
Strategic Opportunities
- Southeast Asia travel retail:Singapore and Bangkok duty-free channels are expanding sample-size LDPE bottle procurement for premium beauty brands.
- India BIS certification alignment:Early compliance with Bureau of Indian Standards resin purity mandates positions suppliers for import-substitution contracts.
- Advanced barrier coextrusion:Oxygen-scavenging and EVOH layer integration is opening LDPE to sensitive pharmaceutical and nutraceutical applications.
Industry Challenges
- Blow-molding technician scarcity:Skilled operators for multi-layer parison control are concentrated among legacy converters, constraining capacity expansion.
- FDA food-contact notification timelines:New additive approvals require 120-180 day review cycles that delay product launches in U.S. food packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Density Polyethylene (LDPE) Bottles Market |
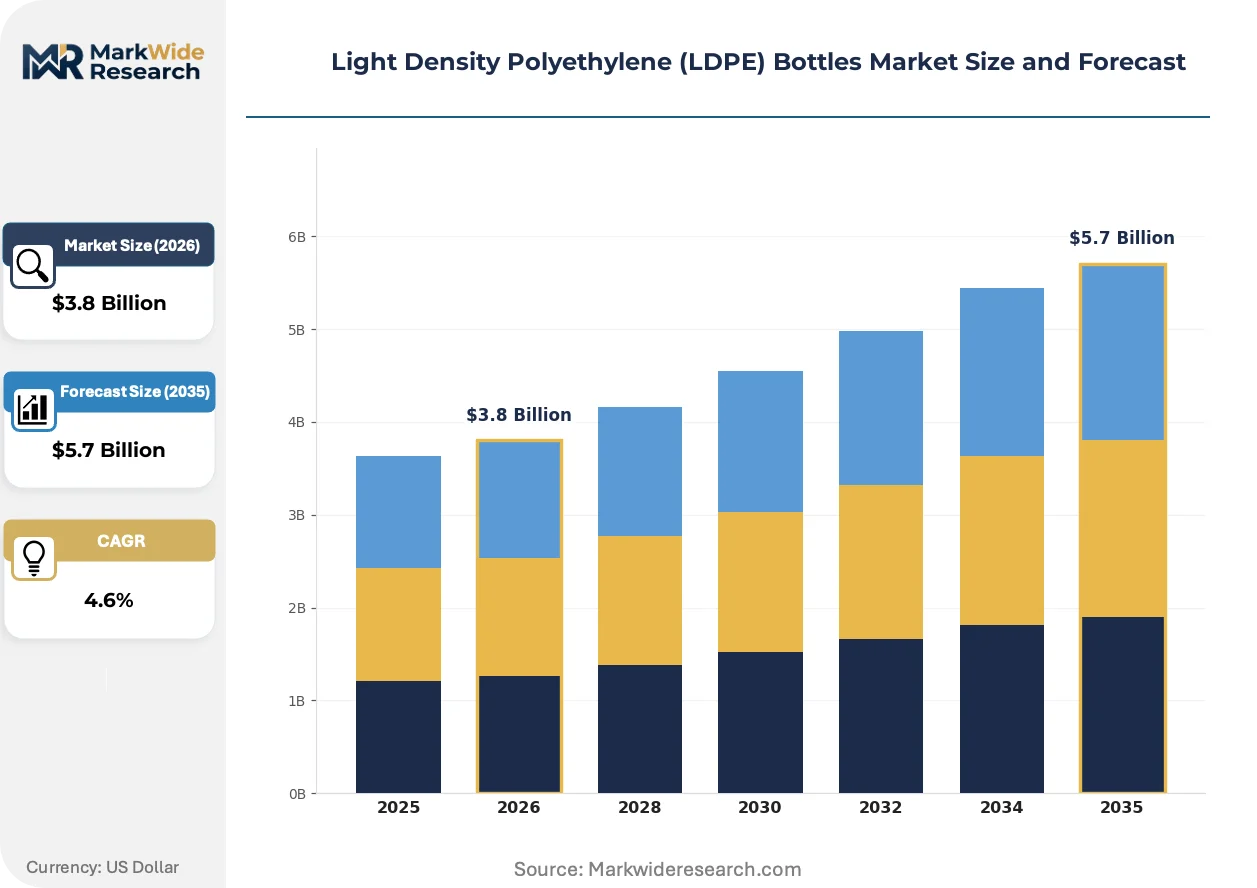
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Bottles, Square Bottles, Specialty Bottles, Nozzled Bottles End User: Cosmetics, Food & Beverage, Pharmaceuticals, Household Products Size: Small, Medium, Large, Extra Large Closure Type: Screw Caps, Snap Caps, Pump Dispensers, Flip Tops |
| Companies Covered | Plastipak Holdings Inc., Silgan Holding Inc., Berry Global Inc., Gerresheimer AG, Berlin Packaging, Amcor Plc, Graham Packaging Company LP, Nampac Limited, ALPLA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Density Polyethylene (LDPE) Bottles Market Shifts & Advancements
Material science advances and regulatory precision are reshaping how LDPE bottles compete across squeeze-format applications, with flexibility and compliance emerging as dual design imperatives.
Multi-layer coextrusion with ethylene-vinyl alcohol barrier cores is supplanting monolayer LDPE in pharmaceutical and high-acid food segments. European and North American pharmaceutical packagers are specifying five- and seven-layer structures for moisture-sensitive formulations. This technology is compressing the addressable market for standard LDPE while expanding total value per unit.
EU MDR substance documentation requirements are forcing colorant and stabilizer reformulation across medical and cosmetic LDPE applications. Manufacturers must maintain detailed supply chain records for REACH SVHC screening. Small-batch cosmetics producers in France and Germany are responding by consolidating supplier bases to reduce compliance audit burden.
Direct-to-brand procurement platforms are disintermediating traditional distributor networks for standard LDPE bottle formats. Personal care contract manufacturers in India and Indonesia are sourcing squeeze bottles through digital marketplaces that aggregate converter capacity. This channel shift is most visible among mid-tier beauty brands seeking shorter lead times than legacy distribution provides.
Light Density Polyethylene (LDPE) Bottles Market Segmentation
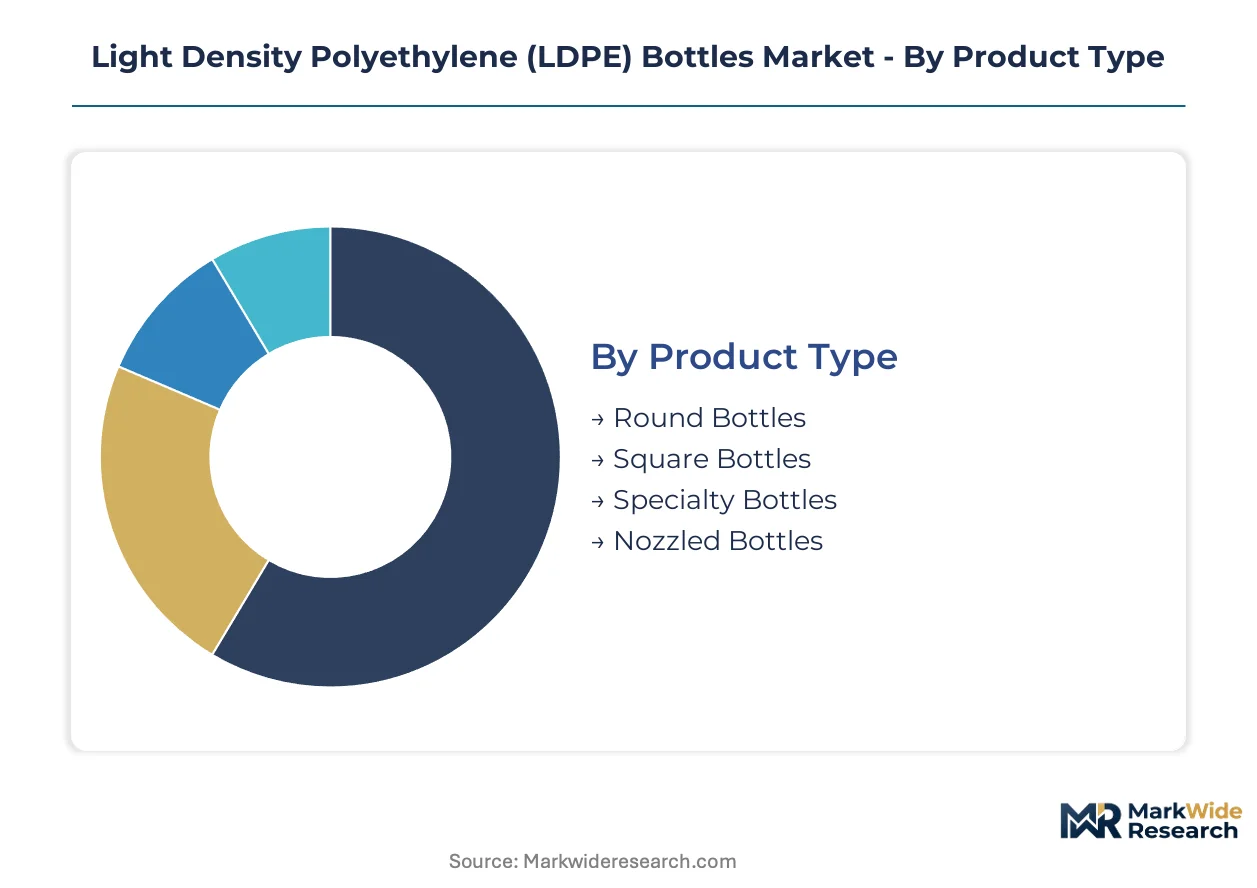
LDPE bottle purchasing patterns fragment sharply across product geometry, end-use chemistry compatibility, and dispensing mechanics. Each segmentation axis carries distinct margin profiles and regulatory exposure that reshape supplier priorities.
Product Type:
Round bottles dominate domestic procurement across North American and European filling lines, while square and specialty formats concentrate in export-led cosmetics channels from India and Southeast Asia.
- Round Bottles:Universal compatibility with high-speed capping machinery and established conveyor systems makes these the default for household and personal care filling operations. Demand concentrates in US and German manufacturing corridors where legacy equipment investments favor cylindrical geometry, though FDA food-contact notification timelines delay new resin approvals for this high-volume segment.
- Square Bottles:Shelf-stacking efficiency and label adhesion properties drive adoption in retail-facing cosmetics and condiment applications. Procurement is accelerating in Maharashtra and Gujarat cosmetics clusters where injection-blow-molded square formats offer premium differentiation for domestic beauty brands expanding into Middle East export markets.
- Specialty Bottles:Custom shapes for travel retail and gift sets concentrate margin pools in Singapore and Bangkok duty-free channels.
- Nozzled Bottles:Precision dispensing designs serve pharmaceutical and high-viscosity food segments requiring controlled flow rates.
Round bottles hold the largest share; momentum sits with square bottles.
End User:
Cost tier stratification separates commodity household applications from premium pharmaceutical and cosmetics segments with stringent migration testing requirements.
- Cosmetics:Squeeze-format flexibility and collapsible travel sizes dominate procurement for lotions, shampoos, and serums. Maharashtra and Gujarat manufacturing clusters are scaling domestic LDPE bottle production to serve India's expanding beauty sector, with BIS certification mandates tightening import substitution timelines for compliant resin suppliers.
- Food & Beverage:Condiment and sauce brands are converting glass and rigid containers to LDPE squeeze formats for portion control and reduced breakage. This segment climbs the fastest as high-acid food applications drive multi-layer coextrusion adoption with EVOH barrier cores.
- Pharmaceuticals:Oxygen-scavenging layer integration and EU MDR substance documentation requirements concentrate demand among specialized European converters.
- Household Products:Standard monolayer LDPE serves cleaning and automotive chemical applications with lower regulatory barriers.
Cosmetics commands the highest unit values; food and beverage gains share fastest.
Size:
Volume concentration in small formats for travel retail contrasts with bulk procurement economics for industrial and household applications.
- Small:Sample and travel-size bottles below 100ml capture premium unit economics in duty-free and direct-to-consumer beauty channels. Singapore and Bangkok travel retail expansion is concentrating procurement for TSA-compliant LDPE formats with enhanced decoration capabilities.
- Medium:Standard personal care and condiment sizes between 100-500ml represent the volume anchor for converter capacity planning.
- Large:Family-size and institutional formats serve food service and janitorial supply chains with compressed margins.
- Extra Large:Bulk industrial and refill applications concentrate in B2B procurement with minimal branding requirements.
Medium sizes anchor volume; small formats deliver margin expansion.
Closure Type:
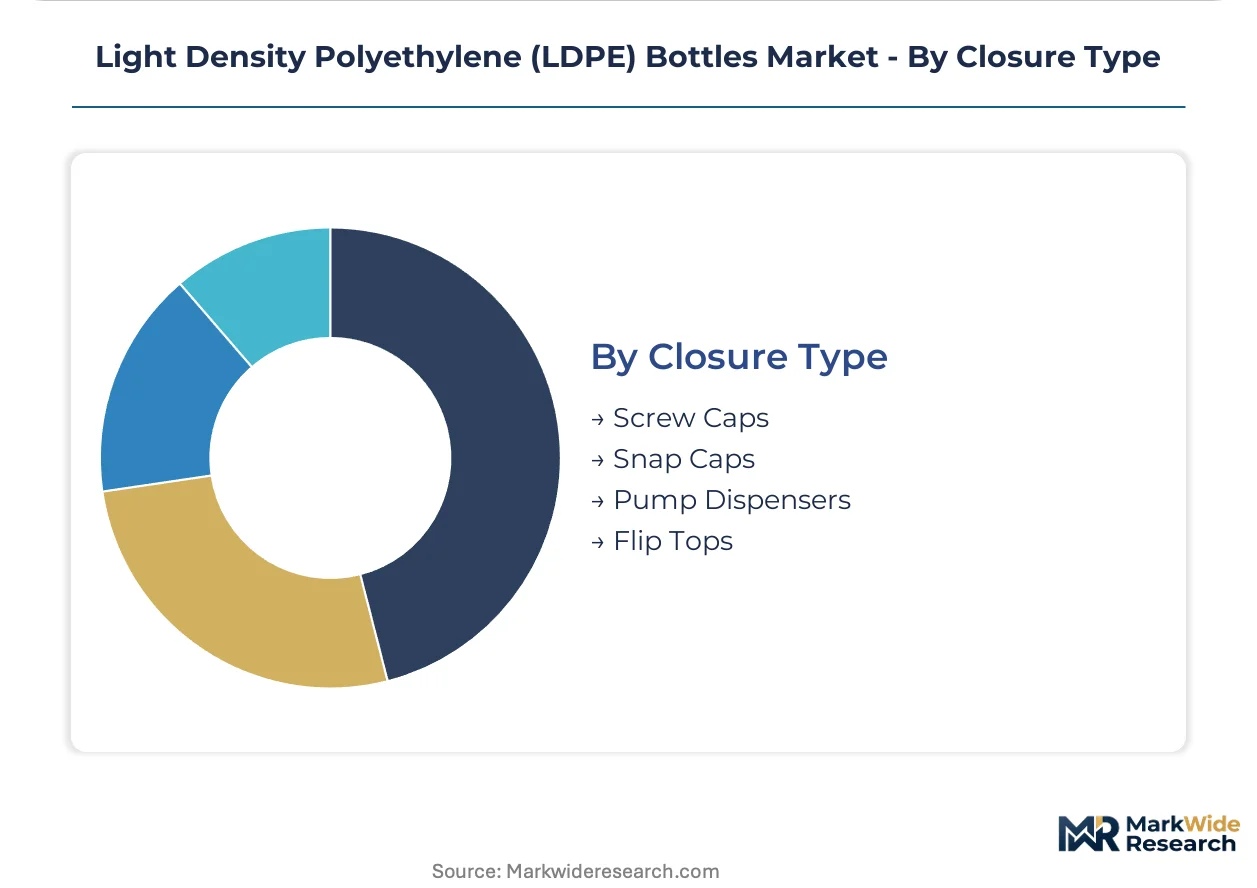
Application chemistry and dispensing precision determine closure specification, with pump mechanisms commanding technical premiums over standard cap formats.
- Screw Caps:Universal threading standards and lowest unit cost maintain dominance across food and household segments with non-viscous contents.
- Snap Caps:Child-resistant and tamper-evident features serve pharmaceutical and chemical applications requiring safety compliance.
- Pump Dispensers:Metered dosing and airless properties command premium positioning in cosmetics and pharmaceutical segments. EU REACH substance-of-very-high-concern screening extends to pump spring and gasket materials, complicating supplier qualification for European medical and beauty channels.
- Flip Tops:One-handed operation drives adoption in food service and personal care convenience formats.
Screw caps dominate unit volume; pump dispensers expand value per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian converters export squeeze-format LDPE bottles to Middle Eastern cosmetics distributors, while Southeast Asian duty-free channels source premium travel sizes from regional thermoforming clusters.
United States
Condiment brands drive food-contact squeeze bottle procurement as FDA food-contact notification timelines delay new resin approvals. The EPA oversees chemical safety standards for polyethylene additives. Converter capacity concentrates in Ohio and Illinois manufacturing corridors serving legacy filling-line infrastructure.
Germany
Pharmaceutical packagers specify multi-layer EVOH barrier structures for moisture-sensitive formulations. ECHA REACH substance-of-very-high-concern screening governs colorant and stabilizer selection. Converter expertise clusters in Baden-Württemberg and North Rhine-Westphalia for EU MDR-compliant medical packaging.
India
Domestic cosmetics manufacturing scales rapidly in Maharashtra and Gujarat, concentrating procurement for injection-blow-molded bottles. BIS certification mandates tighten import substitution timelines for compliant resin suppliers. Mumbai and Ahmedabad house dedicated beauty-sector facilities serving Middle East export markets.
Singapore
Duty-free travel retail expansion accelerates sample-size LDPE bottle procurement for premium beauty brands. The country's national standards body aligns with ASEAN harmonized packaging safety frameworks. Changi Airport corridor converters specialize in TSA-compliant formats with enhanced decoration capabilities.
Thailand
Bangkok-based contract manufacturers source squeeze bottles through digital procurement platforms disintermediating traditional distributor networks. The national industrial standards institute enforces food-contact material migration limits. Eastern Economic Corridor thermoforming capacity serves regional personal care brand consolidation.
Light Density Polyethylene (LDPE) Bottles Market Competitive Landscape
Listed leaders compete with private specialists across resin qualification capabilities and geographic coverage. The vendor base spans multinational packaging conglomerates with global thermoforming footprints and regional converters serving single-country cosmetics clusters. Three archetypes dominate: integrated resin-to-bottle manufacturers, specialized cosmetics packaging houses, and diversified rigid container players extending into flexible formats. Capacity expansion and strategic partnerships represent the dominant competitive moves as converters seek compliant resin supply security.
Among diversified packaging conglomerates, Berry Global Inc. and Amcor Plc exemplify scale-driven positions spanning multiple substrate technologies and end-use segments. ALPLA Group occupies a specialist tier focused on injection-blow-molded designs. These three entities represent contrasting strategic postures: broad thermoforming diversification, global pharmaceutical-grade barrier capabilities, and dedicated European cosmetics channel focus.
| Leading Market Players |
|---|
| Plastipak Holdings Inc. |
| Silgan Holding Inc. |
| Berry Global Inc. |
| Gerresheimer AG |
| Berlin Packaging |
| Amcor Plc |
| Graham Packaging Company LP |
| Nampac Limited |
| ALPLA Group |
| Others |
Supply & Pricing Matrix
BIS certification mandates in India gate both resin supplier qualification and price differentiation, as compliant converters command premiums while non-certified imports face exclusion from Maharashtra and Gujarat cosmetics procurement clusters. FDA food-contact notification timelines in the United States simultaneously delay new additive approvals and compress margins for converters awaiting clearance, creating a bifurcated pricing landscape where regulatory readiness determines tier positioning.
Pricing Analysis
Monolayer extrusion blow-molding represents the prior-generation cost floor, while five-layer EVOH barrier coextrusion commands the next-generation premium tier. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade multi-layer formats from cosmetic monolayer squeeze bottles and commodity household containers. Cost compression in standard monolayer tiers is intensifying because clarified polypropylene resins capture premium personal care segments previously served by LDPE. Mid-tier cosmetics contract manufacturers in India exhibit the highest price sensitivity, whereas European pharmaceutical packagers demonstrate the lowest due to EU MDR compliance requirements.
Supply Chain Analysis
Ethylene feedstock transit through the Strait of Hormuz underwrites resin cost volatility for converters across India and Southeast Asia. LDPE bottle manufacturing draws from Saudi Arabian and Qatari ethylene supply, German and Austrian injection-blow-molding equipment, and Chinese colorant and additive production. Single-source vulnerability concentrates in skilled blow-molding technicians for multi-layer parison control, with legacy operators concentrated in Ohio, Illinois, Baden-Württemberg, and North Rhine-Westphalia. Distribution runs through direct-to-brand digital procurement platforms disintermediating traditional distributor networks, particularly visible among Indonesian and Thai contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified multi-layer coextrusion technicians represent the critical capability gap constraining capacity expansion, as demand for pharmaceutical-grade barrier bottles outstrips converter technical capacity across European and North American manufacturing corridors.
For Market Incumbents: Fortify resin qualification pipelines by securing captive supply agreements with Saudi and Qatari ethylene producers before BIS certification mandates tighten import substitution timelines in India. Expand dedicated beauty-sector facility capacity in Maharashtra and Gujarat to capture domestic cosmetics manufacturing scale-up. Clarified polypropylene substitution in premium personal care segments threatens LDPE squeeze-format dominance, requiring barrier coextrusion R&D investment to defend position. For New Entrants and Emerging Players: BIS certification fast-track programs offer the most penetrable entry point for resin suppliers targeting India's import-substitution procurement surge. Target Southeast Asia travel-retail sample-size formats below 100ml, where premium unit economics offset lower volumes and decoration capabilities differentiate offerings. Digital marketplace aggregation of converter capacity provides the go-to-market angle for mid-tier beauty brands seeking shorter lead times than legacy distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade multi-layer coextrusion as EVOH barrier core integration and oxygen-scavenging layer technology raise equipment and technical qualification thresholds. Long-term viability over the next decade rests on converters with demonstrated FDA food-contact notification success and EU REACH SVHC screening documentation. Acquisition target archetype: regional specialists with certified resin supply relationships and existing pharmaceutical customer bases. Monitor FDA additive approval timeline compression as the signal to watch for inflection in U.S. food-contact squeeze-format adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Layer Coextrusion Capacity Expansion | Five-layer EVOH barrier integration opens pharmaceutical and high-acid food segments to LDPE formats. |
| BIS Certification Alignment | Early compliance with Bureau of Indian Standards resin purity mandates secures import-substitution contracts in Maharashtra and Gujarat. |
| Digital Procurement Platform Integration | Direct-to-brand aggregation disintermediates traditional distributor networks for Indonesian and Thai contract manufacturers. |
| Backward Integration into Ethylene Supply | Captive Saudi and Qatari feedstock agreements insulate converter margins from naphtha-linked volatility. |
| Advanced Barrier Technology Licensing | Oxygen-scavenging layer integration from European pharmaceutical packagers transfers to nutraceutical applications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food-contact notification databases, EU ECHA REACH substance registrations, BIS certification records, and trade flow data from Indian customs authorities. Conversations with blow-molding plant managers, cosmetics procurement leads at Maharashtra and Gujarat manufacturing clusters, pharmaceutical packaging engineers, and thermoforming equipment distributors informed demand-side validation. Bottom-up resin consumption estimates triangulate against top-down converter capacity assessments across North American, European, and Asian production corridors.
Segmentation dimensions modeled include product geometry, end-use chemistry compatibility, dispensing mechanics, and regional regulatory cluster across the projection horizon. CAGRs derive from unit volume trajectories by segment, weighted by value-per-unit differentials between monolayer and multi-layer formats. Forecast inputs incorporate ethylene feedstock pricing sensitivity, FDA additive approval pipeline status, and EU MDR substance documentation requirement phase-in schedules.
Underlying assumptions cover stable crude-linked naphtha pricing, sustained FDA review timelines, and gradual BIS enforcement escalation, with deviation risk concentrated in ethylene supply disruptions, accelerated REACH SVHC list expansion, and polypropylene substitution acceleration in premium personal care. Practitioners should keep alternative scenarios live as regulatory compliance thresholds and substitute material performance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Sanitary Cans Market
Containers
Half Height Containers Market
Containers
Lever Lid Tinplate Containers Market
Containers
Wire Containers Market
Containers
Thin Wall Containers Market
Containers
PUR Containers Packaging Market
Containers
Old Corrugated Containers (OCC) Market
Containers
Spout Containers Market
Containers
Clear Hinged Container Market
Containers
Pails Market
Containers
Lift-Off Lid Box Market
Containers
Foam Hinged Take-Out Containers Market
Containers
Pail Lids Market
Containers
Global Cardboard Box and Container Market
Containers
Conipack Pails Market
Containers
Disposable Lids Market