
 Container Mouth Inner Seal Market | 2026-2036
Container Mouth Inner Seal Market Size, Share, and Industry Trends Forecast 2026-2036
Container Mouth Inner Seal Market Outlook
ISO 15378 certification for primary packaging materials is redrawing competitive boundaries in the container mouth inner seal sector. Seliger Group leverages its pharmaceutical-grade manufacturing infrastructure to sustain dominance across European health-product supply chains. Tekni-Plex anchors North American demand through vertically integrated foam and film operations that control liner substrate quality from resin to finished gasket. Meyer Seals GmbH specializes in precision-cut aluminum and composite induction seals, competing on tight dimensional tolerances demanded by automated capping lines.
A container mouth inner seal is a discrete closure component, typically 0.5–2.0 mm in thickness, engineered from laminated aluminum-polymer composites or extruded polyethylene foams, that adheres to container land surfaces to create hermetic barriers against moisture, oxygen, and microbial ingress. Plastic liners dominate volume in beverage and household chemical applications where cost sensitivity prevails, while induction seal designs command premium positioning in pharmaceutical packaging due to their tamper-evident properties and compatibility with child-resistant closures. Metal-reinforced configurations occupy the fastest-growing niche as brands seek extended shelf stability for aseptic and retort-processed foods.
The FDA enforces cGMP standards that mandate seal integrity validation for drug packaging, while the EMA's Annex 1 revisions on sterile manufacturing elevate barrier performance requirements for parenteral and oral solid dose containers. REACH compliance through ECHA restricts certain phthalate plasticizers in seal coatings, redirecting formulation R&D toward bio-based adhesion promoters and halogen-free polymer alternatives. Stakeholders must monitor evolving pharmacopeial extractables testing protocols and regional extended producer responsibility mandates that will reshape material selection and liner recyclability specifications.
Market Dynamics
Pharmaceutical serialization mandates and aseptic processing expansion are compressing specification tolerances across the container mouth inner seal supply base, forcing converters to recalibrate lamination and die-cutting infrastructure for sub-millimeter precision.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revisions:Barrier performance requirements for parenteral containers are tightening acceptance criteria for seal integrity validation, pulling advanced induction-seal designs into European pharmaceutical packaging lines.
- Extended shelf stability protocols:Retort-processed and aseptic food brands are specifying metal-reinforced seal configurations to combat oxygen ingress during thermal processing cycles.
- German packaging cluster density:Concentrated converter and liner producer presence around Meyer Seals GmbH and specialized substrate manufacturers accelerates prototype-to-production timelines for Central European exporters.
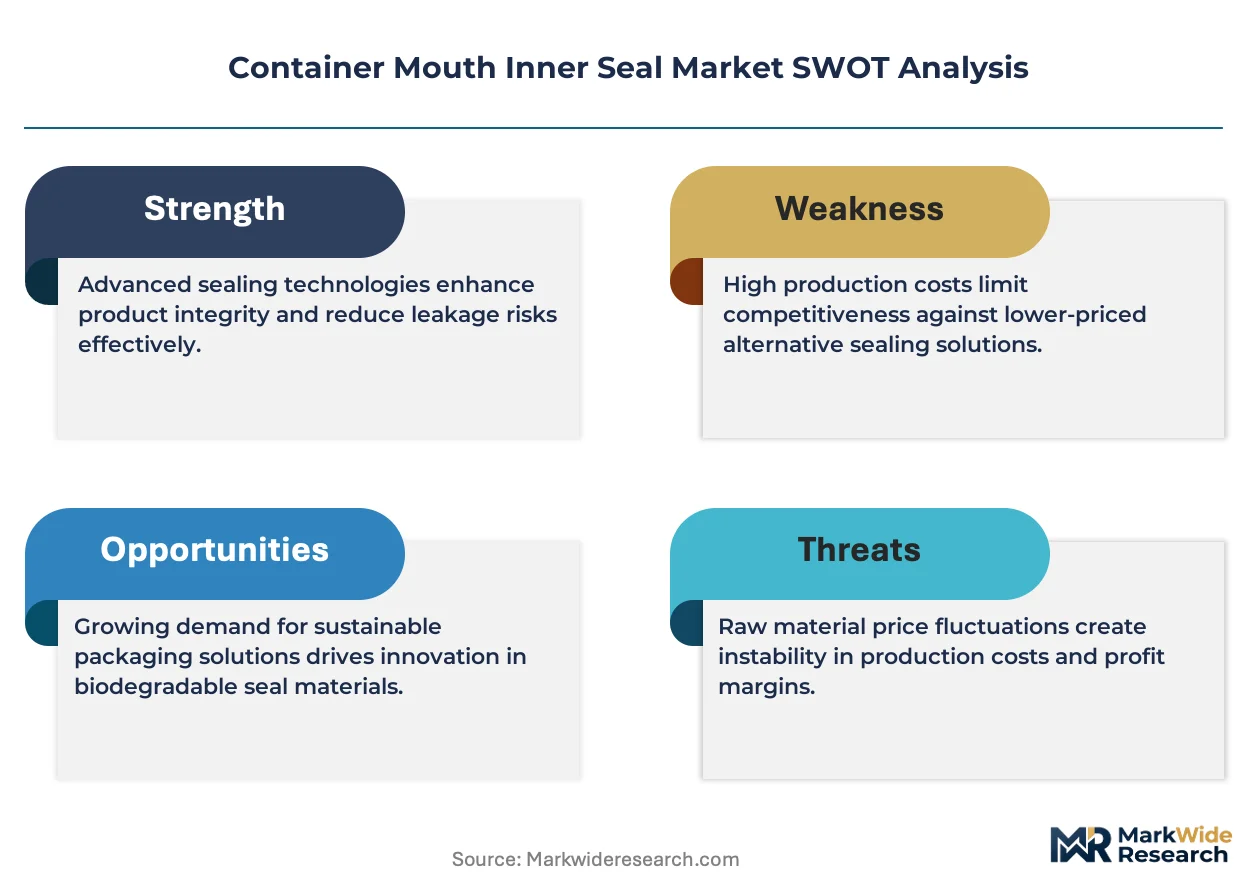
Market Restraints
- Aluminum foil supply concentration:Rolled aluminum substrate sourcing depends on a narrow base of European and Asian smelter-refiner networks, exposing converters to energy-cost pass-through volatility.
- REACH phthalate restrictions:ECHA-mandated elimination of certain plasticizers in seal coatings forces reformulation cycles that extend qualification timelines with pharmaceutical customers.
- Polymer foam density limitations:Extruded polyethylene foams face compression-set performance ceilings in high-temperature autoclave applications, capping penetration in steam-sterilized parenteral packaging.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO-aligned manufacturers supplying regulated markets are upgrading from basic wad seals to induction-sealed containers with tamper-evident features.
- EU F-Gas Regulation compliance services:Lower-emission sealing material verification and supply chain documentation support represent attachable service revenue for converters.
- Bio-based adhesion promoters:Halogen-free polymer alternatives and plant-derived bonding layers are converging with pharmaceutical sustainability procurement criteria.
Industry Challenges
- ISO 15378 certification timelines:Primary packaging material qualification for pharmaceutical-grade manufacturing extends eighteen to twenty-four months, straining converter cash conversion cycles.
- Multi-layer lamination skill scarcity:Adhesive chemistry and coextrusion process engineering expertise concentrates in aging workforces across European and North American converter bases.
- Legacy capping line integration:Automated pharmaceutical filling lines with fixed head spacing and torque specifications resist retrofit for next-generation seal thickness profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Container Mouth Inner Seal Market |
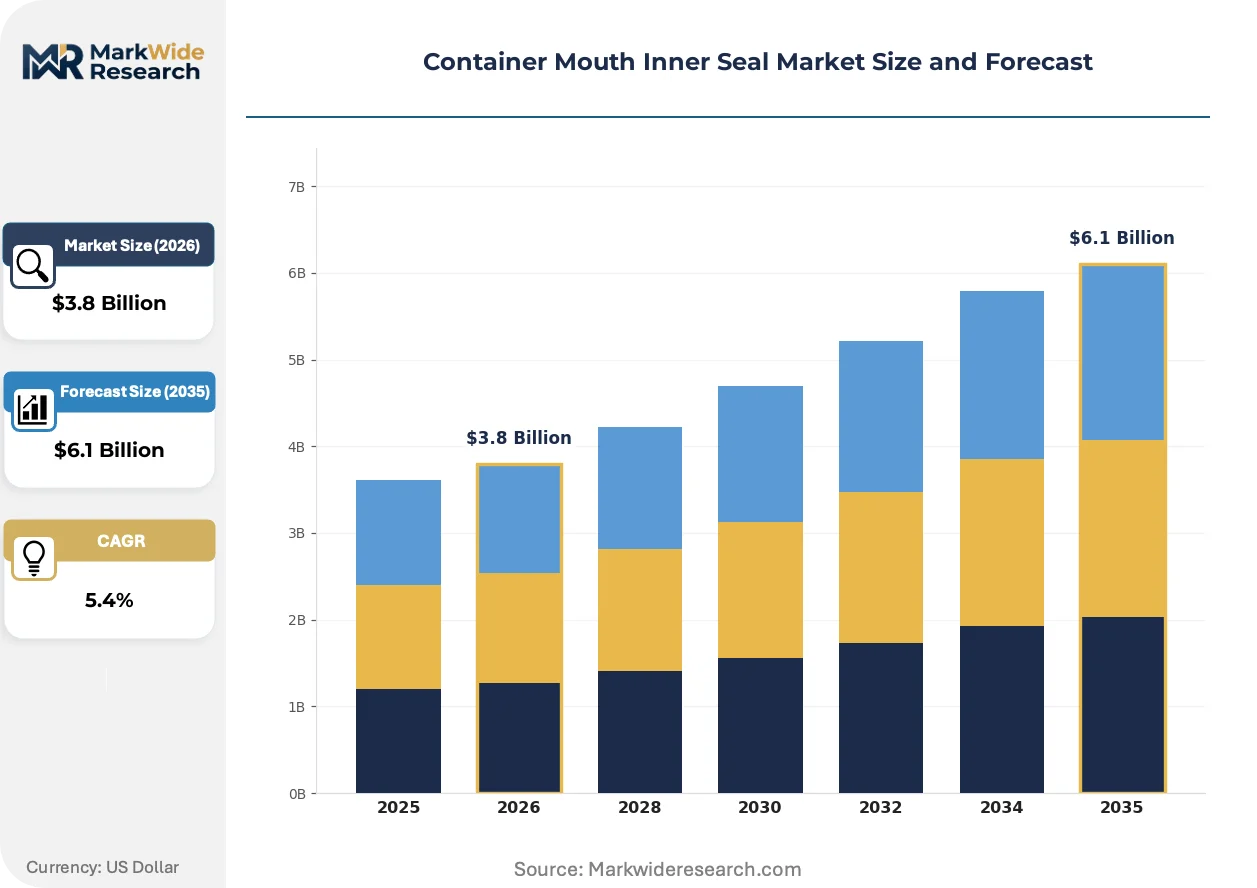
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Metal, Rubber, Silicone Application: Beverages, Food Packaging, Pharmaceuticals, Household Chemicals Seal Design: Pressure-Sensitive, Induction Seal, Vacuum Seal, Snap-On End User: Manufacturers, Distributors, Retailers, E-Commerce |
| Companies Covered | Seliger Group, Tekni-Plex, Pres-On, Meyer Seals GmbH, Bluemay Weston Limited, Integrated Liner Technologies, B&B Cap Liners LLC, Qorpak, Inc., Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Container Mouth Inner Seal Market Strategic Shifts
Digital printing and smart-seal technologies are collapsing minimum order quantities and enabling lot-level traceability, rewiring converter-customer relationships from volume-based to specification-intensive partnerships.
Laser-etched micro-QR codes and NFC-enabled induction seals are fragmenting the traditional commodity liner segment into traceability-embedded product tiers. Pharmaceutical contract packagers in Germany and Switzerland are piloting these seals for anti-counterfeiting verification. The technology is fragmenting price structures by attaching authentication premiums to previously undifferentiated barrier components.
REACH authorization procedures for persistent organic pollutants in seal coatings are accelerating substitution toward bio-based adhesion systems. European converters face reformulation deadlines that compress R&D resource allocation. Pharmaceutical and food contact applications in the EU are responding with pre-emptive supply chain audits to lock in compliant material streams ahead of sunset dates.
Consolidated buying desks at multinational pharmaceutical firms are compressing supplier panels and demanding integrated material-validation services. Regional converters with captive testing laboratories are displacing pure-play liner distributors. This concentration is most visible in German and Swiss health-product supply chains, where Meyer Seals GmbH and similar specialists bundle seal supply with extractables testing protocols.
Container Mouth Inner Seal Market Segmentation
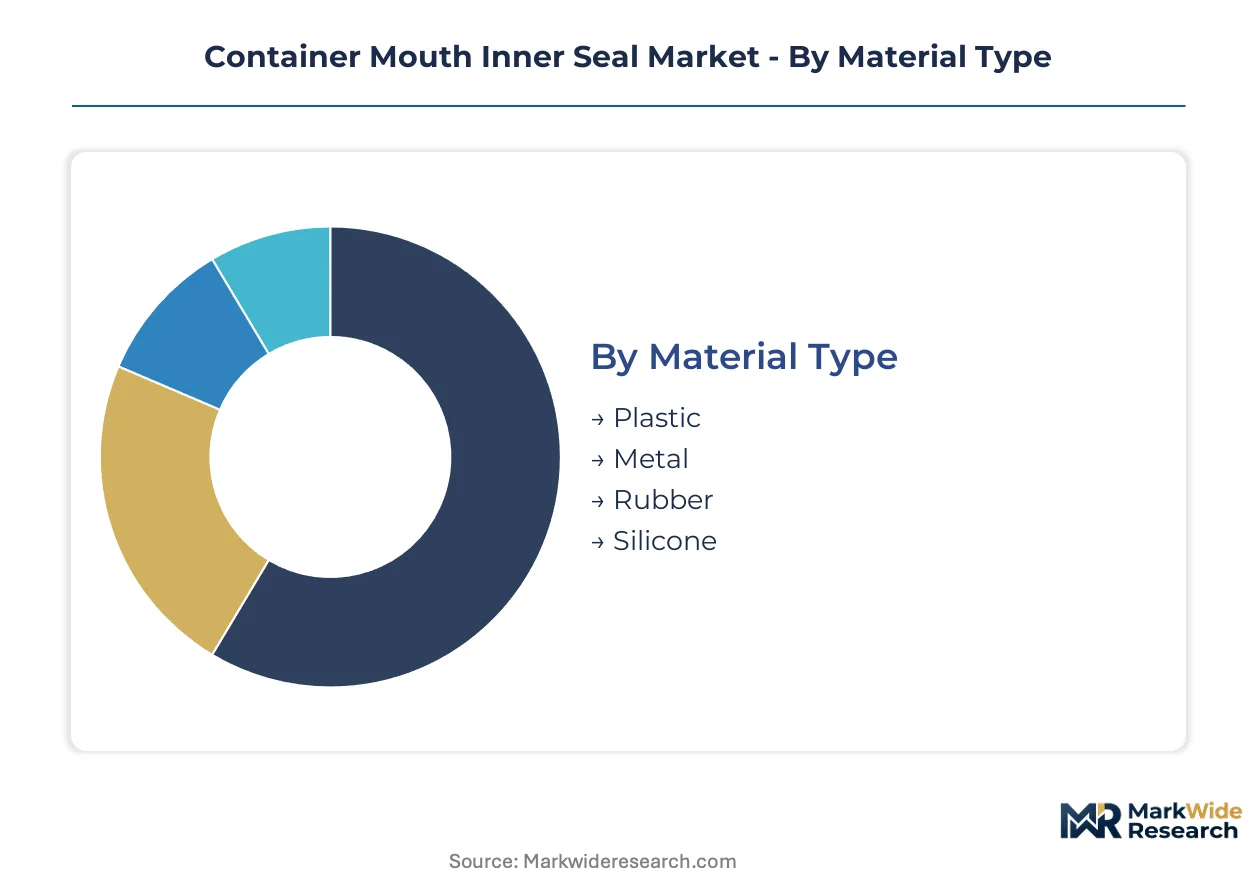
Segmentation in the container mouth inner seal market reveals divergent specification requirements across pharmaceutical, food, and beverage end-uses. Material selection and seal design choices directly determine barrier performance, regulatory compliance pathways, and integration complexity with automated capping infrastructure.
Material Type:
Domestic consumption patterns favor plastic and rubber formulations in beverage and household chemical applications, while export-oriented pharmaceutical packaging drives metal-reinforced specifications across Central European supply chains.
- Plastic:Extruded polyethylene and polypropylene foams dominate volume in cost-sensitive beverage and household chemical segments. German converters supply standardized density grades to Central European bottlers with limited barrier requirements.
- Metal:Laminated aluminum-polymer composites command premium positioning in pharmaceutical induction seals. EMA Annex 1 sterile manufacturing revisions pull metal-reinforced configurations into parenteral packaging lines across Switzerland and Germany.
- Rubber:Compression-molded synthetic rubber liners serve general-purpose food containers where moderate elasticity suffices. Italian and Spanish olive oil exporters specify natural rubber alternatives for organic product lines.
- Silicone:Platinum-cured silicone seals penetrate high-temperature autoclave applications in parenteral drug packaging. Swiss pharmaceutical contract manufacturers specify medical-grade silicone for steam-sterilized vial closures.
Plastic holds the largest share; momentum sits with metal-reinforced configurations.
Application:
Cost tiers stratify sharply across these four application clusters, with pharmaceutical specifications commanding 3-5x unit economics versus beverage commodity liners.
- Beverages:Carbonated soft drink and bottled water producers specify single-layer polyethylene foam wads. German mineral water exporters anchor volume demand with standardized 1.0-1.5 mm thickness profiles.
- Food Packaging:Retort-processed and aseptic food brands specify metal-reinforced induction seals to combat oxygen ingress during thermal cycles. Italian tomato processor exports to Middle Eastern markets drive specification tightening.
- Pharmaceuticals:ISO 15378-certified induction seals with tamper-evident features dominate parenteral and oral solid dose containers. Swiss and German health-product supply chains concentrate demand for extractables-tested barrier components.
- Household Chemicals:Bleach and solvent containers specify chemically resistant polyethylene formulations. French and Benelux detergent manufacturers prioritize compression-set resistance in automated capping lines.
Pharmaceuticals capture the highest margin tier; food packaging applications are climbing the fastest on retort and aseptic processing expansion.
Seal Design:
Volume concentration favors legacy pressure-sensitive and snap-on designs, while induction seal technology concentrates in pharmaceutical-grade manufacturing clusters with extended qualification timelines.
- Pressure-Sensitive:Adhesive-coated foam liners adhere through cap torque alone without heat activation. Beverage and household chemical applications in Germany and France standardize on these cost-minimized configurations.
- Induction Seal:Electromagnetic field-activated aluminum-polymer laminates create hermetic barriers with tamper-evident properties. Swissmedic-regulated pharmaceutical packagers in Basel and Zurich mandate these designs for export to regulated markets.
- Vacuum Seal:Negative-pressure activated gaskets serve specialized food preservation and laboratory containment. German laboratory reagent exporters specify vacuum-compatible silicone for air-sensitive compounds.
- Snap-On:Mechanical interference-fit liners press into cap shells without adhesive bonding. Low-cost beverage applications in Eastern European markets favor tool-free changeover compatibility.
Pressure-sensitive designs hold the largest share; induction seal configurations are expanding most quickly on pharmaceutical serialization mandates.
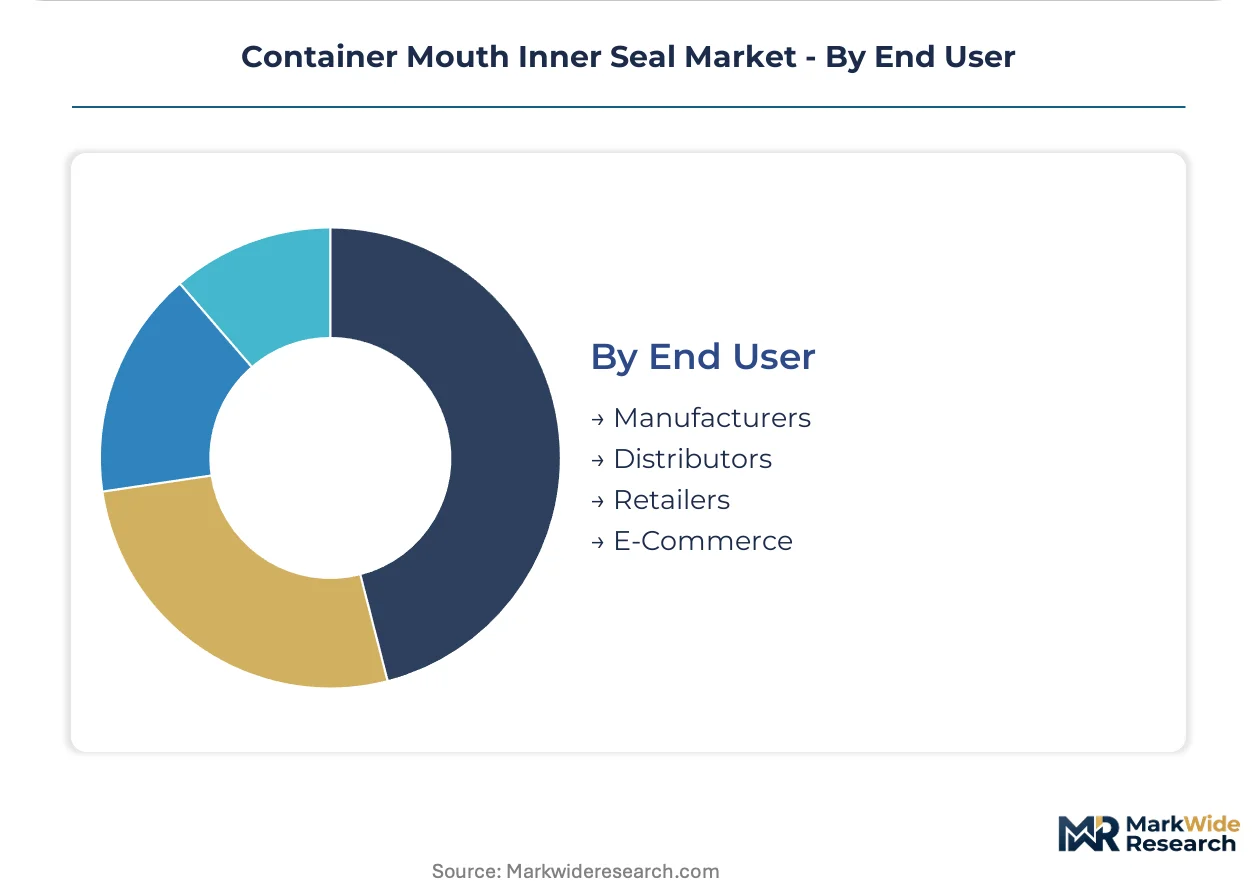
End User:
Procurement patterns diverge between captive manufacturing operations and distributed supply chains, with direct pharmaceutical manufacturer relationships commanding specification influence.
- Manufacturers:Brand-owning pharmaceutical and food companies specify seal performance criteria directly. German pharmaceutical manufacturers like those in the Rhine-Main cluster conduct incoming seal integrity validation under cGMP protocols.
- Distributors:Packaging material wholesalers aggregate demand across mid-tier beverage and chemical converters. Benelux distribution hubs stock standardized liner inventories for rapid-response replenishment.
- Retailers:Private-label food and beverage brands exert indirect pressure through converter specification requirements. Swiss and Austrian retail chains increasingly mandate tamper-evident features for premium private-label oils and sauces.
- E-Commerce:Direct-to-consumer fulfillment channels prioritize leak-resistant seals for variable orientation shipping. German online pharmacy fulfillment centers specify induction-sealed containers to prevent moisture ingress during transit.
Manufacturers hold the largest share; e-commerce channels are gaining share fastest on pharmaceutical direct-to-patient delivery expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract packagers and food exporters concentrate purchasing power in clustered industrial corridors. Converter proximity to automated filling lines and regulatory validation infrastructure shapes procurement patterns across major manufacturing basins.
Germany
EMA Annex 1 sterile manufacturing revisions pull advanced induction-seal designs into pharmaceutical packaging lines serving export markets. The country's F-Gas Regulation compliance deadlines accelerate converter migration toward lower-emission sealing materials. The Rhine-Main cluster around Frankfurt anchors dense concentrations of ISO 15378-certified liner producers serving Central European health-product supply chains.
Switzerland
Swissmedic-regulated pharmaceutical packagers in Basel and Zurich mandate tamper-evident induction seals for export to regulated markets. REACH authorization procedures for persistent organic pollutants compress reformulation timelines for seal coatings. The Basel pharmaceutical corridor concentrates demand for extractables-tested barrier components among contract manufacturing organizations.
United States
FDA cGMP standards mandate seal integrity validation for drug packaging across parenteral and oral solid dose applications. The EPA oversees chemical safety in seal coating formulations while OSHA regulates converter workplace exposure. The New Jersey-Pennsylvania pharmaceutical corridor anchors North American demand for validated liner substrates.
India
CDSCO-aligned manufacturers supplying regulated markets upgrade from basic wad seals to induction-sealed containers with tamper-evident features. The country's pharmaceutical export incentives under PLI schemes accelerate packaging line modernization. The Mumbai-Pune corridor concentrates converter investment serving generic drug exporters to US and European markets.
Italy
Retort-processed and aseptic food brands specify metal-reinforced induction seals to combat oxygen ingress during thermal cycles. EFSA food contact material regulations govern seal coating composition for olive oil and tomato product exports. The Emilia-Romagna packaging belt anchors converter capacity serving Mediterranean food processor demand.
Container Mouth Inner Seal Market Competitive Environment
Player mix skews toward mid-cap specialists with captive lamination and precision die-cutting capabilities. The vendor base organizes around three strategic tiers: pharmaceutical-grade converters with ISO 15378 certification, vertically integrated foam and film producers controlling substrate quality, and regional distributors aggregating standardized liner demand. Consolidation pressure intensifies as multinational pharmaceutical firms compress supplier panels and demand integrated material-validation services. Geographic expansion and backward integration into resin compounding represent dominant competitive moves.
Among German-based precision converters, Meyer Seals GmbH exemplifies the specialist archetype serving automated pharmaceutical capping lines. Seliger Group and Tekni-Plex occupy positions across the pharmaceutical-grade manufacturing tier, with the former representing European health-product supply chain dominance and the latter anchoring North American vertically integrated foam and film operations. These three entities illustrate the competitive structure: geography-anchored specialists, certification-heavy pharmaceutical players, and substrate-integrated North American operators.
| Leading Market Players |
|---|
| Seliger Group |
| Tekni-Plex |
| Pres-On |
| Meyer Seals GmbH |
| Bluemay Weston Limited |
| Integrated Liner Technologies |
| B&B Cap Liners LLC |
| Qorpak, Inc. |
| Sealed Air Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at German aluminum-polymer lamination facilities shapes both supply concentration and price floors across European pharmaceutical seal markets. Converter scale economies in the Rhine-Main cluster compress per-unit costs for ISO 15378-certified induction seals while marginal producers in Eastern Europe struggle to match qualification timelines.
Pricing Analysis
Cost-plus contracts with London Metal Exchange aluminum indexation dominate pharmaceutical-grade seal procurement. Pricing stratifies across ISO 15378-certified premium tiers, standard industrial grades, and economy beverage wads based on extractables testing depth and dimensional tolerance precision. Price erosion runs through commodity polyethylene foam segments as Asian converters expand capacity for beverage applications. Beverage bottlers exhibit highest price sensitivity, while Swiss and German pharmaceutical manufacturers prioritize barrier performance over unit cost.
Supply Chain Analysis
Rolled aluminum foil supply from European and Asian smelter-refiner networks creates a chokepoint that exposes converters to energy-cost pass-through volatility. German, Swiss, and Italian converter bases draw from concentrated aluminum substrate sources and specialized polymer resin compounding operations. Single-source vulnerability in pharmaceutical-grade adhesive chemistry concentrates risk among aging European workforces. Distribution runs through converter-direct relationships with pharmaceutical manufacturers and Benelux-based packaging material wholesalers serving mid-tier beverage and chemical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA Annex 1 sterile manufacturing revisions are accelerating specification turnover in pharmaceutical packaging, creating high-growth disruption as converters retool for sub-millimeter precision and tamper-evident traceability features.
For Market Incumbents: Secure ISO 15378 certification renewal timelines and captive extractables testing laboratory capacity to defend against regional converters bundling validation services. Deepen backward integration into aluminum-polymer lamination substrate production to offset energy-cost volatility from European smelter networks. Anchor relationships with Swissmedic-regulated contract packagers through integrated material-validation service offerings. For New Entrants and Emerging Players: Integrated supply chain documentation and F-Gas Regulation compliance verification services represent white-space opportunities where incumbent converters under-serve mid-tier pharmaceutical exporters. Target Indian CDSCO-aligned manufacturers upgrading from basic wad seals to induction-sealed containers with tamper-evident features. Pursue go-to-market partnerships with Mumbai-Pune corridor packaging line modernization integrators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision die-cutting and digital printing capabilities as pharmaceutical serialization mandates fragment minimum order quantities. Long-term viability hinges on converter assets with pharmaceutical-grade manufacturing infrastructure and regulatory validation relationships. Monitor ECHA REACH authorization procedure timelines for persistent organic pollutants as inflection indicators for reformulation-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Investment | Primary packaging material qualification opens pharmaceutical supply chains to EMA-regulated exporters. |
| Backward Integration into Lamination Substrates | In-house aluminum-polymer composite production insulates margins from LME volatility and energy-cost pass-through. |
| Digital Printing and Smart-Seal Technology Deployment | Laser-etched micro-QR and NFC-enabled seals capture authentication premiums in anti-counterfeiting applications. |
| Extractables Testing Laboratory Captivity | Integrated validation services displace pure-play distributors as pharmaceutical firms compress supplier panels. |
| Geographic Expansion into Indian Pharmaceutical Corridor | CDSCO-aligned packaging line modernization creates demand pull for induction-sealed container expertise. |
Study Parameters
Desk research of EMA regulatory filings, ECHA REACH authorization databases, and pharmaceutical packaging trade publications preceded structured interviews with converter operations managers, pharmaceutical packaging engineers, and regulatory affairs specialists at ISO 15378-certified facilities. Primary fieldwork across German, Swiss, and Italian manufacturing clusters was triangulated against customs trade data, SEC 10-K disclosures from listed packaging material firms, and aluminum industry association capacity reports. Bottom-up seal volume estimates by material type and application were cross-validated through top-down pharmaceutical packaging expenditure analysis.
Variance decomposition across material type, seal design, application, and end-user segments structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate synthesis anchored to pharmaceutical serialization mandate implementation timelines and retort-processed food export expansion patterns. Modeled inputs included EMA Annex 1 sterile manufacturing revision adoption curves, EU F-Gas Regulation compliance cost pass-through assumptions, and Indian PLI scheme pharmaceutical export incentive uptake rates.
Forecasts assume regulatory continuity in EMA sterile manufacturing standards and ECHA REACH authorization procedures; material policy shifts would require re-modeling of pharmaceutical-grade material qualification timelines and substitution chemistry R&D allocation. Practitioners should keep alternative scenarios live as aluminum smelter energy-cost volatility and Indian pharmaceutical export incentive extensions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Laboratory Sample Container Market
Containers
Sandwich Containers Market
Containers
Latin America Intermediate Bulk Container Liner Market
Containers
ISO Container Market
Containers
EMEA Container Technology Market
Containers
Cylindrical Cans Market
Containers
Sample Containers Market
Containers
Gable Top Container Market
Containers
Tottle Containers Market
Containers
Algeria Container Glass Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Conipack Pails Market
Containers
Foldable Steel Containers Market
Containers
Steel Containers Market
Containers
Vials Market
Containers
Pinch Grip Jars Market