
 ISO Container Market | 2026-2036
ISO Container Market Size, Share, and Industry Trends Forecast 2026-2036
ISO Container Market Intelligence
The integration of real-time tracking and condition monitoring services is realigning the value proposition beyond physical container sales. China International Marine Containers (Group) Co., Ltd. (CIMC) leverages its massive manufacturing scale to dominate the dry cargo segment. Stolt-Nielsen Limited specializes in the tank container niche, focusing on the transport of bulk liquids and chemicals. Singamas Container Holdings Ltd. competes through a diversified portfolio that includes specialized and refrigerated containers.
An ISO container is a standardized reusable steel box designed for intermodal freight transport across ship, rail, and truck. Constructed primarily from Corten steel, these units feature standardized dimensions and corner castings for secure handling and stacking. Dry cargo containers constitute the largest product type by volume, while refrigerated units command higher margins for temperature-sensitive goods. Shipping lines represent the primary end user for new purchases, with leasing companies providing critical fleet flexibility to the market.
Adherence to International Organization for Standardization (ISO) standards, particularly ISO 668 for dimensions, is fundamental for market access. The Convention for Safe Containers (CSC) and specific regional rules from bodies like the US Occupational Safety and Health Administration (OSHA) dictate inspection and safety protocols. Stakeholders must now decide whether to invest in proprietary smart container technology or rely on third-party service providers for fleet intelligence.
Market Dynamics
The central structural force shaping the ISO container market is the transition from a hardware-centric model to a service-based ecosystem. This shift is driven by the integration of smart technologies, which creates a new competitive layer based on data and fleet intelligence rather than sheer manufacturing scale.
Growth Catalysts
- Intermodal Expansion:The continued expansion of intermodal transport networks, particularly rail freight corridors in Asia and Africa, necessitates larger fleets of standardized containers to ensure seamless cargo flow.
- Smart Container Technology:Adoption of IoT sensors for real-time tracking and condition monitoring allows shippers to optimize logistics, reduce spoilage for perishable goods, and enhance cargo security, creating new service-based revenue streams.
- Trade Facilitation Policies:International agreements aimed at streamlining customs procedures, such as the WTO's Trade Facilitation Agreement, reduce port dwell times and encourage investment in efficient containerized shipping.
Market Restraints
- Input Cost Volatility:The market is highly sensitive to fluctuations in the price of Corten steel and specialized paints, which constitute a significant portion of the total manufacturing cost and can erode producer margins.
- Manufacturing Concentration:An overwhelming concentration of production capacity in China creates geopolitical and supply chain risks, leaving the global market vulnerable to regional policy shifts, port congestion, or trade disputes.
- Cyclical Oversupply:The industry is subject to boom-and-bust cycles where periods of high demand lead to over-ordering, resulting in a subsequent glut of containers that suppresses prices and newbuild orders.
Strategic Opportunities
- Specialized Container Development:There is an opportunity to design and market specialized containers for nascent sectors, such as modular battery energy storage systems, mobile data centers, and vertical farming units.
- Inland Logistics Penetration:Targeting the development of containerized logistics for inland and last-mile delivery in underpenetrated markets like South America and parts of Southeast Asia offers a new frontier for growth.
- Blockchain Integration:Combining IoT tracking with blockchain technology can create highly secure and transparent supply chains, offering a premium service for high-value goods like pharmaceuticals and electronics.
Industry Challenges
- Regulatory Compliance Burden:Manufacturers and operators must navigate a complex web of standards, including ISO 668 for dimensions and the Convention for Safe Containers (CSC) for safety, which requires continuous investment in certification and inspection.
- High Capital Expenditure:The significant capital investment required for fleet renewal and expansion, particularly for higher-cost refrigerated and smart units, poses a barrier for smaller shipping lines and leasing companies.
- Legacy System Integration:Integrating data from new smart container platforms with existing, often decades-old, terminal operating systems and enterprise resource planning software presents a significant technical and operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ISO Container Market |
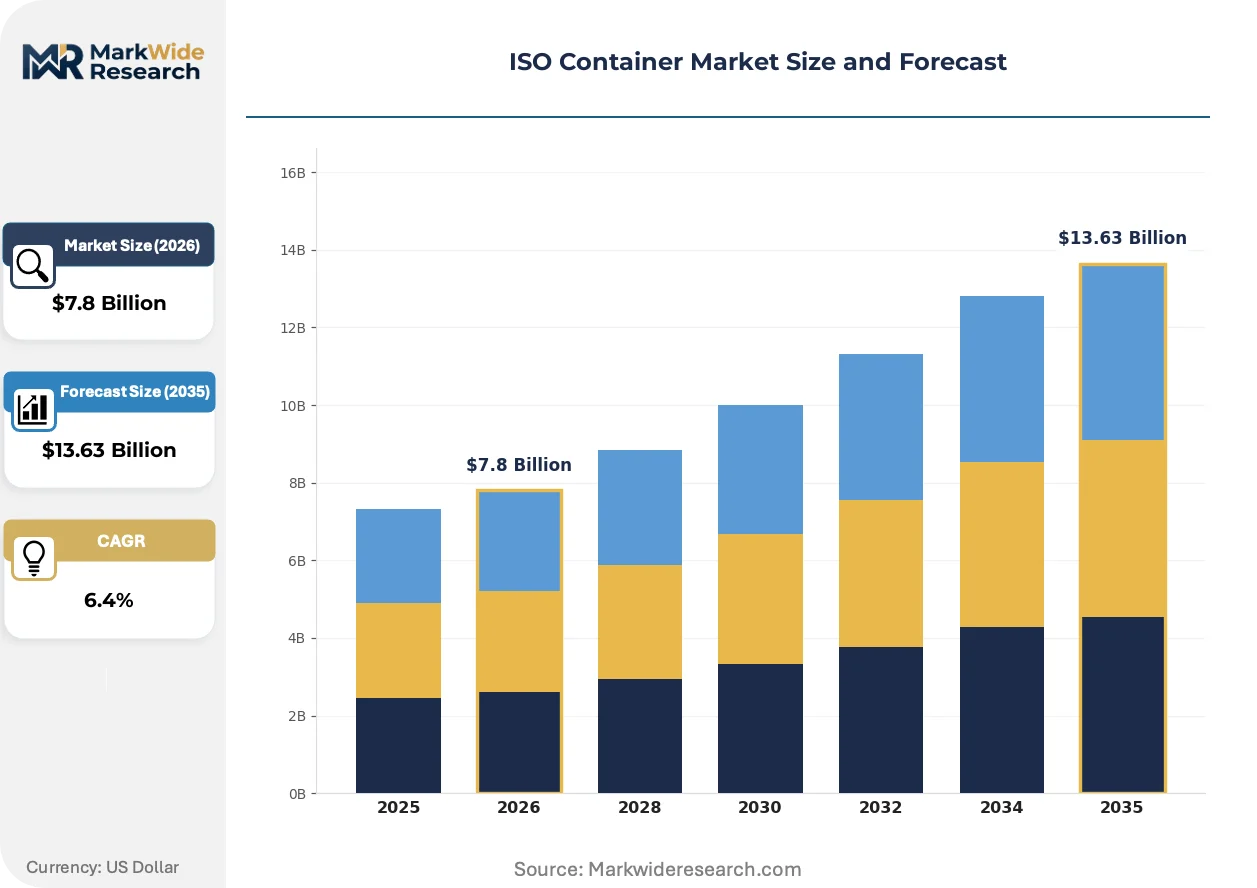
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Cargo, Refrigerated, Tank, Open Top, Flat Rack, Bulk Material: Steel, Aluminum, Composite, Fiberglass, High-Density Polyethylene, Wood End User: Shipping Lines, Freight Forwarders, Charterers, Leasing Companies, Port Terminals, Logistics Service Providers Application: Intermodal Transport, Warehousing, Temporary Storage, Containerized Cargo, Military Logistics, Disaster Relief |
| Companies Covered | Singamas Container Holdings Ltd., Cryeng Group, China International Marine Containers (Group) Co., Ltd. (CIMC), Air Water Inc., Lapesa Grupo Empresarial S.L., Dong Fang International Container Group (DFIC), Chart Industries, Inc., Stolt-Nielsen Limited, CXIC Group Containers Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ISO Container Market Strategic Shifts & Innovations
A fundamental re-evaluation of the container as a connected asset is underway, moving its value proposition beyond physical cargo carriage to that of a mobile data node. This evolution is compelling stakeholders to invest in digital capabilities to remain competitive in a logistics environment that increasingly prioritizes visibility and predictability.
IoT sensors embedded within the container structure provide real-time data on location, temperature, humidity, and shock events. Shipping lines and cargo owners are the primary adopters, seeking to mitigate risks for sensitive shipments and improve supply chain efficiency. This integration of hardware and software is consolidating the market's value proposition around data-driven fleet intelligence, moving beyond the physical asset.
New sustainability mandates, such as the EU's Corporate Sustainability Reporting Directive (CSRD), are influencing equipment choices. The directive requires large companies to disclose Scope 3 emissions, which directly implicates their logistics and transportation activities. The refrigerated container segment is most affected, as operators now seek units with higher energy efficiency and advanced monitoring to accurately report and reduce their carbon footprint.
A distinct behavioral shift sees shipping lines favoring flexible, long-term leasing models over direct ownership for a significant portion of their fleets. This strategy allows carriers to adjust fleet size in response to fluctuating trade demand without committing massive capital, effectively transferring asset risk to large container leasing firms. The practice is most visible in the standard dry cargo segment, where managing container repositioning and trade imbalances is a constant operational focus.
ISO Container Market Segmentation
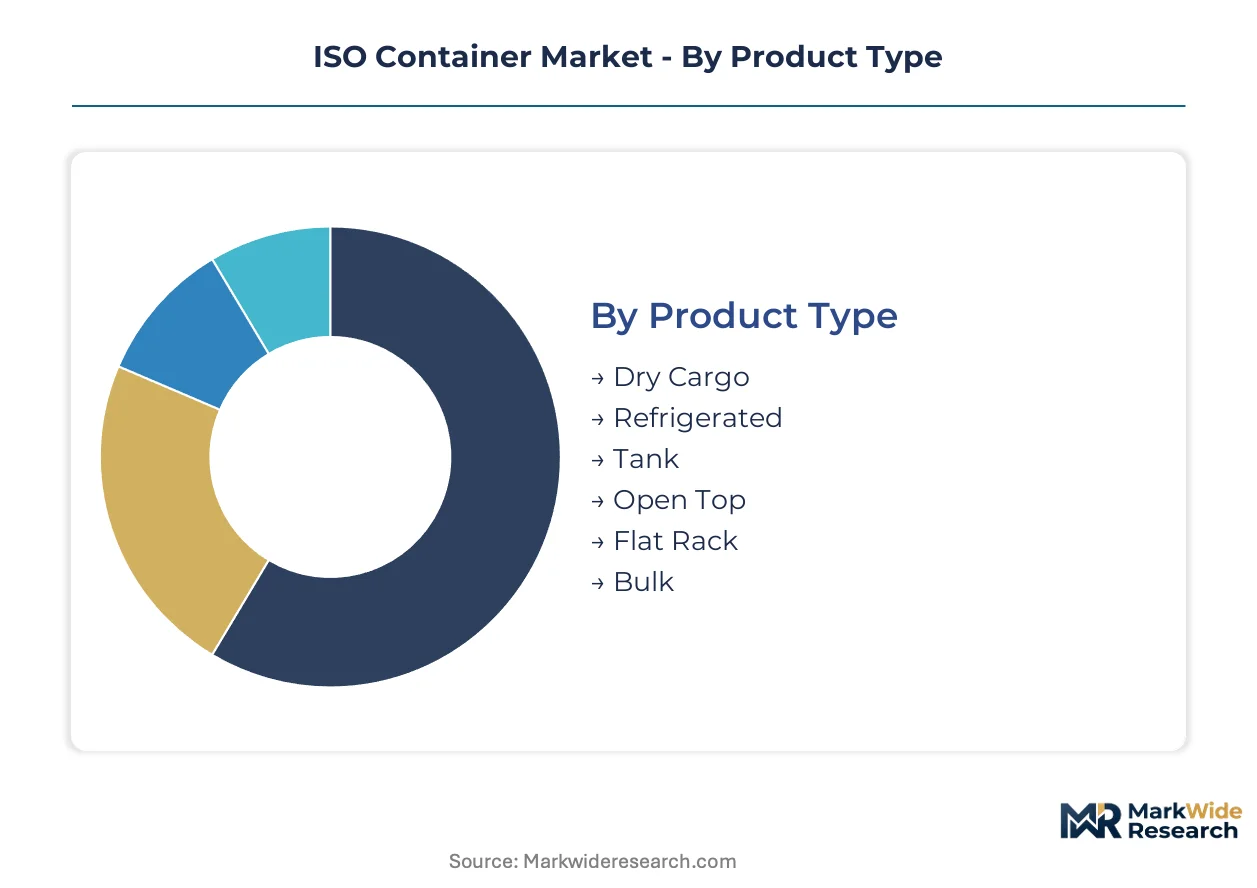
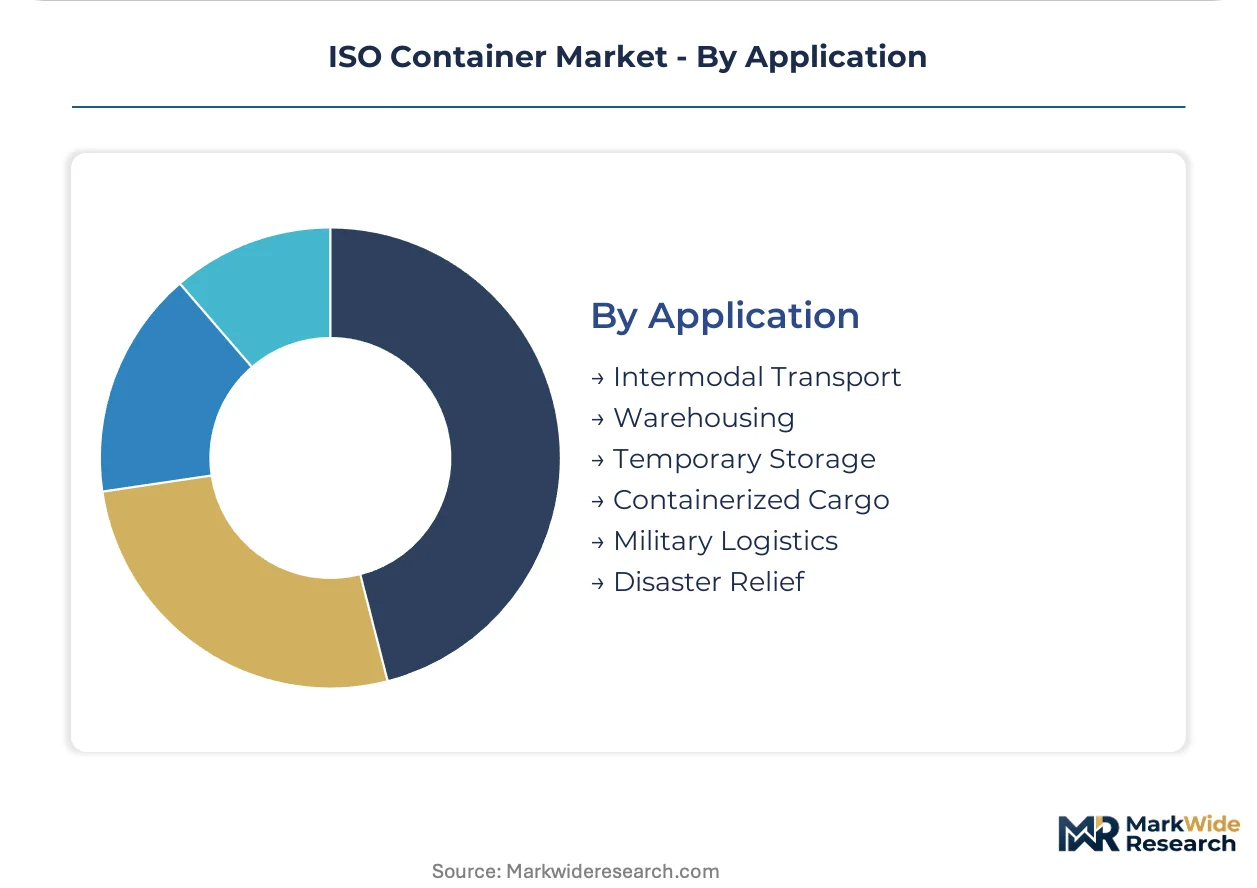
Segmentation provides a structured view of the ISO container market, highlighting distinct demand drivers and operational requirements across different product types, materials, end users, and applications. Understanding these segments is crucial for stakeholders to tailor product development and strategic investments effectively within the evolving logistics landscape.
Product Type:
Buyers of ISO containers are primarily differentiated by the specific cargo characteristics and handling requirements their goods demand.
- Dry Cargo:These are standardized reusable steel boxes, predominantly made from Corten steel, designed for general purpose intermodal freight transport. Demand concentrates in China due to its extensive manufacturing base and global trade routes, driven by the need for efficient movement of consumer goods.
- Refrigerated:These insulated units feature integrated cooling systems to maintain precise temperature ranges for perishable goods, such as food and pharmaceuticals. Demand is concentrating in sectors sensitive to spoilage, with sustainability mandates like the EU's CSRD driving investment in energy-efficient models.
- Tank:These specialized containers are designed for the safe transport of bulk liquids, gases, and chemicals, adhering to strict safety and material compatibility standards.
- Open Top:Featuring a removable tarpaulin roof instead of a solid one, these containers facilitate the loading of oversized cargo from the top by crane, common for heavy machinery.
- Flat Rack:These units consist of a flat base with fixed or collapsible end walls, ideal for transporting heavy, bulky, or irregularly shaped goods that cannot fit into standard containers.
- Bulk:Designed for granular materials or powders, these containers often feature specialized loading hatches and discharge systems, optimizing the transport of commodities like grain or minerals.
Volume sits with Dry Cargo containers; growth tilts toward Refrigerated units.
Material:
Material choices for ISO containers are dictated by the specific application environments and structural integrity requirements.
- Steel:Corten steel is the predominant material, offering high tensile strength, excellent corrosion resistance, and robust durability for demanding intermodal transport conditions. This material dominates the dry cargo segment, chosen by shipping lines for its cost-effectiveness and proven performance across global trade routes.
- Composite:These advanced materials, often fiber-reinforced polymers, provide a lightweight alternative with enhanced insulation properties and resistance to specific chemical environments. Demand for composite containers is expanding in specialized applications like refrigerated units and air cargo, where weight reduction and thermal efficiency are paramount.
- Aluminum:Offering a lighter weight than steel, aluminum containers are used in niche applications where payload capacity is critical, despite their higher cost and susceptibility to certain types of damage.
- Fiberglass:Primarily employed in specialized tank containers, fiberglass offers excellent chemical resistance and is suitable for transporting corrosive liquids or specific bulk chemicals.
- High-Density Polyethylene:This plastic material is used for certain types of liquid bulk containers or reusable intermediate bulk containers (IBCs), valued for its chemical inertness and lighter weight.
- Wood:While not a primary structural material for ISO containers, wood is used for specialized internal linings, flooring, or custom crating within containers for delicate or specific cargo.
The primary material choice is influenced by the trade-off between durability and weight reduction.
End User:
End users are differentiated by their operational models and their strategic approach to fleet ownership versus leasing.
- Shipping Lines:These entities directly purchase and operate vast fleets of containers to facilitate their global maritime transport networks, managing complex logistics and repositioning. Shipping lines represent the primary end user for new container purchases, driven by the need to maintain operational efficiency and fleet capacity for intermodal transport.
- Leasing Companies:These firms own large container fleets and provide flexible leasing options to shipping lines and other operators, enabling them to adjust capacity without significant capital expenditure. Leasing companies provide critical fleet flexibility to the market, absorbing asset risk and managing repositioning, particularly for standard dry cargo segments.
- Freight Forwarders:These companies coordinate the shipment of goods for clients, often utilizing containers leased from other providers or securing space on existing shipping lines.
- Charterers:These entities hire vessels or containers for specific voyages or periods, typically for project cargo or specialized transport needs outside regular liner services.
- Port Terminals:While not direct purchasers of containers for transport, port terminals are critical end users of container handling equipment and storage, facilitating their role as intermodal hubs.
- Logistics Service Providers:Offering integrated supply chain solutions, these providers manage diverse aspects of cargo movement, often incorporating containerized transport for inland and last-mile delivery.
Shipping Lines remain the largest direct procurement channel, while Leasing Companies enable market agility.
Application:
Applications are distinguished by the primary functional purpose the ISO container serves within the supply chain.
- Intermodal Transport:This application involves the seamless movement of cargo in the same container across multiple modes of transport—ship, rail, and truck—without intermediate handling of the cargo itself. Global trade routes and the expansion of rail freight corridors in Asia necessitate robust intermodal capabilities to ensure efficient cargo flow and reduce transit times.
- Containerized Cargo:This broad application encompasses the general purpose of using ISO containers to protect and transport a wide variety of goods, from manufacturing components to finished consumer products, across global supply chains. This application is central to manufacturing output and consumer goods distribution, particularly benefiting from China's extensive manufacturing and export capabilities.
- Warehousing:Containers are frequently repurposed or utilized on-site for temporary or semi-permanent storage solutions, offering flexible and secure space for goods at various points in the supply chain.
- Temporary Storage:This application leverages containers for short-term storage needs, such as during peak seasons, construction projects, or for overflow inventory, providing a quick and adaptable storage option.
- Military Logistics:ISO containers are essential for transporting military equipment, supplies, and personnel, enabling rapid deployment and secure storage in various operational theaters.
- Disaster Relief:In humanitarian efforts, containers serve as critical infrastructure for transporting aid, medical supplies, and temporary shelters, facilitating rapid response to emergencies.
The core utility of ISO containers centers on Intermodal Transport, with Containerized Cargo representing its broadest functional expression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ISO container market exhibits a distinct geographical divide between concentrated production capacity and widespread consumption demand. Manufacturing hubs, primarily in Asia, supply a global network of shipping lines and logistics providers. This structural dynamic influences regional investment priorities and supply chain resilience.
China
China's vast manufacturing base drives significant demand for dry cargo containers to support its export-oriented economy. The dual carbon goals influence container production towards more sustainable materials and energy-efficient manufacturing processes. Major port cities like Shanghai and Shenzhen serve as critical gateways, handling immense container volumes and facilitating global trade.
United States
Demand in the United States stems from extensive intermodal transport networks connecting major consumer markets to import hubs. OSHA regulations mandate strict safety standards for container handling and maintenance within its borders. Inland logistics hubs such as Chicago and Kansas City are expanding, requiring consistent container availability for rail and truck distribution.
Germany
European manufacturing output and sophisticated logistics infrastructure sustain robust demand for specialized and dry cargo containers in Germany. The EU Green Deal and CSRD are accelerating the adoption of energy-efficient refrigerated units and transparent supply chain data. Major ports like Hamburg and Bremen are central to Northern European trade, necessitating efficient container flow.
India
India's expanding manufacturing sector and infrastructure projects fuel increased domestic and international containerized trade. The PLI scheme supports local manufacturing, influencing future container production capacity. Port cities such as Mundra and JNPT are undergoing significant expansion, boosting demand for new container fleets.
Brazil
Agricultural exports and a growing internal market generate demand for ISO containers, particularly for bulk and refrigerated goods. ANVISA regulations impact temperature-sensitive pharmaceuticals, driving demand for compliant refrigerated units. The port of Santos, as Latin America's largest, requires substantial container capacity for its diverse cargo mix.
ISO Container Market Key Industry Players
Capital-heavy producers compete with asset-light leasing companies in the ISO container market. The market structure is moderately consolidated among core manufacturers but fragmented among numerous operators and lessors providing fleet flexibility. Strategic archetypes include large-scale dry cargo manufacturers, specialized container fabricators, and advanced fleet management solution providers. Dominant competitive moves involve significant capacity expansion by manufacturers and strategic partnerships with global shipping lines and logistics service providers.
Among the prominent players, China International Marine Containers (Group) Co., Ltd. (CIMC) anchors the large-scale dry cargo manufacturing segment, leveraging its substantial production capabilities. Stolt-Nielsen Limited exemplifies specialization, focusing on the tank container niche for bulk liquids and chemicals, meeting stringent safety and material compatibility standards. Singamas Container Holdings Ltd. occupies a position of portfolio diversification, offering a range of specialized and refrigerated containers to cater to varied cargo requirements. These entities collectively shape the global supply dynamics and innovation trajectory within their respective segments.
| Leading Market Players |
|---|
| Singamas Container Holdings Ltd. |
| Cryeng Group |
| China International Marine Containers (Group) Co., Ltd. (CIMC) |
| Air Water Inc. |
| Lapesa Grupo Empresarial S.L. |
| Dong Fang International Container Group (DFIC) |
| Chart Industries, Inc. |
| Stolt-Nielsen Limited |
| CXIC Group Containers Co., Ltd. |
Cost & Logistics Intelligence
Capital-heavy producers, predominantly state-backed entities in China, dictate global ISO container supply dynamics. Their expansive manufacturing capacity directly influences market pricing and inventory levels.
Pricing Analysis
Price erosion across standard dry cargo containers traces to cyclical oversupply and intense manufacturing concentration. The dominant pricing model involves long-term contract-based leasing for fleet flexibility and transactional sales for new builds. Price differentiation stems from container specialization, such as refrigerated or tank units, and integration of smart technologies for real-time data. Buyers of temperature-sensitive units for pharmaceuticals exhibit lower price sensitivity compared to general dry cargo shipping lines.
Supply Chain Analysis
Logistics and freight costs significantly influence the global ISO container supply chain, particularly for repositioning empty units. Production capacity concentrates overwhelmingly in China, with key manufacturers like CIMC and DFIC dominating. The supply chain relies heavily on Corten steel and specialized paints as primary raw materials. This geographic concentration creates supply chain risks from regional policy shifts or port congestion. Distribution runs through direct sales to shipping lines and long-term leasing agreements with specialized companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
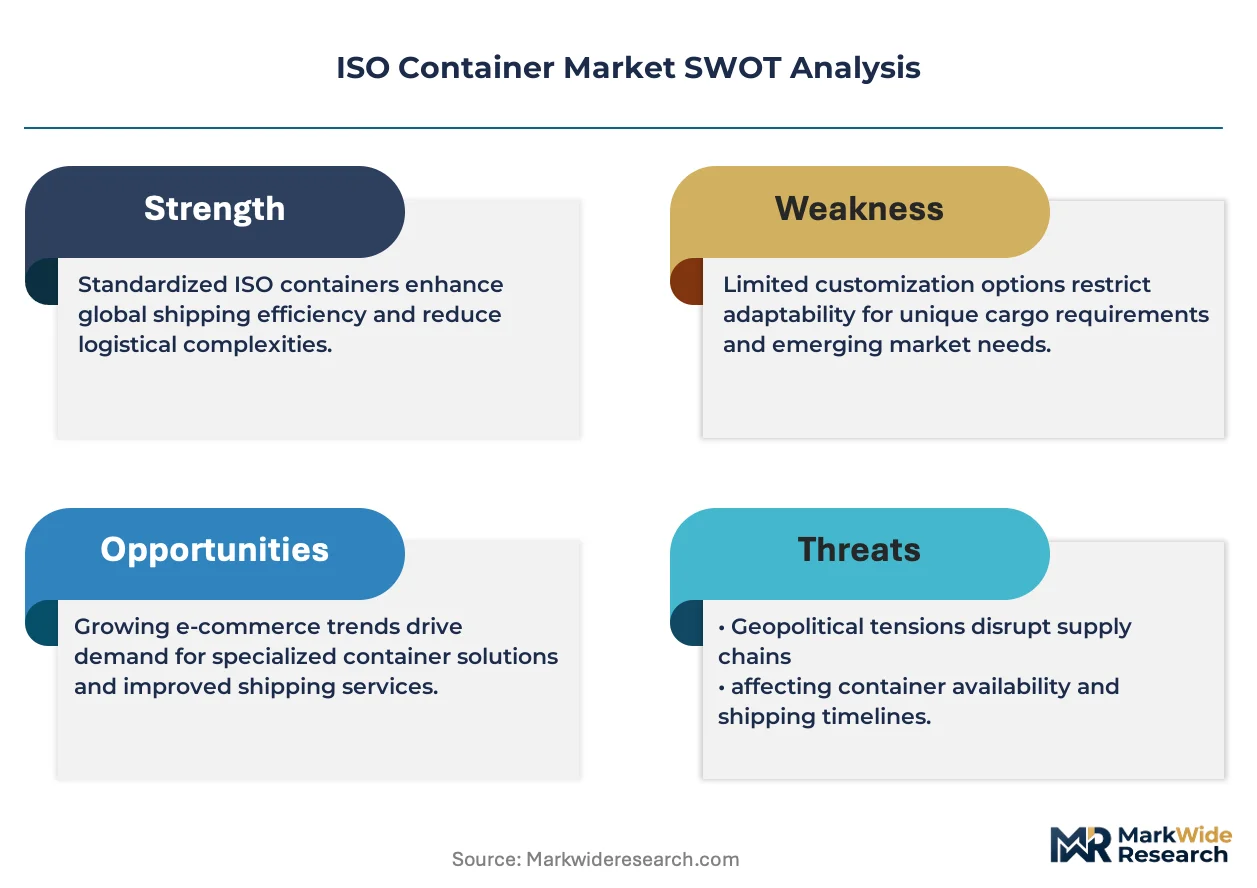
The ISO container market presents a supply-constrained narrative, particularly for specialized units. Limited global manufacturing capacity for refrigerated containers props pricing for temperature-sensitive logistics.
For Market Incumbents: Anchor market share through strategic investments in smart container technology development and advanced material research for specialized units. Incumbents like CIMC face the threat of margin erosion from input cost volatility and geopolitical supply chain risks. Expanding manufacturing capacity in diversified geographies, beyond China, and investing in certification for new smart features are critical levers. This approach mitigates over-reliance on single-region production.
For New Entrants and Emerging Players: Price-point gaps exist between premium specialized containers and standard dry cargo units, offering entry opportunities. New entrants should target niche applications like modular battery energy storage systems or mobile data centers, which require specialized designs. Inland logistics penetration in underpenetrated markets, such as South America, represents a significant growth frontier. A go-to-market angle focused on integrated blockchain and IoT solutions provides a premium service for high-value goods.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized container fabricators in Europe, particularly those focused on tank or refrigerated units. The long-term viability of the ISO container market remains strong due to persistent global trade and intermodal expansion. Investors should target mid-sized technology providers offering smart container solutions and fleet intelligence platforms. A critical signal to watch is the sustained increase in new build orders for specialized containers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Specialized Units | This initiative addresses demand for high-margin refrigerated and tank containers, enhancing global supply resilience. |
| Smart Container Technology Integration | IoT sensors and blockchain integration provide real-time visibility, improving supply chain efficiency for shipping lines. |
| Diversification into Niche Applications | Developing containers for modular battery systems or mobile data centers opens new revenue streams beyond traditional cargo. |
| Inland Logistics Market Penetration | Targeting underpenetrated markets like South America expands containerized transport applications and regional trade. |
| Sustainable Material Adoption | Utilizing energy-efficient designs and advanced composites aligns with EU CSRD mandates and reduces operational carbon footprints. |
Research Approach
Independent corroboration across industry reports, customs data, and company financial filings underwrites the qualitative findings. This study combined extensive primary interviews with shipping line executives, container manufacturers, leasing company operators, and logistics service providers. Secondary validation utilized trade association publications, port authority statistics, and regulatory body guidelines, including ISO and CSC standards. Bottom-up and top-down triangulation refined market size estimations and growth projections.
Rate-of-change decomposition isolated key growth drivers and market restraints across the analysis window. The analytical framework modeled segmentation dimensions by product type, material, end user, and application. Compound annual growth rates were derived from historical data analysis and projected demand-supply imbalances. Key forecast inputs included global trade volumes and raw material price indices.
Inputs from major container manufacturers and shipping lines were available through the study window; gaps in real-time smart container adoption data introduce uncertainty bands. Forecasts reflect assumptions regarding global economic stability and trade policy evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Global Food Storage Container Market
Containers
Steel Containers Market
Containers
Canning Jars Market
Containers
HDPE Bottles Market
Containers
Global Container Monitoring Market
Containers
Algeria Container Glass Market
Containers
Lever Lid Tinplate Containers Market
Containers
PUR Containers Packaging Market
Containers
Global Styrene Compartment Boxes Market
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Oblong Jar Market
Containers
Disposable Lids Market
Containers
Composite Ibcs System Market
Containers
Cylindrical Cans Market
Containers
Clear Hinged Container Market