
 Hot Chocolate Market | 2026-2036
Hot Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Chocolate Market Intelligence
Premium flavor development and co-branding with café chains is reconfiguring profit pools away from commoditized powdered mixes. Nestlé leverages its vast distribution network to command shelf space in supermarkets globally. Godiva specializes in the premium, gift-oriented segment, often through its own specialty stores. Starbucks, in contrast, dominates the ready-to-drink and in-café service channels, setting trends for flavor profiles.
Hot chocolate is a heated beverage consisting of shaved chocolate, melted chocolate, or cocoa powder, dissolved in a liquid such as milk or water. Its composition, specifically the ratio of cocoa solids to cocoa butter, determines its richness and classification. While powdered mix remains the largest product type by volume, ready-to-drink formats represent the fastest-growing segment. Within formulations, sugar-free and milk-based alternatives are gaining share, driven by health-conscious consumers.
Product formulation and labeling are governed by food safety authorities such as the US FDA and the European Food Safety Authority (EFSA). Regulations concerning sugar content, allergen declarations, and country-of-origin labeling for cocoa beans directly impact manufacturing. In India, the FSSAI sets standards for beverage safety and quality. Navigating the patchwork of international food standards and ethical sourcing certifications is a central strategic challenge for market participants.
Market Dynamics
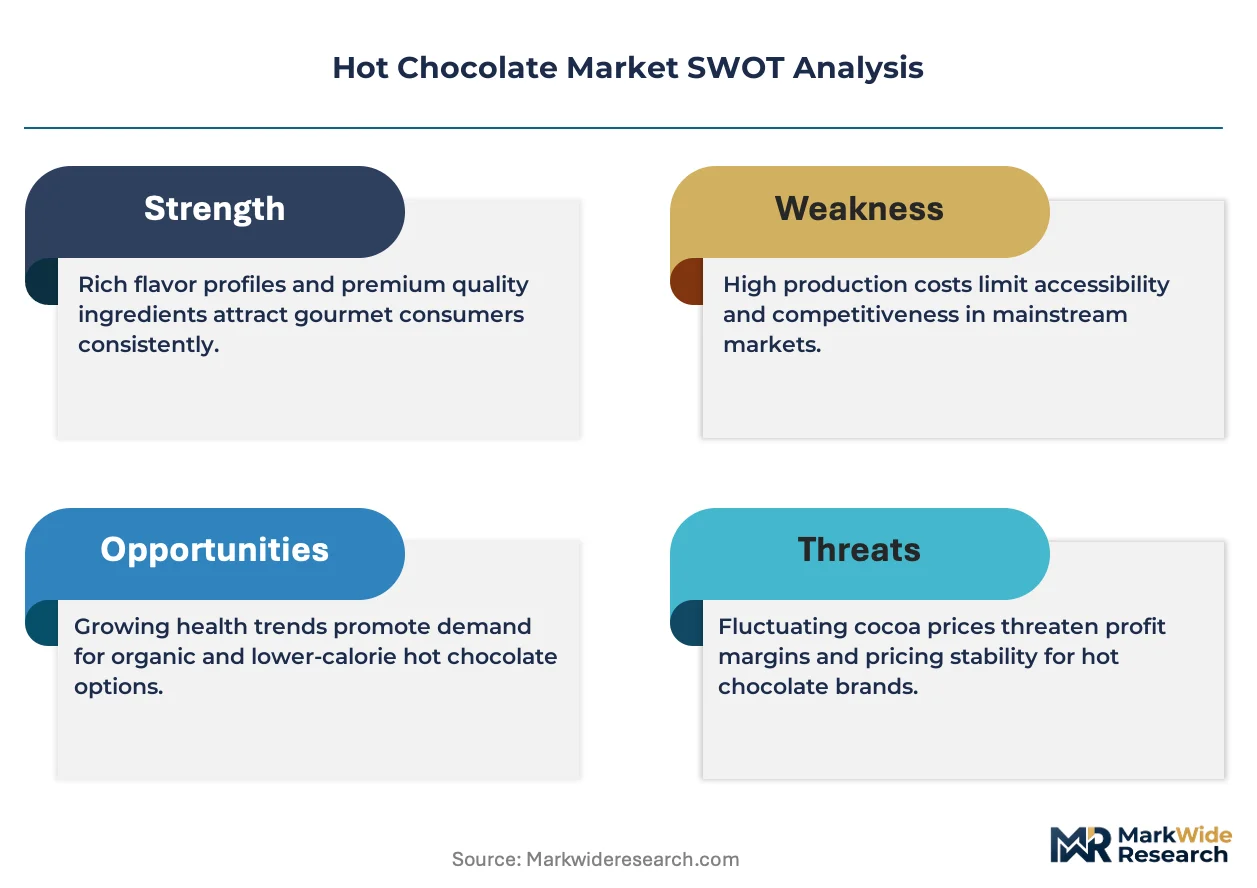
The central tension shaping the hot chocolate market is the collision between consumer demand for premium, indulgent experiences and mounting regulatory pressure for sugar reduction. This dynamic forces innovation in formulation, balancing rich flavor profiles against clean-label and health-oriented product attributes.
Growth Catalysts
- Premiumization in Food Service:The expansion of global café chains, particularly in the United States and Europe, creates a primary channel for introducing consumers to gourmet and artisanal hot chocolate preparations, elevating the category beyond commoditized retail mixes.
- Clean-Label Reformulation:Guidelines from the US FDA on added sugar labeling are compelling brands to innovate with natural sweeteners and simpler ingredient lists, appealing to health-conscious consumers and opening new product categories.
- Functional Ingredients:The integration of functional additives such as plant-based proteins, probiotics, and vitamins into hot chocolate mixes is attracting new consumer segments seeking beverages that offer benefits beyond simple indulgence.
Market Restraints
- Cocoa Price Volatility:Unpredictable fluctuations in the price of cocoa beans, driven by climate events and political instability in key growing regions like West Africa, create significant cost pressure and margin uncertainty for manufacturers.
- Sugar Content Regulation:Strict regulations on sugar content in beverages, enforced by bodies like the European Food Safety Authority (EFSA), limit formulation possibilities and increase compliance costs, particularly for mass-market products.
- Beverage Category Substitution:Intense competition from other premium hot beverages, including specialty coffees, wellness teas, and functional lattes, presents a persistent substitution threat, especially among younger, trend-driven consumers.
Strategic Opportunities
- Emerging Market Expansion:Underpenetrated markets with rising disposable incomes, such as India and Southeast Asian nations, present significant white space for both retail and food service hot chocolate brands to establish a foothold.
- Direct-to-Consumer Channels:The rise of e-commerce platforms enables artisanal and specialty hot chocolate makers to build direct relationships with consumers, bypassing traditional retail gatekeepers and capturing higher margins.
- Plant-Based Formulations:Developing a wider range of high-quality, dairy-free hot chocolate options using oat, almond, or soy milk bases caters to the growing vegan and flexitarian consumer populations in developed markets.
Industry Challenges
- Certification Complexity:Navigating the fragmented landscape of ethical and sustainable sourcing certifications, such as Fair Trade and Rainforest Alliance, requires substantial administrative investment and complex supply chain verification processes.
- Supply Chain Traceability:Implementing robust traceability systems to comply with country-of-origin labeling mandates and prove ethical sourcing claims is a major operational hurdle for brands sourcing cocoa from multiple regions.
- Maintaining Flavor Consistency:As brands reformulate products to reduce sugar or incorporate functional ingredients, maintaining the expected taste and texture profile that consumers associate with the brand becomes a critical R&D challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Chocolate Market |
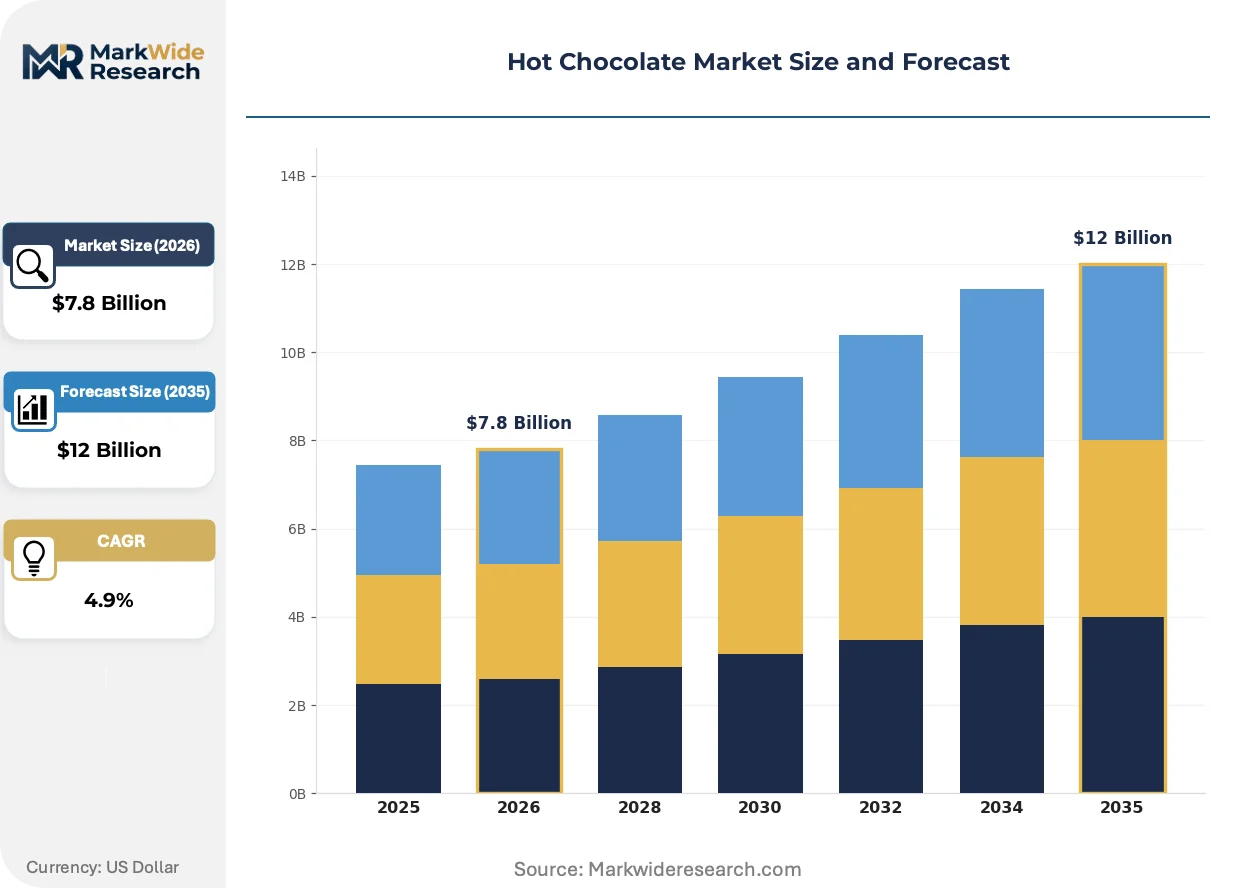
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Mix, Liquid, Cocoa Beans, Ready-to-Drink Formulation: Milk-Based, Dark Chocolate, White Chocolate, Sugar-Free Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Cafés Consumer Type: Adults, Children, Health-Conscious, Gourmet Enthusiasts |
| Companies Covered | Ghirardelli Chocolate Company, Unilever, Nestlé, Godiva, Lindt & Sprungli, The Hershey Company, Starbucks, Swiss Miss, Mondelez International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Chocolate Market Strategic Shifts & Innovations
Formulation science is advancing to meet dual consumer demands for both health-conscious ingredients and premium sensory experiences. This evolution, combined with new regulatory frameworks and changing consumption habits, is fundamentally altering the product landscape and competitive dynamics of the hot chocolate market.
Micro-encapsulation technology provides a method for protecting sensitive ingredients within powdered hot chocolate mixes. Premium and functional food brands are adopting this process to shield volatile flavor compounds, vitamins, and probiotics from degradation during storage and preparation. The product category is migrating from simple powder blends to sophisticated delivery systems that ensure ingredient efficacy and enhance the final beverage's aroma and taste.
European Food Safety Authority (EFSA) guidance on reducing added sugar intake is directly influencing food policy and manufacturer behavior across the continent. This regulatory pressure compels brands to invest in R&D for alternative sweeteners like stevia and monk fruit to reformulate existing product lines. The sugar-free and low-sugar segments are most impacted, with innovation focused on achieving authentic chocolate flavor without relying on sucrose.
A notable behavioral shift sees hot chocolate moving beyond its traditional role as a seasonal winter beverage. Consumers are increasingly enjoying it year-round, often in iced or blended cold formats, which disrupts conventional marketing calendars tied to colder months. This trend is most prominent in the ready-to-drink segment and within café chains in North America, which are adding chilled chocolate drinks to permanent menus.
Hot Chocolate Market Segmentation
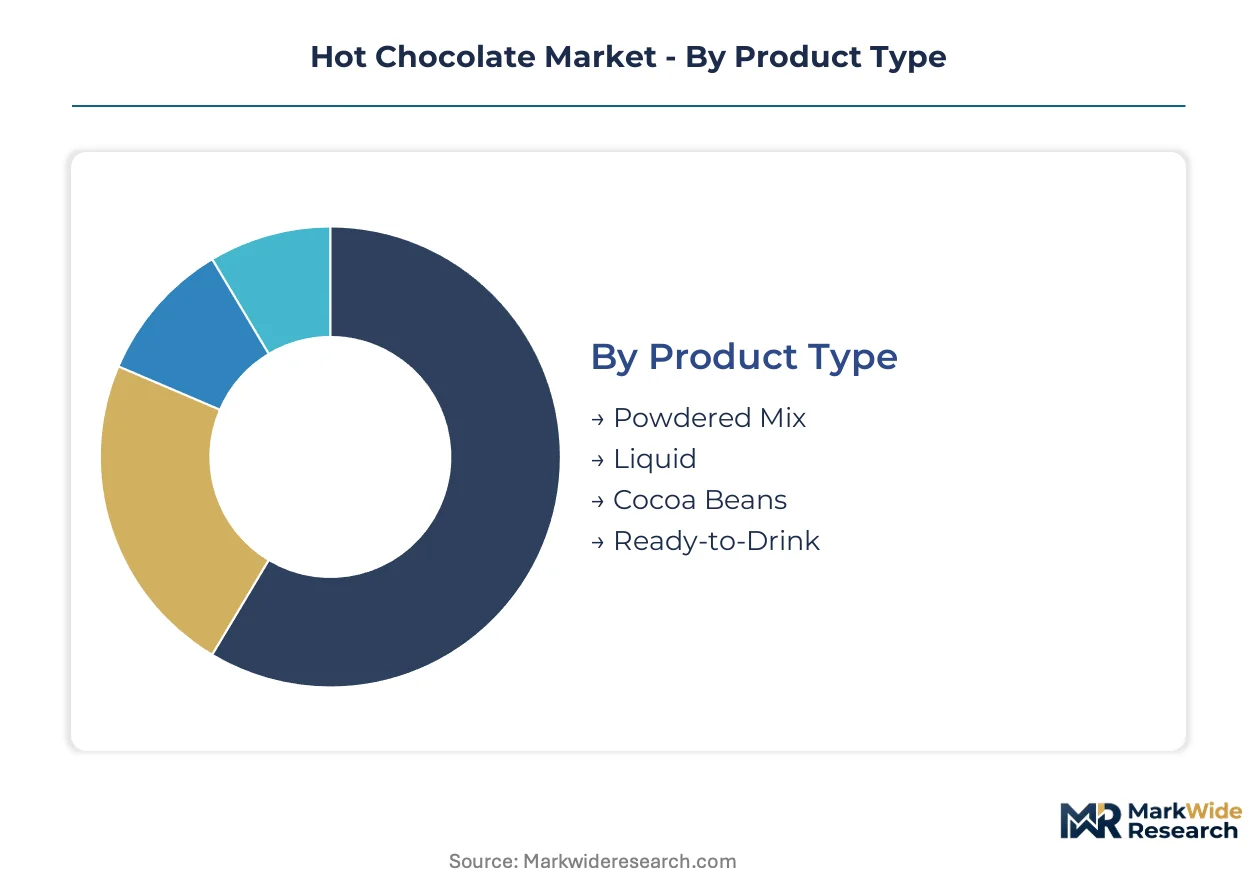
A granular understanding of the hot chocolate market requires dissecting its various components. This segmentation highlights distinct product forms, ingredient compositions, sales channels, and consumer preferences. Analyzing these divisions reveals where value creation and demand shifts are most pronounced across different market participants.
Product Type:
The product type dimension delineates hot chocolate offerings based on their physical form and preparation method.
- Powdered Mix:These products typically consist of cocoa powder, sugar, and often powdered milk solids, requiring hot liquid for reconstitution. Demand for powdered mixes concentrates in household consumption, driven by convenience and cost-effectiveness for everyday use.
- Liquid:Liquid hot chocolate typically involves concentrated syrup or melted chocolate, often used in café environments for premium beverage creation.
- Cocoa Beans:This segment represents the raw material for chocolate production, primarily traded as commodities to manufacturers.
- Ready-to-Drink:Pre-mixed and often shelf-stable or refrigerated beverages, these products offer immediate consumption without preparation. Demand for RTD formats is accelerating in convenience stores and food service, appealing to consumers seeking on-the-go indulgence.
Powdered Mix holds installed capacity. Ready-to-Drink is rotating up the share rankings.
Formulation:
Ingredient composition significantly influences the flavor profile and nutritional attributes of hot chocolate products.
- Milk-Based:These formulations incorporate dairy or plant-based milk powders, creating a creamy texture and milder chocolate flavor. Consumer preference for milk-based varieties remains strong in traditional markets, supported by established taste profiles.
- Dark Chocolate:Formulations characterized by a higher cocoa solid content, offering a more intense and less sweet chocolate experience.
- White Chocolate:This formulation lacks cocoa solids, using cocoa butter, sugar, and milk solids to create a distinct creamy, sweet profile.
- Sugar-Free:Products formulated without added sucrose, relying on alternative sweeteners like stevia or monk fruit to meet health-conscious demands. Demand for sugar-free options is concentrating in developed markets like the United States and Europe, driven by regulatory pressures and health trends.
Milk-Based formulations retain broad consumer appeal. Sugar-Free formulations are expanding most quickly.
Distribution Channel:
Sales pathways for hot chocolate products vary significantly, impacting brand reach and consumer access.
- Supermarkets:Large retail outlets offering a wide selection of powdered mixes and ready-to-drink hot chocolate, catering to mass consumer markets.
- Online Retail:E-commerce platforms facilitate direct-to-consumer sales for artisanal brands and broad distribution for established manufacturers. This channel sees demand concentrating among younger, digitally native consumers seeking convenience and niche products.
- Specialty Stores:Dedicated chocolate shops or gourmet food retailers provide curated selections of premium hot chocolate, often emphasizing origin and craftsmanship.
- Cafés:Food service establishments serving prepared hot chocolate beverages, often featuring premium ingredients and custom flavor profiles. Demand in cafés is driven by the desire for indulgent, out-of-home experiences, particularly in urban centers.
Supermarkets provide foundational market access. Cafés are gaining share fastest as premium outlets.
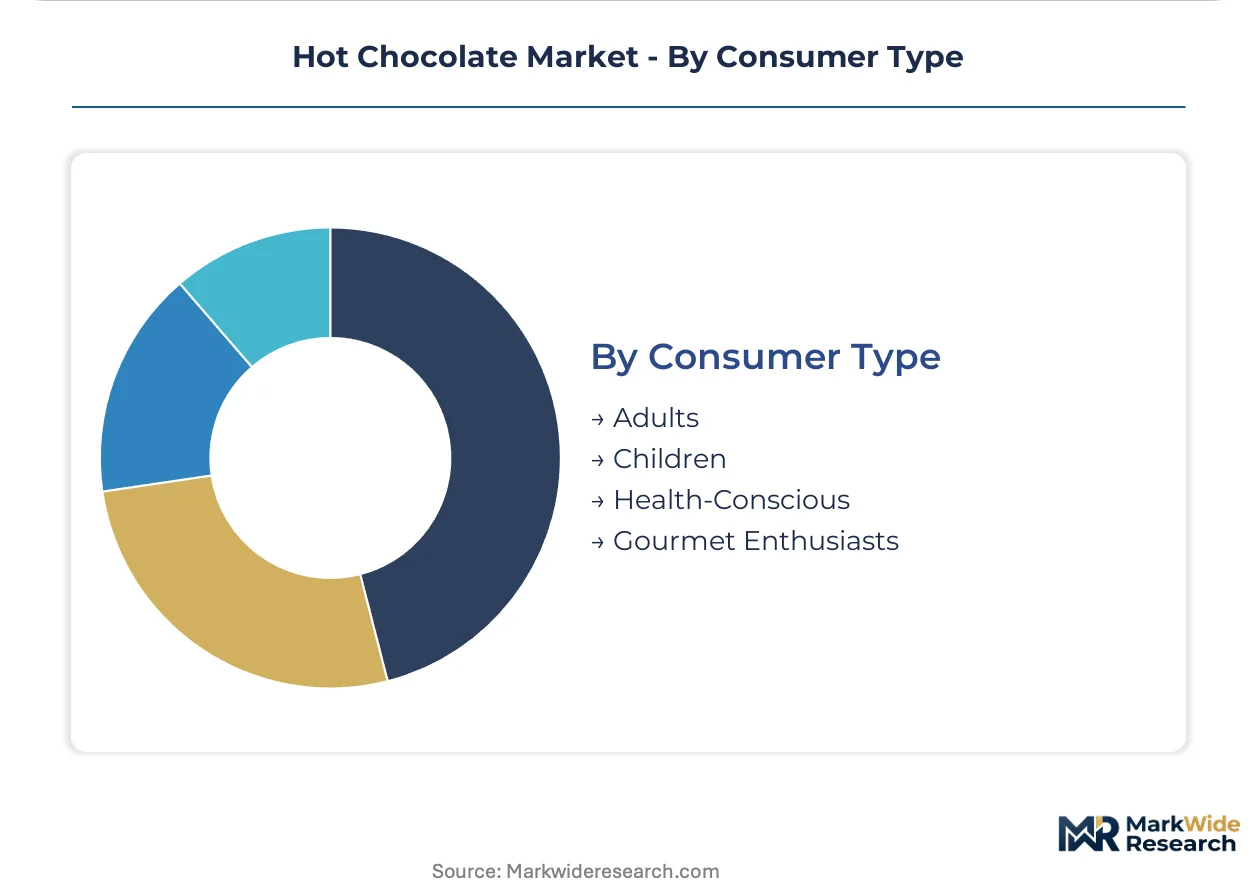
Consumer Type:
Consumer type segmentation considers the demographic and psychographic profiles of hot chocolate purchasers.
- Adults:This broad segment consumes hot chocolate for comfort, indulgence, or as a coffee alternative, often preferring sophisticated flavor profiles.
- Children:This segment primarily consumes sweeter, milk-based hot chocolate, often marketed with appealing packaging and simple preparation.
- Health-Conscious:Consumers prioritizing products with lower sugar, natural ingredients, or functional additives like protein or vitamins. This segment's demand is concentrating in regions with strong wellness trends, such as Western Europe, driven by dietary awareness.
- Gourmet Enthusiasts:Individuals seeking high-quality, artisanal hot chocolate with unique flavor notes, single-origin cocoa, or premium ingredients. Demand for gourmet products is pronounced in developed markets like Switzerland and the United States, appealing to discerning palates.
Adults form the largest consumer base. Gourmet Enthusiasts represents the fastest-growing segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hot chocolate market exhibits varied consumption patterns globally, with some regions favoring premium indulgence while others prioritize convenience. This consumption-mix differential shapes product development and distribution strategies across continents. Emerging markets are also adapting their preferences.
United States
Demand for gourmet and artisanal hot chocolate concentrates in urban centers, fueled by consumer desire for premium experiences. The US FDA's guidelines on added sugar labeling compel manufacturers to reformulate existing products. Major cities like New York and Los Angeles drive innovation in café-based premium hot chocolate offerings and ready-to-drink formats.
Switzerland
Swiss consumers show strong demand for high-quality, dark chocolate formulations and gift-oriented products. Swissmedic ensures strict food safety and quality standards, influencing premium chocolate manufacturing processes. Zurich and Geneva remain hubs for specialty chocolate boutiques, emphasizing origin, craftsmanship, and exclusive product lines.
Germany
German households maintain consistent demand for traditional powdered hot chocolate mixes due to convenience and value. The European Food Safety Authority (EFSA) regulations on sugar content directly impact beverage formulation in Germany. Berlin's vibrant café culture increasingly adopts plant-based hot chocolate options, reflecting broader dietary trends.
India
India represents an underpenetrated market with rising disposable incomes driving new hot chocolate consumption. The FSSAI sets standards for beverage safety and quality, influencing local and imported product adherence. Major metropolitan areas like Mumbai and Delhi see expanding café chains introducing premium hot chocolate menus.
United Kingdom
The United Kingdom exhibits strong demand for ready-to-drink hot chocolate formats and health-conscious alternatives. Food Standards Agency (FSA) guidance on allergen declarations and nutritional labeling is critical for manufacturers. London's diverse food service sector pioneers innovative flavor profiles and functional ingredient integration in hot chocolate.
Hot Chocolate Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure. The hot chocolate market exhibits a blend of global conglomerates focused on volume and specialized artisanal producers targeting premium segments. Strategic archetypes include mass-market producers leveraging extensive retail presence, premium brand innovators emphasizing ingredient quality, and niche direct-to-consumer specialists. Geographic expansion into underpenetrated markets and portfolio diversification into health-conscious formulations represent dominant competitive moves among market participants.
Within the premium and mass-market tiers, Nestlé exemplifies the strategy of leveraging vast distribution networks for broad product accessibility. Godiva represents the high-end, gift-oriented segment, often through specialized retail channels that emphasize luxury and craftsmanship. Starbucks, known for its in-café service and ready-to-drink formats, occupies a position at the forefront of trend-setting flavor profiles and convenience-driven consumption. These entities collectively demonstrate the diverse archetypes and strategic approaches employed to capture market share across different consumer preferences.
| Leading Market Players |
|---|
| Ghirardelli Chocolate Company |
| Unilever |
| Nestlé |
| Godiva |
| Lindt & Sprungli |
| The Hershey Company |
| Starbucks |
| Swiss Miss |
| Mondelez International |
| Others |
Cost & Logistics Intelligence
West African cocoa-producing regions' capacity fluctuations directly influence global cocoa bean prices, which in turn dictate cost structures for hot chocolate manufacturers worldwide.
Pricing Analysis
Long-term offtake agreements for cocoa beans stabilize costs for major manufacturers, while smaller players often navigate volatile spot markets. Price differentiation stems from quality grade, with gourmet artisanal products commanding higher premiums due to specialized ingredients and brand equity. Pricing pressure intensifies for mass-market powdered mixes, driven by intense competition and consumer demand for value. Health-conscious consumers show less price sensitivity for sugar-free or functional formulations, contrasting with the high sensitivity of traditional powdered mix buyers.
Supply Chain Analysis
Extended payment terms for cocoa farmers in West Africa provide some stability, but supply chain finance facilities are less common across fragmented smallholder networks. The supply chain relies heavily on cocoa beans sourced primarily from Ghana and Côte d'Ivoire, alongside sugar and various milk solids. Commodity price volatility for cocoa beans presents a significant structural risk, impacting margins across the value chain. Distribution runs through a multi-channel model, encompassing mass-market supermarkets, specialized retail outlets, and the rapidly expanding café food service sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hot chocolate market is experiencing a platform-economics inflection, driven by the expanding café ecosystem which fosters new flavor profiles and consumption occasions.
For Market Incumbents: Harden supply chain resilience against cocoa price volatility by diversifying sourcing regions and investing in long-term farmer partnerships. Invest in R&D for natural sweeteners and functional ingredients to mitigate regulatory pressure on sugar content. Control over key distribution channels like supermarkets and café chains remains critical to counter emerging specialty coffee competition. For New Entrants and Emerging Players: Direct-to-consumer e-commerce channels for artisanal, plant-based hot chocolate represent a penetrable entry point in health-conscious developed markets. Focus on unique flavor profiles and clean-label ingredient stories to capture gourmet enthusiasts. Underpenetrated markets like India offer white space for premium ready-to-drink formats. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors brands innovating in functional ingredients and alternative sweeteners for long-term category growth. Acquisition targets should include niche premium brands with strong regional presence or established ethical sourcing certifications. Increased M&A activity within the plant-based or sugar-free segments signals a market inflection point to watch.| Strategic Initiative | Industry Significance |
|---|---|
| Enhance Ethical Sourcing Programs | Reinforces brand reputation and mitigates supply chain risks from cocoa origin countries. |
| Expand Plant-Based Product Lines | Captures demand from vegan and flexitarian consumers in Western European markets. |
| Invest in Micro-Encapsulation R&D | Protects sensitive functional ingredients and volatile flavor compounds in powdered mixes. |
| Forge Café Chain Partnerships | Expands market reach and introduces premium hot chocolate experiences to new consumers. |
| Develop Sugar-Free Formulations | Addresses regulatory pressures and health-conscious consumer preferences in the United States. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory documents, company reports, and trade publications. Primary interviews engaged brand managers, R&D directors, food service procurement leads, and retail category buyers to gather qualitative insights. Secondary sources included FDA guidelines, EFSA regulations, FSSAI standards, and industry association reports. A robust triangulation approach combined bottom-up market sizing with top-down validation of segment trends.
Forecast inputs considered include historical market performance, demographic shifts, and evolving regulatory landscapes across the analysis window. The analytical framework modeled segmentation dimensions such as product type, formulation, distribution channel, consumer type, and regional regulatory frameworks. Compound annual growth rates were derived from historical data extrapolation, competitive intelligence, and expert consensus. Key industry-specific forecast inputs included cocoa bean price trends and consumer health trend adoption rates.
Macroeconomic conditions sit as an overlay; deviation in global economic growth or consumer disposable income would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and technological advancements in ingredient formulation. Unforeseen climate events impacting cocoa harvests or sudden shifts in food safety regulations could revise the forecast.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Citrus Water Market
Beverages
Japan Kombucha Market
Beverages
Europe Fruits and Vegetables Juice Market
Beverages
Ready to Drink Premixes Market
Beverages
South East Asia Bottled Water Market
Beverages
Sparkling Bottled Water Market
Beverages
Fruit Beverages Market
Beverages
Grab and Go Bottles Market
Beverages
Health Drinks Market
Beverages
Asia-Pacific Juices Market
Beverages
Aloe Vera Drinks Market
Beverages
Chocolate Powdered Drinks Market
Beverages
Water Bottle Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Beverage Dispenser Market
Beverages
Mixers Market