
 Aloe Vera Gel Market | 2026-2036
Aloe Vera Gel Market Size, Share, and Industry Trends Forecast 2026-2036
Aloe Vera Gel Market Intelligence
Certified organic cultivation expertise is redrawing competitive boundaries in aloe vera gel supply chains. Forever Living Products Inc. leverages vertical integration across its own plantations to secure raw material consistency, while Lily of the Desert anchors its position through R&D intensity in polysaccharide stabilization. Patanjali Ayurved dominates India's domestic Ayurvedic channel with extensive rural sourcing networks that sustain cost advantages against imported alternatives.
Aloe vera gel constitutes the mucilaginous extract derived from the inner leaf parenchyma of Aloe barbadensis miller, typically standardized to acemannan content between 0.5% and 1.5% for therapeutic and cosmetic applications. Its primary commercial purpose centers on topical anti-inflammatory, moisturizing, and wound-healing functionalities across personal care and nutraceutical formulations. Organic gel commands premium shelf positioning in European and North American specialty retail, while blended formulations capture volume in mass-market cosmetics where cost engineering outweighs purity claims. Direct sales channels occupy the highest margin pool through relationship-based recurring purchases, though online retail is accelerating fastest among millennial and Gen-Z demographics seeking ingredient transparency.
The U.S. FDA oversees aloe vera as a botanical drug substance under its botanical drug development guidance, while the EU Cosmetics Regulation mandates safety assessment and notification through the Cosmetic Products Notification Portal before market entry. India's CDSCO and FSSAI enforce dual-track oversight for aloe vera positioned as pharmaceutical excipients versus food-grade additives, creating compliance complexity for multi-category suppliers. Stakeholders must monitor evolving organic certification reciprocity between USDA NOP and India's APEDA standards to preempt supply disruptions in cross-border ingredient trade.
Market Dynamics
Cold-pressed extraction technology is compressing margins for heat-processed gel suppliers while EU Cosmetics Regulation enforcement tightens purity documentation requirements across export channels.
Growth Catalysts
- EU Cosmetics Regulation:Mandatory safety assessment through the Cosmetic Products Notification Portal is filtering out uncertified suppliers and consolidating demand around verified organic processors.
- Ayurvedic pharmaceutical corridors:India's CDSCO and FSSAI dual-track oversight is formalizing quality standards for aloe vera excipients, expanding institutional procurement from Maharashtra's processing clusters.
- Clean-label cosmetics:South Korean formulators are accelerating acemannan-standardized gel procurement to meet K-beauty transparency mandates, pulling supply from certified organic cultivators.
Market Restraints
- Input cost volatility:Organic certification compliance costs for USDA NOP and APEDA reciprocity protocols are squeezing mid-tier processors unable to absorb audit expenses.
- Supply concentration risk:Maharashtra and Gujarat's plantation belts dominate raw leaf supply, creating monsoon-dependent vulnerability for global gel processors.
- Substitution threat:Centella asiatica and snail mucin extracts are capturing share in South Korean cosmetic formulations where texture properties overlap with aloe vera.
Strategic Opportunities
- Underpenetrated geography:Brazil's ANVISA regulatory pathway for botanical drugs remains underutilized by acemannan-standardized gel suppliers seeking Latin American pharmaceutical channels.
- Regulatory tailwind:India's PLI scheme for herbal extracts offers cost-offset incentives for processors expanding cold-pressed capacity in Andhra Pradesh and Tamil Nadu.
- Distribution innovation:Direct-to-consumer subscription models for raw gel pouches are bypassing traditional ayurvedic retail networks in Tier-2 Indian cities.
Industry Challenges
- Certification timeline compression:USDA NOP organic certification cycles averaging 18-24 months are misaligning with cosmetics brand launch schedules demanding six-month ingredient qualification.
- Skill scarcity in polysaccharide stabilization:R&D chemists capable of maintaining acemannan integrity through cold-chain logistics command premium compensation, constraining mid-cap processor expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aloe Vera Gel Market |
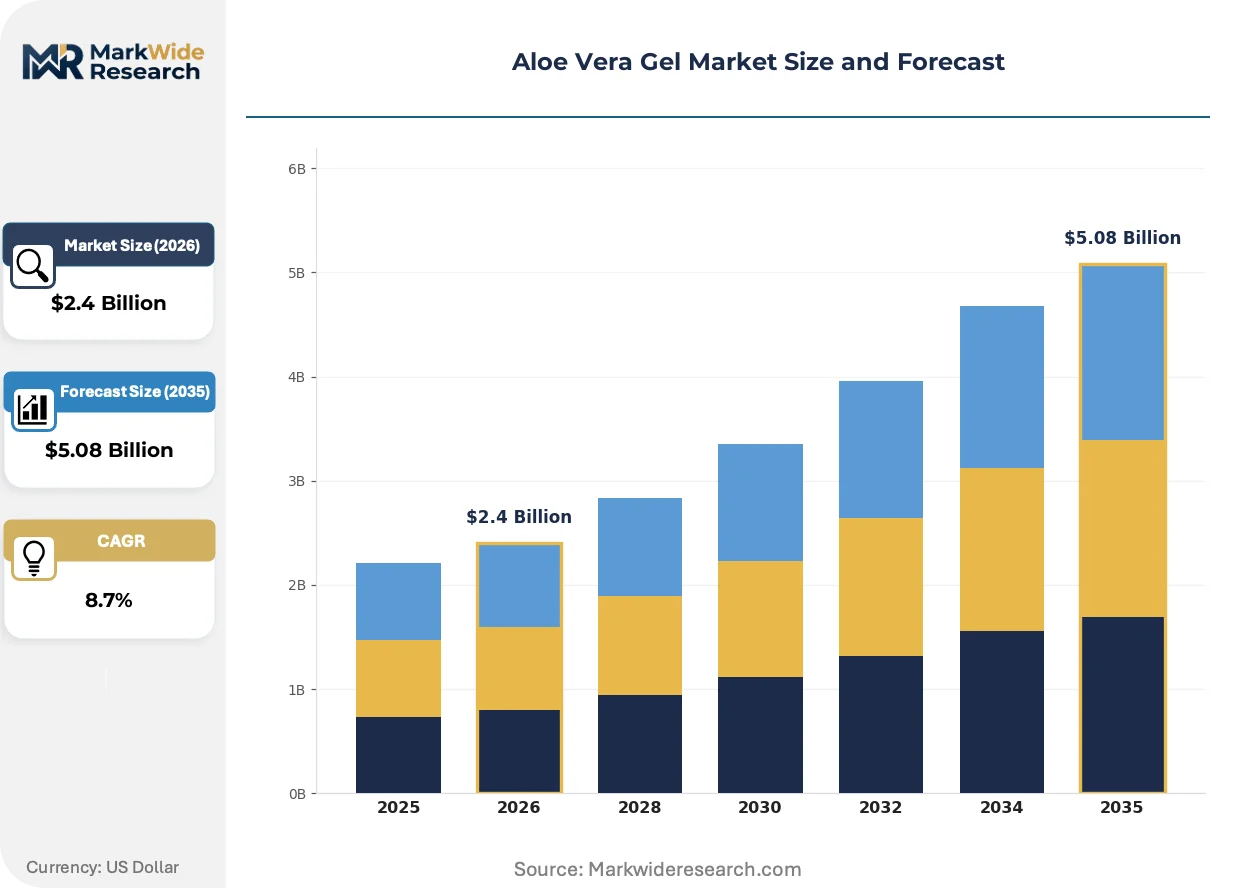
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Gel, Aloe Vera Juices, Aloe Vera Powder, Aloe Vera Creams End User: Healthcare, Cosmetics, Food & Beverages, Pharmaceuticals Formulation: Pure Aloe Vera, Blended Formulations, Concentrates, Ready-to-Use Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Forever Living Products Inc., Lily of the Desert, Aloecorp Inc., Herbalife International Inc., Terry Laboratories Inc., Aloe Laboratories Inc., Aloe Vera of Australia, Patanjali Ayurved, Real Aloe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aloe Vera Gel Market Strategic Shifts & Innovations
Processing technology and regulatory digitization are restructuring competitive advantage around traceability infrastructure rather than commodity volume scale.
Lyophilization technology is decomposing traditional pasteurization's dominance in high-value cosmetic applications. Premium skincare formulators in Germany and France are adopting freeze-dried aloe powder to eliminate preservative load while extending shelf stability. This shift is compressing demand for liquid gel intermediates in European specialty retail channels.
REACH registration requirements for botanical substances are forcing ingredient suppliers to submit full toxicological dossiers for aloe-derived compounds. The industrial consequence is exit pressure on small-scale Indian exporters lacking in-house regulatory affairs capacity. German and Dutch cosmetics manufacturers are responding by consolidating supplier panels around vertically integrated processors with dedicated ECHA compliance teams.
Ingredient transparency platforms are displacing traditional certificate-based trust mechanisms in millennial and Gen-Z purchasing decisions. Clean beauty retailers in California and New York are mandating blockchain-verified farm-to-bottle tracking for shelf placement. This behavioral shift is most visible in direct-to-consumer channels where QR-linked cultivation data now drives repeat purchase rates ahead of price positioning.
Aloe Vera Gel Market Segmentation
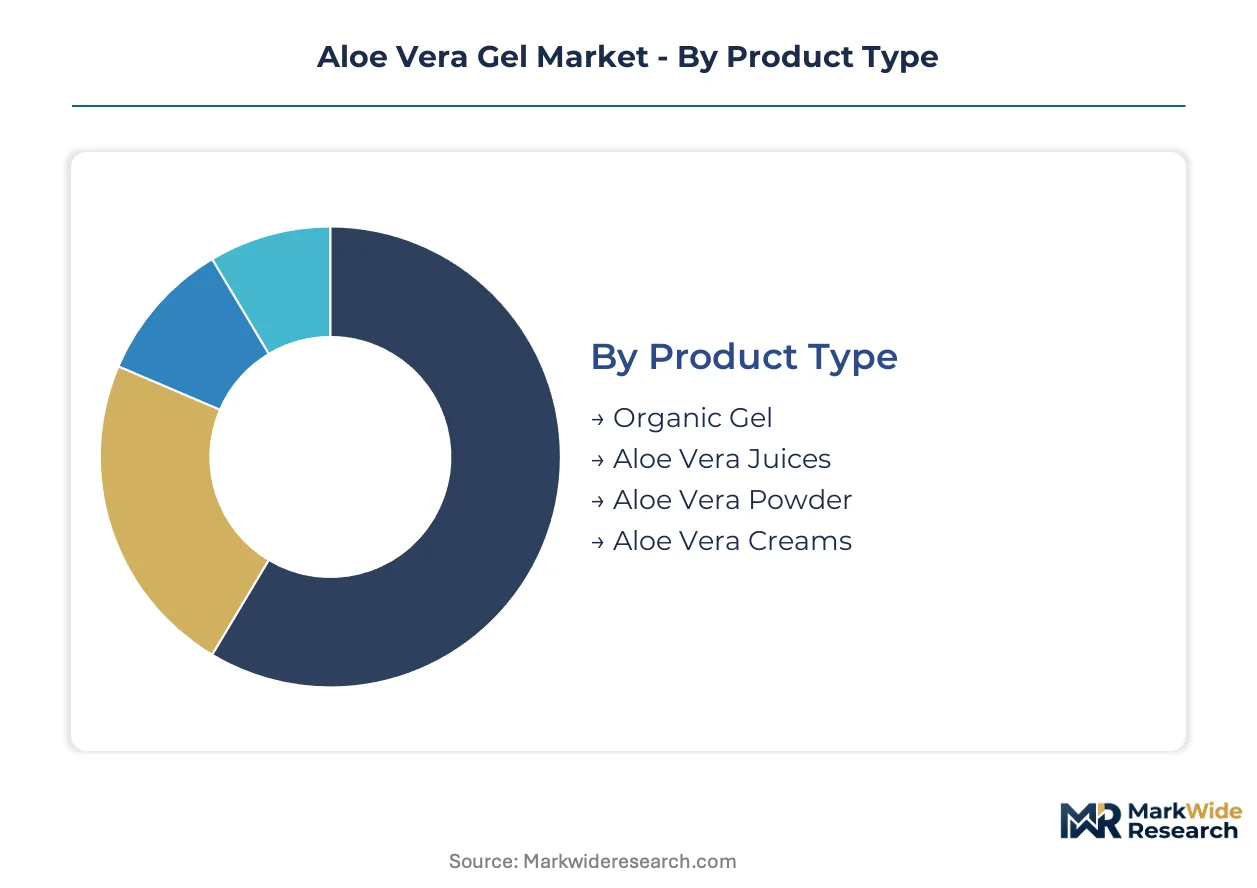
Aloe vera gel's commercial architecture fragments across four distinct taxonomies, each mapping to divergent margin structures and procurement behaviors. Product type stratification separates premium organic certifications from commodity juice concentrates, while distribution channel selection determines whether suppliers capture pharmaceutical-grade margins or mass-market volumes.
Product Type:
Margin pools concentrate in certified organic gel and lyophilized powder formats where acemannan standardization commands pharmaceutical pricing.
- Organic Gel:Cold-pressed extraction preserves polysaccharide chains above 0.5% acemannan content, qualifying for EU Cosmetics Regulation notification and USDA NOP shelf positioning. South Korean K-beauty formulators in Seoul's Gangnam district are consolidating procurement around APEDA-certified Indian suppliers to satisfy clean-label mandates.
- Aloe Vera Juices:Beverage-grade processing accepts heat degradation of bioactive compounds in exchange for volume scale and eighteen-month ambient shelf stability. Maharashtra's FSSAI-registered processors dominate institutional supply to India's Ayurvedic pharmaceutical corridors where therapeutic claims require lower purity thresholds than cosmetic applications.
- Aloe Vera Powder:Lyophilization eliminates preservative load for German and French premium skincare manufacturers adopting freeze-dried intermediates.
- Aloe Vera Creams:Emulsion-based finished goods capture retail margin pools through relationship-based direct sales channels.
The dominant share belongs to Organic Gel, while Aloe Vera Powder is closing the gap fastest.
End User:
Application-driven procurement splits between regulated pharmaceutical channels and discretionary cosmetic spending with divergent compliance burdens.
- Healthcare:Wound-care and burn-treatment applications demand FDA botanical drug substance documentation or CDSCO pharmaceutical excipient registration. Institutional buyers in Maharashtra's hospital networks require cold-chain integrity verification through distribution.
- Cosmetics:K-beauty transparency mandates in South Korea and EU Cosmetics Regulation enforcement are filtering supplier panels toward vertically integrated cultivators with ECHA-compliant toxicological dossiers.
- Food & Beverages:FSSAI and FDA GRAS status governs aloe vera juice incorporation into functional beverages.
- Pharmaceuticals:Acemannan-standardized extracts for oral dosage forms face India's dual-track CDSCO and FSSAI oversight complexity.
Cosmetics commands the largest revenue pool, though Healthcare is expanding most quickly through institutional procurement formalization.
Formulation:
Customer sophistication and use-case specificity determine whether buyers specify raw material purity or accept blended cost engineering.
- Pure Aloe Vera:Unadulterated inner leaf fillet standardized to acemannan content serves German dermatological formulators and Indian Ayurvedic pharmaceutical manufacturers with incompatible purity requirements.
- Blended Formulations:Aloe vera constitutes 15-30% of finished cosmetic matrices where texture modifiers and fragrance load displace bioactive concentration. Mass-market cosmetics in California and New York retail channels prioritize cost engineering over certificate-based provenance.
- Concentrates:Bulk intermediates for downstream dilution reduce logistics expenditure for multinational personal care manufacturers.
- Ready-to-Use:Finished topical gels bypass compounding infrastructure for direct-to-consumer subscription models in Tier-2 Indian cities.
Blended Formulations retains volume leadership, yet Pure Aloe Vera is gaining share fastest through blockchain-verified farm-to-bottle tracking adoption.
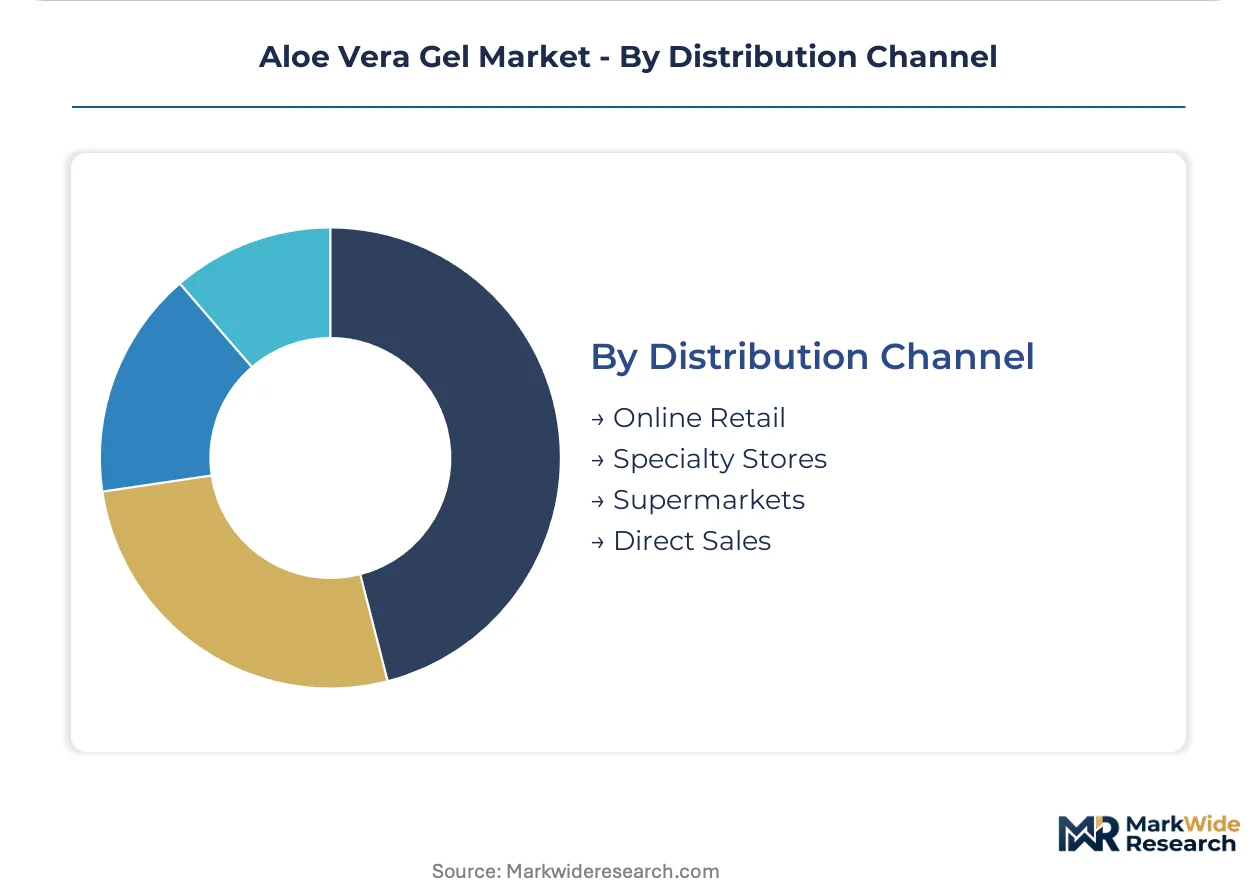
Distribution Channel:
Channel selection stratifies margin capture between high-touch relationship sales and algorithm-driven digital acquisition.
- Online Retail:Millennial and Gen-Z purchasing decisions in California and New York now hinge on QR-linked cultivation data ahead of price positioning. Clean beauty retailers mandate blockchain-verified traceability for shelf placement.
- Specialty Stores:Ayurvedic retail networks in India and organic apothecaries in Germany consolidate demand around certified organic processors with dedicated regulatory affairs capacity.
- Supermarkets:Mass-market juice and cream placement competes on unit economics with limited transparency requirements.
- Direct Sales:Relationship-based recurring purchases through captive distribution occupy the highest margin pool in the channel architecture.
Direct Sales commands premium margin capture, while Online Retail is climbing the fastest through demographic behavioral shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic formulators in South Korea and the United States prioritize acemannan-standardized gel for clean-label procurement, while India's Ayurvedic pharmaceutical corridors consume lower-purity grades for institutional excipient supply. This consumption-mix differential fragments procurement specifications across geographies.
United States
K-beauty transparency mandates and direct-to-consumer subscription models drive demand for blockchain-verified organic gel. The FDA oversees aloe vera as a botanical drug substance under botanical drug development guidance. California's clean beauty retailers in Los Angeles and San Francisco now mandate farm-to-bottle tracking for shelf placement.
South Korea
Seoul's Gangnam district formulators accelerate acemannan-standardized procurement to meet MFDS cosmetic safety mandates. The Korean Ministry of Food and Drug Safety enforces ingredient disclosure requirements through its cosmetics regulatory framework. Busan-Ulsan processing clusters import certified organic gel from Indian suppliers to satisfy K-beauty export specifications.
India
Ayurvedic pharmaceutical corridors in Maharashtra and Gujarat absorb volume for CDSCO-registered excipient applications. India's dual-track CDSCO and FSSAI oversight creates compliance complexity for multi-category suppliers. Andhra Pradesh and Tamil Nadu processing clusters expand cold-pressed capacity under the PLI scheme for herbal extracts.
Germany
Premium skincare manufacturers in Frankfurt and Munich adopt lyophilized aloe powder to eliminate preservative load. ECHA REACH registration requirements force submission of full toxicological dossiers for aloe-derived compounds. Bavaria's cosmetics manufacturers consolidate supplier panels around vertically integrated processors with dedicated regulatory affairs capacity.
Brazil
ANVISA's regulatory pathway for botanical drugs remains underutilized by acemannan-standardized gel suppliers seeking Latin American pharmaceutical channels. The national health surveillance agency's herbal medicine framework offers registration routes for standardized extracts. São Paulo's personal care formulators increasingly specify imported organic gel for premium positioning.
Aloe Vera Gel Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with backward integration into captive plantations separating premium positioning from commodity supply. The competitive structure rewards R&D intensity in polysaccharide stabilization and regulatory compliance capacity across ECHA and FDA frameworks. Two archetypes dominate: vertically integrated cultivators with in-house organic certification, and research-intensive processors specializing in acemannan standardization. Capacity expansion in cold-pressed extraction and strategic partnerships for blockchain traceability infrastructure represent the dominant competitive moves.
Among North American integrated operators, Forever Living Products Inc. and Lily of the Desert occupy positions reflecting distinct strategic archetypes. Forever Living Products Inc. exemplifies the captive supply model through plantation ownership. Lily of the Desert represents the R&D-intensive processor archetype with specialization in bioactive stabilization. Patanjali Ayurved anchors the India-centric Ayurvedic channel through extensive rural sourcing networks. These three entities collectively illustrate how geographic origin and structural positioning determine margin capture across cosmetic, pharmaceutical, and nutraceutical end-uses.
| Leading Market Players |
|---|
| Forever Living Products Inc. |
| Lily of the Desert |
| Aloecorp Inc. |
| Herbalife International Inc. |
| Terry Laboratories Inc. |
| Aloe Laboratories Inc. |
| Aloe Vera of Australia |
| Patanjali Ayurved |
| Real Aloe |
| Others |
Cost & Logistics Intelligence
Lyophilized powder substitution for liquid gel intermediates simultaneously shifts procurement geography toward German and French freeze-dry specialists while compressing margins for Maharashtra's heat-processed bulk suppliers. This displacement dynamic concentrates pricing power with acemannan-standardized processors capable of cold-chain integrity verification.
Pricing Analysis
Long-term offtake contracts anchor pricing stability between Indian cultivators and South Korean K-beauty formulators, while spot purchases dominate European specialty retail channels. Price differentiation hinges on USDA NOP certification tier and volume scale commitments. Cost compression in commodity juice concentrates intensifies as FSSAI-registered Maharashtra processors compete on eighteen-month shelf stability. Mass-market cosmetics buyers exhibit highest price sensitivity, whereas German dermatological formulators prioritize acemannan standardization over unit economics.
Supply Chain Analysis
Monsoon-dependent leaf harvests in Maharashtra and Gujarat constitute the dominant chokepoint for global gel processors serving pharmaceutical and cosmetic channels. Raw material supply draws from certified organic plantations in India, captive cultivation in Texas and Mexico, and emerging acreage in Brazil's northeast. Single-source vulnerability concentrates in Maharashtra's processing clusters where CDSCO-registered excipient output feeds institutional healthcare procurement. Distribution runs through direct sales networks for premium margin capture, supplemented by blockchain-verified online retail for millennial demographic acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among vertically integrated cosmetics formulators in Seoul and Los Angeles, consolidating procurement panels around certified organic suppliers with ECHA-compliant dossiers.
For Market Incumbents: Consolidate backward integration into captive plantation acreage to secure raw material consistency against emerging Brazilian cultivators. Deepen R&D investment in polysaccharide stabilization chemistries to defend premium positioning as lyophilization technology commoditizes. Lock in long-term offtake agreements with Maharashtra's FSSAI-registered processors before India's PLI scheme expands competitor capacity in Andhra Pradesh. For New Entrants and Emerging Players: Lead with blockchain-verified traceability infrastructure targeting California's clean beauty retailers and New York direct-to-consumer subscription channels. Brazil's ANVISA regulatory pathway for botanical drugs offers the most penetrable white-space for acemannan-standardized gel suppliers seeking Latin American pharmaceutical positioning. Pursue white-label partnerships with Tier-2 Indian ayurvedic brands bypassing traditional retail networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier processors lacking in-house ECHA compliance capacity and cold-pressed extraction scale. Long-term viability favors vertically integrated operators with dual USDA NOP and APEDA certification reciprocity. Monitor India's PLI scheme disbursement velocity as the signal indicating when capacity expansion in Tamil Nadu and Andhra Pradesh will pressure Maharashtra's historical supply dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressed Capacity Expansion | Preserves acemannan integrity for EU Cosmetics Regulation compliance in German pharmaceutical channels. |
| Blockchain Traceability Integration | Enables QR-linked farm-to-bottle verification demanded by California clean beauty retailers. |
| Organic Certification Reciprocity | Secures USDA NOP and APEDA alignment to preempt cross-border supply disruptions. |
| Lyophilization Technology Adoption | Eliminates preservative load for French premium skincare manufacturers seeking extended shelf stability. |
| Direct-to-Consumer Channel Buildout | Bypasses traditional ayurvedic retail networks in Tier-2 Indian cities for recurring revenue capture. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with certified organic cultivators, cosmetics formulators, and CDSCO regulatory affairs specialists, alongside secondary validation through FDA botanical drug guidance documents, EU Cosmetics Regulation enforcement records, and FSSAI excipient registration databases. Bottom-up triangulation cross-referenced Maharashtra processing cluster output data with top-down market sizing across product type and end-use segments.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type stratification, geographic regulatory cluster, and channel-specific margin capture. CAGRs were derived from polynomial trend fitting against historical procurement patterns and projected capacity additions under India's PLI scheme. Industry-specific inputs incorporated monsoon variability coefficients for Gujarat and Maharashtra leaf supply, plus MFDS cosmetic safety mandate compliance timelines for South Korean market entry.
Forecasts assume regulatory continuity in FDA botanical drug oversight, EU Cosmetics Regulation enforcement, and India's dual-track CDSCO-FSSAI framework; material policy shifts would require re-modeling. Scenario readiness remains essential as ECHA REACH registration requirements evolve for botanical substances and as K-beauty transparency mandates tighten acemannan disclosure standards. Practitioners should keep alternative scenarios live as certification reciprocity protocols between USDA NOP and APEDA standards develop.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Halal Market
Specialty Foods
Sweet Spreads Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Europe Hummus Market
Specialty Foods
Global Sauerkrauts Market
Specialty Foods
Super Foods Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market
Specialty Foods
Global Cordyceps Militaris Market
Specialty Foods
Edible Mushroom Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Non-GMO Food Products Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
CBD Snacks Market
Specialty Foods
North American Jam, Jelly, and Preserve Market