
 Grape Juice Concentrate for Wine Making Market | 2026-2036
Grape Juice Concentrate for Wine Making Market Size, Share, and Industry Trends Forecast 2026-2036
Grape Juice Concentrate for Wine Making Market Insights
REACH compliance is repositioning the cost-of-entry calculus for European concentrate importers, forcing reformulation of preservative protocols and residue documentation. California Concentrate Company leverages its vertically integrated Central Valley crushing network to sustain year-round supply continuity. Ciatti Company anchors its competitive stance through decades-long brokerage relationships with Napa and Sonoma vintners. Vie-Del differentiates via proprietary flash-pasteurization technology that preserves varietal aromatics through extended storage.
Grape juice concentrate for wine making denotes a reduced-moisture grape must product, typically concentrated to 65–72 degrees Brix through vacuum evaporation, then stabilized for reconstitution into fermentable base wine. The primary industrial purpose centers on providing vintners with vintage-independent raw material that standardizes alcohol potential, color extraction, and acid profiles across production cycles. Red grape concentrate dominates volume flows due to its role in bulk still-wine programs, while organic concentrate commands premium positioning amid tightening EU Green Deal farm-to-fork traceability mandates. Sparkling wine applications represent the fastest-growing demand channel as prosecco-style producers in emerging regions adopt concentrate for base-wine consistency.
The EPA regulates pesticide residue thresholds under the Federal Insecticide, Fungicide, and Rodenticide Act, directly shaping which California-sourced concentrates qualify for domestic winery contracts. EFSA's evolving maximum residue level revisions for oenological processing aids determine European import eligibility, while the USDA National Organic Program certifies concentrate streams destined for premium label claims. Stakeholders must monitor how California's State Water Resources Control Board irrigation restrictions interact with concentrate processor water-use permits to assess future supply reliability.
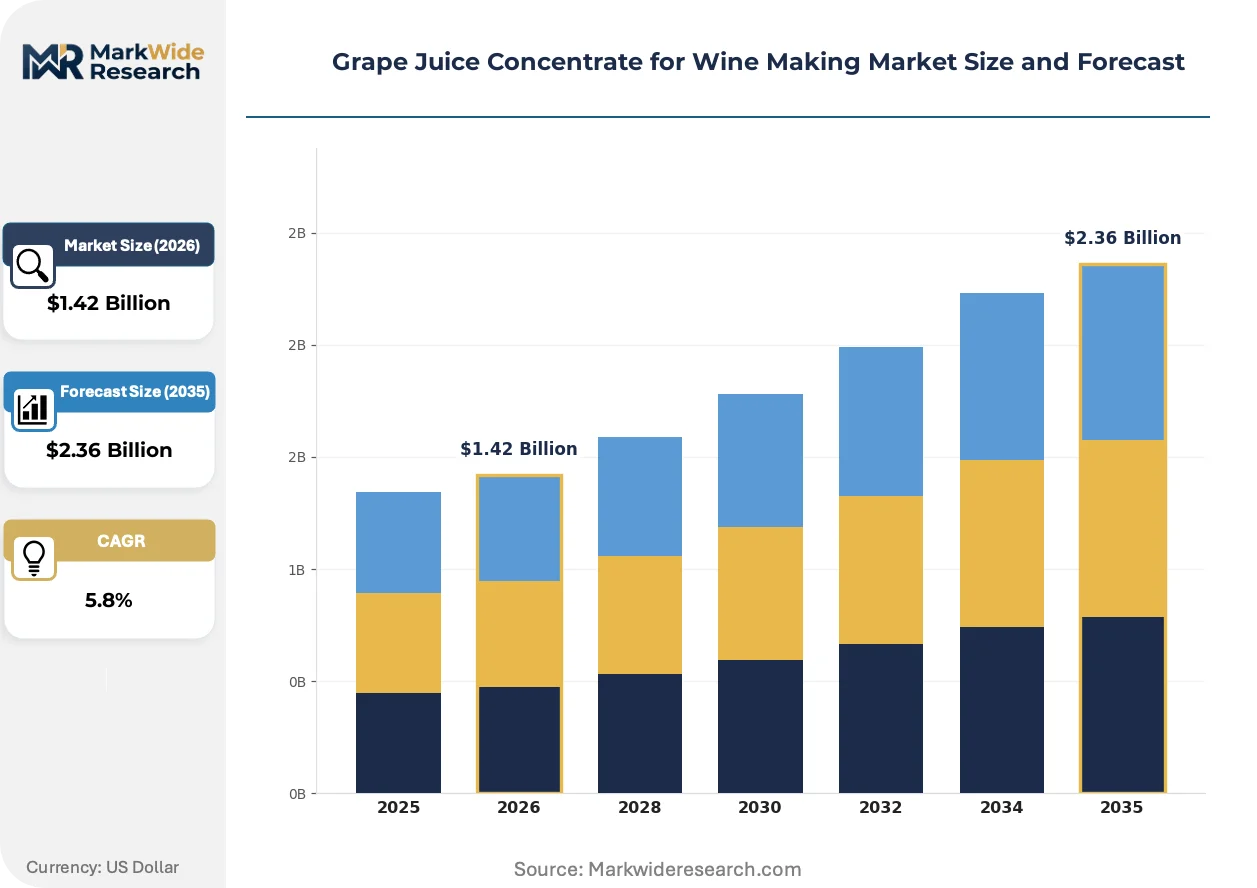
Market Dynamics
Processor-winery integration across California's Central Valley is compressing spot-market liquidity and locking in multi-year supply contracts that reshape price discovery mechanisms for grape juice concentrate.
Growth Catalysts
- EU Green Deal traceability mandates:Farm-to-fork documentation requirements for organic certification are pulling premium concentrate volumes into compliant supply chains, rewarding early-adopter processors with price premiums.
- Prosecco-style base-wine programs:Sparkling wine producers in emerging wine regions are adopting concentrate to standardize alcohol potential and acid profiles across inconsistent vintage conditions.
- Pacific Northwest contract purchasing:Boutique wineries in Oregon and Washington are expanding forward commitments to concentrate suppliers as insurance against frost and heat-spike vintage variability.
Market Restraints
- REACH compliance costs:European importers face reformulation expenses for preservative protocols and residue documentation that elevate cost-of-entry for non-integrated traders.
- California water permit uncertainty:State Water Resources Control Board irrigation restrictions threaten processor operating licenses and concentrate supply reliability in the dominant production cluster.
- Fresh grape must substitution:Large bulk-wine programs in Argentina and Chile can bypass concentrate entirely when fresh fruit pricing collapses in oversupply vintages.
Strategic Opportunities
- Flash-pasteurization aroma preservation:Proprietary thermal processing technologies that maintain varietal character through extended storage open premium private-label channels for mid-tier processors.
- India wine market liberalization:State-level excise reforms in Maharashtra and Karnataka are creating first-mover advantage for concentrate exporters targeting nascent domestic sparkling production.
- Brokerage relationship digitization:Napa and Sonoma vintner networks are migrating from decades-long personal contracts to platform-enabled spot purchasing, creating entry points for new concentrate suppliers.
Industry Challenges
- EFSA MRL revision timelines:European Food Safety Authority's evolving maximum residue level standards for oenological processing aids create certification lag that blocks inventory release.
- Vacuum evaporation capex cycles:Energy-intensive concentration equipment requires 7-10 year replacement horizons that strain processor balance sheets amid interest rate volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grape Juice Concentrate for Wine Making Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Grape Juice, White Grape Juice, Organic Concentrate, Conventional Concentrate End User: Wineries, Home Brewers, Beverage Manufacturers, Food Producers Application: Sparkling Wine, Still Wine, Fortified Wine, Low Alcohol Wine Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | California Concentrate Company, Ciatti Company, Prospero Winery, Vie-Del, Golden Valley Grape Juice & Wine, Walkers Wine Juice, Coloma Frozen Foods, Canandaigua Concentrate, Michigan Grape Juice Concentrates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grape Juice Concentrate for Wine Making Market Trends and Innovations
Flash-pasteurization and vacuum evaporation advances are redefining quality benchmarks while regulatory documentation requirements and procurement digitization reshape commercial relationships across the value chain.
Proprietary low-temperature flash-pasteurization systems are electrifying concentrate quality differentiation by preserving volatile thiol and terpene compounds that conventional thermal processing destroys. Premium sparkling wine producers in Italy's Prosecco corridor are specifying these systems in supplier qualification audits. The technology is electrifying a two-tier equipment market that separates aroma-capable processors from commodity bulk suppliers.
REACH Article 33 extended supply chain disclosure obligations are forcing European importers to map preservative inputs back to California vineyard blocks. This documentation burden is compressing the viable supplier base to vertically integrated processors with captive laboratory capabilities. Organic concentrate streams face the steepest compliance ramps as ECHA scrutinizes copper sulfate and sulfur residue carryover from vineyard to finished product.
Boutique wineries are fragmenting procurement into smaller, more frequent concentrate purchases that mirror their harvest-timing flexibility rather than locking annual volumes. This pattern is displacing the traditional three-year supply agreements that anchored processor revenue planning. The shift is most visible in Oregon's Willamette Valley, where Pinot Noir concentrate buyers now tender quarterly mini-contracts indexed to futures pricing.
Grape Juice Concentrate for Wine Making Market Segmentation
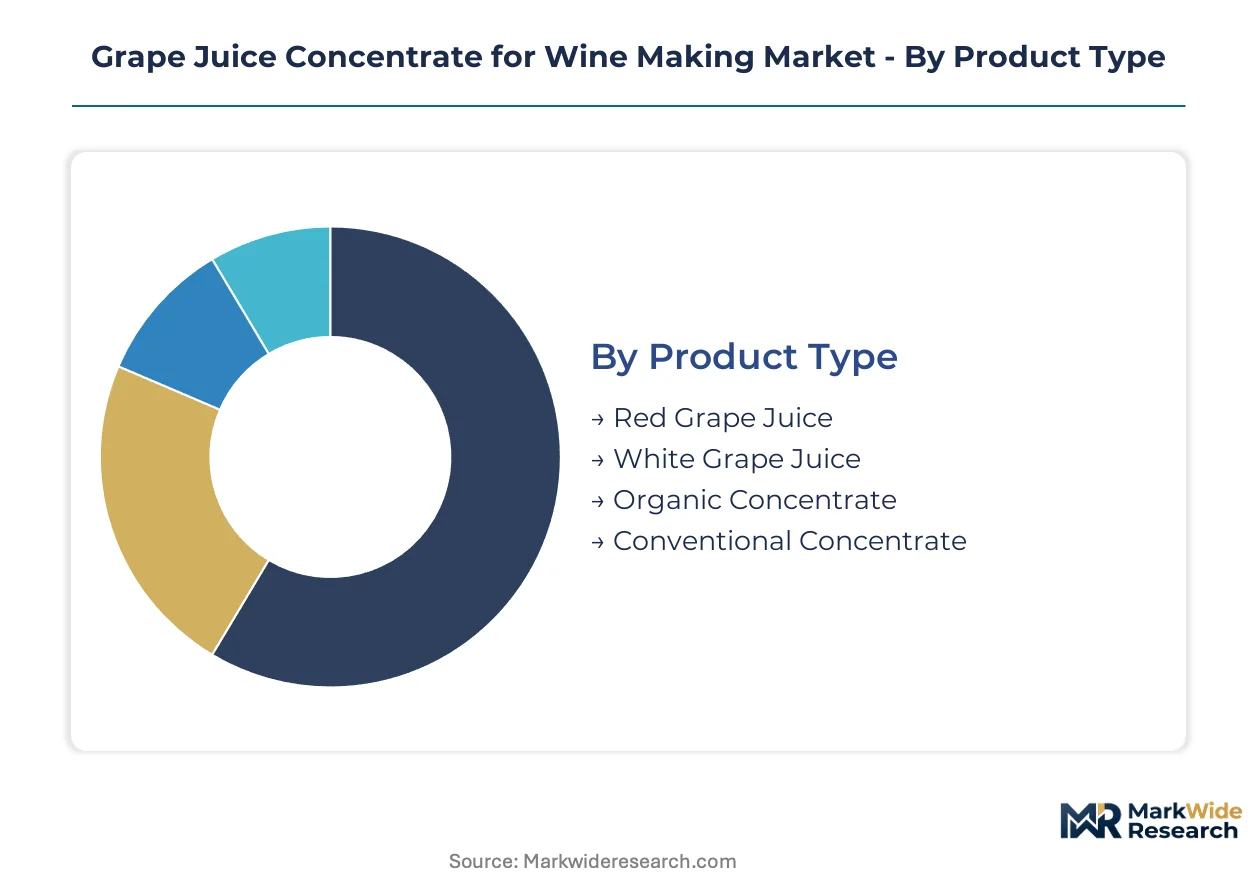
Concentrate specifications dictate fermentation outcomes, shelf stability, and regulatory compliance pathways. Winemakers segment procurement by color chemistry, organic certification, and intended wine style to match concentrate properties with finished product positioning.
Product Type:
Vacuum evaporation parameters and Brix targets vary sharply across color and certification lines, determining processor equipment configuration and margin structure.
- Red Grape Juice:Anthocyanin-rich concentrate from crushed skins delivers color extraction and tannin precursors essential for bulk still-wine programs. California's Central Valley processors dominate volume flows to domestic wineries seeking vintage-independent alcohol standardization.
- White Grape Juice:Lower phenolic load and higher natural acidity suit base-wine programs where clarity and aromatic neutrality take priority. Pacific Northwest wineries specify white concentrate for Riesling and Pinot Gris blending buffers against frost-damaged harvests.
- Organic Concentrate:NOP-certified streams command premium positioning through restricted copper sulfate and sulfur residue thresholds. EU Green Deal traceability mandates are pulling compliant volumes into dedicated supply chains with farm-to-fork documentation.
- Conventional Concentrate:Standard pesticide tolerance and conventional vineyard management enable cost-efficient bulk supply to high-volume still-wine producers.
Red Grape Juice leads on scale; Organic Concentrate leads on momentum.
End User:
Procurement sophistication and volume scale separate commercial wine operations from artisanal and adjacent-industry buyers.
- Wineries:Professional vintners negotiate multi-year contracts with Brix specifications, acid adjustment protocols, and lot traceability requirements. Processor-winery integration across California compresses spot-market liquidity for this buyer class.
- Beverage Manufacturers:Hard seltzer and ready-to-drink wine cocktail producers source concentrate for alcohol base standardization and flavor consistency across production batches.
- Home Brewers:Small-package retail concentrate purchases through online channels and specialty suppliers serve amateur winemaking hobbyists with limited storage infrastructure.
- Food Producers:Vinegar manufacturers and culinary grape derivatives processors utilize concentrate for non-beverage fermentation applications with lower aromatic complexity requirements.
Wineries anchor volume commitment; Beverage Manufacturers are climbing the fastest.
Application:
Fermentation kinetics and finished alcohol targets dictate concentrate selection by wine style category.
- Sparkling Wine:Base-wine programs for prosecco-style production demand precise acid retention and neutral aromatic profiles. Flash-pasteurization technology preserves varietal thiols through extended storage, enabling emerging-region producers to standardize second fermentation inputs.
- Still Wine:Bulk red and white wine production consumes the largest concentrate volumes for alcohol potential adjustment and color correction across inconsistent vintages.
- Fortified Wine:Higher Brix concentrates support port-style and dessert wine programs where residual sugar and elevated alcohol targets require specific must gravity.
- Low Alcohol Wine:Partial fermentation of reconstituted concentrate allows precise alcohol level targeting for dealcoholized and reduced-alcohol wine categories.
Still Wine dominates throughput; Sparkling Wine shows steepest expansion trajectory.
Distribution Channel:
Supply chain configuration determines lot size flexibility, documentation depth, and price discovery mechanisms.
- Wholesale:Broker-mediated bulk concentrate movements through established merchant networks like Ciatti Company connect California processors with Napa and Sonoma vintners on contract terms.
- Direct Sales:Vertically integrated Central Valley processors sell captive production directly to winery clients, eliminating margin extraction by intermediaries.
- Online Retail:E-commerce platforms serve home brewers and small wineries with packaged concentrate in sub-ton quantities, requiring flash-pasteurization for extended shelf stability.
- Specialty Stores:Regional wine supply retailers stock concentrate for local amateur and semi-professional winemakers with immediate pickup needs.
Wholesale channels capture value-chain margin; Direct Sales tightens supply security fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Viticulture expertise clusters in California's Central Valley anchor global concentrate production capacity, while European regulatory pressure and Pacific Northwest vintage volatility reshape demand geography.
United States
California's Central Valley processors dominate global supply through backward integration into crushing networks, with Fresno and Madera counties hosting the densest concentration of vacuum evaporation capacity. EPA enforcement of Federal Insecticide, Fungicide, and Rodenticide Act residue thresholds determines which concentrates qualify for domestic winery contracts. Oregon's Willamette Valley and Washington's Walla Walla AVA are expanding contract purchasing as frost insurance.
Italy
Prosecco-style base-wine programs in Veneto and Friuli-Venezia Giulia are accelerating concentrate adoption for second fermentation standardization. EU Green Deal farm-to-fork traceability mandates pull premium organic volumes into compliant supply chains with EFSA maximum residue level scrutiny. Conegliano-Valdobbiadene processors are specifying flash-pasteurization systems in supplier qualification audits.
Argentina
Mendoza-based bulk wine programs can substitute fresh grape must for concentrate when oversupply vintages collapse fruit pricing. The national agricultural regulator enforces vineyard input documentation that shapes export eligibility to European markets. San Juan province is emerging as a secondary concentrate processing cluster with lower labor costs.
Australia
Riverina district processors in New South Wales supply concentrate for domestic sparkling wine programs seeking vintage consistency. The country's national food standards regulator administers residue thresholds that determine export market access. Barossa Valley wineries are testing smaller-batch concentrate purchases for premium red wine blending.
India
Maharashtra and Karnataka state-level excise reforms are creating first-mover opportunities for concentrate exporters targeting nascent domestic sparkling production. The Food Safety and Standards Authority of India is developing wine-specific processing aid standards that will shape import eligibility. Nashik district wineries are piloting concentrate-based base-wine programs for price-controlled retail segments.
Grape Juice Concentrate for Wine Making Market Competitive Landscape
The competitive structure tilts toward vertically integrated processors with captive vineyard networks and laboratory documentation capabilities. Broker-mediated merchant houses and specialty technology licensors occupy distinct strategic tiers. Consolidation pressure concentrates among Central Valley processors with water permit security, while REACH compliance costs squeeze non-integrated European traders. Dominant competitive moves include backward integration into crushing assets and proprietary thermal processing technology licensing.
Among California-based integrated processors, California Concentrate Company and Vie-Del exemplify the vertically integrated archetype with captive Central Valley supply networks. Ciatti Company represents the brokerage-dependent merchant house model anchored in Napa and Sonoma vintner relationships. These three entities occupy positions across the structure spectrum, from direct sales capacity to relationship-mediated wholesale channels.
| Leading Market Players |
|---|
| California Concentrate Company |
| Ciatti Company |
| Prospero Winery |
| Vie-Del |
| Golden Valley Grape Juice & Wine |
| Walkers Wine Juice |
| Coloma Frozen Foods |
| Canandaigua Concentrate |
| Michigan Grape Juice Concentrates |
| Others |
Pricing and Supply Chain Analysis
Family-owned Central Valley processors with multi-generational vineyard holdings anchor supply discipline through captive crushing capacity and long-dated winery contracts that buffer spot-market volatility. Their ownership structure limits quarterly earnings pressure, enabling patient pricing that reflects vintage risk rather than commodity cycles. This stability contrasts with broker-dependent merchants facing margin compression from documentation compliance costs.
Pricing Analysis
Packaged concentrate for home brewers and small wineries carries unbundled per-unit pricing, while bulk tanker deliveries to integrated processors bundle logistics, acid adjustment, and lot traceability into contract rates. Three-tier pricing structure across premium organic, standard commercial, and economy bulk levels separates NOP-certified streams with EFSA-compliant documentation from conventional pesticide-tolerant supply. Pricing pressure stems from REACH Article 33 disclosure obligations elevating laboratory certification costs for European-bound shipments. Beverage manufacturers sourcing alcohol bases for hard seltzers exhibit highest price sensitivity, while Napa and Sonoma vintners negotiating multi-year contracts prioritize supply security over unit cost.
Supply Chain Analysis
Crushing capacity rests on California's Central Valley, with secondary processing clusters in Argentina's Mendoza and Australia's Riverina providing seasonal surplus absorption. Vacuum evaporation equipment, stainless steel tanker fleets, and flash-pasteurization systems constitute critical capital inputs with 7-10 year replacement cycles. Single-source vulnerability concentrates in Fresno and Madera county water permits, where State Water Resources Control Board restrictions threaten processor operating licenses. Distribution runs through broker-mediated wholesale channels for boutique winery clients and direct sales pipelines for vertically integrated processors serving high-volume still-wine programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as global wine consumption tilts toward sparkling and lower-alcohol formats that standardize through concentrate base wines. Vintage variability insurance maintains contract renewal rates above discretionary input categories.
For Market Incumbents: Hedge frost and heat-spike exposure by expanding forward purchase agreements with Pacific Northwest boutique wineries seeking supply security. Secure water permit renewals through irrigation efficiency investments before State Water Resources Control Board restrictions tighten. Deepen backward integration into organic vineyard blocks to capture EU Green Deal premium pricing and reduce third-party certification dependency. For New Entrants and Emerging Players: Flash-pasteurization technology licensors represent the most penetrable entry channel, as mid-tier processors seek aroma-preservation capabilities without proprietary R&D investment. Target Maharashtra and Karnataka state-level excise reforms in India for first-mover positioning in nascent domestic sparkling production. Pursue platform-enabled spot purchasing relationships with Oregon Willamette Valley Pinot Noir concentrate buyers fragmenting from three-year contracts toward quarterly mini-contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated brokerage-dependent merchants facing REACH compliance cost inflation without captive laboratory capabilities. Five-to-ten year viability favors processors with water permit security and backward integration into crushing networks. Watch EFSA maximum residue level revision timelines as inflection signals that could block inventory release and compress trader margins abruptly.| Strategic Initiative | Industry Significance |
|---|---|
| Flash-Pasteurization Technology Licensing | Proprietary thermal systems preserve varietal thiols for Prosecco-style producers in Veneto. |
| Backward Integration into Organic Vineyards | Captive NOP-certified supply secures EU Green Deal farm-to-fork traceability premium positioning. |
| Water Permit Security Investment | Irrigation efficiency upgrades defend Fresno and Madera county processor operating licenses. |
| Platform-Enabled Spot Purchasing | Digital procurement channels displace decades-long personal contracts with Napa and Sonoma vintners. |
| India Market Entry Partnership | Maharashtra excise reforms create concentrate demand from Nashik district sparkling wine pilots. |
Research Methodology
Coverage spans the United States, Italy, Argentina, Australia, and India, with primary inputs from each regional cluster combining processor interviews, winery procurement director discussions, and regulatory affairs consultations with secondary validation. Crush facility managers, bulk wine brokers, organic certification auditors, and sparkling wine production heads provided operational data. Trade flow databases, EPA pesticide residue filings, EFSA maximum residue level registers, and state water board permit records supplied quantitative anchors. Bottom-up volume builds from processor capacity and top-down demand estimates from winery consumption patterns were triangulated for convergence.
Segmentation granularity modeled product type at the color-certification intersection, end user by commercial sophistication tier, application through fermentation kinetics requirements, and distribution channel by lot size and documentation depth. CAGRs were derived from vintage-adjusted demand elasticity and regulatory compliance cost trajectories across the projection horizon. Forecast inputs incorporated Pacific Northwest frost frequency patterns, EU Green Deal implementation phase-ins, and India state-level excise reform schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to California water permit adjudication and EFSA processing aid standard revisions. Projections reflect documented assumptions about processor-winery integration continuity and sparkling wine format adoption curves. A small set of named triggers—State Water Resources Control Board restriction severity, REACH Article 33 enforcement intensity, and India FSSAI wine-specific standard promulgation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
NFC JUICE Market
Beverages
Bubble Food and Beverages Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
CBD-Infused Beverages Market
Beverages
Sarsaparilla Market
Beverages
Nitro-Infused Cola Market
Beverages
Fusion Beverages Market
Beverages
Packaged Natural Mineral Water Market
Beverages
Caffeine-Based Drinks Market
Beverages
Double Valve Moka Pots Market
Beverages
Semillon Market
Beverages
Sports Drink Market
Beverages
Maple Water Market
Beverages
GCC Bottled Water Market
Beverages
Root Beer Market