
 Soy Sauce Powder Market | 2026-2036
Soy Sauce Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Sauce Powder Market Analytics
A capital-intensity divergence between spray-drying facility operators and blending-focused packagers is redrawing competitive boundaries in soy sauce powder. Kikkoman Corporation leverages captive fermentation infrastructure to control raw liquid soy sauce feedstock quality. Foshan Haitian Flavouring & Food Co., Ltd. anchors its position through massive domestic distribution depth across China's provincial wholesale networks. Sensient Technologies Corporation differentiates via flavor-encapsulation technology that extends shelf stability in high-humidity climates.
Soy sauce powder is a dehydrated derivative of liquid soy sauce, typically manufactured through spray-drying or drum-drying of fermented soybean and wheat substrates to achieve moisture levels below five percent, yielding a shelf-stable umami concentrate for seasoning applications. The primary commercial purpose centers on delivering standardized salt and amino-acid profiles to food manufacturers requiring precise formulation control without liquid handling logistics. Instant and granulated product types command the dominant volume positions, reflecting their integration into industrial-scale seasoning blends for instant noodles and snack coatings. Organic variants are expanding fastest within premium retail channels, though margin pools remain deeper in bulk-format granulated sales to food service distributors.
China's SAMR enforces GB standards for fermented condiment labeling and additive limits, while the FDA governs GRAS status and allergen declarations for soy-derived ingredients in the United States. These frameworks elevate compliance costs for cross-border suppliers but simultaneously filter out substandard entrants, tightening effective supply bases. Stakeholders must monitor divergence between clean-label certification requirements in Western markets and cost-optimized formulation preferences across Asia-Pacific processing hubs.
Market Dynamics
Spray-drying capacity concentration among Southeast Asian toll manufacturers is squeezing margin pools for Western blenders who lack captive fermentation infrastructure. This supply asymmetry forces packaging specialists to absorb input cost volatility while ceding formulation control to integrated Asian producers.
Growth Catalysts
- GB Standards Harmonization:China's SAMR enforcement of unified fermented condiment labeling is consolidating supplier bases and elevating quality thresholds for export-oriented manufacturers.
- Instant Noodle Industrialization:Indonesia's corridor-scale seasoning operations are standardizing granulated umami inputs to achieve batch-to-batch consistency at million-tonne production scales.
- Clean-Label Certification:North American retail channels are mandating additive-disclosure protocols that favor spray-dried powders over liquid alternatives with preservative stabilizers.
Market Restraints
- Fermented Feedstock Volatility:Soybean and wheat substrate costs fluctuate with Black Sea grain flows, compressing margin predictability for non-integrated processors.
- Spray-Dryer Concentration:Toll capacity clusters in Vietnam and Thailand create single-source vulnerability for European and North American seasoning houses.
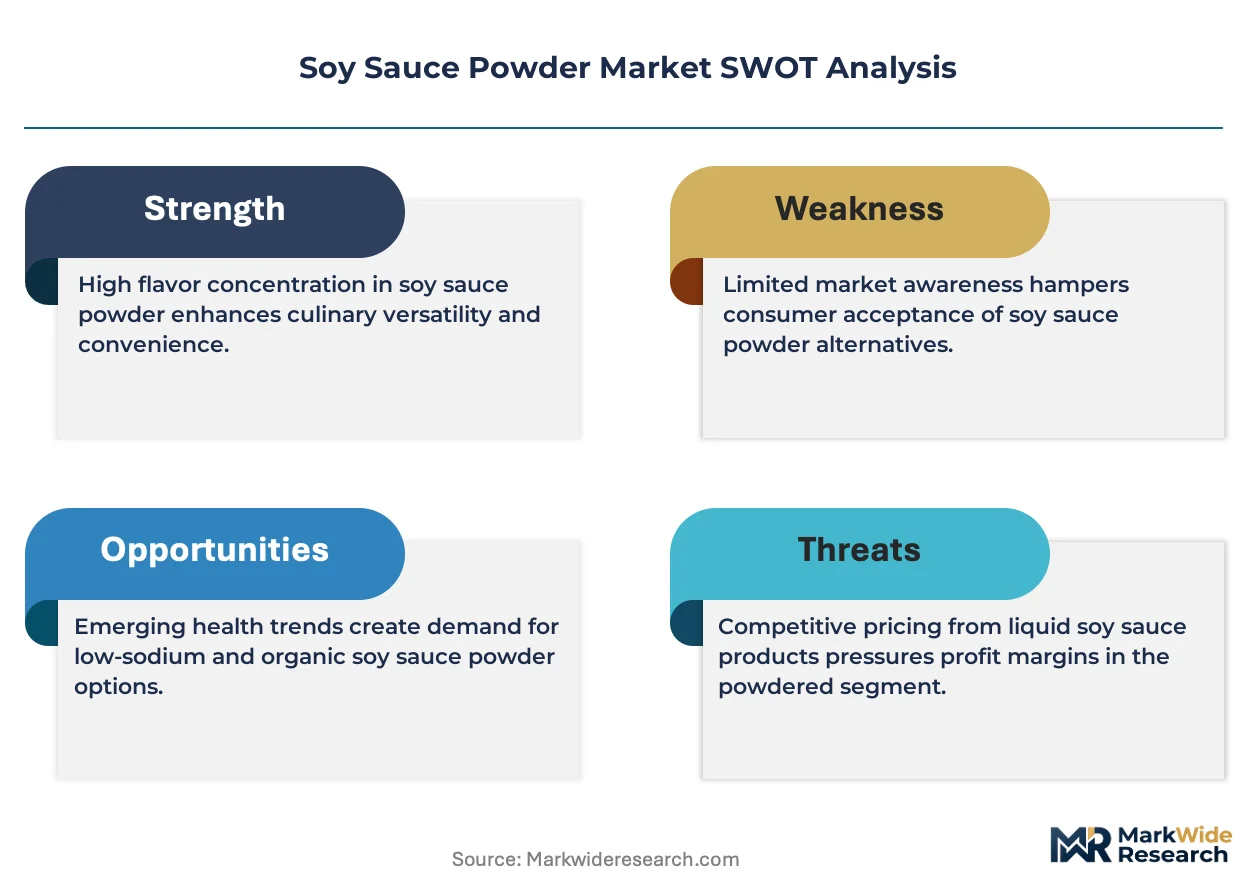
- Flavor Encapsulation Limits:Current microencapsulation technologies degrade above 60% relative humidity, restricting distribution into tropical retail without cold-chain intermediation.
Strategic Opportunities
- Vietnam Condiment Sector Expansion:Domestic sauce manufacturers are upgrading from liquid to powder inputs to supply ASEAN food service distributors.
- Organic Retail Penetration:Premium supermarket channels in Western Europe are creating shelf space for certified-organic variants with traceable fermentation provenance.
- E-Commerce Ingredient Sourcing:Direct-procurement platforms are disintermediating traditional spice importers for mid-scale North American craft food producers.
Industry Challenges
- Spray-Drying Engineering Talent:Operating complex nozzle-atomization systems requires specialized training scarce outside established Asian processing hubs.
- Dual Certification Timelines:Simultaneous organic and halal audits extend product launch cycles by eight to fourteen months for export-focused suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Sauce Powder Market |
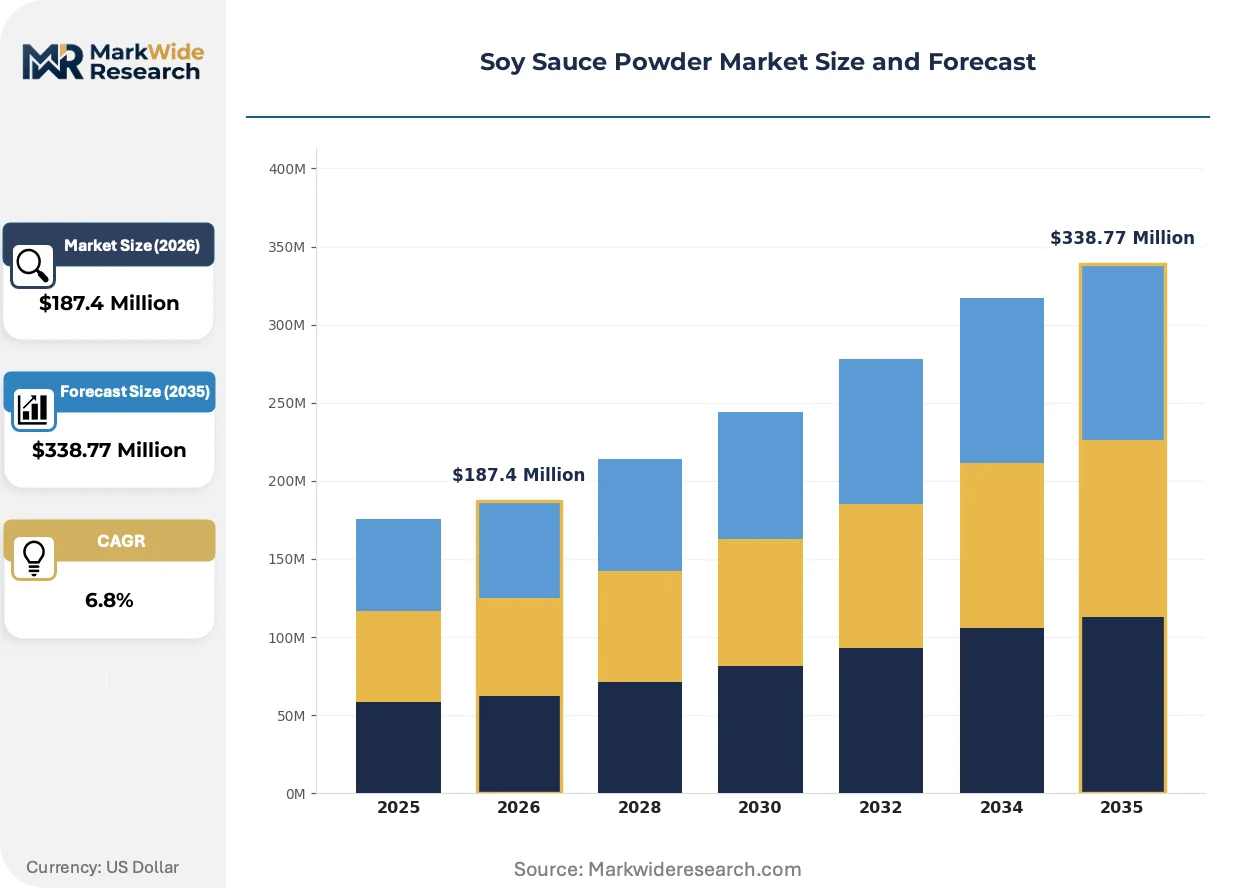
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant, Granulated, Flavored, Organic End User: Food Service, Retail, Food Processing, Catering Packaging Type: Bulk, Sachets, Jars, Pouches Distribution Channel: Online, Offline, Wholesalers, Distributors |
| Companies Covered | Lee Kum Kee Group, Nestlé S.A., Kikkoman Corporation, Kerry Group, Sempio Corporation, Yamasa Corporation, Ajinomoto Co., Inc., Sensient Technologies Corporation, Foshan Haitian Flavouring & Food Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Sauce Powder Market Evolving Landscape
Dehydration technology and regulatory disclosure requirements are fragmenting competitive advantage along capability lines. Process control and certification speed now separate margin leaders from commodity packagers.
Flavor-encapsulation systems using modified starch and gum arabic matrices are bifurcating shelf-stability performance between premium and standard powder grades. High-humidity market entrants in Southeast Asia are adopting these systems aggressively. The technology is compressing acceptable moisture thresholds from 5% to 3% for tropical distribution.
REACH chemical registration requirements in Europe are tightening contaminant limits for 3-MCPD and related process contaminants in hydrolyzed vegetable proteins. Manufacturers must revalidate thermal processing parameters. Powder exporters to Germany and France are investing in HACCP documentation systems to maintain market access.
Direct bulk purchasing by instant-noodle conglomerates is displacing layered distributor networks in Indonesia and Vietnam. Procurement teams now negotiate annual volume contracts with spray-drying operators directly. This concentration is visible most acutely in Java's industrial corridors where seasoning procurement has consolidated among three major buyers.
Soy Sauce Powder Market Segmentation
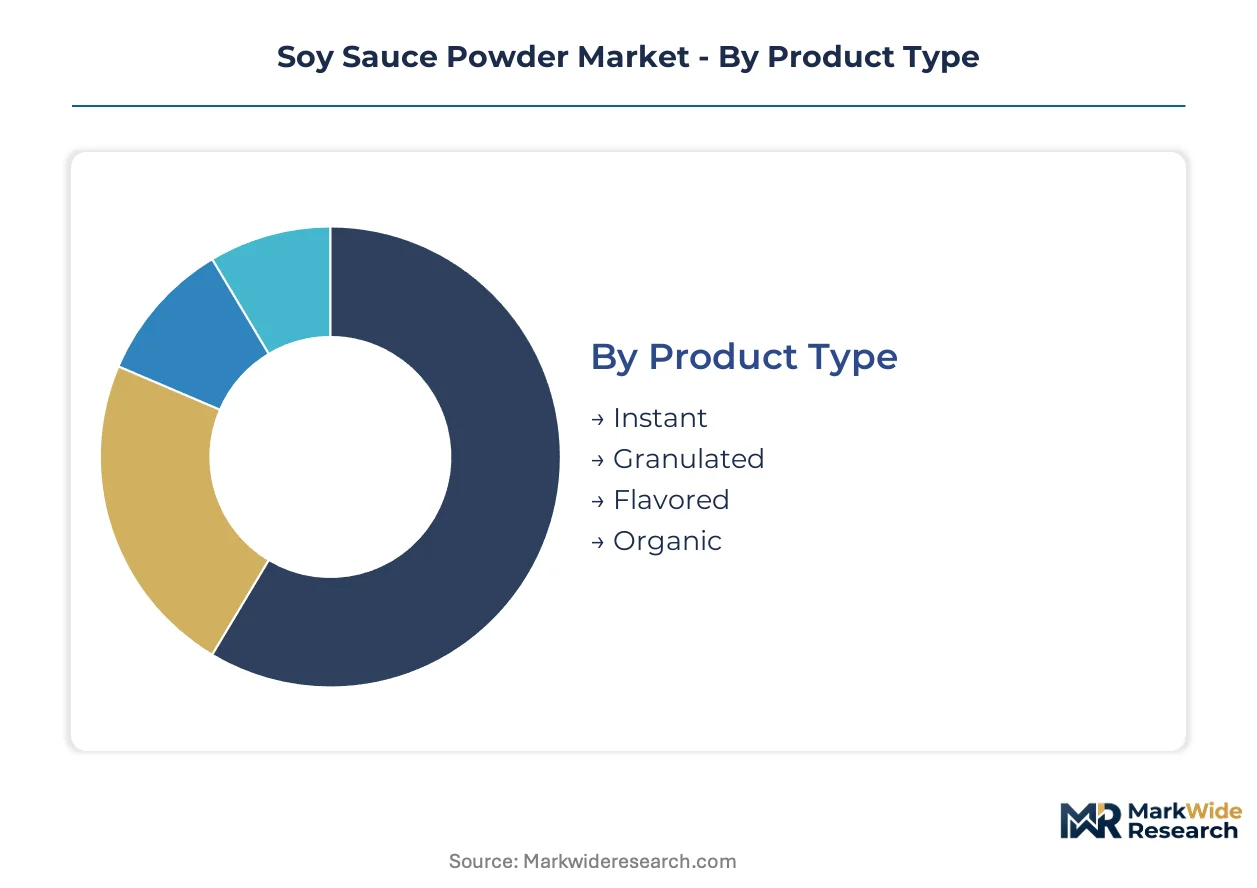
Soy sauce powder segmentation tracks diverging supply chain requirements between industrial-scale food manufacturers and precision-oriented retail channels. Regulatory frameworks governing additive disclosure and fermentation provenance create non-overlapping compliance zones that reshape segment prioritization across geographies.
Product Type:
GB standards for fermented condiment labeling in China and clean-label mandates from the FDA in the United States impose divergent formulation specifications across powder grades.
- Instant:Fine-grain spray-dried powder dissolves rapidly in hot water, achieving sub-5% moisture content through nozzle-atomization systems. Indonesia's instant-noodle manufacturing corridors in Java and North Sumatra standardize this grade for million-tonne seasoning operations requiring batch-to-batch amino-acid consistency.
- Granulated:Agglomerated particles resist caking in high-humidity climates through modified starch binding. Vietnam's condiment sector expansion drives procurement of this format for ASEAN food service distributors navigating tropical distribution without cold-chain infrastructure.
- Flavored:Encapsulated variants incorporate mushroom or seafood extracts for specialized umami profiles; moisture thresholds compress to 3% for tropical retail penetration.
- Organic:Certified-fermentation provenance commands premium shelf space in Western European supermarkets; dual organic-halal audits extend launch timelines by eight to fourteen months.
Established volume favors Instant; emerging adoption favors Organic.
End User:
Cost tier differentiation separates commodity-scale procurement from certification-intensive retail channels.
- Food Processing:Industrial seasoning blenders in Indonesia and Vietnam negotiate annual volume contracts directly with spray-drying operators, displacing layered distributor networks. Precise salt and amino-acid profile control drives specification without liquid handling logistics.
- Food Service:ASEAN distributors source granulated formats for restaurant chain consistency across humid climates; flavor-encapsulation technology extends shelf stability above standard grades.
- Retail:Clean-label certification mandates from the FDA favor spray-dried powders over liquid alternatives with preservative stabilizers; additive-disclosure protocols tighten shelf placement requirements.
- Catering:Bulk procurement concentrates in institutional feeding operations across Southeast Asian urban corridors; cost-optimized formulation preferences dominate over certification requirements.
Margin depth concentrates in Food Processing; certification complexity peaks in Retail.
Packaging Type:
Supply concentration in Southeast Asian toll manufacturing reshapes format economics for export-oriented buyers.
- Bulk:25-kilogram industrial sacks serve instant-noodle conglomerates in Java's industrial corridors; procurement teams negotiate direct with spray-dryer operators to bypass importer markups.
- Sachets:Single-serve portions align with Southeast Asian street-food vendor economics; humidity-resistant laminate structures command premium unit pricing.
- Jars:Retail-facing containers dominate Western European premium supermarket placement; resealability requirements elevate packaging specifications above food service grades.
- Pouches:Flexible formats reduce freight cube for inter-ASEAN distribution; stand-up designs gain share in Vietnam's expanding condiment retail sector.
Volume gravity centers on Bulk; format innovation concentrates in Pouches.
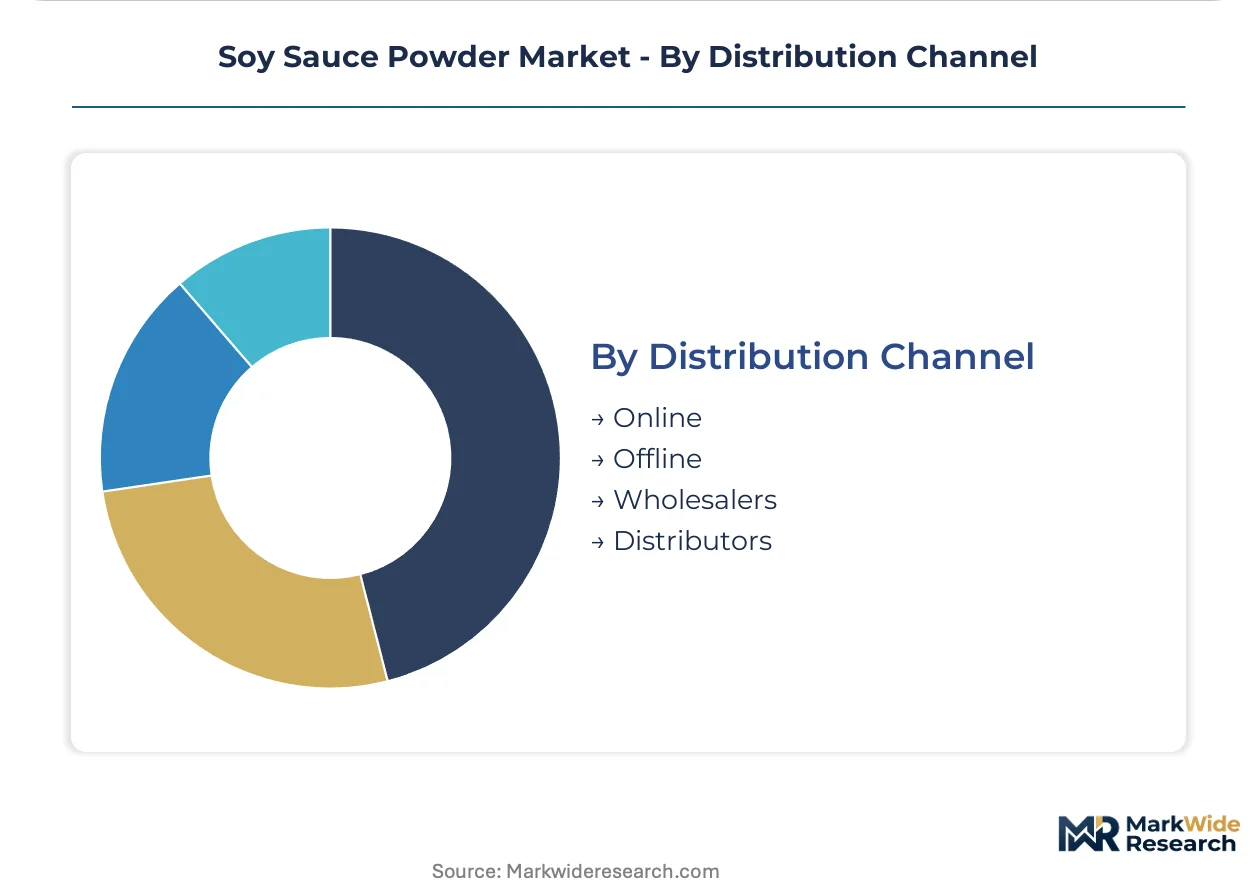
Distribution Channel:
Customer type fragmentation separates direct-procurement platforms from traditional spice importer networks.
- Online:E-commerce ingredient sourcing disintermediates established importers for mid-scale North American craft food producers; REACH documentation requirements filter European market entrants.
- Offline:Provincial wholesale networks across China anchor Foshan Haitian's domestic distribution depth; physical inventory inspection remains preferred for bulk fermentation quality verification.
- Wholesalers:Traditional layered networks face compression as instant-noodle manufacturers consolidate procurement; remaining players specialize in cross-border certification navigation.
- Distributors:ASEAN-focused intermediaries manage humidity-controlled warehousing for tropical retail; microencapsulation technology adoption differentiates service tiers.
Procurement efficiency favors Online; relationship-based verification persists in Offline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands superior pricing leverage through captive fermentation infrastructure, while North American blenders absorb input cost volatility from Southeast Asian toll manufacturers. This asymmetry redistributes margin pools toward integrated Asian producers. Regulatory divergence between SAMR's GB standards and FDA clean-label mandates fragments compliance zones.
China
Industrial seasoning procurement from instant-noodle manufacturers in Guangdong and Shandong provinces drives volume concentration. SAMR enforces GB standards for fermented condiment labeling and additive limits that elevate quality thresholds for export-oriented producers. Foshan Haitian anchors distribution depth across provincial wholesale networks spanning the Yangtze River Delta.
Indonesia
Corridor-scale seasoning operations in Java and North Sumatra standardize granulated umami inputs for million-tonne production scales. The national food and drug regulator enforces halal certification requirements that extend product launch timelines for foreign suppliers. Jakarta's industrial corridors concentrate procurement among three major buyers negotiating direct annual volume contracts.
Vietnam
Domestic sauce manufacturers upgrade from liquid to powder inputs to supply ASEAN food service distributors. The Ministry of Health regulates contaminant limits for hydrolyzed vegetable proteins in processed condiments. Ho Chi Minh City's expanding condiment sector drives adoption of humidity-resistant granulated formats for tropical distribution.
United States
Clean-label certification mandates from the FDA favor spray-dried powders over liquid alternatives with preservative stabilizers. Additive-disclosure protocols tighten shelf placement requirements in premium supermarket channels. Mid-scale craft food producers in the Pacific Northwest and Northeast Corridor disintermediate traditional spice importers through e-commerce ingredient sourcing platforms.
Germany
REACH chemical registration requirements tighten contaminant limits for 3-MCPD in hydrolyzed vegetable proteins. Powder exporters invest in HACCP documentation systems to maintain market access. Industrial seasoning blenders in Bavaria and North Rhine-Westphalia revalidate thermal processing parameters to meet evolving ECHA standards.
Soy Sauce Powder Market Competitive Landscape
Concentration sits with integrated fermentation operators who control raw liquid soy sauce feedstock quality. Spray-drying capacity clusters among Southeast Asian toll manufacturers squeeze margin pools for Western blenders lacking captive infrastructure. Three archetypes dominate: fermentation-integrated multinationals, flavor-encapsulation technology specialists, and regional distribution-depth players. Competitive moves center on backward integration into fermentation assets and geographic expansion through direct procurement platform relationships.
Within the fermentation-integrated tier, Kikkoman Corporation and Foshan Haitian Flavouring & Food Co., Ltd. exemplify divergent geographic anchoring strategies. Sensient Technologies Corporation occupies a position among technology-differentiated specialists focused on shelf-stability extension. Lee Kum Kee Group represents the regional distribution-depth archetype with established condiment market presence.
| Leading Market Players |
|---|
| Lee Kum Kee Group |
| Nestlé S.A. |
| Kikkoman Corporation |
| Kerry Group |
| Sempio Corporation |
| Yamasa Corporation |
| Ajinomoto Co., Inc. |
| Sensient Technologies Corporation |
| Foshan Haitian Flavouring & Food Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Indonesian instant-noodle conglomerates and Vietnamese spray-drying operators lock in both fermentation feedstock access and price visibility across volatile commodity cycles. SAMR's GB standards enforcement and FDA clean-label mandates create divergent certification cost burdens that stratify pricing tiers by export destination rather than intrinsic product grade.
Pricing Analysis
The customization-premium spread separates standard granulated formats from encapsulated variants engineered for tropical humidity thresholds. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity: dual organic-halal audits command top-tier positioning, while bulk unbranded powder serves cost-optimized ASEAN food service procurement. Pricing pressure stems from spray-dryer capacity concentration in Vietnam and Thailand compressing blender margins. Food processing conglomerates exhibit lowest price sensitivity due to volume scale and formulation control requirements; mid-scale craft producers show highest sensitivity as e-commerce disintermediation exposes them to spot input volatility.
Supply Chain Analysis
Inventory lead times stretch longest for European and North American seasoning houses dependent on Southeast Asian toll manufacturing without captive fermentation assets. Supply concentrates in Vietnam, Thailand, and Indonesia where spray-drying capacity clusters serve regional instant-noodle industrialization. Raw material flows draw from Black Sea grain corridors for wheat substrates and South American soybean harvests, creating dual commodity exposure. Single-source vulnerability pervades for non-integrated blenders lacking backward integration into fermentation infrastructure. Distribution runs through direct procurement platforms displacing traditional layered importer networks, particularly for mid-scale North American craft food producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: SAMR's GB standards and FDA additive-disclosure protocols erect compliance barriers that filter substandard entrants and consolidate viable supplier bases behind multi-year certification investments.
For Market Incumbents: Fortify captive fermentation infrastructure against spray-drying capacity concentration in Southeast Asian toll markets. Deepen backward integration into soybean and wheat substrate sourcing to buffer Black Sea grain flow volatility. Prioritize dual organic-halal certification pipelines to defend premium shelf positioning in Western European retail channels against emerging encapsulation technology specialists. For New Entrants and Emerging Players: Lead with flavor-encapsulation technology differentiation targeting tropical humidity distribution gaps where incumbent microencapsulation degrades above 60% relative humidity. Vietnam's condiment sector expansion presents the most penetrable white space as domestic manufacturers upgrade from liquid to powder inputs. Pursue e-commerce direct-procurement relationships with mid-scale North American craft food producers to bypass entrenched spice importer networks. For Investors and Strategic Acquirers: Capital is best deployed toward fermentation-integrated operators with established SAMR export compliance and provincial wholesale network depth across China's Yangtze River Delta. Long-term viability across the analysis window favors backward-integrated assets over packaging specialists exposed to input cost volatility. Monitor REACH contaminant limit tightening for 3-MCPD in hydrolyzed vegetable proteins as the signal indicating margin compression for non-compliant European market entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Assets | Kikkoman's captive infrastructure model demonstrates feedstock quality control and margin defense against toll manufacturing concentration. |
| Flavor-Encapsulation Technology Licensing | Sensient's modified starch and gum arabic matrices extend shelf stability into tropical retail channels without cold-chain intermediation. |
| Dual Certification Pipeline Investment | Organic-halal audit parallelization compresses launch timelines for export-focused suppliers targeting Western European premium supermarkets. |
| Direct Procurement Platform Partnership | E-commerce disintermediation of traditional spice importers captures mid-scale North American craft food producer demand. |
| Spray-Drying Capacity Expansion in Vietnam | Ho Chi Minh City's condiment sector growth supports ASEAN food service distributor supply without Indonesian corridor concentration risk. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with fermentation plant managers, instant-noodle procurement leads, ASEAN food service distributors, retail category buyers, and spray-drying equipment specialists. Secondary validation drew from SAMR regulatory filings, FDA GRAS notifications, REACH registration databases, customs trade flows, and industry association technical standards. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, and packaging format segmentation dimensions.
Across the analysis window, forecasts applied structured growth rate derivation from historical trajectory analysis and driver elasticity modeling. Segmentation dimensions tracked include product grade tier, certification intensity level, geographic regulatory cluster, and downstream channel structure. Industry-specific inputs incorporated Black Sea grain flow volatility indices and spray-dryer capacity utilization surveys from Vietnamese and Thai toll operators.
The analysis sits within stated boundaries; outcomes outside sustained ASEAN industrialization, stable GB standards enforcement, or intact Black Sea agricultural export corridors would require recalibration. Forecasts reflect documented assumptions regarding fermentation feedstock availability and encapsulation technology adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
Carvone Market
Flavorings and Food Additives
North America Flavors and Fragrances Market
Flavorings and Food Additives
Winter Melon Peel Extract Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Global Acerola Extracts Market
Flavorings and Food Additives
Mint Essential Oils Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Orange Extract Market