
 Aloe Vera Juice Market | 2026-2036
Aloe Vera Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Aloe Vera Juice Market Analysis
Cold-pressed extraction and flash-pasteurization is reshaping how aloe vera juice retains bioactive polysaccharides through processing. Forever Living Products International, Inc. leverages its captive aloe plantations in Texas and the Dominican Republic to control raw material quality from leaf to bottle. Dabur India Limited anchors its position through Ayurvedic heritage positioning and dense rural distribution across India. Patanjali Ayurved Limited competes on price-aggressive formulations targeting mass-market households through its vast retail network.
Aloe vera juice is a botanical beverage derived from the inner gel of Aloe barbadensis miller leaves, typically containing 95-99.5% water with acemannan polysaccharides, vitamins, and trace minerals as functional constituents. The liquid undergoes filleting, washing, grinding, and stabilization to preserve mucopolysaccharide activity for digestive and topical applications. Pure Aloe Vera Juice occupies the premium tier where margin pools concentrate due to minimal processing claims and organic certification premiums. The Online Retail channel is accelerating fastest as direct-to-consumer subscriptions and wellness platforms bypass traditional grocery slotting fees. Nutraceutical Companies represent a structurally growing end-user segment as contract manufacturers incorporate aloe vera juice into immunity and gut-health formulations.
The FDA enforces identity standards and aduloin content limits under botanical food regulations, while EFSA evaluates health claim substantiation for European market access. India's FSSAI mandates BIS certification for packaged aloe beverages, creating compliance thresholds for imported products. Stakeholders must monitor evolving polysaccharide testing protocols and organic certification reciprocity agreements between major producing and consuming jurisdictions.
Market Dynamics
Cold-pressed extraction and flash-pasteurization technologies are compressing processing timelines while preserving acemannan bioactivity, forcing legacy thermal processors to retool or cede premium positioning to minimally-processed competitors.
Growth Catalysts
- EFSA health claim substantiation pathways:European manufacturers investing in clinical trials for digestive wellness positioning gain regulatory-validated differentiation against commodity juice competitors.
- Nutraceutical contract manufacturing:Immunity and gut-health formulation demand from functional food producers is pulling aloe vera juice into standardized ingredient supply chains.
- Direct-to-consumer subscription platforms:Wellness apps and personalized nutrition services are bypassing traditional grocery slotting fees, capturing margin pools previously lost to retail intermediaries.
Market Restraints
- Raw material concentration:Premium leaf supply concentrates in Texas, Dominican Republic, and Mexican growing regions, exposing processors to climate volatility and single-origin risk.
- FDA aduloin content limits:Botanical food identity standards impose testing burdens that disqualify small-batch producers lacking spectroscopy capabilities.
- Plant-based beverage substitution:Coconut water and birch sap alternatives compete for identical shelf space and consumer hydration occasions.
Strategic Opportunities
- South Korean functional drink market:Beauty-from-within positioning and established consumer familiarity with botanical extracts create premium pricing headroom for certified organic entrants.
- Ayurvedic cross-border e-commerce:India's FSSAI-certified producers can leverage heritage positioning to access diaspora demand in North American and European urban centers.
- Flash-pasteurization and aseptic cold-fill convergence:Combining minimal heat treatment with extended shelf-life packaging enables ambient distribution without refrigeration infrastructure.
Industry Challenges
- Polysaccharide testing protocol fragmentation:Lack of harmonized acemannan quantification standards between FDA, EFSA, and FSSAI creates multi-jurisdiction compliance costs.
- Organic certification reciprocity gaps:USDA-NOP, EU 2018/848, and India Organic logos require separate audits, extending certification timelines for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aloe Vera Juice Market |
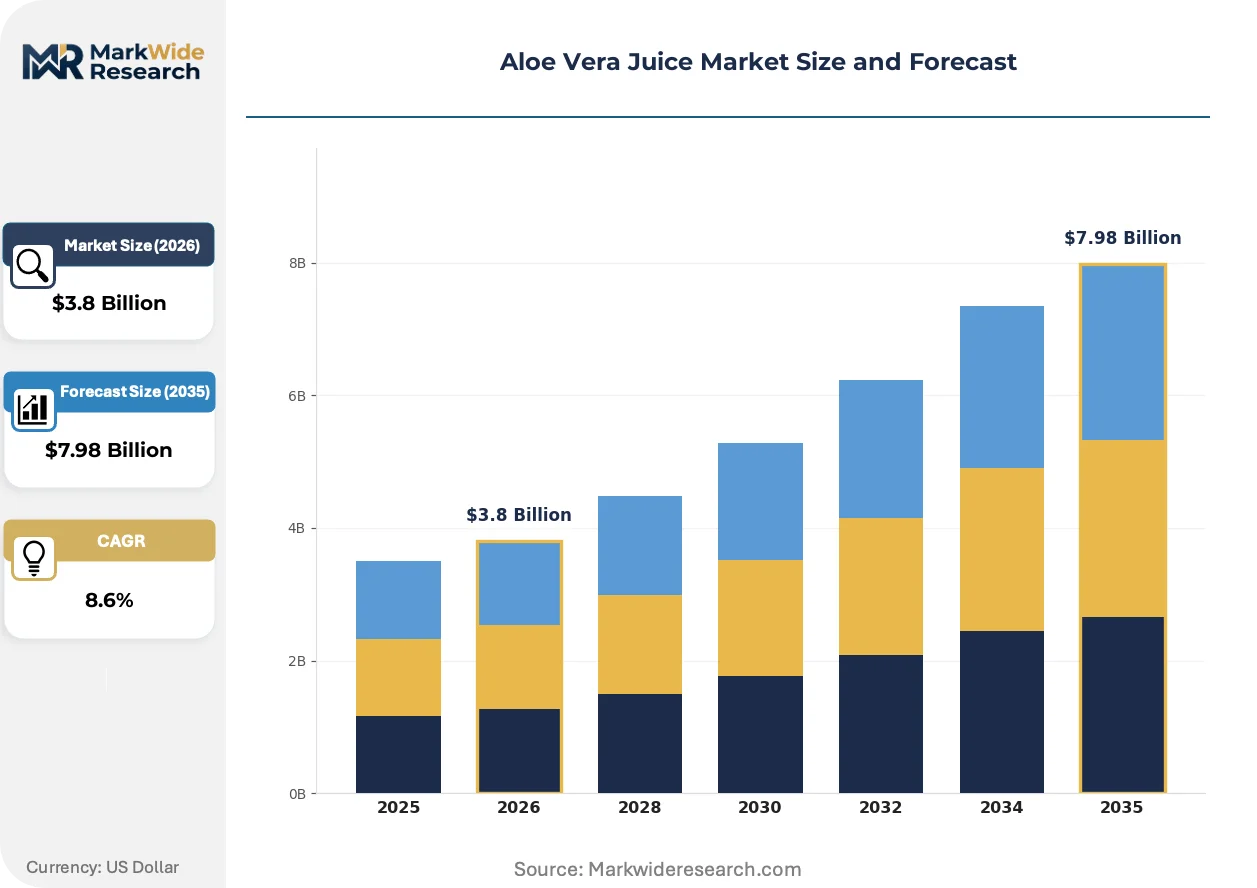
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Aloe Vera Juice, Aloe Vera with Added Sugar, Aloe Vera Drinks, Aloe Vera Gel Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores End User: Households, Food Service Providers, Beverage Manufacturers, Nutraceutical Companies Packaging Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | OKF Corporation Co., Ltd., Simplee Aloe LLC, Forever Living Products International, Inc., Dabur India Limited, Lakewood Organic Juice Company, Aloecorp, Inc., ALO Beverage Company, Inc., Patanjali Ayurved Limited, Lily of the Desert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aloe Vera Juice Market Emerging Trajectories
Processing technology convergence and regulatory tightening are compressing traditional competitive advantages while opening white space for traceability-verified, bioactive-standardized products.
Spectroscopic polysaccharide fingerprinting is digitizing quality assurance workflows across contract manufacturing facilities. Mid-sized nutraceutical processors in Germany and South Korea are adopting near-infrared rapid testing to verify acemannan concentration without batch destruction. This instrumentation is digitizing supplier qualification decisions, compressing procurement cycles from weeks to hours and marginalizing producers lacking real-time bioactivity documentation.
EFSA's evolving botanical health claim guidance is tightening evidentiary thresholds for digestive wellness positioning. Manufacturers must now submit randomized controlled trial data rather than traditional use evidence, elevating R&D spend for European market access. Premium juice segments in Germany and France are responding by funding investigator-initiated studies to secure Article 13.5 proprietary claims.
Direct subscription models are displacing conventional retail procurement for repeat-purchase households. Wellness platforms in the United States and South Korea are bundling aloe vera juice with personalized microbiome testing, capturing lifetime value through data-driven replenishment. This channel rotation is most visible in coastal metropolitan markets where grocery foot traffic has not recovered to pre-pandemic levels.
Aloe Vera Juice Market Segmentation
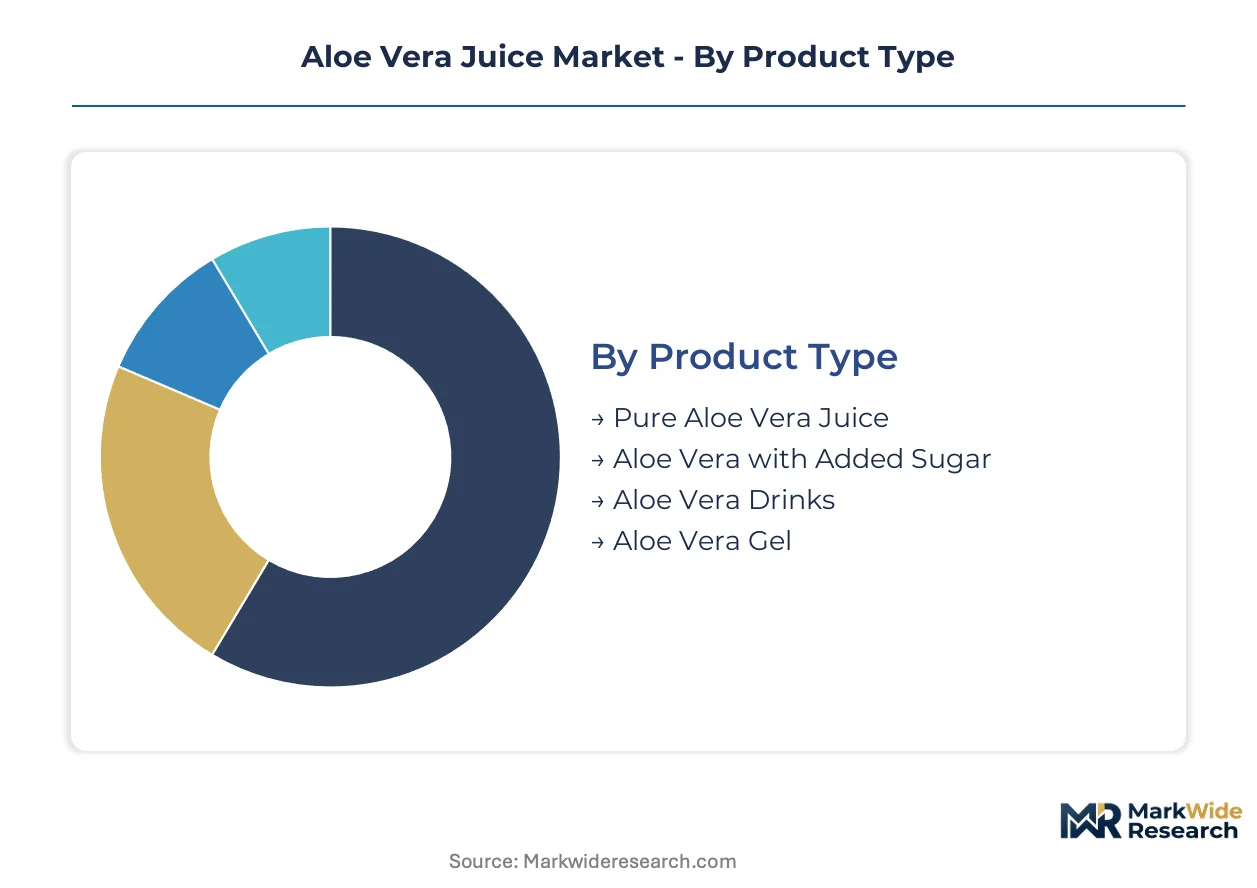
Segmentation in the aloe vera juice market reveals distinct margin pools tied to processing intensity, certification grade, and channel control. Manufacturers configure production lines and procurement strategies around these divides, with premium pure juice commanding fundamentally different economics than sweetened commodity variants.
Product Type:
Use-case spectrum spans clinical nutraceutical formulations to mass-market refreshment, with processing method and additive content defining price realization and regulatory pathway.
- Pure Aloe Vera Juice:Unfiltered inner leaf gel with acemannan polysaccharides preserved through cold-pressed extraction, typically achieving organic certification premiums. Demand concentrates in German and South Korean functional drink markets where EFSA-aligned health claims support shelf price positioning. Minimal thermal processing limits scale economies but protects bioactive integrity for nutraceutical contract manufacturing.
- Aloe Vera with Added Sugar:Palatability-modified formulations blending aloe gel with cane or alternative sweeteners at 8-12% concentration, targeting mass-market hydration occasions in price-sensitive Indian and Mexican retail channels. Volume leadership in supermarket beverage aisles comes at compressed margins due to commodity input exposure and intense coconut water substitution pressure.
- Aloe Vera Drinks:Value-added formulations incorporating flavor systems, carbonation, or functional additives like vitamins and electrolytes for on-the-go consumption.
- Aloe Vera Gel:Thickened topical and oral preparations with mucopolysaccharide concentrations above standard juice specifications, serving cosmetic and digestive therapeutic applications.
Established volume favors aloe vera with added sugar; emerging adoption favors pure aloe vera juice.
Distribution Channel:
Channel economics diverge sharply between inventory-light digital fulfillment and slotting-fee-dependent brick-and-mortar retail, reshaping working capital requirements and customer acquisition costs.
- Online Retail:Direct-to-consumer subscription platforms and wellness marketplaces bypass traditional grocery intermediaries, capturing recurring revenue from microbiome-conscious households in US coastal metros. Flash-pasteurized products with ambient stability ship efficiently through consolidated logistics, though cold-chain variants face last-mile cost pressure.
- Supermarkets:Mass-market volume anchor with standardized shelf placement fees and promotional calendar dependency, concentrating sweetened drink variants in high-traffic beverage aisles.
- Health Food Stores:Curated SKU environments with educated staff recommendation influence, favoring certified organic pure juice with transparent supply chain documentation.
- Specialty Stores:Ayurvedic practitioners, spa retail, and cosmetic boutiques with consultative selling dynamics and premium price tolerance for gel formulations.
Supermarkets retain volume dominance; online retail is gaining share fastest.
End User:
Customer type determines specification rigor, with nutraceutical and food service procurement imposing certificate-of-analysis requirements that exclude commodity-grade suppliers.
- Households:Direct consumption spanning daily wellness rituals to occasional hydration, with subscription loyalty highest among gut-health-motivated purchasers in South Korea and Germany.
- Food Service Providers:Smoothie bars, wellness cafes, and hospitality operations requiring consistent batch quality and food safety documentation for ingredient incorporation.
- Beverage Manufacturers:White-label and co-packing demand from functional drink brands seeking aloe vera as a differentiation ingredient, with acemannan standardization critical for label claim substantiation.
- Nutraceutical Companies:Contract manufacturers and supplement brands incorporating aloe vera juice into immunity, digestive, and beauty-from-within formulations, driving demand for spectroscopically-verified polysaccharide content and organic certification.
Households anchor current volume; nutraceutical companies represent the steepest expansion trajectory.
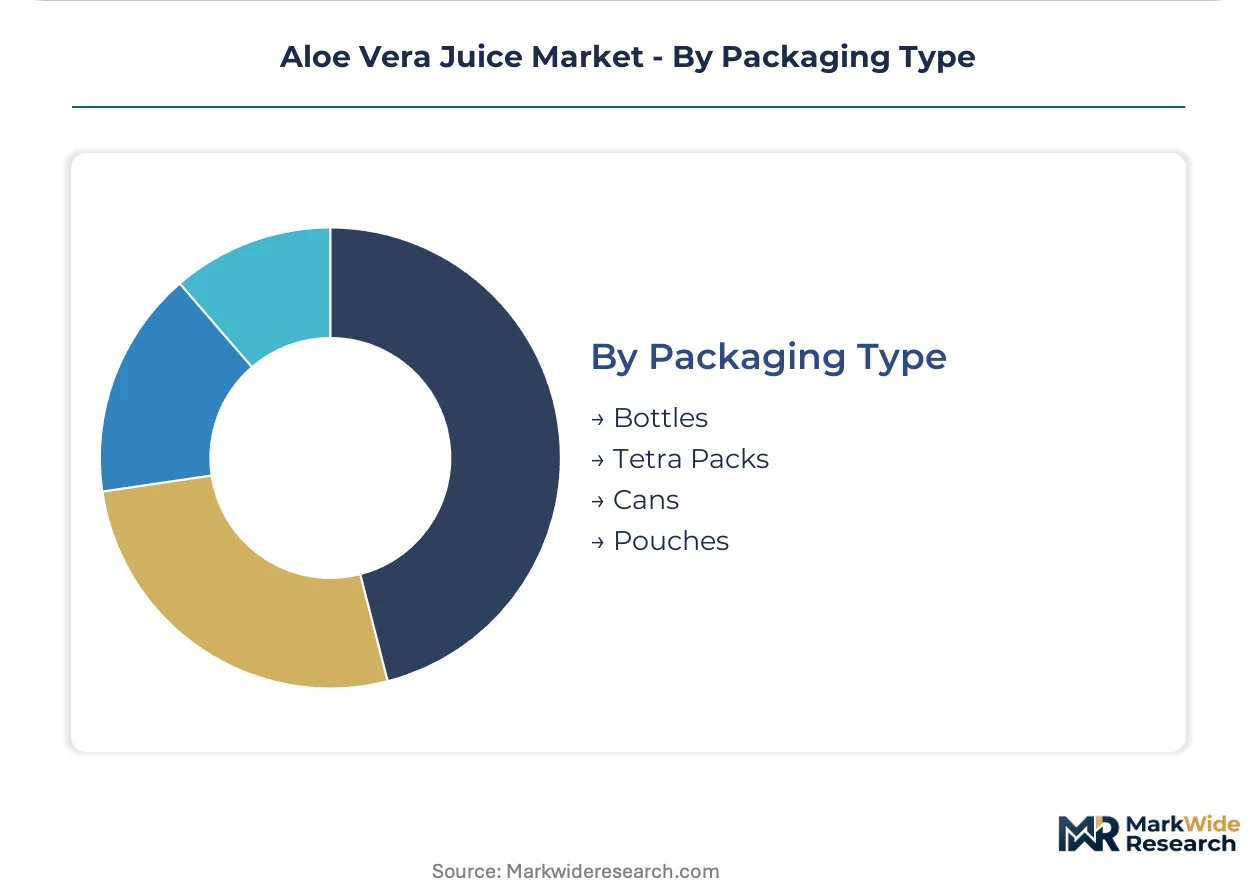
Packaging Type:
Format selection balances shelf-life extension, sustainability positioning, and cold-chain infrastructure availability across target markets.
- Bottles:PET and glass formats dominating premium pure juice positioning, with amber glass protecting light-sensitive bioactives in pharmacy and health store channels.
- Tetra Packs:Aseptic carton technology enabling ambient distribution without refrigeration, critical for flash-pasteurized products targeting emerging market expansion.
- Cans:Aluminum formats gaining traction in carbonated aloe drink variants for convenience store and vending placement.
- Pouches:Flexible stand-up formats with portion control and portability advantages, concentrated in South Korean single-serve consumption occasions and travel retail.
Bottles command premium positioning; Tetra Packs enable geographic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dominican Republic leaf exports supply US and German processors seeking EFSA-aligned organic certification. Trade corridors from Texas plantations serve nutraceutical contract manufacturers in South Korea and Japan. Indian gel concentrate moves through Ayurvedic e-commerce channels to diaspora clusters in North America and Europe.
United States
Household subscription demand from gut-health-motivated consumers in coastal metros drives premium pure juice positioning. FDA enforces botanical food identity standards and aduloin content limits through spectroscopy requirements. Texas captive plantations and California formulation clusters anchor domestic supply chains for flash-pasteurized products.
Germany
Functional drink manufacturers seek EFSA-validated digestive wellness claims through randomized controlled trial investment. EFSA Article 13.5 proprietary claim pathways elevate R&D spend for European market access. Bavarian and Baden-Württemberg nutraceutical processors adopt near-infrared acemannan testing for supplier qualification.
South Korea
Beauty-from-within positioning and established botanical extract familiarity create premium pricing tolerance for certified organic entrants. MFDS regulates functional food labeling and health claim substantiation for domestic and imported aloe beverages. Seoul Capital Area wellness platforms bundle aloe juice with microbiome testing for subscription retention.
India
Mass-market hydration demand from price-sensitive households concentrates in sweetened drink variants. FSSAI mandates BIS certification for packaged aloe beverages, creating compliance thresholds for imports. Maharashtra and Gujarat formulation hubs serve rural distribution networks through Ayurvedic heritage positioning.
Dominican Republic
Captive plantation supply to US and European processors leverages organic certification premiums and climate-advantaged growing cycles. Export-oriented leaf processing facilities align with USDA-NOP and EU 2018/848 audit requirements. Santiago and Santo Domingo concentration zones supply cold-pressed gel to premium nutraceutical contract manufacturers.
Aloe Vera Juice Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent margin pools. Supermarket slotting fee dominance favors beverage conglomerates with promotional calendar scale, while direct-to-consumer platforms reward traceability-verified specialists with subscription economics. Three archetypes define positioning: captive-plantation integrators, Ayurvedic heritage brands, and flash-pasteurization technology adopters. Competitive moves concentrate on M&A for organic certification portfolios and strategic partnerships for polysaccharide testing protocol alignment.
Among US-based integrators, Forever Living Products International, Inc. and Lily of the Desert exemplify captive-plantation control over raw material quality from leaf to bottle. Indian heritage-positioned players Dabur India Limited and Patanjali Ayurved Limited occupy distinct tier positions through rural distribution density versus price-aggressive mass-market formulations. These four anchors represent divergent strategic bets on channel control, certification grade, and processing technology investment.
| Leading Market Players |
|---|
| OKF Corporation Co., Ltd. |
| Simplee Aloe LLC |
| Forever Living Products International, Inc. |
| Dabur India Limited |
| Lakewood Organic Juice Company |
| Aloecorp, Inc. |
| ALO Beverage Company, Inc. |
| Patanjali Ayurved Limited |
| Lily of the Desert |
| Others |
Supply Flow & Price Mechanics
Idle capacity at Dominican Republic processing facilities is pressuring contract manufacturers to absorb certification audit costs rather than pass through to buyers, compressing margins for organic-certified gel suppliers while forcing price concessions from non-certified competitors.
Pricing Analysis
Cold-pressed extraction technology commands a 40-60% premium over legacy thermal processing, while flash-pasteurization equipment investments create a mid-tier price band between commodity heat-treated juice and raw unpasteurized alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by acemannan concentration verification and organic certification grade. Pricing pressure stems from coconut water and birch sap substitution in mass-market hydration occasions. Households in Indian and Mexican retail channels exhibit highest price sensitivity; nutraceutical contract manufacturers in Germany and South Korea demonstrate lowest sensitivity due to formulation value-capture.
Supply Chain Analysis
Tariff exposure between Dominican Republic and European Union markets dominates supply chain risk planning for USDA-NOP certified leaf processors seeking EU 2018/848 equivalency. Raw material supply concentrates in Texas, Dominican Republic, and Mexican growing regions. Processing depends on acemannan-preserving extraction equipment, aseptic cold-fill packaging lines, and spectroscopic testing instrumentation. Single-origin vulnerability from climate volatility in Caribbean hurricane corridors threatens leaf supply continuity. Distribution runs through direct-to-consumer subscription platforms, health food store networks, and nutraceutical contract manufacturing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer subscription platforms represent a service-attach opportunity where recurring replenishment revenue expands faster than one-time bottle sales, particularly for wellness apps bundling aloe juice with microbiome testing protocols.
For Market Incumbents: Pre-empt flash-pasteurization technology diffusion by retrofitting legacy thermal lines or acquiring certified organic capacity in Dominican Republic and Texas. Coconut water substitution pressure in mass-market channels demands defensive certification investment to maintain shelf positioning. Backward integration into captive plantation control protects raw material quality claims against commodity gel competitors. For New Entrants and Emerging Players: Rural Indian distribution networks present underpenetration for FSSAI-certified Ayurvedic heritage positioning at price points below Patanjali's mass-market formulations. South Korean beauty-from-within functional drink segments offer premium pricing headroom for EFSA-aligned organic entrants. Direct-to-consumer subscription bundling with personalized nutrition platforms bypasses grocery slotting fee barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer wellness platforms with subscription retention above 60% and data-driven replenishment algorithms. Long-term viability favors traceability-verified specialists with captive plantation supply and spectroscopic bioactivity documentation capabilities. Watch for MFDS regulatory harmonization with EFSA health claim standards as inflection signal for South Korean market access premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Flash-Pasteurization Technology Adoption | Enables ambient distribution without refrigeration infrastructure, expanding geographic reach into emerging markets. |
| Organic Certification Portfolio Expansion | USDA-NOP and EU 2018/848 dual certification unlocks premium pricing in German and South Korean functional drink segments. |
| Direct-to-Consumer Subscription Launch | Bypasses traditional grocery slotting fees while capturing lifetime value through microbiome testing bundling. |
| Spectroscopic Polysaccharide Testing Investment | Near-infrared acemannan verification compresses procurement cycles and marginalizes producers lacking real-time bioactivity documentation. |
| Ayurvedic Cross-Border E-Commerce Expansion | FSSAI-certified producers leverage heritage positioning to access diaspora demand in North American and European urban centers. |
Methodological Framework
Initial hypotheses were tested against primary input from beverage formulation chemists, health food store category buyers, nutraceutical contract manufacturing procurement leads, and Ayurvedic brand managers, and refined through secondary validation against FDA botanical food identity standards, EFSA health claim guidance documents, FSSAI packaged beverage regulations, and trade flow data from Dominican Republic export authorities. Bottom-up volume modeling from processor capacity utilization and top-down demand estimation from household consumption surveys were triangulated to constrain forecast variance.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by product type (pure juice, sweetened variants, functional drinks, gel preparations), distribution channel (online retail, supermarkets, health food stores, specialty outlets), end user (households, food service, beverage manufacturers, nutraceutical companies), and packaging format (bottles, Tetra Packs, cans, pouches). CAGRs were derived from fitted growth curves calibrated to observed adoption rates in South Korean beauty-from-within and German digestive wellness positioning. Forecast inputs incorporated acemannan standardization protocol evolution and organic certification reciprocity agreement timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by flash-pasteurization technology adopters or EFSA-aligned clinical trial investors would shift outcomes beyond modeled ranges. Regulatory harmonization between FDA, EFSA, and FSSAI polysaccharide testing standards represents a specific revision risk. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Germany Probiotic Drinks Market
Beverages
GCC Coconut Water Market
Beverages
South America Energy Drink Market
Beverages
Gluten Free Beverages Market
Beverages
Ready-To-Drink (RTD) Beverages Market
Beverages
Ready to Drink Premixes Market
Beverages
Fiber Fortified Beverages Market
Beverages
Still Drinks Market
Beverages
Beverage Cooler Market
Beverages
Global Electrolyte Drinks Market
Beverages
Blackstrap Molasses Market
Beverages
Middle East Energy Drinks Market
Beverages
Asia-Pacific Vinegar Market
Beverages
South America Ready to Drink Beverages Market
Beverages
Soft Serves Market
Beverages
Rose Floral Water Market