
 Canada Soy Protein Market | 2026-2036
Canada Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Soy Protein Market Outlook
Modular ingredient bundling is realigning how Canadian food manufacturers source soy protein for plant-based formulations. Cargill Limited leverages its Prairie crush network to secure consistent isolate supply for domestic meat-alternative producers. Burcon NutraScience Corporation specializes in novel extraction technologies that improve protein yield from non-GMO Canadian soybean varieties. Kerry Group PLC competes through flavor-masked concentrate systems tailored to North American palates.
Soy protein comprises refined or concentrated protein fractions extracted from defatted soybean meal, typically achieving protein concentrations from fifty percent in flour to over ninety percent in isolate grades through aqueous extraction and precipitation methods. The ingredient serves as a functional emulsifier, gelling agent, and nutritional fortifier across food systems, animal nutrition, and select pharmaceutical applications. Isolate commands premium positioning due to its neutral flavor profile and superior amino acid completeness for beverage applications, while textured soy protein retains dominant volume share in meat analog manufacturing. Powder form leads current shipments owing to extended shelf stability and ease of dry blending in industrial bakery and snack operations.
Health Canada enforces protein content accuracy through its Food and Drug Regulations, compelling manufacturers to substantiate label claims with validated analytical methods. The Canadian Food Inspection Agency coordinates with Health Canada to audit imported soy protein concentrates for allergen labeling compliance and genetically modified organism disclosure. Protein Industries Canada, a federal innovation supercluster, channels public-private funding toward novel fractionation research that could reshape domestic processing economics. Stakeholders must track pending amendments to Canada's Safe Food for Canadians Regulations that may impose additional preventive control requirements on soy protein ingredient facilities.
Market Dynamics
Modular ingredient bundling is compressing procurement cycles across Canadian plant-based meat manufacturing, forcing suppliers to integrate flavor-masking and texture systems alongside base protein isolates rather than selling commodity fractions alone.
Growth Catalysts
- Health Canada Labeling Mandates:Updated protein content verification protocols under the Food and Drug Regulations are compelling manufacturers to source higher-grade isolates that withstand analytical scrutiny, pulling demand toward premium suppliers.
- Prairie Crush Infrastructure:Concentrated soybean processing capacity across Manitoba and Saskatchewan is shortening supply chains for domestic meat-alternative producers, reducing lead times and import dependency.
- Livestock Feed Formulation:Western Canadian cattle and hog operations are expanding soy protein concentrate inclusion rates in rations to replace fishmeal and reduce feed costs.
Market Restraints
- Input Cost Volatility:Non-GMO soybean premiums and natural gas pricing for hexane solvent recovery are squeezing isolate processor margins, particularly for smaller fractionation facilities.
- Supply Concentration Risk:Prairie-region crushing capacity is dominated by three integrated agribusiness networks, creating bottleneck vulnerability during harvest-season logistics disruptions.
- Technical Limitation:Current aqueous extraction methods fail to recover functional protein from high-fiber soybean varieties, limiting feedstock flexibility for specialty processors.
Strategic Opportunities
- Alberta Pet Food Expansion:Underpenetrated premium pet nutrition manufacturing in Calgary-Edmonton corridor presents white space for textured soy protein targeting high-protein kibble formulations.
- Protein Industries Canada Supercluster:Federal public-private funding for novel fractionation research could commercialize enzymatic extraction methods that bypass hexane entirely.
- Cellular Agriculture Integration:Convergence of precision fermentation with soy protein scaffolding is creating hybrid meat-alternative platforms that require customized isolate grades.
Industry Challenges
- Allergen Compliance Timeline:Canadian Food Inspection Agency audits for soy allergen labeling accuracy are extending certification cycles by four to six weeks for imported concentrate shipments.
- Specialized Technician Scarcity:Protein chemists familiar with isoelectric precipitation optimization and spray-drying parameter control are concentrated at legacy Prairie processors, constraining new facility staffing.
- Legacy Equipment Retrofit Costs:Existing defatted flake processing lines require capital-intensive upgrades to achieve Health Canada's preventive control requirements under pending Safe Food for Canadians Regulations amendments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Soy Protein Market |
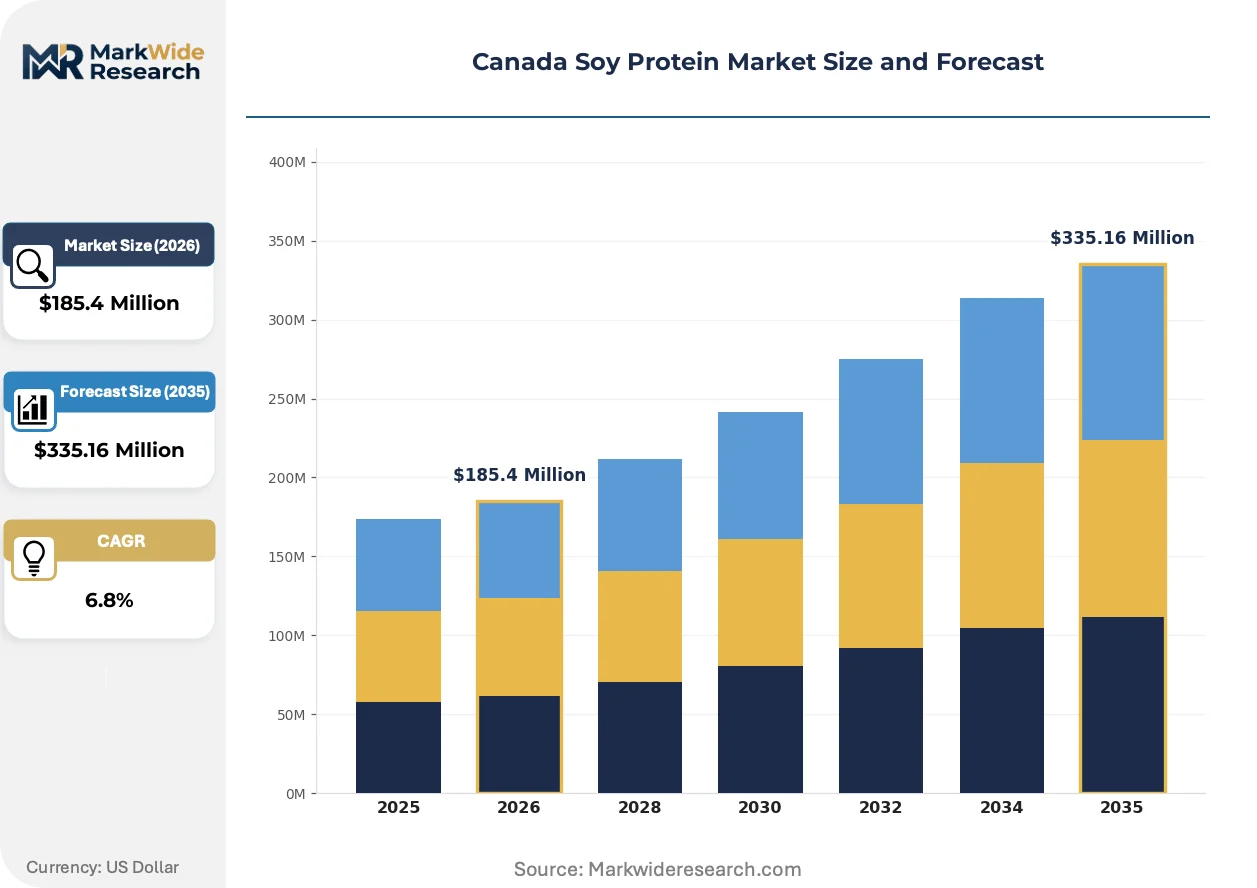
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $335.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Flour, Textured Soy Protein Application: Food & Beverages, Animal Feed, Pharmaceuticals, Cosmetics Form: Powder, Liquid, Granules, Coated End User: Food Manufacturers, Nutraceutical Companies, Livestock Producers, Restaurants |
| Companies Covered | Archer Daniels Midland Company, CHS Inc., DuPont de Nemours Inc., Kerry Group PLC, The Scoular Company, Cargill Limited, Burcon NutraScience Corporation, Protein Industries Canada, Maple Leaf Foods Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Soy Protein Market Strategic Shifts
Electrification of extraction technology is compressing energy intensity benchmarks while regulatory pressure on solvent-based methods intensifies. Canadian processors are piloting alternatives that promise to reshape cost structures.
Membrane filtration systems employing ceramic microfiltration and ultrafiltration cascades are electrifying protein recovery economics by eliminating hexane solvent loops entirely. Prairie processing facilities are retrofitting pilot lines with these electrodialysis-assisted configurations to reduce natural gas dependency and volatile organic compound emissions. This electrification is enabling smaller-scale regional processors to compete with integrated crushing networks on isolate purity metrics.
Health Canada's pending amendments to the Safe Food for Canadians Regulations are tightening preventive control documentation for soy protein ingredient facilities, mandating hazard analysis at critical control points for allergen cross-contact. The Canadian Food Inspection Agency is coordinating enforcement timelines with industry associations to avoid simultaneous compliance deadlines across multiple ingredient categories. Concentrate importers are responding by front-loading third-party audit investments to secure uninterrupted customs clearance.
Consolidated procurement contracts are displacing spot-market purchasing across Ontario and Quebec meat-alternative manufacturers, with annual volume commitments replacing quarterly tenders. This shift is compressing supplier rosters to three to four approved vendors per processor and extending contract durations to twenty-four or thirty-six months. The pattern is most visible in Toronto-Waterloo corridor plant-based dairy operations seeking isolate supply security.
Canada Soy Protein Market Segmentation
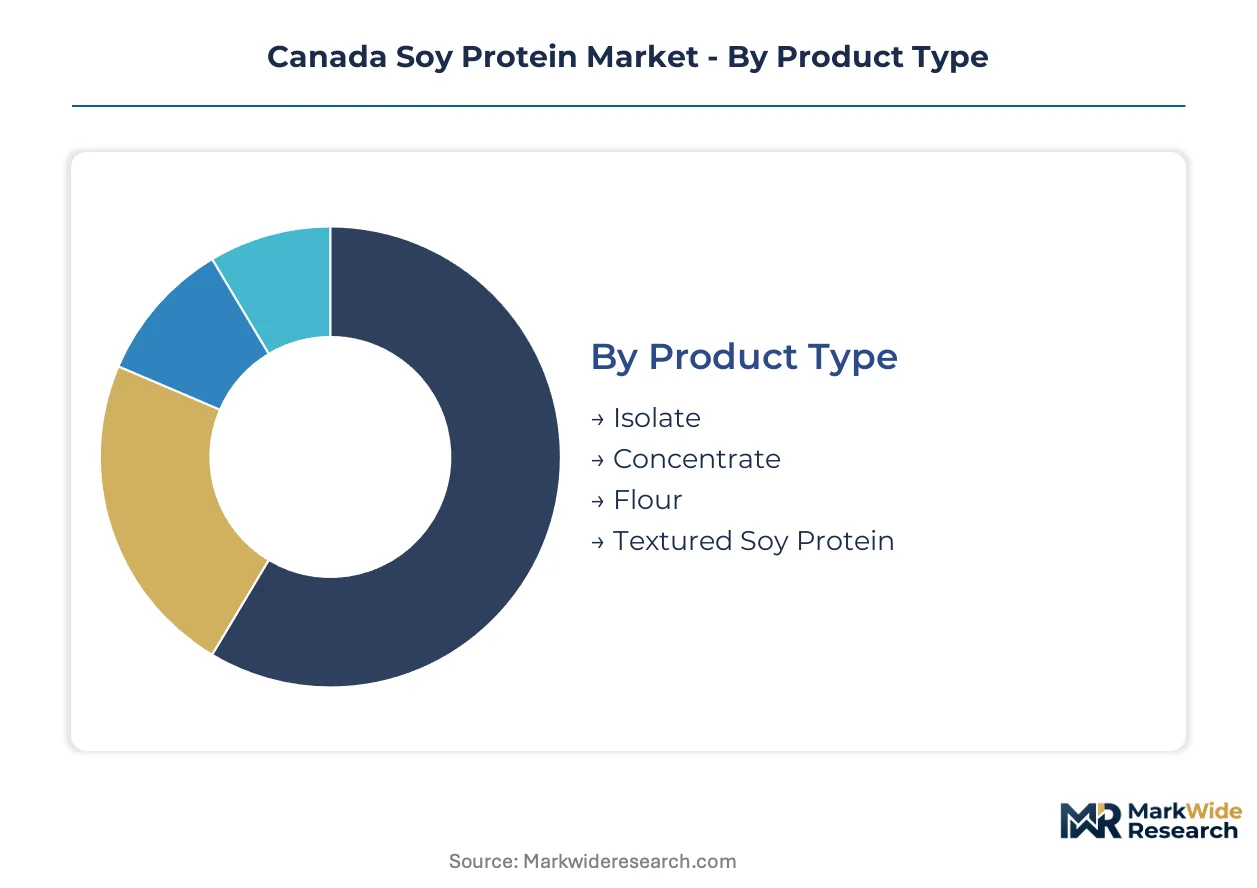
Canadian soy protein procurement patterns diverge sharply across product grades and end-use specifications, with Health Canada's labeling mandates and Prairie processing infrastructure creating distinct buyer segments. Understanding these fault lines reveals where margin pools concentrate and which formulations face supply bottlenecks.
Product Type:
Buyers in this category separate by protein purity requirements and functional performance thresholds rather than price sensitivity alone.
- Isolate:Refined protein fractions exceeding 90% concentration through aqueous extraction and isoelectric precipitation. Ontario and Quebec plant-based meat manufacturers are pulling isolate volumes toward neutral-flavor beverage applications as Health Canada tightens protein content verification protocols.
- Concentrate:Intermediate grades achieving 70% protein content through alcohol washing of defatted flakes. Western Canadian livestock feed operations in Alberta and Saskatchewan are expanding concentrate inclusion rates to replace fishmeal in cattle and hog rations.
- Flour:Full-fat or defatted ground soybean meal retaining native fiber and oil content. Industrial bakeries across the Prairie provinces utilize flour for protein fortification in bread and snack formulations where texture tolerance permits lower purity.
- Textured Soy Protein:Extruded defatted flour or concentrate processed into fibrous, meat-like structures. Calgary-Edmonton corridor pet food manufacturers represent underpenetrated demand for premium kibble applications requiring chew simulation.
Volume sits with Concentrate in livestock feed; growth tilts toward Isolate as beverage-grade specifications harden.
Application:
End-use differentiation tracks regulatory exposure and formulation complexity, with food-grade buyers facing stricter audit cycles than industrial users.
- Food & Beverages:Plant-based dairy and meat-alternative formulations requiring flavor-masked, high-solubility protein grades. Toronto-Waterloo corridor processors are consolidating procurement contracts to twenty-four-month isolate commitments.
- Animal Feed:Cattle, hog, and aquaculture rations leveraging concentrate cost advantages over fishmeal. Manitoba and Saskatchewan crush facilities shorten supply chains for domestic feed compounders.
- Pharmaceuticals:Excipient and nutritional supplement applications demanding non-GMO certification and batch traceability. Health Canada's Food and Drug Regulations impose protein content substantiation requirements that elevate documentation burdens.
- Cosmetics:Hair and skin conditioning formulations utilizing hydrolyzed soy protein fractions. This segment remains nascent in Canada relative to European and Asian markets.
Revenue concentrates in Food & Beverages; steepest expansion trajectory belongs to Animal Feed as western Canadian operations scale concentrate inclusion.
Form:
Physical state selection hinges on shelf stability requirements and blending equipment compatibility across processing facilities.
- Powder:Spray-dried isolates and concentrates dominating industrial bakery and dry-mix operations. Extended shelf stability and ease of pneumatic conveying make powder the default for Prairie-region processing facilities.
- Liquid:Pre-hydrated slurries for ready-to-drink beverage manufacturers seeking reduced mixing cycle times. Quebec dairy-alternative producers are piloting liquid concentrate systems to bypass reconstitution steps.
- Granules:Agglomerated particles improving dispersibility in high-speed meat grinding operations. Ontario plant-based meat facilities utilize granule forms for controlled hydration in extrusion processes.
- Coated:Lipid-encapsulated isolates masking bitter off-notes in pediatric and senior nutrition products. This form commands formulation premiums but remains volume-constrained by coating equipment availability.
Shipment volume clusters in Powder; product development momentum favors Liquid as beverage manufacturers target mixing efficiency gains.
End User:
Customer type stratification reflects scale economies and technical service intensity, with large manufacturers extracting supplier integration commitments unavailable to smaller buyers.
- Food Manufacturers:Integrated meat-alternative and dairy-alternative processors in Ontario and Quebec driving modular ingredient bundling. These buyers now require flavor-masking and texture systems alongside base protein isolates.
- Nutraceutical Companies:Supplement formulators seeking non-GMO and organic-certified isolates for sports nutrition and clinical nutrition products. Health Canada labeling mandates elevate their documentation requirements relative to conventional food users.
- Livestock Producers:Western Canadian cattle and hog operations purchasing concentrate directly or through feed compounders. Their procurement is displacing fishmeal on cost grounds while maintaining amino acid profile targets.
- Restaurants:Foodservice operators incorporating textured soy protein into plant-based menu items. This segment remains fragmented with spot purchasing patterns unlike the contract consolidation visible among manufacturers.
Contract value aggregates with Food Manufacturers; fastest volume gains are emerging from Livestock Producers as western feed operations expand soy protein inclusion rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's soy protein market exhibits a pronounced production-consumption divide: Prairie provinces crush and process the majority of domestic supply, while Ontario and Quebec absorb the bulk of food-grade isolate demand for plant-based manufacturing.
Ontario
Toronto-Waterloo corridor processors drive isolate procurement for meat-alternative and dairy-alternative formulations. Health Canada's Food and Drug Regulations impose protein content verification protocols that elevate documentation burdens for food manufacturers. Consolidated procurement contracts now extend to twenty-four-month commitments as buyers seek supply security.
Quebec
Montreal-area plant-based dairy operations are piloting liquid concentrate systems to bypass reconstitution steps in beverage manufacturing. The province's food processors face tightening audit cycles from the Canadian Food Inspection Agency for allergen labeling compliance. Flavor-masked concentrate systems tailored to North American palates dominate technical service discussions.
Alberta
Calgary-Edmonton corridor pet food manufacturers represent underpenetrated demand for textured soy protein in premium kibble formulations. Livestock feed operations across the province are expanding concentrate inclusion rates to replace fishmeal in cattle and hog rations. Provincial processing capacity remains constrained relative to western Canadian demand growth.
Prairie Provinces
Manitoba and Saskatchewan crush facilities anchor domestic soybean processing infrastructure, shortening supply chains for Prairie-region feed compounders. Protein Industries Canada channels federal public-private funding toward novel fractionation research that could reshape domestic processing economics. Three integrated agribusiness networks dominate crushing capacity, creating bottleneck vulnerability during harvest-season logistics disruptions.
British Columbia
Vancouver-area nutraceutical companies seek non-GMO and organic-certified isolates for sports nutrition and clinical nutrition products. The province's coastal position facilitates import flows of specialty grades not produced domestically. Health Canada labeling mandates elevate documentation requirements relative to conventional food users in this segment.
Canada Soy Protein Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Canada's soy protein value chain, creating a tiered structure where scale advantages clash with technical agility. The vendor base clusters around three integrated crushing networks controlling Prairie infrastructure, while smaller fractionation facilities compete on specialty grades and extraction innovation. Two strategic archetypes dominate: agricultural processors with backward integration into seed supply, and ingredient technology specialists with proprietary extraction intellectual property. Competitive intensity centers on capacity expansion in Prairie crush assets and strategic partnerships linking isolate supply to plant-based meat-alternative offtake.
Within the diversified agribusiness tier, Cargill Limited anchors its position through Prairie crush network control, while Archer Daniels Midland Company exemplifies the multinational trading house model with Canadian operational presence. Kerry Group PLC represents the ingredient systems specialist archetype, competing through integrated flavor and texture solutions rather than commodity protein fractions. Burcon NutraScience Corporation occupies a distinct position as a technology-centric pure-play focused on novel extraction methodologies. These three entities collectively illustrate the competitive tension between scale-driven commodity supply and innovation-led specialty positioning.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| CHS Inc. |
| DuPont de Nemours Inc. |
| Kerry Group PLC |
| The Scoular Company |
| Cargill Limited |
| Burcon NutraScience Corporation |
| Protein Industries Canada |
| Maple Leaf Foods Inc. |
| Others |
Value Chain & Pricing Dynamics
Electrification of extraction technology is compressing energy intensity benchmarks while simultaneously redistributing processing economics toward smaller regional facilities, fragmenting the Prairie crush network's historical pricing power over isolate grades. This shift enables non-integrated processors to compete on purity metrics while tightening margins at legacy hexane-dependent operations.
Pricing Analysis
Margin tightening in standard-grade concentrate reflects natural gas volatility and non-GMO soybean premiums squeezing Prairie processor returns. Three-tier pricing structure across premium isolate, standard concentrate, and economy flour segments tracks protein purity and certification burden. Cost-down pressure on isolate grades accelerates as Health Canada labeling mandates force buyers toward analytically defensible high-purity supply. Livestock feed compounders in Alberta and Saskatchewan exhibit highest price sensitivity, while Toronto-Waterloo beverage manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Domestic-content procurement rules under Protein Industries Canada supercluster funding are reshaping sourcing patterns toward Manitoba and Saskatchewan crush facilities. Geographic supply concentration centers on Canada, with secondary flows from US Midwest processors and limited European specialty imports. Raw material dependencies include non-GMO soybean seedstock, hexane solvent for conventional extraction, and ceramic membrane systems for electrified fractionation. Single-source vulnerability concentrates in three integrated agribusiness networks controlling Prairie crushing capacity. Distribution runs through bulk rail to Ontario and Quebec food manufacturers, with truck delivery dominating western Canadian feed operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
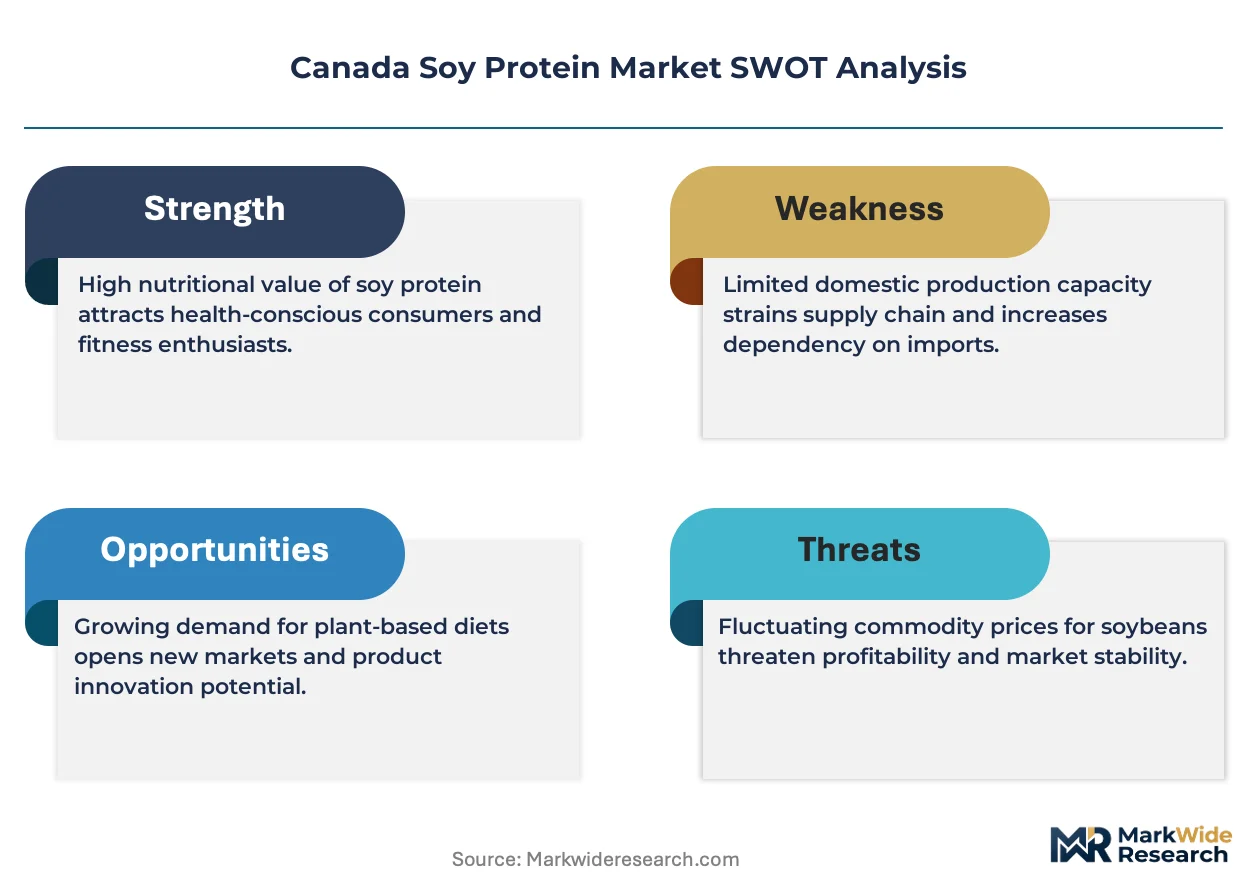
Canada's soy protein sector is consolidating around electrified extraction capabilities and modular ingredient bundling, with Health Canada regulatory burdens and Prairie infrastructure concentration forcing subscale processors toward exit or acquisition.
For Market Incumbents: Extend Prairie crush network control through selective retrofit of pilot lines with membrane filtration systems, eliminating hexane dependency and capturing electrification premiums. Lock in twenty-four-month procurement commitments from Toronto-Waterloo corridor meat-alternative manufacturers before pending Safe Food for Canadians Regulations amendments elevate compliance costs for smaller competitors. Threat substitution from precision fermentation platforms demands accelerated R&D partnership with cellular agriculture developers to secure hybrid scaffolding offtake. For New Entrants and Emerging Players: Enter via Alberta's Calgary-Edmonton corridor pet food manufacturing cluster, where textured soy protein penetration in premium kibble formulations remains underdeveloped relative to Ontario and Quebec saturation. Target enzymatic extraction technology licensing from Protein Industries Canada-funded research to bypass capital-intensive hexane infrastructure entirely. Go-to-market angle should emphasize non-GMO certification and batch traceability for Vancouver-area nutraceutical companies seeking domestic alternatives to import-dependent supply. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated agribusiness networks seeking electrified fractionation capabilities and Health Canada-compliant documentation systems. Long-term viability favors processors with backward integration into seed supply and forward partnerships with plant-based meat-alternative offtake. Acquisition target archetype: regional fractionation facilities with membrane filtration pilot capacity and established CFIA audit relationships. Signal to watch is enforcement timeline coordination for Safe Food for Canadians Regulations amendments, which will trigger distressed divestiture among undercapitalized concentrate importers.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Electrified extraction eliminates hexane loops, reducing natural gas exposure and volatile organic compound emissions at Prairie facilities. |
| Long-Term Procurement Contracting | Twenty-four-month isolate commitments from Ontario manufacturers compress supplier rosters and secure volume visibility for capacity planning. |
| Protein Industries Canada Partnership | Federal supercluster funding accelerates commercialization of enzymatic extraction methods bypassing conventional solvent infrastructure. |
| Cellular Agriculture Integration | Hybrid meat-alternative platforms combining precision fermentation with soy protein scaffolding create customized isolate grade demand. |
| Preventive Control Compliance Investment | Health Canada documentation upgrades position processors for uninterrupted customs clearance under pending regulatory amendments. |
Study Parameters
Multi-period observation of crush capacity utilization, isolate purity premiums, and CFIA enforcement patterns anchored the trend analysis, supplemented by interviews with Prairie plant managers, Ontario food manufacturer procurement leads, Alberta feed compounder nutritionists, and Health Canada regulatory affairs specialists. Secondary validation drew from Canadian Food Inspection Agency audit disclosures, Protein Industries Canada funding announcements, SEC filings of multinational agribusiness parents, and customs trade data tracking concentrate import flows. Bottom-up volume modeling triangulated against top-down expenditure estimates from federal innovation supercluster allocations.
Segment-weighting across product type, application, physical form, and end-user categories structured the analytical framework across the projection horizon. Modeled dimensions included isolate-concentrate-flour-textured grades, food-beverage-feed-pharma-cosmetic end-uses, powder-liquid-granule-coated formats, and manufacturer-nutraceutical-livestock-restaurant customer archetypes. CAGRs derived from elasticity-adjusted demand curves incorporating Health Canada regulatory compliance cost trajectories and Prairie crush capacity expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under harvest-season logistics disruptions or accelerated Safe Food for Canadians Regulations enforcement. Projections reflect assumptions regarding Protein Industries Canada funding continuity and electrification technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
EPA and DHA Omega-3 Ingredient Market
Ingredients
Low Fat Oil Market
Ingredients
Non-GMO Soya Market
Ingredients
Vegetable Fats Market
Ingredients
Native Starch Market
Ingredients
Drum to Hopper Blends Premix Market
Ingredients
Pea Fiber Market
Ingredients
Starch-Derived Fiber Market
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Fish Gelatin Market
Ingredients
Canola Protein Market
Ingredients
Alginate Market
Ingredients
Milk Mineral Concentrate Market
Ingredients
Global Yeast Market
Ingredients
Industrial Starch Market
Ingredients
Salt Content Reduction Ingredients Market