
 Europe Ready-To-Drink Beverages Market | 2026-2036
Europe Ready-To-Drink Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ready-To-Drink Beverages Market Insights
Multi-source ingredient procurement is pivoting toward vertically integrated supply chains as European bottlers seek greater control over natural extracts and sweetener traceability. Nestlé S.A. anchors its RTD coffee dominance through captive roasting and dairy sourcing across Switzerland and France. PepsiCo leverages its snack-beverage co-location strategy to secure impulse placement in convenience channels. Red Bull GmbH differentiates through proprietary energy formulations and tight control over its Austrian production base.
Europe Ready-To-Drink Beverages are commercially prepared, shelf-stable liquid formulations packaged in cans, glass, or recyclable PET containers, typically processed through hot-fill, aseptic, or high-pressure processing methods to ensure microbiological safety without preservatives. These products serve immediate consumption occasions across retail, foodservice, and on-the-go channels where preparation time and portability determine purchase decisions. Tea-based RTD variants lead volume contribution due to established consumption rituals in the United Kingdom and Germany, while functional coffee smoothies command margin concentration through protein fortification and plant-based milk integration. Online retail distribution is accelerating fastest among channels, though supermarket chains still control the bulk of replenishment purchases through promotional calendar alignment.
EMA food-contact material standards, EFSA novel food ingredient approvals, and the EU Single-Use Plastics Directive collectively govern formulation safety, label claims, and packaging compliance across member states. EFSA scrutiny of caffeine and adaptogen dosage thresholds directly constrains energy drink innovation pipelines and cross-border formulation standardization. Stakeholders must monitor evolving Extended Producer Responsibility schemes and deposit-return system expansions as these mechanisms will determine packaging cost structures and regional manufacturing location decisions.

Market Dynamics
The EU Single-Use Plastics Directive is compressing packaging formats while aseptic cold-fill bottling spreads across Western European production lines, forcing simultaneous capital deployment and formulation reformulation.
Growth Catalysts
- EFSA novel food pathways:Accelerated approval timelines for adaptogen and botanical extracts enable faster functional beverage launches in France and Germany.
- Urban millennial tea rituals:RTD matcha and kombucha variants penetrate metropolitan German convenience channels through health-positioned placement.
- Aseptic cold-fill adoption:Extended shelf life without preservatives opens distribution into rural UK and Scandinavian retail networks previously unreachable.
Market Restraints
- Natural extract supply concentration:Vanilla and yerba mate sourcing clusters in Madagascar and Argentina create input volatility for European formulators.
- Deposit-return system fragmentation:Inconsistent national implementations across Germany, Sweden, and the Netherlands inflate compliance costs for multi-market SKUs.
- Aluminum can capacity constraints:European smelter output limitations restrict packaging availability during peak summer demand windows.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania show functional beverage consumption gaps of 40-60% versus Western European per-capita benchmarks.
- Foodservice fountain systems:Post-mix RTD coffee and tea dispensers displace traditional brewed alternatives in UK workplace catering contracts.
- EU Green Deal packaging incentives:Biodegradable bottle mandates in France and Italy subsidize rPET transition investments for early movers.
Industry Challenges
- Aseptic engineering talent scarcity:European bottlers compete for limited specialists capable of commissioning cold-fill lines with 6-month lead times.
- Cross-border formulation harmonization:Caffeine ceiling variations between Germany, France, and the UK force SKU proliferation or lowest-common-denominator dilution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ready-To-Drink Beverages Market |
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tea, Coffee, Juice, Smoothies Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Vending Machines Price Tier: Premium, Mid-Range, Economy, Value End User: Adults, Teenagers, Children, Athletes |
| Companies Covered | The Coca-Cola Company, PepsiCo, Nestlé S.A., Monster Beverage Corporation, Red Bull GmbH, Suntory Holdings Limited, Starbucks Corp., Danone SA, Britvic PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ready-To-Drink Beverages Market Trends and Innovations
Formulation science and packaging engineering are converging to eliminate preservatives while extending shelf stability, reshaping how European bottlers design production assets and label claims.
High-pressure processing (HPP) is decentralizing quality control away from centralized hot-fill infrastructure. Mid-sized bottlers in Spain and Italy adopt HPP units for small-batch functional launches. This technology is decentralizing production economics by enabling distributed manufacturing without aseptic line investments.
REACH chemical registration requirements for food-contact materials now mandate full polymer supply chain disclosure. Bottlers must document rPET origin through mechanical recycling certificates. German and French regulators enforce this most stringently, pushing suppliers toward mass-balance accounting systems.
Subscription replenishment models displace supermarket promotional calendars for habitual RTD coffee consumers. UK direct-to-consumer platforms capture urban professionals seeking flavor customization. This channel rotation concentrates highest in London and Manchester metropolitan zones where delivery density supports unit economics.
Europe Ready-To-Drink Beverages Market Segmentation
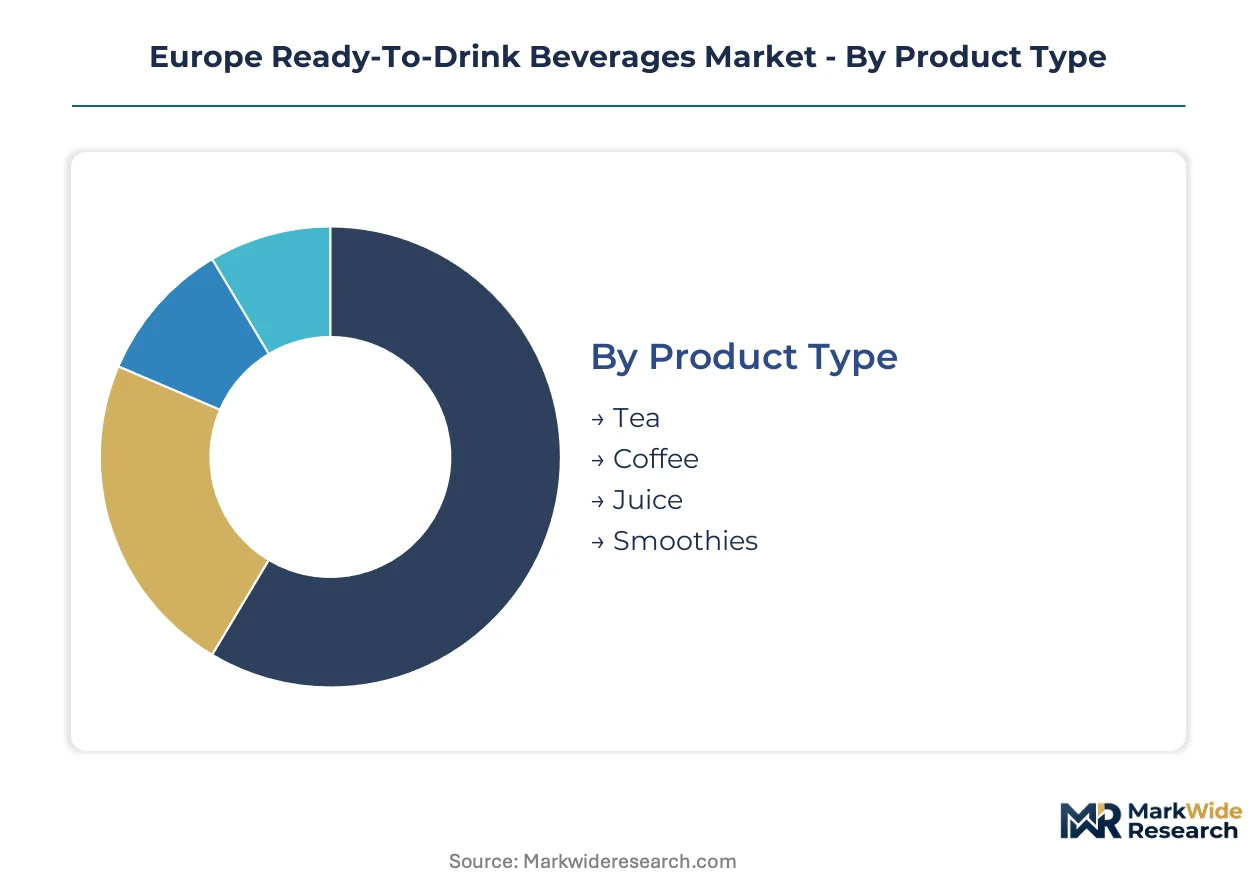
European RTD beverage segmentation reveals how formulation technology, channel infrastructure, and consumer occasion intersect to determine commercial outcomes. Distinct packaging and shelf-life requirements separate tea and coffee variants from juice and smoothie formats, while distribution density shapes which price tiers penetrate specific metropolitan corridors.
Product Type:
Hot-fill and aseptic processing capabilities define competitive positioning across liquid formulations, with thermal treatment intensity directly constraining ingredient selection and label claims.
- Tea:RTD tea formulations rely on hot-fill or high-pressure processing to stabilize polyphenol content without preservatives. United Kingdom metropolitan demand concentrates around unsweetened black and green variants, driven by established daily consumption rituals among urban professionals seeking reduced-sugar alternatives to carbonated soft drinks.
- Coffee:Cold-brew and flash-brew extraction methods preserve aromatic compounds in shelf-stable formats. German convenience channels show accelerating placement of functional coffee smoothies with protein fortification, as health-positioned SKUs command placement in railway station and airport retail networks.
- Juice:NFC and reconstituted variants dominate volume, with pasteurization intensity determining clean-label positioning.
- Smoothies:High-pressure processing enables raw fruit preservation in refrigerated distribution, constraining reach to cold-chain-capable retail.
Mature deployment sits with Tea. Newer deployment is concentrated in Coffee.
Distribution Channel:
Channel economics separate replenishment purchases from impulse occasions, with cold-chain requirements and promotional calendar alignment determining which product types dominate each route.
- Supermarkets:Multi-SKU replenishment purchases concentrate in German and French hypermarket chains, where promotional calendar alignment drives volume concentration in tea and juice categories. Shelf-space negotiations favor established suppliers with proven velocity metrics.
- Convenience Stores:Impulse-driven single-serve purchases in urban UK and Netherlands petrol station networks favor premium-priced coffee and energy variants. Refrigerated cabinet placement determines visibility, with EFSA-compliant caffeine ceilings constraining formulation standardization across borders.
- Online Retail:Subscription replenishment models capture habitual coffee consumers in London and Manchester, where delivery density supports direct-to-consumer unit economics.
- Vending Machines:Post-mix fountain systems displace brewed alternatives in workplace catering contracts, with cashless payment integration driving adoption in Scandinavian office corridors.
Volume concentrates in Supermarkets. Margin expansion is climbing the fastest in Online Retail.
Price Tier:
Raw material provenance and processing sophistication stratify offerings, with organic certification and functional ingredient fortification commanding tier placement.
- Premium:Organic-certified and adaptogen-fortified variants target health-conscious millennials in Paris and Berlin, where EFSA novel food approvals enable faster botanical extract launches than conventional regulatory pathways.
- Mid-Range:Clean-label reformulations without artificial sweeteners dominate German supermarket placement, balancing accessibility with ingredient transparency demands.
- Economy:Private-label juice and tea variants capture price-sensitive volume in Southern European discount chains.
- Value:Basic reconstituted formulations serve rural distribution networks with extended shelf-life requirements.
Private-label momentum sits with Economy. Brand investment concentrates in Premium.
End User:
Demographic targeting determines caffeine content ceilings, portion sizing, and functional claim positioning across regulatory jurisdictions.
- Adults:Functional coffee and adaptogen teas target working-age professionals in UK and German urban centers, with protein fortification and nootropic positioning driving repeat purchase rates.
- Teenagers:EFSA caffeine thresholds constrain energy drink formulations, with flavor innovation and packaging design becoming primary differentiation vectors.
- Children:Vitamin-fortified juice boxes face sugar content scrutiny under national school nutrition policies.
- Athletes:Electrolyte and protein-enhanced RTD smoothies penetrate sports nutrition specialty retail, with batch-tested certification required for competitive use claims.
Established positioning sits with Adults. Emerging formulation investment is gaining share fastest in Athletes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentinian yerba mate and Madagascan vanilla supply chains anchor European formulator procurement strategies, while production assets cluster along the Rhine corridor and Greater London logistics networks.
Germany
Urban millennial demand for functional RTD teas accelerates through Berlin and Munich convenience channels. EFSA novel food approval pathways enable faster botanical extract launches than conventional regulatory routes. The Baden-Württemberg industrial corridor hosts aseptic cold-fill bottling investments serving cross-border distribution.
United Kingdom
Established daily tea consumption rituals drive unsweetened black and green variant penetration among London professionals. The UK deposit-return system expansion pressures packaging format standardization across Scottish and English retail networks. Manchester and Birmingham distribution hubs support direct-to-consumer subscription replenishment models.
France
Organic-certified and adaptogen-fortified premium variants target health-conscious millennials in Paris metropolitan zones. EU Green Deal packaging incentives subsidize rPET transition investments for early movers. The Île-de-France logistics cluster concentrates cold-chain distribution infrastructure for refrigerated smoothie formats.
Italy
High-pressure processing adoption spreads among mid-sized bottlers for small-batch functional launches. REACH chemical registration requirements for food-contact materials mandate full polymer supply chain disclosure. The Lombardy production corridor integrates mechanical recycling certificate systems for German and French retail compliance.
Poland
Functional beverage consumption gaps of 40-60% versus Western European per-capita benchmarks attract capacity expansion interest. Extended Producer Responsibility scheme preparations reshape packaging cost structures for Warsaw and Kraków retail networks. The Silesian manufacturing zone offers lower-cost production bases for EU market access.
Europe Ready-To-Drink Beverages Market Competitive Landscape
Backward integration into natural extract sourcing dominates the current landscape as bottlers seek supply security. The vendor base organizes around three strategic archetypes: multinational beverage conglomerates with captive roasting and dairy infrastructure, energy drink specialists with proprietary formulation control, and mid-sized regional bottlers leveraging high-pressure processing flexibility. M&A activity concentrates on aseptic engineering capabilities and botanical extract suppliers, while capacity expansion targets Eastern European underpenetrated markets.
Among Switzerland-based and Austria-based formulators, Nestlé S.A. and Red Bull GmbH exemplify divergent competitive models. Nestlé S.A. anchors its positioning through captive supply chain control across dairy and coffee roasting assets. Red Bull GmbH occupies a specialist tier through tight production base concentration and proprietary energy formulation stewardship. PepsiCo represents the snack-beverage co-location archetype, securing impulse placement through channel integration strategies.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Nestlé S.A. |
| Monster Beverage Corporation |
| Red Bull GmbH |
| Suntory Holdings Limited |
| Starbucks Corp. |
| Danone SA |
| Britvic PLC |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap bottlers across the Baden-Württemberg and Lombardy corridors anchor supply discipline through generational capital structures that resist quarterly pricing pressure. Their captive relationships with yerba mate cooperatives and vanilla extract importers insulate formulation costs from commodity volatility while sustaining premium positioning in Paris and Berlin metropolitan channels.
Pricing Analysis
Service-bundling separates aseptic engineering support from base product quotes, with extended shelf-life warranties commanding 15-20% uplifts over standard hot-fill equivalents. Three-tier pricing structure across premium, standard, and economy levels reflects organic certification status and cold-chain dependency rather than ingredient cost alone. Cost compression in the economy tier intensifies because private-label juice contracts face sugar input volatility and discount chain procurement consolidation. Convenience channel buyers show lowest price sensitivity, while supermarket replenishment purchasers negotiate hardest on promotional calendar terms.
Supply Chain Analysis
Aseptic engineering talent scarcity across Germany, Italy, and Switzerland constrains line commissioning schedules and inflates specialist contractor rates. European bottling draws from Argentinian yerba mate clusters, Madagascan vanilla estates, and domestic rPET mechanical recycling streams. Single-source vulnerability concentrates in botanical extract supply, where climate disruption in source regions propagates formulation cost spikes. Distribution runs through Rhine corridor logistics hubs serving cross-border retail networks, with Greater London terminals handling UK-specific cold-chain requirements.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe RTD beverages sector sits in a processing-technology transition, with aseptic cold-fill systems displacing legacy hot-fill infrastructure and reshaping capital deployment priorities.
For Market Incumbents: Deploy captive sourcing agreements to lock yerba mate and vanilla extract supply before Argentine and Madagascan harvest volatility intensifies. Nestlé-style backward integration into dairy and coffee roasting assets defends margin position against private-label encroachment in German supermarket channels. Channel control through snack-beverage co-location, per PepsiCo's convenience network strategy, secures impulse placement against direct-to-consumer subscription models. For New Entrants and Emerging Players: The premium-economy price gap in Polish and Romanian functional beverage markets creates entry space for mid-tier positioning with Western European formulation standards. White-space targets concentrate in Warsaw and Kraków workplace catering contracts, where post-mix fountain systems remain underdeployed versus UK benchmarks. Go-to-market execution should leverage HPP equipment flexibility for small-batch adaptogen launches ahead of EFSA novel food approval pathways. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized Italian and Spanish bottlers with installed HPP capacity and pending EFSA botanical extract approvals. Long-term viability hinges on aseptic engineering capability scarcity resolving through apprenticeship pipeline expansion rather than M&A premium inflation. Watch German deposit-return system harmonization progress as the inflection signal for multi-SKU packaging cost rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Fill Line Investment | Extends shelf life without preservatives, opening rural UK and Scandinavian distribution previously unreachable. |
| Captive Botanical Extract Sourcing | Secures yerba mate and vanilla supply chains against Argentine and Madagascan climate volatility. |
| Direct-to-Consumer Subscription Launch | Captures habitual coffee consumers in London and Manchester through delivery-density economics. |
| rPET Transition Certification | Qualifies for EU Green Deal packaging incentives in France and Italy while meeting REACH disclosure mandates. |
| Eastern European Distribution Expansion | Addresses 40-60% per-capita consumption gaps in Poland and Romania versus Western benchmarks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with RTD beverage category managers, aseptic engineering specialists, EFSA regulatory consultants, and convenience channel procurement leads. Secondary validation drew from EU Single-Use Plastics Directive implementation trackers, EFSA novel food approval databases, German and UK deposit-return system filings, and European bottler association capacity surveys. Bottom-up SKU velocity modeling triangulated against top-down regional consumption benchmarks.
Data-stream reconciliation across production capacity announcements, retail audit velocity, and import-export flows informed the analytical framework. Segmentation dimensions modeled include product type, distribution channel, price tier, and end-user demographic across the analysis window. CAGRs derived from curve-fitting historical volume trajectories against regulatory milestone impacts and technology adoption S-cycles. Forecast inputs incorporated aseptic line commissioning lead times and EFSA approval pipeline velocity.
Inputs from EFSA submission databases and national Extended Producer Responsibility registries were available through the study window; gaps in real-time botanical extract inventory positions introduce uncertainty bands around input cost assumptions. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology adoption rates. Supply disruption in Argentinian yerba mate or Madagascan vanilla regions, plus German deposit-return harmonization delays, warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
GCC Sports and Energy Drinks Market
Beverages
Fusion Beverages Market
Beverages
Packaged Coconut Water Market
Beverages
GCC Bottled Water Market
Beverages
Low Fat Drinks Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
Fruit Juice Market
Beverages
Spring Water Market
Beverages
Italy Bottled Water Market
Beverages
Extra Virgin Olive Oil Market
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
Superfood Infused Beverages Market
Beverages
Citrus Water Market
Beverages
Global Vinegar Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
Caffeinated Beverage Market