
 South East Asia Bottled Water Market | 2026-2036
South East Asia Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
South East Asia Bottled Water Market Analytics
Office procurement teams are reorganizing bottled water purchasing away from single-serve retail formats toward bulk dispenser systems and refillable gallon containers. Danone S.A. leverages its regional manufacturing footprint to supply institutional clients across Indonesia and Vietnam. Fraser & Neave Holdings Bhd anchors its competitive position through deep convenience store penetration in Malaysia and Singapore. Suntory PepsiCo Vietnam Beverage Co. Ltd. dominates the northern Vietnamese market through direct-store-delivery logistics networks.
Bottled water in South East Asia refers to potable water sealed in food-grade containers, processed through reverse osmosis, ultraviolet treatment, or ozonation to meet microbiological safety thresholds, and sold for immediate consumption without further treatment. Still water commands the largest product type share due to price accessibility and daily consumption habits across tropical climates. Plastic bottles sustain volume leadership in packaging type despite regulatory pressure, while glass bottles capture premium positioning in restaurant and hotel channels. Online retail represents the fastest-growing distribution channel, driven by platform consolidation and subscription-based household replenishment models.
Indonesia's BPOM, Vietnam's Ministry of Health, and Thailand's FDA enforce divergent mineral content disclosure and packaging material standards, fragmenting compliance costs for multinational operators. The EU Green Deal's extraterritorial influence shapes PET recycling mandates and extended producer responsibility frameworks adopted by ASEAN member states. Stakeholders must monitor evolving national labeling requirements and recyclability quotas to secure shelf access across fragmented regulatory jurisdictions.
Market Dynamics
Office procurement teams across South East Asia are reorganizing purchasing away from single-serve retail formats toward bulk dispenser systems and refillable gallon containers as hybrid work patterns stabilize. This structural shift compresses unit economics while elevating logistics complexity for bottlers serving institutional accounts.
Growth Catalysts
- Mineral Content Labeling Mandates:Indonesia's BPOM enforces stricter disclosure standards, forcing reformulation investments that upgrade product quality across the regional supply base.
- PET Recycling Infrastructure:Vietnam's Mekong Delta manufacturing corridor expands reprocessing capacity to serve Ho Chi Minh City distribution hubs, creating circular material loops.
- Direct-Store-Delivery Networks:Northern Vietnamese beverage distributors deploy route-optimization technology to penetrate convenience store channels with same-day replenishment.
Market Restraints
- Resin Price Volatility:PET feedstock costs fluctuate with crude oil benchmarks, squeezing margin predictability for bottlers operating on annual procurement contracts.
- Regulatory Fragmentation:Divergent mineral content standards between Indonesia's BPOM, Vietnam's Ministry of Health, and Thailand's FDA multiply compliance testing burdens.
- Tap Water Infrastructure:Municipal pipeline upgrades in Malaysian urban centers reduce perceived safety gaps, eroding the convenience premium for still water.
Strategic Opportunities
- Subscription Replenishment Models:Platform consolidation in Indonesian e-commerce enables household auto-replenishment programs with predictive delivery scheduling.
- EU Green Deal Alignment:Extended producer responsibility frameworks adopted by ASEAN member states reward early PET recyclability investments with preferential shelf access.
- Glass Bottle Premium Positioning:Restaurant and hotel channels in Singapore and Bangkok differentiate through imported mineral water in reusable glass packaging.
Industry Challenges
- Reverse Osmosis Technician Scarcity:Bottlers struggle to hire certified maintenance engineers for membrane replacement and calibration protocols.
- Cross-Border Label Harmonization:Multinational operators face 12-18 month adaptation timelines to synchronize packaging artwork across national regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South East Asia Bottled Water Market |
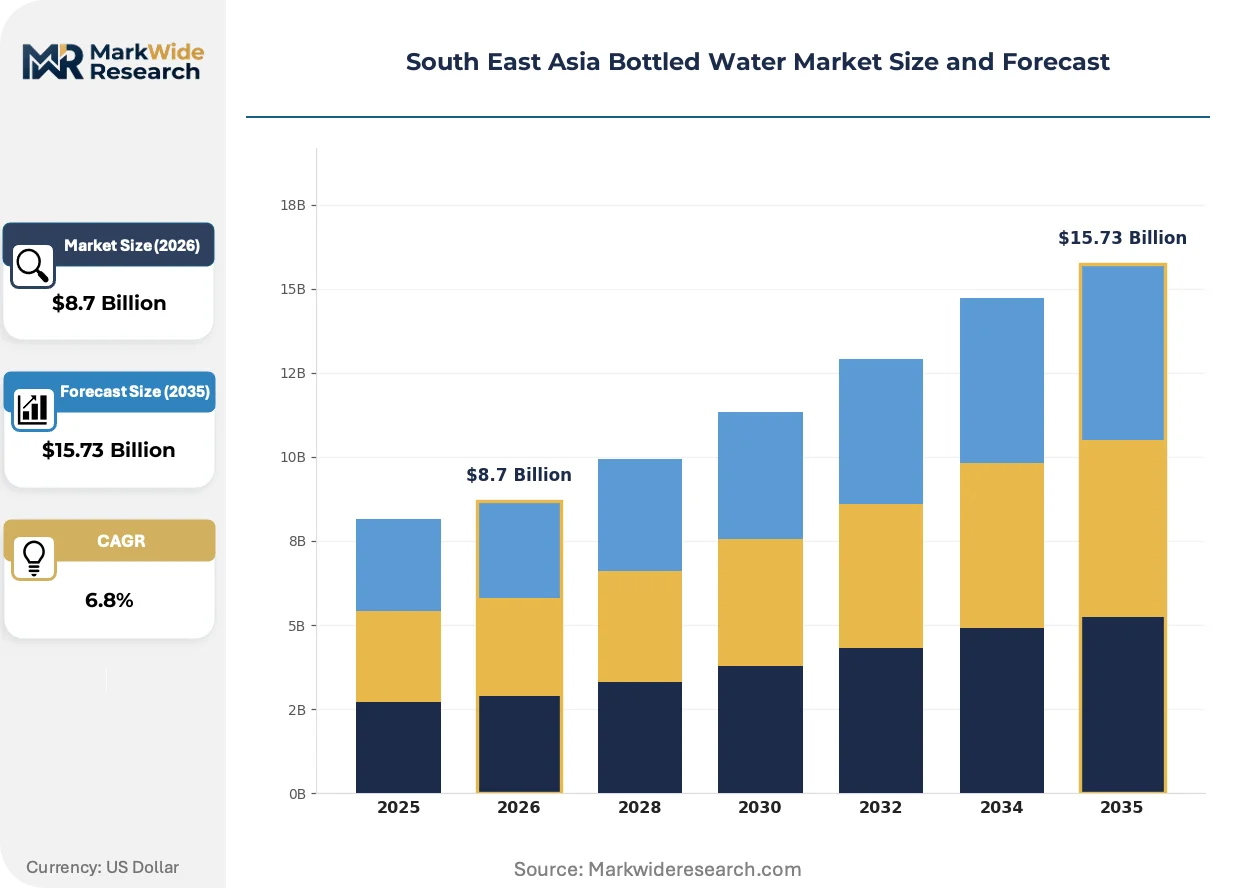
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Still Water, Sparkling Water, Flavored Water, Mineral Water End User: Retail Consumers, Offices, Restaurants, Events Packaging Type: Plastic Bottles, Glass Bottles, Cartons, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Vending Machines |
| Companies Covered | Danone S.A., The Coca-Cola Company, Nestle S.A., PepsiCo. Inc., Spritzer Bhd, Fraser & Neave Holdings Bhd, Asia Brewery Incorporated, Vinh Hao Mineral Water Corporation, Suntory PepsiCo Vietnam Beverage Co. Ltd., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South East Asia Bottled Water Market Evolving Landscape
Ultraviolet treatment systems and ozonation protocols are advancing rapidly across South East Asian bottling facilities, reshaping microbiological safety thresholds while reducing chemical dependency. These technology shifts intersect with packaging material transitions and procurement model evolution.
Ultraviolet LED sterilization technology is miniaturizing from industrial-scale systems to point-of-use dispensers. Office facility managers in Jakarta and Manila are retrofitting breakroom units with compact UV modules that eliminate chlorine residual taste. This hardware compression is enabling dispenser placement in smaller floorplates previously excluded by footprint constraints.
Thailand's FDA revised its bottled water quality standards to mandate quarterly microbiological testing with public disclosure requirements. The regulation forces mid-tier bottlers to invest in in-house laboratory capacity or third-party certification contracts. Still water products bearing updated compliance marks are capturing shelf preference in Bangkok's modern trade channels.
Household replenishment behavior is fragmenting between scheduled delivery subscriptions and impulse convenience purchases. Younger consumers in Vietnamese urban centers favor platform-based gallon exchanges with app-tracked delivery windows. This channel bifurcation pressures bottlers to maintain parallel logistics networks with incompatible cost structures.
South East Asia Bottled Water Market Segmentation
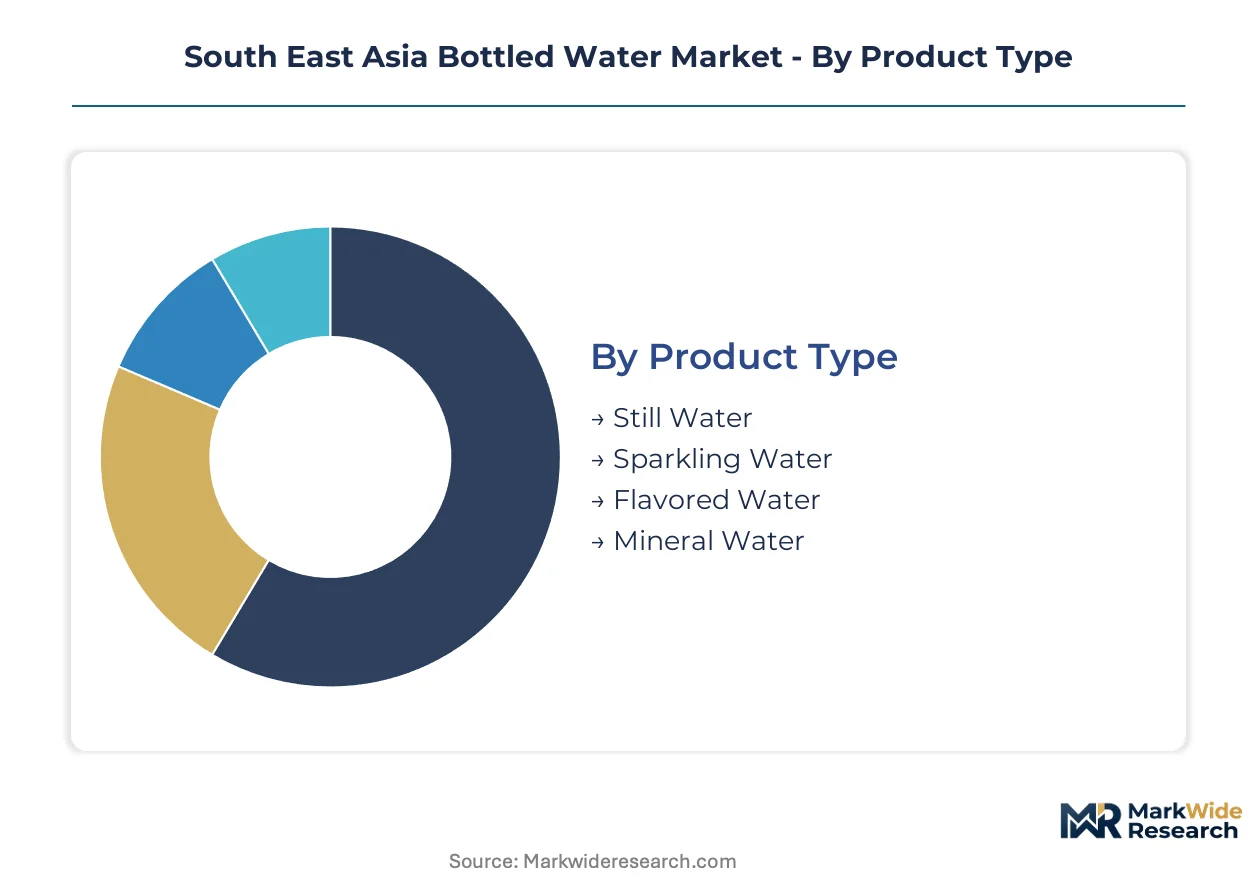
Segmentation in South East Asia's bottled water market reveals how procurement patterns diverge across tropical consumption habits, institutional purchasing reforms, and regulatory pressure on packaging materials. Understanding these divides exposes where margin pools concentrate and which logistics investments yield shelf access.
Product Type:
Still water dominates domestic consumption across Indonesia, Vietnam, and Thailand, while mineral water and sparkling variants find stronger traction in Singapore's export-oriented hospitality sector and cross-border retail channels.
- Still Water:Un-carbonated potable water processed through reverse osmosis or UV treatment, meeting microbiological safety thresholds without added minerals. Demand concentrates in Vietnam's Mekong Delta manufacturing corridor, where local bottlers expand PET recycling capacity to serve Ho Chi Minh City distribution hubs facing daily hydration requirements in tropical climates.
- Mineral Water:Naturally sourced or artificially mineralized water with disclosed calcium, magnesium, and sodium content per Indonesia's BPOM labeling mandates. Singapore and Bangkok hotels source imported European and Australian brands in glass packaging to differentiate premium positioning, though domestic bottlers in Indonesia's volcanic highlands are reformulating to capture this tier.
- Sparkling Water:Carbonated variants targeting urban professionals and restaurant channels in Kuala Lumpur and Jakarta. The segment relies on imported carbonation equipment and faces higher logistics costs due to pressurized container requirements.
- Flavored Water:Low-calorie infused variants with fruit essences or herbal extracts, primarily distributed through convenience stores in Manila and Bangkok. Younger consumers drive trial, though repeat purchase rates trail unflavored alternatives.
Still water commands the established base. The steepest expansion runs through mineral water as labeling transparency upgrades reshape quality perceptions.
End User:
Cost tier stratification separates high-frequency, low-margin household replenishment from negotiated institutional contracts with diverging logistics requirements and payment terms.
- Retail Consumers:Individual households purchasing single-serve bottles or gallon refills through supermarkets, convenience stores, and platform-based delivery. Younger Vietnamese urbanites favor app-tracked subscription exchanges with predictive scheduling, fragmenting replenishment behavior away from impulse purchases.
- Offices:Corporate procurement teams reorganizing toward bulk dispenser systems and refillable gallon containers as hybrid work patterns stabilize across Jakarta, Manila, and Kuala Lumpur. This shift compresses unit economics while elevating route-optimization requirements for bottlers serving institutional accounts.
- Restaurants:Foodservice operators in Singapore and Bangkok differentiating through imported mineral water in reusable glass packaging, while mid-tier establishments in Indonesia and Vietnam prioritize cost-efficient still water in plastic bottles for table service.
- Events:Temporary consumption spikes at concerts, conferences, and sporting gatherings requiring mobile refrigeration and rapid-deployment logistics. Post-pandemic event volume recovery remains uneven across national markets.
Retail consumers generate volume foundations. Office procurement is shifting fastest as hybrid work stabilization rewires institutional purchasing protocols.
Packaging Type:
Volume scale and recyclability mandates drive diverging investment priorities, with plastic sustaining mass-market leadership while glass and alternative materials capture premium positioning and regulatory compliance advantages.
- Plastic Bottles:PET containers dominating volume leadership despite regulatory pressure from EU Green Deal-influenced extended producer responsibility frameworks adopted by ASEAN member states. Vietnam's Mekong Delta bottlers are expanding reprocessing capacity to create circular material loops serving Ho Chi Minh City hubs.
- Glass Bottles:Premium positioning in restaurant and hotel channels across Singapore and Bangkok, with higher per-unit costs offset by deposit-return schemes and reusable logistics. Weight and fragility limit geographic reach beyond urban centers.
- Cartons:Aseptic packaging gaining trial in Indonesian and Malaysian supermarket channels for family-size still water, though recycling infrastructure for composite materials remains underdeveloped relative to PET.
- Pouches:Flexible film packaging for low-cost single-serve distribution in rural Indonesian and Philippine markets, with limited shelf stability and higher leakage rates constraining premium channel penetration.
Plastic bottles anchor volume scale. Glass packaging is climbing the fastest as hospitality channels prioritize premium differentiation and circular material credentials.
Distribution Channel:
Customer type fragmentation pressures bottlers to maintain parallel logistics networks with incompatible cost structures, from high-frequency direct-store-delivery to scheduled subscription replenishment.
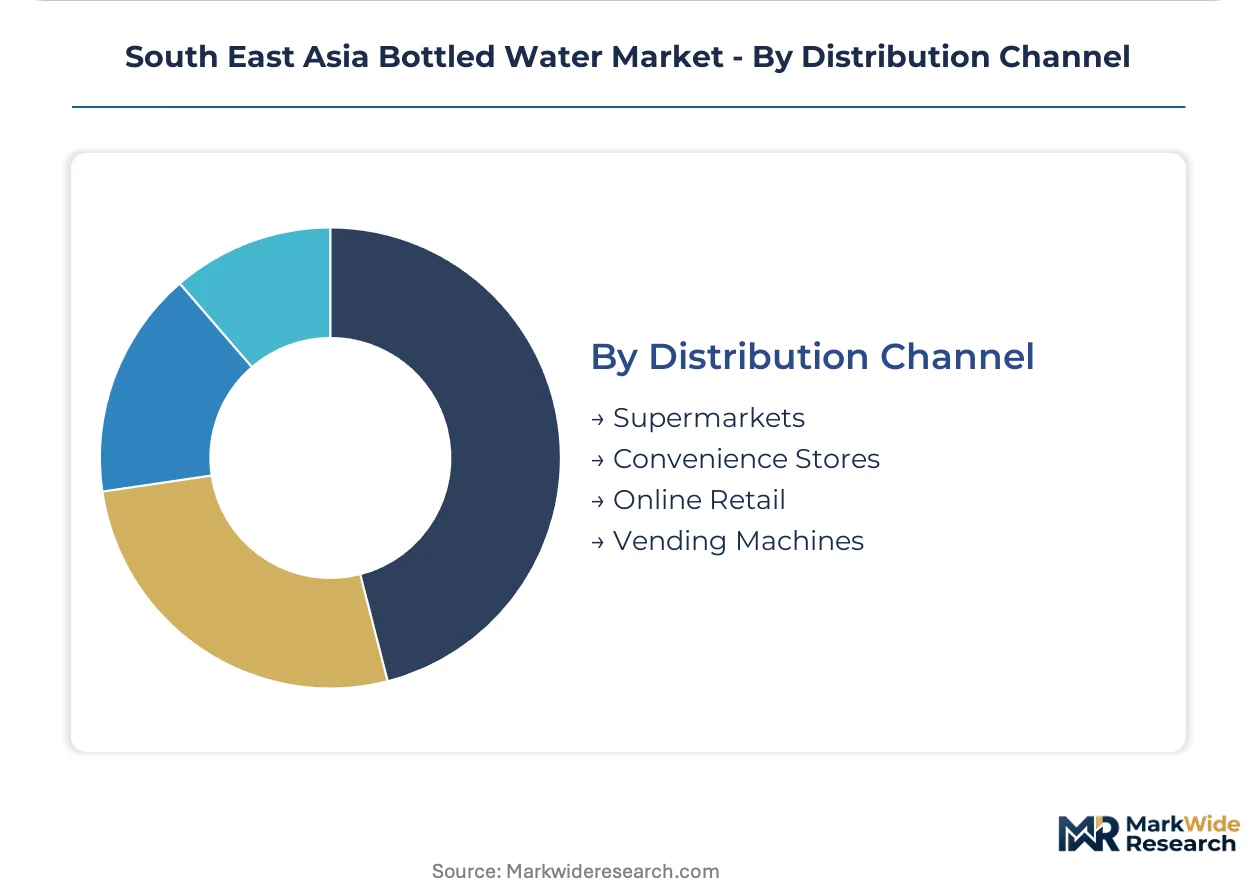
- Supermarkets:Modern trade channels in Bangkok and Jakarta capturing planned household stock-up trips, with shelf space allocation increasingly tied to recyclability certifications and mineral content disclosure compliance.
- Convenience Stores:High-margin impulse purchases in 24-hour urban outlets across Malaysia and Singapore, replenished through direct-store-delivery networks with same-day restitution requirements. Fraser & Neave Holdings Bhd anchors competitive position through deep penetration in this channel.
- Online Retail:Platform consolidation in Indonesian e-commerce enabling household auto-replenishment programs with predictive delivery scheduling. This channel is expanding most quickly as subscription models lock in recurring revenue and reduce customer acquisition costs.
- Vending Machines:Automated dispensing in office buildings, transit stations, and educational campuses, with cashless payment integration advancing rapidly in Vietnamese and Thai urban centers. Machine placement density remains concentrated in premium real estate locations.
Supermarkets and convenience stores retain the established base. Online retail shows the steepest expansion trajectory as platform consolidation and subscription mechanics reshape household replenishment behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate procurement teams and household subscribers dominate demand across South East Asia's tropical markets, with institutional buyers in Jakarta, Manila, and Kuala Lumpur driving bulk dispenser adoption while Vietnamese and Indonesian consumers accelerate platform-based replenishment.
Indonesia
Household auto-replenishment programs and office dispenser retrofits power demand in Jakarta and Surabaya. BPOM enforces stricter mineral content labeling standards, forcing cross-border brands into reformulation investments. Local bottlers in Java's volcanic highlands expand production to capture premium mineral water positioning.
Vietnam
Direct-store-delivery networks and app-tracked gallon exchanges reshape consumption in Ho Chi Minh City and Hanoi. The Ministry of Health mandates divergent mineral disclosure protocols from neighboring jurisdictions. Mekong Delta manufacturing clusters build PET reprocessing capacity to serve southern distribution hubs.
Thailand
Modern trade shelf space and hospitality procurement sustain volume in Bangkok and Chiang Mai. FDA quarterly microbiological testing mandates with public disclosure requirements pressure mid-tier bottlers into laboratory investments. Eastern seaboard industrial zones host upgraded ozonation and UV treatment facilities.
Malaysia
Convenience store penetration and suburban household stock-up trips anchor demand in Kuala Lumpur and Penang. Municipal pipeline upgrades in urban centers erode perceived safety gaps for still water. Northern manufacturing corridors supply PET containers to cross-border Singapore distribution.
Singapore
Premium restaurant and hotel channels drive imported mineral water demand in glass packaging. Extended producer responsibility frameworks aligned with EU Green Deal standards reward recyclability investments. Central distribution hubs facilitate re-export to regional hospitality networks.
South East Asia Bottled Water Market Competitive Landscape
Player mix skews toward multinational beverage conglomerates with regional manufacturing footprints and local bottlers with deep convenience store penetration. Market structure concentrates around three strategic archetypes: diversified multinational operators leveraging cross-category distribution, national champions anchored in specific channel dominance, and mid-tier specialists pursuing premium mineral positioning. Competitive moves center on direct-store-delivery network expansion and PET recycling infrastructure integration.
Among multinational operators, Danone S.A. and PepsiCo. Inc. occupy positions exemplifying diversified beverage portfolio leverage across institutional and retail channels. Fraser & Neave Holdings Bhd represents the national champion archetype through convenience store channel anchoring. Suntory PepsiCo Vietnam Beverage Co. Ltd. sits within the territory-specialist tier, illustrating how joint venture structures combine global brand equity with localized logistics execution.
| Leading Market Players |
|---|
| Danone S.A. |
| The Coca-Cola Company |
| Nestle S.A. |
| PepsiCo. Inc. |
| Spritzer Bhd |
| Fraser & Neave Holdings Bhd |
| Asia Brewery Incorporated |
| Vinh Hao Mineral Water Corporation |
| Suntory PepsiCo Vietnam Beverage Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Fourteen-day inventory cycles for PET resin stockpiles concentrate pricing leverage with Vietnam's Mekong Delta manufacturing clusters, where bottlers serving Ho Chi Minh City distribution hubs negotiate annual procurement contracts against crude oil benchmark volatility. This lead-time compression ties input cost exposure directly to regional polymer supply concentration, amplifying margin pressure when feedstock prices spike.
Pricing Analysis
Current-generation ultraviolet treatment systems command a 15-20% premium over legacy ozonation infrastructure, while next-generation LED sterilization modules remain in pilot deployment. Three-tier pricing structure across premium mineral, standard still, and economy bulk dispenser levels segments buyers by certification grade and delivery reliability. Price erosion runs through the economy tier as Indonesian local bottlers expand PET recycling capacity and compress per-unit costs. Household subscribers show highest price sensitivity, while Singapore hospitality procurement teams prioritize mineral content transparency over per-liter rates.
Supply Chain Analysis
Indonesia and Vietnam anchor PET bottle manufacturing, with Thailand's eastern seaboard hosting upgraded ozonation and UV treatment facilities. Raw material flows draw from Singapore resin traders, Malaysian labeling converters, and domestic mineral extraction in Java's volcanic highlands. Single-source vulnerability concentrates in imported carbonation equipment for sparkling water variants, with European and Japanese suppliers dominating pressurized system technology. Distribution runs through parallel networks: direct-store-delivery for convenience store replenishment and platform-coordinated subscription exchanges for household gallon refills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South East Asia's bottled water market sits in early-cycle expansion as hybrid work stabilization institutionalizes bulk dispenser procurement and platform-based subscription models penetrate Indonesian and Vietnamese urban households.
For Market Incumbents: Secure route-optimization technology investments to defend institutional account margins against logistics complexity from hybrid office footprints. Anchor shelf access through preemptive compliance with Indonesia's BPOM mineral disclosure mandates before cross-border competitors complete reformulation timelines. Deepen convenience store penetration in Malaysia and Singapore where Fraser & Neave Holdings Bhd has established channel control. For New Entrants and Emerging Players: BPOM certification fast-track programs in Indonesia's volcanic highlands offer the most penetrable entry vector for premium mineral water positioning. Target Vietnam's northern provinces where Suntory PepsiCo Vietnam Beverage Co. Ltd.'s direct-store-delivery network shows coverage gaps in secondary cities. Launch app-tracked gallon exchange platforms with predictive scheduling to capture younger Vietnamese urbanites fragmenting away from impulse purchases. For Investors and Strategic Acquirers: Long-term, this sits as a circular infrastructure play because ASEAN extended producer responsibility frameworks reward early PET recyclability investments with preferential shelf access. Acquisition targets should cluster around Mekong Delta manufacturing clusters with captive reprocessing capacity. The signal to watch is quarterly microbiological testing compliance marks capturing shelf preference in Bangkok's modern trade channels.| Strategic Initiative | Industry Significance |
|---|---|
| PET Recycling Infrastructure Expansion | Vietnam's Mekong Delta bottlers create circular material loops serving Ho Chi Minh City distribution hubs. |
| Direct-Store-Delivery Network Upgrade | Route-optimization technology penetration captures same-day replenishment requirements in Malaysia's convenience store channel. |
| Mineral Content Certification Investment | BPOM compliance marks differentiate shelf positioning in Jakarta's modern trade and hospitality procurement. |
| Subscription Platform Integration | Predictive scheduling mechanics lock in recurring revenue from Indonesian household auto-replenishment programs. |
| UV LED Dispenser Deployment | Compact sterilization modules enable office retrofit opportunities in smaller Jakarta and Manila floorplates. |
Research Methodology
Operator-level perspectives from bottling plant managers, convenience store category buyers, office facility procurement heads, and PET recycling facility operators anchored the qualitative base. These primary inputs combined with secondary validation from BPOM disclosure filings, Vietnam Ministry of Health regulatory circulars, Thai FDA microbiological testing records, and ASEAN customs trade data. Bottom-up volume triangulation across product type, packaging format, and distribution channel intersected with top-down macroeconomic elasticity modeling.
Sensitivity analysis across resin price volatility bands and hybrid work adoption scenarios shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, end-user archetype, packaging material, and distribution channel complexity. CAGRs derived from historical trajectory analysis adjusted for structural shifts in institutional procurement patterns and platform-based subscription penetration. Forecast inputs incorporated PET reprocessing capacity buildout timelines and regulatory compliance cost burdens across national jurisdictions.
Underlying assumptions cover hybrid work stabilization, EU Green Deal influence on ASEAN extended producer responsibility adoption, and mineral content labeling harmonization timelines, with deviation risk concentrated in municipal tap water infrastructure upgrades eroding still water convenience premiums. Recalibration cycles align with material shifts in BPOM enforcement intensity, platform consolidation outcomes, and PET feedstock price regime changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Beverages Market
Beverages
GCC Coconut Water Market
Beverages
Collagen Drinks Market
Beverages
Europe Bottled Water Processing Market
Beverages
Semillon Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Beverage Cooler Market
Beverages
Packaged Coconut Water Market
Beverages
Reconstituted Juice Market
Beverages
Europe Yerba Mate Market
Beverages
Water Bottle Market
Beverages
Saudi Arabia Food & Beverage Market
Beverages
Bottled Deep Ocean Water Market
Beverages
Nitro-Infused Beverages Market
Beverages
Bangladesh Energy Drinks Market