
 Sparkling Soda Market | 2026-2036
Sparkling Soda Market Size, Share, and Industry Trends Forecast 2026-2036
Sparkling Soda Market Analytics
Natural sweeteners including stevia and monk fruit extracts is restructuring cost structures across mid-tier sparkling soda portfolios. The Coca-Cola Company leverages its captive stevia supply chain to stabilize input costs across Latin American bottling operations. PepsiCo sustains formulation R&D intensity through dedicated beverage innovation centers in North America and Europe. National Beverage Corp. differentiates through aggressive flavor experimentation that occupies a distinct niche between mass-market and premium craft positioning.
Sparkling soda denotes carbonated water infused with flavoring agents, sweeteners, and acidulants, typically containing dissolved carbon dioxide at two to four volumes for palate-appropriate effervescence, produced through cold-fill or tunnel-pasteurization processes depending on preservative content. Its primary commercial purpose centers on delivering refreshment in single-serve and multi-serve formats across at-home and away-from-home occasions. Flavored variants generate disproportionate margin pools as consumers trade up from standard cola-lemon-lime profiles toward botanical and exotic fruit formulations. Cans dominate packaging economics in North American convenience channels, while glass bottles sustain premium positioning in European retail and on-premise accounts where deposit-return systems reinforce circular packaging preferences.
The FDA governs added-sugar disclosure and GRAS status for novel sweeteners in US sparkling soda formulations, while the EU Green Deal packaging directives and national deposit schemes across Germany, Sweden, and Denmark reshape material choices for brands operating in European markets. Health Canada and PMRA coordinate on caffeine limits and natural health product claims that constrain functional positioning in Canadian retail channels. Stakeholders must monitor evolving front-of-pack labeling requirements across multiple jurisdictions, as regulatory divergence between sugar-warning schemes and nutrient-profile models threatens to fragment formulation strategies and complicate pan-regional brand architecture decisions.
Market Dynamics
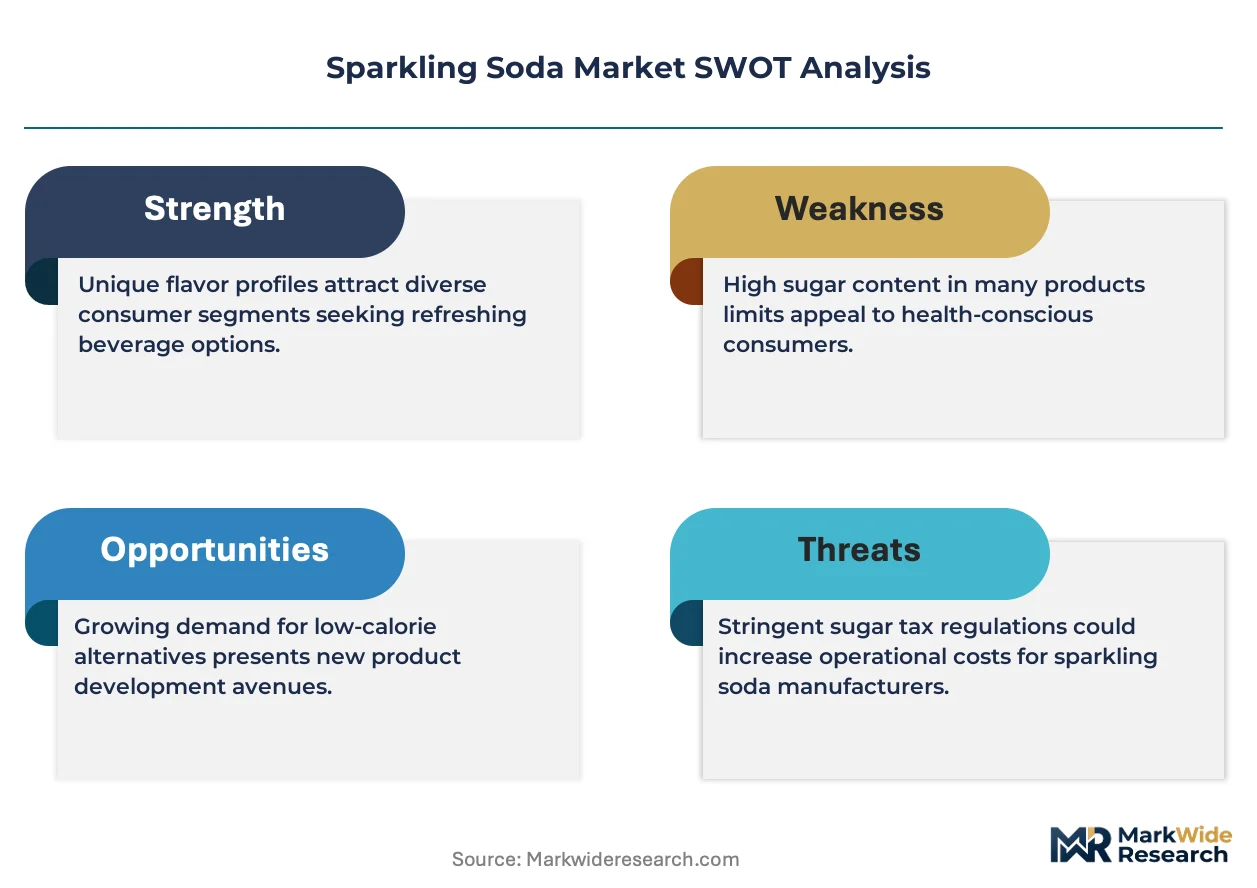
Sugar-reduction mandates from health regulators across multiple jurisdictions are compressing formulation flexibility and forcing bottlers to rebuild ingredient supply chains around natural sweetener alternatives.
Growth Catalysts
- EU Green Deal packaging directives:Deposit-return systems in Germany, Sweden, and Denmark are accelerating circular packaging investments that reduce virgin material exposure for brands operating across European markets.
- On-premise beverage program upgrades:Restaurants and cafés are expanding carbonated offerings as consumer preference shifts toward premium sparkling options in foodservice channels.
- Brazil urban center expansion:Local bottlers and international brands compete aggressively for share of throat in growing metropolitan areas, concentrating demand generation in South America's largest consumer market.
Market Restraints
- Stevia and monk fruit input cost volatility:Natural sweetener supply concentration in specific growing regions creates margin pressure when harvest yields fluctuate.
- GRAS status uncertainty for novel sweeteners:FDA review timelines for new natural alternatives extend formulation lock-in periods and delay product pipeline advancement.
- Functional beverage substitution:Enhanced waters and kombucha variants capture health-conscious consumers seeking lower-sugar refreshment with added functional claims.
Strategic Opportunities
- Botanical and exotic fruit formulation white space:Flavored variants generate disproportionate margin pools as consumers trade up from standard cola-lemon-lime profiles toward differentiated taste experiences.
- Glass bottle premium positioning:European retail and on-premise accounts sustain higher price realization where deposit-return systems reinforce circular packaging preferences.
- Health Canada caffeine limit harmonization:Coordinated natural health product claim pathways with PMRA create regulatory clarity for functional sparkling soda positioning in Canadian channels.
Industry Challenges
- Tunnel-pasteurization equipment retooling:Preservative-free formulation shifts require capital-intensive production line modifications that strain mid-tier bottler balance sheets.
- Front-of-pack labeling divergence:Sugar-warning schemes in some jurisdictions conflict with nutrient-profile models in others, fragmenting pan-regional brand architecture decisions and complicating unified marketing execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sparkling Soda Market |
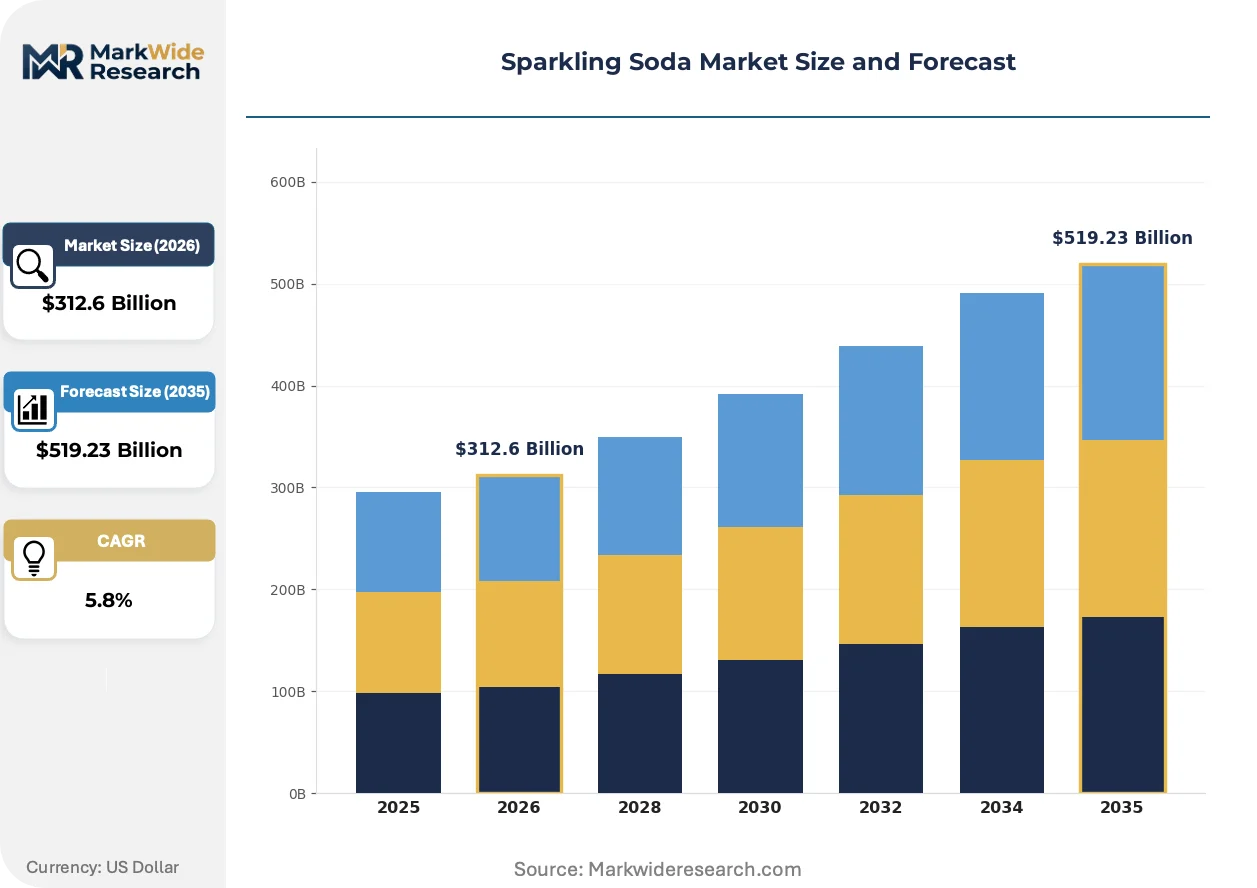
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Diet, Flavored, Organic Packaging Type: Cans, Bottles, Tetra Packs, Kegs End User: Retail Consumers, Restaurants, Cafés, Events Distribution Channel: Supermarkets, Online, Convenience Stores, Vending Machines |
| Companies Covered | The Coca-Cola Company, PepsiCo, Keurig Dr Pepper, National Beverage Corp., SodaStream, Jones Soda Co., Danone, Anadolu Group, Polar Beverages, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sparkling Soda Market Evolving Landscape
Reformulation around natural sweetener systems is restructuring cost structures and competitive positioning across mid-tier and premium sparkling soda portfolios.
Cold-fill carbonation technology is absorbing flavor-sensitive botanical formulations that degrade under thermal processing. Premium craft-positioned bottlers are adopting these systems to preserve volatile aromatic compounds in limited-run releases. The technology is absorbing margin compression from shorter production runs while enabling price premiums in specialty retail channels.
REACH chemical safety registrations for novel acidulants are tightening formulation disclosure requirements across EU member states. Manufacturers must submit extended safety dossiers for alternative acid systems replacing traditional phosphoric acid. Brands targeting German and Scandinavian markets are responding by accelerating clean-label acidulant transitions ahead of compliance deadlines.
Direct-to-foodservice distribution partnerships are consolidating procurement decisions for fountain and pre-packaged sparkling programs. National restaurant chains are centralizing beverage category management, displacing fragmented local distributor relationships. Brazil and select US metropolitan clusters exhibit the most pronounced buyer concentration, with contract duration extending to secure supply stability.
Sparkling Soda Market Segmentation
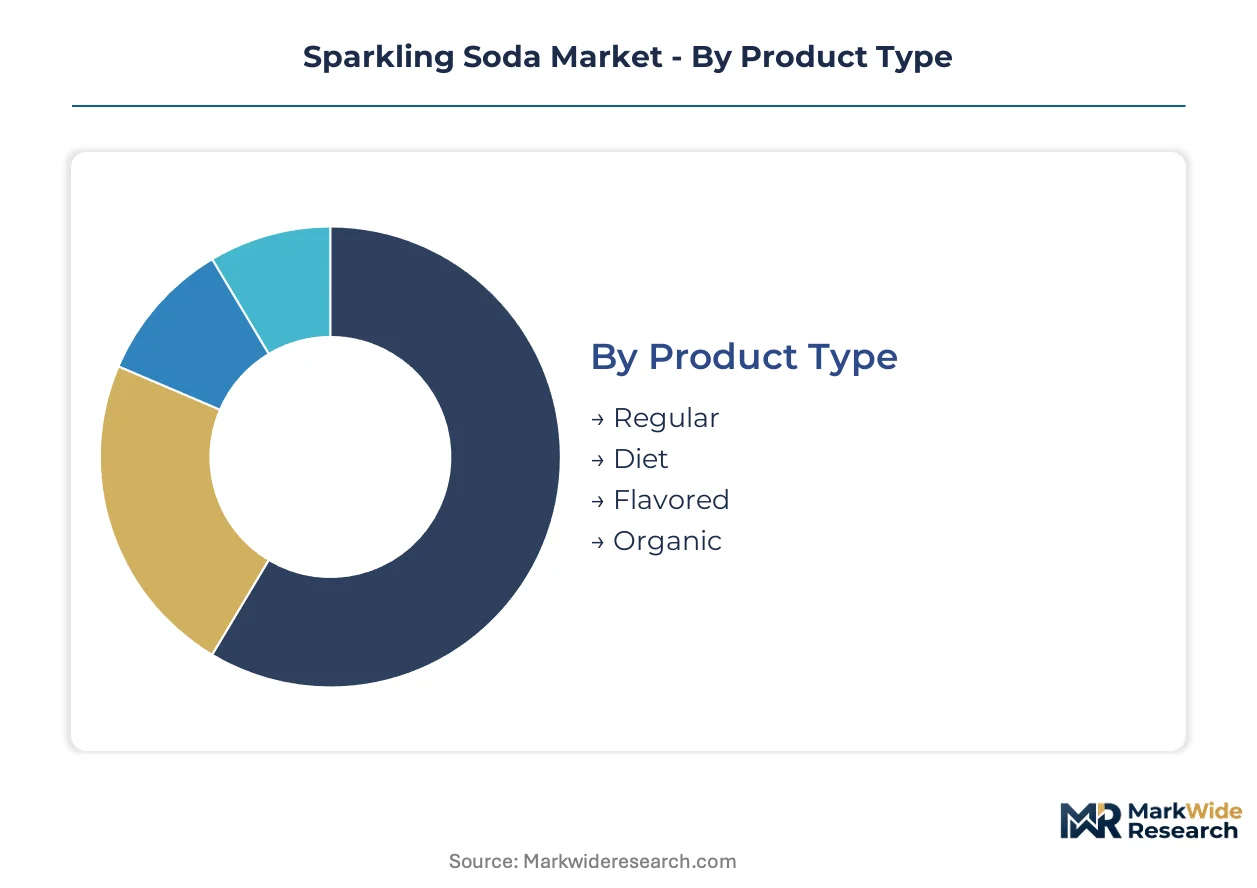
Sparkling soda segmentation reveals how formulation choices, packaging economics, and channel access fragment purchasing behavior across consumer occasions. Manufacturers align R&D and supply chain investments against these divides to capture margin pools.
Product Type:
Buyers in this category separate by health orientation and willingness to pay for ingredient provenance versus standard refreshment.
- Regular:Full-sugar formulations with dissolved carbon dioxide at two to four volumes. Volume concentrates in Brazil's expanding urban centers where local bottlers and international brands compete aggressively for share of throat.
- Diet:Zero-calorie variants using artificial or natural sweetener systems. Demand is tilting toward stevia-based formulations as FDA GRAS timelines and sugar-reduction mandates compress formulation flexibility across multiple jurisdictions.
- Flavored:Botanical and exotic fruit infusions commanding disproportionate margin pools.
- Organic:Certified ingredient sourcing with restricted additive profiles.
Volume sits with Regular; growth tilts toward Flavored as consumers trade up from cola-lemon-lime profiles.
Packaging Type:
Channel economics and circular infrastructure availability determine which formats capture procurement decisions.
- Cans:Aluminum single-serve containers dominating North American convenience channel economics through lightweight logistics and recycling stream density.
- Bottles:Glass and PET variants sustaining premium price realization in European retail and on-premise accounts where deposit-return systems reinforce circular packaging preferences.
- Tetra Packs:Aseptic cartons for ambient distribution in emerging market retail.
- Kegs:Stainless steel returnable containers for fountain and foodservice carbonation systems.
Procurement concentrates in Cans; expansion tilts toward Bottles as EU Green Deal packaging directives accelerate circular investments.
End User:
Occasion-based consumption patterns split between at-home replenishment and away-from-home refreshment moments.
- Restaurants:Full-service dining accounts upgrading carbonated beverage programs as on-premise consumption recovers. Demand is expanding most quickly here as operators trade up to premium sparkling options.
- Cafés:Coffee-forward formats integrating sparkling sodas into all-day beverage menus.
- Retail Consumers:Household pantry stocking and immediate consumption purchases.
- Events:Stadium, festival, and catering bulk procurement with seasonal concentration.
Volume rests with Retail Consumers; momentum accumulates in Restaurants as beverage program upgrades concentrate procurement decisions.
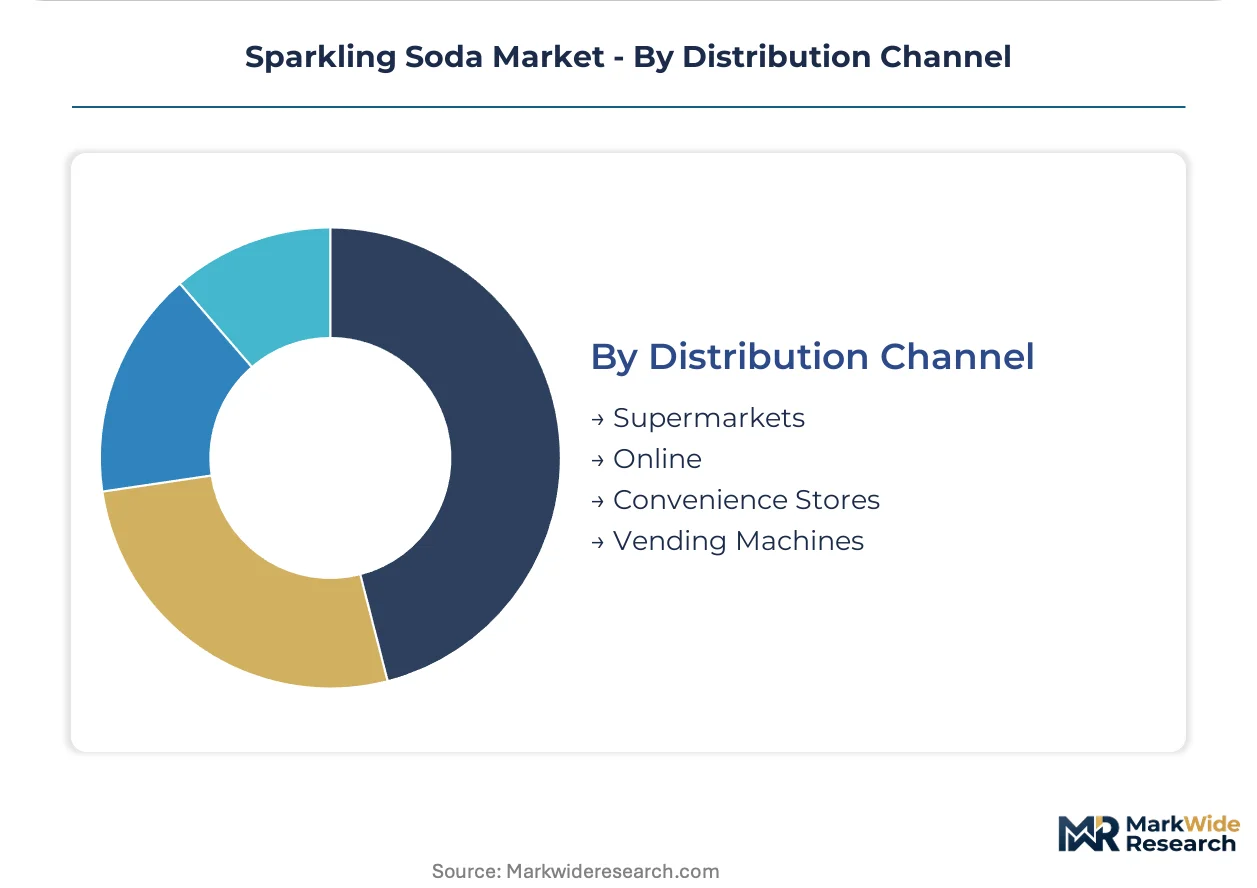
Distribution Channel:
Route-to-market selection reflects shopper mission type and impulse versus planned purchase behavior.
- Supermarkets:Multi-pack destination shopping with promotional intensity driving volume. Shelf space allocation favors established brand portfolios with proven velocity metrics.
- Online:Direct-to-consumer and third-party platform sales with subscription model potential.
- Convenience Stores:Immediate consumption occasions with single-serve can dominance.
- Vending Machines:Automated retail in workplaces, transit hubs, and educational institutions.
Transaction density clusters in Supermarkets; share capture is accelerating in Online as digital grocery penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most intensely in Brazil, where local bottlers and international brands compete aggressively for share of throat in expanding urban centers. This South American concentration shapes supply chain investments and flavor localization strategies across the industry.
United States
Restaurants and cafés are upgrading on-premise beverage programs as consumer preference shifts toward premium sparkling options. FDA GRAS review timelines for novel natural sweeteners extend formulation lock-in periods and compress R&D pipeline velocity. Atlanta-based The Coca-Cola Company leverages captive stevia supply chains to stabilize input costs across Latin American bottling operations.
Brazil
Urban center expansion in São Paulo and Rio de Janeiro concentrates demand generation for both regular and flavored variants. ANVISA sugar-reduction mandates are compressing formulation flexibility and forcing bottlers to rebuild ingredient supply chains around stevia and monk fruit alternatives. Local bottlers compete head-to-head with international brands for shelf space in expanding metropolitan retail channels.
Germany
Deposit-return systems accelerate circular packaging investments that reduce virgin material exposure for brands operating across European markets. EU Green Deal packaging directives and REACH chemical safety registrations for novel acidulants tighten formulation disclosure requirements. Berlin and Hamburg retail accounts sustain premium price realization for glass bottles where circular infrastructure reinforces consumer preferences.
Canada
Health Canada and PMRA coordinate on caffeine limits and natural health product claims that constrain functional positioning in retail channels. Front-of-pack labeling requirements diverge from US standards, complicating unified North American brand architecture. Toronto and Vancouver metropolitan clusters exhibit pronounced buyer concentration as national restaurant chains centralize beverage procurement decisions.
United Kingdom
Sugar-warning schemes and nutrient-profile models create regulatory friction that fragments pan-regional formulation strategies. London and Southeast England foodservice channels drive demand for botanical and exotic fruit formulations that command disproportionate margin pools. Cold-fill carbonation technology adoption preserves volatile aromatic compounds in limited-run premium releases targeting specialty retail.
Sparkling Soda Market Competitive Landscape
Strategic partnerships dominate the current landscape as bottlers seek to secure natural sweetener supply stability and foodservice distribution access. The vendor base separates into three distinct tiers: multinational beverage conglomerates with captive ingredient supply chains, mid-tier regional bottlers with flexible flavor experimentation capabilities, and premium craft-positioned specialists with cold-fill production infrastructure. Competitive intensity manifests through M&A activity targeting distribution networks and technology licensing agreements for preservative-free formulation systems.
Among multinational beverage conglomerates, The Coca-Cola Company and PepsiCo occupy positions defined by scale-driven supply chain control and dedicated beverage innovation centers in North America and Europe. National Beverage Corp. exemplifies the mid-tier archetype through aggressive flavor experimentation that carves distinct positioning between mass-market and premium craft segments. These three anchors illustrate how competitive advantage derives from either upstream ingredient control, R&D intensity, or niche differentiation rather than overlapping strategic postures.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Keurig Dr Pepper |
| National Beverage Corp. |
| SodaStream |
| Jones Soda Co. |
| Danone |
| Anadolu Group |
| Polar Beverages |
| Others |
Value Network & Pricing Analysis
Stevia and monk fruit extract costs cascade through sparkling soda pricing tiers, with harvest volatility in specific growing regions compressing margins at the standard tier while premium botanical variants absorb input spikes through price inelasticity. Bottlers facing ANVISA sugar-reduction mandates in Brazil and FDA GRAS uncertainty in the United States rebuild formulation supply chains around these natural sweeteners, forcing a repricing of the entire category.
Pricing Analysis
Volume concentrates in regular full-sugar formulations where Brazilian urban consumers drive transaction density, while margins accumulate in flavored botanical variants commanding trade-up premiums. Three-tier pricing structure across premium glass-bottle European on-premise, standard aluminum can North American retail, and economy PET multi-pack emerging market tiers reflects packaging circular infrastructure availability and deposit-return system participation. Pricing pressure stems from stevia supply concentration in Paraguay and China harvest zones, with cost compression intensifying in mid-tier portfolios lacking captive ingredient sourcing. Retail consumers exhibit highest price sensitivity in supermarket promotional cycles, while restaurants and cafés demonstrate lowest sensitivity when upgrading beverage programs.
Supply Chain Analysis
Natural sweetener supply rests on Paraguayan stevia cultivation, Chinese monk fruit processing, and Brazilian cane sugar refining for residual regular formulations. Aluminum can sheet feeds from US and Canadian rolling mills, while glass bottle manufacturing concentrates in Germany, Italy, and France to serve EU deposit-return systems. Single-source vulnerability in stevia leaf extraction capacity creates bottleneck risk when climatic events disrupt South American harvests. Distribution runs through consolidated direct-to-foodservice partnerships in Brazil and US metropolitan clusters, with national restaurant chains displacing fragmented local distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural sweetener extraction capacity constraints prop pricing power for bottlers with backward-integrated supply relationships, as ANVISA and FDA regulatory timelines extend formulation lock-in periods.
For Market Incumbents: Deploy captive stevia supply chain leverage to stabilize input costs across Latin American bottling operations while accelerating cold-fill carbonation technology licensing to mid-tier partners. Defensive consolidation should prioritize distribution network acquisitions in Brazil's expanding urban centers where local bottlers threaten share of throat. Functional beverage substitution from enhanced waters and kombucha variants represents the primary demand-side threat requiring flavor innovation response. For New Entrants and Emerging Players: Launch via direct-to-foodservice distribution partnerships targeting national restaurant chain beverage program upgrades in São Paulo, Rio de Janeiro, and Toronto metropolitan clusters. Botanical and exotic fruit formulation white space offers the most penetrable segment, with cold-fill production infrastructure enabling limited-run premium positioning between mass-market and craft tiers. Go-to-market execution should emphasize deposit-return system participation in European markets to capture circular packaging preference premiums. For Investors and Strategic Acquirers: FDA GRAS approval acceleration for novel natural sweeteners is the leading indicator that formulation flexibility will expand and compress first-mover advantages in stevia-based portfolios. Long-term viability favors bottlers with backward-integrated ingredient sourcing and cold-fill production technology over asset-light brand licensors. Acquisition target archetype: mid-tier regional bottlers with flexible flavor experimentation capabilities and established foodservice distribution relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Stevia Supply Chain Development | Paraguayan cultivation partnerships insulate Brazilian bottlers from harvest yield volatility. |
| Cold-Fill Carbonation Technology Licensing | Preservative-free formulation systems enable premium botanical positioning in EU markets. |
| Direct-to-Foodservice Distribution Consolidation | National restaurant chain partnerships displace fragmented local distributor relationships. |
| Glass Bottle Circular Infrastructure Investment | German and Scandinavian deposit-return systems reinforce premium price realization. |
| Botanical Formulation R&D Expansion | Exotic fruit and botanical infusions capture trade-up margin pools from cola-lemon-lime migration. |
Research Methodology
Independent corroboration across bottler procurement executives, foodservice beverage program directors, and natural sweetener agronomists underwrites the qualitative findings in this study. Primary interviews with supply chain managers at Latin American bottling operations, category buyers at national restaurant chains, and regulatory affairs leads navigating FDA GRAS and ANVISA compliance were cross-referenced against customs trade data, SEC beverage segment filings, and EU packaging directive implementation records. Bottom-up volume triangulation from country-level bottler capacity and top-down value estimation from retail audit channels were reconciled to produce segment outputs.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects, with CAGRs derived from trend extrapolation of per-capita consumption, channel shift elasticities, and formulation trade-up coefficients. Segmentation modeling spans product type, packaging format, end-user occasion, and distribution channel, with regional regulatory cluster effects layered as overlay variables. Industry-specific forecast inputs include ANVISA sugar-reduction mandate implementation timelines and EU Green Deal packaging directive compliance deadlines.
Stevia harvest yield volatility, FDA GRAS review timeline extensions, and front-of-pack labeling scheme divergence are the dominant revision risks to the forecast framework. Forecasts reflect assumptions about regulatory implementation pacing and consumer trade-up elasticity that warrant sensitivity testing. A small set of named triggers—natural sweetener supply disruptions, carbonation equipment retooling cost spikes, and foodservice procurement centralization acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Asia-Pacific Energy Drink Market
Beverages
Solid Beverages Market
Beverages
Hot Chocolate Market
Beverages
Chocolate Malt Drink Market
Beverages
Ready to Drink Premixes Market
Beverages
North America Sugar Free Energy Drinks Market
Beverages
Water Bottle Market
Beverages
Detox Drinks Market
Beverages
GCC Coconut Water Market
Beverages
Reconstituted Juice Market
Beverages
Nitro-Infused Beverages Market
Beverages
Asia-Pacific Vinegar Market
Beverages
Botanical Infused Beverages Market
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
Germany Probiotic Drinks Market
Beverages
United States Smoothie Market