
 Almond Drink Market | 2026-2036
Almond Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Almond Drink Market Intelligence
Formulations with higher almond content and clean-label ingredients is bifurcating the market between premium and mass-market offerings. Blue Diamond Growers leverages its extensive almond farming cooperative for supply chain control. Danone S.A. operates across multiple price points with its Alpro and other brands, capturing a wide consumer base. Califia Farms specializes in the premium segment, focusing on unique flavor profiles and distinctive packaging.
Almond drink is a plant-based beverage made from ground almonds and water, often undergoing homogenization and pasteurization for stability and safety. Products are frequently fortified with nutrients like calcium, vitamin D, and vitamin E to enhance their nutritional value. Unsweetened product types are gaining significant traction among health-conscious consumers. While supermarkets constitute the primary distribution channel, the convenience of online retail is accelerating its share of sales.
Product labeling and health claims are governed by bodies such as the FDA in the United States and the European Food Safety Authority (EFSA). These agencies set strict guidelines on nutritional information and the use of terms like 'milk' on plant-based alternatives. Producers must navigate these evolving regulatory landscapes while investing in transparent sourcing to build consumer trust.
Market Dynamics
The market's structure is defined by a widening gap between premium and mass-market segments. This bifurcation stems from consumer demand for clean-label formulations with higher almond content, forcing separate supply chain and branding strategies for each tier.
Growth Catalysts
- Plant-Based Diet Adoption:The mainstreaming of veganism in developed nations like Germany creates a foundational consumer base seeking non-dairy options for health reasons.
- Nutrient Fortification:Health claim regulations from the EFSA allow producers to market fortified products, enhancing their appeal to health-conscious consumers.
- Supply Chain Stability:Large almond farming cooperatives in the United States provide the consistent raw material supply needed for mass-market expansion.
Market Restraints
- Water Dependency:Almond cultivation's high water usage creates input cost volatility and supply risk from droughts in key growing regions.
- Substitute Competition:The beverage faces intense competition from other plant-based alternatives like oat milk, which often has a lower price and creamier texture.
- Labeling Regulations:Evolving FDA and EFSA rules on using dairy terms like 'milk' create marketing uncertainty and potential rebranding costs.
Strategic Opportunities
- Asia-Pacific Markets:Untapped consumer bases in Asia-Pacific, where lactose intolerance is common, offer significant potential for geographic expansion.
- Culinary Applications:Marketing almond drink as a versatile ingredient for cooking and baking opens new use-cases beyond direct consumption as a beverage.
- Functional Blends:Incorporating ingredients like added protein or probiotics allows for the development of premium products that target specific wellness trends.
Industry Challenges
- Allergen Cross-Contamination:Preventing contamination in shared facilities requires costly, dedicated production lines and stringent operational protocols to ensure consumer safety.
- Sensory Profile:Overcoming consumer perceptions of a thin texture or distinct aftertaste compared to dairy milk requires continuous investment in formulation R&D.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Almond Drink Market |
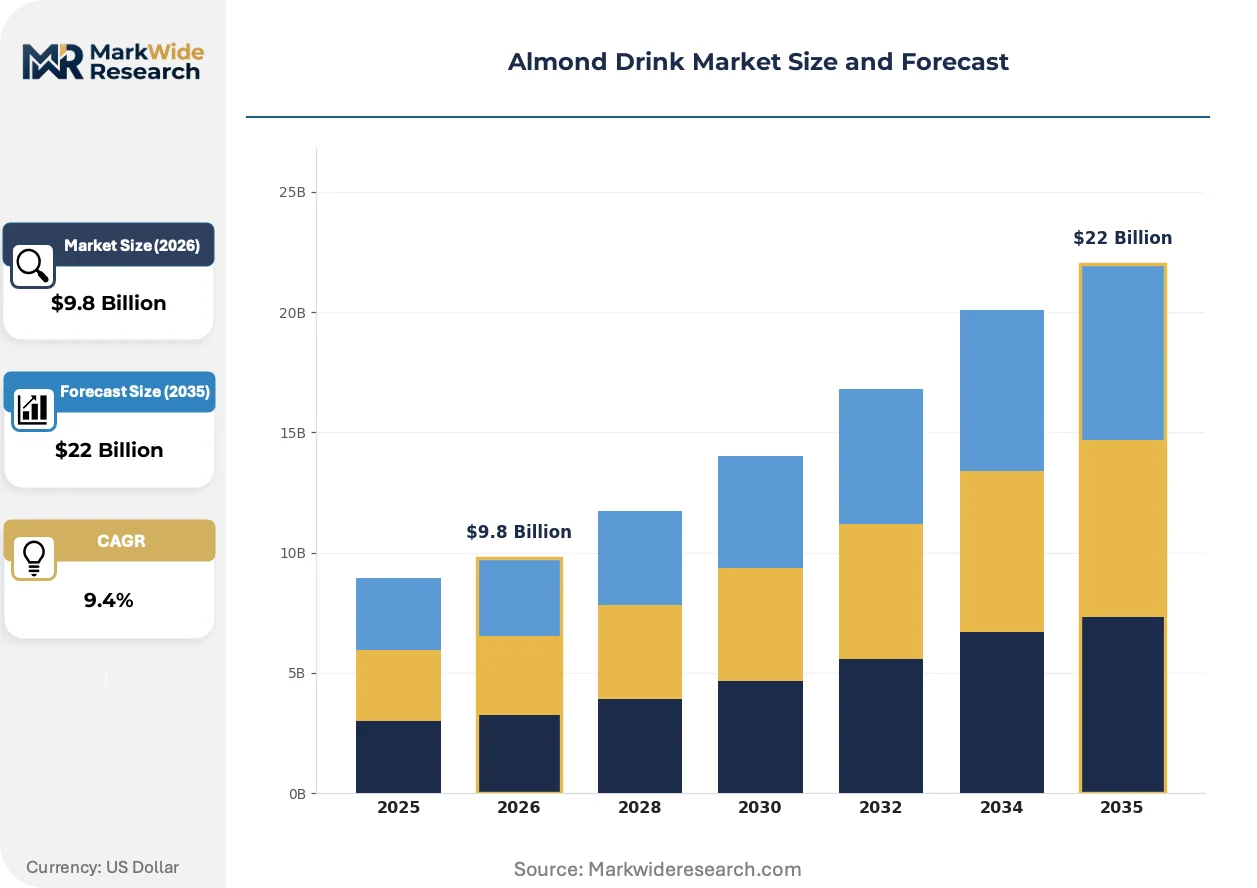
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $22 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsweetened, Sweetened, Vanilla Flavor, Chocolate Flavor Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores Packaging Type: Cartons, Bottles, Tetra Packs, Pouches Consumer Type: Health-Conscious Consumers, Vegans, Lactose Intolerant Individuals, Families |
| Companies Covered | Blue Diamond Growers, Danone S.A., Califia Farms, Hain Celestial Group, SunOpta Inc., Nestlé S.A., Alpro, Ripple Foods, Malk Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Almond Drink Market Strategic Shifts & Innovations
Almond drink is evolving from a simple dairy alternative into a sophisticated beverage platform. This transition is driven by innovations in ingredient science and a deeper understanding of consumer wellness priorities, creating new product identities.
Advanced homogenization techniques use ultra-high pressure to create smaller, more uniform almond particles for a creamier mouthfeel. Health-conscious consumers in the premium segment are rapidly adopting these smoother formulations. This technology is decomposing the traditional trade-off between clean-label ingredients and a desirable, dairy-like texture, enabling premiumization.
The FDA's draft guidance on the labeling of plant-based milk alternatives recommends voluntary nutrient statements comparing them to dairy milk. This encourages producers to fortify their products to meet specific nutritional targets. Unsweetened and fortified product segments are most affected, now using on-pack charts to communicate nutritional equivalency.
A notable behavioral shift is the move toward online subscription and direct-to-consumer purchasing models for specialty plant-based beverages. This disintermediates traditional supermarket channels, which are losing share among brand-loyal, premium-segment consumers. The trend is most visible in urban centers within the United States and Western Europe.
Almond Drink Market Segmentation
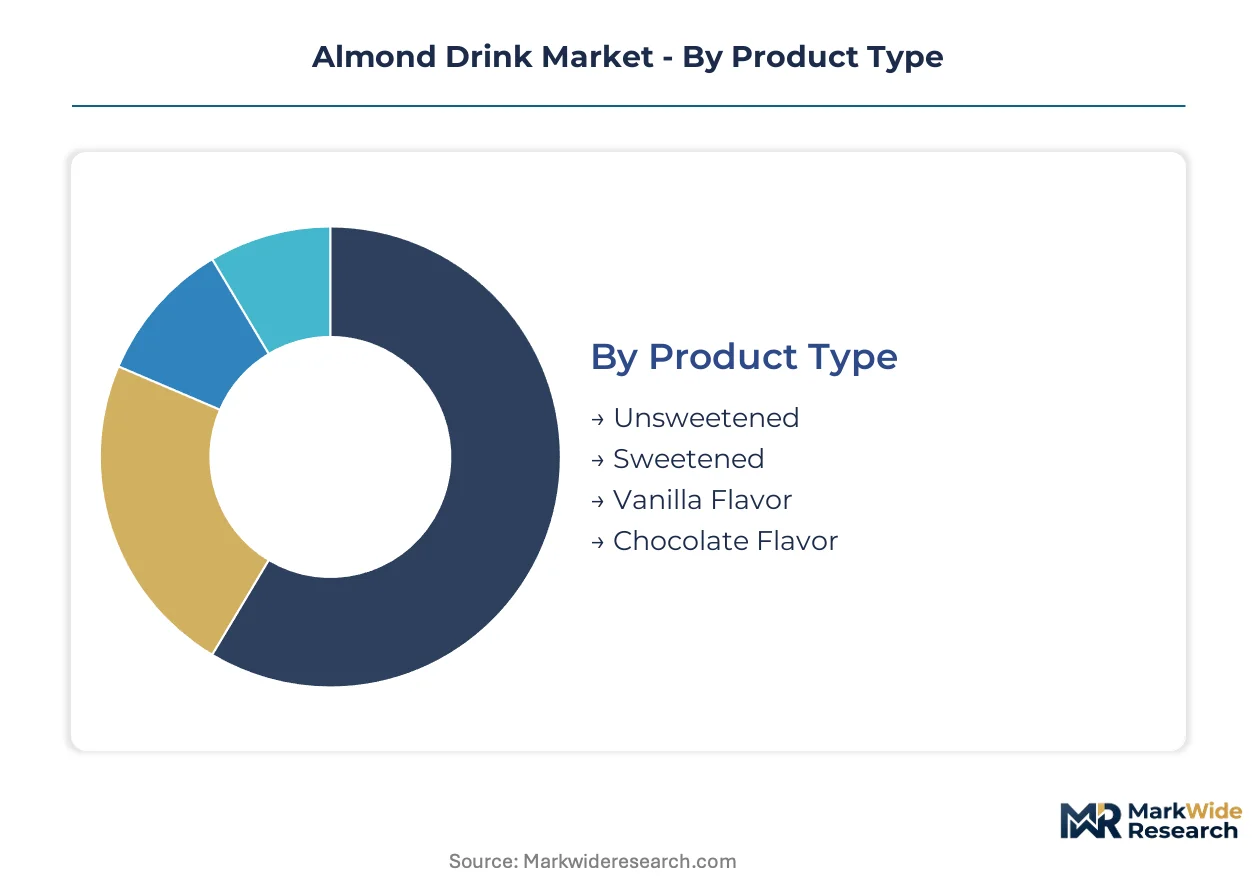
The almond drink market segments across various dimensions, reflecting diverse consumer needs and strategic industry responses. Understanding these segment dynamics allows producers to tailor product development, marketing efforts, and distribution strategies effectively.
Product Type:
Product formulations face different regulatory scrutiny regarding nutritional claims and sugar content from bodies like the FDA and EFSA.
- Unsweetened:Unsweetened almond drink contains only ground almonds and water, without added sugars or artificial sweeteners. Demand concentrates among health-conscious consumers in markets like Germany, driven by preferences for low-sugar diets and clean-label products.
- Sweetened:Sweetened almond drink includes various caloric or non-caloric sweeteners to enhance taste and palatability. This type serves a broader consumer base, particularly in emerging markets, where taste preference often outweighs strict health considerations.
- Vanilla Flavor:This variant incorporates natural or artificial vanilla extracts, appealing to consumers seeking a familiar and aromatic taste profile.
- Chocolate Flavor:Chocolate-flavored almond drink combines cocoa with almond base, targeting younger demographics and those seeking indulgent, dairy-free options.
Established volume favors Sweetened almond drinks; emerging adoption favors Unsweetened variants.
Distribution Channel:
Consumer purchasing habits and the desire for convenience significantly influence the market's distribution dynamics.
- Supermarkets:Supermarkets represent the traditional and largest distribution channel, offering wide product assortments and competitive pricing. Mass-market consumers in developed economies like the United States rely on supermarkets for regular grocery purchases, driving consistent volume.
- Online Retail:Online retail platforms provide direct-to-consumer options and subscription services, offering convenience and broader brand access. Brand-loyal, premium-segment consumers in urban centers of Western Europe increasingly utilize online channels for specialty plant-based beverages.
- Convenience Stores:These outlets cater to immediate consumption needs, offering smaller pack sizes for on-the-go consumers in busy urban environments.
- Health Food Stores:Health food stores serve niche consumer segments prioritizing organic, non-GMO, and specialty plant-based options.
Supermarkets maintain significant market share, while online retail exhibits the steepest expansion trajectory.
Packaging Type:
Packaging type directly impacts product shelf-life, consumer convenience, and environmental footprint.
- Cartons:Cartons, often made from paperboard with a polyethylene lining, are widely used for refrigerated almond drinks requiring cold chain distribution. They dominate the fresh and chilled segments in established markets like the United States, appealing to consumers seeking dairy-like freshness.
- Bottles:Glass or plastic bottles are utilized for premium or single-serve almond drinks, often emphasizing aesthetic appeal and reusability. Demand for bottles is growing among consumers prioritizing sustainability and premium aesthetics.
- Tetra Packs:Tetra Pak packaging offers multi-layered aseptic protection, enabling extended shelf-life for ambient storage without refrigeration. This format is preferred for mass-market distribution across diverse climates, including emerging Asia-Pacific regions, due to logistical efficiency.
- Pouches:Flexible pouches offer lightweight, portable solutions, gaining traction for on-the-go consumption and reduced material usage.
Tetra Packs dominate ambient shelf-stable segments, while Cartons lead refrigerated offerings.
Consumer Type:
Different consumer segments exhibit distinct purchasing motivations and product preferences, driving specific formulation and marketing strategies.
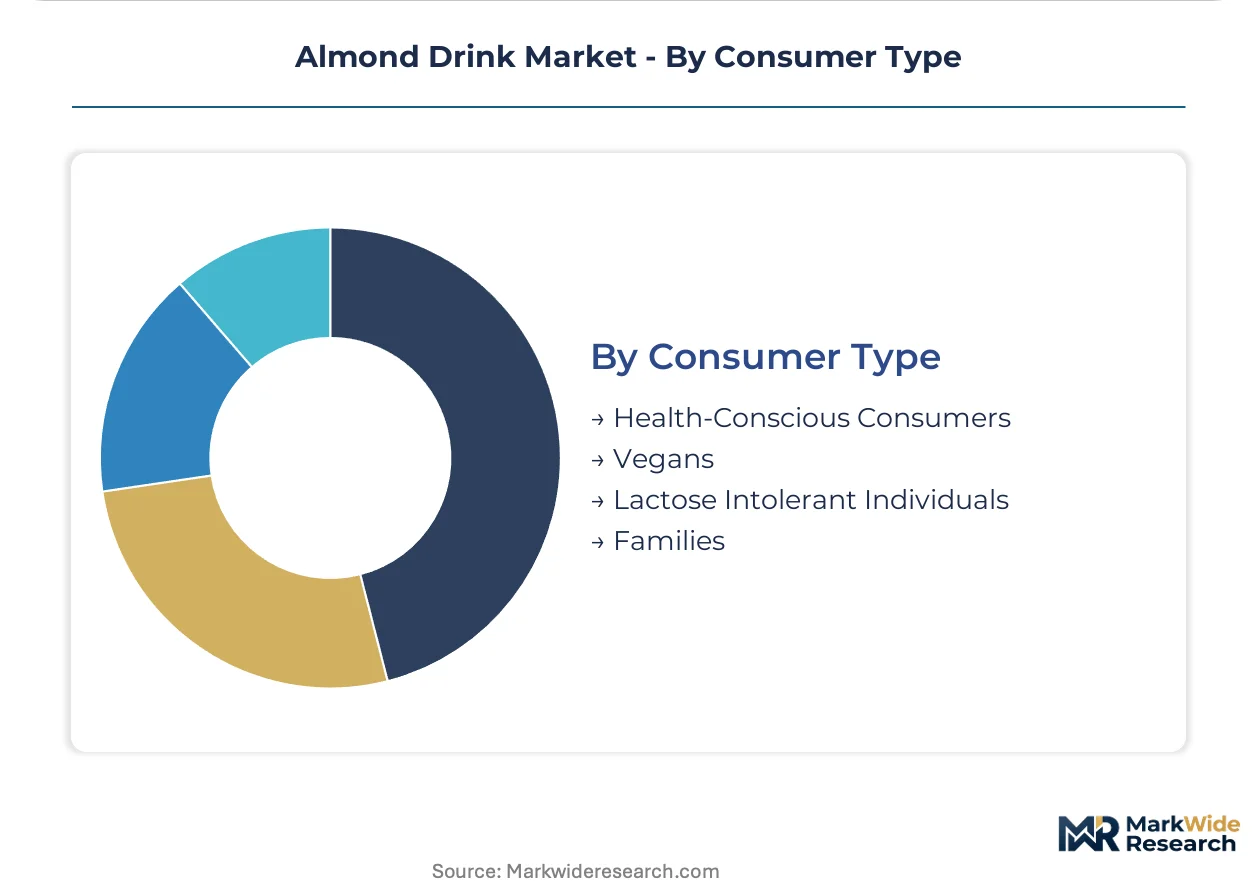
- Lactose Intolerant Individuals:These consumers avoid dairy products due to digestive discomfort caused by lactose, seeking plant-based alternatives. Demand is particularly strong in Asia-Pacific markets, where lactose intolerance prevalence is high, creating a foundational consumer base.
- Health-Conscious Consumers:This group prioritizes products with perceived health benefits, such as lower sugar content, added nutrients, and clean-label ingredients. Unsweetened and fortified almond drinks appeal to this segment in developed markets, influencing product innovation and marketing.
- Vegans:Individuals adhering to a vegan diet consistently choose almond drink as a staple dairy-free alternative for ethical and environmental reasons.
- Families:Families often purchase larger formats for household consumption, using almond drink in cereals, cooking, and as a beverage alternative for children.
Core demand originates from Lactose Intolerant Individuals, with expanding market reach through Health-Conscious Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across the almond drink market, with price-sensitive consumers in emerging economies contrasting with health-conscious buyers in developed markets who prioritize premium formulations. This disparity influences product accessibility and market penetration strategies. Producers adapt offerings to meet diverse purchasing power and nutritional expectations.
Germany
Plant-based diet adoption drives strong demand for almond drink among health-conscious consumers in Germany, seeking low-sugar and clean-label products. EFSA regulations stringently influence product labeling and health claims, encouraging nutrient fortification for market acceptance. Urban centers like Berlin and Hamburg show high consumption rates, reflecting mainstream acceptance of dairy alternatives in cafes and retail.
United States
Health-conscious consumers and lactose intolerant individuals drive significant demand for almond drink in the United States, particularly for unsweetened and fortified variants. FDA guidance on plant-based milk labeling encourages clear nutritional comparisons to dairy, impacting product formulation. California, a major almond growing region, sees robust product development and distribution innovation.
India
The high prevalence of lactose intolerance and a growing middle class fuel demand for dairy alternatives in India, particularly in urban areas. The FSSAI regulates food standards, ensuring product safety and nutritional labeling for plant-based beverages entering the market. Major metropolitan areas like Mumbai and Delhi are emerging as key consumption hubs for almond drink.
United Kingdom
The United Kingdom exhibits robust demand for almond drink, fueled by veganism and health trends among urban populations prioritizing sustainable and ethical choices. UK food standards agencies align with broader European guidelines on nutritional information and ingredient transparency, influencing local producers. London's vibrant food scene actively integrates almond drinks into cafes and diverse retail offerings.
Japan
Japan's aging population and increasing health awareness contribute to a rising demand for fortified and unsweetened almond drinks, often seeking functional benefits. METI standards guide food product innovation, supporting the development of advanced plant-based beverages with specific health claims. Tokyo's competitive retail landscape sees a proliferation of premium almond drink brands and new product introductions.
Almond Drink Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the almond drink market, leading to a distinct bifurcation between premium and mass-market offerings. The industry features large CPG conglomerates focusing on scale, specialized plant-based brands emphasizing innovation, and raw material suppliers controlling upstream value. Key competitive moves include strategic portfolio diversification across price points and backward integration for enhanced supply chain control.
Mass-market scale producers like Danone S.A. represent a strategy focused on broad distribution and diverse brand portfolios, capturing a wide consumer base across various price points. Blue Diamond Growers exemplifies strong supply chain control, leveraging its extensive almond farming cooperative for consistent raw material supply and cost efficiencies. On the premium-tier vector, Califia Farms occupies a position emphasizing unique flavor profiles and distinctive packaging, catering to specialized consumer preferences and higher-value segments. These players collectively shape the market's tiered offerings.
| Leading Market Players |
|---|
| Blue Diamond Growers |
| Danone S.A. |
| Califia Farms |
| Hain Celestial Group |
| SunOpta Inc. |
| Nestlé S.A. |
| Alpro |
| Ripple Foods |
| Malk Organics |
| Others |
Cost & Logistics Intelligence
Extensive scale economies in almond cultivation and processing shape both supply concentration and the underlying price floors for mass-market almond drink products. This structural dynamic influences how producers manage input costs and position their offerings across various price points.
Pricing Analysis
The FDA's draft guidance on plant-based milk labeling dictates the pricing tier structure, encouraging fortification to meet nutritional targets. Premium-mid-economy pricing differentiation exists, driven by clean-label ingredients and higher almond content for premium offerings, versus cost efficiencies for mass-market products. Pricing pressure stems from intense competition from alternative plant-based beverages like oat milk, which often have a lower cost base. Health-conscious consumers seeking unsweetened, fortified variants demonstrate lower price sensitivity compared to mass-market buyers in emerging economies.
Supply Chain Analysis
The United States, particularly California, anchors global almond production, providing the primary raw material for almond drink. The supply chain depends on almonds and water, with additional reliance on fortification nutrients like calcium and vitamins. Water dependency creates input cost volatility and supply risk from droughts in key growing regions. Distribution runs through a hybrid model, with supermarkets dominating mass-market sales and online retail expanding rapidly for premium, brand-loyal consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The almond drink market presents a fragmentation opportunity, driven by evolving consumer wellness priorities creating distinct niches for specialized products.
For Market Incumbents: Fortify existing brand portfolios by investing in advanced homogenization techniques to improve sensory profiles and clean-label ingredient sourcing. Diversify product offerings with functional blends to counter substitute competition from oat milk and other plant-based alternatives. Expand into high-growth Asia-Pacific markets through strategic partnerships to leverage established distribution networks.
For New Entrants and Emerging Players: Niche service-layer gaps exist in premium, localized, and specialized functional blends, which incumbents often under-serve. Target urban centers in Western Europe and the United States with unique flavor profiles and sustainable packaging options. A direct-to-consumer online subscription model offers a compelling go-to-market angle for brand-loyal consumers seeking specialty plant-based beverages.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among brands with strong online direct-to-consumer models and dedicated health-conscious consumer bases. Long-term viability over a 5-10 year window favors players capable of sustained R&D into sensory improvement and functional ingredient integration. A signal to watch is the sustained growth of unsweetened and fortified product segments, indicating robust consumer demand for nutritional value.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Portfolio Diversification | Expands market reach by offering new flavor profiles and functional blends to diverse consumer segments. |
| Supply Chain Optimization | Mitigates raw material cost volatility and ensures consistent almond sourcing for large-scale production. |
| Digital Channel Expansion | Captures brand-loyal premium consumers through direct-to-consumer and online subscription services in urban areas. |
| Nutrient Fortification Investment | Aligns products with evolving health claims and FDA/EFSA regulations, enhancing appeal to health-conscious buyers. |
| Flavor Profile Innovation | Addresses sensory perceptions of thin texture, attracting consumers seeking dairy-like experiences in plant-based options. |
Research Approach
A spread of perspectives from brand managers, R&D scientists, retail category buyers, and supply chain managers converged on the working assumptions for the almond drink market. This involved combining primary interviews with industry stakeholders and secondary validation from regulatory filings, trade association reports, and company financial statements. Bottom-up and top-down triangulation ensured robust data accuracy.
The market's segmentation dimensions modeled include Product Type, Distribution Channel, Packaging Type, Consumer Type, and Regional Outlook across the analysis window. Compound annual growth rates were derived from historical data analysis and projected market dynamics, factoring in plant-based diet adoption rates and almond harvest yields. The analytical framework considers the interplay of regulatory shifts and consumer preferences.
Forecasts assume regulatory continuity in the United States and European Union; material policy shifts would require re-modeling. These projections reflect assumptions regarding water availability for almond cultivation and the intensity of substitute competition. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Vegan Butter Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
United Kingdom Dairy Alternatives Market
Dairy Alternatives
Dairy-Free Spreads Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
Dairy-Free Smoothies Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market
Dairy Alternatives
Germany Dairy Alternatives Market