
 Vegan Butter Market | 2026-2036
Vegan Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Butter Market Outlook
Foodservice buyers is collapsing into household and bakery segments as retail distribution of plant-based spreads matures. Miyoko's Creamery leverages artisanal positioning and cultured fermentation to command premium placement in specialty grocers. Upfield Holdings B.V. anchors broad retail penetration through Flora and Country Crock brand architectures across multiple continents. Earth Balance competes on allergen-free formulations, sustaining loyalty among soy-sensitive consumers in North American mass retail.
Vegan butter is a water-in-fat emulsion manufactured from plant-derived oils, typically containing 78-80% fat content with lecithin and natural flavoring to replicate dairy butter's mouthfeel and functionality in cooking and baking applications. Coconut oil formulations dominate current volume due to superior solid-fat functionality at room temperature, while almond oil variants occupy premium positioning driven by clean-label perception and compatibility with paleo and keto diet frameworks. Spreadable applications lead household consumption, though baking demand from commercial kitchens and artisanal producers is expanding fastest as institutional buyers reformulate recipes to exclude animal fats.
The FDA maintains standards of identity for butter that exclude plant-based alternatives from using the term on U.S. labels, compelling vegan butter producers to adopt "plant-based spread" nomenclature and reshape consumer education strategies. EFSA and ECHA frameworks under the EU Green Deal govern sustainable sourcing claims and palm oil traceability, directly influencing formulation decisions and supplier qualification for brands selling into European retail. Stakeholders must monitor evolving nomenclature battles and carbon-labeling requirements as regulators on both sides of the Atlantic redefine what constitutes acceptable product communication for dairy alternatives.
Market Dynamics
The EU F-Gas Regulation and EU Green Deal targets are pressuring food manufacturers to abandon conventional dairy supply chains, forcing wholesale reformulation of fat-based products across European retail networks. This regulatory compression is redrawing procurement relationships between plant-based ingredient suppliers and institutional bakery buyers.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in dairy processing infrastructure raises operational costs for conventional butter production, tilting cost structures toward ambient-stable plant-based alternatives that require less cold-chain intensity.
- Germany's retail shelf expansion:Urban supermarket networks in Berlin, Munich, and Hamburg have quadrupled dedicated plant-based fat sections since 2022, creating physical distribution density that accelerates household trial and repeat purchase velocity.
- Cultured fermentation processes:Precision fermentation of plant lipids delivers dairy-identical flavor compounds without animal inputs, allowing artisanal bakeries to reformulate classic European pastries without sensory compromise or recipe restructuring.
Market Restraints
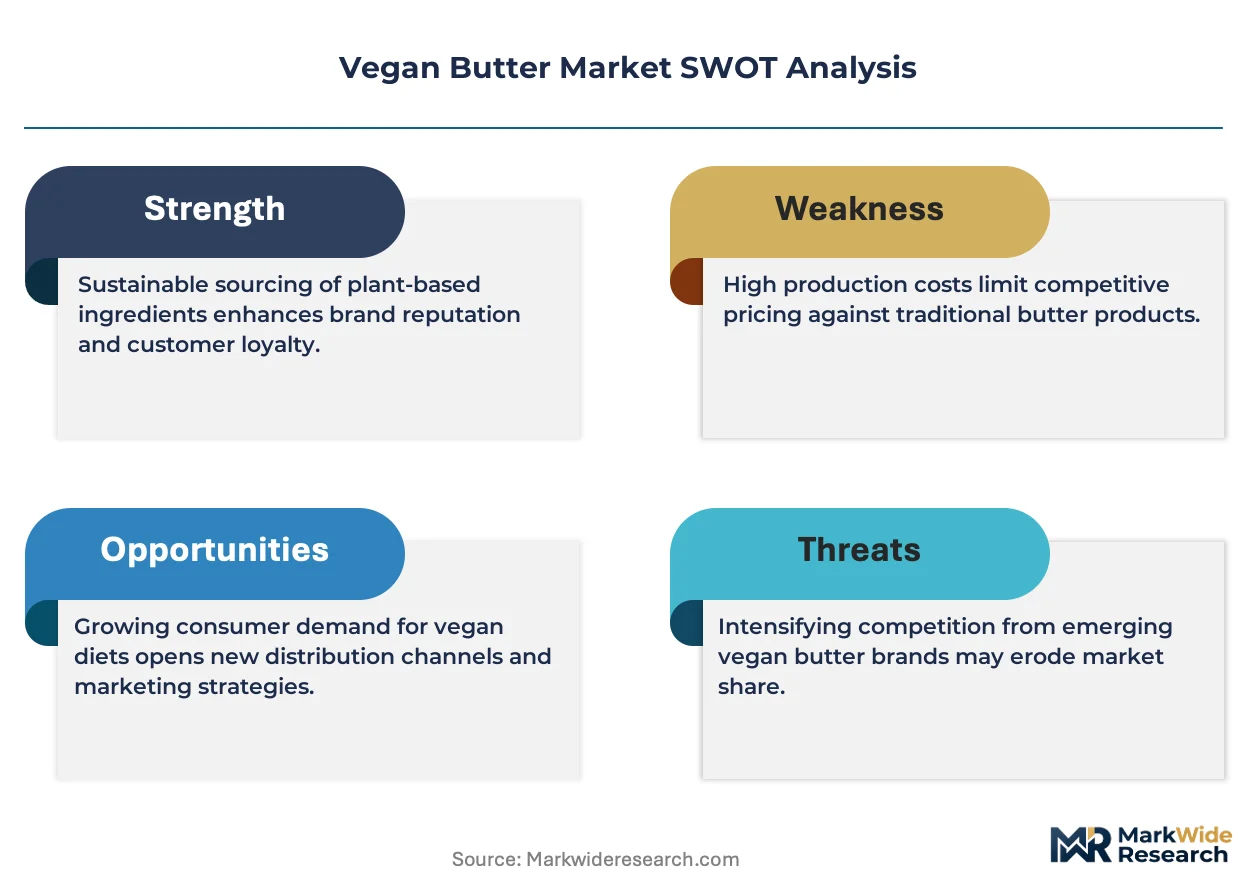
- Coconut oil price volatility:Concentrated sourcing from Southeast Asian producers exposes margins to weather-driven supply shocks and currency fluctuations that ripple through 78-80% fat-content formulations.
- FDA standards of identity:The prohibition on "butter" nomenclature for plant-based products in the United States forces costly consumer education campaigns and packaging redesign cycles for brands targeting American retail.
- Palm oil traceability requirements:ECHA and EFSA frameworks under the EU Green Deal mandate granular supply chain documentation that disqualifies non-certified Southeast Asian suppliers and compresses available feedstock pools.
Strategic Opportunities
- Artisanal foodservice channels:Independent bakeries and specialty cafés in France and Italy represent underpenetrated accounts where premium positioning and cultured fermentation credentials command price premiums unavailable in mass retail.
- Almond oil keto-paleo convergence:Clean-label positioning aligned with restrictive diet frameworks opens household penetration among health-motivated consumers who prioritize ingredient transparency over price sensitivity.
- Carbon-labeling differentiation:Early adoption of ISO-compliant product carbon footprinting creates competitive separation as EU retailers begin requiring environmental impact disclosures for shelf placement eligibility.
Industry Challenges
- Emulsion stability expertise:Water-in-fat formulation chemistry requires specialized food science talent scarce in traditional dairy engineering pipelines, creating recruitment bottlenecks for R&D expansion.
- Multi-jurisdiction label compliance:Simultaneous navigation of FDA nomenclature restrictions, EFSA health claim protocols, and emerging national carbon-labeling schemes fragments packaging development timelines and marketing asset deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Butter Market |
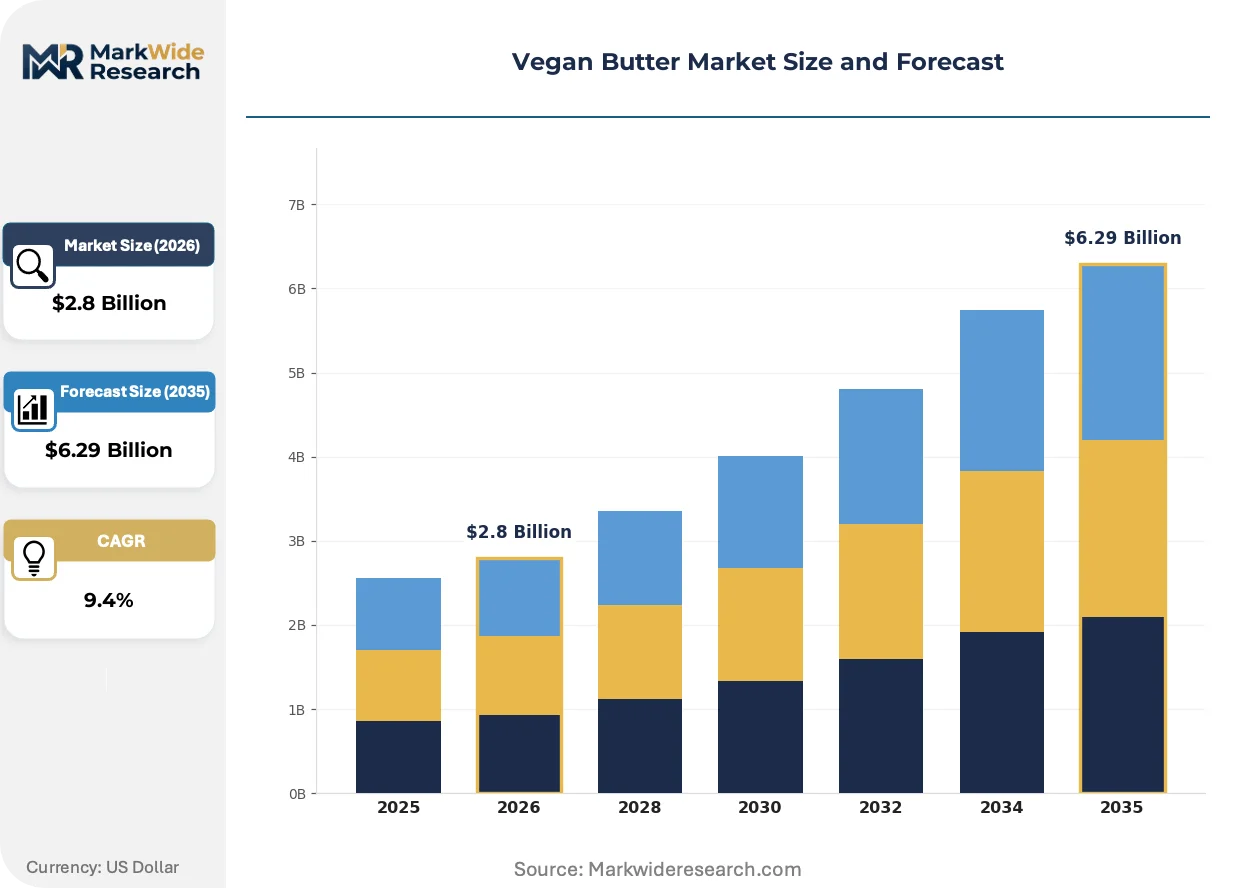
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Oil, Almond Oil, Soybean Oil, Olive Oil Application: Baking, Spreadable, Cooking, Sauces End User: Households, Restaurants, Cafes, Bakeries Packaging Type: tubs, Pouches, Sticks, Sachets |
| Companies Covered | Naturli Foods Ltd., Kite Hill, Miyoko's Creamery, Melt Organic, Country Crock, Upfield Holdings B.V., Violife, WayFare Foods, Earth Balance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Butter Market Strategic Shifts
Precision fermentation of plant lipids is collapsing the sensory gap between dairy and plant-based fats, enabling functional equivalence in high-heat baking applications that previously rejected alternative formulations.
Cultured fermentation technology is decomposing the historical trade-off between clean-label positioning and functional performance in vegan butter formulations. Artisanal producers in Germany and France are adopting these processes at accelerating velocity, replacing conventional emulsifier systems with microbial-derived stabilizers that withstand laminating and creaming methods. This shift is compressing the premium pricing gap between plant-based spreads and conventional cultured butter in specialty retail channels.
The EU Green Deal's F-Gas Regulation is systematically raising capital and operating costs for dairy processing infrastructure dependent on hydrofluorocarbon refrigeration systems. Industrial bakeries across the Netherlands and Denmark are responding by qualifying plant-based fat suppliers whose ambient stability reduces cold-chain requirements and simplifies logistics compliance. This regulatory pressure differential is most acute in commercial kitchen segments where procurement teams prioritize total cost of ownership over ingredient heritage.
Household purchasing patterns are rotating toward spreadable formats that emphasize convenience and immediate usability over block formats requiring tempering. Urban consumers in German supermarket networks are displacing traditional butter sticks with tub-based plant-based alternatives that integrate seamlessly into breakfast and snacking occasions. This consumption-pattern shift is most visible in Berlin and Hamburg, where single-person households and flexible eating schedules dominate demographic composition.
Vegan Butter Market Segmentation
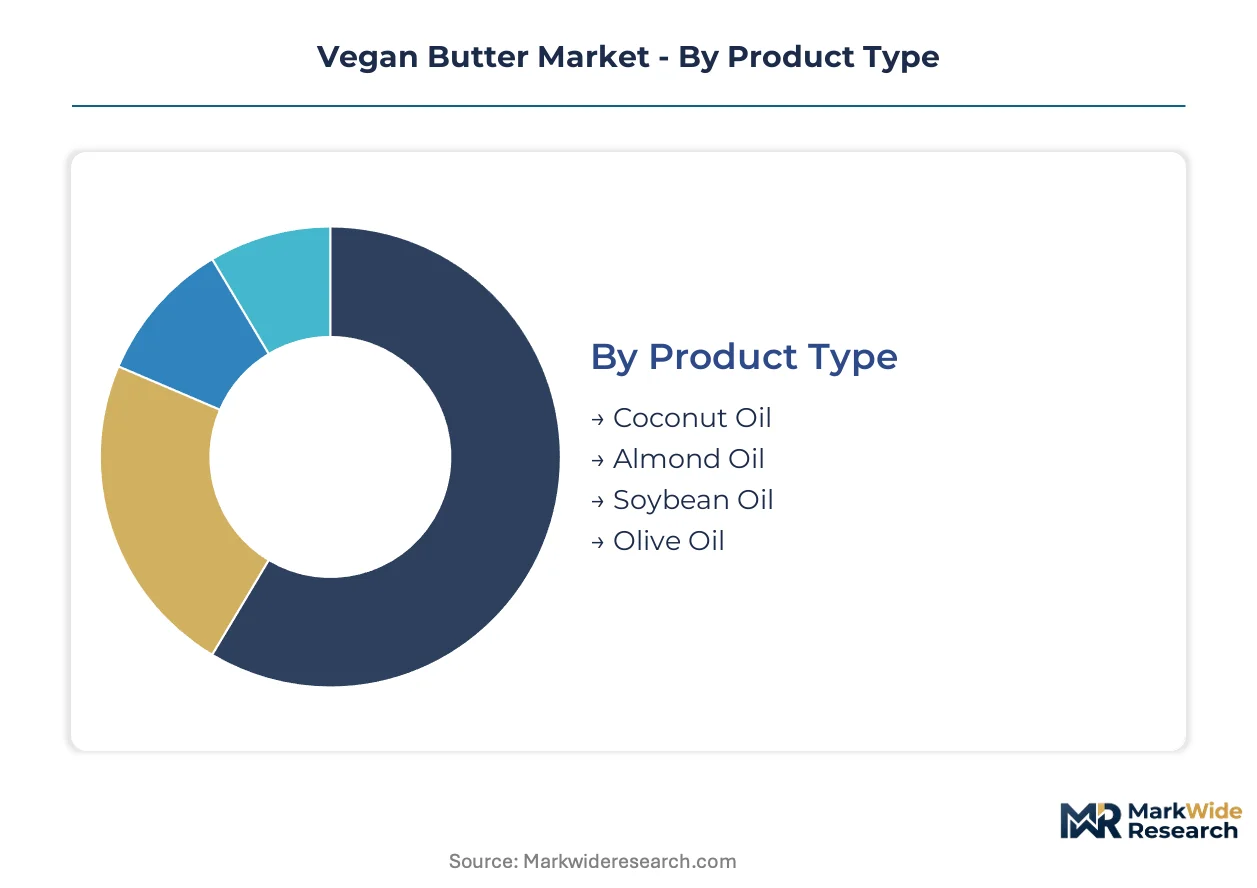
Segmentation in vegan butter reveals how formulation chemistry, consumption occasion, and procurement channel intersect to create distinct margin profiles. Each dimension carries regulatory and supply-chain implications that reshape competitive positioning.
Product Type:
Channel distribution varies sharply by oil base: coconut formulations flow through mass retail and industrial bakery procurement, while almond variants concentrate in specialty grocers and direct-to-consumer platforms.
- Coconut Oil:Dominates current volume with superior solid-fat functionality at room temperature, enabling spreadable textures without hydrogenation. Demand concentrates in German urban supermarkets where ambient stability reduces cold-chain costs under EU F-Gas Regulation pressure.
- Almond Oil:Commands premium positioning through clean-label compatibility with paleo and keto diet frameworks. Expansion concentrates among health-motivated households in France and Italy where ingredient transparency overrides price sensitivity.
- Soybean Oil:Anchors economy-tier production with established supply infrastructure and neutral flavor profiles. Procurement runs through North American mass retail channels constrained by FDA standards of identity nomenclature restrictions.
- Olive Oil:Occupies Mediterranean-market positioning with polyphenol-related health claims governed by EFSA protocols. Volume remains limited by oxidative stability challenges in high-heat applications.
Coconut oil dominates installed base. Almond oil is where expansion concentrates.
Application:
Margin structure inverts across use cases: spreadable formats compete on convenience and repeat purchase velocity, while baking applications command technical qualification and long-term supply contracts.
- Baking:Requires precise fat crystallization and emulsion stability for laminating, creaming, and high-heat tolerance. Demand from artisanal bakeries in the Netherlands and Denmark is climbing fastest as ECHA frameworks pressure reformulation away from dairy.
- Spreadable:Emphasizes immediate usability at refrigeration temperatures with minimal tempering. Household penetration in Berlin and Hamburg supermarket networks has displaced traditional butter sticks among single-person urban demographics.
- Cooking:Prioritizes smoke point performance and neutral flavor release across sautéing and pan-frying applications. Restaurant procurement in Germany favors coconut-base formulations for cost predictability.
- Sauces:Demands emulsion stability under thermal stress and acid conditions. Café adoption remains constrained by chef skepticism toward plant-based fat functionality in classical reduction techniques.
Spreadable formats anchor household revenue. Baking applications carry the steepest expansion trajectory.
End User:
Procurement sophistication escalates from household impulse purchase through institutional tender processes, with each tier imposing distinct formulation and documentation requirements.
- Households:Drive volume through retail trial and repeat purchase cycles influenced by shelf placement and packaging convenience. German urban consumers have quadrupled plant-based fat section engagement since 2022.
- Restaurants:Require consistent supply security and price hedging for menu cost management. Kitchens in France prioritize cultured fermentation credentials for premium positioning.
- Cafes:Focus on breakfast and snacking occasion integration with minimal preparation friction. Independent operators in Italy represent underpenetrated accounts where artisanal credentials command price premiums.
- Bakeries:Impose the most stringent functional specifications for lamination, proofing, and finished product texture. Industrial bakeries across the Netherlands are qualifying suppliers whose ambient stability simplifies logistics compliance under EU Green Deal targets.
Households dominate transaction volume. Bakeries concentrate margin expansion.
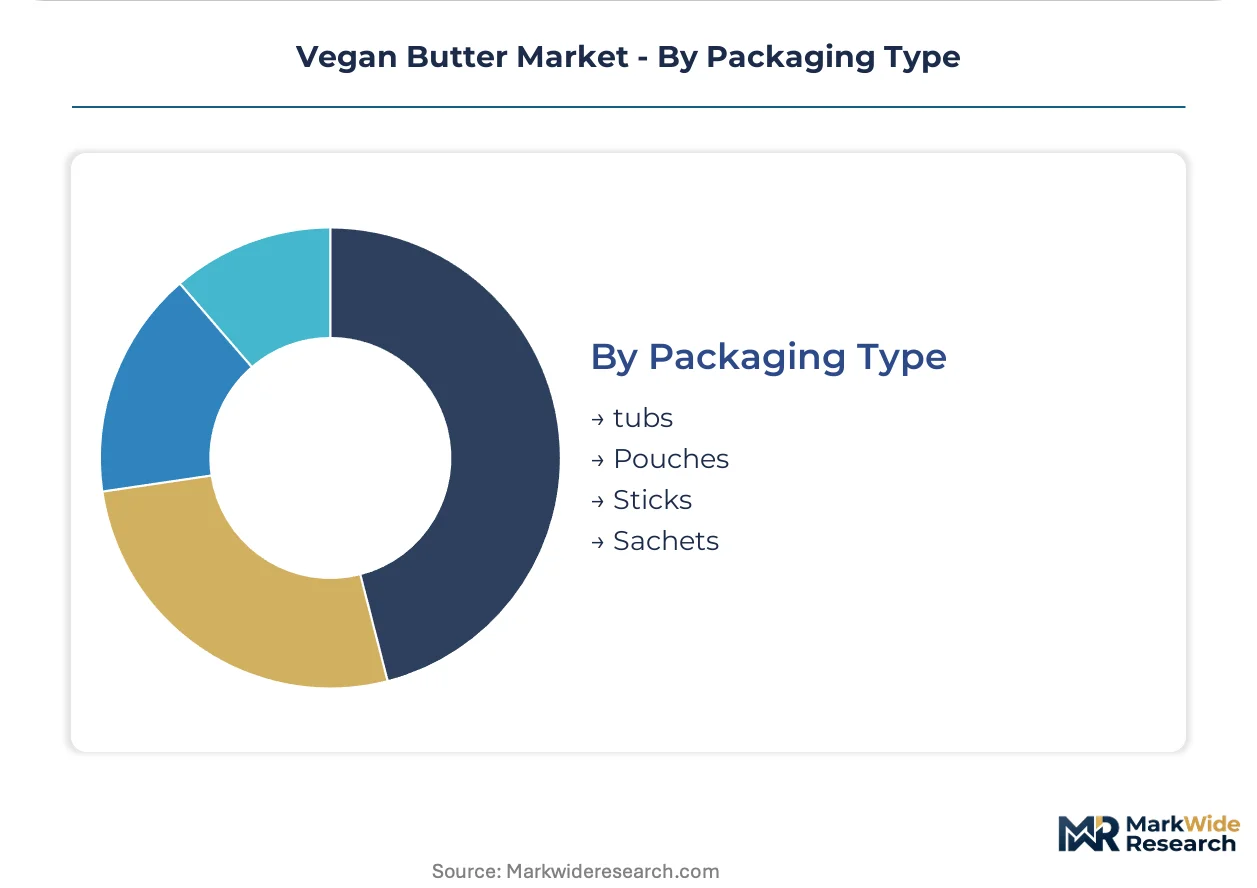
Packaging Type:
Format selection directly shapes distribution economics: ambient-stable configurations reduce refrigeration capital requirements while portion-controlled options target specific consumption occasions.
- Tubs:Dominates household spreadable consumption with resealable convenience and portion flexibility. Berlin and Hamburg supermarket networks have expanded tub-based shelf space most aggressively.
- Pouches:Serves foodservice bulk procurement with reduced packaging weight and disposal costs. Restaurant chains in Germany favor pouch formats for back-of-house efficiency.
- Sticks:Replicates conventional butter measurement conventions for baking applications. Bakeries in France and Italy maintain stick-format preference for recipe standardization.
- Sachets:Targets single-serve hospitality and airline catering segments with portion control and extended ambient stability. Volume remains constrained by unit economics at small scale.
Tubs dominate installed base. Pouches are where foodservice expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in European dairy-alternative manufacturing corridors where EU Green Deal compliance costs are restructuring procurement patterns. German retail networks and Dutch industrial bakeries anchor current volume, while North American nomenclature battles constrain label architecture.
Germany
Urban supermarket networks in Berlin, Munich, and Hamburg have quadrupled dedicated plant-based fat shelf space since 2022, accelerating household trial velocity. The EU F-Gas Regulation raises refrigeration costs for conventional dairy, tilting procurement toward ambient-stable alternatives. Industrial bakeries in Bavaria are qualifying suppliers whose cultured fermentation credentials satisfy artisanal positioning requirements.
Netherlands
Foodservice distributors in Rotterdam and Amsterdam report climbing procurement from commercial kitchens reformulating away from animal fats. ECHA traceability mandates under the EU Green Deal disqualify non-certified palm oil suppliers, compressing available feedstock pools. Large-scale bakery operations in North Brabant prioritize suppliers with ISO-compliant carbon footprinting for retail shelf placement eligibility.
United States
FDA standards of identity prohibit "butter" nomenclature for plant-based products, forcing costly consumer education campaigns and packaging redesign cycles. Mass retail channels in California and New York Metro drive volume through allergen-free formulations targeting soy-sensitive households. Specialty grocers in Pacific Northwest clusters allocate premium placement to cultured fermentation brands with artisanal credentials.
France
Independent bakeries in Paris and Lyon represent underpenetrated accounts where precision fermentation technology commands price premiums unavailable in mass retail. EFSA health claim protocols govern polyphenol-related positioning for olive oil formulations. Artisanal producers in Provence-Alpes-Côte d'Azur are adopting microbial-derived stabilizers that withstand classical laminating methods without sensory compromise.
United Kingdom
Retail chains in London and the Southeast have expanded plant-based spread sections in response to shifting household consumption patterns. The country's national food standards regulator maintains strict labeling requirements that parallel FDA restrictions on dairy terminology. Specialty cafés in Greater Manchester and Birmingham are testing cultured fermentation suppliers for breakfast occasion integration.
Vegan Butter Market Competitive Environment
Concentration sits with diversified plant-based food conglomerates and artisanal fermentation specialists. The vendor base spans three tiers: multinational CPG platforms with refrigerated distribution scale, mid-cap regional producers leveraging clean-label positioning, and venture-backed precision fermentation startups. Strategic moves cluster around M&A for manufacturing capacity and technology licensing for emulsion stability IP.
Among diversified CPG platforms, Upfield Holdings B.V. and Country Crock anchor broad retail penetration across multiple continents through established brand architectures. Miyoko's Creamery occupies the artisanal tier, exemplifying premium positioning through cultured fermentation credentials in specialty grocery channels. These three entities represent distinct competitive vectors: scale-driven distribution, mass-market accessibility, and craft-oriented premiumization.
| Leading Market Players |
|---|
| Naturli Foods Ltd. |
| Kite Hill |
| Miyoko's Creamery |
| Melt Organic |
| Country Crock |
| Upfield Holdings B.V. |
| Violife |
| WayFare Foods |
| Earth Balance |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between German industrial bakeries and coconut oil processors lock in supply access while insulating procurement teams from Southeast Asian spot-market volatility. These contractual structures concentrate pricing power among processors with certified sustainable sourcing credentials under ECHA traceability mandates.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across European procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates cultured fermentation brands from commodity coconut formulations and soy-based economy options. Price differentiation rests on EFSA-compliant health claims and carbon-footprint certification. Cost compression in economy tiers is intensifying because palm oil traceability requirements disqualify non-certified Southeast Asian suppliers. Household consumers in German urban supermarkets demonstrate lowest price sensitivity, while North American mass retail buyers face highest pressure from FDA-mandated nomenclature redesign costs.
Supply Chain Analysis
Inventory cycles for coconut oil feedstock stretch 8-12 weeks from Southeast Asian processors to European formulation facilities. Supply concentrates in Indonesia, the Philippines, and Malaysia for raw coconut oil extraction, with secondary processing clustered in the Netherlands and Germany. Raw material dependencies include lecithin emulsifiers, natural flavoring compounds, and microbial cultures for fermentation variants. Single-source vulnerability runs through concentrated Southeast Asian coconut processing infrastructure exposed to climate-driven yield shocks. Distribution runs through refrigerated and ambient logistics networks serving retail, foodservice, and industrial bakery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. ECHA traceability mandates and FDA nomenclature restrictions create switching costs that protect qualified suppliers from commodity competition.
For Market Incumbents: Consolidate backward integration into coconut oil processing assets in certified Southeast Asian origins to secure feedstock pools disqualified from competitors under EU Green Deal sourcing rules. Expand capacity in Bavaria and North Brabant to capture industrial bakery procurement shifting away from dairy cold-chain dependence. For New Entrants and Emerging Players: Anchor in artisanal café channels in France and Italy where precision fermentation credentials command price premiums unavailable in mass retail. Target independent bakeries in Paris and Lyon with microbial-derived stabilizer formulations that withstand classical laminating methods without recipe restructuring. For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation technology platforms with scalable emulsion stability IP and established supplier qualification under EFSA frameworks. Long-term viability hinges on carbon-labeling adoption velocity as EU retailers mandate environmental impact disclosures for shelf placement eligibility. Watch for inflection when ISO-compliant product carbon footprinting becomes mandatory for retail distribution contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Coconut Processing | Secures ECHA-compliant feedstock pools disqualified from non-certified competitors under EU Green Deal mandates. |
| Precision Fermentation Technology Licensing | Delivers dairy-identical flavor compounds that enable artisanal bakery reformulation without sensory compromise. |
| ISO-Compliant Carbon Footprinting Program | Creates competitive separation as EU retailers require environmental impact disclosures for shelf placement. |
| Artisanal Foodservice Channel Expansion | Captures price premiums in underpenetrated French and Italian independent bakery accounts. |
| Multi-Jurisdiction Label Compliance Investment | Navigates simultaneous FDA nomenclature restrictions and EFSA health claim protocols for packaging deployment. |
Study Parameters
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings. Primary fieldwork engaged plant-based food R&D directors, industrial bakery procurement managers, specialty grocery category buyers, ECHA compliance consultants, and precision fermentation technology leads. Secondary validation drew from EFSA guidance documents, ECHA substance registration databases, EU Green Deal implementation reports, and customs trade records for coconut oil imports. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates.
Sensitivity analysis across oil base formulations, application use cases, and procurement channel tiers stress-tests projection outputs. The analytical framework models coconut, almond, soybean, and olive oil variants against spreadable, baking, cooking, and sauce applications through household, restaurant, café, and bakery end-user segments. CAGRs were derived from trend extrapolation of retail shelf space expansion, regulatory cost compression effects, and fermentation technology adoption curves. Forecast inputs include EU F-Gas Regulation compliance cost trajectories and carbon-labeling scheme rollout schedules.
Material uncertainties — regulatory revision timelines, coconut oil supply shocks, and precision fermentation scale-up bottlenecks — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology adoption rates and regulatory enforcement consistency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Dairy-Free Chocolate Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
Dairy Free Yogurt Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Germany Non-Dairy Milk Market
Dairy Alternatives
Middle East Dairy Alternatives Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Dairy Whiteners Market
Dairy Alternatives
Pet Milk Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Dairy-Free Creams Market
Dairy Alternatives
Vegan Ice Cream Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Peanut Milk Market
Dairy Alternatives
Non-Dairy Yogurt Market