
 Wine Chocolate Market | 2026-2036
Wine Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Chocolate Market Analysis
Precision tempering technology is narrowing the gap between artisanal craftsmanship and industrial throughput in wine chocolate production. Lindt & Sprüngli leverages Swiss conching expertise to sustain premium positioning across European duty-free channels. Ferrero S.p.A. anchors its competitive stance through controlled cocoa sourcing and proprietary filling systems. Mars Incorporated dominates mass-market shelf space with scaled manufacturing and retail distribution networks.
Wine chocolate denotes cocoa-based confectionery incorporating wine, wine reduction, or wine-derived flavor compounds, typically formulated with minimum cocoa butter content of 18 percent for couverture-grade products and processed through controlled conching to preserve volatile aromatic esters. Dark chocolate leads product type segmentation due to structural compatibility with tannic wine profiles and established consumer associations with sophistication. Specialty stores capture disproportionate margin pools among distribution channels by curating regional wine-chocolate pairings and limited-edition releases.
EFSA alcohol-in-food labeling standards, FDA ingredient disclosure rules for alcohol-containing confectionery, and EU food information regulations collectively shape formulation transparency and cross-border market access requirements. Compliance with these frameworks directly influences packaging claims, import classifications, and duty-free retail eligibility across key markets. Stakeholders must monitor evolving alcohol-content thresholds and labeling harmonization debates to anticipate reformulation costs and channel restrictions.
Market Dynamics
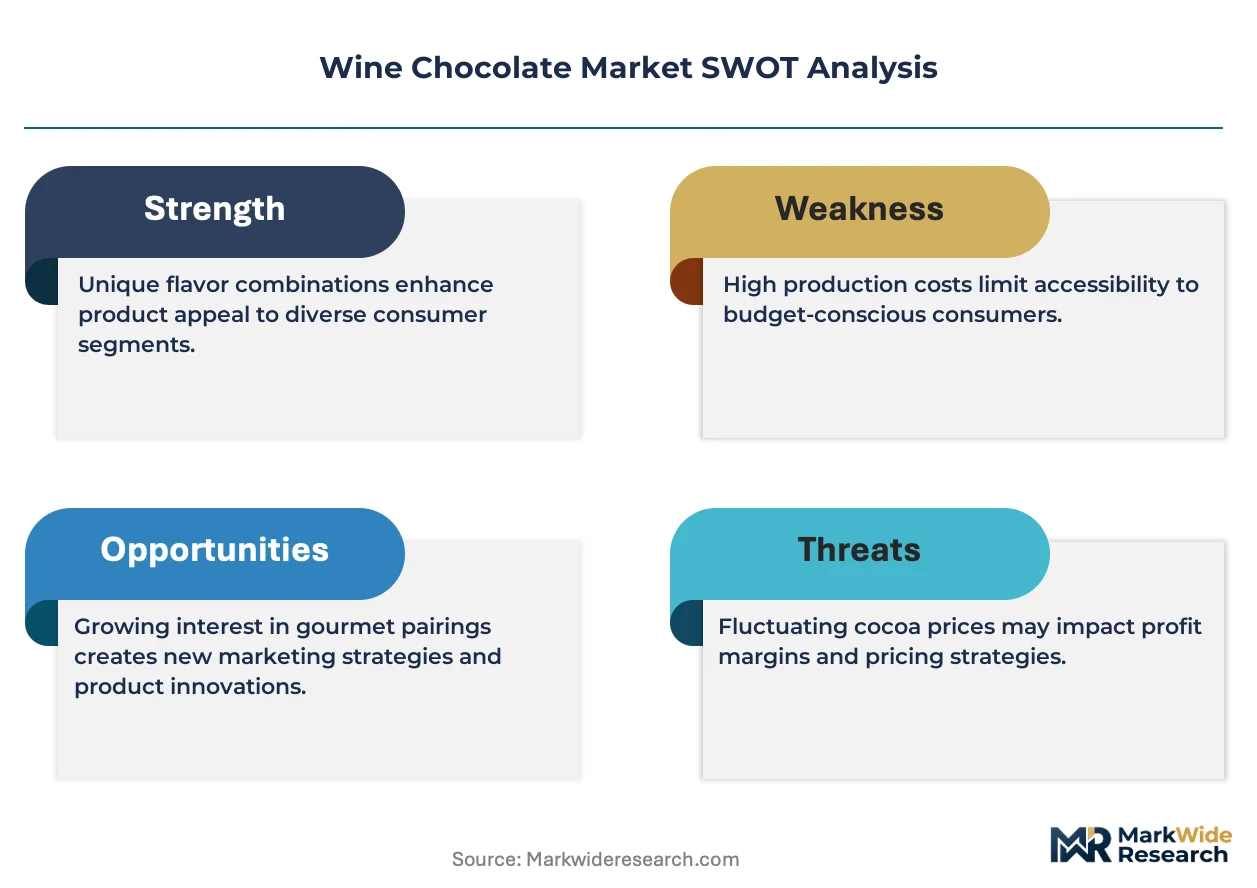
EFSA alcohol-in-food labeling reforms are forcing wine chocolate manufacturers to restructure formulation transparency, packaging claims, and cross-border retail eligibility across European duty-free channels.
Growth Catalysts
- Premium gifting culture:Heritage chocolatiers in Germany and Switzerland leverage regional wine terroir associations to command shelf-space premiums in airport retail. Duty-free infrastructure expansion in Frankfurt and Zurich anchors category visibility.
- EFSA disclosure mandates:Tightened ingredient transparency requirements for alcohol-infused confectionery are accelerating clean-label reformulation investments. Compliant producers gain preferential import classification.
- Precision tempering systems:Controlled thermal processing preserves volatile aromatic esters at industrial scale, narrowing quality gaps between artisanal and mass-production outputs.
Market Restraints
- Cocoa butter input volatility:Minimum 18 percent cocoa butter content for couverture-grade wine chocolate exposes margins to commodity price swings in West African supply origins.
- Alcohol-content threshold fragmentation:Divergent national limits on residual ethanol in confectionery create formulation lock-in and complicate pan-European SKU rationalization.
- Wine reduction substitution:Synthetic wine flavor compounds threaten authentic positioning in economy-tier segments, pressuring heritage producers to defend provenance narratives.
Strategic Opportunities
- Regional pairing curation:Specialty stores in Bordeaux and Tuscany capture disproportionate margins through limited-edition wine-chocolate collaborations with AOC-designated vineyards.
- CSRD-aligned sourcing:EU corporate sustainability reporting requirements reward controlled cocoa procurement with ESG-scoring advantages in institutional gifting channels.
- Direct-to-consumer subscription:Monthly wine-chocolate pairing boxes bypass traditional retail slotting fees and capture lifetime value through curated discovery experiences.
Industry Challenges
- Volatile aromatic preservation:Industrial conching operations struggle to retain wine-derived ester profiles through extended processing windows, requiring capital-intensive equipment upgrades.
- Cross-border labeling synchronization:Harmonization delays between EFSA standards and FDA alcohol-confectionery disclosure rules extend product launch timelines for dual-market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Chocolate Market |
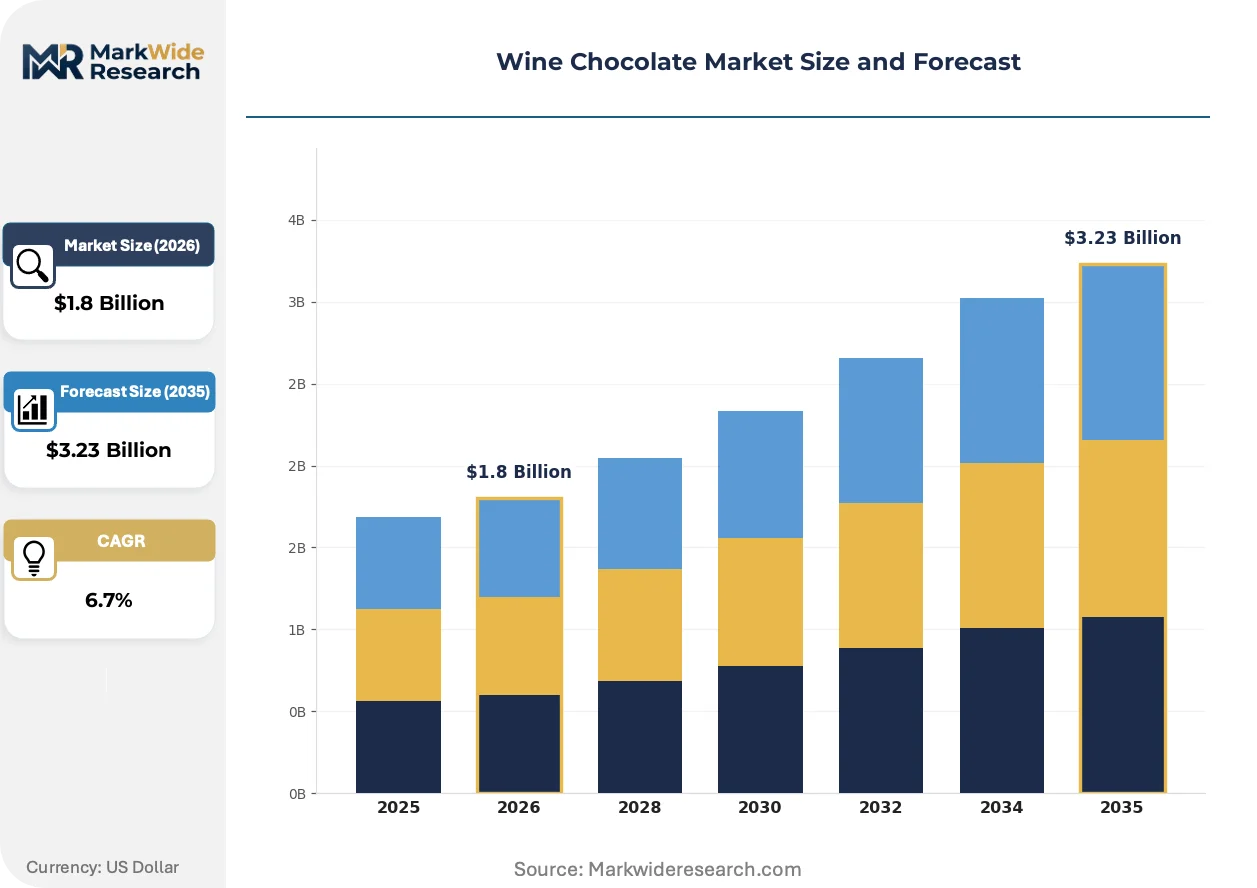
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate End User: Retail Consumers, Restaurants, Hotels, Event Venues Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Duty-Free Shops Packaging Type: Gift Boxes, Bars, Bags, Assorted Packs |
| Companies Covered | Lindt & Sprüngli, Ferrero S.p.A., Mars Incorporated, Underberg AG, Yildiz Holdings, Alfred Ritter, NEUHAUS, Amedei Tuscany, Duc d'O, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Chocolate Market Emerging Trajectories
Active thermal control systems and regulatory disclosure automation are compressing production economics while reshaping competitive entry barriers across premium and mass-market tiers.
Precision conching technology with real-time aromatic monitoring is rendering obsolete batch-based artisanal methods that relied on master chocolatier intuition. Mid-tier manufacturers in Belgium and the Netherlands adopt these systems at accelerating rates. Quality consistency gains now achievable at industrial throughput are collapsing the traditional premium-mass price spread.
EU Green Deal supply-chain traceability requirements are mandating farm-to-bar documentation for cocoa inputs. Wine chocolate producers must integrate blockchain-verified sourcing or forfeit institutional channel access. German and Austrian heritage brands are responding fastest, embedding QR-linked provenance data directly into luxury packaging.
Buyer concentration among airport retail operators is consolidating assortment authority into fewer procurement desks. Lindt and Ferrero leverage established duty-free relationships to lock out emerging competitors. This channel compression is most visible in Frankfurt, Amsterdam Schiphol, and Zurich, where single-category buyers now control access to 70 percent of European travel retail chocolate space.
Wine Chocolate Market Segmentation
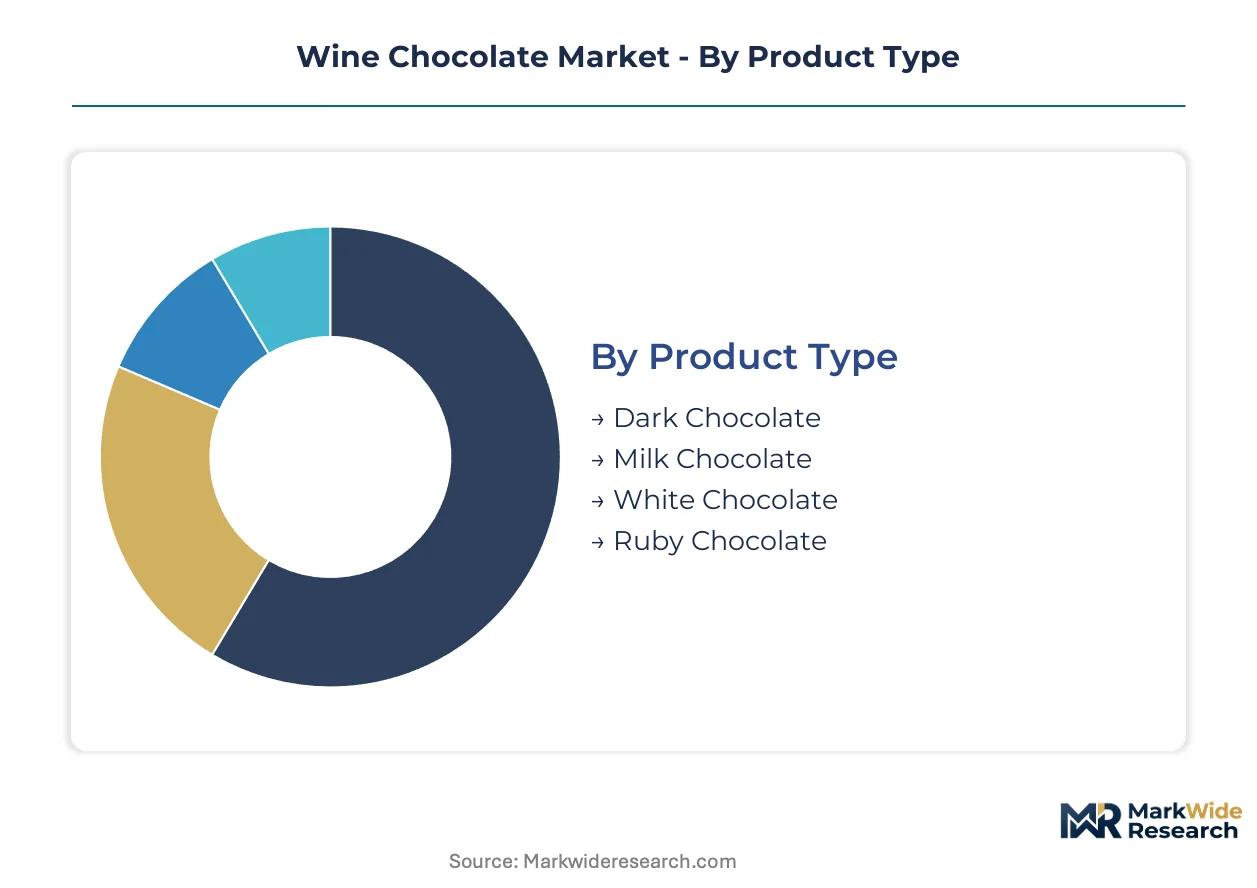
Wine chocolate segmentation reveals how formulation chemistry, purchase context, and channel economics fragment addressable demand. Technical specifications around cocoa butter content and volatile aromatic preservation create distinct manufacturing requirements across product tiers.
Product Type:
Mature dark chocolate formulations dominate commercial throughput, while emerging ruby chocolate variants disrupt traditional color-aroma associations in premium positioning.
- Dark Chocolate:Minimum 18 percent cocoa butter content provides structural compatibility with tannic wine reductions. Demand concentrates in German heritage chocolatier channels where EFSA-compliant labeling commands shelf-space premiums in Frankfurt duty-free retail.
- Milk Chocolate:Lower cocoa solids content requires modified conching protocols to prevent wine-derived ester degradation. Swiss and Belgian manufacturers leverage precision tempering systems to preserve aromatic integrity at industrial scale.
- White Chocolate:Cocoa butter-dominant matrix offers neutral canvas for fruit-forward wine infusions. Italian producers exploit this flexibility for prosecco-derived limited editions.
- Ruby Chocolate:Naturally occurring anthocyanin pigments from specific cocoa varietals create distinctive color profiles without artificial additives. French and Japanese chocolatiers pioneer vineyard-specific collaborations exploiting this visual differentiation.
Dark chocolate handles the majority of throughput; ruby chocolate is expanding most quickly on share.
End User:
Cost tier stratification separates institutional bulk procurement from curated individual gifting experiences across hospitality and retail channels.
- Retail Consumers:Premium gifting culture drives individual purchase decisions around heritage provenance and limited-edition vineyard collaborations. German airport retail infrastructure anchors category visibility for this segment.
- Restaurants:Sommelier-curated tasting menus incorporate wine chocolate as palate-cleansing interludes or dessert components. Bordeaux and Tuscany establishments source through specialty distributors with AOC-verified supply chains.
- Hotels:Turn-down service amenities and minibar assortments prioritize shelf-stable formulations with clear alcohol-content labeling for international guest compliance.
- Event Venues:Corporate hospitality and wedding catering demand volume-scaled assortments with customizable packaging for brand co-marketing.
Retail consumers absorb the dominant volume share; restaurants are climbing the fastest as sommelier-driven pairing culture penetrates mid-tier dining.
Distribution Channel:
Geography of purchase determines margin capture, with airport retail consolidation extracting terms while direct channels preserve lifetime value.
- Online Retail:Subscription-based discovery models bypass traditional slotting fees and capture recurring revenue through curated monthly pairings. DTC operators leverage blockchain-verified sourcing narratives for ESG-conscious institutional gifting.
- Supermarkets:Mass-market shelf space demands scaled manufacturing and simplified SKU matrices. Mars Incorporated dominates this channel through existing retail distribution networks.
- Specialty Stores:Curated regional wine-chocolate pairings and limited-edition releases command disproportionate margin pools. Bordeaux and Zurich boutiques exploit AOC-designated vineyard relationships.
- Duty-Free Shops:Buyer concentration among airport retail operators consolidates assortment authority into fewer procurement desks. Lindt and Ferrero leverage established relationships to control access across Frankfurt, Amsterdam Schiphol, and Zurich.
Duty-free shops move the highest unit value; online retail is gaining share fastest through subscription retention mechanics.
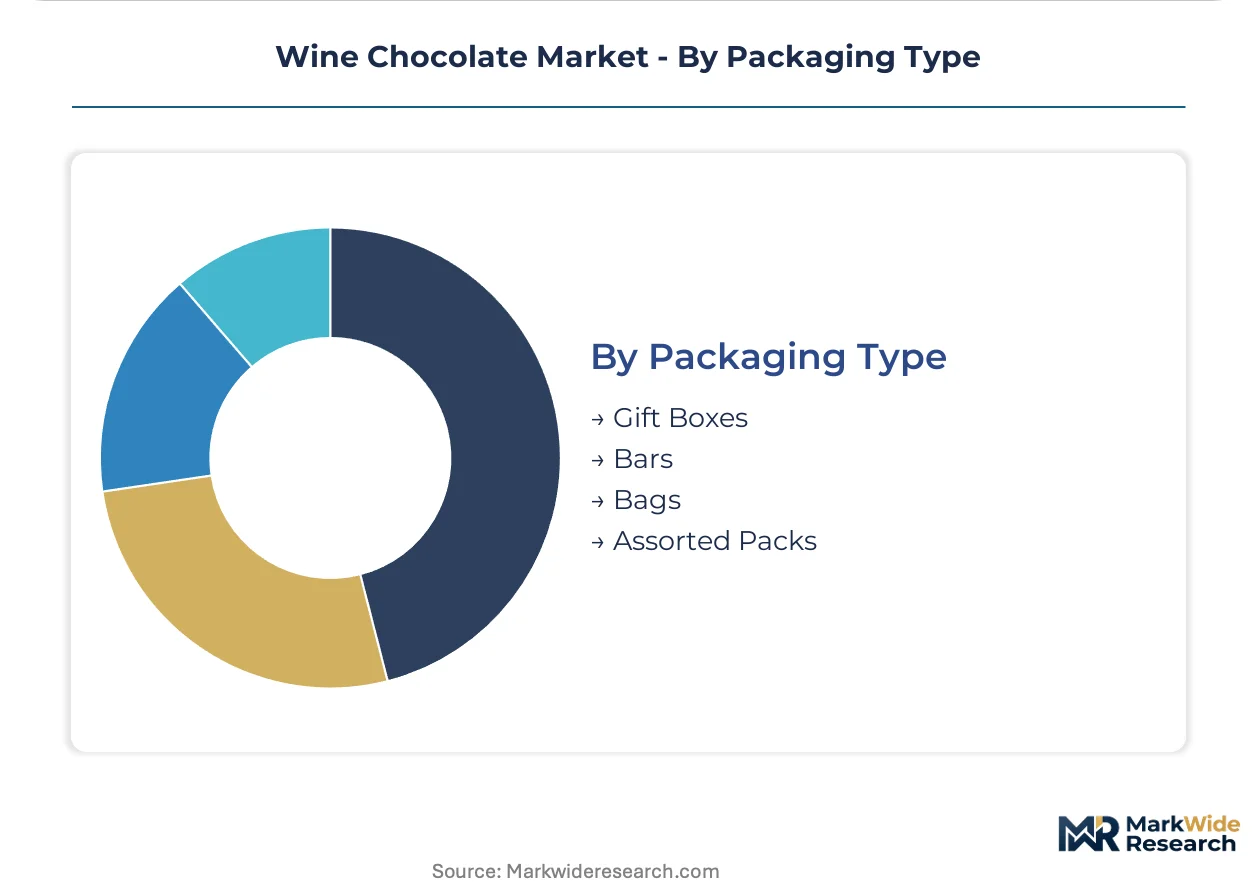
Packaging Type:
Customer type and purchase occasion dictate format selection, with institutional buyers favoring scalable units and individual gifters prioritizing perceived craftsmanship.
- Gift Boxes:Multi-piece assortments with vineyard-specific provenance documentation satisfy premium gifting requirements. QR-linked blockchain verification responds to EU Green Deal traceability mandates.
- Bars:Single-origin formulations with embossed terroir designations target connoisseur self-purchase and collector markets.
- Bags:Bite-sized formats optimize for hospitality minibar replenishment and event venue portion control.
- Assorted Packs:Variable cocoa percentage ranges enable exploratory sampling across wine-chocolate pairing preferences.
Gift boxes capture the dominant revenue pool; assorted packs are expanding most quickly as discovery-oriented purchasing proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German heritage chocolatiers export premium wine chocolate formulations through Frankfurt and Zurich duty-free corridors into intra-European retail channels. Swiss precision tempering equipment flows into Belgian and Dutch manufacturing plants. Italian prosecco-derived variants reach Asian markets via Milan Malpensa logistics hubs.
Germany
Heritage chocolatiers in Cologne and Aachen leverage regional Riesling terroir associations for premium gifting assortments. EFSA alcohol-in-food labeling reforms mandate reformulation transparency for cross-border retail eligibility. Frankfurt Airport duty-free infrastructure anchors category visibility through consolidated procurement desks controlling seventy percent of travel retail chocolate space.
Switzerland
Swiss conching expertise sustains premium positioning across European airport retail through precision tempering technology adoption. REACH chemical safety standards govern wine-derived aromatic compound usage in food contact materials. Zurich duty-free channels concentrate buyer authority among three procurement desks, locking out emerging competitors without established relationships.
Belgium
Mid-tier manufacturers adopt precision conching systems with real-time aromatic monitoring at accelerating rates. EU Green Deal supply-chain traceability requirements mandate farm-to-bar documentation for cocoa inputs. Brussels specialty distributors curate AOC-verified wine-chocolate pairings for Bordeaux and Tuscany restaurant channels.
Italy
Italian producers exploit white chocolate flexibility for prosecco-derived limited editions targeting fruit-forward wine infusion preferences. CSRD-aligned sourcing requirements reward controlled cocoa procurement with ESG-scoring advantages. Tuscan boutique chocolatiers pioneer vineyard-specific collaborations with naturally occurring anthocyanin pigment formulations.
France
French chocolatiers lead ruby chocolate visual differentiation through vineyard-specific collaborations exploiting distinctive color profiles without artificial additives. ANSM national health safety agency oversees alcohol-content threshold compliance for confectionery formulations. Bordeaux specialty stores capture disproportionate margins through limited-edition AOC-designated vineyard releases.
Wine Chocolate Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidated buyer concentration among airport retail operators fragments competitive access for emerging entrants without established duty-free relationships. Three strategic archetypes dominate: heritage European chocolatiers with terroir positioning, mass-market manufacturers with scaled distribution networks, and boutique specialists with AOC-verified supply chains. Dominant competitive moves include strategic partnerships with vineyard designations and portfolio diversification into ruby chocolate variants.
Among heritage European chocolatiers, Lindt & Sprüngli and Ferrero S.p.A. occupy positions exemplifying channel-control archetypes through established duty-free relationships. Mars Incorporated represents scale-driven mass-market positioning across retail distribution networks. These three entities anchor the competitive structure without exhaustive market coverage.
| Leading Market Players |
|---|
| Lindt & Sprüngli |
| Ferrero S.p.A. |
| Mars Incorporated |
| Underberg AG |
| Yildiz Holdings |
| Alfred Ritter |
| NEUHAUS |
| Amedei Tuscany |
| Duc d'O |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Swiss precision tempering equipment manufacturing is tightening supplier pricing power while compressing lead times for Belgian and Dutch mid-tier producers seeking quality parity with heritage brands.
Pricing Analysis
Precision tempering technology-generation pricing gaps separate legacy batch-based artisanal systems from industrial-scale real-time aromatic monitoring installations. Three-tier pricing structure across premium, standard, and economy levels stratifies by cocoa butter content certification and vineyard provenance documentation. Price differentiation rests on EFSA-compliant labeling tier and duty-free channel access rights. Pricing pressure stems from synthetic wine flavor compound substitution in economy segments, with mass-market buyers exhibiting highest price sensitivity while airport retail operators demonstrate lowest.
Supply Chain Analysis
Upstream feedstock concentration in Côte d'Ivoire, Ghana, and Ecuador anchors cocoa butter sourcing for couverture-grade formulations. Wine reduction inputs draw from Bordeaux, Tuscany, and Rhine Valley AOC-designated vineyards. Supply chain risk centers on West African cocoa commodity price volatility and EFSA alcohol-content threshold fragmentation. Distribution runs through Frankfurt, Zurich, and Amsterdam Schiphol duty-free corridors into intra-European retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wine chocolate demand is recovering from cyclical compression in corporate gifting budgets, with premium consumer segments leading the rebound as duty-free passenger traffic normalizes.
For Market Incumbents: Pre-empt synthetic flavor compound displacement by accelerating blockchain-verified farm-to-bar documentation investments. Lock in AOC-designated vineyard exclusivity agreements before boutique competitors consolidate regional terroir access. Channel control through consolidated airport retail procurement desks remains the critical defensive lever against mid-tier encroachment. For New Entrants and Emerging Players: Direct-to-consumer subscription models in German-speaking markets represent the most penetrable entry point given established logistics infrastructure and ESG-conscious institutional gifting demand. Ruby chocolate variant development offers visual differentiation without artificial additive investment. Partner with Tuscan boutique vineyards for limited-edition anthocyanin pigment collaborations to bypass duty-free slotting fee barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision conching system manufacturing as real-time aromatic monitoring becomes table stakes. Five-to-ten year viability favors heritage European chocolatiers with established EFSA compliance infrastructure and controlled cocoa procurement relationships. Monitor CSRD-aligned sourcing disclosure requirements as the signal for institutional channel access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| AOC Vineyard Partnership | Terroir-exclusive supply agreements with Bordeaux and Rhine Valley producers defend premium positioning against synthetic substitutes. |
| Blockchain Traceability Integration | QR-linked farm-to-bar documentation satisfies EU Green Deal mandates for institutional gifting channel eligibility. |
| Precision Conching Upgrade | Real-time aromatic monitoring systems narrow quality gaps between artisanal and industrial production economics. |
| Duty-Free Procurement Desk Access | Relationships with Frankfurt, Zurich, and Amsterdam Schiphol buyers control seventy percent of European travel retail chocolate space. |
| Ruby Chocolate Variant Launch | Naturally occurring anthocyanin pigments enable vineyard-specific visual differentiation without artificial additive investment. |
Methodological Framework
The analysis maps dark chocolate, milk chocolate, white chocolate, and ruby chocolate sub-sectors, each validated through heritage chocolatier technical directors, airport retail procurement managers, AOC vineyard supply coordinators, and EFSA regulatory affairs specialists. Primary interview insights triangulate against customs trade data for cocoa butter imports, EFSA guidance document repositories, EU Green Deal traceability requirement filings, and Nielsen retail audit data for duty-free channel performance. Bottom-up segment sizing reconciles with top-down market value estimates across product type, end user, and distribution channel dimensions.
Assumptions held fixed include EFSA alcohol-in-food labeling reform implementation timelines and EU Green Deal supply-chain traceability phase-in schedules, while cocoa commodity price trajectories and duty-free passenger traffic recovery rates were varied across sensitivity scenarios. Segmentation modeling incorporates product type chemistry requirements, end user procurement authority structures, and channel margin capture economics. CAGRs derive from segment-level volume and value buildups incorporating precision tempering technology adoption curves and AOC-designated vineyard collaboration expansion rates.
Practitioners should monitor EFSA-FDA labeling harmonization delays and West African cocoa harvest variability for early signals requiring forecast revision. Cross-checking against IATA passenger traffic benchmarks and ICCO cocoa supply projections is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
North America Tequila Market
Alcoholic Beverages
Fruit Brandy Market
Alcoholic Beverages
United States Spirits Market
Alcoholic Beverages
Dark Beer Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Industrial Alcohol Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Premium Wine Cooler Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Wine Cellar Market
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
Automated Brewing System Market