
 Germany Dairy Alternatives Market | 2026-2036
Germany Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Dairy Alternatives Market Insights
Oat protein is decoupling Germany's dairy alternatives sector from soy-dependent cost structures that dominated prior decades. Danone SA leverages its fermentation expertise to anchor shelf-stable yogurt alternatives across German retail chains. Oatly Group AB competes through dedicated oat-milk processing infrastructure near its Malmö supply base. Alpro GmbH dominates the extended-shelf-life segment with aseptic carton formats purpose-built for German supermarket logistics.
Germany dairy alternatives comprise formulated plant-based beverages, cultured products, and solid analogs designed to replicate the functional properties—emulsification, mouthfeel, protein content—of conventional dairy through enzymatic treatment, fermentation, or mechanical homogenization of oilseed, cereal, or nut substrates. Plant-based milk leads volume as the most mature substitution category with established cold-chain and ambient distribution protocols. Cheese substitutes capture accelerating foodservice interest as meltability and stretchability formulations improve. Yogurt alternatives sustain premium positioning through live-culture claims and probiotic alignment with German consumer health priorities.
The Federal Ministry of Food and Agriculture enforces strict labeling protocols that distinguish "milk" from plant-based descriptors, while EU EFSA standards govern novel protein safety assessments for emerging oat and pea isolates. German organic certification through BNN and EU organic regulations shape ingredient sourcing requirements and price positioning. Stakeholders must monitor evolving EU protein-strategy funding allocations and Berlin's municipal procurement preferences that increasingly specify climate-accounted food alternatives.
Market Dynamics
Oat protein extraction infrastructure is decoupling Germany's dairy alternatives sector from soy-dependent cost structures that dominated prior decades. The Federal Ministry of Food and Agriculture's protein strategy redirects agricultural subsidies toward domestic legume and grain cultivation, reshaping raw material sourcing geography and supplier economics across the value chain.
Growth Catalysts
- EU Green Deal agricultural subsidies:The framework redirects CAP payments toward legume cultivation for alt-milk processing, expanding domestic oat and pea protein supply.
- Berlin municipal procurement:Climate-accounted food mandates in public cafeterias and hospitals create institutional demand pull for plant-based alternatives.
- Enzymatic hydrolysis advances:Improved protein solubility and mouthfeel matching enable cultured product formats to replicate conventional dairy functional properties.
Market Restraints
- EFSA novel food approval timelines:Safety assessments for emerging oat and pea protein isolates create 18-24 month market entry delays.
- Organic ingredient supply concentration:BNN-certified oat sourcing clusters in northern Germany and southern Sweden, creating geographic dependency risk.
- Technical limitation in cheese analogs:Meltability and stretchability formulations remain below foodservice performance thresholds for pizza and fondue applications.
Strategic Opportunities
- Hamburg foodservice corridor:Cruise terminal and airport catering contracts specify plant-based alternatives, creating volume anchor demand.
- Live-culture yogurt positioning:Probiotic alignment with German consumer health priorities enables premium pricing in refrigerated dairy cases.
- Extended-shelf-life carton innovation:Aseptic packaging formats reduce cold-chain dependency and unlock discount retail channel access.
Industry Challenges
- Fermentation technician scarcity:Industrial-scale precision fermentation for yogurt alternatives requires specialized microbiology expertise concentrated in pharmaceutical and brewing sectors.
- Dual certification complexity:Simultaneous EU organic and BNN compliance creates documentation burden and audit timeline coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Dairy Alternatives Market |
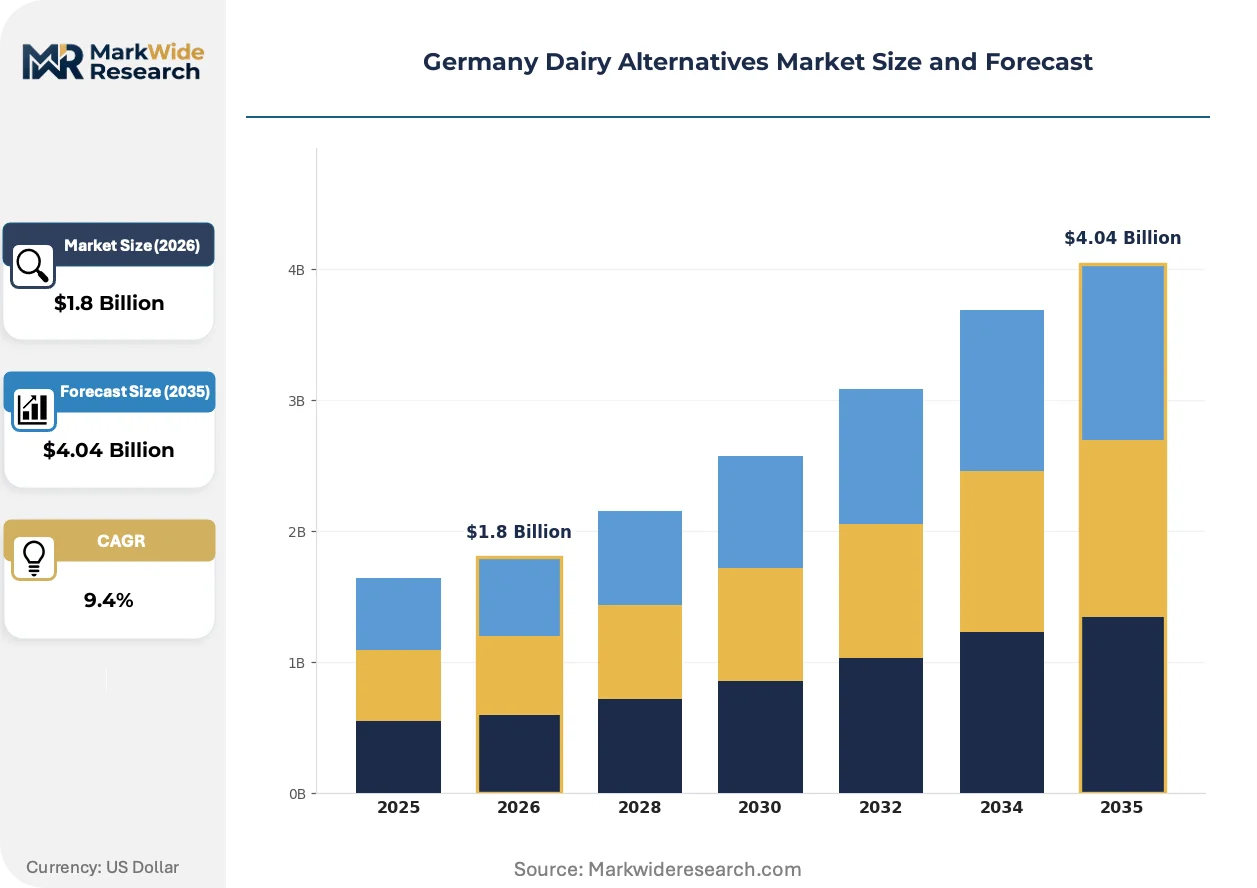
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Milk, Yogurt Alternatives, Cheese Substitutes, Ice Cream Alternatives Consumer Type: Health-Conscious Consumers, Vegans, Lactose Intolerant Individuals, Flexitarians Packaging Type: Bottles, Tetra Packs, Cartons, Jars Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Shops |
| Companies Covered | Upfield Holdings BV, Bel Group, Danone SA, Veganz Group, Alpro GmbH, Nestlé SA, AlnaturA Produktions- und Handels GmbH, Simply V, Oatly Group AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Dairy Alternatives Market Trends and Innovations
Precision fermentation and enzymatic treatment protocols are compressing the functional gap between plant-based analogs and conventional dairy. Three convergent forces—automation of protein extraction, regulatory clarity on labeling, and procurement specification of climate-accounted alternatives—are restructuring competitive positioning and channel access.
Membrane filtration technology is automating the concentration and separation of oat proteins at commercial scale. Mid-sized dairy processors in Bavaria and Baden-Württemberg are retrofitting existing whey processing lines for oat milk production within 12-18 month cycles. This capital-light conversion path is compressing the traditional 5-year infrastructure buildout timeline for new entrants.
Germany's Federal Ministry enforces strict labeling protocols that distinguish "milk" from plant-based descriptors under EU food information regulations. The industrial consequence is standardized packaging communication that reduces consumer confusion while creating defendable brand positioning territory. Cheese substitute manufacturers face the tightest compliance scrutiny given historical dairy sector political influence.
Foodservice procurement in Munich and Hamburg is specifying climate-accounted alternatives in institutional contracts. Hospital and university catering operators are displacing conventional dairy with oat-based beverages through centralized purchasing mandates. Berlin's vegan restaurant density creates concentrated demand for specialty cultured products with live-culture claims.
Germany Dairy Alternatives Market Segmentation
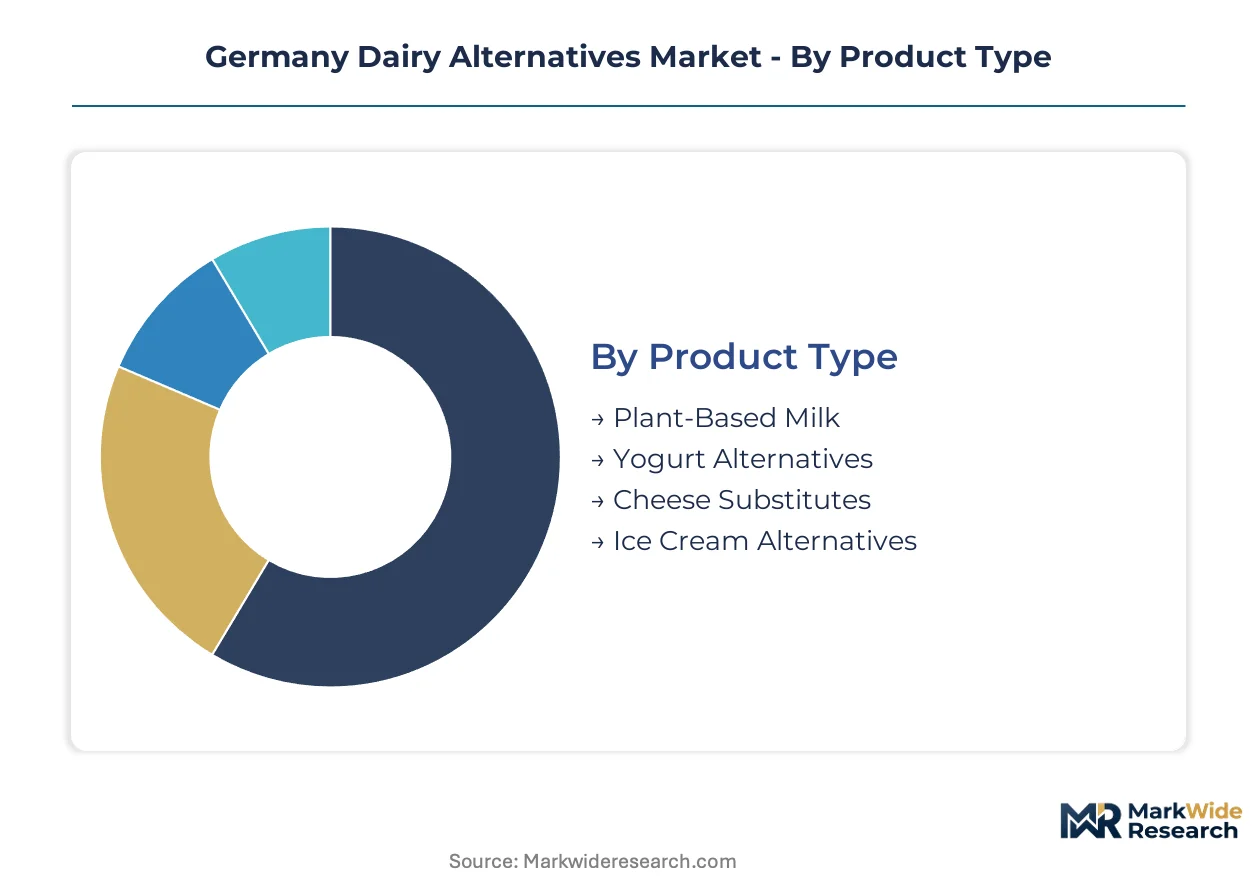
Segmentation in Germany's dairy alternatives market reveals distinct purchasing logics that shape formulation priorities, packaging investments, and channel strategy. Manufacturers must align product architecture with specific consumer health motivations and retail format requirements to capture shelf space and repeat purchase.
Product Type:
German households select dairy alternatives based on functional replication needs and meal-context compatibility rather than single-attribute substitution.
- Plant-Based Milk:Oat and almond formulations dominate German retail, with enzymatic hydrolysis improving mouthfeel to match conventional dairy in coffee and baking applications. Berlin and Hamburg supermarkets report highest velocity for barista-specific foaming variants.
- Yogurt Alternatives:Live-culture positioning with probiotic strains anchors premium pricing in refrigerated cases. Munich's health-focused retail corridors sustain demand for coconut and oat-based skyr alternatives with protein parity claims.
- Cheese Substitutes:Meltable formulations for pizza and sandwich applications drive foodservice procurement in institutional catering contracts.
- Ice Cream Alternatives:Ben & Jerry's and local craft producers compete on indulgence positioning with cashew and oat fat bases.
Plant-Based Milk leads on scale; Yogurt Alternatives lead on momentum.
Consumer Type:
Purchase frequency and price tolerance diverge sharply across motivation-based segments, requiring differentiated communication and distribution depth.
- Health-Conscious Consumers:Protein content and clean-label ingredient lists drive selection, with organic certification through BNN commanding 15-25% price premiums in specialty retail.
- Vegans:Ethical alignment and complete nutritional adequacy requirements sustain loyalty to brands with transparent supply chain documentation.
- Lactose Intolerant Individuals:Functional necessity purchases concentrate in mass retail channels with family-size formats and promotional sensitivity.
- Flexitarians:Experimentation with hybrid consumption patterns creates trial demand for novel formats and limited-edition flavor launches.
Flexitarians expand the addressable base; Health-Conscious Consumers deliver margin.
Packaging Type:
Format selection in Germany reflects cold-chain infrastructure maturity, retail logistics constraints, and consumer convenience expectations across consumption occasions.
- Tetra Packs:Aseptic carton technology enables ambient distribution and extended shelf life, unlocking discount retail channel access across rural Germany.
- Bottles:Refrigerated PET and glass formats signal freshness and premium positioning in urban convenience and specialty channels.
- Cartons:Gable-top refrigerated containers dominate fresh oat milk segments with shorter shelf life and local production claims.
- Jars:Glass packaging for yogurt alternatives and spreads supports reuse and deposit-return system compliance in German retail.
Tetra Packs capture volume efficiency; Bottles sustain premium differentiation.
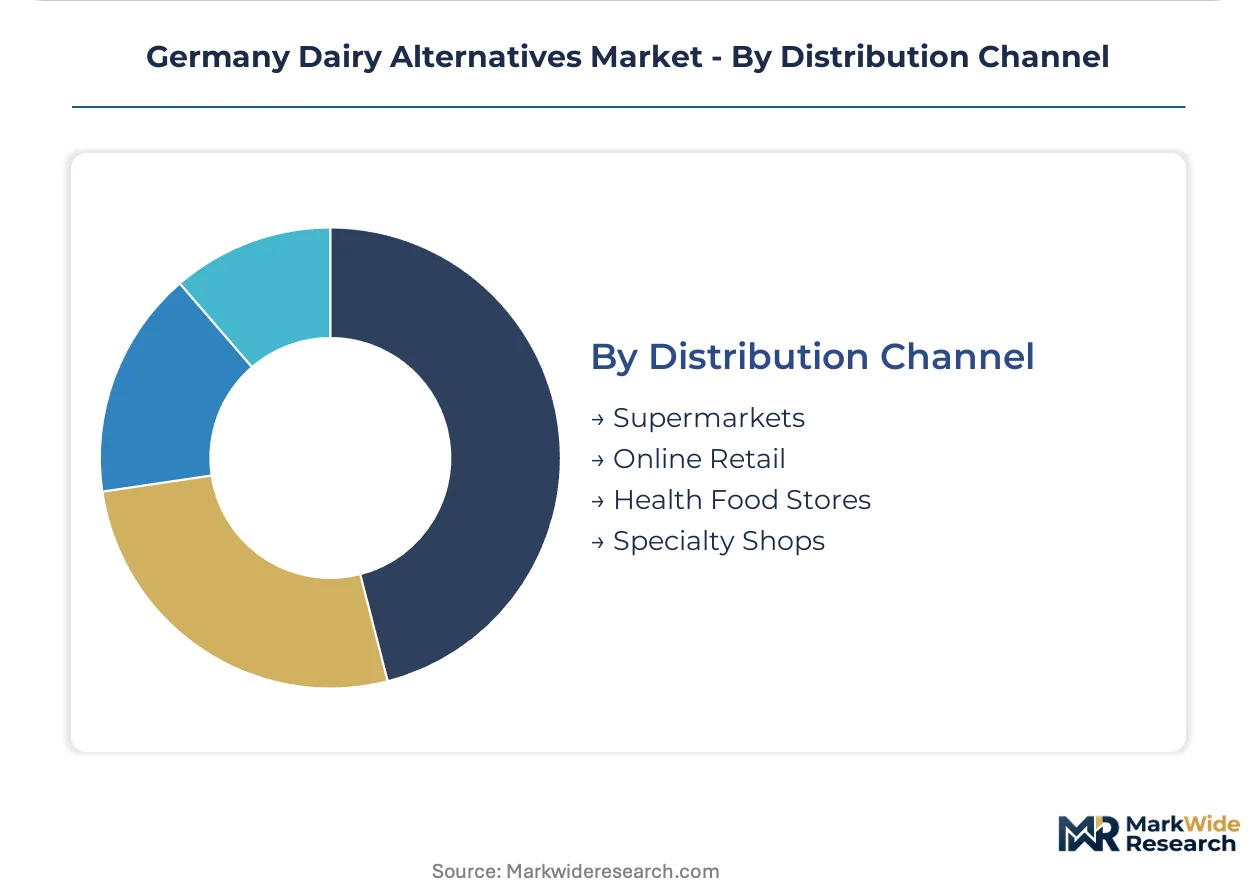
Distribution Channel:
Channel strategy must account for Germany's concentrated retail consolidation and the regulatory complexity of organic certification display requirements.
- Supermarkets:Edeka, Rewe, and Aldi Süd control the majority of volume, with private-label expansion compressing branded shelf space in standard plant-based milk.
- Online Retail:Subscription models and direct-to-consumer platforms sustain niche and imported specialty products with limited brick-and-mortar distribution.
- Health Food Stores:Alnatura and independent organic retailers maintain stricter BNN and EU organic compliance standards with educated staff consultation.
- Specialty Shops:Vegan boutiques in Berlin's Friedrichshain and Munich's Glockenbachviertel curate cultured products and artisan cheese substitutes for dedicated consumers.
Supermarkets concentrate volume throughput; Specialty Shops generate product discovery and trend translation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin-Brandenburg anchors Germany's dairy alternatives demand through its dense vegan restaurant network and municipal procurement mandates. The Federal Ministry of Food and Agriculture's protein strategy redirects agricultural subsidies toward domestic oat and legume cultivation, reshaping raw material sourcing across federal states.
Bavaria
Munich's health-focused retail corridors sustain premium demand for live-culture yogurt alternatives with probiotic claims. The Bavarian State Ministry for Food, Agriculture and Forestry enforces strict organic certification protocols through EU organic regulations. Mid-sized dairy processors in Baden-Württemberg retrofit existing whey processing lines for oat milk production within compressed 12-18 month cycles.
North Rhine-Westphalia
Cologne and Düsseldorf concentrate foodservice procurement for meltable cheese substitutes in institutional catering contracts. EFSA novel food approval timelines for emerging oat and pea protein isolates create 18-24 month market entry delays affecting regional innovators. The Rhine-Ruhr industrial corridor hosts retrofitting facilities converting traditional dairy infrastructure for plant-based beverage production.
Hamburg
Cruise terminal and airport catering contracts specify climate-accounted plant-based alternatives, creating volume anchor demand for oat-based beverages. Hamburg's municipal procurement policies increasingly mandate climate-accounted food alternatives in public institutions. The port city's logistics infrastructure enables efficient distribution of aseptic carton formats to discount retail channels across northern Germany.
Baden-Württemberg
Stuttgart's automotive industry workforce drives demand for convenient plant-based milk formats in workplace catering and retail. BNN-certified oat sourcing clusters create geographic dependency risk for organic ingredient supply. Precision fermentation specialists in the region leverage pharmaceutical and brewing sector microbiology expertise for yogurt alternative production.
Lower Saxony
Hanover's central location supports distribution hub operations for extended-shelf-life carton formats penetrating rural discount retail. The EU Green Deal's Common Agricultural Policy redirects payments toward legume cultivation for alt-milk processing, expanding domestic protein supply. Agricultural cooperatives in the region transition grain cultivation toward oat varieties optimized for beverage processing.
Germany Dairy Alternatives Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and retail channel access. The market exhibits tiered concentration with multinational food conglomerates holding ambient distribution advantages while domestic specialists capture organic and live-culture segments. Three archetypes dominate: fermentation-anchored dairy diversifiers, oat-native specialists with Malmö-proximate supply bases, and private-label manufacturers serving consolidated German retail. Competitive moves center on retrofitting existing dairy infrastructure and securing BNN-EU dual organic certification.
Within the fermentation-anchored tier, Danone SA and Bel Group exemplify dairy incumbents leveraging existing microbiology capabilities for cultured product expansion. Among oat-native specialists, Oatly Group AB occupies a position defined by dedicated processing infrastructure near Nordic grain supply clusters. Alpro GmbH anchors the extended-shelf-life segment through aseptic format expertise purpose-built for German supermarket logistics. Upfield Holdings BV represents the plant-based spread and cheese analog archetype with European formulation heritage.
| Leading Market Players |
|---|
| Upfield Holdings BV |
| Bel Group |
| Danone SA |
| Veganz Group |
| Alpro GmbH |
| Nestlé SA |
| AlnaturA Produktions- und Handels GmbH |
| Simply V |
| Oatly Group AB |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up oat processing specialists anchor Germany's dairy alternatives supply base, translating concentrated upstream ownership into disciplined pricing architecture across retail tiers. Their Malmö-proximate infrastructure and BNN-certified sourcing clusters enable margin defense against volatile grain inputs while sustaining premium positioning in Berlin and Hamburg foodservice channels.
Pricing Analysis
Input-cost pass-through from Nordic oat protein concentrates and enzymatic hydrolysis reagents shapes pricing architecture across German retail tiers. Three-tier pricing structure across premium, standard, and economy levels separates BNN-certified organic variants from conventional formulations and private-label economy formats. Price differentiation rests on certification grade and volume scale, with bulk institutional contracts commanding steepest discounts. Pricing pressure stems from Aldi Süd and Lidl private-label expansion in ambient plant-based milk, compressing branded shelf space and promotional budgets. Lactose-intolerant households in mass retail channels exhibit highest price sensitivity, while health-conscious consumers in Munich's specialty corridors tolerate 15-25% organic premiums.
Supply Chain Analysis
Freight cost escalation across Baltic Sea routes and Rhine-Ruhr inland corridors reshapes sourcing economics for German dairy alternatives manufacturers. Supply concentrates in southern Sweden for BNN-certified oat cultivation, northern Germany for domestic grain processing, and the Netherlands for aseptic packaging equipment. Raw material dependencies span oat protein isolates, live-culture fermentation strains, and barrier-coated carton substrates. Single-source vulnerability in precision fermentation microbiology expertise—concentrated among pharmaceutical and brewing sector technicians—creates recruitment bottlenecks for yogurt alternative scale-up. Distribution runs through Edeka and Rewe's consolidated retail networks, with Hamburg's port infrastructure enabling efficient penetration of discount channels across rural federal states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's dairy alternatives market compounds as a regulatory play, with the EU Green Deal's CAP subsidy redirection toward legume cultivation creating structural demand pull for domestic oat and pea protein supply.
For Market Incumbents: Anticipate margin compression from private-label expansion by retrofitting existing dairy infrastructure for oat milk production within compressed cycles. Secure dual BNN-EU organic certification ahead of evolving Berlin municipal procurement mandates that specify climate-accounted alternatives. Prioritize fermentation technician recruitment from pharmaceutical and brewing sectors to defend live-culture yogurt positioning against oat-native specialists. For New Entrants and Emerging Players: Begin with Hamburg's cruise terminal and airport catering corridor, where climate-accounted procurement specifications create volume anchor demand with limited incumbent penetration. Target meltable cheese substitute formulations for pizza and fondue applications, where technical performance gaps persist below foodservice thresholds. Pursue direct-to-institutional sales models bypassing consolidated retail gatekeepers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized Bavarian and Baden-Württemberg dairy processors holding retrofit-ready whey processing lines and established retail relationships. Long-term viability hinges on capturing organic-certified supply chain control as EU protein strategy subsidies reshape agricultural economics. Watch EFSA novel food approval timelines for oat and pea protein isolates as inflection signals for ingredient cost compression and competitive entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Dairy Infrastructure | Bavarian processors convert whey lines to oat milk within 12-18 month cycles, compressing capital requirements. |
| Dual Organic Certification | Simultaneous BNN-EU compliance unlocks Berlin municipal procurement and Alnatura channel access. |
| Precision Fermentation Scale-Up | Live-culture yogurt alternatives command premium positioning in Munich's health-focused retail corridors. |
| Aseptic Carton Innovation | Extended-shelf-life formats reduce cold-chain dependency and penetrate Aldi Süd discount channels. |
| Foodservice Procurement Capture | Hamburg institutional contracts specify climate-accounted alternatives, creating volume anchors. |
Research Methodology
Coverage spans Germany's federal states, Sweden's Skåne grain belt, and the Netherlands' packaging equipment corridor, with primary inputs from each. The analysis combines structured interviews with plant-based R&D directors, Edeka category buyers, precision fermentation specialists, and BNN certification auditors with secondary validation from EU CAP subsidy disclosures, EFSA novel food registers, and German Federal Ministry agricultural statistics. Bottom-up volume modeling triangulates against top-down protein strategy expenditure flows.
Granularity-level framing applies product type, packaging format, distribution channel, and consumer motivation segments at the federal-state level across the projection horizon. CAGRs derive from enrollment curve analysis of oat protein extraction capacity and elasticity-adjusted price response to private-label share gains. Forecast inputs incorporate EFSA approval pipeline status for emerging isolates and Berlin-Hamburg-Munich municipal procurement specification timelines.
Several conditions sit outside the modeled scope, including abrupt CAP subsidy suspension, EFSA safety reassessment of established oat proteins, and trade disruption in Baltic Sea grain logistics. Forecasts reflect documented assumptions about enzymatic hydrolysis cost curves and fermentation technician labor pool expansion. Stakeholders should weight assumptions against their own operating context and regional certification compliance capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Coconut Cream Market
Dairy Alternatives
Sugar-Free Soy Milk Powder Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
Spelt Milk Market
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
North America Non-Dairy Cheese Market
Dairy Alternatives
Legumes Plant-Based Milk Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
United States Non-Dairy Milk Market
Dairy Alternatives
Dairy-Free Chocolate Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market