
 Calcium Butyrate Market | 2026-2036
Calcium Butyrate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Butyrate Market Analysis
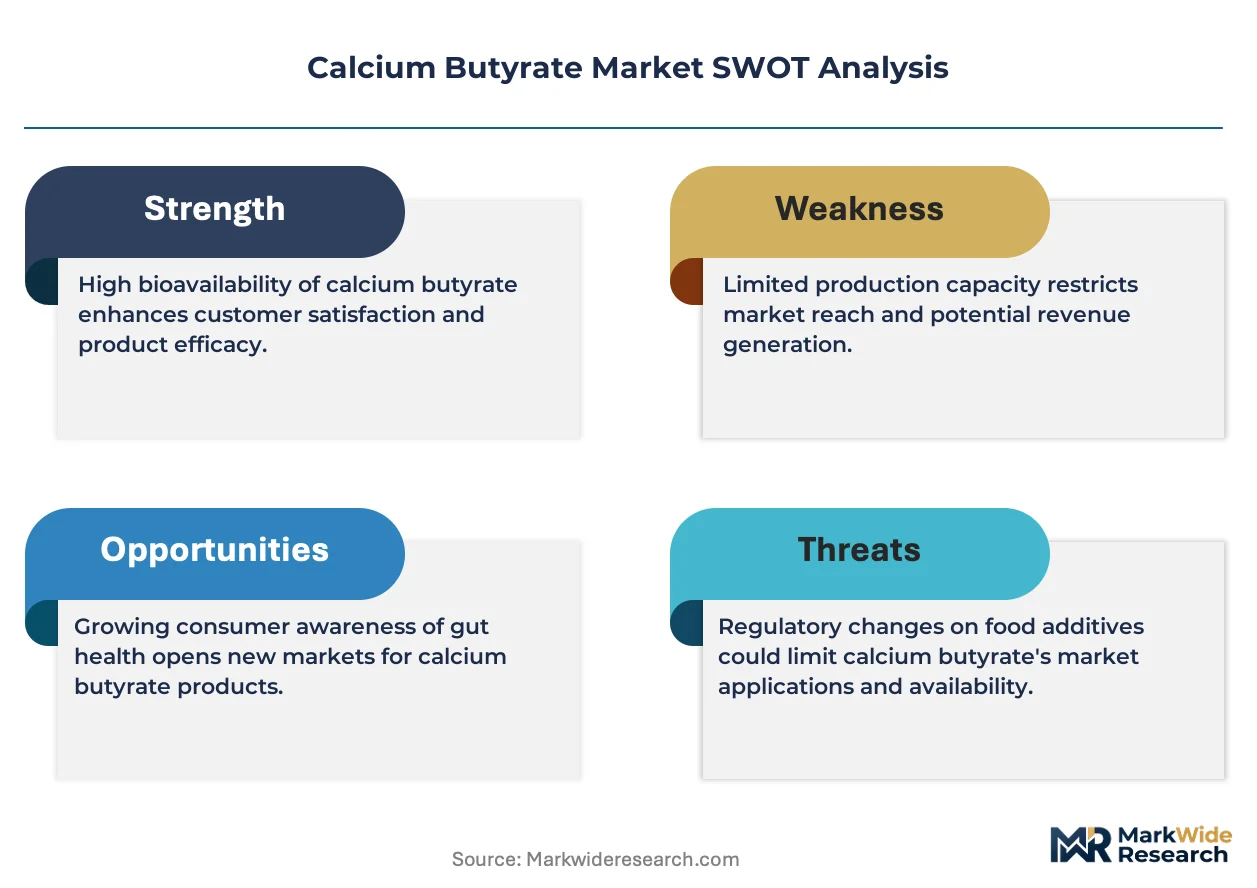
Organic acid blends are consolidating around calcium butyrate as poultry and swine operations phase out zinc oxide and antibiotic growth promoters across major producing regions. Perstorp Holding AB leverages its integrated carboxylic acid platform to sustain cost-advantaged feed additive supply chains from European base chemicals through Asian distribution. Kemin Industries Inc. anchors its position through species-specific gut health formulations that extend beyond commodity butyrate into precision nutrition services. Zhonglan Industry Co. Ltd. competes on manufacturing scale and captive calcium sourcing, controlling raw material cost volatility that challenges smaller Chinese producers.
Calcium butyrate is the calcium salt of butyric acid (C8H14CaO4), typically manufactured through neutralization of butyric acid with calcium hydroxide or carbonate, yielding a white crystalline powder with butyric acid content ranging from 50% to 98% depending on grade and intended use. Its primary industrial purpose centers on intestinal epithelial cell energy metabolism, where it serves as the preferred fuel source for colonocytes and modulates tight junction protein expression to reduce pathogen translocation. Powder and granule formats dominate commercial volumes for feed additive applications, while tablet and liquid formulations capture margin pools in pharmaceutical and dietary supplement channels where dosing precision and patient compliance command price premiums. The feed additive application segment leads absolute volume, though gut health positioning in human nutraceuticals represents the fastest-growing demand pool as microbiome science advances from academic research to formulated consumer products.
FDA feed additive regulations and USDA organic livestock standards shape product formulation requirements and label claims in the United States, while EFSA evaluations under EU Regulation 1831/2003 determine calcium butyrate authorization for specific species and inclusion rates across European member states. China's Ministry of Agriculture and Rural Affairs feed additive catalog and GB standards for compound feed set the compliance baseline for domestic production and import qualification. Stakeholders must monitor evolving maximum residue limits and species-specific withdrawal periods as regulatory agencies tighten antimicrobial stewardship frameworks without restricting performance-enhancing nutritional alternatives.
Market Dynamics
Antibiotic growth promoter bans across major livestock-producing jurisdictions are forcing feed compounders to rebuild formulation protocols around gut health modulators, with calcium butyrate emerging as the preferred energy substrate for intestinal epithelial repair.
Growth Catalysts
- EU Regulation 1831/2003:EFSA's systematic review of feed additive authorizations has validated calcium butyrate for multiple species, creating regulatory certainty that accelerates procurement decisions by European integrators.
- Poultry gut health protocols:Broiler operations in Brazil and Thailand are standardizing butyrate inclusion rates above 500 ppm to control necrotic enteritis without therapeutic antibiotics.
- Butyric acid fermentation advances:Microbial production methods using Clostridium strains are reducing dependency on petroleum-derived butyric acid, improving cost structures for Asian manufacturers.
Market Restraints
- Calcium carbonate price volatility:Feed-grade calcium sourcing concentrates in Hebei province and Rajasthan state, exposing compounders to freight surcharges and export license delays.
- Butyric acid supply concentration:Three European chemical groups control over 60% of synthetic butyric acid capacity, creating bottleneck risk for non-integrated feed additive producers.
- Organic acid substitution:Formic acid and propionic acid blends offer lower unit costs for pH modulation, pressuring butyrate positioning in price-sensitive swine finishing diets.
Strategic Opportunities
- Aquaculture expansion:Shrimp and salmon producers in Vietnam and Norway are trialing butyrate-coated feeds to improve gut integrity under high-density stocking conditions.
- USDA organic livestock standards:Certification requirements for antibiotic-free production create mandatory demand for microbiome-supporting additives in premium meat channels.
- Precision delivery systems:Microencapsulation technology combining butyrate with medium-chain fatty acids enables targeted release in the lower intestinal tract, opening pharmaceutical-tier pricing.
Industry Challenges
- Formulation chemistry expertise:Feed mills lack technical staff to optimize butyrate stability under steam-pelleting temperatures above 85°C, causing degradation losses.
- Dual registration pathways:Separate approvals for feed additive and veterinary medicinal product classifications in Brazil and India extend commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Butyrate Market |
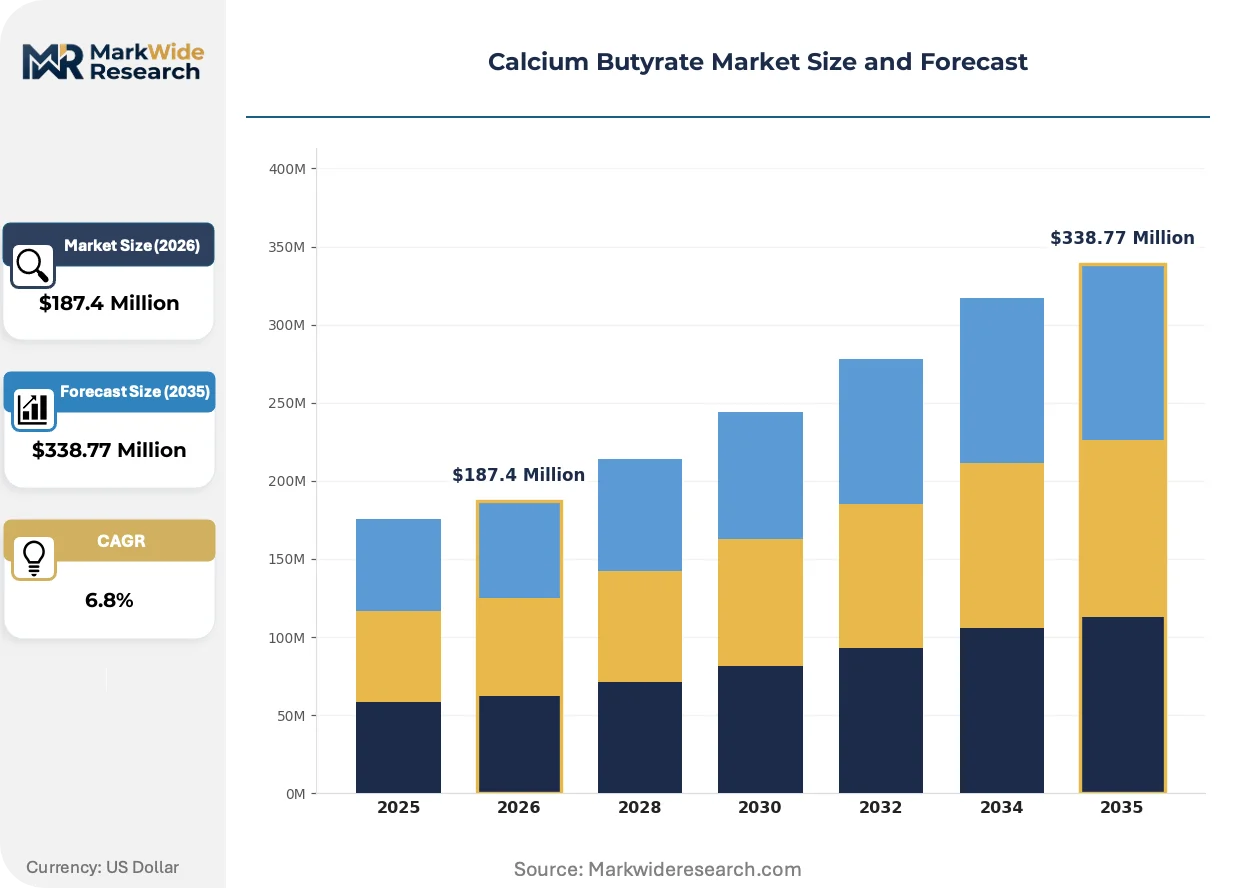
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granule, Powder, Tablet, Liquid End User: Pharmaceuticals, Dietary Supplements, Animal Feed, Food & Beverage Application: Gut Health, Nutritional Enhancement, Lactic Acid Production, Feed Additive Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers |
| Companies Covered | Eastman Chemical Company, Celanese Corporation, Thermo Fisher Scientific Inc., Kemin Industries Inc., Perstorp Holding AB, Snowco Industrial, Nutrients Scientific, Zhonglan Industry Co. Ltd., Yufeng International Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Butyrate Market Emerging Trajectories
Calcium butyrate markets are experiencing rapid product-format diversification as manufacturers compete on bioavailability metrics and handling characteristics rather than commodity purity alone.
Microencapsulated butyrate formats using hydrogenated vegetable oil matrices are overtaking standard powder grades in European poultry premix applications. DSM and Evonik have scaled lipid-embedding capacity to protect butyrate from gastric absorption, enabling distal colon delivery. This format shift is compressing margins on unprotected commodity grades while rewarding patent-protected delivery technologies.
China's Ministry of Agriculture and Rural Affairs revised its feed additive catalog in 2023, explicitly listing calcium butyrate for swine and poultry species with defined maximum inclusion rates. The regulation eliminates provincial interpretation variance that previously blocked inter-provincial trade. Domestic producers in Shandong and Jiangsu are now qualifying for export registration to Southeast Asian markets under harmonized standards.
Integrators are consolidating procurement decisions at headquarters level, bypassing regional feed mill autonomy that historically fragmented additive sourcing. Cargill's protein business and JBS SA have centralized gut health ingredient selection, demanding species-specific efficacy data and supply chain audit documentation. This concentration is visible most acutely in Brazil's southern states, where three protein groups control 70% of broiler feed volume.
Calcium Butyrate Market Segmentation
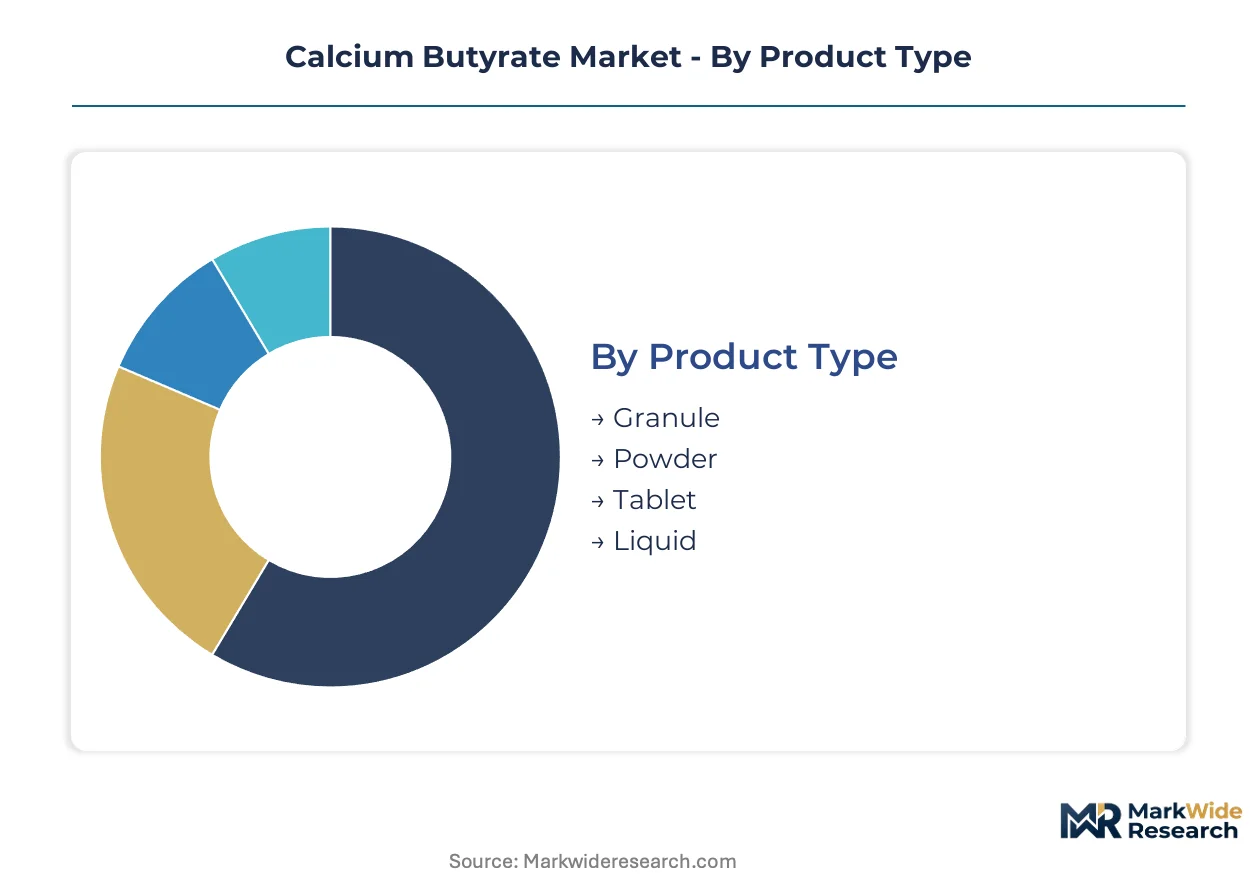
Calcium butyrate manufacturers compete across distinct product formats and customer workflows, with formulation chemistry and delivery precision determining margin capture. Segmentation reveals where technical differentiation commands pricing power versus commodity positioning.
Product Type:
Feed compounders and pharmaceutical formulators upgrade from basic powders to precision-engineered formats as bioavailability requirements tighten across regulatory jurisdictions.
- Granule:Hydrogenated vegetable oil matrices protect butyrate from gastric degradation, enabling distal colon delivery in European poultry operations. DSM and Evonik have scaled lipid-embedding capacity for this format. Brazilian integrators now specify granule grades above 500 ppm inclusion for necrotic enteritis control.
- Powder:Standard crystalline grades with 50-98% butyric acid content dominate feed additive volumes due to lower unit costs. Steam-pelleting temperatures above 85°C cause degradation losses, limiting adoption in high-heat processing environments.
- Tablet:Compressed formats with defined dissolution profiles serve dietary supplement channels where patient compliance and dosing precision command pharmaceutical-tier pricing.
- Liquid:Aqueous solutions facilitate homogeneous distribution in liquid feed systems and aquaculture applications, with Vietnam shrimp producers trialing coated liquid formulations for high-density stocking conditions.
Powder sits at the top of the volume ranking, with granule climbing the fastest.
End User:
Customer sophistication varies dramatically across end-use sectors, with regulatory stringency and technical staff availability shaping format preferences and procurement criteria.
- Animal Feed:Broiler and swine operations in Brazil, Thailand, and China standardize butyrate inclusion as antibiotic growth promoter bans force gut health protocol rebuilding. Feed-grade demand concentrates where livestock operations scale and veterinary drug regulations tighten.
- Pharmaceuticals:Enteric coating and controlled-release specifications require pharmaceutical-grade calcium butyrate with documented impurity profiles and batch-to-batch consistency for regulatory submission packages.
- Dietary Supplements:Microbiome positioning in human nutraceuticals represents expanding demand as consumer science advances from academic research to formulated products with specific colony-forming unit claims.
- Food & Beverage:Flavor masking and thermal stability challenges limit penetration, with niche applications in fermented product categories where butyric acid's characteristic odor aligns with sensory profiles.
Animal Feed generates the largest absolute volume, though Pharmaceuticals maintains the steepest expansion trajectory on a value basis.
Application:
Functional positioning determines formulation complexity, with therapeutic claims requiring veterinary medicinal product registration pathways that extend commercialization timelines.
- Feed Additive:Energy substrate for intestinal epithelial repair dominates procurement volumes, with EFSA authorizations under EU Regulation 1831/2003 validating species-specific inclusion rates.
- Gut Health:Tight junction protein modulation and colonocyte fuel applications drive premium positioning in precision nutrition services extending beyond commodity butyrate.
- Nutritional Enhancement:Mineral fortification and acidification protocols in compound feed leverage calcium butyrate's dual contribution of butyrate anion and calcium cation.
- Lactic Acid Production:Fermentation process optimization in dairy and probiotic manufacturing represents emerging technical applications with specialized purity requirements.
Feed Additive anchors volume concentration, with Gut Health gaining share fastest as microbiome science commercializes.
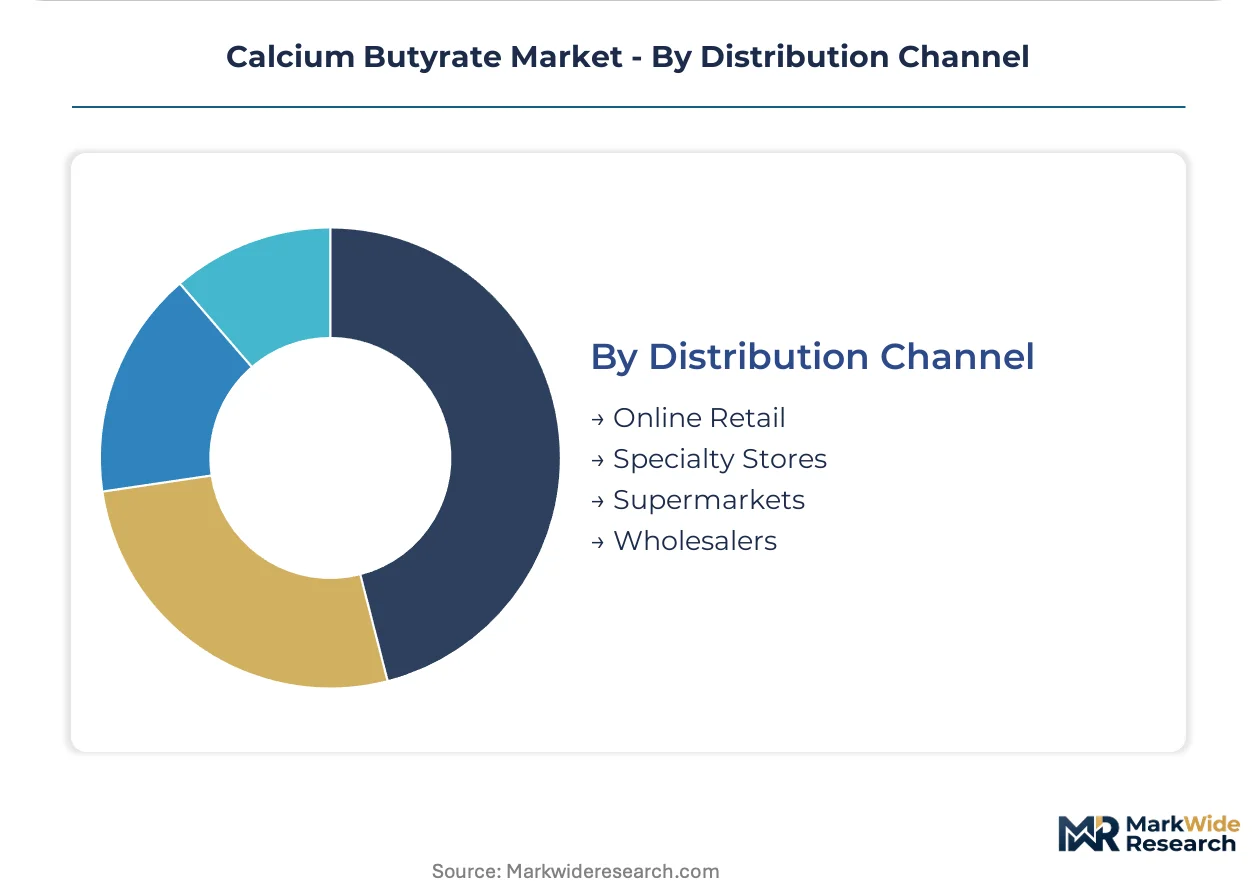
Distribution Channel:
Procurement centralization at integrator headquarters is compressing channel diversity, with direct manufacturer relationships displacing traditional wholesale intermediaries.
- Wholesalers:Regional feed additive distributors maintain relevance in fragmented markets where technical support and inventory financing remain valued.
- Specialty Stores:Nutraceutical and veterinary supply channels serve small-scale livestock operations and companion animal practitioners with smaller lot sizes.
- Online Retail:E-commerce penetration accelerates in dietary supplements as direct-to-consumer microbiome brands bypass traditional retail markup structures.
- Supermarkets:Mass-market food and beverage applications remain minimal due to formulation complexity and sensory challenges.
Wholesalers retain volume leadership in feed-grade segments, with Online Retail expanding most quickly in human health applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors calcium butyrate manufacturing capacity through integrated petrochemical corridors linking butyric acid synthesis to downstream salt production. Regional demand patterns diverge sharply between mature regulatory environments enforcing antibiotic-free livestock protocols and emerging markets scaling industrial animal production.
China
Hebei province's calcium carbonate deposits supply captive feed-grade material to Shandong-based manufacturers, insulating integrated producers from raw material freight volatility. The Ministry of Agriculture and Rural Affairs 2023 feed additive catalog revision eliminated provincial interpretation barriers, accelerating inter-provincial trade and export registration to Vietnam and Indonesia. Jiangsu province fermentation facilities now deploy Clostridium-derived butyric acid to reduce petroleum feedstock dependency.
Brazil
Three protein integrators in Paraná and Santa Catarina states centralize procurement decisions for 70% of southern broiler feed volume, mandating butyrate inclusion above 500 ppm for necrotic enteritis control. ANVISA's veterinary drug residue monitoring tightens antimicrobial stewardship without restricting nutritional alternatives. São Paulo state feed compounders now require species-specific efficacy documentation and supply chain audit trails for headquarters-level approval.
United States
USDA organic livestock certification creates mandatory demand for microbiome-supporting additives in premium meat channels as antibiotic-free production expands across Iowa and North Carolina hog operations. FDA feed additive regulations shape formulation requirements and label claims for intestinal health positioning. California and Texas integrators are consolidating gut health ingredient selection at corporate level, displacing regional mill autonomy.
Germany
EFSA evaluations under EU Regulation 1831/2003 validate calcium butyrate authorizations for multiple species, creating regulatory certainty that accelerates procurement by Dutch and Polish integrators sourcing through German distributors. North Rhine-Westphalia's chemical industry provides synthetic butyric acid feedstock to captive additive operations. Bavaria-based premix formulators now specify microencapsulated grades with hydrogenated vegetable oil matrices for distal colon delivery.
India
Rajasthan state's calcium carbonate deposits expose compounders to export license delays and freight surcharges that concentrate procurement among vertically integrated manufacturers. FSSAI and BIS standards for compound feed set compliance baselines for domestic production as Maharashtra and Gujarat livestock operations professionalize gut health protocols. CDSCO's dual registration pathway for feed additive and veterinary medicinal product classifications extends commercialization timelines by 18-24 months.
Calcium Butyrate Market Vendor Landscape
Global majors compete with regional champions across integrated carboxylic acid platforms and species-specific formulation capabilities. The vendor base organizes around three strategic archetypes: European chemical conglomerates with backward integration into butyric acid synthesis, Asian manufacturers leveraging captive calcium sourcing and fermentation advances, and precision nutrition specialists extending beyond commodity butyrate into microbiome services. Dominant competitive moves include capacity expansion in lipid-embedding microencapsulation and geographic licensing partnerships to bypass dual registration bottlenecks.
Within the integrated chemical tier, Perstorp Holding AB and Eastman Chemical Company exemplify cost-advantaged supply chains spanning base chemical production through regional distribution networks. Kemin Industries Inc. occupies a position in the precision nutrition archetype, anchoring its market presence through gut health formulations that extend into technical services. Zhonglan Industry Co. Ltd. represents the scale-driven Chinese manufacturing segment, competing on manufacturing scale and captive calcium sourcing that controls raw material cost volatility challenging smaller domestic producers.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Celanese Corporation |
| Thermo Fisher Scientific Inc. |
| Kemin Industries Inc. |
| Perstorp Holding AB |
| Snowco Industrial |
| Nutrients Scientific |
| Zhonglan Industry Co. Ltd. |
| Yufeng International Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Microencapsulation technology adoption in European poultry premix applications simultaneously compresses commodity-grade margins and concentrates pricing power among lipid-embedding specialists with patented delivery systems. This format transition redraws cost economics around gastric protection efficacy rather than butyric acid purity alone, rewarding manufacturers with in-house hydrogenated vegetable oil matrix capabilities while exposing standard powder producers to price erosion.
Pricing Analysis
Input-cost pass-through from synthetic butyric acid and calcium carbonate volatility shapes contract structures across feed-grade segments. Three-tier pricing structure across microencapsulated premium, standard granule, and commodity powder levels reflects certification grade and steam-pelleting stability performance. Pricing pressure stems from formic acid and propionic acid blends offering lower unit costs for pH modulation in price-sensitive swine finishing diets. Regional feed mills exhibit highest price sensitivity due to technical staff shortages, while pharmaceutical formulators accept pharmaceutical-tier premiums for documented impurity profiles.
Supply Chain Analysis
Feed additive catalog registration under China's Ministry of Agriculture and Rural Affairs gates inter-provincial trade and export qualification to Vietnam and Indonesia. Manufacturing capacity concentrates in China's Shandong province, Germany's North Rhine-Westphalia chemical corridor, and India's Rajasthan state. Raw material dependencies rest on petroleum-derived butyric acid from European chemical groups, Hebei province calcium carbonate deposits, and fermentation-derived alternatives from Jiangsu province Clostridium facilities. Single-source vulnerability runs through the three European chemical groups controlling over sixty percent of synthetic butyric acid capacity. Distribution runs through integrator headquarters procurement consolidation displacing regional feed mill autonomy, particularly in Brazil's southern states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcium butyrate market compounds steadily as antibiotic growth promoter bans across major livestock-producing jurisdictions mandate gut health protocol rebuilding. Regulatory certainty from EFSA evaluations and China's 2023 feed additive catalog revision provides predictable demand visibility for formulation investments.
For Market Incumbents: Lock in microencapsulation capacity advantages before lipid-embedding technology commoditizes. Perstorp Holding AB's integrated carboxylic acid platform and Kemin Industries Inc.'s species-specific formulation services demonstrate how backward integration into butyric acid synthesis and precision nutrition technical services respectively defend against organic acid substitution threats. Prioritize certification investment for veterinary medicinal product registration pathways in Brazil and India where dual classification extends commercialization timelines. For New Entrants and Emerging Players: Precision delivery systems combining butyrate with medium-chain fatty acids offer a technology-first wedge into pharmaceutical-tier pricing pools where established feed-grade players lack formulation chemistry expertise. Aquaculture applications in Vietnam shrimp and Norway salmon operations represent underpenetrated white-space with high-density stocking conditions driving gut integrity trials. Pursue geographic licensing partnerships to bypass eighteen-to-twenty-four month dual registration bottlenecks in India and Brazil. For Investors and Strategic Acquirers: Valuations sit cheapest among Chinese manufacturers with captive calcium sourcing but limited microencapsulation capabilities, offering consolidation targets for technology transfer. Long-term viability centers on microbiome science commercialization extending butyrate positioning from commodity feed additive into precision nutrition services. Watch for EFSA authorization expansions to additional species as the inflection signal for European procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Capacity Expansion | DSM and Evonik scaling lipid-embedding protects margins against commodity powder erosion. |
| Backward Integration into Fermentation | Jiangsu province Clostridium-derived butyric acid reduces petroleum feedstock dependency for Asian manufacturers. |
| Species-Specific Efficacy Documentation | Brazilian integrators mandating data packages centralizes procurement decisions at headquarters level. |
| Geographic Licensing Partnerships | Joint ventures bypass CDSCO and ANVISA dual registration bottlenecks extending commercialization timelines. |
| Aquaculture Feed Coating Development | Vietnam shrimp producers trialing liquid formulations opens high-density stocking application channel. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with feed compounder procurement directors, veterinary nutritionists at Brazilian protein integrators, pharmaceutical formulators, and regulatory affairs specialists with secondary validation. Trade data from Chinese customs records, EFSA feed additive authorization databases, ANVISA veterinary drug monitoring reports, and SEC filings from publicly traded chemical conglomerates anchored supply-side sizing. Bottom-up segment builds across product formats and end-use applications triangulated against top-down macroeconomic drivers.
Segment-weighting approaches modeled feed additive, gut health, nutritional enhancement, and lactic acid production applications across powder, granule, tablet, and liquid formats. Animal feed, pharmaceutical, dietary supplement, and food and beverage end-use sectors were projected over the analysis window with CAGRs derived from regulatory enforcement trajectories and livestock operation scaling patterns. Butyric acid fermentation technology maturation and integrator procurement centralization served as key forecast inputs.
The model holds under sustained antibiotic growth promoter ban enforcement and stable calcium carbonate supply from Hebei province and Rajasthan state deposits; deviation in EFSA authorization reversals or petroleum feedstock price spikes would shift volume trajectories. A model refresh is warranted upon material change in China's feed additive catalog implementation or major aquaculture butyrate adoption inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
Beverage Encapsulants Market
Food Additives and Ingredients
Russia Food Preservatives Market
Food Additives and Ingredients
Canada Food Emulsifiers Market
Food Additives and Ingredients
India Food Acidulants Market
Food Additives and Ingredients
North America Clean Label Ingredient Market
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market
Food Additives and Ingredients
Global Organic Food Preservatives Market
Food Additives and Ingredients
Anti-Caking Agents Market
Food Additives and Ingredients
Acetylated Monoglycerides (AMG) Market
Food Additives and Ingredients
Spain Food Acidulants Market
Food Additives and Ingredients
Plant-Based Emulsifiers Market
Food Additives and Ingredients
Spain Food Enzymes Market
Food Additives and Ingredients
Gardenia Food Color Market