
 Nutritional Food and Drink Market | 2026-2036
Nutritional Food and Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Nutritional Food and Drink Market Analysis
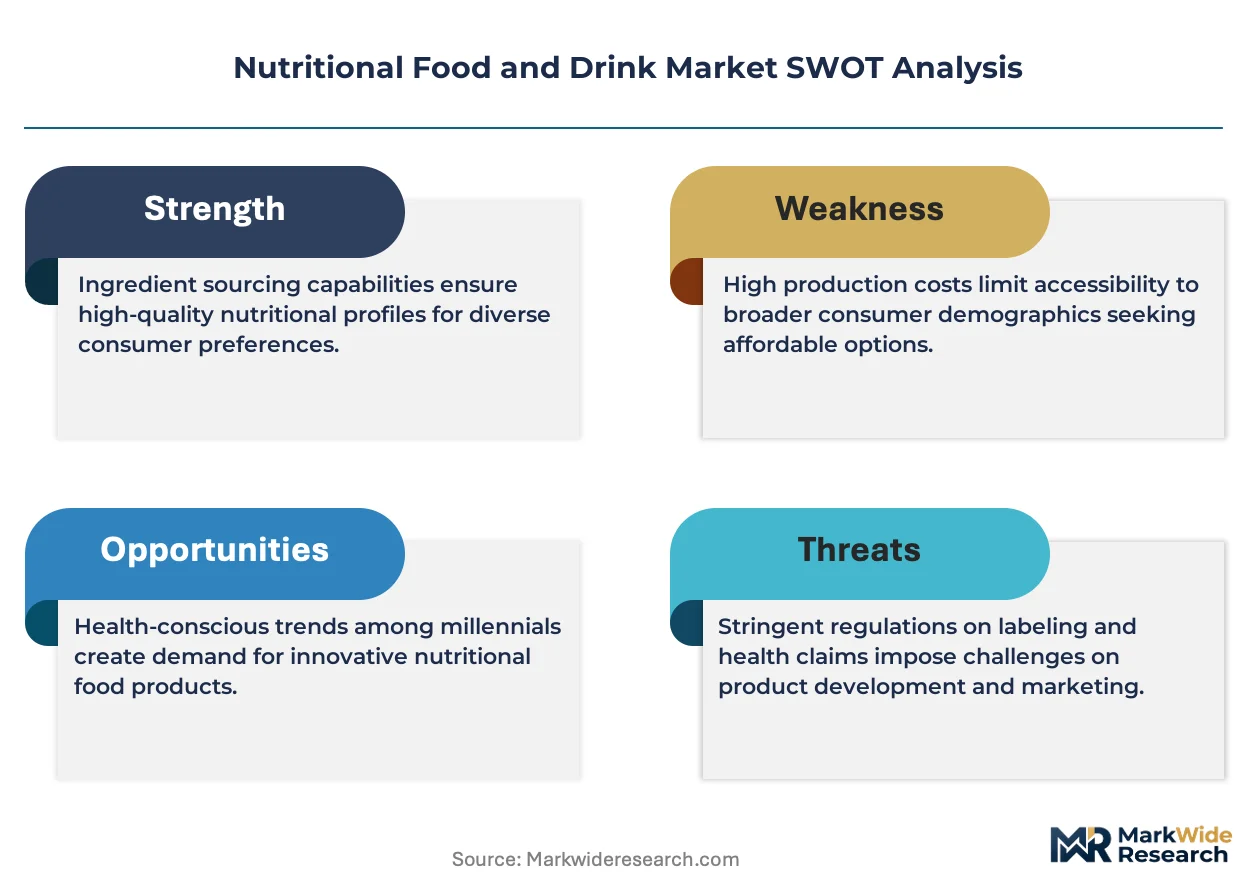
The EU Green Deal is decoupling nutritional product formulation from carbon-intensive supply chains, forcing reformulation across major portfolios. Nestlé leverages its dairy protein infrastructure to anchor European clean-label production. PepsiCo competes through sports nutrition scale in North American convenience channels. Danone differentiates via specialized fermentation capabilities for probiotic functional beverages.
Nutritional food and drink encompasses formulated products delivering targeted macronutrient, micronutrient, or bioactive compound profiles through controlled manufacturing processes such as microencapsulation, spray drying, and cold-aseptic filling to achieve specified shelf stability and bioavailability parameters. These products serve commercial purposes spanning clinical nutrition support, athletic performance optimization, and convenient dietary supplementation. Functional beverages lead product type momentum as ready-to-drink formats capture on-the-go consumption occasions, while sports nutrition maintains the fastest expansion trajectory among fitness enthusiasts. Meal replacements occupy mature positioning with stable margin pools in corporate wellness programs.
EFSA and FDA standards govern label claims and novel ingredient approvals, restricting market access for unverified bioactive formulations. The EU Green Deal and REACH frameworks compound compliance costs for imported ingredient streams. Stakeholders must monitor evolving protein source regulations and carbon disclosure mandates to preserve formulation flexibility and channel placement across priority markets.
Market Dynamics
The EU Green Deal is forcing nutritional food and drink manufacturers to decouple from carbon-intensive dairy and soy supply chains, triggering wholesale reformulation of protein portfolios across functional beverages and sports nutrition segments.
Growth Catalysts
- Clean-label mandates:EFSA disclosure requirements under the EU Green Deal accelerate consumer trust in European-manufactured functional beverages.
- Fitness culture maturation:Sports nutrition adoption deepens among recreational athletes seeking performance optimization beyond professional tiers.
- Microencapsulation advances:Cold-aseptic filling technologies extend shelf stability for bioactive compounds in ready-to-drink formats.
Market Restraints
- Ingredient import friction:REACH compliance costs inflate prices for novel bioactive streams entering European manufacturing facilities.
- Protein source volatility:Pea and fava bean concentrate markets face supply concentration among Canadian and Baltic processors.
- Novel food approval timelines:EFSA novel ingredient pathways stretch 18-24 months, freezing formulation pipelines for fermented proteins.
Strategic Opportunities
- Precision fermentation scale-up:Specialized bioreactor capacity for probiotic beverages remains underdeveloped in Southern Europe.
- Corporate wellness channel expansion:Meal replacement programs penetrate self-insured employer health plans seeking metabolic intervention tools.
- Carbon disclosure differentiation:CSRD-aligned supply chain auditing creates premium positioning for verified low-emission protein sources.
Industry Challenges
- Formulation talent scarcity:Food scientists with dual expertise in bioavailability engineering and clean-label stability command premium compensation.
- Legacy equipment retrofit costs:Cold-aseptic filling lines require capital outlays that strain mid-tier contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutritional Food and Drink Market |
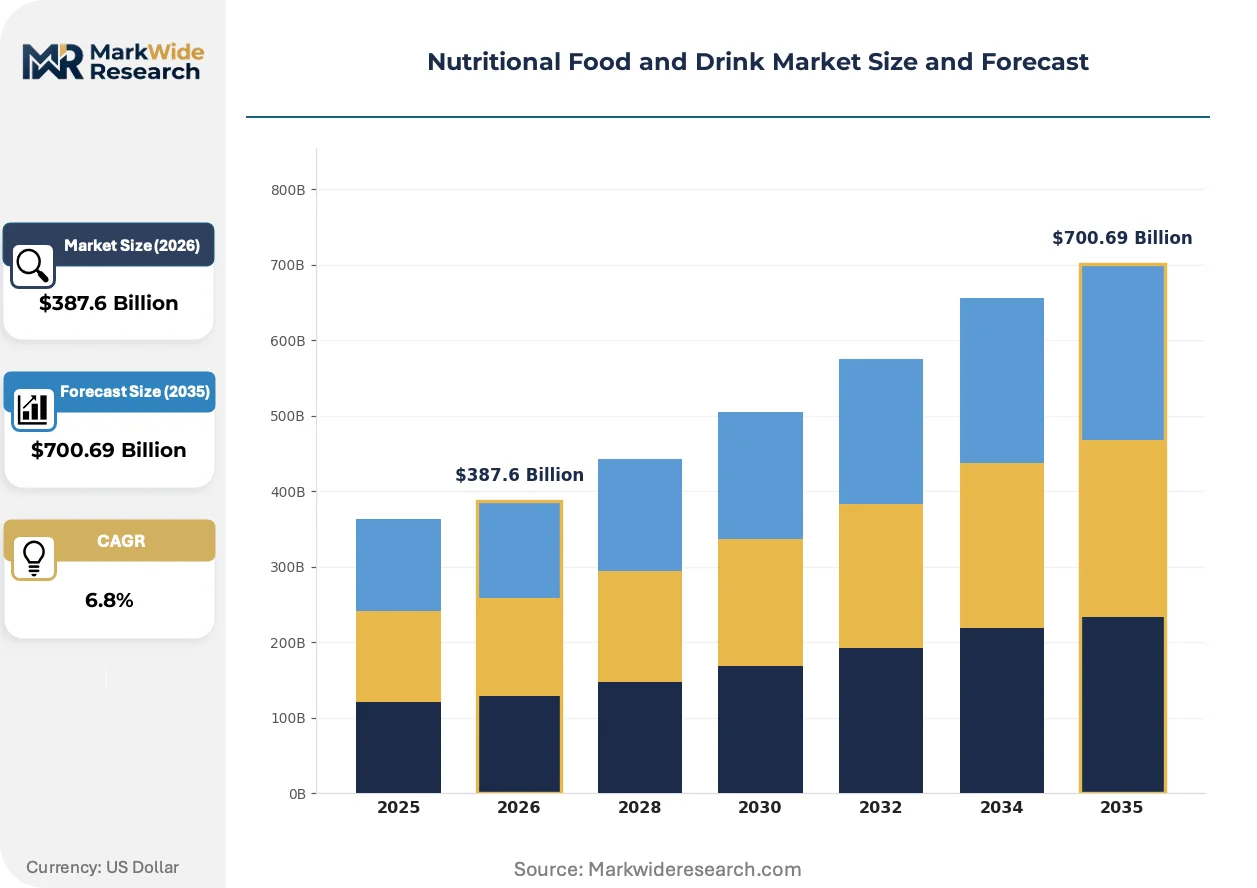
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fortified Foods, Sports Nutrition, Meal Replacements, Functional Beverages Form: Powder, Liquid, Bar, Capsule End User: Fitness Enthusiasts, Health-Conscious Consumers, Seniors, Athletes Ingredient Type: Vitamins, Minerals, Proteins, Probiotics |
| Companies Covered | Nestlé, Abbott, PepsiCo, Glanbia PLC, Danone, Herbalife International of America, Amway Corp, Kellogg’s, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutritional Food and Drink Market Emerging Trajectories
Formulation science and regulatory disclosure are converging to reshape how nutritional products demonstrate efficacy and environmental accountability to institutional and individual buyers.
Precision fermentation infrastructure is modularizing production economics for probiotic functional beverages. Mid-sized European dairy processors are adopting 5,000-liter bioreactor units to enter the category without greenfield facility investments. This distributed manufacturing model is modularizing regional supply structures that previously concentrated probiotic culture production in Danish and Dutch facilities.
EFSA's evolving protein health claim guidelines are tightening evidentiary standards for muscle maintenance and satiety positioning. Manufacturers must now submit human intervention trials rather than extrapolating from compositional data. Sports nutrition brands targeting German and French markets face compressed margin structures as clinical validation costs mount.
Direct-to-consumer subscription models are displacing traditional retail replenishment for personalized nutrition stacks. Fitness enthusiasts in urban United States markets favor algorithm-driven micronutrient recommendations over mass-market multivitamins. This channel pivot concentrates customer acquisition spending on digital platforms rather than shelf placement negotiations.
Nutritional Food and Drink Market Segmentation
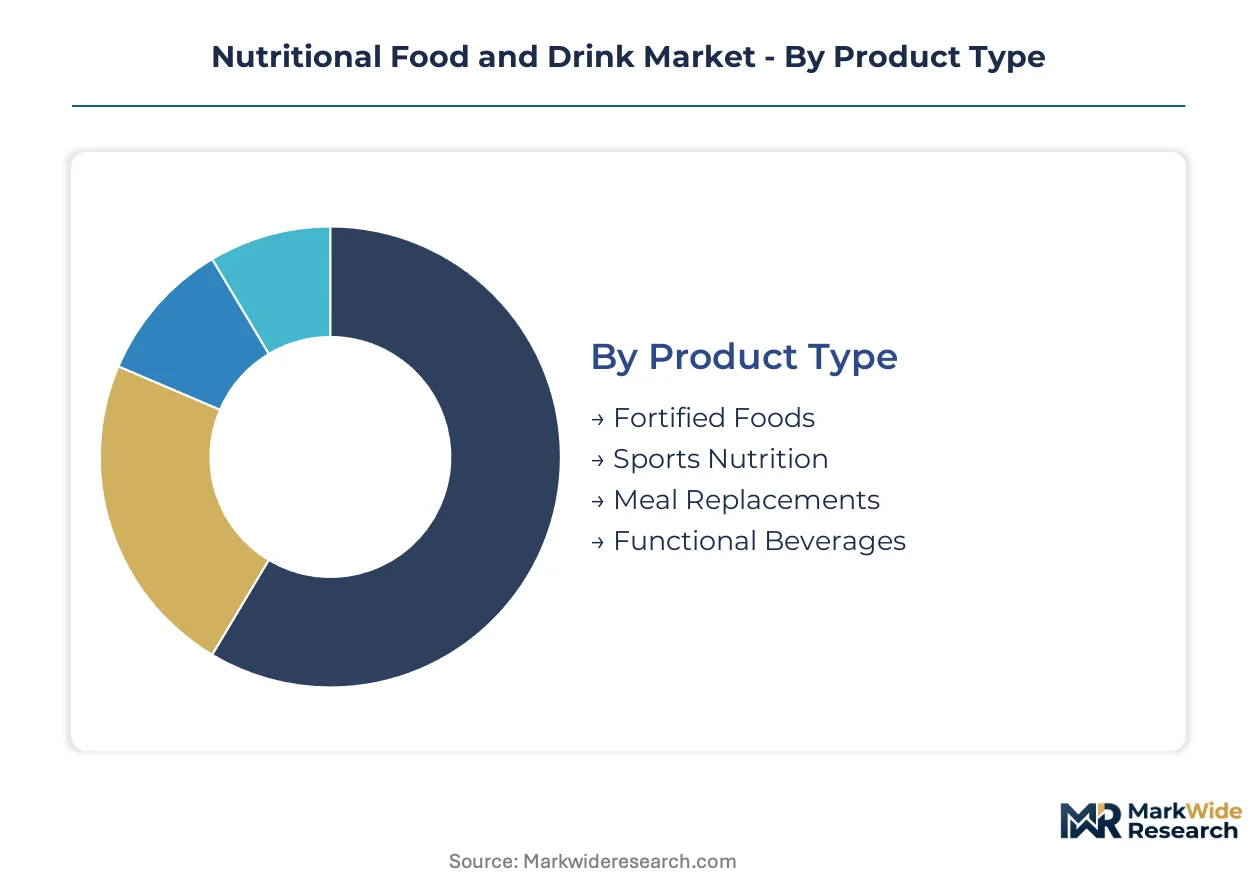
Nutritional food and drink manufacturers align portfolio architecture with distinct consumption occasions and bioavailability requirements. Upgrade cycles vary sharply across product types, with functional beverage formats refreshing every 18-24 months while meal replacement platforms stabilize over 5-7 year horizons.
Product Type:
Replacement cycles accelerate where formulation science advances fastest, compressing competitive windows for brands dependent on shelf-stable bioactive delivery.
- Fortified Foods:Cereals, dairy, and baked goods enhanced with micronutrient premixes through microencapsulation to preserve thermal stability. Demand clusters in German and French retail channels where EFSA health claim enforcement drives clinical substantiation investments.
- Sports Nutrition:Targeted macronutrient formulations including protein isolates, pre-workout compounds, and recovery blends manufactured via cold-aseptic filling to protect bioactive integrity. Fitness enthusiasts in United States metropolitan markets drive SKU proliferation as personalized stacking replaces mass-market positioning.
- Meal Replacements:Complete macro- and micronutrient profiles in controlled-calorie formats for weight management and clinical nutrition support. Corporate wellness programs in self-insured employer plans provide stable contract volumes with lower formulation turnover.
- Functional Beverages:Ready-to-drink formats delivering probiotics, adaptogens, or targeted vitamins through aseptic processing. Japanese and South Korean convenience retail channels favor novel fermentation-derived ingredients requiring accelerated regulatory pathways.
Volume placements concentrate in fortified foods; the faster expansion belongs to sports nutrition.
Form:
Cost tier stratification separates premium-positioned delivery technologies from commodity powder formats, with liquid and bar segments commanding manufacturing complexity premiums.
- Powder:Spray-dried or agglomerated concentrates requiring reconstitution, dominating bulk sports nutrition and meal replacement economics. Contract manufacturers in Netherlands and Belgium specialize in high-throughput blending lines serving private-label demand.
- Liquid:Cold-aseptic filled beverages and shots with extended shelf stability for bioactive compounds. Precision fermentation infrastructure constraints in Southern Europe limit regional supply expansion for probiotic liquids.
- Bar:Extruded or cold-pressed formats binding proteins with hydrocolloid stabilizers for texture retention. United States specialty retailers drive clean-label bar innovation with compressed ingredient lists.
- Capsule:Hard-shell or soft-gel delivery for fat-soluble vitamins and mineral chelates with controlled release profiles. Senior-focused direct-to-consumer channels favor capsule convenience over powder preparation requirements.
Manufacturing margins peak in liquid formats; powder retains the highest absolute volume throughput across production networks.
End User:
Application-specific formulation requirements diverge sharply between performance optimization and clinical support, with distinct regulatory pathways governing each.
- Fitness Enthusiasts:Recreational athletes seeking body composition and recovery benefits beyond basic dietary supplementation. Algorithm-driven personalization platforms in United States urban markets displace generic multivitamin stacking.
- Health-Conscious Consumers:Preventive wellness seekers prioritizing clean-label transparency and carbon-disclosed supply chains. EU Green Deal compliance costs filter out mid-tier competitors lacking verified low-emission protein sourcing.
- Seniors:Age-related sarcopenia and micronutrient absorption concerns driving medical nutrition positioning. Japanese regulatory frameworks for Foods for Specified Health Uses create premium reimbursement pathways.
- Athletes:Elite and professional competitors requiring batch-tested formulations free from prohibited substances. Informed Sport and NSF Certified for Sport certifications command 15-20% price premiums in competitive channels.
Health-conscious consumers provide the broadest addressable base; fitness enthusiasts generate the steepest per-capita spending trajectories.
Ingredient Type:
Supply concentration among Canadian and Baltic processors for plant proteins creates procurement vulnerability, while fermentation capacity constraints limit probiotic expansion.
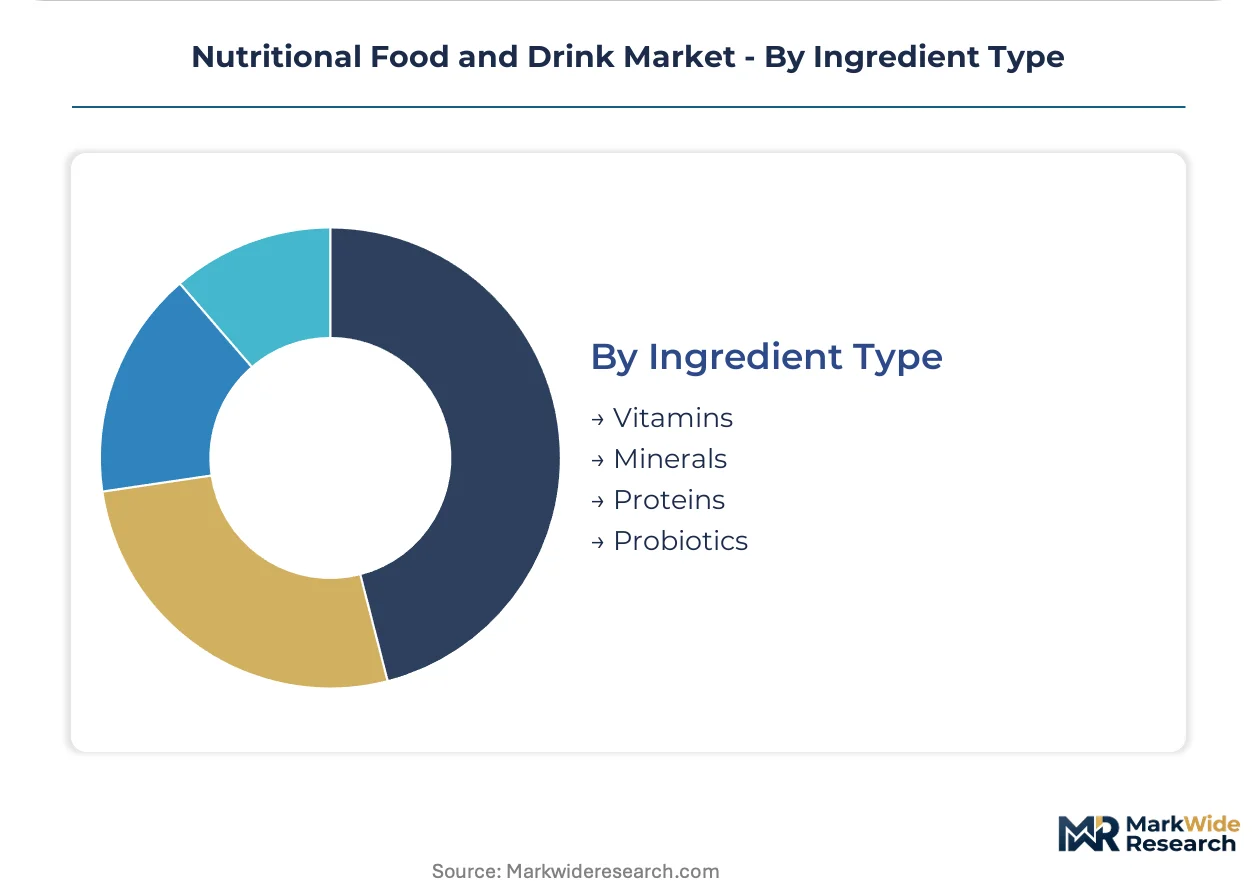
- Vitamins:Synthetic or nature-identical compounds including fat-soluble (A, D, E, K) and water-soluble (B-complex, C) forms. Chinese fermentation-derived B-vitamin production dominates global feedstock supply.
- Minerals:Chelated or inorganic salts engineered for bioavailability optimization in specific pH environments. EFSA novel food approval timelines of 18-24 months delay next-generation organic mineral launches.
- Proteins:Dairy isolates, plant concentrates, and emerging precision fermentation-derived alternatives. Pea and fava bean supply chains face weather-induced volatility in Canadian prairie regions.
- Probiotics:Live microbial cultures requiring cold-chain integrity and strain-specific stability engineering. Danish and Dutch facilities concentrate bulk culture production, with modular bioreactor adoption spreading to mid-tier Southern European processors.
Protein sourcing commands the largest procurement spend; probiotics are climbing the fastest as functional beverage penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Western Europe and North America while consumption growth accelerates across Asian urban centers. EU Green Deal carbon accounting requirements reshape procurement patterns for multinational portfolios. Cold-aseptic filling infrastructure concentrates in established dairy processing regions.
United States
Fitness enthusiasts in metropolitan markets drive algorithm-driven personalization platforms for sports nutrition stacking. FDA enforcement of New Dietary Ingredient notifications constrains novel bioactive launches. Greater Chicago hosts specialized contract manufacturing facilities for cold-aseptic functional beverages.
Germany
EFSA health claim substantiation requirements elevate clinical validation investments for fortified food positioning. REACH compliance costs filter mid-tier competitors from European ingredient sourcing. Bavaria's dairy processing infrastructure anchors clean-label protein isolate production for export markets.
China
Middle-class urban consumers adopt probiotic functional beverages through convenience retail channels. SAMR novel food approval pathways extend timelines for fermented protein ingredients. Yangtze River Delta biotech clusters develop precision fermentation capacity for domestic probiotic culture supply.
Japan
Senior-focused medical nutrition demand supports Foods for Specified Health Uses reimbursement pathways. METI standards govern functional claim substantiation for aging-related positioning. Kansai region maintains concentrated probiotic research infrastructure linking academia to commercial culture production.
Netherlands
Private-label powder blending demand from Northern European retailers sustains high-throughput contract manufacturing. CSRD-aligned carbon disclosure mandates create procurement advantages for verified low-emission protein sourcing. Rotterdam-Antwerp logistics corridors facilitate ingredient import flows subject to REACH documentation requirements.
Nutritional Food and Drink Market Vendor Landscape
The competitive structure tilts toward diversified nutrition conglomerates with captive dairy protein infrastructure and specialized fermentation capabilities. Tiered positioning separates mass-market fortified food portfolios from premium sports nutrition and medical nutrition specialists. Strategic archetypes include integrated dairy processors leveraging clean-label credibility, beverage multinationals scaling functional ready-to-drink formats, and contract manufacturers serving private-label powder demand. Capacity expansion and portfolio diversification represent dominant competitive moves as players respond to EU Green Deal supply chain restructuring.
Among diversified nutrition conglomerates, Nestlé, Danone, and PepsiCo exemplify distinct strategic positioning within the competitive landscape. Nestlé represents integrated dairy processing infrastructure adapted to European clean-label production requirements. Danone occupies a position anchored in specialized fermentation capabilities for probiotic functional beverages. PepsiCo sits within the scale-driven beverage multinational archetype competing through sports nutrition penetration in North American convenience channels.
| Leading Market Players |
|---|
| Nestlé |
| Abbott |
| PepsiCo |
| Glanbia PLC |
| Danone |
| Herbalife International of America |
| Amway Corp |
| Kellogg's |
| General Mills |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up contract manufacturers in the Netherlands and Belgium anchor powder blending capacity, linking concentrated ownership structures to disciplined pricing in bulk sports nutrition while constraining margin expansion for mid-tier European brands facing REACH compliance burdens.
Pricing Analysis
Margin tightening in standard-tier powders reflects Canadian pea protein concentrate volatility and Baltic fava bean supply interruptions. Three-tier pricing structure across premium, standard, and economy levels separates Informed Sport-certified formulations from private-label commodity blends. Cost-down pressure on economy-tier powders accelerates because self-insured employer wellness programs negotiate annual volume contracts. Fitness enthusiasts in United States metropolitan markets exhibit lowest price sensitivity, prioritizing algorithm-driven personalization over per-unit cost.
Supply Chain Analysis
Dual-sourcing requirements for probiotic cultures now mandate qualification of both Danish bulk culture facilities and modular Southern European bioreactor operators. Raw material flows draw from Canadian prairie pea processors, Baltic fava bean concentrators, and Chinese fermentation-derived B-vitamin production. Single-source vulnerability concentrates in precision fermentation capacity for functional beverages. Distribution runs through Rotterdam-Antwerp logistics corridors subject to REACH documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-aseptic filling technology is displacing legacy hot-fill lines in functional beverage manufacturing, compressing equipment replacement cycles and reshaping capital allocation priorities across formulation tiers.
For Market Incumbents: Acquire precision fermentation bioreactor capacity in Southern Europe to preempt supply bottlenecks for probiotic functional beverages. Nestlé and Danone should deepen backward integration into verified low-emission protein sourcing to defend margin position against EU Green Deal carbon disclosure mandates. EFSA novel food approval timelines threaten formulation pipelines for fermented proteins. For New Entrants and Emerging Players: EU Green Deal compliance costs in Germany and France open a window for carbon-verified protein positioning among health-conscious consumers. Target corporate wellness channels in self-insured employer plans with metabolic intervention meal replacements. Pursue direct-to-consumer subscription models with algorithm-driven micronutrient stacking to bypass retail slotting fee barriers. For Investors and Strategic Acquirers: Modular bioreactor adoption among mid-sized Southern European dairy processors is the leading indicator that distributed probiotic manufacturing will fragment concentrated Danish-Dutch supply structures. Long-term viability hinges on fermentation infrastructure ownership rather than brand equity alone. Watch EFSA protein health claim guideline revisions as inflection signal for clinical validation cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Modular bioreactor deployment in Southern Europe reduces dependency on Danish-Dutch culture concentration. |
| Carbon Disclosure Certification | CSRD-aligned supply chain auditing creates procurement advantages for verified low-emission protein sourcing. |
| Direct-to-Consumer Channel Expansion | Algorithm-driven personalization platforms in United States urban markets displace mass-market multivitamin retail. |
| Clinical Validation Investment | EFSA health claim substantiation requirements elevate barrier to entry for fortified food positioning in Germany. |
| Backward Integration into Plant Protein | Captive sourcing from Canadian prairie processors mitigates weather-induced pea concentrate price volatility. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this nutritional food and drink analysis. Primary interviews with formulation scientists, cold-aseptic filling equipment specialists, EFSA regulatory affairs consultants, and procurement leads at self-insured employer wellness programs complemented documentary sources. Bottom-up volume modeling across product type, form, end user, and ingredient type dimensions triangulated against top-down trade flow analysis.
Reconciliation of production capacity databases with consumption survey data and channel inventory estimates shaped the analytical framework across the analysis window. Segmentation modeling incorporated product type, form, end user archetype, and ingredient sourcing origin as core dimensions. CAGRs were derived from trend extrapolation of historical volume trajectories adjusted for regulatory inflection points including EU Green Deal implementation and EFSA novel food pathway timelines.
The model assumes a particular technology adoption path for cold-aseptic filling and precision fermentation scale-up; alternative pathways for probiotic culture production would alter the outlook for Southern European manufacturing competitiveness. Deviation in EFSA protein health claim evidentiary standards or REACH enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Krill Oil Supplements Market
Nutritional Supplements
Zinc Gluconate Market
Nutritional Supplements
Zinc Supplement Market
Nutritional Supplements
Europe Nutritional Beverages Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Nutritional Drink Market
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
Indonesia Beauty Supplements Market
Nutritional Supplements
Human Nutrition Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
South America Botanical Supplements Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Hair Growth Supplements Market