
 Plant-Based Cheese Wedges Market | 2026-2036
Plant-Based Cheese Wedges Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Cheese Wedges Market Analytics
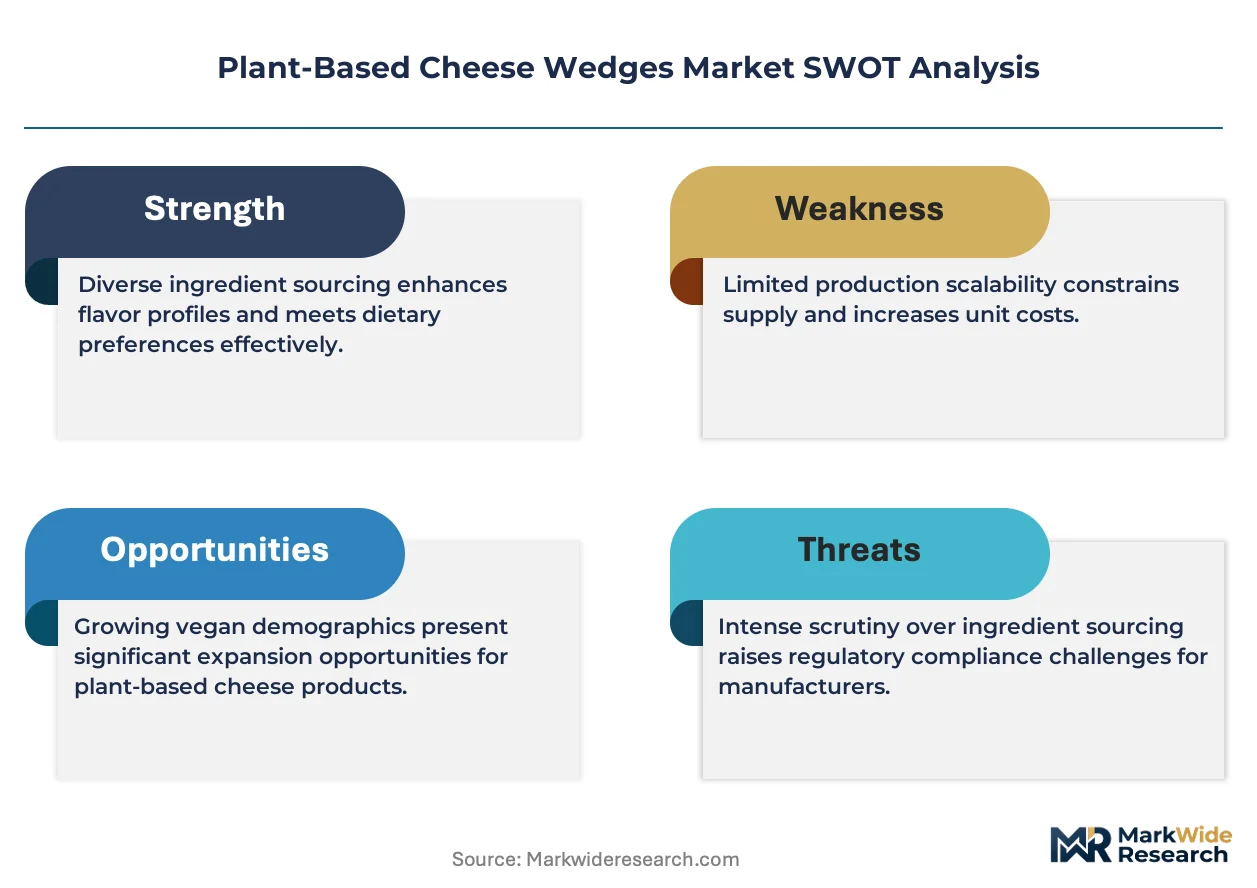
European capacity build-out is rewriting competitive dynamics in plant-based cheese wedges as fermentation infrastructure scales across the Netherlands and Denmark. Violife leverages its Greek manufacturing base to sustain pan-European distribution density. Miyoko's Creamery anchors premium positioning through cultured cashew processes that command shelf space in specialty retail. Bel Group competes via dairy-adjacent brand credibility as it extends reformulated lines into plant-based formats.
Plant-based cheese wedges are fermented or emulsified analogs typically containing 15-35% fat content, designed to replicate the wedge-shaped portioning and melt behavior of dairy cheese for retail and foodservice applications. The ingredient base dimension stratifies sharply: coconut oil formulations dominate volume production due to cost structure, while pea protein variants represent the fastest-growing sub-segment as manufacturers target improved stretch and protein claims. Spreadable product types occupy mature shelf-stable channels, whereas blocks command margin pools in artisan-positioned retail.
EFSA novel food assessments shape ingredient approval timelines for European entrants, while FDA labeling standards in the United States constrain how "cheese" terminology appears on packaging. REACH compliance obligations for emulsifiers and flavor carriers add formulation complexity for suppliers serving multiple geographies. Stakeholders must monitor evolving enzyme and fermentation-derived ingredient classifications that could unlock cleaner label positioning or trigger reformulation mandates.
Market Dynamics
Fermentation-derived casein analogs are compressing formulation timelines for plant-based cheese wedges, forcing incumbent coconut oil processors to recalibrate fat structuring methods or cede melt-performance claims to precision-fermentation entrants.
Growth Catalysts
- EU Green Deal targets:Member states face binding sustainable food system mandates that accelerate reformulation approvals and expand retail placement quotas for plant-based alternatives in Germany, the Netherlands, and Denmark.
- Foodservice menu expansion:North American restaurant chains are embedding plant-based cheese wedges into limited-time offerings and permanent LTO rotations as dairy-free options capture lunch and casual dining occasions.
- Pea protein isolate advances:Improved stretch and shred performance in extruded protein matrices enables manufacturers to match mozzarella functionality without coconut oil's saturated fat profile.
Market Restraints
- Input cost volatility:Coconut oil prices fluctuate with Southeast Asian harvest cycles and weather patterns, compressing margin predictability for volume producers dependent on tropical fat sources.
- EFSA novel food timelines:European entrants face 18-24 month assessment windows for fermentation-derived proteins, delaying product launches relative to jurisdictions with expedited GRAS pathways.
- Technical melt limitations:Current starch and gum systems fail to replicate dairy cheese's Maillard browning and oil separation behavior under broiler and pizza oven conditions.
Strategic Opportunities
- German retail shelf expansion:Discounters and conventional supermarkets in Bavaria and North Rhine-Westphalia are dedicating incremental linear footage to plant-based cheese wedges beyond traditional organic channels.
- Precision fermentation convergence:Partnerships between dairy protein startups and established plant-based brands enable hybrid positioning that leverages clean-label fermentation with familiar brand equity.
- Direct-to-foodservice distribution:Specialized distributors are building temperature-controlled logistics networks that bypass retail slotting fees and capture institutional cafeteria and contract catering volumes.
Industry Challenges
- Enzyme sourcing bottlenecks:Lipase and protease suppliers face capacity constraints as demand surges across plant-based meat and dairy analog categories simultaneously.
- Clean-label certification complexity:Multiple competing non-GMO and organic standards across North American and European jurisdictions create packaging and formulation versioning burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Cheese Wedges Market |
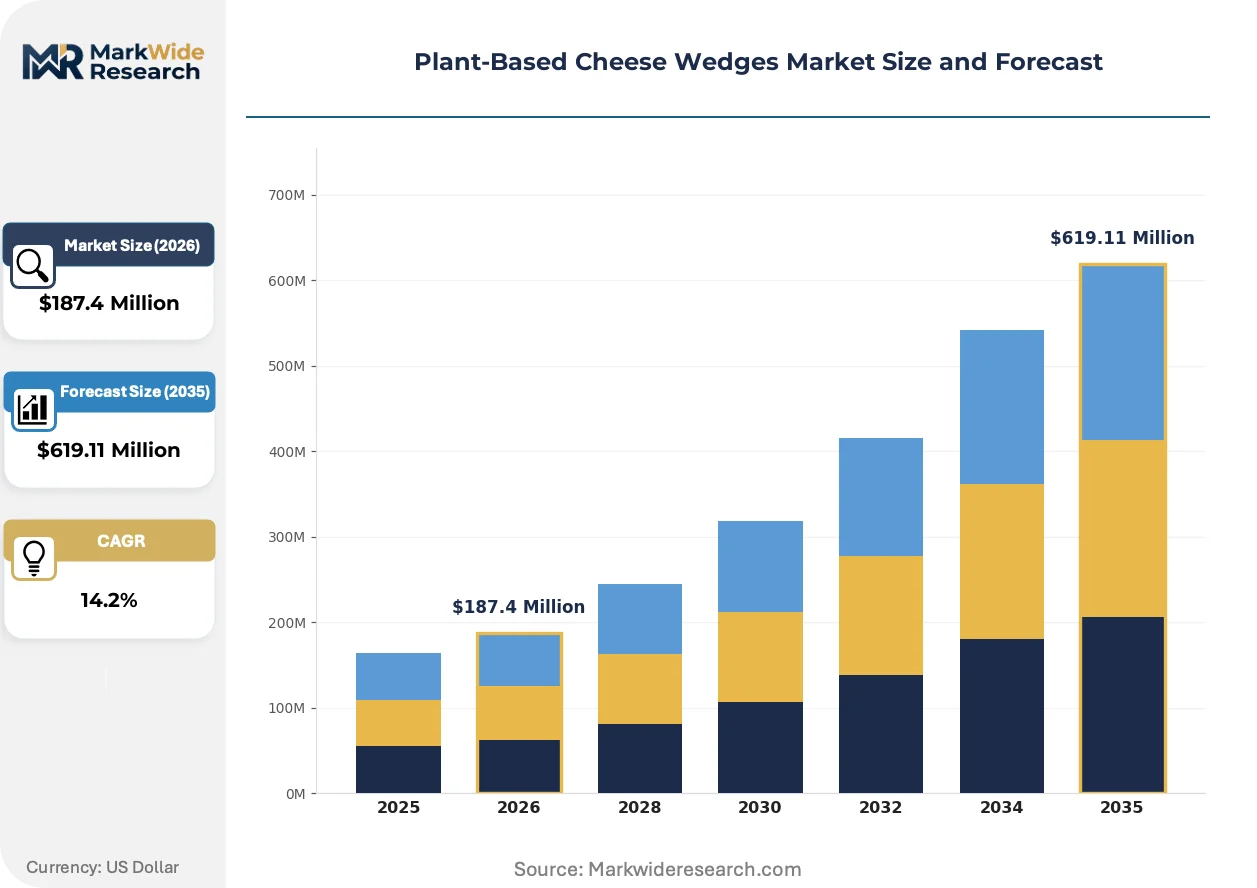
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spreadable, Slices, Shredded, Blocks Ingredient Base: Nuts, Soy, Coconut, Pea Protein Flavor Profile: Cheddar, Mozzarella, Creamy Garlic, Spicy Pepper Packaging Type: Jars, Recyclable Pouches, Trays, Tubs |
| Companies Covered | GOOD PLANeT Foods, Bel Group, Follow Your Heart, Daiya Foods, Miyoko’s Creamery, Kite Hill, Violife, Parmela Creamery, Nurishh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Cheese Wedges Market Evolving Landscape
Active culture fermentation is displacing static emulsification as the dominant processing paradigm, with implications for equipment investment, shelf-life management, and flavor development timelines across the category.
Filamentous fungal fermentation is migrating from pharmaceutical applications into food-grade casein production, enabling stretch and melt properties previously unattainable with plant proteins alone. Specialty retail buyers in the United States and Germany are prioritizing these cultured products for premium positioning. This technology shift is compressing the performance gap between plant-based and dairy cheese wedges, forcing commodity coconut oil formulators toward price-driven positioning or exit.
REACH compliance obligations for emulsifiers and flavor carriers are tightening formulation flexibility for suppliers serving European markets, with ECHA substance evaluations triggering reformulation mandates for specific hydrocolloid grades. Manufacturers are responding by qualifying alternative stabilizer systems and consolidating supplier relationships to reduce audit burden. The Netherlands and Denmark, as fermentation infrastructure hubs, face disproportionate compliance cost concentration relative to smaller member states.
Buyer concentration in North American foodservice is consolidating purchasing decisions into centralized procurement functions at multi-unit restaurant chains, compressing supplier negotiation leverage and standardizing product specifications across regional markets. Independent distributors and specialty foodservice brokers are losing share to direct manufacturer relationships with national account teams. This pattern is most visible in quick-service and fast-casual segments where menu standardization drives volume commitments.
Plant-Based Cheese Wedges Market Segmentation
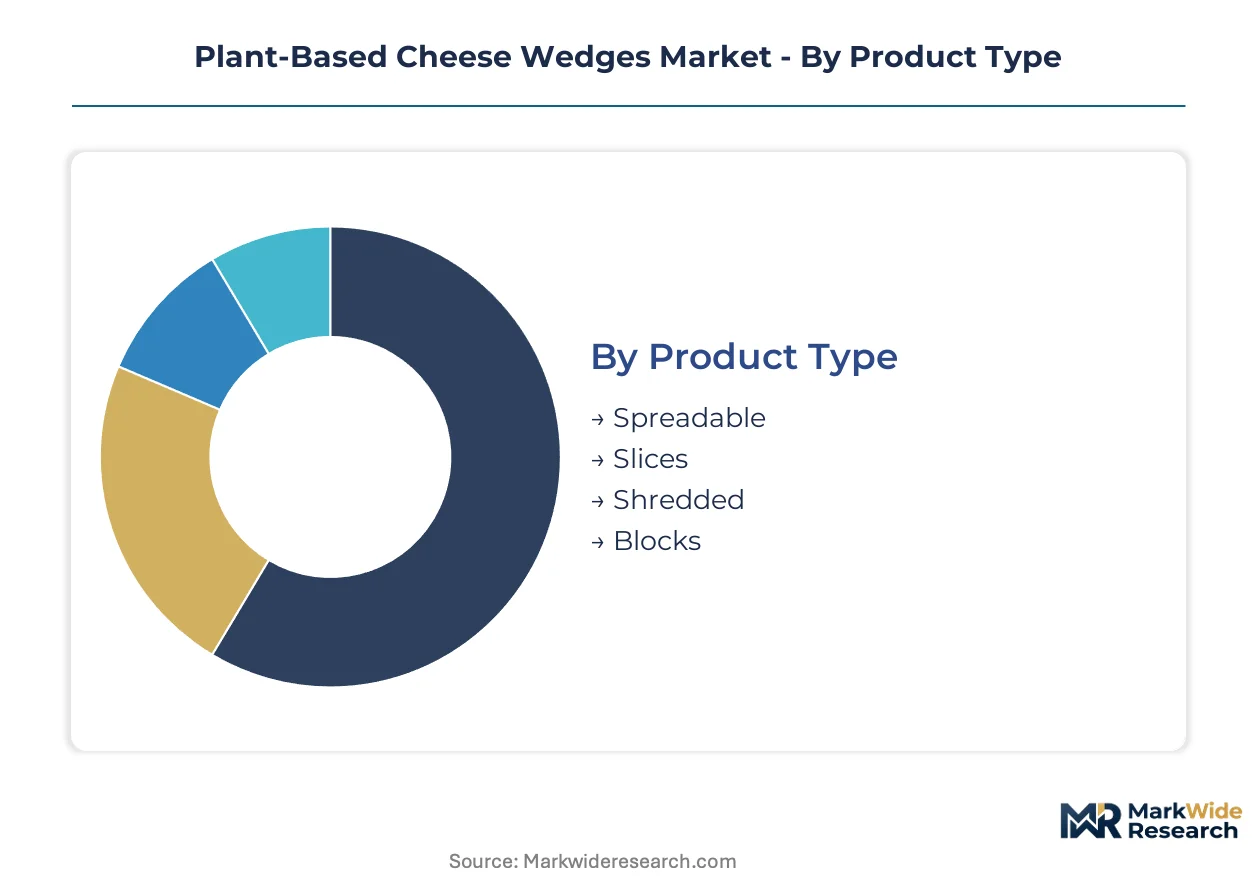
Segmentation in plant-based cheese wedges reveals divergent margin structures and formulation investment requirements across product formats and ingredient bases. Manufacturers must align production capabilities with distinct channel specifications and consumer price elasticity profiles.
Product Type:
After-sales service intensity varies sharply across product formats, with spreadable variants requiring minimal technical support while block formats demand culinary training and menu integration assistance for foodservice accounts.
- Spreadable:Emulsified oil-in-water systems with 20-30% fat content designed for cold application on crackers and sandwiches. Demand concentrates in German and Dutch retail discounters where convenience positioning drives repeat purchase frequency among flexitarian households.
- Blocks:Firm-set analogs requiring controlled fermentation or starch retrogradation to achieve sliceable texture. Artisan retail in Bavaria and North Rhine-Westphalia anchors volume, with specialty buyers prioritizing cultured processes that justify premium shelf positioning.
- Slices:Pre-portioned formats optimized for sandwich assembly with standardized thickness and peel-release properties.
- Shredded:Grated analogs treated with anti-caking agents for pizza and casserole applications where melt distribution matters.
Spreadable holds the largest share; momentum sits with blocks.
Ingredient Base:
Cost tier stratification separates commodity coconut oil formulations from precision-fermented proteins, with capital requirements and regulatory pathways determining competitive entry points.
- Coconut:Refined and fractionated tropical oils providing fat structuring at lowest unit cost. Volume production concentrates in Southeast Asian processing hubs where harvest volatility creates margin pressure for European and North American formulators.
- Pea Protein:Isolate and concentrate matrices enabling protein claims and improved stretch performance. German retail buyers are expanding facings for pea-based wedges as EFSA novel food approvals accelerate and clean-label positioning strengthens.
- Nuts:Cashew and almond bases requiring soaking and blending for creamy textures in premium positioning.
- Soy:Traditional protein source with established supply chains but declining consumer preference in Western markets.
Coconut dominates current volume; pea protein is expanding most quickly.
Flavor Profile:
Application-driven formulation separates commodity mozzarella analogs from differentiated specialty flavors, with R&D investment intensity scaling toward complex taste engineering.
- Cheddar:Aged-culture simulation using annatto coloring and lactic acid profiles to replicate sharpness. North American foodservice chains specify cheddar wedges for burger and sandwich applications where color contrast and familiar naming drive menu acceptance.
- Mozzarella:Low-moisture part-skim analogs targeting pizza melt and stretch benchmarks. Italian-style pizzerias in Germany and the Netherlands test fermentation-derived variants as EFSA assessments progress for precision ingredients.
- Creamy Garlic:Compound flavor system with dehydrated allium and stabilizer adjustments for spreadable formats.
- Spicy Pepper:Capsicum-infused variants targeting specialty retail and direct-to-consumer channels.
Mozzarella holds the largest share; momentum sits with cheddar.
Packaging Type:
Supply concentration in European flexible packaging creates geographic dependency for sustainable material sourcing, with regulatory pressure reshaping format specifications.
- Trays:Thermoformed PET or PP structures with modified atmosphere sealing for sliced and block formats. German supermarkets mandate recyclable tray systems as EU Green Deal implementation tightens packaging waste directives.
- Recyclable Pouches:Mono-material flexible films replacing multi-layer laminates to meet ECHA substance evaluation requirements. Dutch retailers lead adoption, with Albert Heijn and Jumbo specifying pouch formats for shredded and spreadable lines.
- Jars:Glass containers for premium spreadable positioning with resealability and table-presence advantages.
- Tubs:Injection-molded PP containers for foodservice bulk and club retail formats.
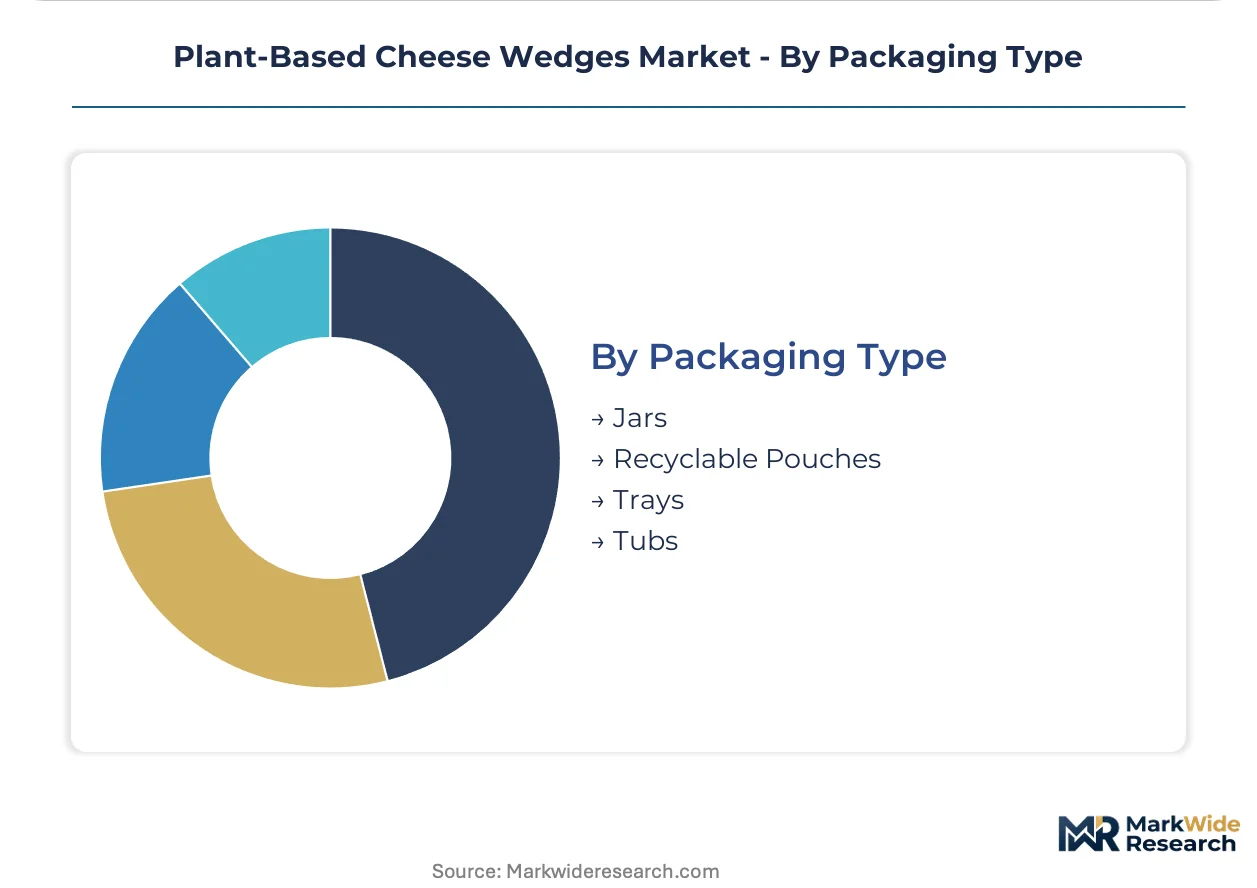
Trays hold the largest share; recyclable pouches are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food assessments anchor European regulatory timelines, while FDA labeling constraints shape North American product positioning. Manufacturing clusters concentrate in the Netherlands and Denmark as fermentation infrastructure scales.
Germany
Retail shelf expansion in Bavaria and North Rhine-Westphalia drives volume growth for plant-based cheese wedges. The EU Green Deal mandates sustainable food system targets that accelerate reformulation approvals across member states. Berlin-Brandenburg hosts multiple precision-fermentation startups scaling casein-analog production.
United States
Foodservice menu integration at multi-unit restaurant chains concentrates purchasing decisions into centralized procurement functions. FDA standards constrain "cheese" terminology on packaging, forcing brand-level positioning adjustments. California anchors cultured cashew processing capacity for premium retail placement.
Netherlands
Albert Heijn and Jumbo specify recyclable pouch formats for shredded and spreadable lines, reshaping packaging specifications. REACH compliance obligations for emulsifiers tighten formulation flexibility for suppliers serving European markets. Eindhoven Region concentrates fermentation infrastructure investment as precision-fermentation capacity builds.
Denmark
Filamentous fungal fermentation migrates from pharmaceutical applications into food-grade casein production. ECHA substance evaluations trigger reformulation mandates for specific hydrocolloid grades. Copenhagen anchors clean-label positioning demand as specialty retail buyers prioritize cultured products.
United Kingdom
Discounters and conventional supermarkets dedicate incremental linear footage to plant-based alternatives beyond traditional organic channels. CSRD reporting requirements pressure supply chain transparency for emulsifier and flavor carrier sourcing. London/Southeast concentrates foodservice distribution networks targeting contract catering volumes.
Plant-Based Cheese Wedges Market Competitive Landscape
Dairy-adjacent legacy players and precision-fermentation specialists split the market into distinct capability tiers. Incumbent coconut oil formulators face margin compression as fermentation-derived proteins achieve melt-performance parity. Three archetypes dominate: established dairy brands extending reformulated lines, plant-native specialists leveraging cultured processes, and fermentation startups commercializing casein analogs. Capacity expansion in Dutch and Danish infrastructure hubs and strategic partnerships between protein startups and retail brands represent the dominant competitive moves.
Within the dairy-extension archetype, Bel Group occupies a position leveraging brand credibility across European retail. Violife exemplifies pan-European distribution density sustained through Greek manufacturing scale. Miyoko's Creamery anchors premium-tier positioning through specialty retail channel presence. These three represent divergent geographic and positioning strategies rather than direct operational overlap.
| Leading Market Players |
|---|
| GOOD PLANeT Foods |
| Bel Group |
| Follow Your Heart |
| Daiya Foods |
| Miyoko's Creamery |
| Kite Hill |
| Violife |
| Parmela Creamery |
| Nurishh |
| Others |
Value Network & Pricing Analysis
Overcapacity in Southeast Asian coconut oil processing is forcing European and North American formulators into defensive pricing postures while fermentation infrastructure build-out in the Netherlands and Denmark creates premium-tier pricing power for precision-fermented casein analogs.
Pricing Analysis
German retail discounters command 15-20% price spreads below specialty channel positioning for identical SKUs. Three-tier pricing structure across premium, standard, and economy levels separates cultured cashew wedges from commodity coconut oil blocks from private-label spreadables. Price compression in the coconut oil tier stems from harvest volatility and margin pressure from precision-fermentation entrants achieving melt-performance parity. Foodservice buyers exhibit lowest price sensitivity due to menu integration costs, while German discounter shoppers drive hardest bargain.
Supply Chain Analysis
Extended payment terms from Dutch and Danish retailers are squeezing working capital for Southeast Asian coconut processors, accelerating supplier consolidation. Raw material sourcing concentrates in Indonesia and the Philippines for tropical fats, with pea protein isolate drawn from Canadian and Chinese extraction facilities. Single-source vulnerability in lipase and protease enzyme supply creates formulation bottlenecks as demand surges across analog categories. Distribution runs through temperature-controlled logistics networks bypassing retail slotting fees for direct foodservice penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through a capacity-led recovery as fermentation infrastructure investment in Northern Europe absorbs capital previously allocated to commodity coconut oil expansion.
For Market Incumbents: Entrench fermentation partnerships before precision-fermentation startups achieve scale economics. Secure backward integration into enzyme supply through captive lipase capacity or exclusive supplier agreements. Defend German retail shelf position against private-label encroachment by accelerating EFSA novel food submissions for clean-label ingredient claims.
For New Entrants and Emerging Players: North American contract catering represents the most penetrable white-space channel, with institutional buyers seeking direct manufacturer relationships outside retail slotting fee structures. Target pea protein-based mozzarella analogs for pizza foodservice applications where stretch performance gaps persist. Lead with sustainability credentials aligned to EU Green Deal procurement mandates.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision-fermentation specialists with EFSA-approved ingredient platforms and locked-in offtake agreements. Long-term viability favors hybrid models combining fermentation-derived proteins with established brand equity. Monitor EFSA novel food approval velocity as the inflection signal for category-wide margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Eindhoven and Copenhagen hubs enable casein-analog production at melt-performance parity with dairy. |
| EFSA Novel Food Submission Acceleration | Early approvals unlock German retail expansion ahead of competitors facing 18-24 month assessment windows. |
| Direct-to-Foodservice Distribution Network | Temperature-controlled logistics bypass Albert Heijn and Jumbo slotting fees for institutional catering volumes. |
| Pea Protein Isolate Supply Agreement | Canadian and Chinese extraction capacity secures protein claims and stretch performance improvement. |
| Recyclable Pouch Format Qualification | Mono-material flexible films meet ECHA substance evaluation requirements for Dutch retailer specifications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with fermentation facility engineers, retail category buyers at Albert Heijn and Jumbo, foodservice procurement directors at multi-unit chains, and R&D leads at coconut oil processors. Secondary validation drew from EFSA novel food registers, REACH substance evaluation databases, EU Green Deal implementation trackers, and customs records for tropical fat imports. Bottom-up volume modeling triangulated against top-down category spend estimates.
Calibration against historical capacity utilization rates and approval timeline distributions anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, ingredient base, flavor profile, packaging type, and channel specification. CAGRs derived from elasticity-adjusted price-volume trajectories, with fermentation capacity build-out curves and EFSA assessment velocity as category-specific forecast inputs.
Practitioners should monitor EFSA novel food approval backlogs, coconut oil harvest disruptions, and enzyme supplier capacity constraints for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Dairy Whiteners Market
Dairy Alternatives
Dairy Free Yogurt Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Almond Drink Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Non-Dairy Ice Cream Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
Low Calorie Cream Cheese Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Dairy Alternatives Market
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Walnut Milk Market
Dairy Alternatives
Coconut Milk and Cream Market