
 Almond Market | 2026-2036
Almond Market Size, Share, and Industry Trends Forecast 2026-2036
Almond Market Analysis
Premium-grade kernel specifications is unwinding commodity pricing structures across the Almond Market. Blue Diamond Growers leverages its cooperative scale to dominate California processing capacity. Wonderful Pistachios & Almonds sustains vertical control from orchards to branded retail. Borges Agricultural & Industrial Nuts anchors European supply through its Spanish processing network.
Almonds are the seeds of Prunus dulcis trees, typically containing 50-55% oil and 20-25% protein by weight, harvested through mechanical shaking and subsequent hulling and shelling operations for food ingredient and direct consumption applications. Raw almonds occupy the largest volume position across product type segments, while almond flour captures expanding margin pools from gluten-free and keto-formulation demand among food manufacturers. Snack producers represent the fastest-growing end user channel as clean-label positioning accelerates in convenience retail.
USDA grading standards and FDA food safety regulations govern kernel quality classification and pasteurization requirements for domestic and export market access. California's State Water Resources Control Board irrigation allocations directly constrain bearing acreage expansion in the Central Valley. EU REACH compliance and EFSA novel food evaluations shape European import thresholds for processed almond derivatives. Stakeholders must monitor water-right adjudications and carbon accounting disclosures as sustainability credentials increasingly determine contract eligibility with multinational food manufacturers.
Market Dynamics
California's State Water Resources Control Board irrigation allocations are constraining bearing acreage expansion across the Central Valley, forcing processors to compete for limited kernel supply while food manufacturers accelerate plant-based dairy formulation demand.
Growth Catalysts
- Plant-based dairy alternatives:Food manufacturers reformulate yogurt, milk, and ice cream bases with almond protein concentrates to meet clean-label portfolio mandates from retail buyers.
- USDA grading standardization:Uniform kernel quality classification enables export contract standardization, reducing transaction friction for European and Asian importers.
- Snack channel expansion:Convenience retail clean-label positioning drives roasted and flavored almond product line extensions from national grocery chains.
Market Restraints
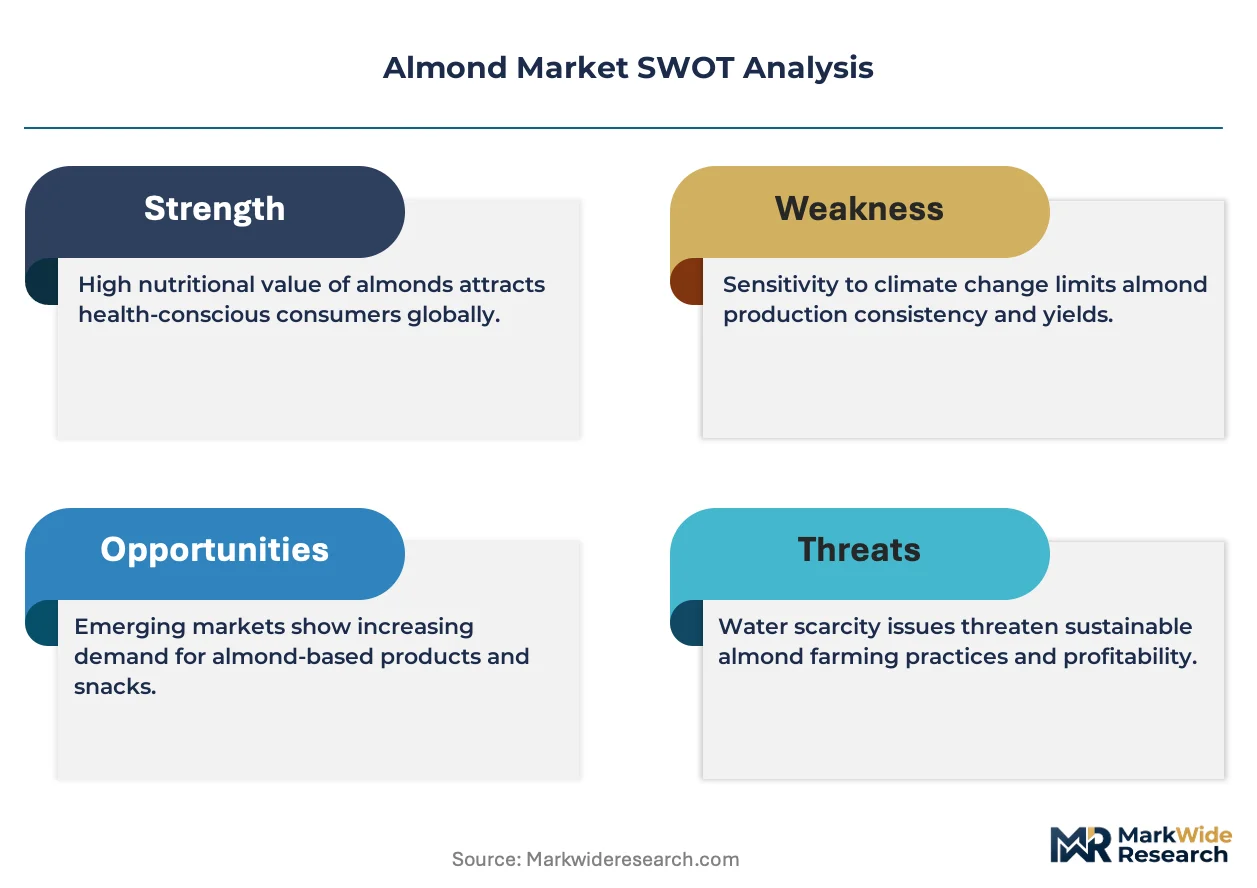
- Water allocation scarcity:California's Central Valley irrigation restrictions limit orchard expansion regardless of price signals, capping supply elasticity.
- Single-origin concentration risk:Processing capacity clusters in California's San Joaquin Valley, exposing buyers to regional drought or frost events.
- Pistachio and oat substitution:Alternative tree nuts and grain-based dairy substitutes compete for identical shelf space and formulation slots in plant-based portfolios.
Strategic Opportunities
- Spanish processing network expansion:Borges Agricultural & Industrial Nuts demonstrates European supply anchoring potential for Mediterranean climate almond cultivation.
- Almond flour keto-formulation:Gluten-free bakery and low-carbohydrate snack segments create margin pool capture opportunities from commodity kernel pricing.
- Carbon accounting disclosure mandates:EU CSRD requirements favor suppliers with verified water-use and emissions data, rewarding early sustainability credential investments.
Industry Challenges
- Pasteurization compliance timelines:FDA food safety regulations require validated kill-step documentation that delays new processor market entry.
- Mechanical harvest labor coordination:Shaking, hulling, and shelling operations demand precise timing windows that strain equipment and crew availability during peak season.
- Legacy irrigation infrastructure retrofit costs:Micro-drip and subsurface systems require capital deployment that smaller orchard operators cannot finance independently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Almond Market |
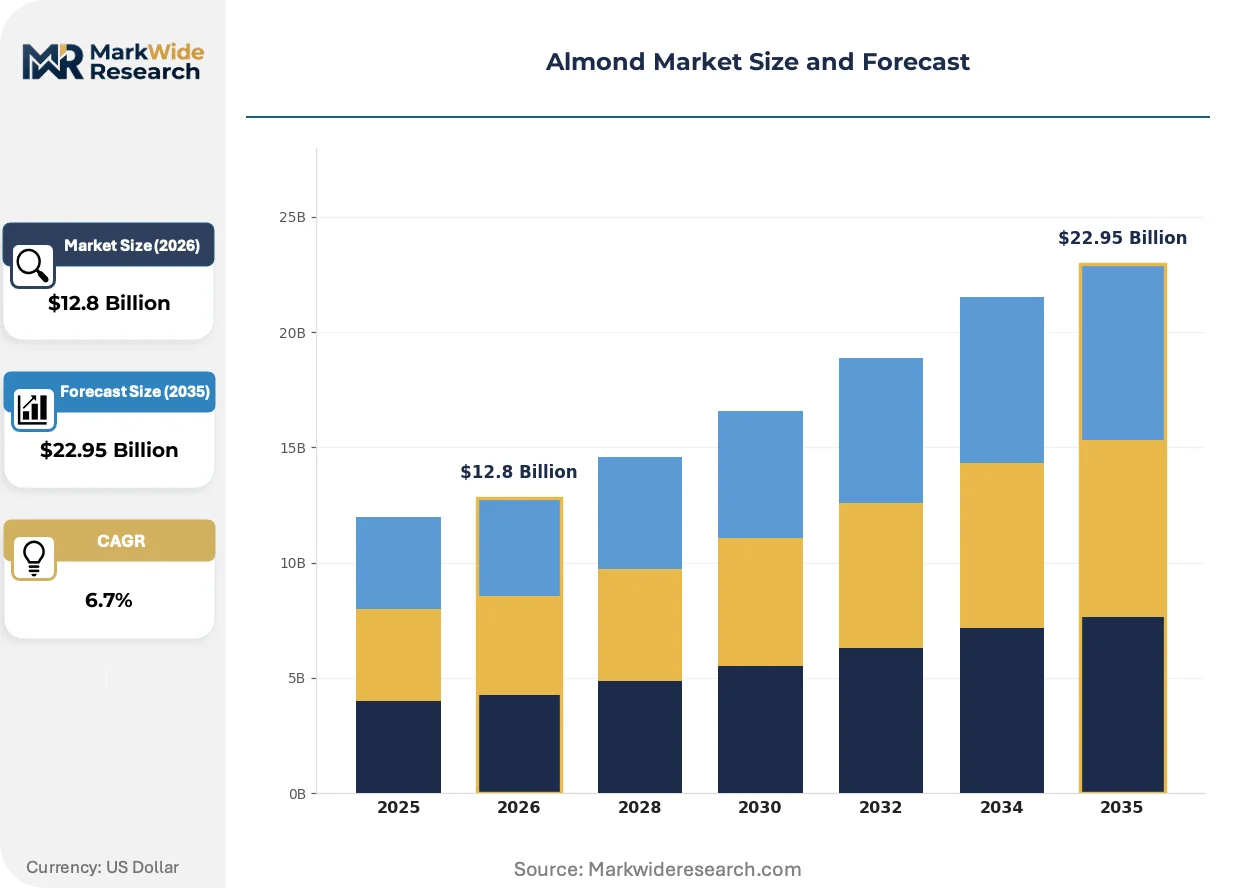
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Almonds, Roasted Almonds, Almond Flour, Almond Oil End User: Retail Consumers, Food Manufacturers, Beverage Industry, Snack Producers Packaging Type: Bulk Packaging, Retail Pack, Eco-friendly Bags, Vacuum Packs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | John B. Sanfilippo and Son, Royal Nut Company, Blue Diamond Growers, Harris Woolf Almonds, Treehouse California Almonds, Wonderful Pistachios & Almonds, Borges Agricultural & Industrial Nuts, Tariş, Select Harvests, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Almond Market Emerging Trajectories
Kernel specification grading and processing technology are actively fragmenting traditional commodity pricing structures, while regulatory water constraints and buyer sustainability mandates reshape competitive positioning across the value chain.
Precision irrigation sensor networks are bifurcating orchard management practices across California's Central Valley. Large-scale cooperatives deploy soil moisture telemetry and variable-rate drip systems to optimize water-use efficiency under state allocation caps. This technology is compressing yield variance between capital-intensive operations and smaller holdings unable to finance equivalent infrastructure.
EU REACH compliance and EFSA novel food evaluations are tightening import thresholds for processed almond derivatives entering European markets. Food manufacturers now demand comprehensive contaminant testing and supply chain documentation to satisfy distributor liability requirements. Small-to-mid processors face certification cost barriers that favor vertically integrated suppliers with in-house laboratory capabilities.
Clean-label snack procurement now prioritizes single-origin and organic kernel certifications over commodity-grade sourcing. National retail chains contract directly with California cooperatives for private-label roasted products, bypassing traditional wholesale distributors. This channel compression concentrates most visibly in United States convenience retail, where shelf-space allocation favors suppliers with third-party sustainability verification.
Almond Market Segmentation
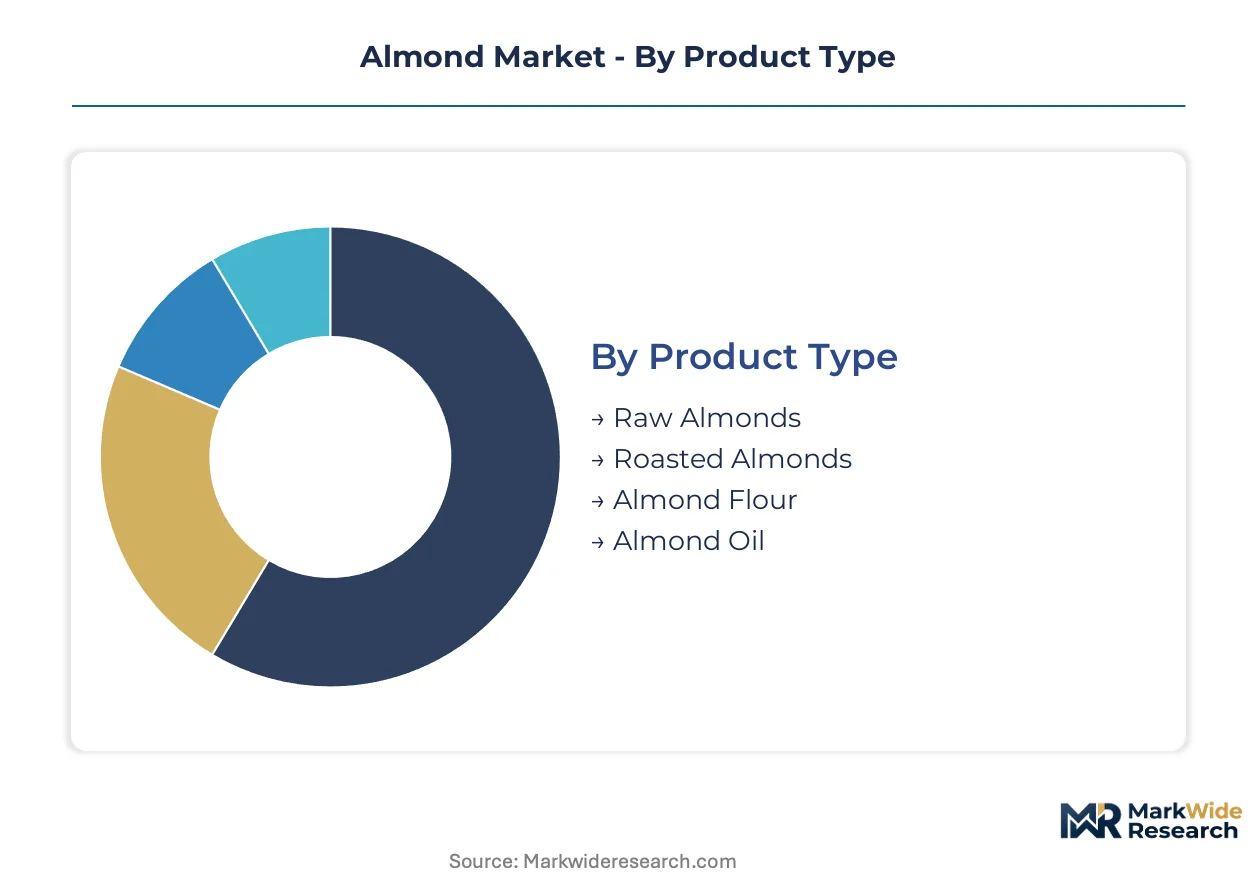
Kernel processing depth and packaging format determine margin capture across the almond value chain. Food manufacturers and retail buyers apply divergent procurement criteria, forcing suppliers to maintain parallel specification streams.
Product Type:
Roasted and value-added derivatives face intensifying substitution pressure from pistachio kernels and oat-based alternatives in clean-label formulations.
- Raw Almonds:Unprocessed kernels retain 50-55% oil content and 20-25% protein by weight, serving as the feedstock for downstream processing. California's Central Valley orchards supply bulk volumes to food manufacturers requiring pasteurization flexibility under FDA regulations. Water allocation scarcity constrains expansion regardless of price signals.
- Almond Flour:Finely milled blanched kernels deliver gluten-free functionality for keto bakery applications. Food manufacturers in the United States reformulate low-carbohydrate snack lines, capturing margin premiums from health-positioned retail buyers. EFSA novel food evaluations govern European import eligibility.
- Roasted Almonds:Thermal processing extends shelf stability for convenience retail distribution.
- Almond Oil:Cold-pressed extraction serves cosmetic and premium culinary segments.
Raw almonds retain volume leadership; almond flour holds the steepest expansion curve.
End User:
Procurement scale separates commodity-volume buyers from specification-intensive formulators seeking certified supply chains.
- Snack Producers:Roasted and flavored product lines dominate convenience retail shelf space. National grocery chains in the United States contract directly with California cooperatives for private-label clean-label positioning. Third-party sustainability verification determines contract eligibility.
- Food Manufacturers:Plant-based dairy reformulation drives concentrate and protein isolate demand. Almond protein substitutes for dairy bases in yogurt and ice cream applications under USDA grading standardization. Pasteurization compliance timelines constrain processor qualification.
- Retail Consumers:Direct purchase of raw and roasted kernels for home consumption.
- Beverage Industry:Almond milk extraction requires specific kernel sizing and blanching protocols.
Food manufacturers command the largest contract volumes; snack producers are climbing the fastest.
Packaging Type:
Carbon accounting disclosure mandates favor formats with verifiable lifecycle data under EU CSRD requirements.
- Bulk Packaging:Industrial totes and supersacks serve food manufacturer procurement at scale. California processors load direct-to-tanker shipments for multinational dairy alternative producers. Weight-based pricing minimizes per-unit handling costs.
- Eco-friendly Bags:Compostable and recyclable materials satisfy retail buyer sustainability mandates. European importers demand comprehensive supply chain documentation to satisfy distributor liability under REACH compliance. Certification cost barriers favor vertically integrated suppliers.
- Retail Pack:Consumer-facing portion control for grocery shelf placement.
- Vacuum Packs:Oxygen barrier extension for premium kernel preservation.
Bulk packaging dominates tonnage movement; eco-friendly bags gain share fastest.
Distribution Channel:
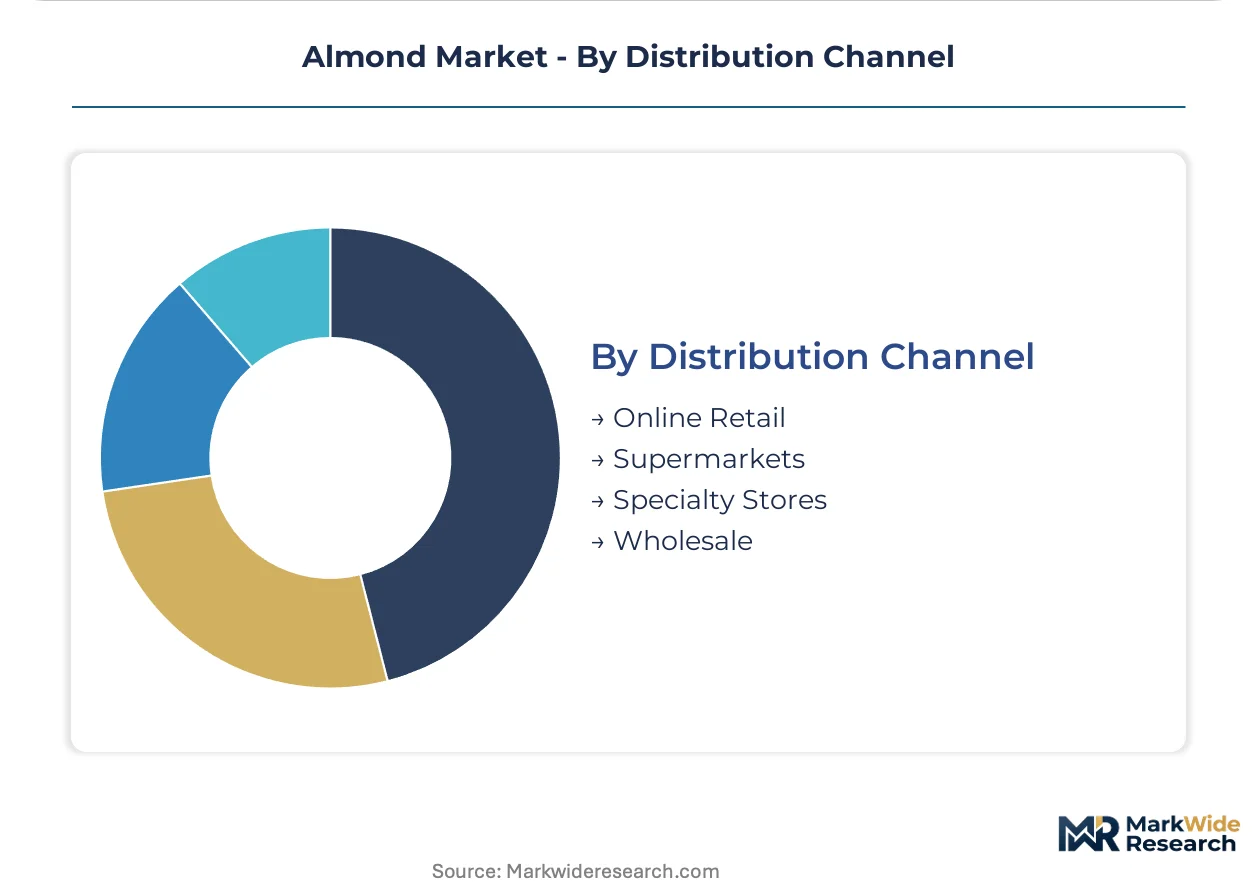
Channel compression concentrates in United States convenience retail as chains bypass traditional wholesale tiers.
- Supermarkets:National grocery chains allocate shelf space based on third-party sustainability verification. California cooperatives deliver private-label roasted products through direct contracting arrangements. Clean-label positioning determines placement priority.
- Online Retail:E-commerce platforms aggregate specialty and organic kernel certifications for dispersed geographic demand. Spanish processing networks anchor European supply through Borges Agricultural distribution infrastructure. Last-mile cold chain requirements segment fulfillment economics.
- Specialty Stores:Premium and organic positioning for health-focused retail formats.
- Wholesale:Traditional distributor intermediation for independent retail accounts.
Supermarkets maintain volume leadership; online retail shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt toward deficit positions in European and Asian markets, while the United States maintains surplus capacity constrained by irrigation policy. Water scarcity and phytosanitary protocols are redirecting trade flows toward Mediterranean and Australian suppliers.
United States
California's Central Valley supplies bulk kernel volumes to food manufacturers reformulating plant-based dairy lines. The State Water Resources Control Board caps irrigation allocations, forcing processors to compete for limited bearing acreage. Fresno and Kern counties concentrate mechanical harvesting and hulling operations under pasteurization mandates from the FDA.
Spain
Mediterranean climate cultivation supports European demand for raw and processed almond derivatives. EU REACH compliance and EFSA novel food evaluations govern import thresholds for protein concentrates and flour. Catalonia and Andalusia host Borges Agricultural processing networks that anchor continental supply chains.
Australia
Select Harvests and domestic cooperatives serve Asia-Pacific snack and ingredient demand through counter-seasonal harvest windows. The country's national agricultural regulator enforces biosecurity protocols for kernel export certification. Riverina and Sunraysia regions concentrate orchard development with precision irrigation infrastructure.
Turkey
Tariş and Aegean cooperatives supply Middle Eastern and European markets with organic and conventional kernel grades. The country's food safety authority mandates aflatoxin testing protocols for cross-border shipments. Manisa and Aydın provinces dominate smallholder cultivation with traditional harvesting methods.
China
Domestic consumption of roasted and value-added products expands through e-commerce and convenience retail channels. The National Health Commission sets maximum residue limits for imported kernels under food safety standards. Xinjiang's Tarim Basin hosts state-backed orchard development targeting self-sufficiency in tree nut supply.
Almond Market Vendor Landscape
Concentration sits with cooperative-scale processors and vertically integrated agribusinesses that control orchard-to-retail value chains. Three archetypes dominate: California-based grower cooperatives with captive processing capacity, Mediterranean suppliers leveraging EU regulatory proximity, and Australian operators exploiting counter-seasonal harvest timing. Competitive moves center on backward integration into irrigation infrastructure and direct contracting with multinational food manufacturers bypassing wholesale tiers.
Within the cooperative-processor tier, Blue Diamond Growers exemplifies scale-driven consolidation across California's San Joaquin Valley. Wonderful Pistachios & Almonds occupies a position spanning orchard ownership through branded retail placement. Borges Agricultural & Industrial Nuts anchors European supply architecture through its Spanish processing network.
| Leading Market Players |
|---|
| John B. Sanfilippo and Son |
| Royal Nut Company |
| Blue Diamond Growers |
| Harris Woolf Almonds |
| Treehouse California Almonds |
| Wonderful Pistachios & Almonds |
| Borges Agricultural & Industrial Nuts |
| Tariş |
| Select Harvests |
| Others |
Supply Flow & Price Mechanics
Oat milk substitution at food manufacturers simultaneously shifts procurement geography toward Nordic grain suppliers and compresses almond kernel premiums at the ingredient tier. This displacement dynamic rewards processors with backward integration into irrigation infrastructure while penalizing commodity traders lacking sustainability verification.
Pricing Analysis
Industrial OEM buyers anchor contract structures around long-term offtake agreements indexed to USDA grading tiers. Pricing stratifies across premium, standard, and economy tiers based on kernel size classification and organic certification status. Cost compression in standard-grade supply is intensifying because pistachio kernels compete for identical formulation slots in plant-based portfolios. Snack producers demonstrate highest price sensitivity due to thin retail margins, while cosmetic-grade almond oil buyers absorb premiums with minimal volume elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate procurement behavior as California water allocation uncertainty elevates supply security priorities. Geographic concentration centers on the United States, Spain, and Australia as primary kernel sources. The chain rests on pollinator hive availability, micro-drip irrigation hardware, and hulling equipment maintenance as critical inputs. Single-origin concentration risk exposes buyers to Central Valley drought events. Distribution runs through direct processor-to-manufacturer contracting that bypasses wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against oat and pistachio substitution threats that are capturing clean-label formulation slots across dairy alternative portfolios.
For Market Incumbents: Fortify supply security through backward integration into precision irrigation infrastructure across Fresno and Kern counties. Secure pasteurization capacity expansion ahead of FDA compliance timeline bottlenecks that constrain processor qualification. Channel control through direct contracting with national grocery chains insulates against wholesale margin erosion. For New Entrants and Emerging Players: Anchor in Spanish processing network expansion where EU REACH compliance proximity reduces certification barriers for European almond flour demand. Mediterranean climate cultivation offers counter-seasonal supply windows absent California frost exposure. Target organic kernel certification gaps as the most penetrable premium tier for keto-formulation supply. For Investors and Strategic Acquirers: EU CSRD disclosure mandates reshape the acquisition landscape toward suppliers with verified water-use telemetry and carbon accounting infrastructure. Long-term viability favors vertically integrated orchard-to-retail operators with in-house laboratory capabilities. The signal to watch is State Water Resources Control Board allocation adjudications that determine bearing acreage carrying capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Irrigation Infrastructure Deployment | Soil moisture telemetry optimizes yield under California allocation caps enforced by the State Water Resources Control Board. |
| Direct Processor-to-Retailer Contracting | Channel compression bypasses wholesale tiers for private-label clean-label positioning at national grocery chains. |
| Organic and Single-Origin Certification Investment | Third-party sustainability verification determines contract eligibility under EU CSRD procurement mandates. |
| Almond Flour Production Capacity Expansion | Gluten-free and keto-formulation demand captures margin premiums from commodity kernel pricing structures. |
| Counter-Seasonal Supply Network Development | Australian and Spanish harvest windows reduce single-origin concentration risk from Central Valley climate events. |
Methodological Framework
Desk research of USDA crop reports, FDA food safety filings, and EU REACH compliance databases preceded structured interviews with almond cooperative executives, food manufacturer procurement directors, and irrigation technology suppliers. Primary fieldwork with California Central Valley orchard operators and Spanish processing network managers validated secondary trade flow estimates. Analysis combined bottom-up acreage and yield modeling with top-down demand segmentation triangulation.
Variance decomposition across kernel grade, processing depth, and end-use application segments shaped the analytical framework over the projection horizon. Modeled dimensions included product type, packaging format, distribution channel, and regional regulatory cluster. CAGRs were derived from trend extrapolation of plant-based dairy formulation rates and snack channel clean-label adoption curves. Forecast inputs incorporated California State Water Resources Control Board allocation scenarios and EU EFSA novel food evaluation timelines.
Material uncertainties — drought severity, pollinator colony collapse, and pistachio substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about irrigation technology adoption rates and sustainability certification penetration. Revision becomes warranted when State Water Resources Control Board allocations fall below orchard maintenance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Dry Fruits Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Rubus Fructicosus (Blackberry) Seed Market
Nuts and Seeds
Flax Seed Meal Market
Nuts and Seeds
Processed Walnuts Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
Dry Roasted Almonds Snack Market
Nuts and Seeds
United States Nuts Market
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
Packaged Sunflower Seeds Market
Nuts and Seeds
Nutmeg Market
Nuts and Seeds
Strawberry Seed Oil Market
Nuts and Seeds
Horse Chestnut Seed Extract Market
Nuts and Seeds
North America Hazelnut Market