
 Fortified Yeast Market | 2026-2036
Fortified Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Fortified Yeast Market Analysis
Subscription-based technical support and formulation consulting is restructuring how fortified yeast suppliers capture recurring revenue beyond commodity powder sales. Angel Yeast Co., Ltd. leverages its integrated fermentation infrastructure to dominate bulk nutritional yeast supply across Asia-Pacific food manufacturers. Lallemand Inc. sustains competitive positioning through specialized active dry yeast strains engineered for high-stress industrial baking environments. Lesaffre Group anchors European demand with deep R&D investment in mineral-fortified baker's yeast tailored to regional flour profiles.
Fortified yeast denotes Saccharomyces cerevisiae biomass intentionally enriched with vitamins, minerals, or amino acids through controlled fermentation conditions, typically achieving B-complex concentrations exceeding standard nutritional yeast by 40-200% depending on fortification protocol. Manufacturers deploy spray-drying or drum-drying to preserve thermolabile nutrient activity for downstream food and feed applications. Nutritional yeast flakes command premium positioning in health retail channels where clean-label positioning supports margin expansion, while food fortification applications in bakery and dairy alternatives represent the fastest-growing demand vector. Powder and granule forms retain dominance in industrial procurement due to handling efficiency and dosing precision.
The FDA's food additive regulations and GRAS self-determination framework govern vitamin fortification levels in US-labeled yeast products, while EFSA's Novel Food catalog and health claim authorization process shape European market access for emerging fortified strains. BIS standards in India and China's SAMR national food safety standards impose compositional testing requirements that filter out substandard imports. Stakeholders must monitor evolving maximum permitted vitamin concentrations and substantiation thresholds for immune and metabolic health claims as regulatory divergence between major jurisdictions intensifies compliance complexity.
Market Dynamics
The fortified yeast market pivots on regulatory divergence between major jurisdictions, where EFSA's Novel Food catalog and FDA's GRAS framework impose conflicting substantiation thresholds that force manufacturers to maintain parallel formulation portfolios.
Growth Catalysts
- EFSA Novel Food authorization:The streamlined approval pathway for Saccharomyces cerevisiae biomass with enhanced B-vitamin profiles accelerates European commercialization timelines for functional food applications.
- Plant-based dairy alternatives:Oat and almond milk manufacturers in Germany and the Netherlands integrate nutritional yeast for umami depth and fortification density, displacing synthetic vitamin premixes.
- Fermentation infrastructure concentration:Dedicated bioreactor capacity in China's Hubei and Shandong provinces enables cost-efficient mineral enrichment at industrial scale for export markets.
Market Restraints
- Molasses price volatility:Sugar cane harvest disruptions in Brazil and India directly squeeze fermentation feedstock costs, compressing margin buffers for bulk nutritional yeast producers.
- Single-source supply risk:High-purity selenium and chromium salts for mineral fortification concentrate among three specialty chemical suppliers, creating input bottleneck vulnerability.
- Thermolabile nutrient degradation:Drum-drying temperatures above 80°C destroy thiamine and folate activity, forcing expensive low-temperature spray-drying alternatives.
Strategic Opportunities
- India's FSSAI micronutrient mandate:Mandatory wheat flour fortification creates immediate demand pull for mineral-enriched baker's yeast strains tailored to local climatic baking conditions.
- Precision fermentation convergence:CRISPR-edited yeast platforms combined with AI-driven media optimization enable targeted amino acid profiles for sports nutrition applications.
- Direct-to-baker subscription channels:Artisan sourdough revival in Melbourne and Portland creates premium procurement pathways bypassing traditional ingredient distributors.
Industry Challenges
- PhD-level fermentation biochemistry expertise:Talent scarcity in strain development and nutrient bioavailability modeling constrains R&D throughput for mid-tier manufacturers.
- Dual certification timelines:Simultaneous pursuit of organic certification and novel food status requires 18-24 month documentation cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortified Yeast Market |
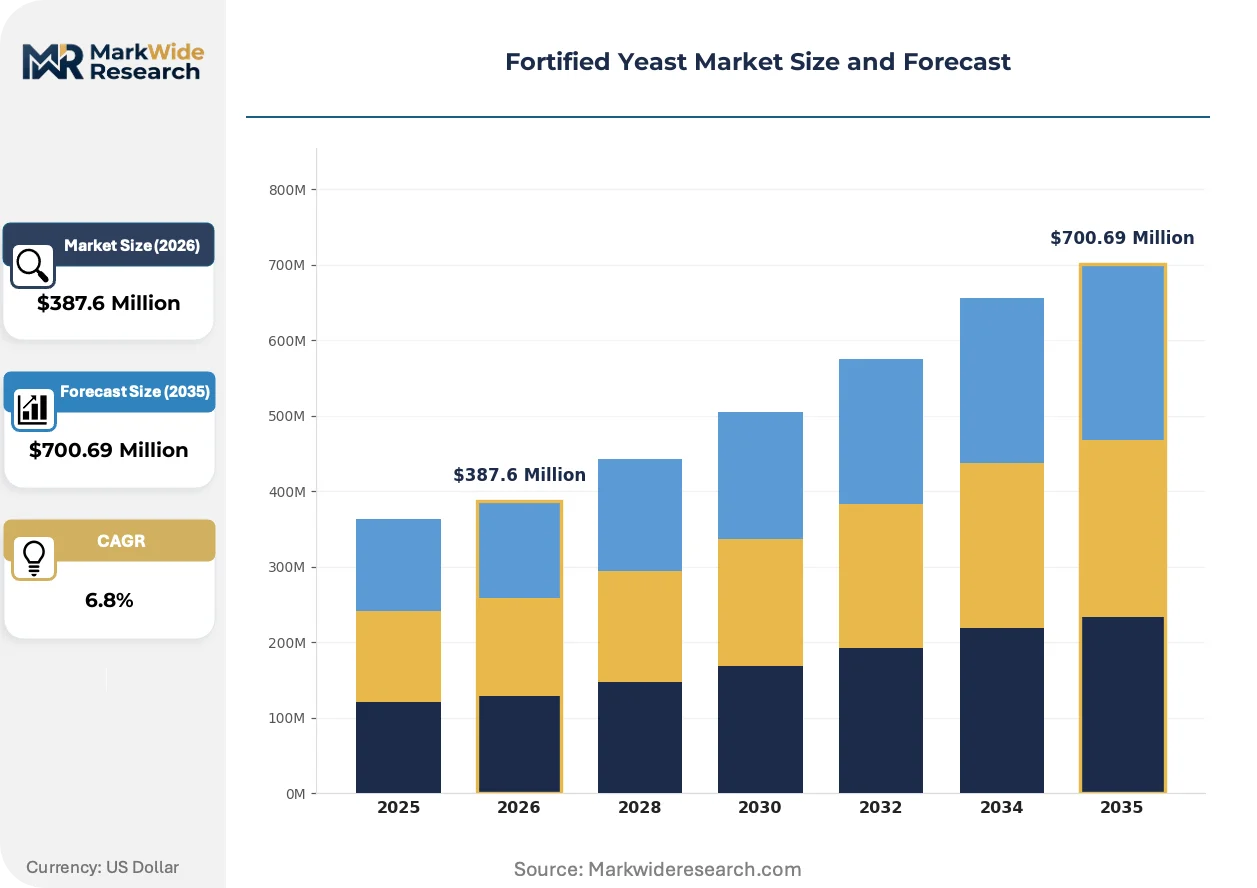
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nutritional Yeast, Active Dry Yeast, Instant Yeast, Brewer's Yeast Application: Baking, Food Fortification, Animal Feed, Nutritional Supplements Form: Flakes, Powder, Granules, Tablets End User: Food Manufacturers, Restaurants, Health Retailers, Households |
| Companies Covered | Angel Yeast Co., Ltd., Alltech Inc., Lallemand Inc., Lesaffre Group, Archer Daniels Midland Company, Cargill, Incorporated, Associated British Foods plc, Koninklijke DSM N.V., Leiber GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortified Yeast Market Emerging Trajectories
Continuous fermentation monitoring via Raman spectroscopy and dissolved oxygen sensors is compressing batch-to-batch variability, enabling real-time nutrient titer adjustments that were previously impossible.
CRISPR-Cas9 edited yeast strains with enhanced riboflavin biosynthetic pathways is electrifying the high-potency nutritional yeast segment. Supplement manufacturers in California and British Columbia are adopting these strains at pilot scale for vegan B-complex capsules. The technology is electrifying competitive positioning by collapsing the cost premium between natural and synthetic vitamin sources.
REACH authorization requirements for novel mineral chelates used in yeast fortification are tightening substance dossier standards across EU member states. Industrial bakeries in France and Poland now demand full supply chain transparency for selenium-enriched strains to preempt regulatory enforcement. The bakery segment is responding by consolidating supplier relationships with fermentation houses possessing established EFSA dossier libraries.
Clean-label procurement mandates from European retail chains are displacing synthetic vitamin premixes in favor of whole-food fortification sources. German discounters and British supermarkets now specify nutritional yeast-derived B-vitamins in private-label plant-based cheese formulations. This shift is most visible in the Nordics, where Coop Denmark and ICA Sweden have implemented 2025 formulation deadlines for natural-only fortification.
Fortified Yeast Market Segmentation
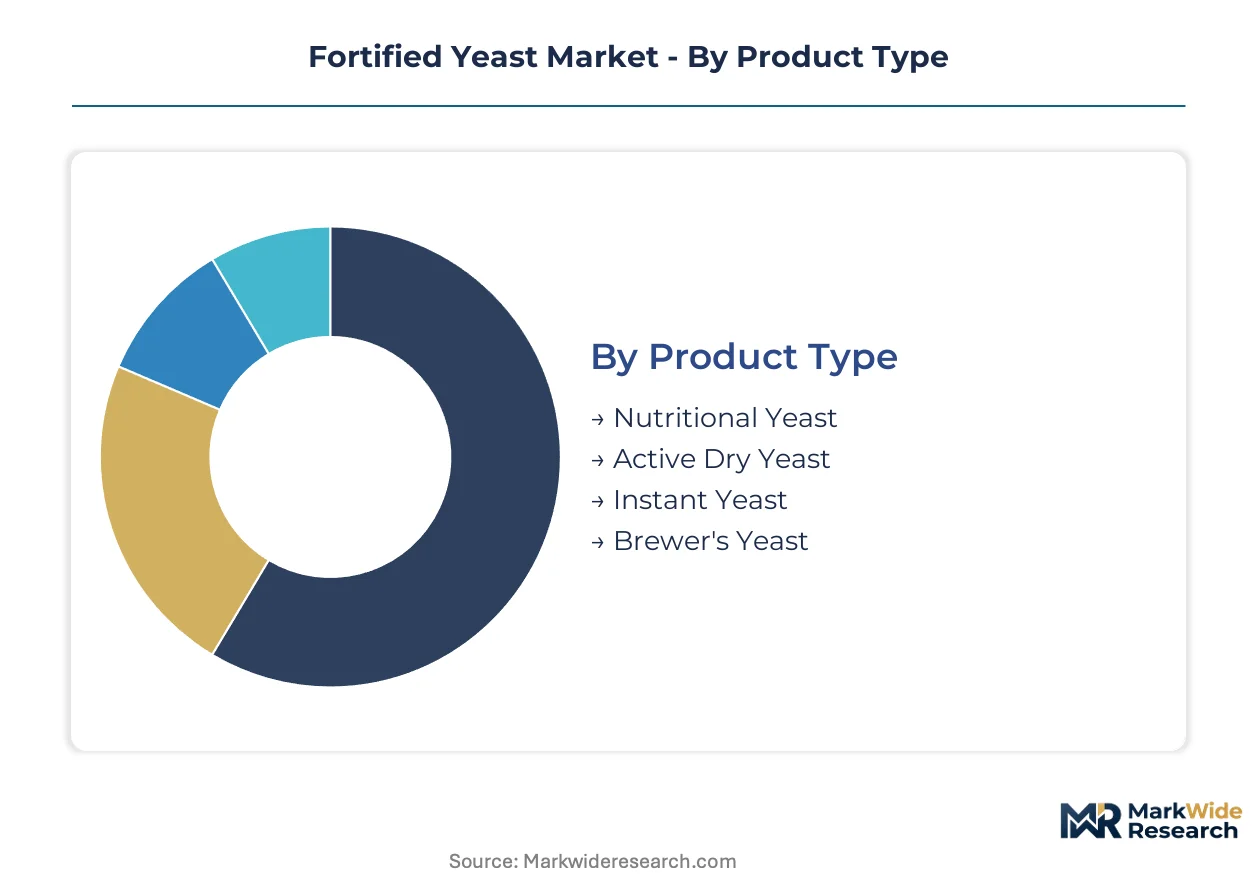
Segmentation in fortified yeast markets reveals divergent technical specifications and procurement patterns across downstream applications. Product form and fortification density requirements vary sharply between industrial bakery procurement and direct-to-consumer health retail channels.
Product Type:
Upgrade cycles in fortified yeast product lines track reformulation timelines in downstream food manufacturing, with mineral-enriched strains replacing standard nutritional yeast every 3-5 years as fortification mandates tighten.
- Nutritional Yeast:Inactive Saccharomyces cerevisiae biomass with B-vitamin enrichment through controlled fermentation, typically achieving 40-200% higher vitamin concentration than unfortified variants. German and Dutch plant-based dairy manufacturers in Cologne and Amsterdam are displacing synthetic premixes with nutritional yeast for umami depth and clean-label positioning. Demand concentrates in health retail channels where flake and powder formats command premium shelf placement.
- Active Dry Yeast:Living yeast cells in dehydrated granule form engineered for high-stress industrial baking environments with mineral fortification protocols. French and Polish industrial bakeries specify selenium-enriched strains to meet EFSA substantiation thresholds for health claims. Volume placements concentrate in commercial bakery procurement where fermentation reliability and mineral bioavailability determine supplier selection.
- Instant Yeast:Finely milled active yeast with rapid rehydration properties and vitamin B-complex fortification for accelerated dough development.
- Brewer's Yeast:Byproduct of beer fermentation with inherent mineral content from malted barley, typically requiring additional B-vitamin enrichment for supplement-grade specifications.
Volume placements concentrate in Active Dry Yeast; the faster expansion belongs to Nutritional Yeast.
Application:
Application-driven segmentation in fortified yeast tracks divergent margin structures between commodity food manufacturing and specialized health product formulations.
- Baking:Mineral-fortified yeast strains tailored to regional flour protein profiles and climatic fermentation conditions. India's FSSAI micronutrient mandate for wheat flour fortification is pulling demand for chromium and selenium-enriched baker's yeast strains adapted to high-temperature baking environments. Industrial procurement in Mumbai and Delhi specifies rapid-fermentation active dry variants with guaranteed mineral retention through proofing cycles.
- Food Fortification:B-vitamin and mineral delivery systems for processed foods including plant-based dairy alternatives and fortified cereals. German discounters and British supermarkets now mandate nutritional yeast-derived fortification in private-label plant-based cheese formulations with 2025 formulation deadlines. Clean-label procurement mandates from Coop Denmark and ICA Sweden are displacing synthetic vitamin premixes entirely.
- Animal Feed:Selenium and zinc-enriched yeast biomass for livestock mineral supplementation, particularly in poultry and aquaculture nutrition.
- Nutritional Supplements:High-potency B-complex delivery in capsule and tablet formats, with CRISPR-edited strains gaining pilot-scale adoption in California and British Columbia.
Procurement scale favors Baking; the steepest expansion trajectory is in Food Fortification.
Form:
Form selection in fortified yeast markets reflects handling efficiency requirements and thermolabile nutrient preservation constraints across distribution channels.
- Flakes:Large dehydrated particles with distinctive yellow coloration and savory flavor profile, produced through low-temperature drum-drying to preserve thiamine and folate activity. Health retailers in Melbourne and Portland source premium flake formats for artisan sourdough revival and direct-to-consumer subscription channels. Drum-drying above 80°C destroys vitamin activity, forcing expensive process controls.
- Powder:Fine-milled particles optimized for industrial dosing precision and homogeneous distribution in bulk food manufacturing. Powder and granule forms retain dominance in industrial procurement across China's Hubei and Shandong fermentation clusters due to handling efficiency and automated dosing compatibility.
- Granules:Intermediate particle size combining flowability with rapid dissolution, preferred in commercial bakery and animal feed applications.
- Tablets:Compressed nutritional yeast with standardized B-vitamin content for supplement channel distribution and precise dosage compliance.
Industrial throughput concentrates in Powder; the fastest volume gains are in Flakes.
End User:
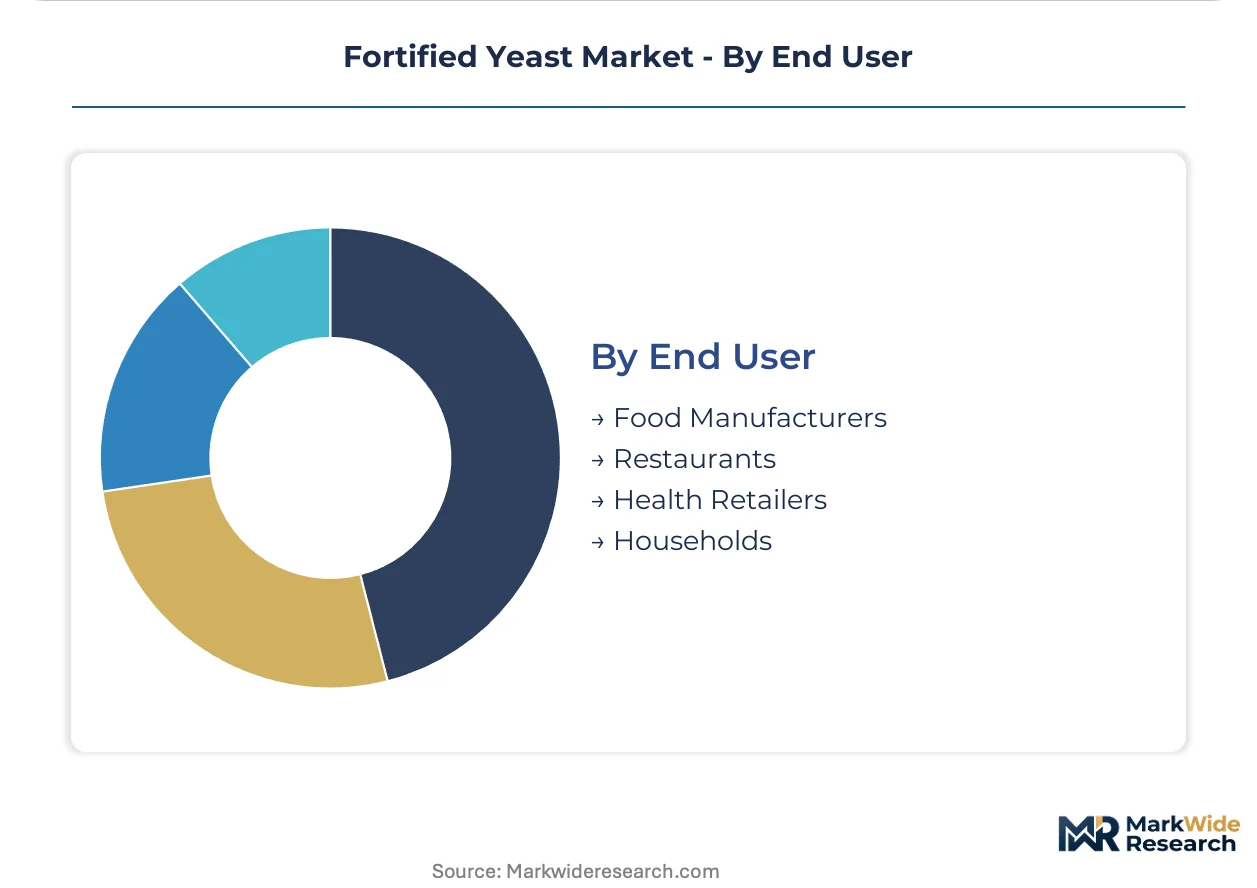
End-user segmentation reveals divergent technical support requirements and pricing sensitivity between institutional procurement and household consumption patterns.
- Food Manufacturers:Large-scale industrial buyers requiring batch certification, supply chain transparency documentation, and formulation consulting services. Subscription-based technical support and formulation consulting is restructuring supplier revenue capture beyond commodity powder sales. REACH authorization requirements for novel mineral chelates are tightening dossier standards across EU member states.
- Restaurants:Mid-volume procurement focused on consistent fermentation performance and umami enhancement for plant-based menu development.
- Health Retailers:Premium-channel distributors emphasizing clean-label positioning, organic certification, and non-GMO verification for nutritional yeast flakes and supplements.
- Households:Small-package consumers purchasing through e-commerce and specialty grocery, with demand concentrated in vegan and allergen-free diet adherents.
Procurement volume aggregates in Food Manufacturers; the most rapid expansion is occurring in Health Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wuhan anchors fortified yeast manufacturing through Angel Yeast's integrated fermentation campus, while Hubei and Shandong provinces concentrate China's export-oriented bioreactor capacity for mineral-enriched strains.
China
Domestic food manufacturers in Wuhan and Jinan source selenium-enriched nutritional yeast for infant formula fortification under SAMR's national food safety standards. The regulator's compositional testing requirements filter substandard imports and elevate quality benchmarks for export-bound production. Shandong's fermentation clusters supply chromium-fortified baker's yeast strains to Southeast Asian bakery chains expanding clean-label product lines.
Germany
Cologne and Hamburg-based plant-based dairy manufacturers displace synthetic vitamin premixes with nutritional yeast for umami depth in oat and almond milk formulations. EFSA's Novel Food catalog and streamlined authorization pathways for Saccharomyces cerevisiae biomass accelerate functional food commercialization timelines. Industrial bakeries in Munich specify mineral-fortified active dry yeast tailored to regional wheat protein profiles and climatic fermentation conditions.
United States
California and British Columbia supplement manufacturers pilot CRISPR-edited yeast strains for vegan B-complex capsules targeting sports nutrition channels. FDA's GRAS self-determination framework governs vitamin fortification levels while creating parallel substantiation requirements distinct from European protocols. Portland's artisan sourdough revival generates premium procurement through direct-to-baker subscription channels bypassing traditional distributors.
India
Mumbai and Delhi industrial bakeries procure rapid-fermentation active dry variants with guaranteed mineral retention through high-temperature proofing cycles. FSSAI's mandatory wheat flour fortification mandate creates immediate demand pull for chromium and selenium-enriched baker's yeast strains adapted to local climatic baking conditions. BIS standards impose compositional testing requirements that elevate quality thresholds for domestic procurement.
Netherlands
Amsterdam-headquartered plant-based cheese manufacturers integrate nutritional yeast-derived B-vitamins to meet Coop Denmark and ICA Sweden's 2025 natural-only fortification deadlines. REACH authorization requirements for novel mineral chelates tighten substance dossier standards across EU member states. Rotterdam's ingredient distribution hubs consolidate supplier relationships with fermentation houses possessing established EFSA dossier libraries.
Fortified Yeast Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the fortified yeast value chain, with integrated fermentation houses maintaining captive bioreactor capacity while specialized strain developers license intellectual property to contract manufacturers. The supplier base concentrates around three strategic tiers: bulk commodity powder producers serving industrial food manufacturing, premium flake and supplement-grade specialists targeting health retail channels, and precision fermentation technology platforms pursuing CRISPR-edited high-potency strains. Dominant competitive moves include backward integration into molasses feedstock sourcing and geographic expansion through regional toll-manufacturing partnerships.
Within the integrated fermentation tier, Angel Yeast Co., Ltd. and Lesaffre Group exemplify divergent geographic anchoring strategies, with the former representing Asia-Pacific bulk supply dominance and the latter occupying European R&D-intensive positioning. Lallemand Inc. sits within the specialized industrial yeast segment, its naming convention suggesting North American incorporation and active dry yeast concentration. These three entities collectively illustrate how supplier archetypes map to distinct downstream procurement channels.
| Leading Market Players |
|---|
| Angel Yeast Co., Ltd. |
| Alltech Inc. |
| Lallemand Inc. |
| Lesaffre Group |
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Associated British Foods plc |
| Koninklijke DSM N.V. |
| Leiber GmbH |
| Others |
Supply Flow & Price Mechanics
Molasses feedstock costs cascade through fermentation economics to stratify fortified yeast pricing across three distinct tiers. Brazilian sugar cane harvest volatility transmits directly to bulk nutritional yeast margins, while mineral-enriched specialty strains command premium positioning through EFSA dossier investments.
Pricing Analysis
Yield-guaranteed performance anchors pricing for active dry yeast strains engineered for high-stress industrial baking environments. Three-tier pricing structure across premium, standard, and economy levels separates CRISPR-edited high-potency strains from conventional nutritional yeast and commodity baker's yeast grades. Cost compression in bulk powder segments intensifies because molasses price volatility squeezes margin buffers for Asian fermentation houses. Industrial food manufacturers exhibit highest price sensitivity due to volume procurement scale, while health retailers absorb premiums for organic-certified flake formats.
Supply Chain Analysis
Selenium and chromium salt supply rests on three specialty chemical producers concentrated in Germany, Belgium, and the United States. Fermentation feedstock draws from Brazilian and Indian sugar cane processors, while bioreactor capacity concentrates in China's Hubei and Shandong provinces. Single-source vulnerability for high-purity mineral inputs creates bottleneck exposure during geopolitical trade disruptions. Distribution runs through Rotterdam and Singapore ingredient hubs serving European and Asia-Pacific food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA's Novel Food authorization timelines erect a cost-of-compliance barrier that rewards incumbent fermentation houses with established dossier libraries. This regulatory moat filters substandard imports and consolidates supplier relationships around proven regulatory navigation capability.
For Market Incumbents: Cement market position by deepening captive molasses sourcing partnerships in Brazil and India to buffer feedstock volatility. Expand bioreactor capacity in Shandong province to capture India's FSSAI-mandated wheat flour fortification demand. CRISPR-edited strain developers represent the primary competitive threat requiring accelerated R&D throughput investment.
For New Entrants and Emerging Players: Launch via direct-to-baker subscription channels in Melbourne and Portland where artisan sourdough revival bypasses traditional distributor control. Target precision fermentation platforms for sports nutrition applications as the most penetrable white space. Differentiate through AI-driven media optimization capabilities rather than commodity bulk supply.
For Investors and Strategic Acquirers: EFSA streamlined approval pathway activation for Saccharomyces cerevisiae biomass is the leading indicator that regulatory-compliant strain portfolios will command acquisition premiums. Long-term viability favors integrated fermentation houses with backward feedstock control. Watch for India's FSSAI enforcement intensity as the signal for emerging market demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Sourcing | Captive Brazilian and Indian feedstock supply buffers margin compression from harvest volatility. |
| CRISPR Strain Development Investment | Enhanced riboflavin biosynthetic pathways collapse cost premiums versus synthetic vitamin sources. |
| EFSA Dossier Library Expansion | Established Novel Food documentation accelerates European commercialization timelines for new strains. |
| Direct-to-Baker Channel Development | Subscription-based technical support captures recurring revenue beyond commodity powder transactions. |
| Precision Fermentation Platform Buildout | AI-driven media optimization enables targeted amino acid profiles for sports nutrition applications. |
Methodological Framework
Independent corroboration across fermentation plant managers, procurement leads at German and Dutch plant-based dairy manufacturers, distribution channel partners in Rotterdam and Singapore, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with technical R&D directors at integrated yeast houses combined with secondary validation from EFSA Novel Food catalog entries, SAMR national food safety standards documentation, FSSAI micronutrient mandate circulars, and customs trade data for molasses and mineral salt inputs. Bottom-up strain-level production estimates and top-down food fortification program penetration rates underwent cross-triangulation.
Comparable historical reference periods spanning regulatory transition windows anchored the forecast framework across the analysis window. Segmentation dimensions modeled include product type, application, form, and fortification density tier alongside regional regulatory cluster differentiation. CAGRs derived from slope-consistency checks against documented food fortification program expansion trajectories. Forecast inputs incorporated molasses price elasticity coefficients and EFSA authorization pipeline velocity.
Molasses harvest disruption, EFSA substantiation threshold revisions, and FSSAI enforcement intensity variations are the dominant revision risks. Forecasts reflect documented assumptions regarding regulatory pathway timelines and mineral salt supply continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Tocopherols Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
High Calcium Fortified Food Market
Vitamin Fortified
Food Grade Vitamin C Market
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Pantothenic Acid Market
Vitamin Fortified
Global Quercetin Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Europe Vitamin a Market
Vitamin Fortified
Beta Carotene Market
Vitamin Fortified
Middle East Feed Vitamins Market