
 Dairy-Free Spreads Market | 2026-2036
Dairy-Free Spreads Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy-Free Spreads Market Outlook
The EU Green Deal is expanding compliance obligations for food manufacturers across Europe. Upfield leverages its manufacturing scale to supply retailers with reformulated oil blends that meet emerging carbon thresholds. Miyoko's Creamery differentiates through fermentation-based processes that replicate dairy mouthfeel without allergen risk. Kite Hill specializes in almond-derived spreads, occupying premium shelf space in specialty grocers.
Dairy-free spreads are emulsified fat-based products formulated from plant oils, nut pastes, or legume derivatives, typically containing 60-80% lipid content with stabilizers and emulsifiers to achieve spreadable consistency at refrigeration temperatures. Their primary commercial purpose is to replace butter and cream cheese in both retail and food service applications where lactose intolerance, vegan preference, or allergen avoidance drives substitution. Nut butters anchor the product type segment with established household penetration, while vegetable oil spreads compete on price in conventional retail. The distribution channel dimension shows supermarkets controlling mainstream volume, though health food shops capture margin-rich specialty buyers seeking organic certification.
EFSA governs novel food approvals and allergen labeling standards that determine which plant bases enter European formulations, while REACH restricts certain emulsifier chemistries in food-contact packaging. FDA oversees GRAS determinations for new protein sources in the United States, creating divergence in formulation strategies across Atlantic markets. Stakeholders must monitor how ECHA's expanding substance restrictions and state-level U.S. labeling laws reshape ingredient sourcing and packaging material choices.
Market Dynamics
EU Green Deal carbon-labeling mandates are forcing reformulation across European manufacturing, compressing margins for oil-blend suppliers while creating first-mover advantages for fermentation-based processors.
Growth Catalysts
- EU Green Deal compliance:Carbon-threshold requirements for packaged foods accelerate plant-based menu expansion across food service operators. Retail chains in Germany actively promote allergen-free private label spreads to capture sustainability-conscious shoppers.
- Fermentation technology:Microbial precision fermentation replicates dairy mouthfeel without allergen exposure, opening formulation pathways previously blocked by texture limitations. Specialty grocers allocate premium shelf space to these differentiated products.
- Almond-derived spreads:California almond cultivation provides stable raw material supply for high-margin spreads. Health food shops leverage organic certification to capture specialty buyers seeking clean-label alternatives.
Market Restraints
- Input cost volatility:Palm and coconut oil prices fluctuate with Southeast Asian weather patterns and export restrictions. Manufacturers face margin compression when reformulating to meet carbon thresholds.
- Supply concentration risk:Stabilizer and emulsifier chemistries cluster among German and Dutch specialty chemical suppliers. REACH restrictions on food-contact packaging materials limit alternative sourcing.
- Technical limitation:Cold-chain requirements for fermentation-based spreads constrain distribution reach. Refrigeration-dependent shelf stability blocks penetration into ambient retail channels.
Strategic Opportunities
- Underpenetrated food service:Institutional catering in France and Italy retains butter-dominant formulations. Plant-based procurement mandates in public sector contracts create substitution windows.
- Regulatory tailwind:EFSA novel food approval pathways for legume-derived proteins accelerate product pipeline expansion. Early filers secure multi-year formulation exclusivity.
- Channel innovation:Direct-to-restaurant distribution bypasses supermarket slotting fees. Chef-education programs build brand preference before retail placement.
Industry Challenges
- Skill gap in fermentation scale-up:Industrial microbiology talent concentrates in pharmaceutical and brewing sectors. Dairy-free spread manufacturers compete for bioprocess engineers.
- Certification timeline compression:EFSA novel food safety assessments extend 18-24 months. Product launch schedules misalign with seasonal menu planning cycles.
- Integration complexity:Legacy dairy equipment requires retrofitting for plant oil handling. CapEx for dedicated allergen-free production lines strains mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy-Free Spreads Market |
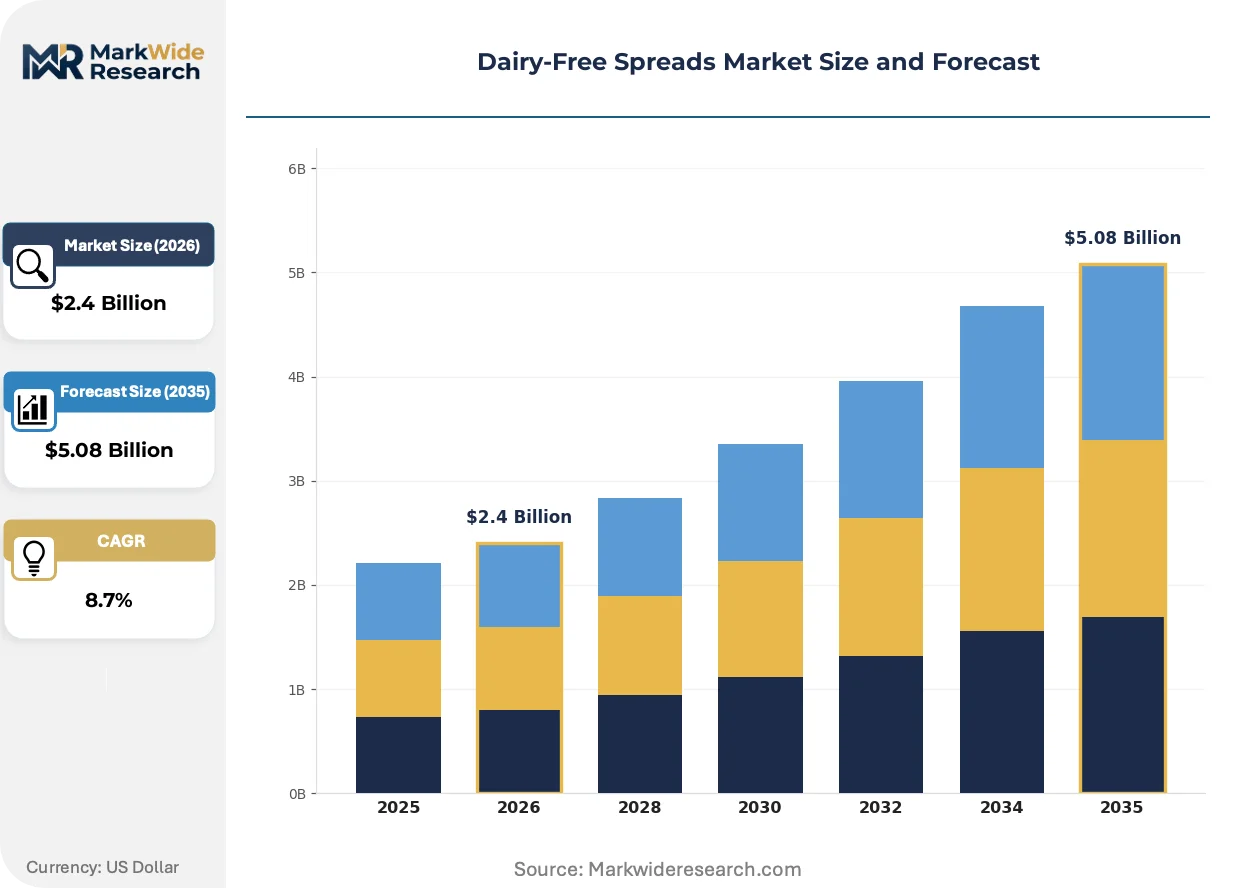
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut Butters, Coconut Spread, Soy-Based Spread, Vegetable Oil Spread End User: Health Conscious Consumers, Vegan Individuals, Food Service, Retail Packaging Type: Glass Jar, Plastic Tub, Pouch, Recyclable Container Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Health Food Shops |
| Companies Covered | Follow Your Heart, Daiya Foods, Miyoko's Creamery, Wayfare Foods, Amy's Kitchen, Kite Hill, Upfield, Organic Valley, Meridian Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy-Free Spreads Market Strategic Shifts
Fermentation-based processing is displacing conventional oil-blend formulations across premium segments, while regulatory carbon accounting reshapes ingredient sourcing and procurement models pivot toward direct supplier relationships.
Precision fermentation using fungal and bacterial strains is expanding into spreadable fat production, generating lipid structures that mimic butter crystallization without hydrogenation. Specialty grocers in Germany and the Netherlands accelerate adoption, placing these products in refrigerated premium sets. This technology is expanding into conventional retail as price parity approaches through manufacturing scale.
REACH restrictions on emulsifier chemistries in food-contact packaging are forcing material substitutions across European supply chains. Manufacturers reformulate with plant-derived lecithins and modified starches to maintain shelf stability. The vegetable oil spread segment faces the steepest compliance burden, with German retailers demanding full substance disclosure.
Buyer concentration among food service procurement groups compresses supplier negotiation cycles. Group purchasing organizations consolidate plant-based spread contracts, displacing fragmented distributor relationships. This concentration is most visible in French and Italian institutional catering, where sustainability scorecards determine vendor selection.
Dairy-Free Spreads Market Segmentation
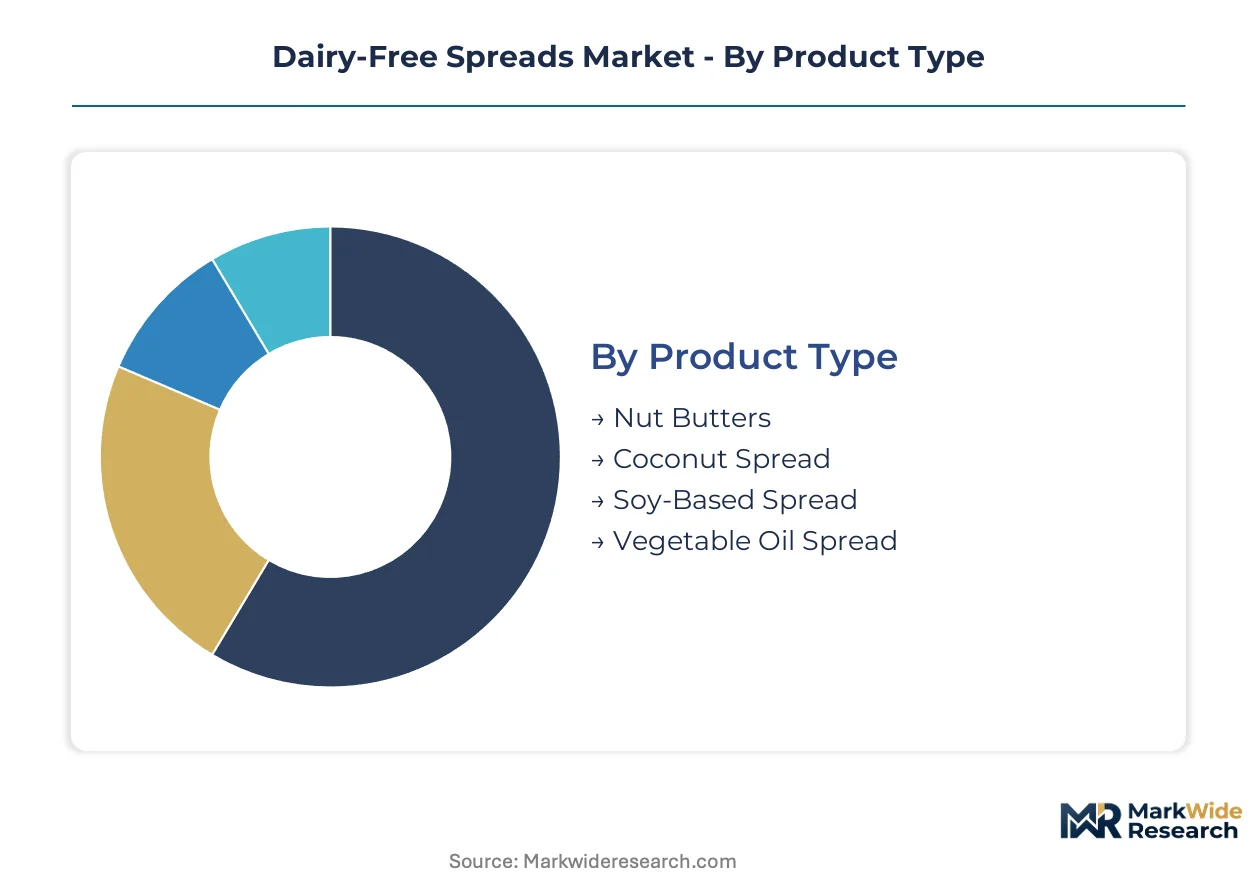
Segmentation in dairy-free spreads reveals how formulation chemistry, buyer motivation, and channel economics partition value capture. Manufacturers align R&D spend and production assets against these divides to defend margin position.
Product Type:
Supply concentration clusters around oil extraction infrastructure and nut processing capacity, with raw material geography dictating regional manufacturing footprints.
- Nut Butters:Ground nut pastes with 50-70% lipid content achieve spreadable viscosity through particle size reduction rather than emulsification. German and Dutch retail chains drive volume through private label programs targeting allergen-free households.
- Vegetable Oil Spread:Emulsified blends of palm, coconut, and sunflower oils with added stabilizers compete on price parity with conventional butter. Southeast Asian export restrictions on base oils compress margins for European compounders.
- Coconut Spread:Virgin and refined coconut oil bases leverage tropical supply chains concentrated in Indonesia and the Philippines.
- Soy-Based Spread:Protein-stabilized emulsions from soybean oil and lecithin occupy mid-tier positioning in conventional retail.
Vegetable Oil Spread absorbs the bulk of installed capacity; Nut Butters is expanding most quickly.
End User:
Application requirements split between shelf-stable retail formats and cold-chain-dependent food service delivery, reshaping packaging and logistics specifications.
- Food Service:Institutional buyers in France and Italy specify spreadable performance across temperature fluctuations for bakery and catering applications. EU Green Deal procurement mandates in public sector contracts accelerate plant-based substitution.
- Health Conscious Consumers:Clean-label seekers prioritize organic certification and minimal ingredient lists, paying shelf-space premiums in specialty channels.
- Vegan Individuals:Ethical avoidance of animal products drives brand loyalty toward fermentation-based alternatives with dairy-comparable mouthfeel.
- Retail:Mass-market buyers respond to promotional pricing and placement in conventional supermarket dairy aisles.
Food Service captures the steepest procurement volume growth; Health Conscious Consumers command the highest per-unit margins.
Packaging Type:
Material selection balances shelf stability, sustainability credentials, and logistics economics across ambient and refrigerated distribution networks.
- Glass Jar:Inert barrier properties suit premium nut butters with extended ambient stability requirements. German retailers demand full carbon footprint disclosure for glass-heavy formats under EU Green Deal compliance.
- Plastic Tub:Polypropylene and PET containers dominate conventional vegetable oil spreads with cost-efficient injection molding.
- Pouch:Flexible film structures reduce shipping cube for food service bulk delivery and single-serve hospitality portions.
- Recyclable Container:Post-consumer recycled content and mono-material designs respond to ECHA packaging substance restrictions.
Plastic Tub retains the largest production volume; Recyclable Container is climbing the fastest on regulatory pressure.
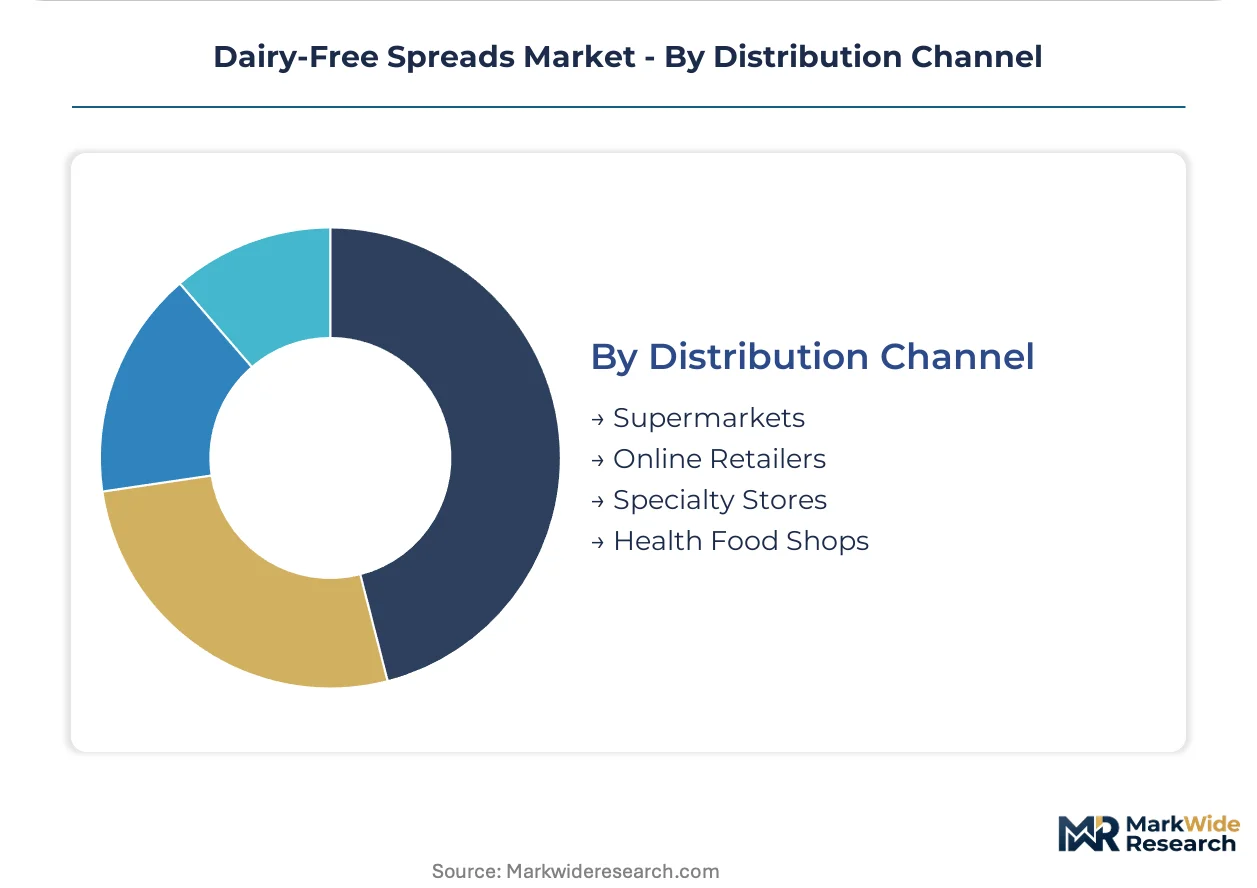
Distribution Channel:
Channel concentration determines margin structure, with direct procurement relationships displacing fragmented wholesale networks in institutional segments.
- Supermarkets:Centralized category management controls mainstream volume through slotting fee negotiations and promotional calendar alignment. German chains actively promote allergen-free private label spreads to sustainability-conscious shoppers.
- Specialty Stores:Curated assortments of fermentation-based and organic-certified products capture premium pricing from informed buyers.
- Health Food Shops:Independent retailers leverage staff expertise to move high-margin almond-derived spreads with clean-label positioning.
- Online Retailers:Direct-to-consumer fulfillment enables subscription models and flavor variety packs with reduced working capital requirements.
Supermarkets absorb the bulk of volume throughput; Specialty Stores is gaining share fastest on premium migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of dairy-free spreads concentrates in European manufacturing corridors while consumption growth accelerates across German retail chains and North American food service networks. Supply chains stretch from Southeast Asian oil palm estates to California almond orchards, creating divergent cost structures across regional markets.
Germany
Retail chains in Germany actively promote allergen-free private label spreads to capture sustainability-conscious shoppers seeking carbon-labeled alternatives. EU Green Deal compliance mandates force reformulation timelines that favor domestic compounders with established laboratory infrastructure. The North Rhine-Westphalia chemical corridor hosts emulsifier and stabilizer suppliers serving reformulation demand across European manufacturing.
United States
California almond cultivation provides stable raw material supply for high-margin spreads targeting health food distribution channels. FDA GRAS determinations for novel protein sources create regulatory pathways distinct from European approval timelines, enabling faster product iteration. The Pacific Northwest fermentation cluster attracts bioprocess engineering talent from pharmaceutical and brewing sectors for precision lipid production.
France
Institutional catering in France retains butter-dominant formulations, creating substitution windows as EU Green Deal procurement mandates expand across public sector contracts. ANSM and national food safety authorities align with EFSA novel food frameworks while maintaining country-specific labeling requirements. The Île-de-Paris region concentrates food service procurement group headquarters consolidating plant-based spread contracts.
Netherlands
Specialty chemical suppliers in the Netherlands dominate stabilizer and emulsifier chemistries for European dairy-free spread manufacturing. REACH restrictions on food-contact packaging materials drive material substitution research among Dutch packaging converters. The Rotterdam-Antwerp port corridor handles bulk vegetable oil imports subject to Southeast Asian export volatility.
United Kingdom
Health food shops across London and the Southeast capture premium pricing from informed buyers seeking organic-certified almond and coconut spreads. Divergence from EU regulatory frameworks post-Brexit creates parallel approval pathways for novel food ingredients entering British formulations. The Midlands manufacturing belt hosts contract packing operations serving both domestic retail and export channels.
Dairy-Free Spreads Market Competitive Environment
The competitive structure tilts toward diversified food conglomerates with established oil-blend infrastructure and specialized fermentation startups with differentiated texture capabilities. Tiered positioning separates premium fermentation-based products from price-competitive vegetable oil spreads. Strategic archetypes include manufacturing-scale compounders, precision fermentation specialists, and nut-processing originators. Capacity expansion in cold-chain distribution and direct-to-restaurant procurement relationships represent dominant competitive moves reshaping channel access.
Among North American specialists, Miyoko's Creamery and Kite Hill exemplify the fermentation-based and almond-derived archetypes respectively, while Upfield represents the manufacturing-scale compounder model with European supply chain integration. These three anchors occupy distinct positioning tiers without overlapping core technologies.
| Leading Market Players |
|---|
| Follow Your Heart |
| Daiya Foods |
| Miyoko's Creamery |
| Wayfare Foods |
| Amy's Kitchen |
| Kite Hill |
| Upfield |
| Organic Valley |
| Meridian Technology Group |
| Others |
Value Chain & Pricing Dynamics
Bioprocess engineering talent concentration in the Pacific Northwest and North Rhine-Westphalia chemical corridor creates labor-cost differentials that stratify pricing tiers, with fermentation-based spreads commanding shelf-space premiums while oil-blend suppliers compete on thinner margins.
Pricing Analysis
Margin tightening in vegetable oil spreads reflects Southeast Asian export restrictions on palm and coconut base oils, compressing compounder profitability. Three-tier pricing structure across premium fermentation-based, standard almond-derived, and economy vegetable oil levels segments buyers by mouthfeel fidelity and carbon-labeling requirements. Cost-down pressure on mid-tier soy-based spreads accelerates because REACH compliance adds formulation expense. Food service procurement groups exhibit highest price sensitivity, while health food shops absorb premiums for organic certification.
Supply Chain Analysis
Returns and cold-chain spoilage flows from fermentation-based spreads create reverse-logistics complexity that ambient-stable nut butters avoid. Raw material sourcing draws from Indonesian and Philippine coconut estates, California almond orchards, and Malaysian palm plantations. Stabilizer and emulsifier chemistries hinge on German and Dutch specialty chemical suppliers, creating single-source vulnerability. Distribution runs through Rotterdam-Antwerp port corridors into European manufacturing, with direct-to-restaurant channels displacing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's carbon-labeling mandates construct a compliance moat that rewards early reformulators with sustained shelf access while penalizing laggards with exclusion from German retail chains.
For Market Incumbents: Lock in fermentation capacity through captive bioprocess engineering pipelines before pharmaceutical and brewing sectors absorb available talent. Secure backward integration into California almond cultivation to stabilize input costs against commodity volatility. Defend margin position by retrofitting legacy dairy equipment for allergen-free production lines rather than greenfield construction. For New Entrants and Emerging Players: Enter via direct-to-restaurant distribution in French and Italian institutional catering, where butter-dominant procurement creates substitution windows under EU Green Deal public sector mandates. Target chef-education programs as the most penetrable channel for building brand preference before retail slotting fee exposure. White-space exists in ambient-stable fermentation-based spreads that bypass cold-chain constraints. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation specialists given EFSA novel food approval timelines that confer multi-year formulation exclusivity to early filers. Long-term viability favors archetypes with integrated bioprocess capabilities and established cold-chain partnerships. Monitor ECHA packaging substance restriction expansions as the inflection signal for material substitution investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captures bioprocess engineering talent before pharmaceutical competition intensifies wage pressure. |
| Direct-to-Restaurant Distribution | Bypasses German supermarket slotting fees while building chef preference ahead of retail placement. |
| ESFA Novel Food Filing | Secures formulation exclusivity windows before competitors navigate 18-24 month assessment timelines. |
| Almond Cultivation Integration | Stabilizes raw material supply against California drought cycles and export market volatility. |
| Recyclable Packaging Transition | Anticipates REACH restrictions on food-contact emulsifier chemistries demanded by Dutch retailers. |
Study Parameters
Independent corroboration across fermentation technology suppliers, German retail category managers, and French institutional procurement directors underwrites the qualitative findings. Primary interviews with bioprocess engineers, specialty grocer buyers, and EFSA regulatory consultants combined with secondary validation from EU Green Deal compliance filings, ECHA substance restriction databases, and customs trade records. Bottom-up volume triangulation against top-down category expenditure estimates anchors market sizing.
Comparable-period anchoring to historical reformulation cycles and carbon-labeling adoption curves shaped the projection horizon. Segmentation modeling spanned product type chemistry, end-user application requirements, packaging material compliance tiers, and distribution channel concentration patterns. CAGRs derived from category growth rate convergence with input cost elasticity assumptions. Forecast inputs incorporated REACH regulatory timeline probabilities and food service procurement mandate rollout schedules.
Revisions become necessary when EFSA novel food approval backlogs extend beyond standard assessment windows or when Southeast Asian palm oil export restrictions intensify. Forecasts reflect assumptions about fermentation scale-up feasibility and cold-chain infrastructure expansion. Practitioners should monitor ECHA packaging substance restriction proposals and German retailer carbon-disclosure requirements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Non-Dairy Creamer Powder Market
Dairy Alternatives
Cultured Dairy Blends Market
Dairy Alternatives
Sugar-Free Soy Milk Powder Market
Dairy Alternatives
North America Dairy Alternative Market
Dairy Alternatives
Dairy Free Yogurt Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
North America Non-Dairy Milk Market
Dairy Alternatives
Dairy-Free Evaporated Milk Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
Dairy Alternatives Market