
 Beverage Tester Market | 2026-2036
Beverage Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Tester Market Analysis
Modular benchtop configurations is shifting buyer preference away from monolithic laboratory installations. Thermo Fisher Scientific leverages its chromatography portfolio to anchor high-throughput contract manufacturing accounts. Lee Hung Scientific Pte Ltd competes on portable spectroscopy units calibrated for tropical supply chains. VWR controls distribution density across North American quality control labs with same-day fulfillment networks.
Beverage testers are analytical instruments that measure chemical composition, flavor profiles, and nutritional parameters using spectroscopic, chromatographic, electrochemical, or optical detection methods, typically operating at ppm-level sensitivity for quality assurance in liquid matrices. Portable testers lead unit shipments due to brewery floor deployment, while automatic testers capture premium margin pools through LIMS integration and unattended batch processing. Electrochemical technology sustains cost-sensitive manual segments, whereas spectroscopy dominates research institution procurement for non-destructive flavor analysis.
EFSA standards on additive labeling and the FDA's Food Safety Modernization Act shape instrument validation requirements and demand documentation capabilities. REACH compliance in Europe and China's GB standards for food contact materials restrict sensor materials and calibration reagent compositions. Stakeholders must monitor harmonization gaps between regional certification protocols when configuring export-bound product platforms.
Market Dynamics
Modular benchtop configurations are displacing monolithic laboratory installations as craft breweries and contract manufacturers prioritize floor-deployable quality control. This shift compresses capital requirements while expanding real-time testing access across distributed production networks.
Growth Catalysts
- EFSA additive labeling protocols:European breweries face mandatory expanded chemical disclosure requirements. Automated spectroscopy systems reduce compliance labor while improving batch documentation accuracy.
- Craft beverage proliferation:Small-scale producers in Germany and the United States lack in-house analytical expertise. Portable electrochemical testers fill capability gaps without dedicated laboratory infrastructure.
- Near-infrared spectroscopy maturation:Non-destructive flavor profiling enables inline quality assurance. Breweries integrate these sensors directly into fermentation monitoring loops.
Market Restraints
- Optical component supply concentration:German and Japanese photonics suppliers control grating and detector manufacturing. Disruptions propagate through spectroscopy instrument lead times.
- Calibration reagent cost volatility:Certified reference materials for alcohol content and sugar density verification fluctuate with specialty chemical feedstock prices.
- Electrochemical sensor drift limitations:Manual testers require frequent recalibration in high-humidity brewery environments. Labor overhead erodes unit economics for cost-sensitive buyers.
Strategic Opportunities
- China's GB food contact material standards:Import certification complexity creates demand for pre-validated instrument platforms. Vendors bundling compliance documentation capture premium positioning.
- Subscription-based sensor-as-a-service models:Regional distributors in Southeast Asia replace capital sales with recurring revenue arrangements. Brewery cash flow constraints favor operational expenditure structures.
- Artificial intelligence and chromatography convergence:Machine learning pattern recognition accelerates contaminant identification. Research institutions and large contract manufacturers pilot these integrated workflows.
Industry Challenges
- Spectroscopy technician scarcity:Interpretation of complex spectral data requires specialized training. Smaller producers rely on vendor support contracts rather than in-house expertise.
- LIMS integration complexity:Legacy brewery management software lacks standardized data exchange protocols. Custom middleware development extends deployment timelines and inflates project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Tester Market |
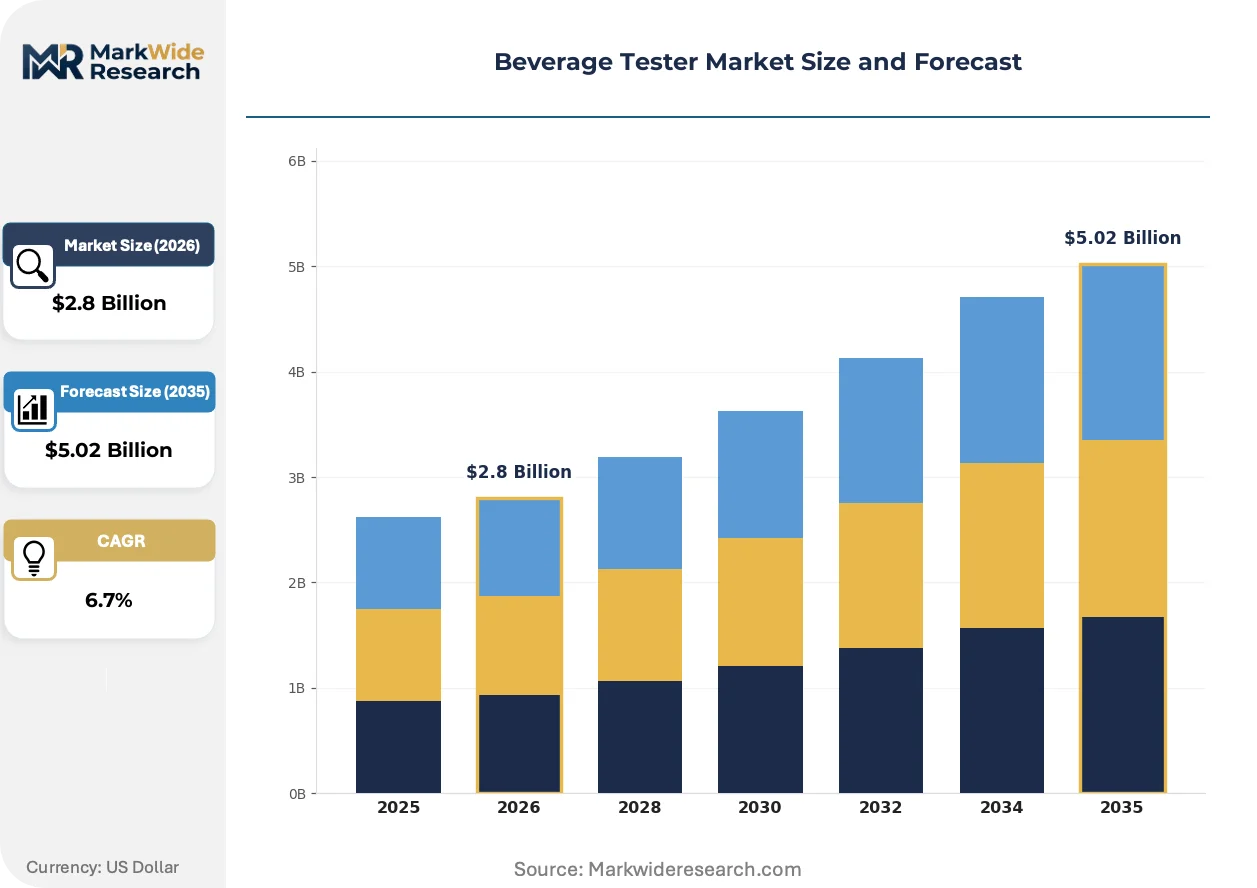
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Tester, Benchtop Tester, Automatic Tester, Manual Tester Technology: Spectroscopy, Chromatography, Electrochemical, Optical End User: Food and Beverage, Research Institutions, Quality Control Labs, Contract Manufacturers Application: Flavor Analysis, Quality Assurance, Chemical Composition, Nutritional Testing |
| Companies Covered | PCS Instruments, Lee Hung Scientific Pte Ltd, Thermo Fisher Scientific, Fisher Scientific Company, VWR, NuAire, Selectech, Q-LAB, Steinfurth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Tester Market Emerging Trajectories
Raman spectroscopy miniaturization is collapsing the boundary between laboratory-grade precision and production-floor accessibility. This convergence enables real-time quality decisions without sample preparation delays or dedicated analytical staff.
Handheld Raman units are consolidating quality control workflows across mid-sized breweries and distilleries. These devices match benchtop accuracy for ethanol and sugar quantification while operating through glass and plastic packaging. Adoption accelerates among craft producers in Colorado and Bavaria seeking to reduce third-party testing dependence. The technology is consolidating multiple analytical steps into single-operator protocols, compressing both capital expenditure and per-test labor costs.
REACH compliance deadlines in Europe are forcing sensor material substitutions across electrochemical and optical instrument lines. Manufacturers reformulate electrode coatings and housing polymers to eliminate restricted substances while maintaining analytical performance. German and Dutch instrument vendors face compressed redesign cycles as 2025 registration evaluation deadlines approach. Supply chain documentation requirements now extend to subcomponent tier-three suppliers, reshaping procurement qualification processes.
Direct purchasing from instrument manufacturers is eroding traditional distribution margins in North American quality control segments. Large brewery groups and beverage conglomerates negotiate enterprise pricing through dedicated account teams, bypassing regional distributors entirely. This disintermediation concentrates volume with vendors maintaining specialized beverage industry application support. The shift is most pronounced among multi-facility operators in California and Wisconsin seeking standardized instrument fleets with centralized calibration management.
Beverage Tester Market Segmentation
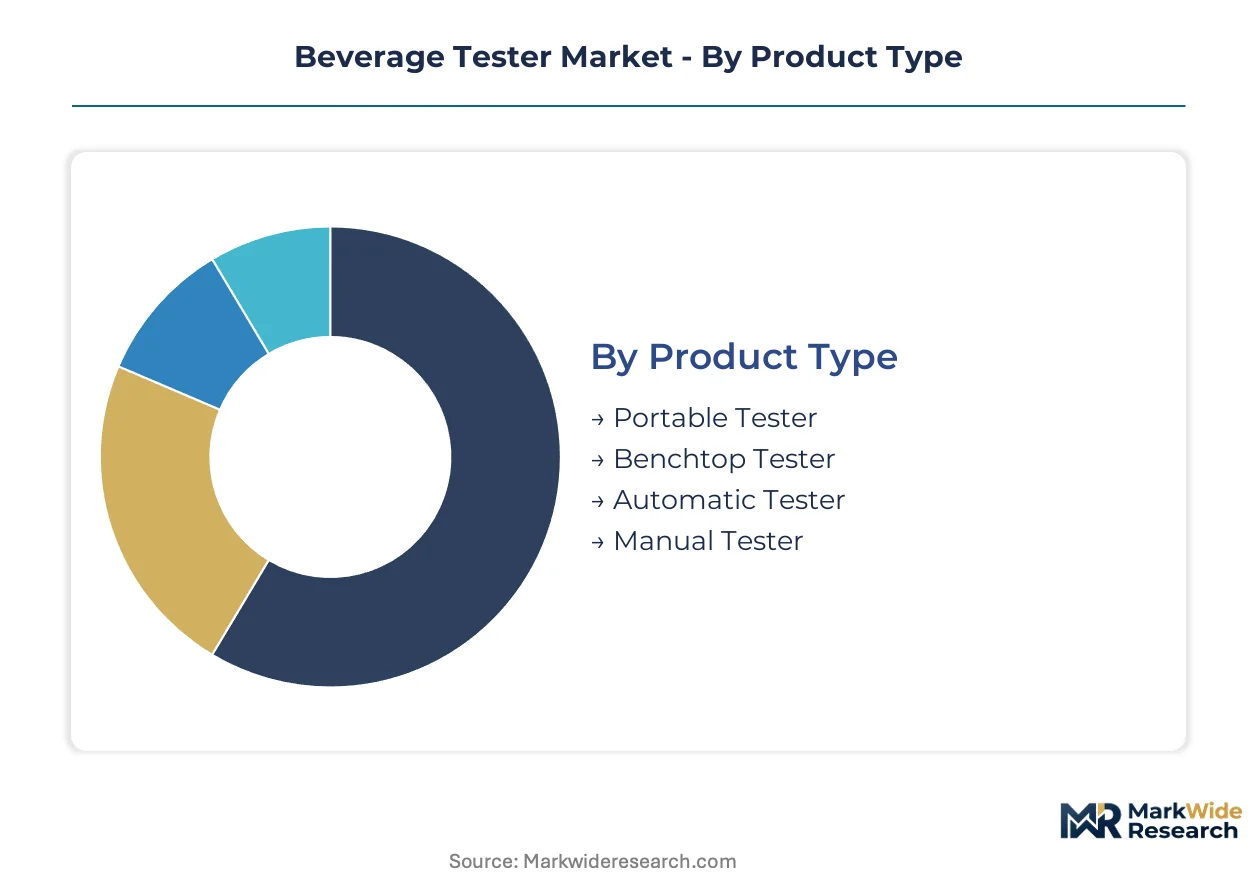
Beverage tester segmentation reveals distinct procurement patterns across instrument mobility, detection physics, and operational workflow integration. Understanding these axes enables vendors to align R&D investment with buyer capability gaps and compliance documentation requirements.
Product Type:
Mobility specifications determine deployment location, capital intensity, and operator skill requirements across brewery quality control networks.
- Portable Tester:Battery-operated units with electrochemical or optical sensors enable floor-level testing without sample transport delays. Colorado craft breweries and Bavarian mid-size producers deploy these for real-time fermentation monitoring where laboratory infrastructure is absent.
- Automatic Tester:LIMS-integrated systems with unattended batch processing capture premium positioning through documentation automation. Large contract manufacturers in Germany and the United States specify these for EFSA and FDA compliance audit trails.
- Benchtop Tester:Modular configurations balance analytical precision with space constraints in distributed production facilities.
- Manual Tester:Entry-level electrochemical devices serve cost-sensitive segments with basic alcohol and pH verification needs.
Portable testers lead on scale; automatic testers lead on momentum.
Technology:
Detection physics selection depends on target analyte complexity, sample matrix interference, and required sensitivity thresholds.
- Spectroscopy:Near-infrared and Raman methods enable non-destructive flavor profiling with ppm-level sensitivity. Research institutions in Germany and quality control labs in California prioritize these for rapid ethanol and sugar quantification without chromatography run times.
- Electrochemical:Potentiometric and amperometric sensors deliver cost-effective measurement of pH, dissolved oxygen, and conductivity. Manual brewery floor applications in tropical supply chains favor these for humidity tolerance and minimal maintenance protocols.
- Chromatography:Gas and liquid chromatography systems anchor high-throughput contract manufacturing for contaminant identification at trace concentrations.
- Optical:Refractometry and photometry methods serve rapid density and color assessment in inline process control loops.
Spectroscopy dominates research procurement; electrochemical devices expand most quickly in craft beverage segments.
End User:
Buyer sophistication and compliance exposure shape instrument specification, validation documentation, and service contract requirements.
- Food and Beverage:Breweries, distilleries, and soft drink manufacturers require floor-deployable quality control with batch traceability. German producers under tightening EFSA additive labeling protocols drive demand for automated documentation capabilities.
- Contract Manufacturers:Multi-brand production facilities need standardized instrument fleets with centralized calibration management across distributed sites.
- Quality Control Labs:Third-party testing services prioritize high-throughput chromatography and spectroscopy for multi-client analytical portfolios.
- Research Institutions:Universities and government laboratories specify cutting-edge detection methods for flavor chemistry and safety research.
Food and beverage producers anchor volume; contract manufacturers gain share fastest.
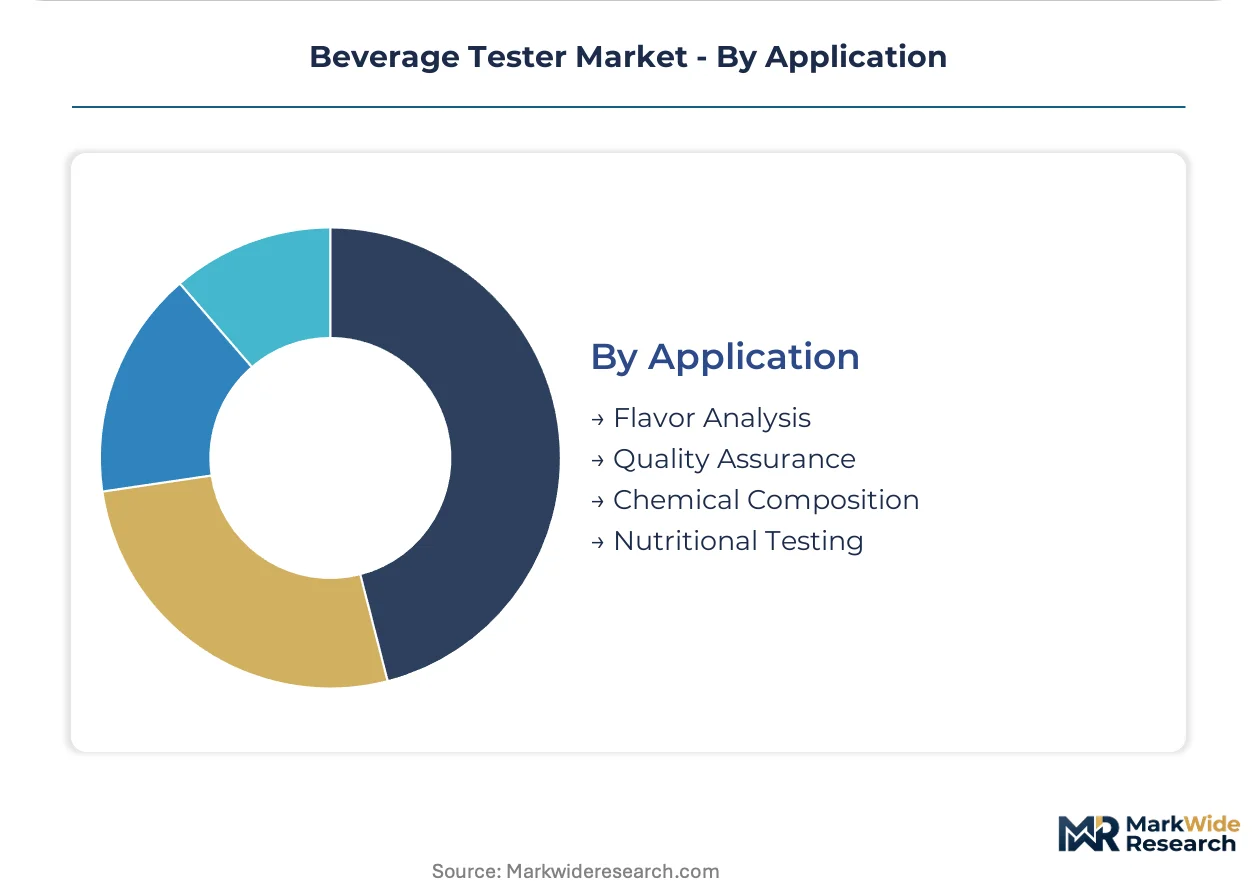
Application:
Analytical purpose determines sensor configuration, data output format, and integration depth with production management systems.
- Flavor Analysis:Spectroscopic and chromatographic methods quantify volatile compounds, ester profiles, and off-flavor precursors. Bavarian and Colorado craft producers deploy handheld Raman units to reduce third-party sensory panel dependence.
- Chemical Composition:Alcohol content, sugar density, and additive verification require certified reference materials and traceable calibration chains under REACH and FDA protocols.
- Quality Assurance:Inline monitoring loops integrate near-infrared sensors for real-time fermentation trajectory adjustment.
- Nutritional Testing:Label claim verification for calories, carbohydrates, and specific gravity supports consumer transparency mandates.
Flavor analysis commands premium pricing; chemical composition testing shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale brewing quality control in the 19th century, establishing analytical standards that still shape instrument specifications across the sector. The Beverage Tester Market now distributes across five concentrated national production hubs, each shaped by distinct regulatory pressures and beverage industry clustering.
Germany
Bavarian craft breweries and North Rhine-Westphalia contract manufacturers drive automated spectroscopy procurement under tightening EFSA additive labeling protocols. REACH compliance deadlines through 2025 force sensor material substitutions across electrochemical instrument lines. Munich and Hamburg anchor quality control lab networks serving multi-brand production facilities with centralized calibration management.
United States
Colorado and California craft beverage clusters deploy handheld Raman units for real-time fermentation monitoring without laboratory infrastructure. The FDA's Food Safety Modernization Act mandates batch documentation capabilities that favor LIMS-integrated automatic testers. Wisconsin multi-facility operators negotiate enterprise pricing directly with manufacturers, bypassing traditional distribution channels.
China
GB standards for food contact materials restrict sensor materials and calibration reagent compositions across imported instrument platforms. Yangtze River Delta contract manufacturers seek pre-validated systems bundling compliance documentation for reduced certification complexity. Shanghai quality control labs pilot artificial intelligence convergence with chromatography for accelerated contaminant identification.
Japan
Precise optical component manufacturing concentrates in German and Japanese photonics suppliers, with METI-supported R&D advancing grating and detector miniaturization. Tokyo and Osaka research institutions specify cutting-edge detection methods for flavor chemistry investigation. Domestic instrument vendors face compressed redesign cycles as REACH-equivalent material restrictions expand through supply chain documentation requirements.
United Kingdom
London and Southeast England quality control services prioritize high-throughput chromatography for multi-client analytical portfolios serving beverage importers. Post-Brexit regulatory divergence from EFSA protocols creates dual validation requirements for instruments serving both UK and EU markets. Midlands craft distilleries adopt portable electrochemical testers to reduce third-party laboratory dependence.
Beverage Tester Market Vendor Landscape
The competitive structure tilts toward diversified laboratory conglomerates with chromatography and spectroscopy portfolios. Thermo Fisher Scientific leverages analytical instrument breadth to anchor high-throughput contract manufacturing accounts, while VWR controls distribution density across North American quality control labs through same-day fulfillment networks. Three strategic archetypes dominate: chromatography-specialized conglomerates, portable spectroscopy regionalists, and distribution-integrated service providers. Competitive moves concentrate on direct enterprise sales bypassing traditional channels and subscription-based sensor-as-a-service models replacing capital expenditure structures.
Among diversified analytical conglomerates, Thermo Fisher Scientific occupies the premium-tier position through chromatography portfolio breadth. Lee Hung Scientific Pte Ltd exemplifies the portable spectroscopy regionalist archetype with units calibrated for tropical supply chain humidity tolerance. VWR represents the distribution-integrated model, controlling fulfillment density across North American laboratory networks. These three anchors illustrate how vendor strategies diverge between technology specialization, geographic adaptation, and service infrastructure investment.
| Leading Market Players |
|---|
| PCS Instruments |
| Lee Hung Scientific Pte Ltd |
| Thermo Fisher Scientific |
| Fisher Scientific Company |
| VWR |
| NuAire |
| Selectech |
| Q-LAB |
| Steinfurth |
| Others |
Supply Flow & Price Mechanics
REACH registration deadlines in Europe gate qualified supply access for electrochemical and optical instrument lines, with compliant sensor materials commanding premium-tier pricing while non-compliant inventory faces forced markdowns. Breweries under tightening EFSA additive labeling protocols pay documentation premiums for pre-validated platforms, compressing margins for vendors lacking certified calibration chains.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates LIMS-integrated automatic testers from modular benchtop units and entry-level manual devices. Price differentiation hinges on certification grade under FDA Food Safety Modernization Act and EFSA protocols, alongside after-sales service bundling for calibration management. Cost compression in the economy tier is intensifying because electrochemical sensor drift forces frequent recalibration labor. Craft breweries in Colorado and Bavaria show highest price sensitivity, while German contract manufacturers demonstrate lowest sensitivity due to compliance audit trail requirements.
Supply Chain Analysis
Photonics component supply rests on German and Japanese specialty manufacturers controlling grating and detector fabrication for spectroscopy instruments. Optical sensors draw from precision glass foundries in Schott, Germany, and Hamamatsu, Japan, while electrochemical electrodes source from platinum group metal processors in South Africa and Russia. Single-source vulnerability concentrates in diffractive optics fabrication, where three suppliers serve the global analytical instrument base. Distribution runs through VWR's same-day fulfillment networks across North American quality control labs, supplemented by direct manufacturer sales for enterprise brewery accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: German producers face compressed redesign cycles under REACH deadlines while Southeast Asian distributors capture recurring revenue through sensor-as-a-service models unburdened by capital expenditure constraints.
For Market Incumbents: Extend chromatography portfolio dominance into AI-integrated contaminant identification workflows before machine learning pattern recognition commoditizes spectral interpretation. Backward integration into certified reference material production insulates against specialty chemical feedstock volatility threatening calibration reagent margins. Thermo Fisher Scientific's anchor position in high-throughput contract manufacturing accounts demonstrates the defensive value of application-specific support infrastructure. For New Entrants and Emerging Players: Handheld Raman miniaturization offers technology-first wedge into mid-sized Bavarian and Colorado craft breweries seeking to eliminate third-party sensory panel dependence. Target white-space in tropical supply chain calibration services, where humidity-tolerant portable spectroscopy units face minimal incumbent competition. Lee Hung Scientific's regionalist model demonstrates viable go-to-market through distributor partnerships bundling compliance documentation for China's GB standards complexity. For Investors and Strategic Acquirers: Valuations sit cheapest among distribution-integrated service providers lacking proprietary detection physics, as direct manufacturer sales erode traditional margin capture. Long-term viability over the coming decade favors vendors with sensor-as-a-service recurring revenue structures replacing capital sales cyclicality. Watch for inflection when AI-chromatography convergence pilots at Shanghai quality control labs achieve production-scale deployment, signaling technology obsolescence risk for non-integrated instrument vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-as-a-Service Transition | Recurring revenue structures align with brewery cash flow constraints in Southeast Asia. |
| REACH-Compliant Material Redesign | German and Dutch vendors face compressed cycles eliminating restricted electrode coatings. |
| AI-Chromatography Integration | Machine learning pattern recognition accelerates contaminant identification for contract manufacturers. |
| Direct Enterprise Sales Expansion | Wisconsin multi-facility operators bypass distributors for standardized instrument fleet pricing. |
| Portable Raman Miniaturization | Handheld units consolidate quality control workflows across Colorado craft beverage clusters. |
Methodological Framework
Bottom-up brewery and contract manufacturer modeling reconciled against top-down spectroscopy and chromatography instrument shipment tracking forms the analytical core. Primary interviews with quality control lab directors, brewery operations managers, regulatory affairs specialists at EFSA-aligned producers, and instrument vendor application engineers combined with secondary validation from FDA Food Safety Modernization Act guidance documents, EFSA additive labeling protocols, REACH registration databases, and customs trade records for analytical instrument categories.
Historical trendline analysis of portable versus automatic tester deployment patterns across German, United States, and China production hubs established baseline growth trajectories. Segmentation dimensions modeled include instrument mobility specifications, detection physics categories, end-user sophistication tiers, and application purpose across flavor analysis and chemical composition verification. CAGRs were derived from shipment volume reconciliations against capital expenditure disclosures in beverage producer filings, with near-infrared spectroscopy maturation curves and electrochemical sensor replacement cycles as industry-specific forecast inputs.
The model holds under stable regulatory harmonization between EFSA and FDA protocols; deviation in REACH-equivalent material restrictions expanding through Asian supply chains would shift component sourcing economics. Forecasts reflect documented assumptions regarding brewery quality control budget expansion and craft beverage proliferation rates. A small set of named triggers warrants ongoing watch: optical component supply disruptions, calibration reagent feedstock volatility, and AI-chromatography convergence adoption velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Food Pathogen Testing Market
Food Safety Testing
Food Authentication Testing Market
Food Safety Testing
Salmonella Testing Market
Food Safety Testing
Global Food Authenticity Testing Market
Food Safety Testing
Global Meat Speciation Testing Market
Food Safety Testing
Testing, Inspection, and Certification in Consumer Goods and Retail Market
Food Safety Testing
Screening Equipment Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Gum Content Tester Market
Food Safety Testing
Salt Meter Market
Food Safety Testing
Bottled Water Testing Equipment Market
Food Safety Testing
Fruit & Vegetable Wash Market
Food Safety Testing
Food Testing Services Market
Food Safety Testing
Europe Food Safety Testing Market
Food Safety Testing
Meat Testing Market
Food Safety Testing
Food Testing Kits Market