
 Airport Terminal Operations Market | 2026-2036
Airport Terminal Operations Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Terminal Operations Market Intelligence
Level 3 biometric integration is reorganizing competitive dynamics across terminal operations. Fraport AG leverages its integrated hub management platforms to sustain throughput leadership at Frankfurt. Aeroports de Paris anchors its position through automated baggage system specialization at Charles de Gaulle. The Port Authority Of New York & New Jersey competes on multi-terminal scale across its metropolitan network.
Airport terminal operations encompass the coordinated management of passenger flow, baggage handling, security screening, and gate resource allocation within commercial aviation facilities, typically requiring systems capable of processing thousands of transactions per hour with sub-minute response times. The primary purpose is to maximize aircraft turnaround efficiency while maintaining regulatory compliance and passenger safety standards. Ground handling and automated baggage systems represent the most capital-intensive technology segments, where margin pools concentrate in integrated system providers rather than point solution vendors. Self-check-in kiosks and digital signage are expanding fastest among technology deployments, driven by labor cost pressures and passenger preference for contactless processing.
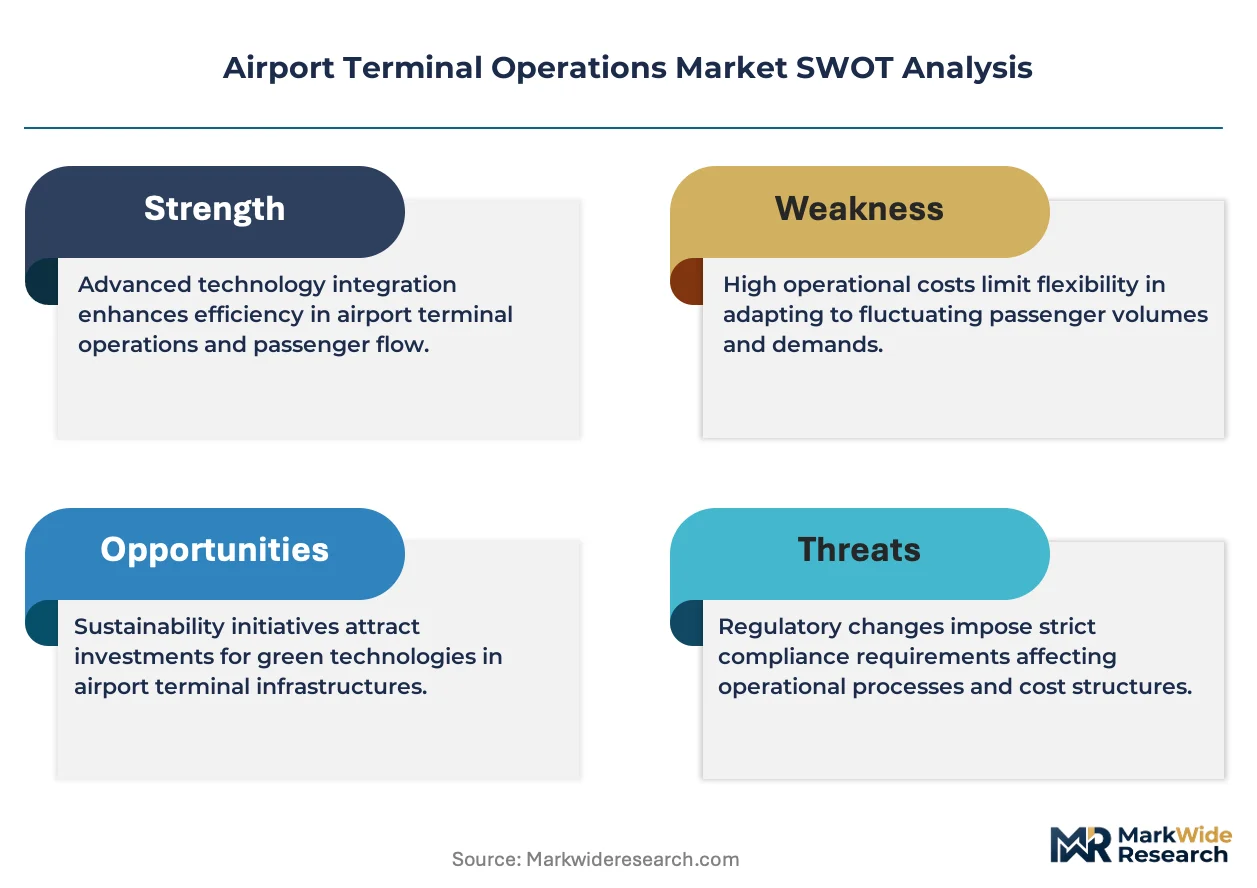
FAA NextGen mandates and EU Green Deal airport sustainability requirements are tightening operational standards for emissions reporting and energy efficiency, directly shaping procurement criteria for terminal infrastructure upgrades. TSA checkpoint technology directives and EASA security compliance frameworks are accelerating replacement cycles for screening equipment across major hubs. Stakeholders must monitor how biometric interoperability standards evolve to determine whether platform consolidation or modular best-of-breed strategies offer superior capital efficiency.
Market Dynamics
Biometric passenger processing systems are compressing operational timelines across major hub terminals. FAA NextGen mandates and EU Green Deal sustainability requirements are simultaneously forcing capital reallocation toward energy-efficient infrastructure while tightening emissions reporting standards.
Growth Catalysts
- FAA NextGen Mandates:The Federal Aviation Administration's modernization directives require terminal operators to upgrade surveillance and data-sharing infrastructure. Major US hubs are accelerating technology replacement cycles to maintain operational certification.
- Automated Baggage Handling:Labor cost pressures and throughput demands are driving adoption of robotic sorting systems. Integrated system providers are capturing margin pools previously fragmented across point solution vendors.
- EU Green Deal Airport Sustainability Framework:European terminal operators face binding energy efficiency targets and emissions disclosure requirements. Capital allocation is shifting decisively toward low-carbon infrastructure upgrades.
Market Restraints
- Integrated System Capex Concentration:Ground handling and automated baggage systems require substantial upfront investment. Point solution vendors struggle to compete against platform providers with captive financing capabilities.
- Biometric Interoperability Friction:Fragmented standards across national border control agencies create integration complexity. Terminal operators face stranded asset risk if dominant protocols shift post-deployment.
- Legacy Infrastructure Lock-in:Existing screening equipment and passenger processing hardware operates on decade-long depreciation cycles. Accelerated replacement timelines strain capital planning frameworks.
Strategic Opportunities
- Contactless Processing Convergence:Self-check-in kiosks and mobile credential verification are merging into unified passenger flow platforms. Early movers in biometric-mobile integration are securing long-term service contracts.
- Energy Retrofit Incentive Stacking:The Inflation Reduction Act and EU Green Deal create overlapping subsidy pools for terminal electrification. Operators combining heat pump HVAC with solar microgrids access accelerated depreciation schedules.
- India Airport Privatization Wave:The Airports Authority of India is transferring brownfield assets to private operators under long-term concession agreements. Greenfield terminal construction is incorporating automated systems from initial design phases.
Industry Challenges
- Cyber-Physical System Integration:Converging operational technology and information technology networks expose terminal operators to ransomware targeting baggage handling and access control systems. Segmentation between legacy SCADA and modern cloud platforms remains incomplete.
- Biometric Data Governance:GDPR in Europe and emerging state-level privacy statutes in the United States impose conflicting retention and consent requirements. Terminal operators face compliance cost multiplication when serving international passenger flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Terminal Operations Market |
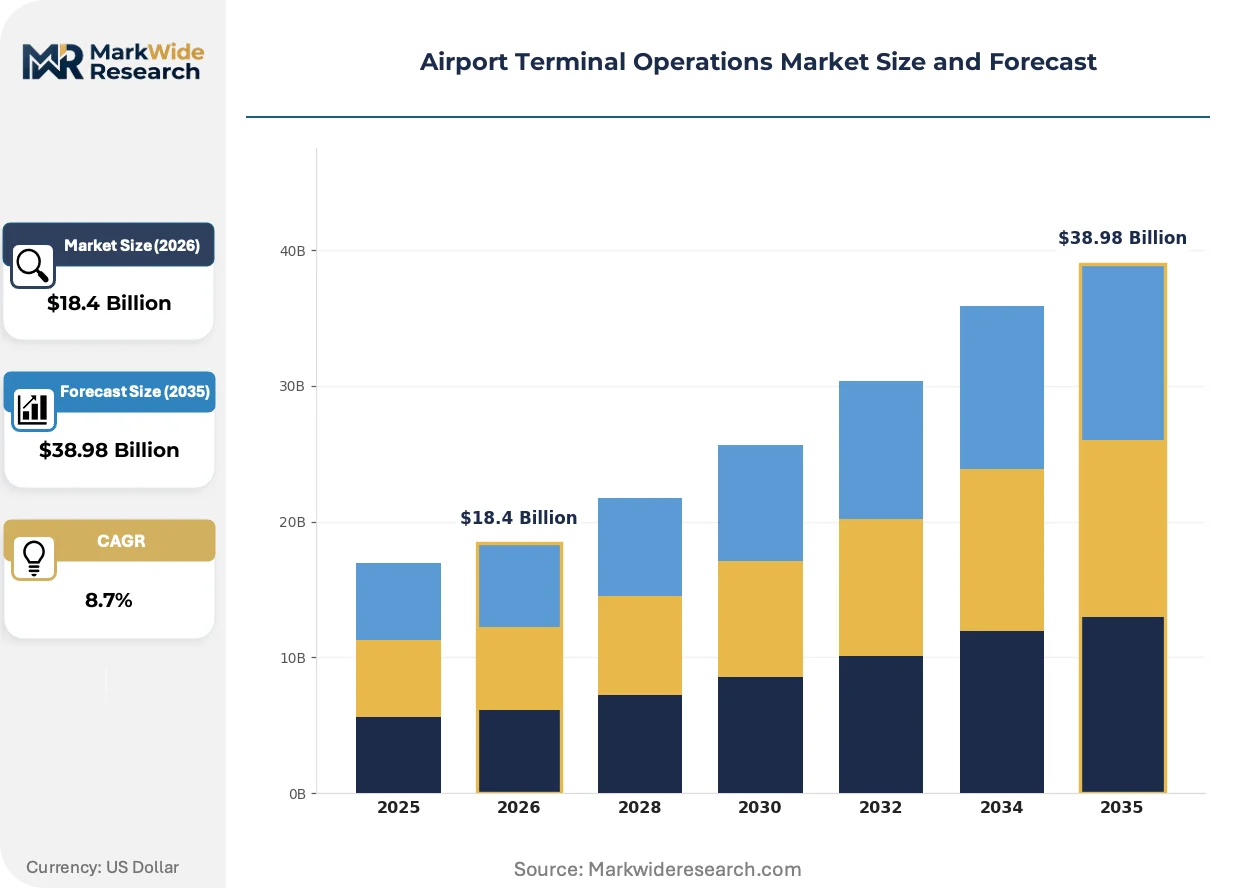
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ground Handling, Baggage Management, Passenger Services, Security Services Technology: Self-Check-In Kiosks, Automated Baggage Systems, Security Screening Equipment, Digital Signage End User: Airlines, Airport Authorities, Ground Handlers, Security Providers Application: Operational Efficiency, Customer Experience, Security Compliance, Resource Management |
| Companies Covered | Fraport AG, SkyCity Airports, The Port Authority Of New York & New Jersey, Grupo Aeroportuario del Pacifico, Corporacion America Airports, Airports Council International, Aena SME, Grupo Aeroportuario del Sureste, Aeroports de Paris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Terminal Operations Market Strategic Shifts & Innovations
Terminal operations technology is fragmenting from monolithic platforms into modular, API-connected components. This architectural shift enables faster deployment cycles while complicating vendor consolidation strategies.
Computer vision-based passenger tracking is decomposing traditional queue management into dynamic, zone-optimized flow control. Dubai International Airport and Singapore Changi are deploying edge-computing cameras that feed real-time occupancy data to gate assignment algorithms. The technology is decomposing fixed check-in counter configurations into flexible, multi-use processing zones that adapt to daily demand patterns.
The EU AI Act's risk classification framework is imposing conformity assessment requirements on automated border control gates. Terminal operators deploying biometric matching systems must now document algorithmic bias testing and human oversight protocols. European hubs are responding by segregating AI-enabled lanes from legacy manual processing to maintain operational continuity during certification delays.
Airport authorities are unbundling long-term operations and maintenance contracts from initial system procurement. Middle Eastern and Southeast Asian greenfield projects are piloting performance-based agreements where vendors retain equipment ownership and charge per-passenger processed. This model is most visible in Saudi Arabia's King Salman International Airport development, where consortium structures align vendor incentives with throughput targets rather than capital expenditure milestones.
Airport Terminal Operations Market Segmentation
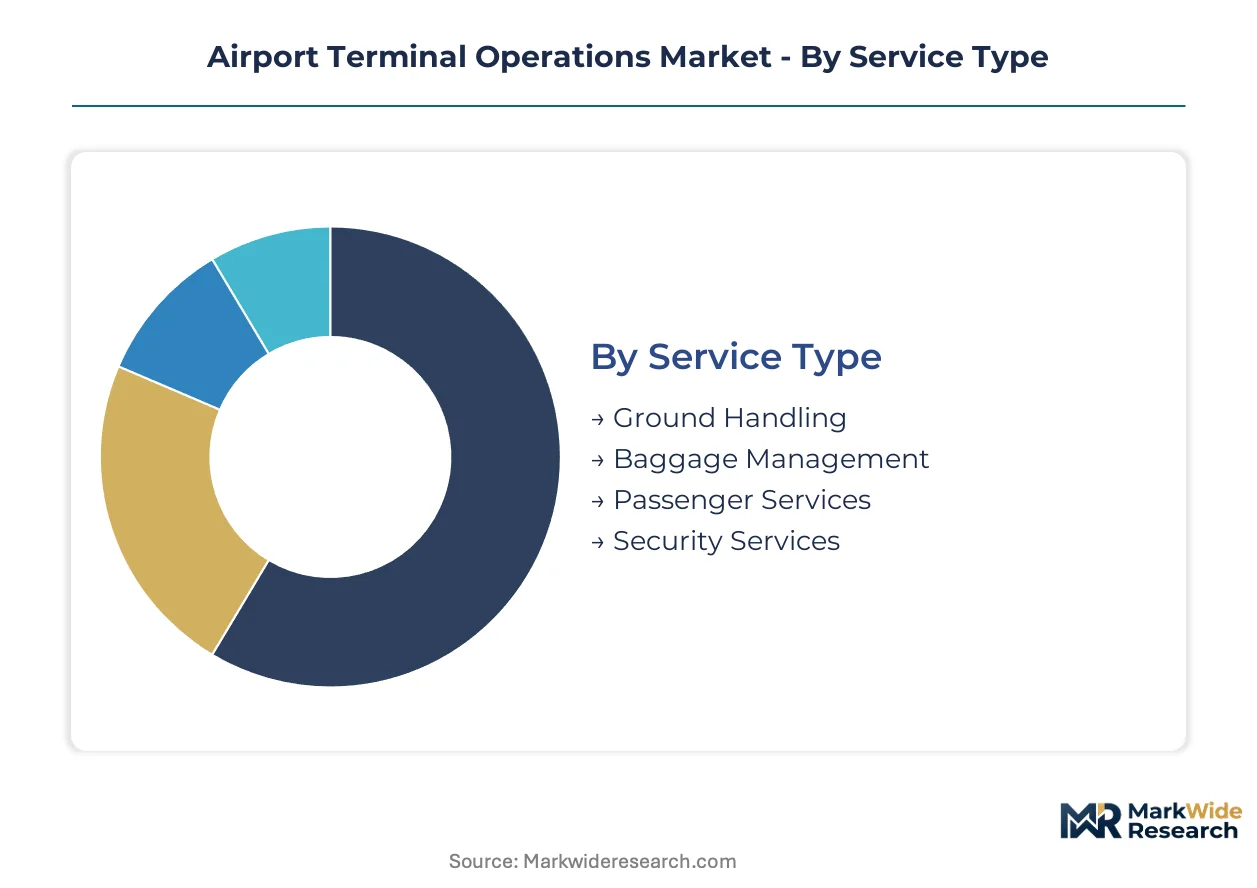
Segmentation in airport terminal operations reveals how capital flows concentrate across service tiers and technology maturity levels. Procurement patterns diverge sharply between legacy infrastructure replacement and greenfield automation deployment.
Service Type:
Ground handling and baggage management face the strongest substitution pressure from autonomous robotics, while passenger-facing services resist automation due to regulatory complexity and customer preference for human assistance during irregular operations.
- Ground Handling:Aircraft marshalling, fueling, and pushback coordination require specialized equipment with high capital intensity. Demand concentrates at Frankfurt, Dubai, and Singapore Changi where hub carriers demand sub-25-minute turnaround windows to maintain connecting bank schedules.
- Baggage Management:Automated sorting systems and RFID tracking infrastructure process thousands of bags per hour through centralized make-up facilities. Investment is accelerating at Charles de Gaulle and Heathrow Terminal 5 as legacy carousel systems reach end-of-life.
- Passenger Services:Check-in counter staffing, wayfinding assistance, and special needs coordination retain substantial labor content despite kiosk proliferation.
- Security Services:Access control perimeter monitoring and document verification operate under TSA and EASA directive compliance frameworks with limited outsourcing flexibility.
Ground handling retains volume leadership; baggage management holds the steepest expansion curve as RFID and robotics displace manual sortation.
Technology:
Technology segments stratify by deployment cost tier, with capital-light digital infrastructure expanding faster than heavy mechanical systems requiring structural terminal modifications.
- Automated Baggage Systems:Tilt-tray sorters and destination-coded vehicles operate on fixed guideways with 20-year depreciation cycles. Procurement clusters at greenfield Middle Eastern airports where Saudi Arabia's King Salman International and Dubai's Al Maktoum International specify fully automated facilities from initial design.
- Self-Check-In Kiosks:CUSS-standard terminals and biometric-enabled units reduce counter staffing requirements while capturing passenger data for airline loyalty programs. Airlines at Atlanta Hartsfield-Jackson and Dallas-Fort Worth are consolidating on common-use platforms to reduce per-gate infrastructure duplication.
- Security Screening Equipment:CT-based cabin baggage scanners and millimeter-wave passenger portals require FAA and EASA certification timelines that extend procurement cycles.
- Digital Signage:Wayfinding displays and flight information systems shift toward cloud-managed LED networks with lower installation cost than mechanical systems.
Self-check-in kiosks dominate deployment volume; automated baggage systems command the highest per-unit investment and longest replacement cycles.
End User:
End user segments map to distinct procurement authority structures, with airport authorities controlling infrastructure capital and airlines driving passenger-facing technology specifications.
- Airport Authorities:Own terminal buildings and common-use infrastructure including baggage systems, security checkpoints, and gate equipment. The Port Authority of New York and New Jersey and Fraport AG allocate capital across multi-terminal networks with coordinated replacement schedules.
- Airlines:Specify passenger service technology at their dedicated facilities and common-use gates. Hub carriers at Atlanta, Dallas-Fort Worth, and Frankfurt negotiate long-term terminal use and improvement agreements that lock in technology refresh commitments.
- Ground Handlers:Contract for apron equipment and aircraft servicing vehicles with shorter procurement cycles than fixed infrastructure.
- Security Providers:Operate under government agency mandates with limited technology selection autonomy.
Airport authorities control infrastructure volume; airlines are expanding fastest in biometric passenger processing investment.
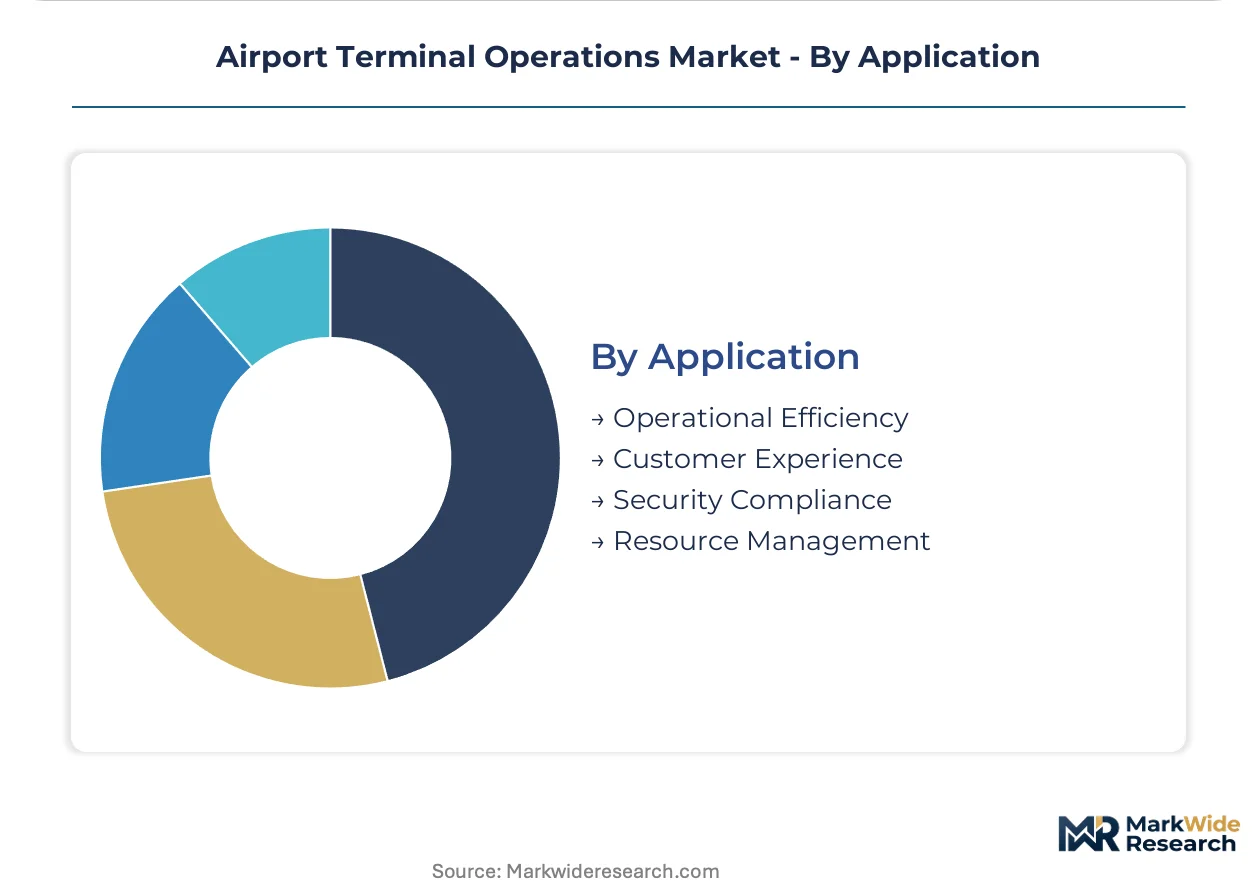
Application:
Application segments align with operational KPI ownership, where efficiency and compliance drive mandatory investment while customer experience spending faces discretionary pressure during revenue downturns.
- Operational Efficiency:Aircraft turnaround time reduction and gate utilization optimization deliver quantifiable cost savings. Dubai International and Singapore Changi deploy computer vision-based passenger tracking to dynamically adjust security lane staffing and gate assignments.
- Security Compliance:TSA checkpoint technology directives and EASA security frameworks mandate equipment replacement regardless of financial performance. US major hubs accelerated CT scanner deployment following congressional funding allocations.
- Customer Experience:Wayfinding, dwell time reduction, and retail exposure optimization compete for capital against hard infrastructure.
- Resource Management:Staff scheduling and equipment allocation systems integrate with airline operational databases.
Security compliance retains mandatory investment priority; operational efficiency is climbing fastest as labor costs and throughput pressure intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States exhibit low price elasticity for biometric integration mandates, while Indian privatization tenders attract cost-sensitive bids from regional system integrators. European operators balance sustainability premiums against regulatory compliance costs.
United States
FAA NextGen mandates drive surveillance infrastructure replacement at Atlanta Hartsfield-Jackson and Dallas-Fort Worth. The Inflation Reduction Act subsidizes terminal electrification retrofits. The Port Authority of New York and New Jersey coordinates multi-terminal modernization across its metropolitan network.
Germany
Frankfurt Airport's hub carrier demands compress turnaround windows below 25 minutes. EU Green Deal binding targets redirect capital toward heat pump HVAC and solar microgrids. Fraport AG deploys integrated hub management platforms across its domestic terminal portfolio.
France
Charles de Gaulle's automated baggage system specialization requires end-of-life carousel replacement. GDPR biometric data governance imposes retention protocol complexity on cross-border passenger flows. Aeroports de Paris anchors capital planning around EASA security compliance frameworks.
India
The Airports Authority of India transfers brownfield assets to private operators under 50-year concessions. Greenfield terminals at Navi Mumbai and Jewar incorporate automated sorting from initial design phases. Maharashtra and Karnataka clusters concentrate procurement authority for metropolitan hub development.
United Arab Emirates
Dubai International deploys computer vision-based passenger tracking for dynamic gate assignment. King Salman International Airport in Saudi Arabia pilots performance-based vendor contracts with per-passenger pricing. Abu Dhabi's mid-field terminal expansion specifies fully automated baggage handling from commissioning.
Airport Terminal Operations Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated platform providers capture margin pools in ground handling and baggage systems through captive financing capabilities. Point solution vendors compete on modular deployment speed and API connectivity. Dominant competitive moves include long-term concession bidding for greenfield airport developments and strategic consolidation of operations-maintenance contracts under performance-based pricing models.
Within the integrated hub management tier, Fraport AG and Aeroports de Paris exemplify operator-archetype competitors that combine terminal ownership with in-house technology deployment. The Port Authority of New York & New Jersey occupies a distinctive position as a multi-jurisdictional public authority coordinating capital allocation across geographically dispersed assets. These entities represent how scale and regulatory relationships shape competitive positioning in developed aviation markets.
| Leading Market Players |
|---|
| Fraport AG |
| SkyCity Airports |
| The Port Authority Of New York & New Jersey |
| Grupo Aeroportuario del Pacifico |
| Corporacion America Airports |
| Airports Council International |
| Aena SME |
| Grupo Aeroportuario del Sureste |
| Aeroports de Paris |
| Others |
Cost & Logistics Intelligence
Performance-based operations and maintenance contracts with per-passenger pricing lock in multi-year supply access for integrated system providers while anchoring price visibility across Frankfurt, Dubai, and Singapore Changi. The EU Green Deal's binding energy efficiency targets and FAA NextGen mandates compress procurement timelines, forcing airport authorities to accept premium positioning for vendors with captive financing capabilities and certified compliance frameworks.
Pricing Analysis
FAA NextGen mandates and EU Green Deal airport sustainability requirements dictate the pricing tier structure across terminal infrastructure procurement. Three-tier pricing stratifies across premium certified platforms, standard integrated systems, and economy point solutions, with differentiation anchored in EASA compliance tier and biometric interoperability certification. Cost compression in the standard tier intensifies as Indian privatization tenders attract aggressive bids from regional system integrators. Ground handlers exhibit the highest price sensitivity due to shorter equipment depreciation cycles, while airport authorities at major US hubs demonstrate low elasticity for biometric integration mandates.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints at Shanghai and Rotterdam elevate inbound logistics costs for automated baggage system components. Manufacturing concentration clusters in Germany, Japan, and the United States for precision sorting equipment and millimeter-wave screening hardware. Supply chains draw from specialized steel alloys, high-resolution sensor arrays, and edge-computing chipsets. Single-source vulnerability persists for EU-certified biometric matching algorithms. Distribution runs through authorized system integrators with direct airport authority relationships rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airport terminal operations sit in early-cycle expansion as Level 3 biometric integration penetrates below twenty percent of major hub capacity, creating runway for platform consolidation before standardization locks in vendor positions.
For Market Incumbents: Fortify hub management platform positions through backward integration into predictive maintenance software and edge-computing infrastructure. The threat of modular API-connected challengers eroding margin pools demands certification investment in EU AI Act conformity assessment protocols. Capacity addition in Saudi Arabia's King Salman International and India's Navi Mumbai greenfield clusters secures long-term service contract anchoring. For New Entrants and Emerging Players: Lead with biometric-mobile integration modules for the India airport privatization wave, where brownfield asset transfers under 50-year concessions create immediate retrofit demand. The most penetrable white-space sits in contactless processing convergence for secondary US hubs below FAA NextGen mandate priority tiers. A go-to-market angle anchored in GDPR-compliant data governance tooling addresses European operator compliance cost multiplication. For Investors and Strategic Acquirers: Capital is best deployed toward integrated platform providers with captive financing capabilities and multi-terminal scale across metropolitan networks. Long-term viability over a five-to-ten year window favors vendors positioned for performance-based contract expansion in Middle Eastern greenfield developments. The signal to watch is biometric interoperability standard convergence between TSA and EASA frameworks as an inflection indicator for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Platform Integration | Unifies passenger flow data across TSA checkpoints and airline loyalty systems at Atlanta Hartsfield-Jackson. |
| Performance-Based Operations Contract | Aligns vendor incentives with throughput targets at Saudi Arabia's King Salman International Airport development. |
| Energy Retrofit Incentive Stacking | Combines Inflation Reduction Act subsidies with EU Green Deal accelerated depreciation for terminal electrification. |
| Greenfield Automation Deployment | Incorporates fully automated baggage handling from initial design phases at India's Navi Mumbai and Jewar terminals. |
| Regulatory Certification Investment | Secures EU AI Act conformity assessment for automated border control gates at Charles de Gaulle. |
Research Approach
Initial hypotheses were tested against primary input from airport operations executives, biometric system procurement leads, ground handling contract managers, and regulatory compliance officers at major hubs, and refined through secondary validation against FAA NextGen implementation timelines, EU Green Deal airport sustainability filings, TSA checkpoint technology directive updates, EASA security framework amendments, and airport authority capital expenditure disclosures. Bottom-up segment sizing triangulated with top-down market reconstruction across service type, technology, end user, and application dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each modeled segment. The analytical framework incorporates deployment model, terminal scale tier, regulatory compliance cluster, and regional privatization status as core segmentation dimensions. CAGRs were derived from fitted adoption curves for biometric integration and energy retrofit penetration, with cross-validation against historical replacement cycles for screening equipment and baggage handling infrastructure.
Forecasts assume regulatory continuity in FAA NextGen mandates, EU Green Deal airport sustainability frameworks, and EASA security compliance requirements; material policy shifts in biometric data governance or emissions reporting standards would require re-modeling. Specific risk factors include stranded asset exposure from protocol fragmentation in biometric interoperability and accelerated depreciation timeline changes in US and European subsidy programs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
South Korea Airport Operations Market
Airport Operations
Europe Airport Operations Market
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
Global Air Charter Services Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Aircraft Ground Handling System Market
Airport Operations
UK Airport Operations Market
Airport Operations
Airport Operations Market
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
Global Airside Services Market
Airport Operations
Canada Airport Operations Market
Airport Operations
Middle East Airport Operations Market
Airport Operations
Business Jet Ground Handling Services Market
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
France Airport Operations Market