
 Business Jet Ground Handling Services Market | 2026-2036
Business Jet Ground Handling Services Market Size, Share, and Industry Trends Forecast 2026-2036
Business Jet Ground Handling Services Market Outlook
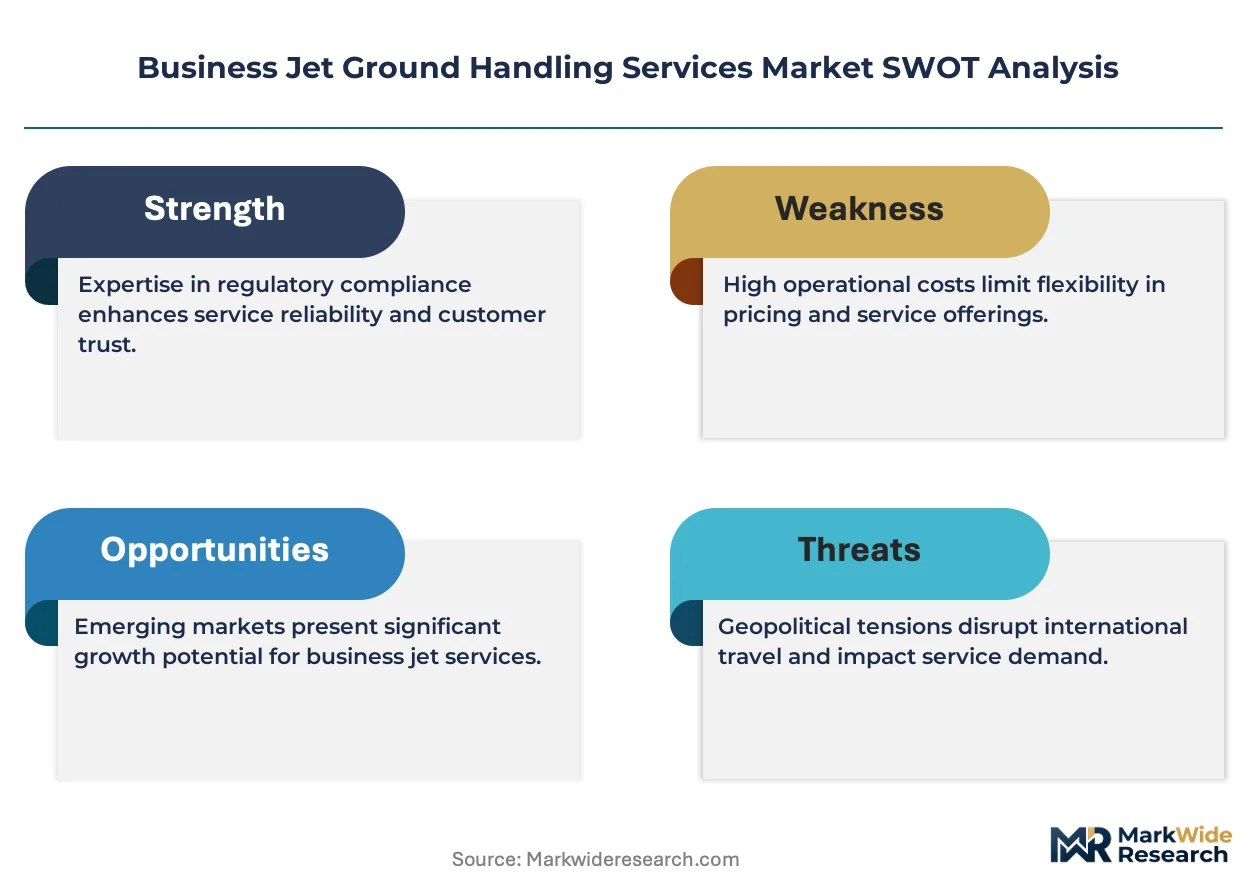
A capital-intensity divergence between full-service fixed-base operators and regional handlers is unwinding competitive stability in business jet ground handling. Signature Aviation leverages its North American hangar network to sustain premium pricing on ultra-long-range turnarounds. Jet Aviation anchors European capacity through Geneva and Zurich infrastructure dominance. dnata competes aggressively across Middle Eastern hubs where government-backed airport expansion accelerates slot allocation for private aviation.
Business jet ground handling services encompass the coordinated aircraft support activities performed between landing and departure, including fueling, catering provisioning, passenger embarkation, baggage transfer, and lavatory servicing under tight turnaround windows typically ranging from thirty to ninety minutes. These services ensure operational continuity for non-scheduled private and corporate aviation where delay costs exceed commercial airline thresholds by an order of magnitude. Passenger services and refueling together command the largest margin pools within the service type dimension, while on-demand frequency arrangements are expanding fastest among charter operators seeking variable-cost structures. Heavy jets and ultra-long-range jets drive disproportionate revenue per movement due to complex catering requirements and extended fueling protocols.
FAA oversight through Part 139 airport certification and EASA's ground handling regulations shape equipment standards and training mandates across the United States and European Union respectively, while ICAO Annex 14 provisions influence safety minimums in non-binding jurisdictions. Environmental regulators including the EPA and EU ETS administrators are pressuring operators to adopt electric ground support equipment and sustainable aviation fuel integration, altering capital deployment priorities. Stakeholders must monitor evolving carbon border adjustments and local noise abatement ordinances that threaten to fragment operational compliance across key destination airports.
Market Dynamics
Ultra-long-range jet fleet expansion is compressing turnaround windows at premium hubs, forcing ground handlers to reconfigure apron workflows and recertify personnel for simultaneous multi-point servicing operations under tighter FAA Part 139 and EASA safety mandates.
Growth Catalysts
- FAA Part 139 Certification Expansion:Airport infrastructure upgrades across the United States are mandating higher-grade firefighting equipment and enhanced runway safety areas, driving contracted ground handling capability investments.
- Sustainable Aviation Fuel Mandates:EU ETS administrators and EPA pressure are requiring SAF-compatible fueling systems at major business aviation terminals, accelerating equipment replacement cycles.
- Intercontinental Charter Density:Dubai and Abu Dhabi super-connector traffic is generating 90-minute turnarounds for ultra-long-range jets, pulling premium service packages into Middle Eastern hub economics.
Market Restraints
- Electric GSE Capital Requirements:Battery-powered ground support equipment carries 40-60% higher upfront costs than diesel equivalents, straining regional handler balance sheets.
- Specialized Technician Scarcity:FAA-certified fuel system operators and EASA-compliant load controllers concentrate in legacy aviation markets, leaving emerging hubs dependent on expatriate labor pools.
- Slot Allocation Rigidity:Government-backed airport authorities in the UAE and Saudi Arabia prioritize scheduled commercial movements, constraining private aviation peak-hour access.
Strategic Opportunities
- Indian Business Aviation Formalization:DGFT import liberalization and BIS safety standard alignment are opening Mumbai and Delhi to international ground handling franchise models.
- Carbon Border Adjustment Preparation:EU Green Deal compliance infrastructure at Geneva and Zurich terminals creates transferable certification assets for handlers expanding into adjacent markets.
- AI-Driven Turnaround Optimization:Machine vision apron monitoring converging with predictive catering logistics is compressing 45-minute service windows for heavy jet categories.
Industry Challenges
- Multi-Jurisdiction Certification Burden:Handlers operating across FAA, EASA, and ICAO Annex 14 jurisdictions face duplicative training audits and non-harmonized equipment standards.
- Legacy Hangar System Integration:1990s-era fixed-base operator IT infrastructure resists API connectivity with modern flight planning and passenger manifest platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Jet Ground Handling Services Market |
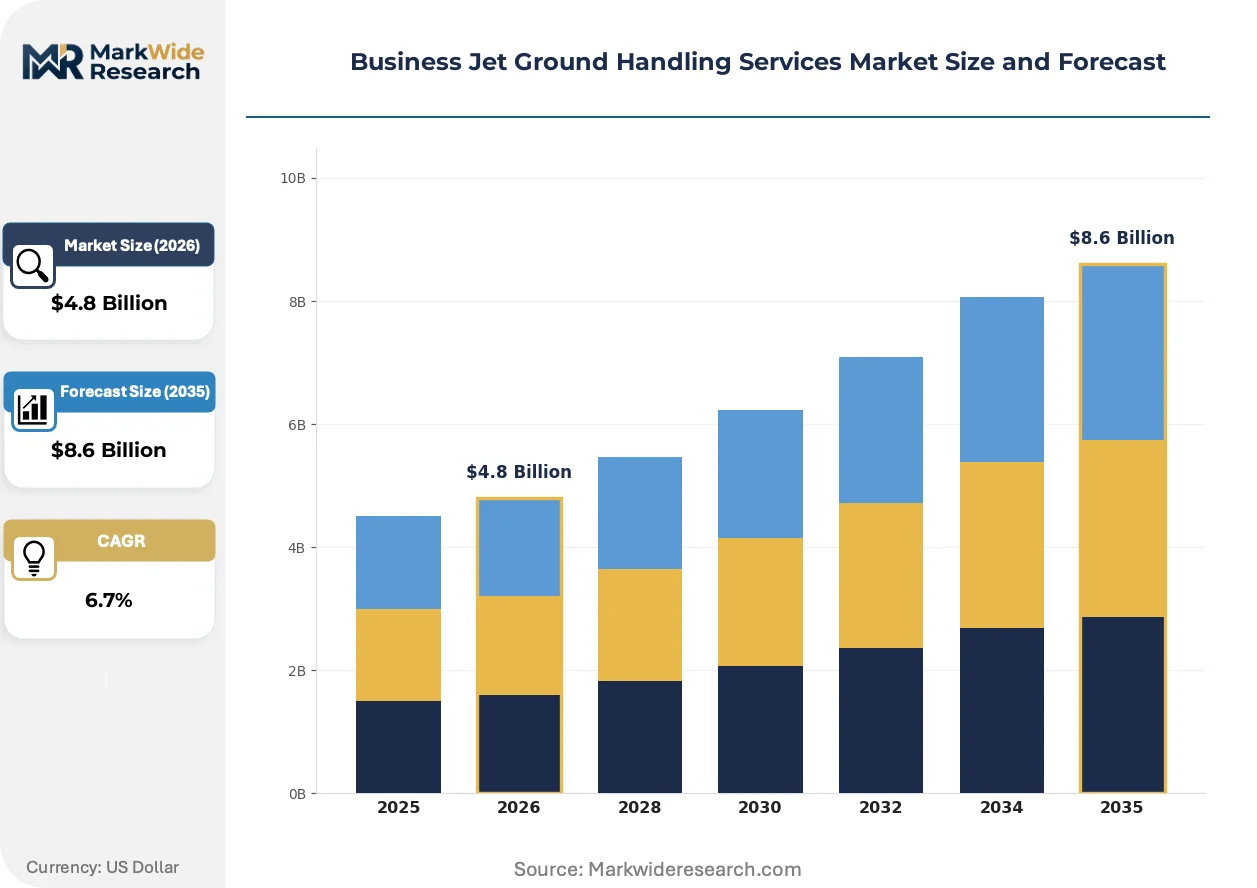
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Catering, Refueling, Passenger Services, Baggage Handling End User: Corporate Clients, Private Owners, Charter Operators, Government Agencies Aircraft Type: Light Jets, Mid-size Jets, Heavy Jets, Ultra-long-range Jets Service Frequency: Daily, Weekly, Monthly, On-demand |
| Companies Covered | Signature Aviation, Jet Aviation, Universal Weather and Aviation, dnata, Swissport International, Atlantic Aviation, ExecuJet Aviation Group, TAG Aviation, Menzies Aviation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Jet Ground Handling Services Market Strategic Shifts
Digital workflow orchestration and electrified ground fleets are displacing manual coordination and diesel-dependent equipment paradigms, while regulatory carbon accounting is embedding emissions tracking into every fueling and catering transaction.
Autonomous baggage tractor technology is miniaturizing through lithium-titanate battery packs that enable 15-minute opportunity charging between movements. Signature Aviation and Jet Aviation are piloting these units at high-frequency North American and European bases. The technology is miniaturizing apron congestion by eliminating driver rest cycles and enabling tighter aircraft stand utilization.
EPA ground support equipment emissions standards and EU F-Gas Regulation refrigerant phase-downs are forcing 2027 equipment replacement deadlines. Handlers face simultaneous HVAC system upgrades and electric tug procurement. Ultra-long-range terminals in Switzerland and the UAE are consolidating compliance investments into single-year capital programs.
Charter operators are unbundling fixed monthly handling contracts in favor of per-movement pricing with dynamic surge premiums. This procurement model shift fragments revenue predictability for fixed-base operators. The pattern concentrates among on-demand fractional ownership platforms operating between New York, London, and Dubai.
Business Jet Ground Handling Services Market Segmentation
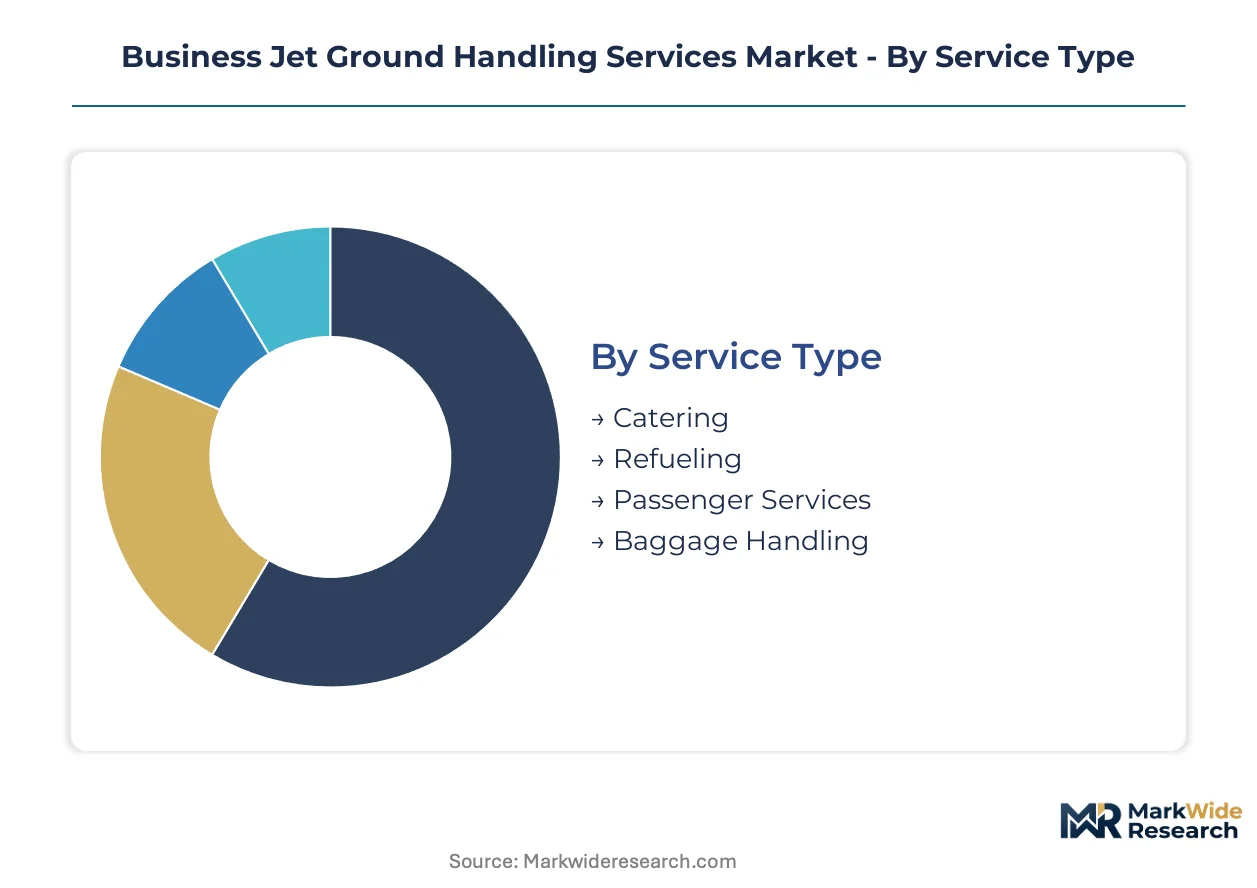
Ground handling economics fragment sharply across service types and aircraft categories, with ultra-long-range operations commanding premium pricing while light jet segments face automation-driven commoditization pressure. Handler profitability hinges on matching capital deployment to the specific operational intensity and regulatory burden of each segment pairing.
Service Type:
Refueling operations face the most acute substitution threat from self-service fueling technologies and airline cooperative arrangements, while passenger services resist automation due to bespoke concierge requirements.
- Refueling:Jet-A and SAF-compatible fueling infrastructure demands FAA-certified system operators and EPA-compliant spill containment. Demand concentrates at Dubai and Abu Dhabi super-connector hubs where 90-minute ultra-long-range turnarounds require simultaneous multi-point servicing under tightening EASA safety mandates.
- Passenger Services:Concierge embarkation, customs facilitation, and lounge provisioning generate the highest margin pools per movement. Corporate flight departments in Geneva and Zurich anchor demand for white-glove protocols that justify premium fixed-base operator pricing.
- Catering:Cold-chain meal provisioning and specialized dietary accommodation for intercontinental sectors. Charter operators between New York and London drive specification intensity.
- Baggage Handling:Rapid transfer protocols for tight turnaround windows with autonomous tractor pilots emerging at high-frequency North American bases.
Refueling retains volume leadership; passenger services holds the steepest expansion curve.
End User:
Cost tier stratification separates predictable corporate accounts from volatile on-demand charter procurement.
- Corporate Clients:Fortune 500 flight departments and multinational headquarters fleets demand guaranteed slot access and standardized global service level agreements. Contract structures emphasize annual minimums with penalty clauses for peak-hour unavailability.
- Charter Operators:On-demand fractional ownership platforms unbundle fixed monthly contracts in favor of per-movement pricing with dynamic surge premiums. This procurement shift fragments revenue predictability for handlers across New York, London, and Dubai corridors.
- Private Owners:Ultra-high-net-worth individuals operating single-aircraft fleets prioritize discretion and flexibility over cost optimization.
- Government Agencies:State aircraft and diplomatic missions require cleared personnel and secure facility access with sovereign immunity complications.
Corporate clients retain volume leadership; charter operators holds the steepest expansion curve.
Aircraft Type:
Operational complexity escalates non-linearly with range capability, concentrating handler investment in heavy and ultra-long-range infrastructure.
- Ultra-long-range Jets:Gulfstream G700 and Global 7500 categories require extended fueling protocols, complex multi-course catering, and augmented lavatory servicing. Dubai and Abu Dhabi terminals have reconfigured apron workflows specifically for 90-minute turnarounds on intercontinental sectors.
- Heavy Jets:Challenger and Falcon categories drive disproportionate revenue per movement through cabin configuration diversity and international catering requirements. Swiss terminals at Geneva and Zurich anchor European capacity for this segment.
- Mid-size Jets:Continental-range categories with standardized servicing requirements and thinner margin profiles.
- Light Jets:Entry-level categories facing automation pressure and handler consolidation toward self-service models.
Heavy jets retain volume leadership; ultra-long-range jets holds the steepest expansion curve.
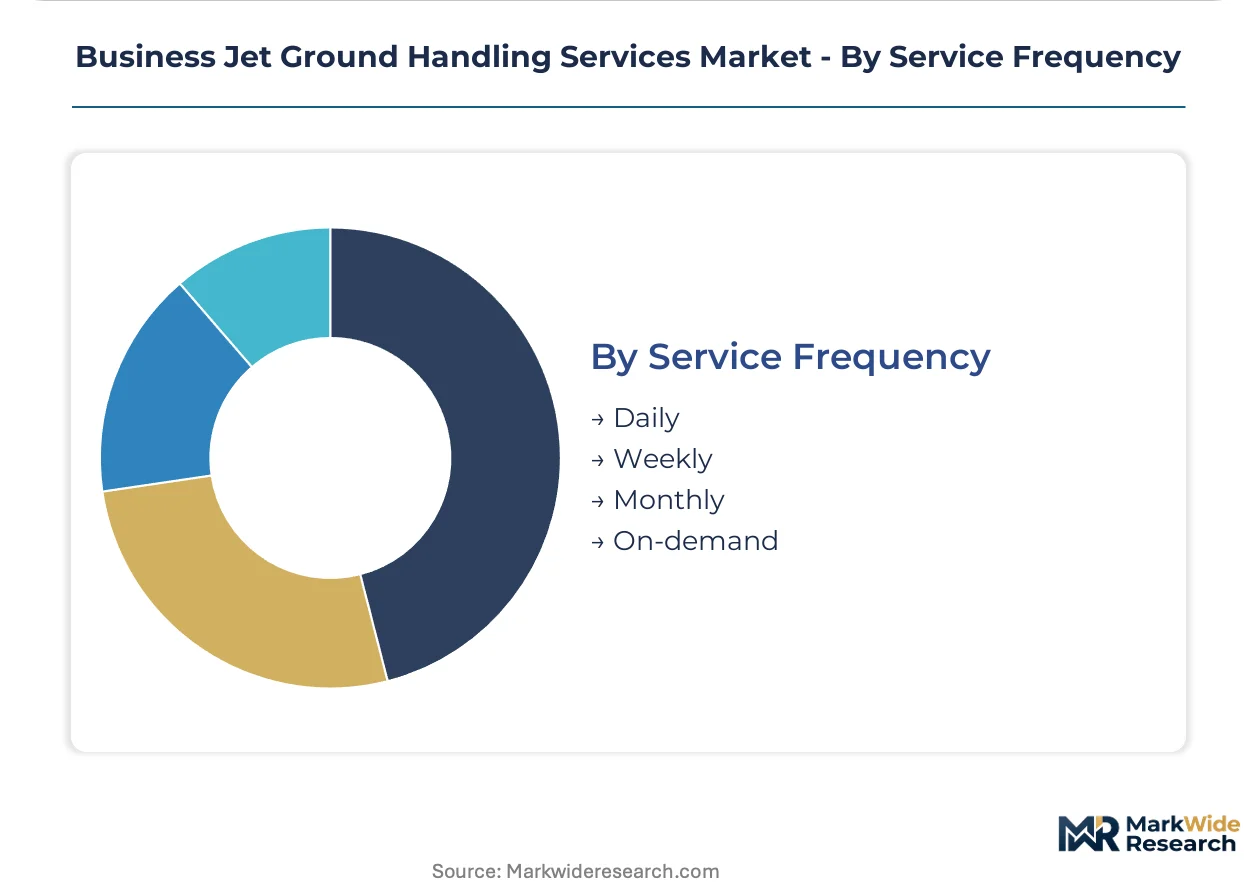
Service Frequency:
Contract maturity separates predictable recurring revenue from transactional spot market exposure.
- On-demand:Per-movement arrangements expanding fastest among charter operators seeking variable-cost structures. Dynamic pricing algorithms now adjust premiums based on slot scarcity and equipment availability in real-time.
- Daily:High-frequency shuttle operations between financial centers with dedicated line service teams and pre-positioned equipment.
- Weekly:Corporate commuter patterns with moderate predictability and seasonal adjustment clauses.
- Monthly:Occasional-use owners with the highest price sensitivity and lowest service loyalty.
Daily contracts retain volume leadership; on-demand arrangements holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium ground handling rates in Switzerland and the UAE command 40-60% markups over equivalent services in India and Southeast Asia. This pricing-power asymmetry reflects apron capacity scarcity at Geneva and Dubai super-connector terminals versus greenfield expansion opportunities in Mumbai and Delhi. Regulatory harmonization gaps between FAA Part 139, EASA directives, and local civil aviation authorities fragment operational compliance costs across these markets.
United States
Corporate flight departments and fractional ownership platforms anchor demand across New York, Los Angeles, and Dallas-Fort Worth metro areas. FAA Part 139 certification mandates drive firefighting equipment upgrades and enhanced runway safety investments at Teterboro, Van Nuys, and Love Field. Signature Aviation and Atlantic Aviation consolidate apron capacity through dedicated hangar networks in these high-frequency corridors.
Switzerland
Geneva and Zurich terminals serve as European anchors for ultra-long-range jet turnarounds requiring complex catering and extended fueling protocols. EASA ground handling directives and Swissmedic-adjacent safety protocols impose stringent personnel certification requirements. Jet Aviation maintains infrastructure dominance across both cities, leveraging carbon border adjustment preparation to build transferable compliance assets.
United Arab Emirates
Dubai and Abu Dhabi function as intercontinental super-connectors generating 90-minute turnaround demand for Gulfstream G700 and Global 7500 categories. MOHAP and GCAA safety mandates converge with government-backed airport expansion programs accelerating slot allocation for private aviation. dnata competes aggressively across both hubs where sovereign wealth financing enables premium apron reconfiguration.
United Kingdom
London-area airports including Farnborough, Biggin Hill, and Luton anchor transatlantic business aviation demand from financial services and technology sectors. CAA oversight aligns with EASA post-Brexit regulatory equivalence agreements on ground handling standards. Universal Weather and Aviation maintains operational presence across these facilities serving corporate and charter operator segments.
India
Mumbai and Delhi international airports face formalization pressure as DGFT import liberalization and BIS safety standard alignment open markets to international franchise models. Regional handlers currently dependent on expatriate labor pools face technician scarcity as domestic certification programs mature. ExecuJet Aviation Group and TAG Aviation position for first-mover advantage in these emerging corridors.
Business Jet Ground Handling Services Market Competitive Environment
Concentration sits with integrated fixed-base operators controlling premium hub infrastructure. North American and European markets exhibit tiered consolidation where full-service handlers sustain pricing power through hangar network density, while regional competitors face margin compression from capital-intensive electric GSE mandates. Three archetypes dominate: legacy FBOs with real estate moats, airline-affiliated ground handlers leveraging commercial aviation infrastructure, and government-backed Middle Eastern operators capturing super-connector traffic. Competitive moves center on apron capacity expansion at constrained hubs and strategic technology partnerships for turnaround optimization software.
Within the legacy FBO tier, Signature Aviation and Jet Aviation exemplify infrastructure-led positioning through North American hangar dominance and European ultra-long-range terminal control respectively. dnata occupies a distinct archetype as a government-affiliated operator scaling across Dubai and Abu Dhabi super-connector economics. These three anchors illustrate how capital access and regulatory relationships determine competitive mobility in apron-constrained markets.
| Leading Market Players |
|---|
| Signature Aviation |
| Jet Aviation |
| Universal Weather and Aviation |
| dnata |
| Swissport International |
| Atlantic Aviation |
| ExecuJet Aviation Group |
| TAG Aviation |
| Menzies Aviation |
| Others |
Value Chain & Pricing Dynamics
Electric ground support equipment substitution for diesel-powered tugs and tractors is simultaneously reshaping supply geography toward battery manufacturing clusters in South Korea and Japan and compressing pricing economics for regional handlers facing 40-60% higher capital deployment requirements.
Pricing Analysis
The customization-premium spread between white-glove ultra-long-range packages and standardized light-jet services spans 40-60% across major hubs. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by FAA Part 139 certification grade and apron slot scarcity at Geneva and Dubai terminals. Pricing pressure stems from charter operators unbundling fixed contracts for per-movement procurement. Corporate flight departments show lowest price sensitivity; regional handlers face highest margin compression.
Supply Chain Analysis
Inbound logistics costs for lithium-titanate battery packs from East Asian manufacturing hubs concentrate supply risk at Rotterdam and Singapore transshipment points. Ground support equipment manufacturing draws from China, Germany, and the United States. Critical dependencies include avionics-grade batteries, SAF-compatible fueling components, and certified firefighting foam. Single-source vulnerability sits with specialized battery cell suppliers. Distribution runs through OEM-direct and aviation distributor networks with long-term service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Business jet ground handling sits in early-cycle expansion as ultra-long-range fleet penetration and super-connector hub economics accelerate premium service adoption beyond traditional corporate aviation strongholds.
For Market Incumbents: Consolidate apron capacity at constrained hubs like Geneva and Dubai through hangar network densification and exclusive slot arrangements. Acquire EASA-compliant training assets to offset technician scarcity threatening turnaround reliability. Prioritize carbon border adjustment infrastructure at Swiss terminals to build transferable compliance moats.
For New Entrants and Emerging Players: FAA Part 135 certification fast-track partnerships with regional airport authorities unlock white-space access in Indian business aviation corridors. Target Mumbai and Delhi formalization momentum where DGFT import liberalization and BIS alignment create franchise-ready conditions. Pursue government-backed airport expansion programs in Saudi Arabia for sovereign-financed infrastructure access.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional FBO networks lacking electric GSE transition capital. Long-term viability favors handlers with sovereign wealth relationships or carbon compliance transferable across jurisdictions. Watch SAF mandate enforcement timing as inflection indicator for equipment replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric GSE Fleet Transition | Battery-powered tugs from South Korean suppliers enable 15-minute opportunity charging at high-frequency bases. |
| SAF-Compatible Fueling Infrastructure | EPA and EU ETS compliance investments at Dubai terminals capture super-connector premium pricing. |
| AI-Driven Turnaround Optimization | Machine vision apron monitoring compresses 45-minute service windows for Gulfstream G700 categories. |
| Carbon Border Adjustment Preparation | Geneva and Zurich compliance infrastructure creates transferable certification assets for adjacent market expansion. |
| Regional Franchise Licensing | DGFT-aligned partnerships in Mumbai and Delhi open first-mover positioning in formalizing Indian corridors. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with FBO operations directors, airport authority slot coordinators, corporate flight department managers, and charter procurement leads; and secondary validation through FAA Part 139 certification databases, EASA ground handling directive filings, GCAA safety mandate records, airport expansion project disclosures, and customs trade data on GSE imports. Bottom-up service volume estimates triangulated against top-down apron capacity and fleet penetration models.
Across the projection horizon, forecasts segment by service type, aircraft category, end-user archetype, and service frequency arrangement. CAGRs derive from equipment replacement cycle analysis, regulatory mandate enforcement timelines, and hub capacity utilization curves. Industry-specific inputs include ultra-long-range fleet delivery schedules and SAF infrastructure deployment rates at major terminals.
Underlying assumptions cover regulatory mandate adherence timelines and sovereign wealth financing continuity for Middle Eastern hub expansion, with deviation risk concentrated in electric GSE supply chain disruptions and technician certification program maturation rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
South Korea Airport Operations Market
Airport Operations
Airport Ground Handling Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
Middle East Airport Operations Market
Airport Operations
Europe Airport Operations Market
Airport Operations
Canada Airport Operations Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Airport Operations Market
Airport Operations
Airport Terminal Operations Market
Airport Operations
Aircraft Ground Handling System Market
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market
Airport Operations
France Airport Operations Market
Airport Operations
Global Airside Services Market
Airport Operations
Global Air Charter Services Market