
 Military Displays Market | 2026-2036
Military Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Military Displays Market Outlook
Ground combat vehicle modernization is realigning procurement priorities across the defense electronics supply chain. BAE Systems leverages its long-running armored systems integration programs to sustain display subsystem orders for tracked and wheeled platforms. Lockheed Martin anchors the fighter cockpit segment with advanced helmet-mounted display architectures. Elbit Systems competes aggressively on export markets through vertically integrated ruggedized display manufacturing.
Military displays are optoelectronic interfaces engineered to operate across temperature extremes from minus 40 to plus 85 degrees Celsius, with luminance outputs exceeding 800 cd/m² for daylight readability and electromagnetic interference shielding compliant with MIL-STD-461. Their primary purpose is to present fused sensor, navigation, and weapons data to operators in tactical environments where consumer-grade screens fail. LCD panels continue to dominate installed base volumes due to proven supply chains and repairability, while OLED technology is capturing retrofit programs demanding faster response times and wider viewing angles. Augmented Reality applications in helmet-mounted systems represent the fastest-expanding technology segment, though holographic displays remain confined to prototype command-station installations with concentrated margin pools.
The US Department of Defense imposes MIL-STD-3009 for night-vision imaging system compatibility, effectively filtering non-compliant suppliers from NATO procurement channels. The EU AI Act and emerging European Defence Fund requirements are adding algorithmic transparency conditions to command-and-control display systems with embedded target-recognition software. Stakeholders must monitor divergence between US military specifications and emerging European certification frameworks when configuring dual-market product architectures.
Market Dynamics
Armored vehicle modernization programs are compressing procurement cycles for ruggedized display systems, forcing suppliers to align development roadmaps with government-issued technical refresh mandates rather than organic technology cycles.
Growth Catalysts
- MIL-STD-3009 Night-Vision Compatibility:NATO standardization mandates are filtering non-compliant suppliers from defense procurement channels, concentrating orders among certified vendors.
- OLED Technology Maturation:Faster response times and wider viewing angles are capturing retrofit programs across fighter cockpit and command-station applications.
- Ground Combat System Allocations:Sustained US Department of Defense budget commitments for tracked and wheeled platforms are accelerating display subsystem orders.
Market Restraints
- Indium Tin Oxide Supply Concentration:Rare earth processing bottlenecks in China create input cost volatility for transparent conductive layers in LCD and OLED panels.
- Electromagnetic Interference Shielding Costs:MIL-STD-461 compliance requires specialized mesh architectures that add 15-25% material overhead versus commercial equivalents.
- Extended Certification Timelines:Dual validation against US military specifications and emerging EU AI Act algorithmic transparency requirements stretches product approval cycles.
Strategic Opportunities
- Augmented Reality Helmet Systems:Fighter pilot and ground vehicle crew applications represent the fastest-expanding technology segment with concentrated margin pools.
- European Defence Fund Alignment:Algorithmic transparency conditions for command-and-control displays with embedded target-recognition software create first-mover advantages for compliant architectures.
- Holographic Command Stations:Prototype installations in naval and fixed-site operations offer premium pricing for suppliers mastering volumetric display engineering.
Industry Challenges
- Thermal Management Engineering Talent:Operating temperature ranges from minus 40 to plus 85 degrees Celsius require specialized optoelectronic thermal design expertise that outstrips current workforce supply.
- Legacy System Interface Integration:New display architectures must maintain backward compatibility with decades-old vehicle databus protocols without performance degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Displays Market |
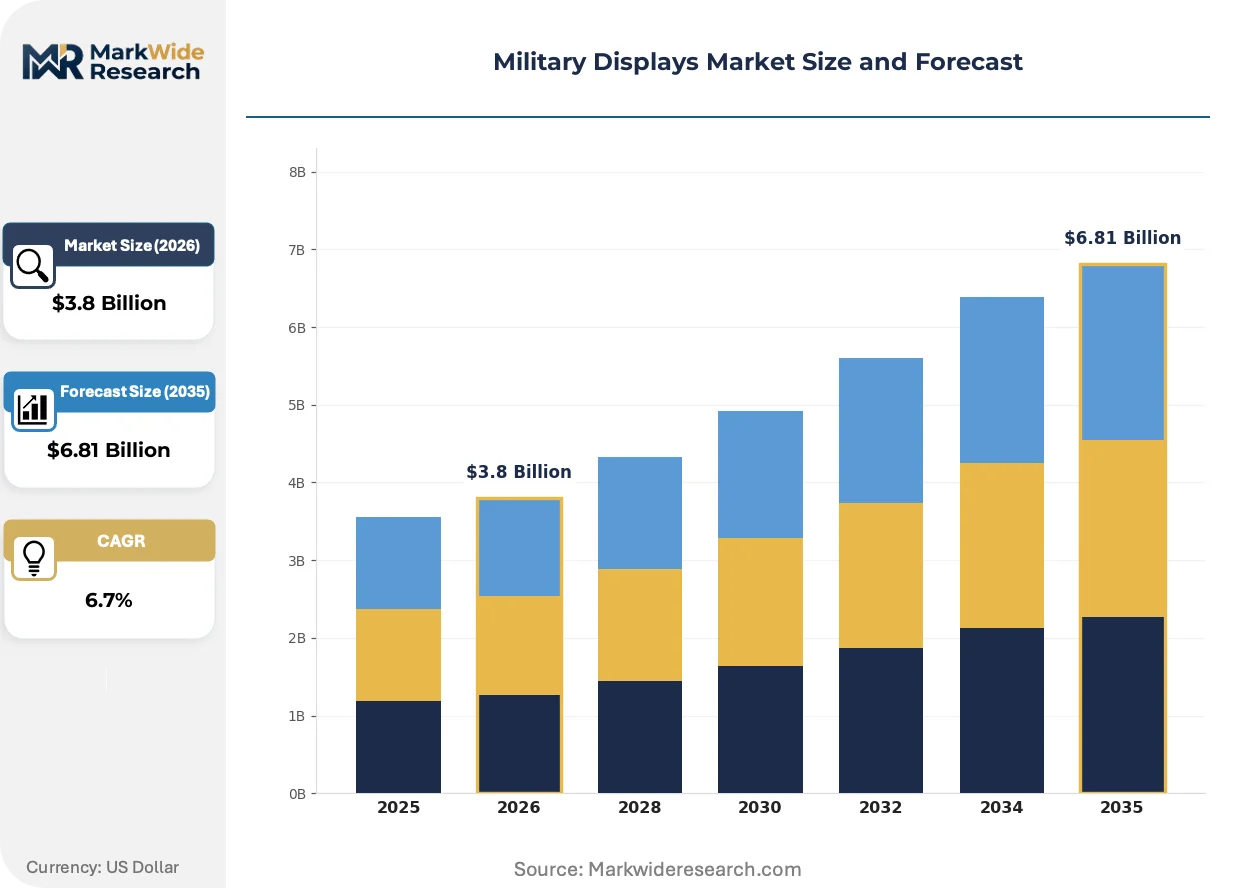
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, LED, Projection Technology: Holographic, Augmented Reality, Virtual Reality, 3D Visualization Application: Situational Awareness, Command & Control, Training Simulations, Surveillance End User: Defense Contractors, Military Organizations, Government Agencies, Aerospace |
| Companies Covered | BAE Systems, Lockheed Martin, Raytheon Technologies, Thales, General Dynamics, Elbit Systems, L3Harris, Leonardo, Curtiss-Wright, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Displays Market Strategic Shifts
Display technology trajectories are diverging between proven LCD supply chains and emerging OLED architectures, while regulatory fragmentation between US and European certification frameworks is forcing parallel product development tracks.
MicroLED backlighting is integrating into next-generation ruggedized panels to achieve luminance outputs exceeding 800 cd/m² for daylight readability without the thermal load of traditional edge-lit architectures. Ground vehicle integrators are piloting these systems in command-station retrofit programs. The technology is integrating sensor fusion rendering capabilities that compress hardware stacks previously requiring separate graphics processing units.
The EU AI Act is imposing algorithmic transparency conditions on command-and-control displays with embedded target-recognition software, requiring explainability logging that US military specifications do not mandate. European defense procurement channels are beginning to filter submissions lacking this documentation. Dual-market suppliers are responding with modular software architectures that segregate inference engines from logging subsystems to satisfy both regulatory regimes.
Defense agencies are consolidating display procurement under platform prime contractors rather than sourcing subsystems directly from component vendors. This channel compression is displacing independent display manufacturers from direct government relationships. The United States and United Kingdom are most visible in this shift, with ground combat vehicle programs leading the restructuring.
Military Displays Market Segmentation
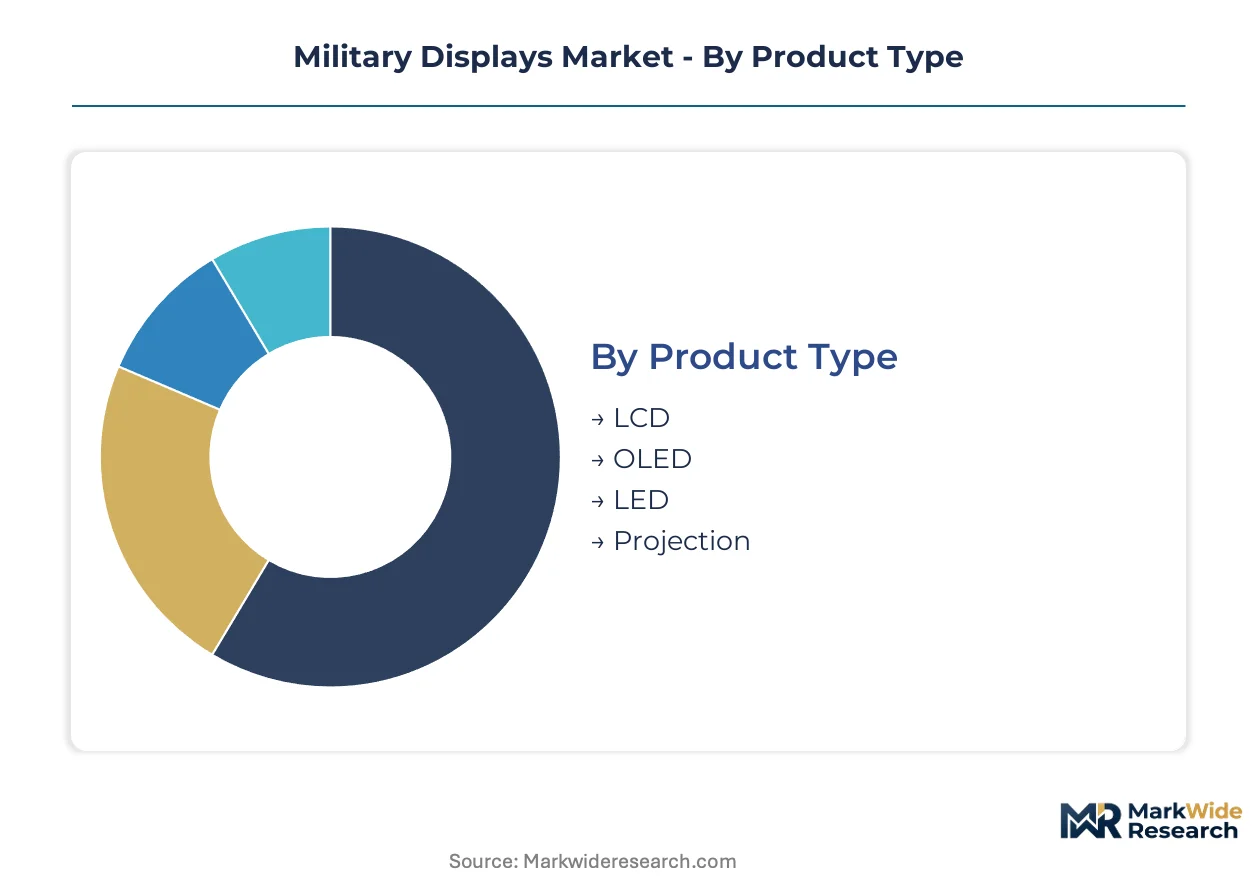
Military display procurement splits sharply between proven architectures with established supply chains and emerging technologies demanding custom engineering. Platform integrators configure specifications around mission profiles rather than selecting from catalogs.
Product Type:
Standardization pressure from MIL-SPEC certification requirements creates divergent sourcing strategies across this category.
- LCD:Dominates installed base through proven supply chains and field-repairable architectures. Demand concentrates in US ground vehicle modernization programs where backward compatibility with legacy databus protocols is mandatory.
- OLED:Captures retrofit programs with faster response times and wider viewing angles for fighter cockpit applications. US Department of Defense and NATO night-vision compatibility mandates are filtering procurement toward certified vendors with MIL-STD-3009 compliance.
- LED:Serves high-luminance command-station applications requiring daylight readability without thermal load penalties.
- Projection:Deploys in fixed-site simulation facilities where volumetric display requirements exceed flat-panel capabilities.
Most installed capacity flows through LCD. Expansion is steepest in OLED.
Technology:
Cost tier separation between mature optoelectronics and experimental interfaces defines competitive positioning in this category.
- Augmented Reality:Fighter pilot and ground vehicle crew helmet systems represent the segment gaining share fastest, with concentrated margin pools from custom optical waveguide engineering.
- Holographic:Prototype naval command-station installations command premium pricing for suppliers mastering volumetric display engineering.
- Virtual Reality:Training simulation procurement from defense contractors drives volume, with EU AI Act algorithmic transparency requirements adding documentation overhead.
- 3D Visualization:Command-and-control applications for fused sensor data rendering, constrained by thermal management engineering talent scarcity.
Volume concentrates in Virtual Reality. Premium pricing attaches to Holographic.
Application:
Customer type determines specification rigor, with frontline deployment applications facing tighter electromagnetic interference and environmental sealing requirements than rear-echelon systems.
- Situational Awareness:Ground combat vehicle crew stations demand minus 40 to plus 85 degrees Celsius operating ranges with MIL-STD-461 shielding compliance.
- Command & Control:EU AI Act conditions on embedded target-recognition software are filtering European procurement toward explainable logging architectures.
- Training Simulations:Defense contractors source projection and VR systems with reduced certification burdens compared to deployed hardware.
- Surveillance:Aerospace end users prioritize luminance outputs exceeding 800 cd/m² for daylight readability in external sensor pod interfaces.
Procurement volume centers on Situational Awareness. Specification complexity peaks in Command & Control.
End User:
Channel compression is restructuring direct relationships, with platform prime contractors consolidating subsystem procurement previously sourced from component vendors.
- Defense Contractors:BAE Systems and Lockheed Martin anchor demand through armored systems integration and fighter cockpit programs respectively.
- Military Organizations:US Department of Defense night-vision compatibility mandates shape NATO standardization efforts.
- Government Agencies:European Defence Fund requirements are adding algorithmic transparency conditions to procurement frameworks.
- Aerospace:Fixed-wing and rotary platforms drive helmet-mounted display specifications with pilot safety-critical certification requirements.
Contractor integration programs capture the largest order flows. Agency certification requirements are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping supplier footprints as certification cost differentials between jurisdictions widen. Production capacity is migrating toward clusters where MIL-SPEC validation infrastructure and defense procurement channels overlap most efficiently.
United States
The US Department of Defense sustains the largest procurement volume through ground combat vehicle modernization and fighter cockpit programs. MIL-STD-3009 night-vision compatibility mandates filter supplier pools aggressively. Defense contractors in Texas and Virginia anchor subsystem integration, with Arlington and Dallas-Fort Worth clusters concentrating prime contractor engineering operations.
United Kingdom
British defense electronics procurement is consolidating under platform prime contractors rather than component vendors. The Ministry of Defence's Land Industrial Strategy accelerates armored vehicle display refresh timelines. BAE Systems facilities in Gloucestershire and Lancashire coordinate display subsystem sourcing for tracked platforms.
Germany
Rheinmetall and Krauss-Maffei Wegmann drive demand for ruggedized crew-station interfaces in Leopard and Boxer programs. KBA vehicle certification standards extend to military variant displays. Bavaria's defense electronics corridor around Munich and Augsburg hosts subsystem suppliers serving NATO standardization requirements.
Israel
Elbit Systems anchors vertically integrated display manufacturing for export markets and domestic applications. Israeli Defense Forces helmet-mounted display specifications influence NATO pilot safety standards. Haifa and Tel Aviv metropolitan clusters concentrate electro-optics engineering talent for thermal management and optical waveguide development.
France
Thales and Safran shape fighter cockpit and naval command-station display requirements through Rafale and FREMM programs. ANSM defense procurement guidelines emphasize electromagnetic interference shielding compliance. The Paris-Saclay cluster and Toulouse aerospace corridor host integration facilities for export-configured systems.
Military Displays Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with platform prime contractors capturing direct government relationships while component vendors serve as tier-two suppliers. Market structure concentrates around five to seven vertically integrated defense electronics houses with captive display engineering capabilities. Three archetypes dominate: systems integrators with armored vehicle programs, cockpit specialists with helmet-mounted display portfolios, and export-focused electro-optics houses. Competitive moves center on backward integration into optical component manufacturing and strategic positioning for European Defence Fund algorithmic transparency compliance.
Among systems integrators with tracked and wheeled platform exposure, BAE Systems and General Dynamics occupy positions shaped by long-running armored vehicle programs. Elbit Systems exemplifies the export-oriented electro-optics archetype through vertically integrated ruggedized display manufacturing. These three anchors represent distinct competitive vectors: domestic platform capture, multi-domain portfolio breadth, and export market specialization.
| Leading Market Players |
|---|
| BAE Systems |
| Lockheed Martin |
| Raytheon Technologies |
| Thales |
| General Dynamics |
| Elbit Systems |
| L3Harris |
| Leonardo |
| Curtiss-Wright |
| Others |
Value Chain & Pricing Dynamics
OLED technology maturation is compressing procurement cycles while simultaneously redistributing pricing power toward certified vendors with MIL-STD-3009 compliance, creating cost premiums for night-vision compatible architectures that legacy LCD suppliers cannot match.
Pricing Analysis
Direct-to-OEM contracting dominates procurement, with platform prime contractors capturing 15-25% margin premiums through bundled subsystem integration. Price differentiation hinges on MIL-STD-461 electromagnetic shielding certification tier and volume scale across armored vehicle programs. Cost compression in LCD retrofit segments is intensifying because Chinese indium tin oxide supply volatility feeds input cost uncertainty. Defense contractors exhibit lowest price sensitivity due to mission-critical specifications, while training simulation procurement shows highest elasticity.
Supply Chain Analysis
Freight costs for specialized optoelectronic components remain elevated due to temperature-controlled handling requirements for minus 40 to plus 85 degrees Celsius rated subassemblies. Manufacturing concentrates in the United States, Israel, and Germany, with display panel fabrication drawing from South Korean and Taiwanese substrate suppliers. Supply chain risk centers on single-source vulnerability for rare earth transparent conductive layers. Distribution runs through platform prime contractor integration facilities rather than direct government channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with EU AI Act algorithmic transparency mandates creating certification moats that concentrate procurement among compliant architectures.
For Market Incumbents: Cement MIL-STD-3009 certification dominance by backward integrating into optical waveguide manufacturing for helmet-mounted systems. Elbit Systems' vertically integrated model demonstrates how captive thermal management engineering capacity defends against workforce scarcity threats. Prioritize European Defence Fund compliance investments to preempt channel displacement from emerging algorithmic transparency requirements.
For New Entrants and Emerging Players: The premium-economy pricing gap in command-station holographic prototypes offers white-space entry with concentrated margin pools. Target naval fixed-site installations where volumetric display engineering requirements filter incumbent competition. Pursue modular software architectures that segregate inference engines from logging subsystems to satisfy dual US-EU regulatory regimes without parallel product lines.
For Investors and Strategic Acquirers: Valuations sit cheapest among component vendors displaced from direct government relationships by channel compression toward platform primes. Five-to-ten year viability favors acquisition targets with captive thermal management engineering talent and existing MIL-SPEC validation infrastructure. Monitor European Defence Fund procurement guideline releases as inflection signals for algorithmic transparency compliance premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| MIL-STD-3009 Certification Investment | Night-vision compatibility mandates filter NATO procurement toward certified vendors exclusively. |
| Backward Integration into Optical Waveguides | Captive waveguide manufacturing secures helmet-mounted display margins against component supply volatility. |
| EU AI Act Compliance Architecture | Modular inference-logging separation enables dual-market product configurations without parallel development tracks. |
| Thermal Management Engineering Acquisition | Specialized optoelectronic thermal design talent scarcity makes captive expertise a defensive moat. |
| Platform Prime Contractor Partnership | Channel compression toward BAE Systems and Lockheed Martin integration programs secures order flow visibility. |
Study Parameters
Bottom-up ground combat vehicle and fighter cockpit platform modeling reconciled against top-down defense electronics supply chain tracking forms the analytical core. Primary interviews with platform integration engineers, military procurement officers, electro-optics R&D directors, and thermal management specialists combined with secondary validation from US Department of Defense budget justifications, NATO standardization documents, SEC 10-K filings from listed defense contractors, and European Defence Fund procurement guidelines. Triangulation between end-use demand signals and component vendor order backlogs anchors volume estimates.
Historical trendline analysis of armored vehicle modernization program spending patterns informs the projection framework across the analysis window. Segmentation dimensions modeled include display technology type, application environment, platform class, and regulatory certification tier. CAGRs derive from weighted average of platform procurement schedules and technology refresh cycle timing. Fighter cockpit helmet-mounted display adoption curves and ground vehicle crew-station retrofit velocities serve as industry-specific forecast inputs.
Caveats apply where US defense budget reallocation or European AI Act enforcement timing could materially shift the outlook. Forecasts reflect assumptions about NATO standardization continuity and rare earth supply chain stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
Military Optoelectronic System Market
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
Rubber Tracks for Defense and Security Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
Military Test Equipment Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Latin America Defense Market
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market
Military Equipment and Infrastructure
Man Portable Military Electronics Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
CBRN Protection Equipment Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market