
 Airport Ground and Cargo Handling Services Market | 2026-2036
Airport Ground and Cargo Handling Services Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Ground and Cargo Handling Services Market Intelligence
EU F-Gas Regulation is hardening the cost-of-entry calculus for ground handling operators across Europe by mandating phasedown of hydrofluorocarbon-based cooling systems in cargo terminals and perishable storage facilities. Menzies Aviation leverages its scale to retrofit cold-chain infrastructure ahead of compliance deadlines. SATS Ltd anchors its competitive position through specialized pharmaceutical handling capabilities in Southeast Asian hubs. Swissport International AG navigates fragmented national regulations while sustaining margin pools in premium cargo segments.
Airport ground and cargo handling services encompass the physical processing, movement, and documentation of aircraft, passengers, baggage, and freight on airport ramps and in terminal facilities, typically requiring coordination of specialized ground support equipment with turnaround times under 90 minutes for narrow-body aircraft. These services exist to ensure safe, time-critical aircraft rotation and uninterrupted cargo flow through global supply chains. Ramp services dominates operational revenue due to its labor intensity and universal requirement across all aircraft movements, while automated guided vehicles represent the fastest-expanding technology segment as airports automate baggage and cargo transport to reduce tarmac congestion. Cargo handling concentrates margin pools in temperature-controlled and pharmaceutical verticals where certification barriers limit competition.
FAA mandates in the United States govern ground support equipment emissions and operational safety standards at commercial airports, while EASA implements parallel requirements across European member states with additional noise and carbon restrictions. ICAO standards provide the baseline framework that national regulators adapt, creating compliance complexity for multinational operators. Stakeholders must monitor how biometric cargo tracking regulations and autonomous vehicle certification protocols reshape capital deployment priorities without assuming technology adoption timelines align across jurisdictions.
Market Dynamics
The EU Green Deal is forcing fleet electrification across European ground handling operations, compressing capital deployment timelines while reshaping equipment procurement strategies across major hub airports.
Growth Catalysts
- E-commerce parcel surge:Air cargo networks are absorbing unprecedented parcel volumes from online retail platforms, expanding dedicated freighter handling capacity at major sorting hubs.
- FAA ground support equipment mandates:Stricter emissions and safety standards in the United States are accelerating replacement cycles for aging diesel-powered tarmac vehicles.
- Pharmaceutical cold-chain certification:Temperature-controlled cargo handling is attracting premium margins as biologics shipments require validated infrastructure.
Market Restraints
- Lithium battery supply concentration:Electrification of ground support equipment depends on battery cell supplies concentrated in East Asian manufacturing clusters.
- F-Gas Regulation compliance costs:The EU's phasedown of hydrofluorocarbon cooling systems imposes retrofit capital burdens on perishable cargo terminals.
- Skilled technician scarcity:Maintenance of automated guided vehicles and electric fleets requires specialized training programs that lag fleet expansion.
Strategic Opportunities
- India airport privatization wave:Greenfield terminals in Delhi, Mumbai, and Bangalore are tendering integrated ground handling concessions to private operators.
- Biometric cargo tracking mandates:ICAO standards for digital freight documentation are creating first-mover advantages for technology-enabled handlers.
- Autonomous vehicle certification:Regulatory frameworks for driverless baggage tractors in Singapore and Dubai are opening operational efficiency gains.
Industry Challenges
- Legacy system integration:Automated guided vehicle fleets must interface with decades-old warehouse management software at established cargo terminals.
- Turnaround time pressure:Narrow-body aircraft rotations under 90 minutes leave minimal margin for equipment repositioning delays during peak scheduling windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Ground and Cargo Handling Services Market |
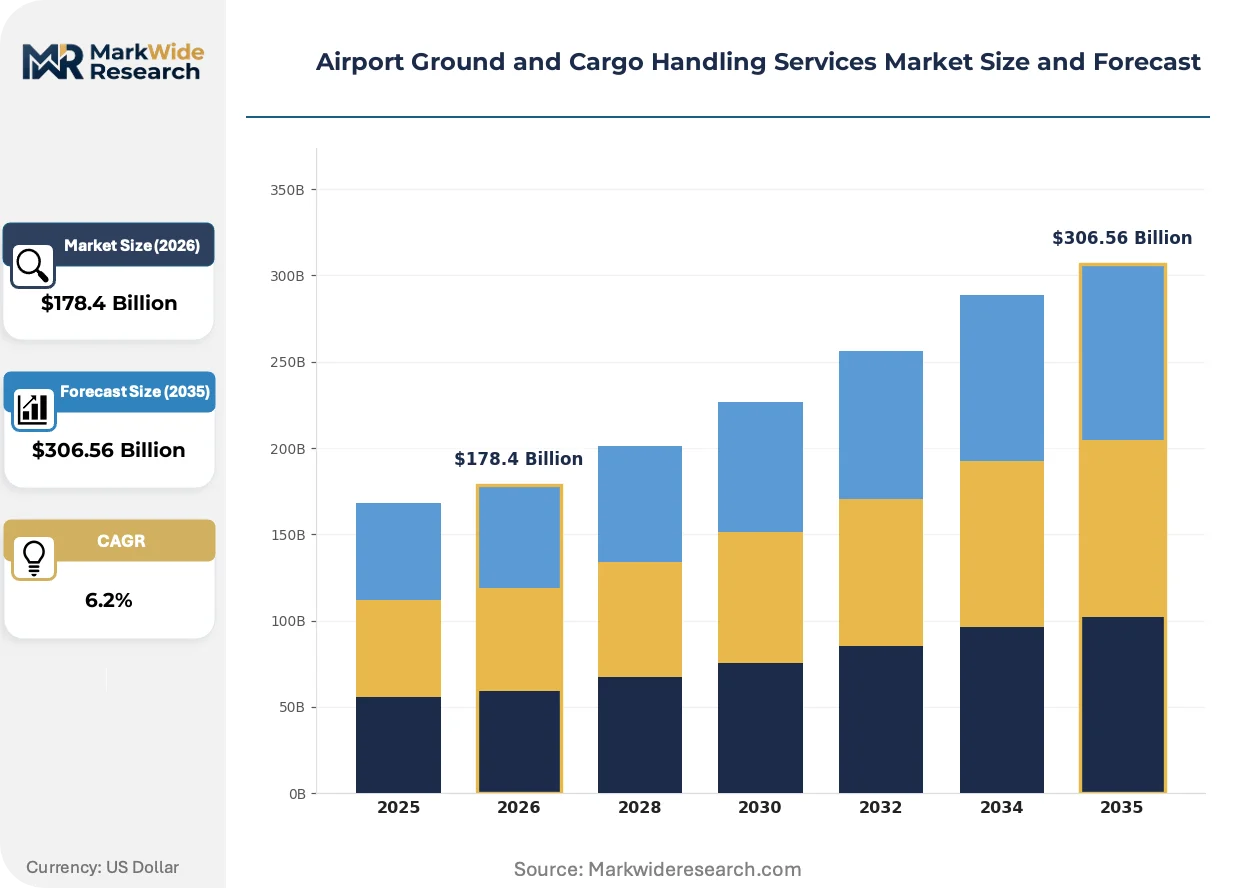
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $306.56 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Baggage Handling, Aircraft Cleaning, Cargo Handling, Fueling Operations, Ramp Services Technology Used: Automated Guided Vehicles, Radio Frequency Identification, Drones, Conveyor Systems, Weighing Scales Customer Type: Airlines, Freight Forwarders, E-commerce Companies, Courier Services, Logistics Providers Deployment Model: In-house Operations, Outsourced Services, Public-Private Partnerships, Joint Ventures |
| Companies Covered | Menzies Aviation, SATS Ltd, Swissport International AG, Fraport AG, Celebi Aviation Holding, Dnata, Aviapartner, dnata LLC, Worldwide Flight Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Ground and Cargo Handling Services Market Strategic Shifts & Innovations
Digital automation and sustainability mandates are converging to redefine operational benchmarks across ramp services and cargo terminals, compressing legacy cost structures while elevating service-level expectations.
Automated guided vehicles are absorbing material handling labor across baggage and cargo transport functions at congested hub airports. Major handlers in Frankfurt and Amsterdam are deploying autonomous tractor fleets to reduce tarmac vehicle conflicts and fuel burn. The technology is absorbing intermediate-distance transport tasks that previously required human-operated equipment, reallocating workforce toward exception management.
The EU F-Gas Regulation is hardening cooling system requirements for pharmaceutical and perishable storage facilities across European cargo terminals. Operators face phased compliance deadlines that compress infrastructure investment timelines. Temperature-controlled handlers in Germany and the Netherlands are retrofitting cold-chain infrastructure ahead of enforcement dates to secure certification continuity.
Airline procurement departments are consolidating ground handling contracts toward multi-service integrated agreements that bundle ramp, cargo, and passenger services. Legacy single-service contracts are losing share to performance-based frameworks with penalty clauses for missed connection windows. This consolidation is most visible among European network carriers restructuring supplier portfolios at hub airports.
Airport Ground and Cargo Handling Services Market Segmentation
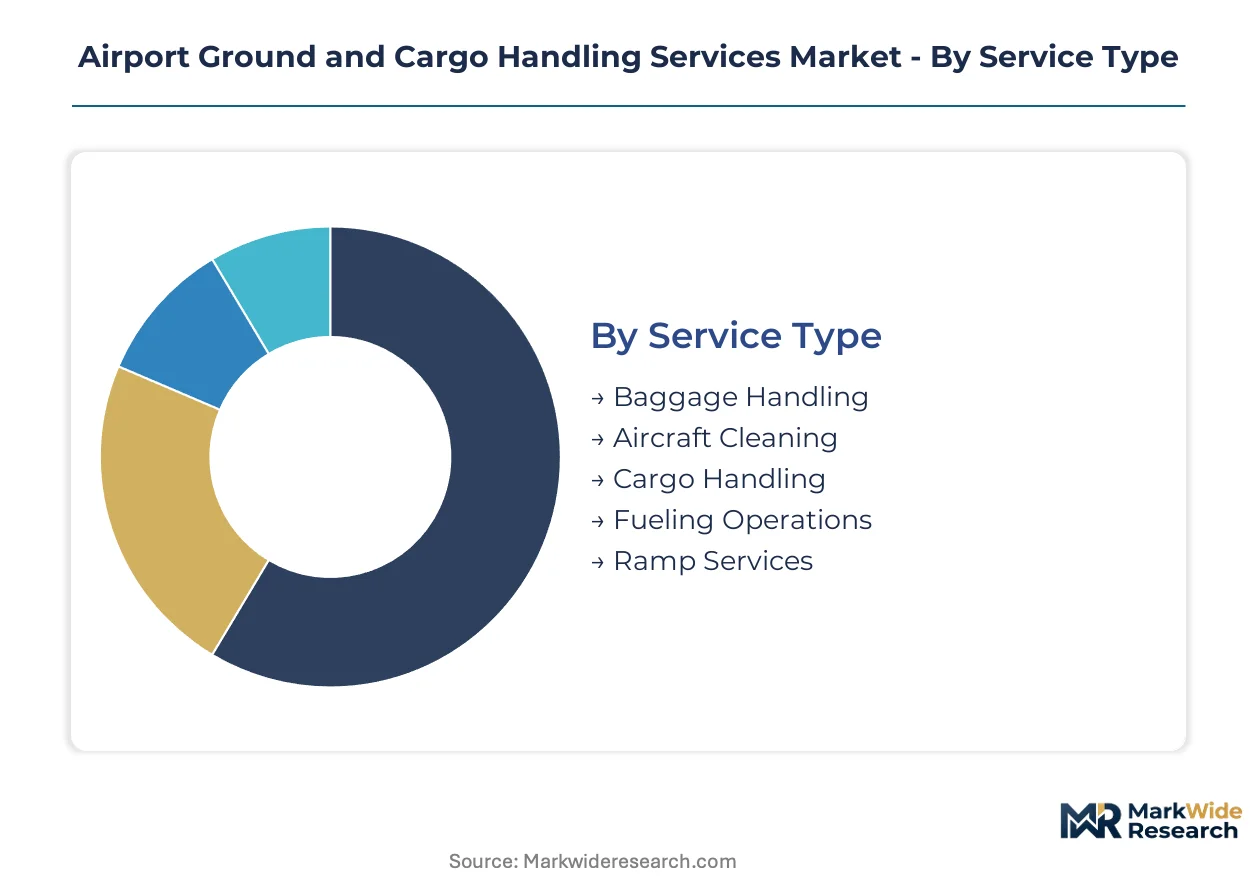
Segmentation in airport ground and cargo handling services reveals how capital allocation, labor intensity, and technology adoption vary across operational functions. Service providers configure equipment fleets and workforce deployment differently depending on which customer type and deployment model they target.
Service Type:
Ramp services concentrate the largest equipment fleets and labor pools across major hub airports, with supply-side scale determining competitive viability in narrow-body turnaround windows.
- Ramp Services:Encompass aircraft marshaling, pushback operations, and ground power unit deployment. Frankfurt Airport handlers maintain specialized teams for 90-minute Airbus A320 rotations. Supply concentration among three major European operators limits price competition at slot-constrained hubs.
- Cargo Handling:Physical processing of freight through terminal facilities including build-up, break-down, and customs documentation. Temperature-controlled pharmaceutical verticals in Singapore and Dubai generate premium margins where CEIV Pharma certification creates entry barriers.
- Baggage Handling:Automated sortation and transfer coordination between check-in and aircraft holds. Conveyor system throughput capacity constrains peak morning departure banks at congested single-runway airports.
- Fueling Operations:Into-plane fuel delivery and quality assurance testing. Hydrant system infrastructure investments lock in long-term service agreements at capital-intensive greenfield terminals.
- Aircraft Cleaning:Cabin sanitization and turnaround preparation between flight segments. Labor arbitrage drives outsourcing to specialized contractors at secondary airports in India and Southeast Asia.
Today's leader: Ramp Services. Tomorrow's challenger: Cargo Handling.
Technology Used:
Technology deployment patterns track airport infrastructure maturity and labor cost structures across different geographies.
- Automated Guided Vehicles:Driverless baggage tractors and cargo dollies navigate tarmac routes using magnetic tape or LiDAR guidance. Amsterdam Schiphol deploys autonomous fleets to reduce fuel burn and vehicle conflict incidents during peak scheduling windows.
- Radio Frequency Identification:Baggage tag tracking through interrogation zones at sortation facilities. IATA Resolution 753 mandates for member airlines are accelerating tag infrastructure deployment across major international hubs.
- Conveyor Systems:Belt and tilt-tray sortation for baggage and small parcel flows. System redundancy requirements at hub airports favor established European and Japanese equipment suppliers.
- Drones:Tarmac inspection and perimeter surveillance applications. Regulatory frameworks from the FAA and EASA currently restrict beyond-visual-line-of-sight operations at most commercial airports.
- Weighing Scales:Integrated load control systems for aircraft weight and balance calculations. Calibration certification requirements create recurring service revenue streams for equipment vendors.
Automated Guided Vehicles are expanding most quickly as labor costs rise and safety regulators tighten tarmac vehicle operation standards.
Customer Type:
Customer mix determines service level agreements, penalty structures, and technology investment priorities for ground handling operators.
- E-commerce Companies:Parcel volume surges from online retail platforms are reshaping air cargo network design. Dedicated freighter handling capacity at Louisville and Leipzig sorting hubs requires specialized conveyor infrastructure for small-package flows.
- Airlines:Full-service carriers negotiate integrated handling contracts covering ramp, cargo, and passenger services. Lufthansa and Air France-KLM consolidation of supplier portfolios at European hubs favors multi-service operators with scale.
- Freight Forwarders:Consolidators requiring neutral handling access across multiple airline networks. Swissport and Menzies maintain dedicated forwarder facilities at major cargo hubs to preserve shipper relationships.
- Courier Services:Time-definite express operators with rigid cutoff schedules. FedEx and DHL network designs depend on guaranteed 60-minute transfer windows at their primary sorting hubs.
- Logistics Providers:Third-party supply chain managers seeking end-to-end visibility. Digital integration requirements with customer warehouse management systems favor handlers with mature IT platforms.
E-commerce Companies are gaining share fastest as parcel volumes displace traditional general cargo in belly-hold and freighter capacity allocation.
Deployment Model:
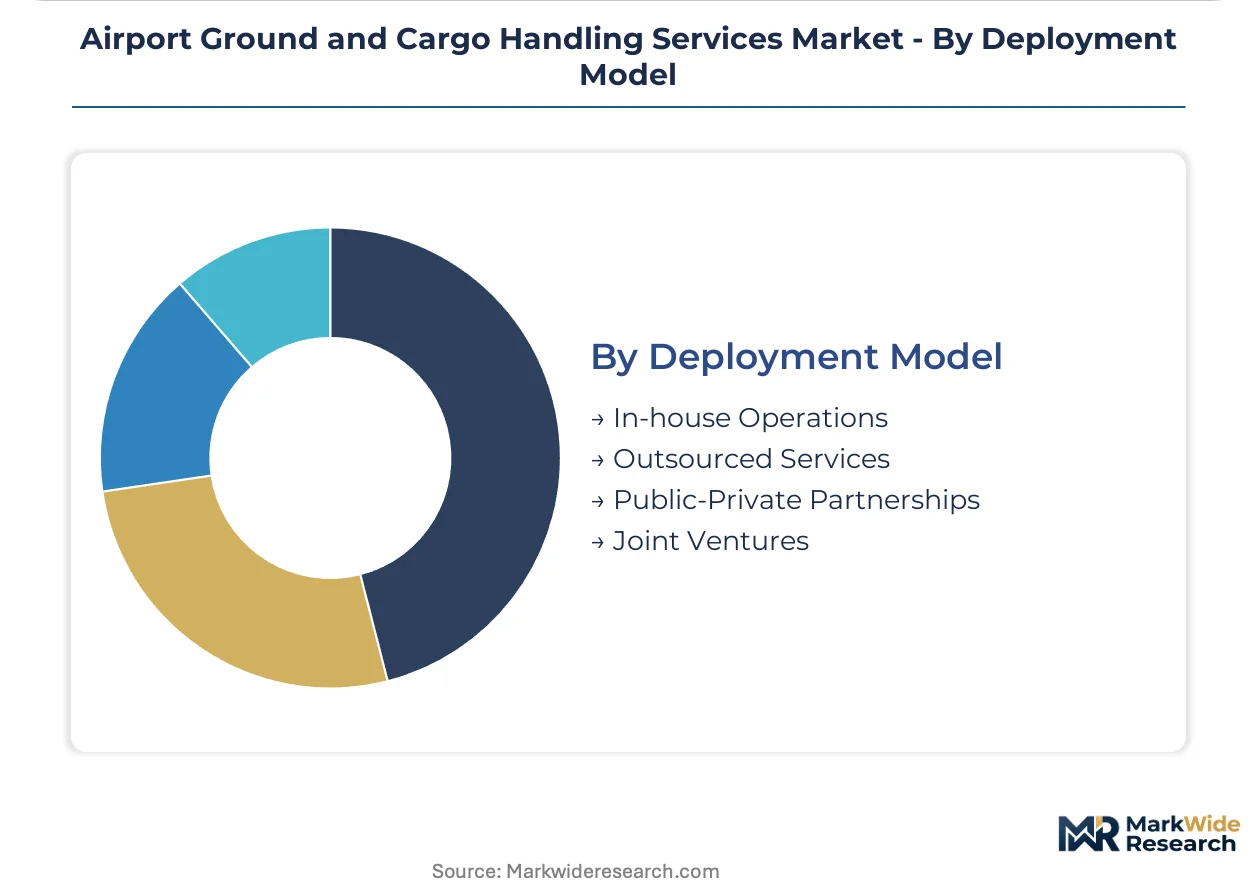
Deployment structure reflects airport ownership patterns, regulatory frameworks, and capital availability in different national markets.
- Outsourced Services:Third-party ground handling specialists operate under concession agreements with airport authorities. EU Directive 96/67 liberalized ground handling markets, enabling entry by independent service providers at major European hubs.
- In-house Operations:Airline-owned handling subsidiaries serving proprietary flight schedules. Delta and United maintain captive ground operations at their primary US hubs to control connection reliability.
- Public-Private Partnerships:Mixed-ownership structures for greenfield terminal developments. India's airport privatization wave has tendered integrated ground handling concessions at Delhi, Mumbai, and Bangalore.
- Joint Ventures:Collaborative entities between airlines and handling specialists. SATS and airline partners operate dedicated cargo terminals at Singapore Changi to secure pharmaceutical certification continuity.
Outsourced Services dominate revenue pools. Joint Ventures are climbing fastest as airlines seek risk-sharing structures for specialized cargo infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aviation ground handling originated in early European airport operations, with formalized services scaling through post-war hub development in Germany and the United Kingdom before spreading to North American and Asian markets.
United States
FAA emissions mandates for ground support equipment are accelerating fleet replacement at major hubs. The Infrastructure Investment and Jobs Act channels federal funding toward airport electrification projects. Atlanta Hartsfield-Jackson and Chicago O'Hare are deploying electric baggage tractors to meet tightening operational standards.
Germany
Frankfurt and Munich airports anchor European cargo throughput, with pharmaceutical cold-chain infrastructure commanding premium handling fees. EU F-Gas Regulation compliance deadlines are forcing terminal refrigeration retrofits. Ground handlers in the Rhine-Main region are consolidating operations to absorb capital burdens from dual electrification and cooling system upgrades.
China
Domestic air cargo volumes are reshaping ground handling requirements at Beijing Capital and Shanghai Pudong. MIIT standards for new energy vehicles extend to airport equipment procurement. The Yangtze River Delta cluster is expanding dedicated freighter handling capacity to absorb e-commerce parcel flows.
Singapore
Changi Airport's pharmaceutical certification hub status attracts specialized cargo investment from global biologics shippers. The Civil Aviation Authority of Singapore is piloting autonomous vehicle frameworks for baggage transport. SATS and airline joint ventures operate temperature-controlled terminals serving Southeast Asian distribution networks.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International are expanding ground handling concessions to private operators. The General Civil Aviation Authority is aligning certification standards with ICAO biometric cargo tracking protocols. Emirates' captive handling subsidiary competes alongside international specialists for third-party airline contracts.
Airport Ground and Cargo Handling Services Market Key Industry Players
The competitive structure tilts toward scale-driven integrated operators with multi-service capabilities across ramp, cargo, and passenger functions. Consolidation pressure favors handlers capable of bundling services under performance-based contracts with penalty clauses. Three archetypes dominate: global network specialists with hub concentration, regional cargo-focused operators with cold-chain certification, and airline-captive subsidiaries prioritizing connection reliability. Dominant competitive moves include concession bidding for greenfield terminal contracts and fleet electrification investments to preempt regulatory compliance deadlines.
Within the global network specialist tier, Menzies Aviation and Swissport International AG exemplify scale-driven positioning across multiple hub airports. SATS Ltd represents the regional cargo-focused archetype with specialized pharmaceutical handling capabilities. These three companies anchor the competitive landscape through differentiated geographic and service segment concentration rather than homogeneous capability portfolios.
| Leading Market Players |
|---|
| Menzies Aviation |
| SATS Ltd |
| Swissport International AG |
| Fraport AG |
| Celebi Aviation Holding |
| Dnata |
| Aviapartner |
| dnata LLC |
| Worldwide Flight Services |
| Others |
Cost & Logistics Intelligence
Full-service carrier procurement departments concentrate buying power through multi-service integrated contracts, compressing margin pools for single-service operators while rewarding handlers with scale across ramp, cargo, and passenger functions. This buyer concentration tilts pricing toward performance-based frameworks with penalty clauses for missed connection windows.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates ground handling contracts, with pharmaceutical cold-chain certification and 90-minute turnaround guarantees commanding top-tier rates. Price differentiation rests on CEIV Pharma certification status and dedicated freighter handling capacity at major sorting hubs. Cost compression in standard-tier ramp services is intensifying because airline procurement departments are consolidating supplier portfolios. Regional cargo-focused operators show highest price sensitivity, while pharmaceutical-certified handlers at Singapore Changi and Frankfurt demonstrate lowest sensitivity due to limited competition.
Supply Chain Analysis
Skilled technician availability in Germany, the Netherlands, and Singapore constrains fleet electrification timelines as maintenance training programs lag behind electric ground support equipment deployment. Battery cell supply draws from East Asian manufacturing clusters, while cold-chain refrigeration components source from European industrial suppliers. Single-source vulnerability in lithium battery supply creates operational risk for handlers accelerating diesel fleet phaseouts. Distribution runs through airport authority concession agreements that lock in multi-year service terms at slot-constrained hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
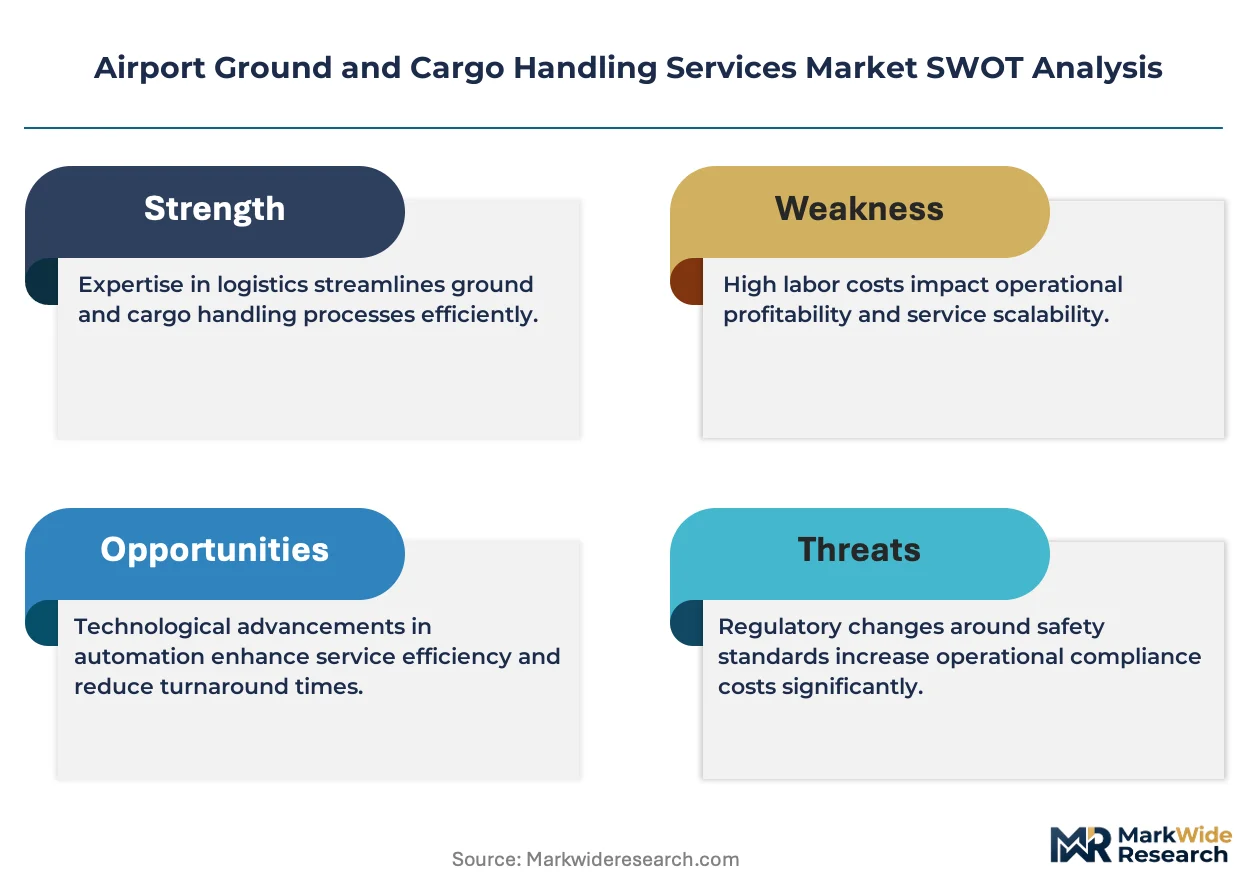
Ground handling operators can exploit geographic arbitrage between EU F-Gas Regulation compliance burdens in Europe and India's airport privatization wave, where capital deployment timelines remain more flexible.
For Market Incumbents: Acquire specialized pharmaceutical handling certifications ahead of EU enforcement deadlines to defend margin pools against emerging cold-chain specialists. Consolidate ramp operations at Frankfurt and Amsterdam to absorb electrification capital burdens from dual equipment and cooling system upgrades. Fleet electrification investments preempt regulatory compliance deadlines and create switching costs for airline customers. For New Entrants and Emerging Players: Secondary city airports in India's privatization pipeline represent underserved buyer concentration with tendering integrated ground handling concessions. Target greenfield terminal developments in Delhi, Mumbai, and Bangalore where legacy infrastructure constraints do not exist. Biometric cargo tracking capability offers a go-to-market angle for technology-enabled handlers seeking first-mover positioning. For Investors and Strategic Acquirers: Airline-captive handling subsidiaries are the most active acquirer in this space, seeking risk-sharing structures for specialized cargo infrastructure. Long-term viability favors handlers with multi-service scale across ramp and cargo functions. Watch autonomous vehicle certification progress in Singapore and Dubai as an inflection indicator for operational efficiency gains.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Program | FAA and EU Green Deal mandates accelerate replacement of diesel-powered tarmac vehicles at major hubs. |
| Pharmaceutical Certification Investment | CEIV Pharma certification at Singapore Changi and Dubai creates entry barriers in temperature-controlled cargo. |
| Autonomous Vehicle Deployment | Amsterdam Schiphol's autonomous tractor fleets reduce fuel burn and vehicle conflict incidents during peak windows. |
| Integrated Service Concession Bidding | India's greenfield terminals in Delhi and Mumbai tender bundled ramp-cargo-passenger contracts. |
| Biometric Cargo Tracking Integration | ICAO standards for digital freight documentation favor handlers with mature IT platform architecture. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ground handling operations directors, airline procurement leads, airport authority concession managers, and cold-chain certification specialists with secondary validation. FAA emissions filings, EASA regulatory notices, IATA resolution databases, and airport authority tender documents anchored supply-side assessment. Bottom-up equipment fleet counts and top-down cargo throughput estimates triangulated market sizing.
Historical reference periods anchored the projection horizon through base-year calibration against reported concession revenues and disclosed fleet compositions. Segmentation modeling tracked service type, technology deployment, customer archetype, and regional regulatory cluster dimensions. CAGRs derived from equipment replacement cycle analysis and e-commerce parcel volume trajectories. Electrification capital deployment schedules and autonomous vehicle certification timelines informed technology adoption curves.
Underlying measurement precision varies by segment; ramp services carry tighter precision than emerging autonomous vehicle deployments due to established reporting conventions. Forecasts reflect assumptions on regulatory enforcement timing and battery supply chain expansion. Material deviation in EU F-Gas Regulation phaseout schedules or lithium battery supply concentration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
France Airport Operations Market
Airport Operations
UK Airport Operations Market
Airport Operations
Global Airside Services Market
Airport Operations
Middle East Airport Operations Market
Airport Operations
Airport Terminal Operations Market
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
Airport Ground Handling Market
Airport Operations
Canada Airport Operations Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
South Korea Airport Operations Market
Airport Operations
Aircraft Ground Handling System Market
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market
Airport Operations
Global Air Charter Services Market
Airport Operations
Airport Operations Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Europe Airport Operations Market