
 France Airport Operations Market | 2026-2036
France Airport Operations Market Size, Share, and Industry Trends Forecast 2026-2036
France Airport Operations Market Insights
The EU Green Deal's aviation emissions framework is consolidating sustainability requirements across French airport operations. Aeroports de Paris leverages its integrated hub model to electrify ground support equipment fleets at Paris-Charles de Gaulle. Vinci anchors civil engineering and concession management capabilities across regional airport upgrades. Air France sustains long-term ground handling partnerships that prioritize emission-reduction metrics in service contracts.
France airport operations encompass the coordinated systems enabling aircraft turnaround, passenger processing, baggage flow, and airside logistics at commercial aviation facilities, requiring compliance with ICAO Annex 14 aerodrome standards and EU SESAR air traffic modernization protocols. Ground handling services dominate operational expenditure pools due to labor intensity and equipment capital requirements, while biometric systems represent the fastest-expanding technology segment as facial recognition boarding gates proliferate at major terminals. Baggage handling systems retain mature infrastructure status with replacement cycles driven by RFID tracking mandates rather than greenfield deployment.
France's national civil aviation authority, the DGAC, enforces operational safety certifications under EASA oversight, while EU F-Gas Regulation phases constrain refrigerant choices in airport HVAC and ground vehicle climate systems. The CSRD disclosure requirements now extend sustainability reporting obligations to major airport concessionaires, reshaping procurement specifications for service providers. Stakeholders must monitor DGAC's implementation timeline for drone integration corridors around Parisian airports, as unmanned aerial system traffic management will reshape airspace allocation and ground risk protocols.
Market Dynamics
The EU Green Deal's aviation emissions framework is compressing operational timelines for French airport operators, forcing simultaneous fleet electrification and infrastructure reinvestment across Parisian hubs and regional terminals. Ground handling service providers face binding emission-reduction clauses in concession contracts that reshape procurement priorities.
Growth Catalysts
- CSRD disclosure mandates:Sustainability reporting obligations now extend to major airport concessionaires, creating standardized procurement specifications for low-emission ground support equipment across French terminals.
- Île-de-France corridor demand:Passenger traffic recovery and cargo expansion at Paris-Charles de Gaulle and Orly are driving infrastructure reinvestment and service capacity expansion.
- Biometric boarding gates:Facial recognition systems are proliferating at major terminals, reducing processing times and labor requirements in passenger handling operations.
Market Restraints
- Labor cost intensity:Ground handling services require substantial workforce deployment, constraining margin flexibility during collective bargaining cycles in French aviation.
- Equipment capital requirements:Fleet electrification demands heavy investment in electric ground support vehicles and charging infrastructure at aging regional airports.
- F-Gas Regulation phase-downs:EU constraints on refrigerant choices limit HVAC system upgrades and ground vehicle climate control options, complicating equipment procurement.
Strategic Opportunities
- Drone integration corridors:DGAC's unmanned aerial system traffic management implementation around Parisian airports will reshape airspace allocation and create new ground risk protocol services.
- RFID tracking mandates:Baggage handling system replacement cycles are accelerating as tracking requirements modernize legacy infrastructure across French terminals.
- Regional airport upgrades:Vinci's concession management capabilities anchor civil engineering projects at underserved provincial hubs outside the Île-de-France corridor.
Industry Challenges
- Skilled technician shortages:Electrified ground support equipment maintenance requires specialized training programs that outpace current vocational pipeline output in French aviation.
- Legacy system integration:Biometric passenger processing systems must interface with existing security architectures, creating interoperability testing burdens at major terminals.
- Concession timeline compression:Sustainability retrofit obligations overlap with standard infrastructure renewal cycles, straining capital allocation across multi-year planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Airport Operations Market |
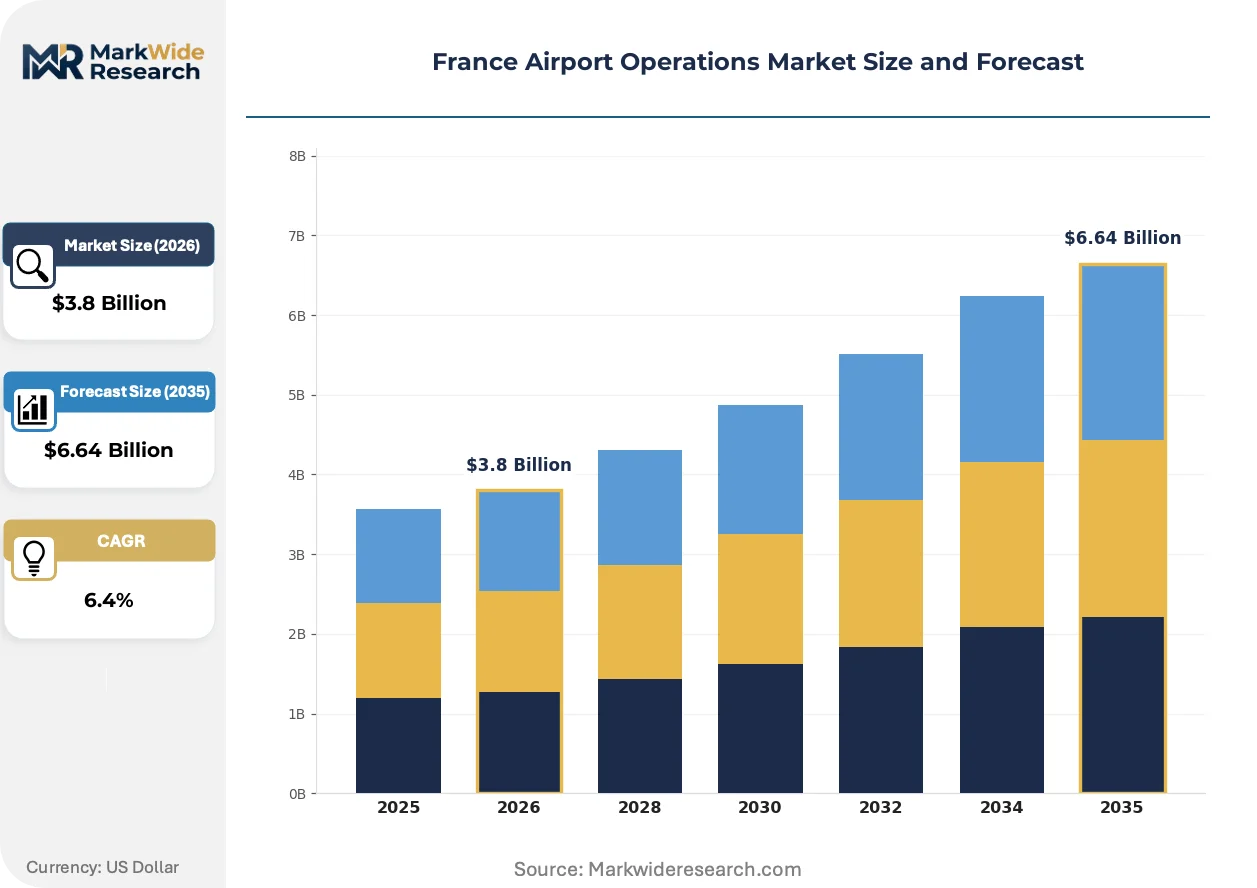
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ground Handling, Air Traffic Control, Security Services, Maintenance Services Technology: Biometric Systems, Baggage Handling Systems, Communication Systems, Monitoring Software End User: Airlines, Government Agencies, Cargo Operators, Service Providers Application: Passenger Management, Baggage Management, Cargo Management, Security Management |
| Companies Covered | Aeroports de Paris, Aeroports de la Cote d'Azur, Vinci, Groupe ADP International, Air France, Zurich Airport Company, Adani Airports, easyJet, La Poste, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Airport Operations Market Trends and Innovations
Operational digitization and emission-monitoring technologies are restructuring service delivery models across French airport operations. Ground handling providers now compete on real-time carbon accounting capabilities alongside traditional turnaround metrics.
Electric ground support equipment is expanding into de-icing, cargo loading, and aircraft pushback functions previously dominated by diesel fleets. Air France-KLM's low-emission mandates are accelerating adoption timelines at Paris-Charles de Gaulle and Orly hubs. This electrification wave is compressing the operational lifespan of legacy diesel fleets and forcing accelerated capital redeployment among independent ground handlers.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerant availability for airport HVAC and ground vehicle climate systems. Equipment manufacturers must redesign thermal management systems using alternative refrigerants or natural cooling methods. French terminal operators are responding by bundling HVAC modernization with broader energy efficiency retrofits to minimize disruption.
Airlines now specify emission-reduction metrics as primary evaluation criteria in ground handling service contracts, displacing price-per-turnaround as the dominant selection factor. This behavioral shift concentrates contract awards among handlers with verified electrified fleets and carbon reporting infrastructure. The Île-de-France corridor exhibits the most pronounced procurement transformation, where Air France's contract structures set benchmarks for regional airport negotiations.
France Airport Operations Market Segmentation
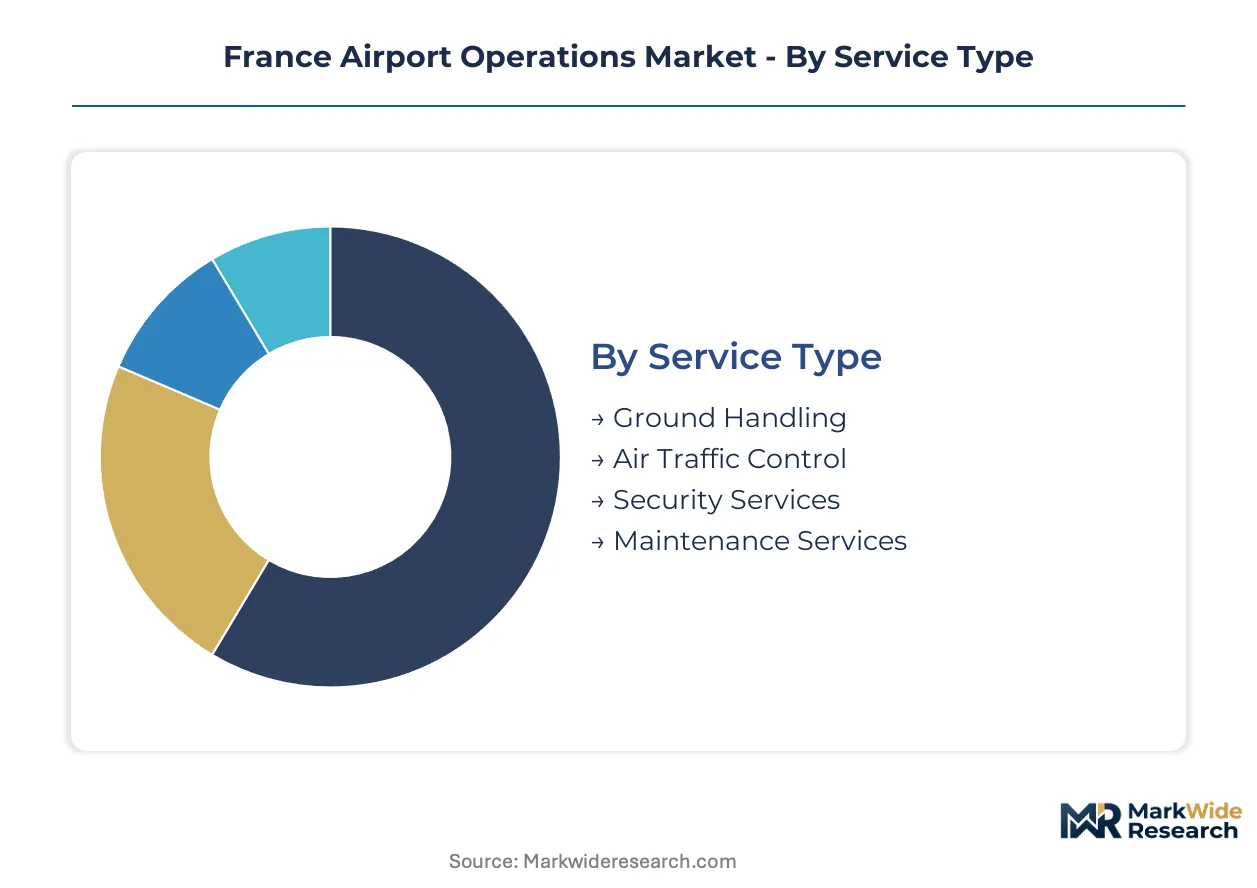
France airport operations segment along four operational dimensions that determine capital deployment priorities and regulatory exposure. Service type dictates labor intensity and equipment requirements, while technology selection shapes compliance with EU Green Deal mandates. End user concentration in the Île-de-France corridor drives infrastructure investment patterns across the market.
Service Type:
Capital intensity varies sharply across service categories, with equipment-heavy segments requiring multi-year investment horizons and specialized certification pathways.
- Ground Handling:Aircraft turnaround services encompass passenger boarding, cargo loading, and aircraft pushback operations using specialized electric ground support vehicles. Paris-Charles de Gaulle and Orly hubs concentrate demand as Air France-KLM mandates accelerate fleet electrification and emission-reduction clauses reshape procurement contracts.
- Air Traffic Control:Airspace management and approach sequencing systems coordinate aircraft movements under DGAC oversight with EASA certification requirements. The Île-de-France corridor absorbs the bulk of technology refresh spending as unmanned aerial system integration corridors reshape airspace allocation protocols.
- Security Services:Passenger and baggage screening operations including explosive detection and access control enforcement.
- Maintenance Services:Runway infrastructure, lighting systems, and terminal facility upkeep requiring continuous operational readiness.
Ground handling absorbs the bulk of installed capacity; air traffic control is expanding most quickly.
Technology:
Technology adoption patterns reflect the tension between legacy infrastructure replacement and greenfield digital deployment across French terminals.
- Biometric Systems:Facial recognition boarding gates and identity verification platforms reduce passenger processing times and labor requirements. Major terminals at Paris-Charles de Gaulle and Orly drive deployment as interoperability testing with existing security architectures creates implementation burdens.
- Baggage Handling Systems:Conveyor networks and automated sorting infrastructure manage passenger luggage flow with RFID tracking integration. RFID mandates from airlines and regulatory bodies accelerate replacement cycles at aging regional airports outside the Île-de-France corridor.
- Communication Systems:Voice and data networks connecting airside and landside operations including ground-to-air links.
- Monitoring Software:Real-time operational dashboards and predictive maintenance platforms for equipment fleet management.
Baggage handling systems retain the largest installed base; biometric systems are climbing the fastest.
End User:
End user procurement authority determines contract structure, with concession-based operators facing distinct sustainability reporting obligations under CSRD mandates.
- Airlines:Commercial carriers contract ground handling and passenger services with emission-reduction metrics now displacing price-per-turnaround as primary evaluation criteria. Air France structures long-term partnerships that prioritize verified electrified fleets and carbon reporting infrastructure across Parisian hubs.
- Government Agencies:DGAC and national security authorities enforce operational certifications and airspace management protocols under EASA oversight frameworks.
- Cargo Operators:Freight carriers and logistics integrators managing air cargo flows through dedicated terminals.
- Service Providers:Independent ground handlers and specialized contractors competing on real-time carbon accounting capabilities.
Airlines command the largest procurement volume; government agencies are gaining share fastest through regulatory mandate expansion.
Application:
Application segmentation tracks operational workflows from passenger arrival through aircraft departure, with each domain carrying distinct technology refresh cycles.
- Passenger Management:Check-in, boarding, and lounge operations integrating biometric verification and queue optimization systems. Paris-Charles de Gaulle concentrates investment as terminal modernization projects align with Air France hub requirements.
- Baggage Management:End-to-end luggage tracking from check-in through reclaim with RFID and automated handling integration.
- Cargo Management:Freight processing, customs coordination, and cold chain logistics for pharmaceutical and perishable shipments.
- Security Management:Access control, perimeter monitoring, and threat detection systems under DGAC safety certifications.
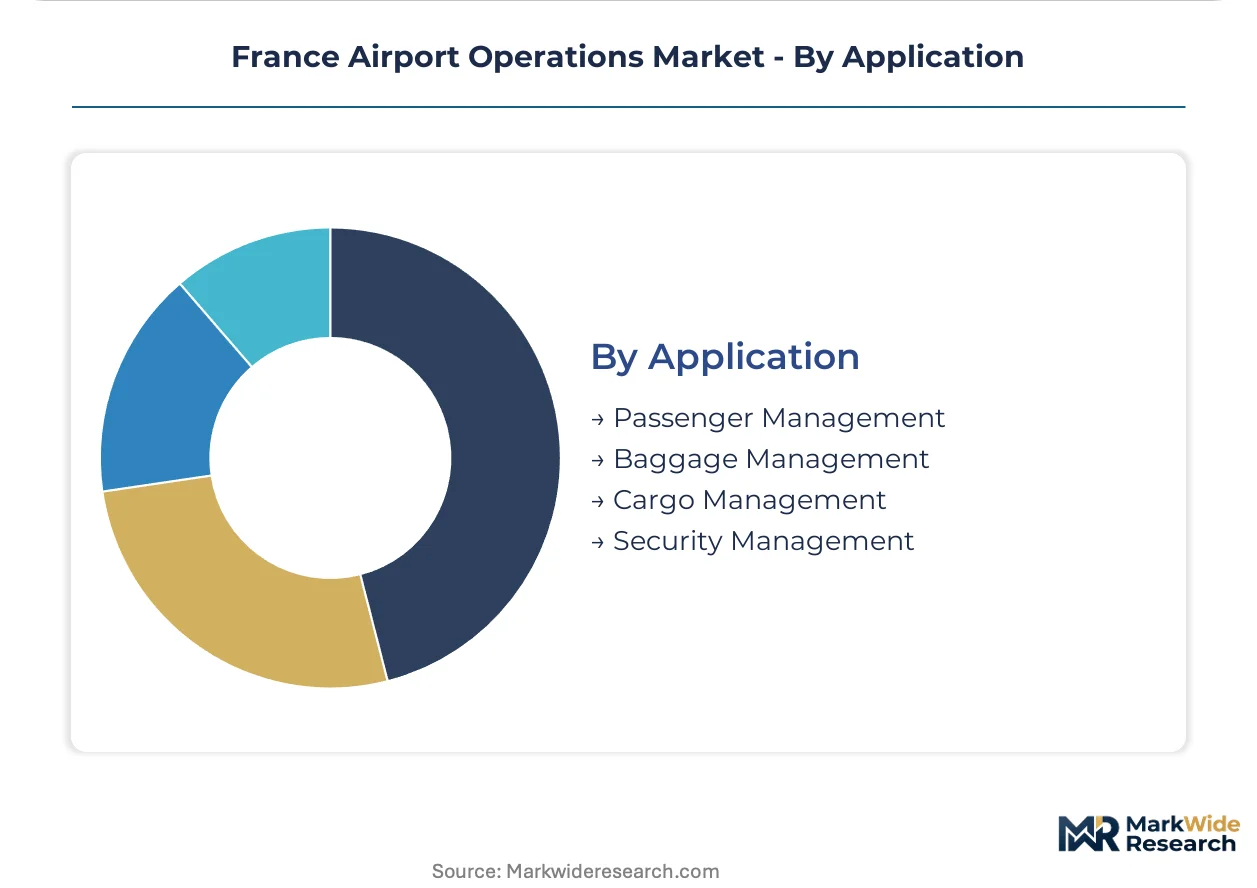
Passenger management dominates current infrastructure spending; cargo management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Île-de-France corridor concentrates France's airport operations activity, with Paris-Charles de Gaulle and Orly hubs driving infrastructure reinvestment and service capacity expansion. Passenger traffic recovery and cargo growth are reshaping procurement priorities across the region.
Île-de-France
Paris-Charles de Gaulle and Orly airports absorb the bulk of ground handling electrification mandates as Air France-KLM imposes low-emission clauses on service contracts. The DGAC enforces operational safety certifications under EASA oversight across both hubs. Biometric boarding gates and RFID baggage tracking systems are proliferating through terminal modernization projects concentrated in Roissy and Orly.
Auvergne-Rhône-Alpes
Lyon-Saint-Exupéry Airport anchors cargo expansion and regional connectivity demand in France's second-largest metropolitan area. The EU Green Deal's aviation emissions targets are reshaping ground handling procurement specifications at the facility. Vinci's civil engineering capabilities support infrastructure upgrades across the Greater Lyon aviation cluster.
Provence-Alpes-Côte d'Azur
Nice Côte d'Azur Airport and Marseille Provence handle seasonal passenger surges and yachting-industry private aviation traffic that strain ground service capacity. Aeroports de la Cote d'Azur manages concession operations under CSRD disclosure mandates that extend sustainability reporting obligations. The Mediterranean corridor is integrating drone corridor planning into airspace management protocols ahead of DGAC implementation timelines.
Hauts-de-France
Lille Airport and regional terminals face equipment capital requirements for fleet electrification that outstrip aging infrastructure replacement budgets. The EU F-Gas Regulation phases constrain HVAC system upgrades and ground vehicle climate control options at these facilities. Vinci anchors civil engineering projects addressing capacity constraints across underserved provincial hubs in the northern corridor.
Nouvelle-Aquitaine
Bordeaux-Mérignac Airport and Biarritz-Pays Basque support wine export cargo flows and tourism-driven seasonal demand patterns. Ground handling service providers compete on real-time carbon accounting capabilities alongside traditional turnaround metrics at these facilities. The southwestern cluster is accelerating baggage handling system replacement cycles driven by airline RFID tracking mandates rather than greenfield deployment.
France Airport Operations Market Competitive Landscape
The competitive structure tilts toward integrated hub operators with concession management capabilities. Aeroports de Paris leverages its dual-airport dominance to standardize electrification requirements across ground handling contracts. Two strategic archetypes define the field: state-linked concession holders with civil engineering integration, and airline-affiliated service providers with emission-reduction mandates embedded in procurement. Dominant competitive moves include fleet electrification partnerships and sustainability reporting infrastructure deployment.
Within the integrated concession tier, Aeroports de Paris exemplifies hub-scale standardization of low-emission ground support requirements. Vinci occupies a position bridging civil engineering execution and airport concession management across regional facility upgrades. Air France represents the airline-affiliated archetype, anchoring long-term ground handling partnerships that prioritize verified electrified fleets and carbon reporting infrastructure. These three entities collectively shape procurement benchmarks that cascade to independent handlers throughout the French terminal network.
| Leading Market Players |
|---|
| Aeroports de Paris |
| Aeroports de la Cote d'Azur |
| Vinci |
| Groupe ADP International |
| Air France |
| Zurich Airport Company |
| Adani Airports |
| easyJet |
| La Poste |
| Others |
Pricing and Supply Chain Analysis
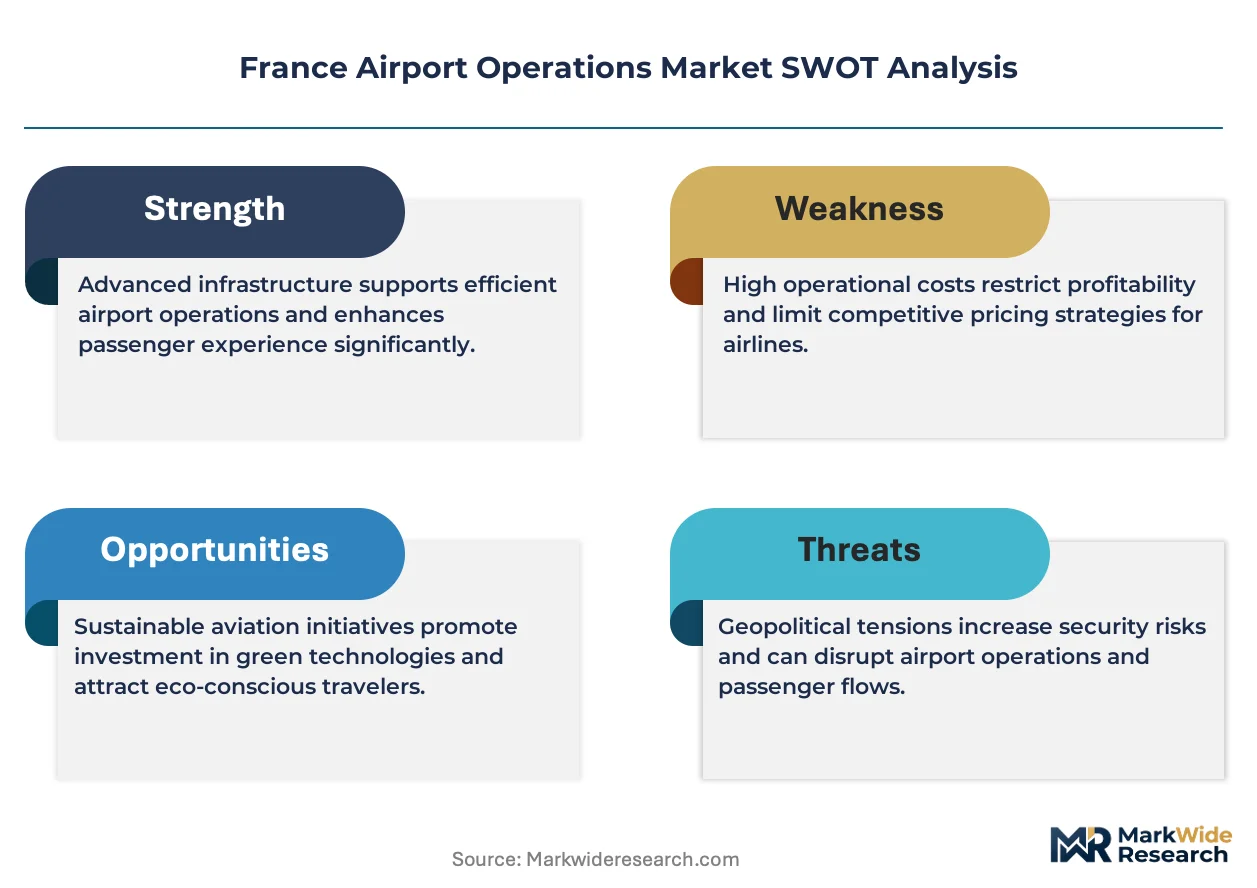
State-linked concession holders with integrated civil engineering capabilities anchor supply-side discipline across French airport operations, translating CSRD-mandated sustainability reporting into procurement specifications that compress margin flexibility for independent ground handlers. Their balance-sheet capacity absorbs fleet electrification capital requirements that price out smaller competitors, concentrating contract awards among operators with verified carbon accounting infrastructure.
Pricing Analysis
Outcome-based pricing tied to aircraft turnaround time and emission-reduction metrics now dominates ground handling contracts at Paris-Charles de Gaulle and Orly. Three-tier pricing structure across premium electrified fleets, standard mixed fleets, and economy diesel-based services reflects certification grade and real-time carbon reporting capabilities. Pricing pressure stems from Air France-KLM's low-emission mandates compressing operational timelines for equipment-heavy segments. Regional airports outside Île-de-France exhibit highest price sensitivity due to constrained infrastructure replacement budgets.
Supply Chain Analysis
Dual-sourcing requirements for electric ground support equipment mandate multi-supplier qualification across German, Italian, and Spanish manufacturers to mitigate single-source vulnerability. Equipment procurement draws from specialized automotive battery suppliers in South Korea and Japan, alongside HVAC component providers constrained by EU F-Gas Regulation phase-downs. Supply chain risk centers on logistics chokepoints for lithium-ion battery transport to aging regional terminals. Distribution runs through Aeroports de Paris's consolidated hub procurement, with Vinci anchoring civil engineering subcontractor networks across provincial upgrades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France airport operations market reads as a cost-of-compliance story where EU Green Deal aviation emissions targets and CSRD disclosure mandates erect barrier-to-entry moats favoring concessionaires with pre-built sustainability reporting infrastructure.
For Market Incumbents: Hedge against margin compression by accelerating backward integration into electric ground support equipment maintenance capabilities and securing long-term technician training partnerships with French vocational institutes. The skilled technician shortage for electrified fleets threatens service-level agreements, while concession timeline compression strains capital allocation across overlapping retrofit and renewal cycles. For New Entrants and Emerging Players: Begin with white-space targeting of drone integration corridor services around Parisian airports as DGAC unmanned aerial system traffic management implementation reshapes airspace allocation protocols. Regional baggage handling system replacement cycles at aging provincial terminals outside Île-de-France offer the most penetrable entry point, with RFID tracking mandate compliance as the primary go-to-market credential. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap ground handlers with partial electrified fleets in Auvergne-Rhône-Alpes and Nouvelle-Aquitaine facing capital constraints from overlapping regulatory obligations. Long-term viability hinges on concession renewal positioning across the next planning horizon. Monitor Air France-KLM contract renegotiation timelines as the critical inflection signal for procurement benchmark shifts cascading to regional airports.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Air France-KLM mandates accelerate verified low-emission ground support deployment across Parisian hubs. |
| CSRD Reporting Infrastructure | Sustainability disclosure capabilities reshape procurement specifications for major airport concessionaires under EU mandates. |
| Drone Corridor Integration | DGAC unmanned aerial system traffic management creates new ground risk protocol service revenue streams. |
| RFID Tracking Modernization | Airline baggage mandates accelerate replacement cycles at aging regional terminals outside Île-de-France. |
| Technician Training Pipeline | Specialized electrified equipment maintenance programs address skilled labor scarcity constraining fleet expansion. |
Research Methodology
Independent corroboration across DGAC regulatory filings, Aeroports de Paris concession disclosures, and EU SESAR deployment documentation underwrites the qualitative findings in this study. Primary interviews with ground handling operations directors, airport procurement managers, and electric vehicle fleet managers combined with secondary validation from EASA certification records, Vinci infrastructure project announcements, and Air France-KLM sustainability reports. Bottom-up service provider capacity assessments and top-down concession revenue analysis establish segment sizing.
Rate-of-change decomposition across the projection horizon separates traffic recovery velocity from equipment replacement cycles and regulatory compliance timelines. Segmentation dimensions modeled include service type, technology adoption stage, end-user procurement authority, and regional infrastructure maturity. CAGRs derive from equipment deployment trajectories under EU Green Deal mandates and passenger throughput recovery patterns. Forecast inputs incorporate CSRD implementation timelines and F-Gas Regulation phase-down schedules.
Underlying measurement precision varies by segment; ground handling electrification metrics carry tighter precision than drone corridor planning estimates where DGAC implementation timelines remain provisional. Forecasts reflect assumptions around Air France-KLM contract structure durability and regional airport concession renewal sequencing. Deviation in EU aviation emissions target acceleration or CSRD scope expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
Business Jet Ground Handling Services Market
Airport Operations
UK Airport Operations Market
Airport Operations
Canada Airport Operations Market
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
Airport Terminal Operations Market
Airport Operations
Airport Ground Handling Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market
Airport Operations
Europe Airport Operations Market
Airport Operations
South Korea Airport Operations Market
Airport Operations
Aircraft Ground Handling System Market
Airport Operations
Airport Operations Market
Airport Operations
Global Air Charter Services Market
Airport Operations
Global Airside Services Market
Airport Operations
Middle East Airport Operations Market