
 Global Non-Aeronautical Market | 2026-2036
Global Non-Aeronautical Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Aeronautical Market Foresight
Project finance tied to long-term concession leases is narrowing the competitive field to operators with balance-sheet depth. Vinci SA leverages its integrated construction-concession model to secure multi-decade retail and parking contracts across Europe and the Americas. Fraport Group anchors its non-aeronautical expansion through in-house real estate development and hospitality verticals at Frankfurt and its international portfolio airports. AENA SME SA sustains margin resilience by controlling advertising and commercial space allocation across Spain's coordinated airport network.
Non-aeronautical revenue encompasses all commercial income generated by airport operators independent of airline landing fees, passenger charges, and cargo handling tariffs, spanning retail concessions, car parking, real estate leasing, and hospitality services that monetize captive passenger dwell time and airport zone accessibility. Revenue Stream segmentation shows retail concessions and real estate leasing commanding the deepest margin pools due to fixed-rent structures and passenger-volume-linked variable components, while ground transportation and car parking face pressure from ride-hailing substitution and urban transit expansion. Service Type dynamics reveal duty-free shops and food and beverage outlets as the highest-frequency touchpoints, with VIP lounges and airport hotels capturing premium spend from business travelers and long-haul transfer passengers.
FDA guidelines on food safety and labeling apply to airport hospitality operations in the United States, while EFSA standards and EU Green Deal carbon accounting requirements shape concession procurement and energy use across European airports. China's SAMR oversees retail pricing transparency and consumer protection at domestic hubs, and Japan's METI coordinates airport commercial zone development through public-private partnership frameworks. Stakeholders must monitor how biometric identification and automated retail technologies alter passenger flow patterns and concession yield calculations.
Market Dynamics
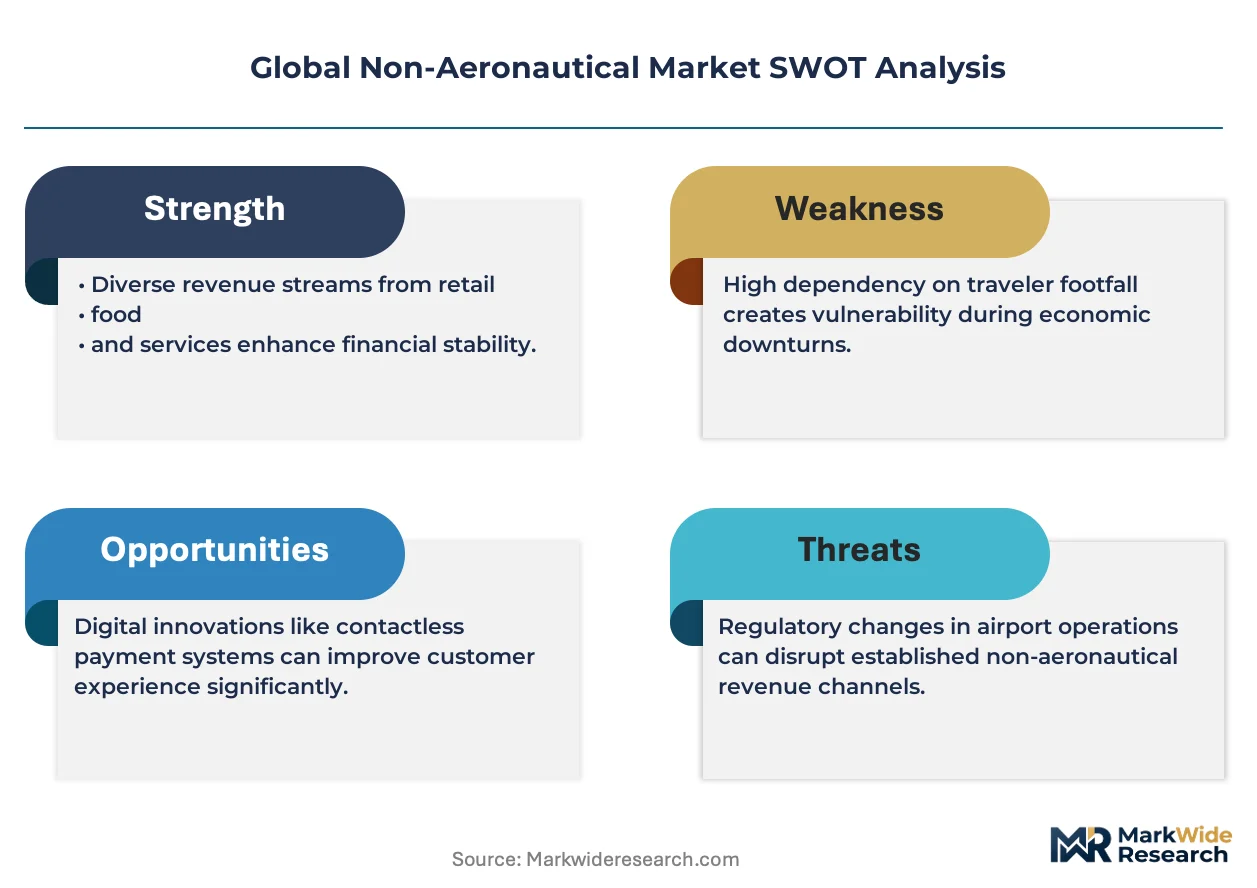
Biometric boarding technologies and automated retail systems are compressing passenger processing times while extending monetizable dwell windows, fundamentally altering how concession economics operate across major international hubs.
Growth Catalysts
- EU Green Deal carbon accounting:European airports now mandate low-carbon procurement for concession operations, creating competitive differentiation for operators with verified supply chain emissions data.
- Digital payment integration:Contactless and biometric payment rails at Dubai, Singapore Changi, and Heathrow are reducing transaction friction and lifting average spend per passenger in duty-free zones.
- Transfer passenger volumes:Long-haul hub strategies at Doha Hamad, Istanbul, and Addis Ababa are deliberately engineering extended connection times to maximize non-aeronautical capture.
Market Restraints
- Ride-hailing substitution:Uber and Didi penetration in urban catchment zones is compressing parking revenue yields at secondary airports in the United States and Western Europe.
- Construction cost escalation:Steel and specialized glazing for retail atrium developments have seen input volatility, stretching project finance timelines for greenfield terminal expansions.
- SAMR pricing transparency mandates:China's State Administration for Market Regulation now requires real-time price disclosure for duty-free goods, limiting margin flexibility at domestic hubs.
Strategic Opportunities
- India's airport privatization wave:The Airports Authority of India concession program for brownfield terminals in Lucknow, Jaipur, and Guwahati opens retail and hospitality development to private operators.
- Automated retail kiosks:Computer vision-enabled grab-and-go stores are eliminating checkout friction in high-traffic gate areas, with early deployment at Amsterdam Schiphol and Tokyo Haneda.
- Japan's METI public-private frameworks:Coordinated commercial zone development at Kansai and Fukuoka airports offers long-term lease structures with revenue-sharing mechanisms favorable to hospitality investors.
Industry Challenges
- Biometric data governance:GDPR compliance for facial recognition payment systems requires specialized legal and IT infrastructure that smaller concession operators struggle to resource.
- Legacy POS integration:Harmonizing new automated retail backends with existing duty-free inventory management systems at established hubs creates deployment delays and cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Aeronautical Market |
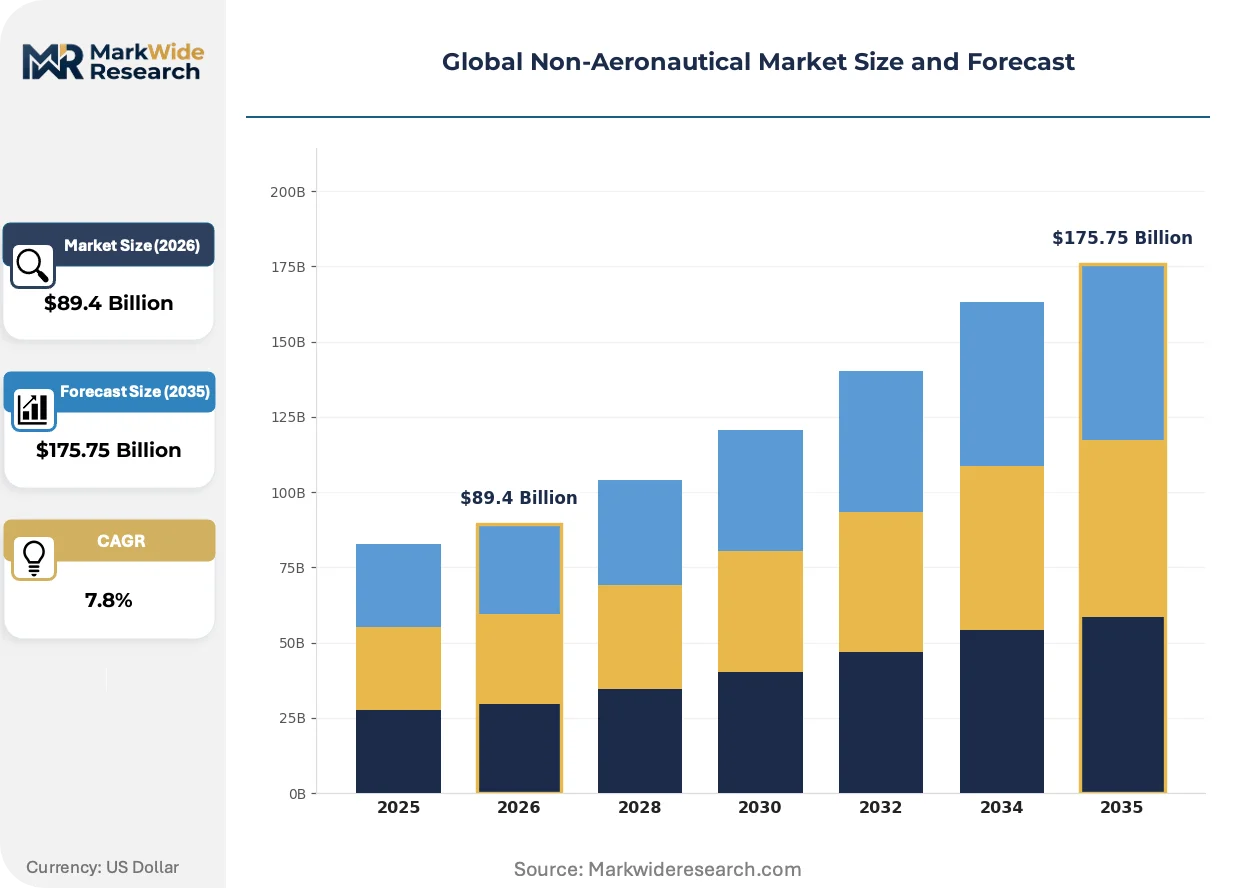
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $175.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Revenue Stream: Retail Concessions, Real Estate Leasing, Advertising Services, Car Parking, Hospitality & Catering, Ground Transportation Service Type: Duty-Free Shops, Food & Beverage Outlet, VIP Lounges, Car Rental Services, Airport Hotels, Event Management Customer Type: Business Travelers, Leisure Passengers, Airport Staff, Local Commuters, Tour Operators, Cargo Handlers Channel: On-Site Sales, Online Booking, Third-Party Vendors, Mobile Applications, Automated Kiosks, Call Centers |
| Companies Covered | AENA SME SA, GROUPE ADP, Airport Authority Hong Kong, Airports of Thailand Plc, Fraport Group, London Heathrow Airports Limited, Japan Airport Terminal Co. Ltd, Vinci SA, Korea Airports Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Aeronautical Market Shifts & Advancements
Retail concession models are pivoting from static lease structures toward dynamic yield-management systems that adjust space allocation and product mix in real time based on flight schedules and passenger demographics.
Computer vision inventory tracking is migrating from pilot installations at Dubai International to standard deployment across major hubs. Changi Airport Group has adopted shelf-mounted cameras that monitor stock levels and shopper dwell patterns automatically. This capability is compressing replenishment cycles from hours to minutes while enabling automated dynamic pricing for perishable food and beverage categories.
EFSA standards for food contact materials and the EU Green Deal's embodied carbon disclosure requirements are reshaping concession procurement specifications across European airports. Operators must now document supply chain emissions for packaged goods and demonstrate recyclability compliance for food service ware. Frankfurt and Amsterdam have moved earliest, requiring tier-one suppliers to submit third-party verified lifecycle assessments as a condition of contract renewal.
Passenger booking behavior now favors pre-ordered duty-free collection over impulse terminal purchases, particularly among Chinese and South Korean outbound travelers. Duty-free operators at Heathrow, Charles de Gaulle, and Incheon have responded by integrating mobile app reservation systems with departure gate logistics, compressing fulfillment windows to under ten minutes from order to collection. This shift is most pronounced on high-value fragrance and cosmetics categories where price comparison shopping occurs pre-departure.
Global Non-Aeronautical Market Segmentation
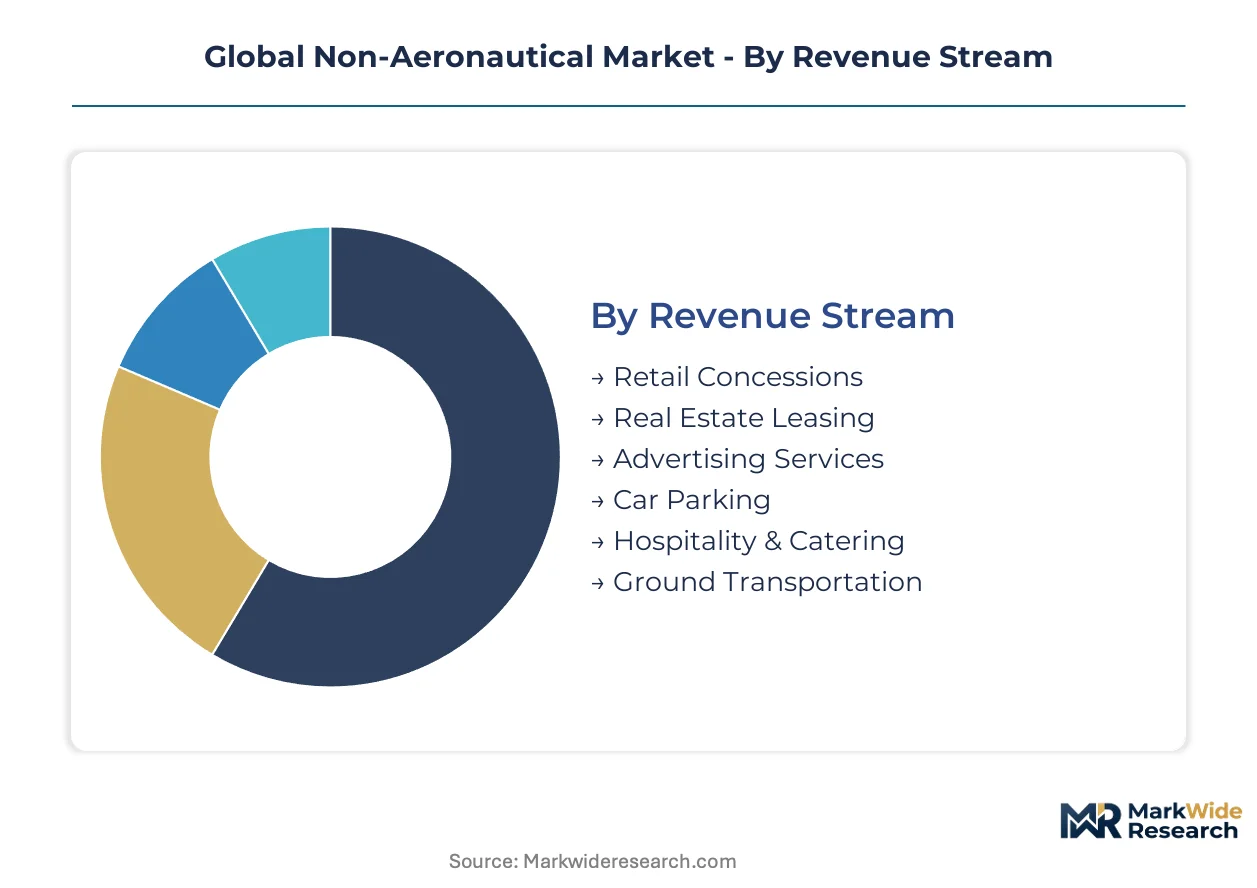
Non-aeronautical revenue segmentation determines how airport operators allocate capital across concession portfolios. Each dimension—revenue stream, service type, customer profile, and channel—reveals distinct margin structures and capital intensity requirements that shape operator strategy.
Revenue Stream:
Cost tier differentiation separates fixed-rent concessions from volume-linked variable income, determining balance sheet exposure and cash flow predictability for airport operators.
- Retail Concessions:Duty-free and specialty retail leases generate fixed base rents plus passenger-volume-linked percentage rents. Dubai International and Heathrow anchor global yield benchmarks through luxury brand clustering in dedicated retail atriums.
- Real Estate Leasing:Long-term commercial property development within airport zones—offices, logistics facilities, and mixed-use—delivers institutional-grade income streams with 15-25 year lease tenors. Frankfurt and Amsterdam Schiphol have expanded this category through dedicated airport cities.
- Advertising Services:Digital screen networks and static installations monetize passenger circulation patterns. Revenue concentrates at high-dwell transfer hubs with extended connection windows.
- Car Parking:Short-stay premium and long-stay economy products face structural pressure from ride-hailing substitution in dense urban catchments. Yield management systems now govern dynamic pricing.
- Hospitality & Catering:Food courts, full-service restaurants, and grab-and-go formats operate on turnover-based concession agreements with minimum rent guarantees.
- Ground Transportation:Bus, coach, and rail concessions provide regulated public service obligations alongside commercial express services to city centers.
Retail Concessions holds installed capacity. Real Estate Leasing is rotating up the share rankings.
Service Type:
Application focus distinguishes high-frequency, low-margin throughput services from premium, reservation-based experiences targeting specific passenger segments.
- Duty-Free Shops:Liquor, tobacco, and luxury goods sales operate under strict customs-controlled zones with pricing advantages over domestic retail. Pre-order mobile integration is compressing fulfillment windows at Incheon and Charles de Gaulle.
- Food & Beverage Outlet:Quick-service, casual dining, and bar concepts dominate passenger dwell zones. Computer vision-enabled grab-and-go formats are eliminating checkout friction at Amsterdam Schiphol and Tokyo Haneda.
- VIP Lounges:Pay-per-use and membership-based premium spaces capture high-yield business travelers with extended dwell. Independent lounge networks now compete with airline-operated facilities.
- Car Rental Services:On-airport consolidated rental centers and off-airport shuttle-dependent operations serve different passenger value segments with distinct land use requirements.
- Airport Hotels:Transit properties, day-use rooms, and conference facilities target crew, misconnect, and business meeting demand. Revenue per available room exceeds comparable urban properties at major hubs.
- Event Management:Terminal and airside venue hire for product launches, filming, and private functions monetizes dormant capacity during low-traffic periods.
Food & Beverage Outlet commands transaction frequency. VIP Lounges is gaining share fastest among premium service tiers.
Customer Type:
Volume concentration varies dramatically by passenger purpose, with transfer behavior and dwell time determining non-aeronautical capture potential.
- Business Travelers:Premium spend concentration in lounges, express services, and convenience retail. This segment shows highest propensity for automated retail and biometric payment adoption.
- Leisure Passengers:Price-sensitive duty-free purchasers with extended pre-departure dwell. Pre-order behavior is most pronounced among Chinese and South Korean outbound travelers.
- Airport Staff:Recurring food service and convenience retail demand with distinct pricing expectations and access patterns separate from passenger flows.
- Local Commuters:Rail and metro interchange passengers using airport facilities as transport nodes with minimal commercial engagement.
- Tour Operators:Block-booked ground transportation and hospitality services with negotiated rates and coordinated arrival patterns.
- Cargo Handlers:Specialized food service and logistics support demand concentrated at freighter hubs with 24-hour operations.
Leisure Passengers holds installed capacity. Business Travelers is rotating up the share rankings.
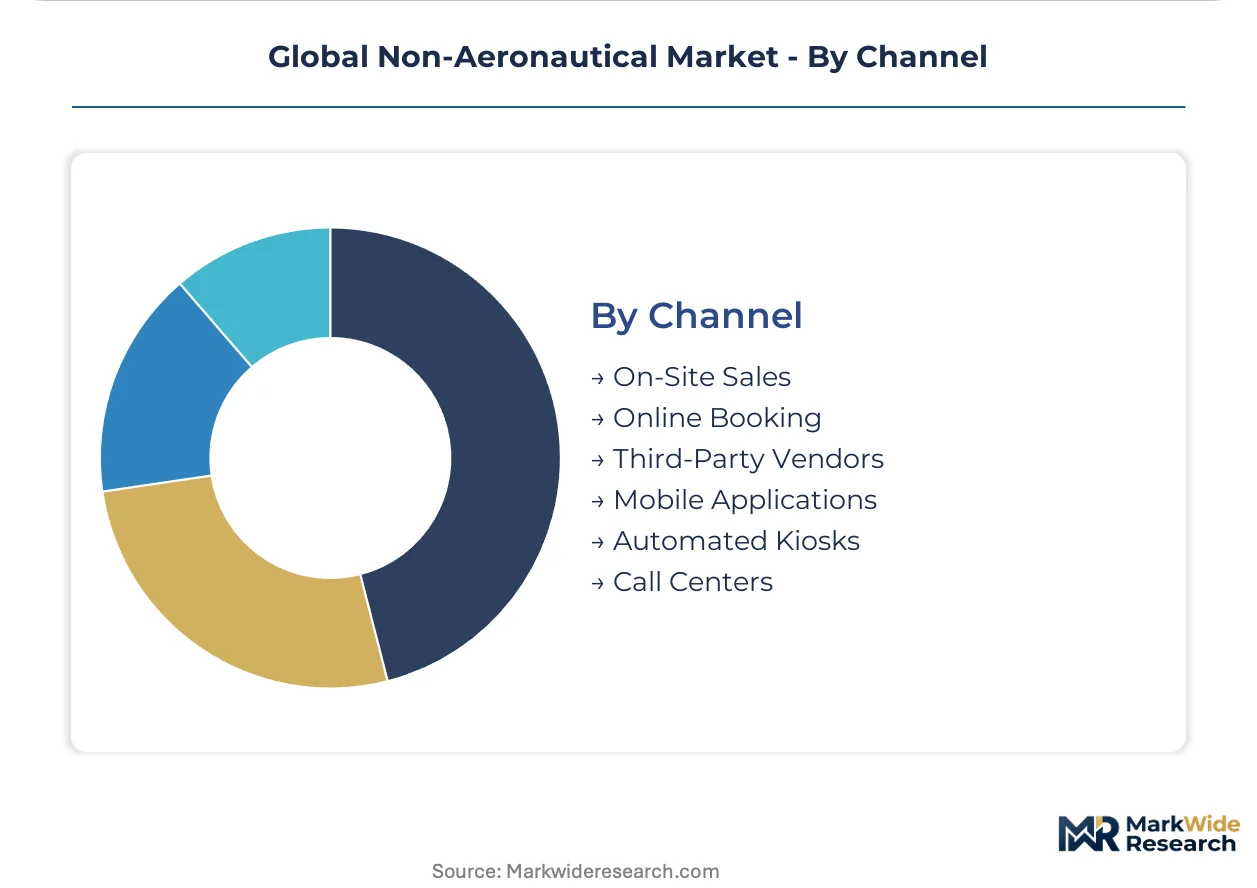
Channel:
Supply concentration is shifting from physical point-of-sale toward digitally intermediated transactions that reshape inventory and fulfillment economics.
- On-Site Sales:Traditional walk-up concession transactions remain dominant for impulse categories and immediate-need food service. Physical retail footprint still governs space allocation decisions.
- Online Booking:Pre-departure reservation of parking, lounges, and duty-free collection compresses terminal dwell friction. Mobile app penetration is highest among Chinese and South Korean travelers.
- Third-Party Vendors:Aggregator platforms and airline partnership channels extend concession reach beyond airport-operated touchpoints with revenue-sharing arrangements.
- Mobile Applications:Integrated payment, wayfinding, and ordering platforms now standard at Dubai, Singapore Changi, and Heathrow.
- Automated Kiosks:Self-service retail and food ordering reduce labor dependency and extend service hours. Deployment concentrates in gate areas with high passenger density.
- Call Centers:Legacy reservation channel for group bookings, accessibility services, and complex itinerary modifications with declining share.
On-Site Sales holds installed capacity. Mobile Applications is climbing the fastest among digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed airport privatization programs and sustainability mandates are redirecting capital toward non-aeronautical infrastructure across major aviation markets. National regulators in China, the United Arab Emirates, and the United Kingdom have issued procurement guidelines favoring concession operators with verified carbon accounting. Mega-hub expansions in these jurisdictions are extending passenger dwell times and expanding monetizable commercial zones.
China
SAMR pricing transparency mandates now require real-time duty-free cost disclosure at domestic hubs, compressing margin flexibility for concession operators. The regulator's consumer protection framework shapes procurement terms for retail tenants at Beijing Capital and Shanghai Pudong. Airport cities in the Yangtze River Delta are integrating mixed-use real estate development with terminal expansions.
United Arab Emirates
Dubai's biometric payment rails and contactless transaction infrastructure are lifting average spend per passenger in duty-free zones. The country's central aviation authority coordinates concession economics across Dubai International and Al Maktoum. Mega-retail atriums at these facilities anchor global yield benchmarks for luxury brand clustering.
United Kingdom
Heathrow's mobile app reservation systems for pre-ordered duty-free collection compress fulfillment windows to under ten minutes. EFSA standards and EU Green Deal carbon accounting requirements shape concession procurement specifications despite post-Brexit regulatory divergence. London's coordinated airport network maintains advertising and commercial space allocation discipline.
Japan
METI public-private partnership frameworks coordinate commercial zone development at Kansai and Fukuoka airports through revenue-sharing mechanisms favorable to hospitality investors. The ministry's long-term lease structures attract balance-sheet-deep operators. Tokyo Haneda's computer vision-enabled grab-and-go formats are eliminating checkout friction in high-traffic gate areas.
Germany
Frankfurt's in-house real estate development and hospitality verticals anchor non-aeronautical expansion through dedicated airport city construction. EFSA food contact material standards and embodied carbon disclosure requirements mandate third-party verified lifecycle assessments from tier-one suppliers. The Rhine-Main cluster concentrates Europe's deepest margin pools for fixed-rent retail concessions.
Global Non-Aeronautical Market Competitive Landscape
On the supply side, the industry is consolidating around integrated construction-concession operators with multi-decade balance sheet capacity. Project finance tied to long-term leases narrows the competitive field to entities capable of sustaining 15-25 year capital commitments. Two archetypes dominate: vertically integrated infrastructure conglomerates that self-perform terminal construction, and specialized airport real estate developers with hospitality verticals. Competitive positioning hinges on securing brownfield concession renewals and deploying automated retail technologies without legacy POS integration burdens.
Within the integrated infrastructure tier, Vinci SA exemplifies the construction-concession model through European and American retail and parking contracts. Fraport Group occupies a position as an in-house real estate developer with dedicated airport city strategies. AENA SME SA represents network-coordinated commercial space allocation across Spain's coordinated airport system.
| Leading Market Players |
|---|
| AENA SME SA |
| GROUPE ADP |
| Airport Authority Hong Kong |
| Airports of Thailand Plc |
| Fraport Group |
| London Heathrow Airports Limited |
| Japan Airport Terminal Co. Ltd |
| Vinci SA |
| Korea Airports Corp |
| Others |
Supply & Pricing Matrix
Steel and specialized glazing suppliers in China and South Korea anchor construction cost structures for retail atrium developments, concentrating margin capture with integrated construction-concession operators capable of absorbing input volatility through multi-decade lease structures.
Pricing Analysis
Certification level creates the primary spread across concession tiers, with EU Green Deal carbon accounting compliance commanding premium positioning at Frankfurt and Amsterdam. Fixed-rent structures dominate long-term retail and real estate leasing, while turnover-based agreements govern food and beverage with minimum rent guarantees. Pricing pressure stems from SAMR pricing transparency mandates compressing duty-free margin flexibility at Chinese hubs. Leisure passengers show highest price sensitivity in duty-free categories, while business travelers accept premium positioning for VIP lounges and automated retail convenience.
Supply Chain Analysis
Integrated construction-concession operators in France, Germany, and Spain hold dominant procurement capacity for terminal retail fit-outs and hospitality verticals. Steel, specialized glazing, and biometric payment hardware constitute critical input dependencies. Supply chain risk centers on single-source vulnerability for computer vision-enabled retail systems. Distribution runs through long-term concession lease frameworks with 15-25 year tenors favoring balance-sheet-deep operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ride-hailing substitution and automated retail technologies threaten legacy parking and food service revenue streams, forcing incumbents to defend concession yield through biometric-enabled dwell extension and dynamic space allocation.
For Market Incumbents: Insulate core concession yields by deploying computer vision inventory tracking to compress replenishment cycles and enable dynamic pricing for perishable categories. Counter ride-hailing substitution through premium short-stay parking products with integrated biometric payment rails. Vertical integration into in-house real estate development, as demonstrated by Fraport Group's airport city strategies, secures institutional-grade income streams with 15-25 year lease tenors. For New Entrants and Emerging Players: Pursue India's brownfield airport privatization wave targeting retail and hospitality development at Lucknow, Jaipur, and Guwahati terminals. Japan's METI public-private frameworks at Kansai and Fukuoka offer favorable revenue-sharing mechanisms for hospitality investors with limited legacy POS integration burdens. Target automated retail kiosk deployment in high-traffic gate areas where computer vision-enabled grab-and-go formats eliminate checkout friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed construction-concession specialists seeking exit liquidity after 7-10 year hold periods. Long-term viability across the analysis window hinges on securing brownfield concession renewals with automated retail technology deployment rights. Monitor biometric data governance compliance costs as an inflection indicator for smaller operator distress and consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Payment Rail Deployment | Dubai and Heathrow implementations demonstrate lift in average spend per passenger through reduced transaction friction. |
| Computer Vision Retail Integration | Changi Airport Group's shelf-mounted cameras compress replenishment cycles from hours to minutes while enabling dynamic pricing. |
| Airport City Real Estate Development | Frankfurt and Amsterdam Schiphol generate institutional-grade income streams through dedicated mixed-use zones. |
| Pre-Order Mobile Platform Launch | Heathrow and Charles de Gaulle integration with departure gate logistics compresses duty-free fulfillment windows under ten minutes. |
| EU Green Deal Compliance Certification | Third-party verified lifecycle assessments now condition contract renewal for tier-one suppliers at European hubs. |
Research Methodology
Cross-validation between primary interviews with airport concession directors, retail operations managers, and hospitality development leads and secondary validation through airport authority financial disclosures, concession lease filings, and regulatory procurement guidelines anchors the qualitative findings. Bottom-up triangulation against passenger traffic databases and top-down reconciliation with national aviation authority statistics ensures coverage consistency across the analysis window.
Calibration against historical concession yield data and verified project finance timelines shapes the analytical framework. Segmentation dimensions span revenue stream, service type, customer profile, and channel with regional regulatory cluster as an industry-specific overlay. CAGRs derive from trend extrapolation moderated by infrastructure investment cycles and passenger traffic recovery patterns. Biometric technology adoption curves and carbon accounting compliance costs feed directly into forecast sensitivity.
Macroeconomic conditions sit as an overlay; deviation in passenger traffic recovery, construction input costs, or sovereign infrastructure spending would shift the trajectory. Quarterly review of concession lease renewal rates, automated retail deployment timelines, and regulatory procurement guideline updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
Global Air Charter Services Market
Airport Operations
South Korea Airport Operations Market
Airport Operations
Global Airside Services Market
Airport Operations
France Airport Operations Market
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
UK Airport Operations Market
Airport Operations
Aircraft Ground Handling System Market
Airport Operations
Canada Airport Operations Market
Airport Operations
Europe Airport Operations Market
Airport Operations
Middle East Airport Operations Market
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Business Jet Ground Handling Services Market
Airport Operations
Airport Ground Handling Market
Airport Operations
Airport Operations Market
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market