
 Europe Offshore Helicopter Services Market | 2026-2036
Europe Offshore Helicopter Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Offshore Helicopter Services Market Foresight
Enhanced safety certification tiers is reorganizing competitive positioning across the Europe offshore helicopter services sector. Babcock International dominates military-adjacent SAR contracts through its integrated training and maintenance infrastructure. CHC Helicopter sustains North Sea oil and gas crew rotation networks through its Aberdeen and Bergen operational hubs. Leonardo S.p.A specializes in next-generation avionics packages that operators increasingly specify for all-weather North Sea missions.
Europe offshore helicopter services encompass rotary-wing aviation operations supporting energy infrastructure, maritime logistics, and emergency response across marine environments, typically utilizing twin-engine aircraft rated for instrument flight rules and equipped with flotation systems, winches, and night-vision goggle compatibility. Personnel transport commands the largest revenue share as daily crew changes on offshore platforms require predictable scheduled rotations regardless of sea state. Wind energy operators represent the fastest-expanding end user category, with turbine technician transport generating new route structures distinct from traditional oil and gas patterns. Heavy lift helicopters capture premium pricing for specialized cargo missions including wind turbine component installation, though twin-engine helicopters retain volume leadership across most service corridors.
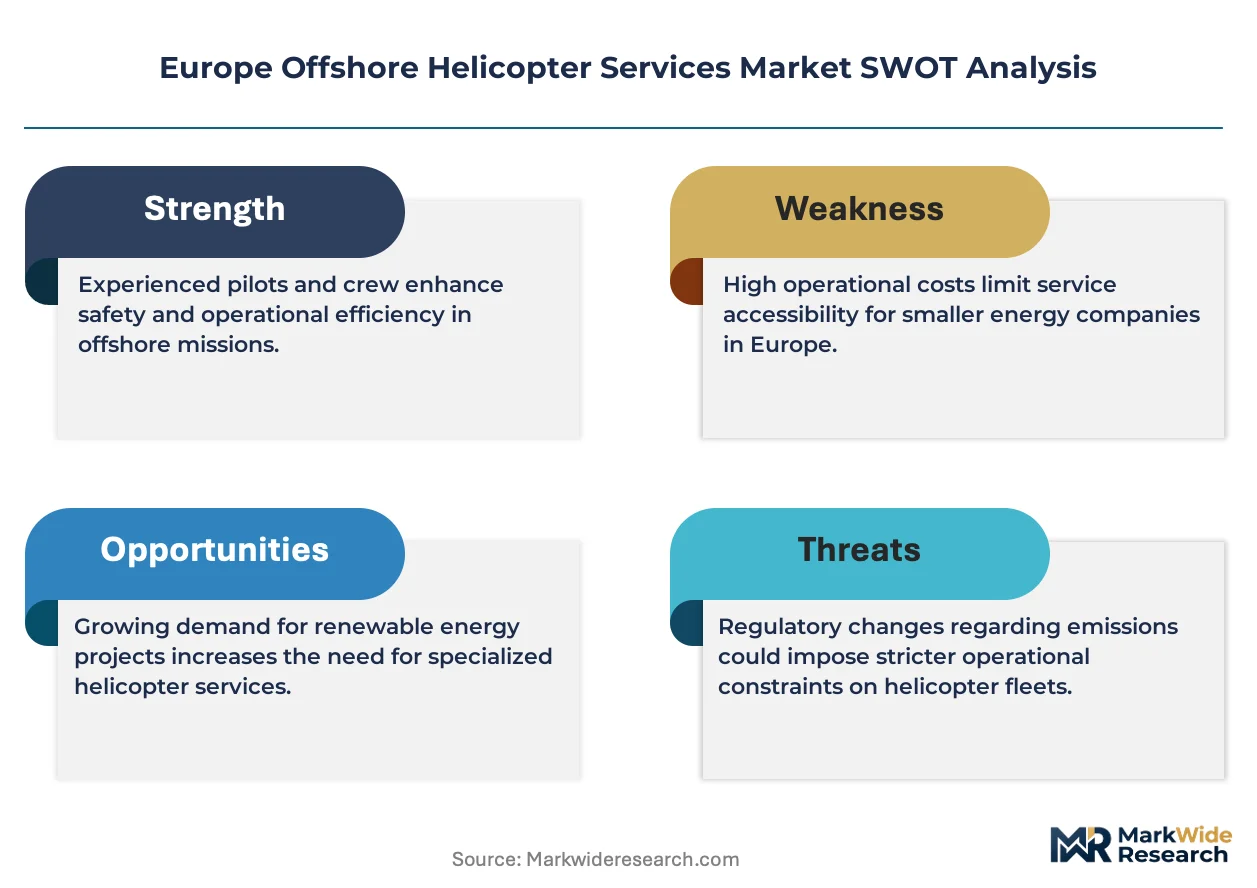
EASA operational standards and the EU's CSRD sustainability disclosure requirements shape fleet investment decisions, pressuring operators to document emissions profiles and transition timelines. The UK's CAA maintains distinct certification protocols for North Sea operations that influence aircraft configuration and pilot training investments. Stakeholders must monitor how overlapping ESG mandates and safety regulations will reshape contract specifications and capital allocation across the European offshore aviation value chain.
Market Dynamics
The EU's F-Gas Regulation is forcing fleet operators to accelerate powertrain transitions while North Sea floating wind projects generate entirely new route demand patterns. This dual pressure reshapes capital allocation, contract specifications, and competitive positioning across European offshore aviation corridors.
Growth Catalysts
- Floating Offshore Wind:Turbine installation and maintenance crews in UK, Norwegian, and Danish waters require dedicated transport networks distinct from legacy oil and gas rotations.
- CSRD Mandates:Corporate sustainability reporting requirements pressure energy majors to document Scope 3 emissions, elevating helicopter service selection criteria toward lower-carbon fleets.
- North Sea Decommissioning:Aging UK and Norwegian platforms require intensive personnel mobilization for dismantling operations, sustaining demand through hydrocarbon transition.
Market Restraints
- Helicopter Manufacturing Concentration:Twin-engine offshore-rated airframe supply concentrates among three OEMs, creating delivery bottlenecks for fleet expansion.
- Pilot Training Pipeline:EASA instrument rating and offshore-specific certification requirements extend qualification timelines, constraining crew availability.
- Jet-A Fuel Price Volatility:Aviation turbine fuel represents 35-40% of operating costs, compressing margins when energy prices spike.
Strategic Opportunities
- Irish Sea Expansion:Ireland's emerging offshore wind licensing rounds lack established helicopter infrastructure, creating first-mover positioning potential.
- Hybrid-Electric Retrofit Pathways:Parallel hybrid powertrain kits for existing airframes offer interim emissions reduction without full fleet replacement.
- Drone-Helicopter Convergence:Autonomous cargo drones for turbine component delivery to fixed structures could free helicopters for personnel-only missions.
Industry Challenges
- Multi-Type Rating Scarcity:Pilots certified across both oil and gas and wind-specific mission profiles remain limited, fragmenting crew scheduling flexibility.
- Dual Certification Complexity:Operators serving both UK CAA and EASA jurisdictions face overlapping but non-identical equipment mandates, increasing compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Offshore Helicopter Services Market |
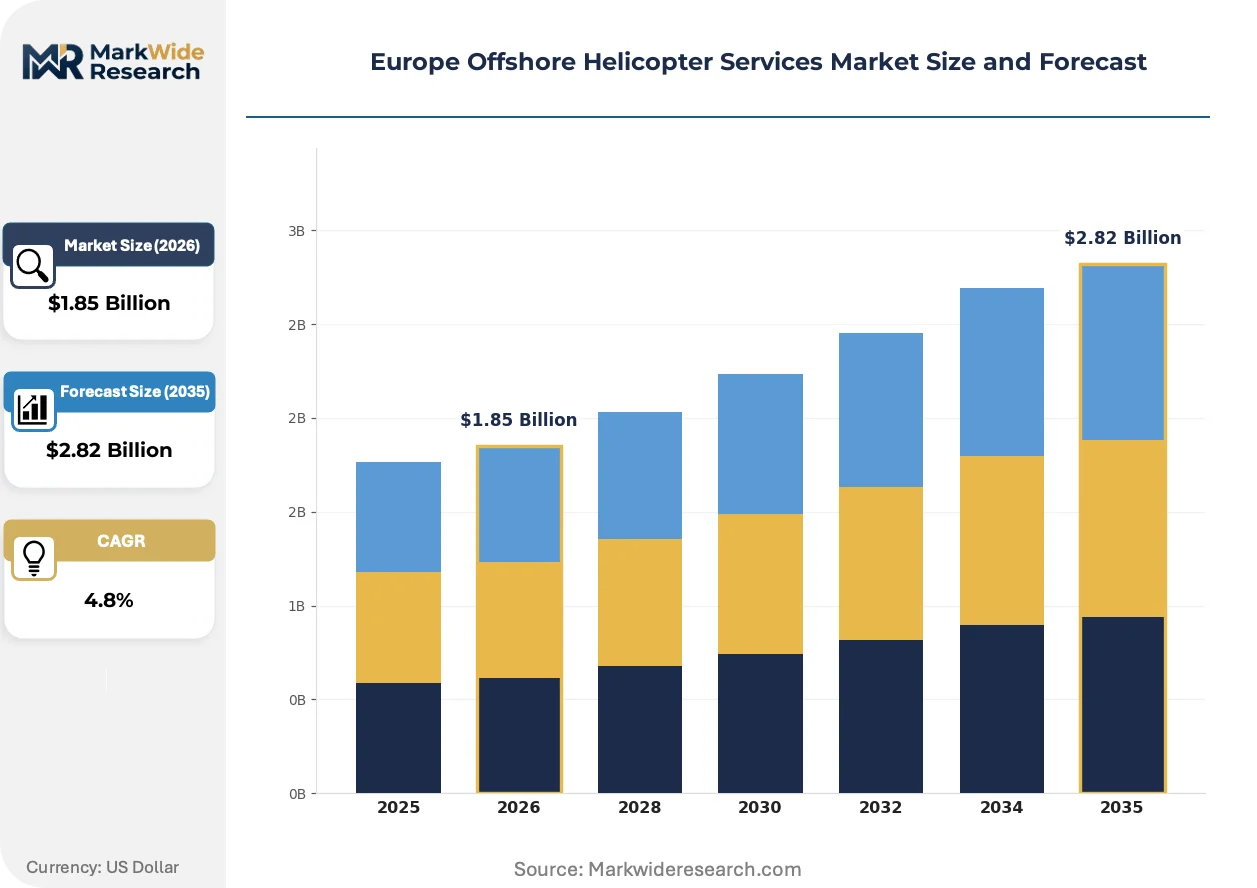
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personnel Transport, Cargo Transport, Medical Evacuation, Search and Rescue End User: Oil & Gas Companies, Wind Energy Operators, Government Agencies, Medical Facilities Aircraft Type: Single-Engine Helicopters, Twin-Engine Helicopters, Heavy Lift Helicopters, UAVs Deployment Model: Onshore Deployment, Offshore Deployment, Ad-Hoc Services, Scheduled Services |
| Companies Covered | Petroleum Helicopters International Inc, Héli-Union, CHC Helicopter, Airbus SE, Babcock International, Bristow Group Inc., Omni Helicopters International S.A., Leonardo S.p.A, NHV Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Offshore Helicopter Services Market Shifts & Advancements
Aviation propulsion technology is bifurcating between evolutionary efficiency gains and revolutionary electrification architectures. Fleet managers must now place technology bets across incompatible development timelines while maintaining operational continuity.
Hybrid-electric propulsion architectures are bifurcating the mid-size twin-engine segment. Wind farm operators in Scottish and German waters are specifying aircraft with 15-20% fuel burn reduction for new contracts. This technology divergence is compressing residual values of conventional turbine helicopters and accelerating OEM development timelines.
The EU's tightened F-Gas Regulation restricts hydrofluorocarbon use in fire suppression and cooling systems, compelling avionics and airframe modifications. Helicopter operators must retrofit or replace affected equipment to maintain airworthiness certification. UK and Norwegian fleets face the steepest compliance curves given their older average fleet age.
Buyer contracting preferences are rotating toward availability-based agreements rather than hourly rates. Oil majors operating Dutch and Danish platforms now penalize downtime rather than rewarding flight hours, transferring operational risk to service providers. This shift concentrates contract awards with operators possessing redundant aircraft pools and predictive maintenance capabilities.
Europe Offshore Helicopter Services Market Segmentation
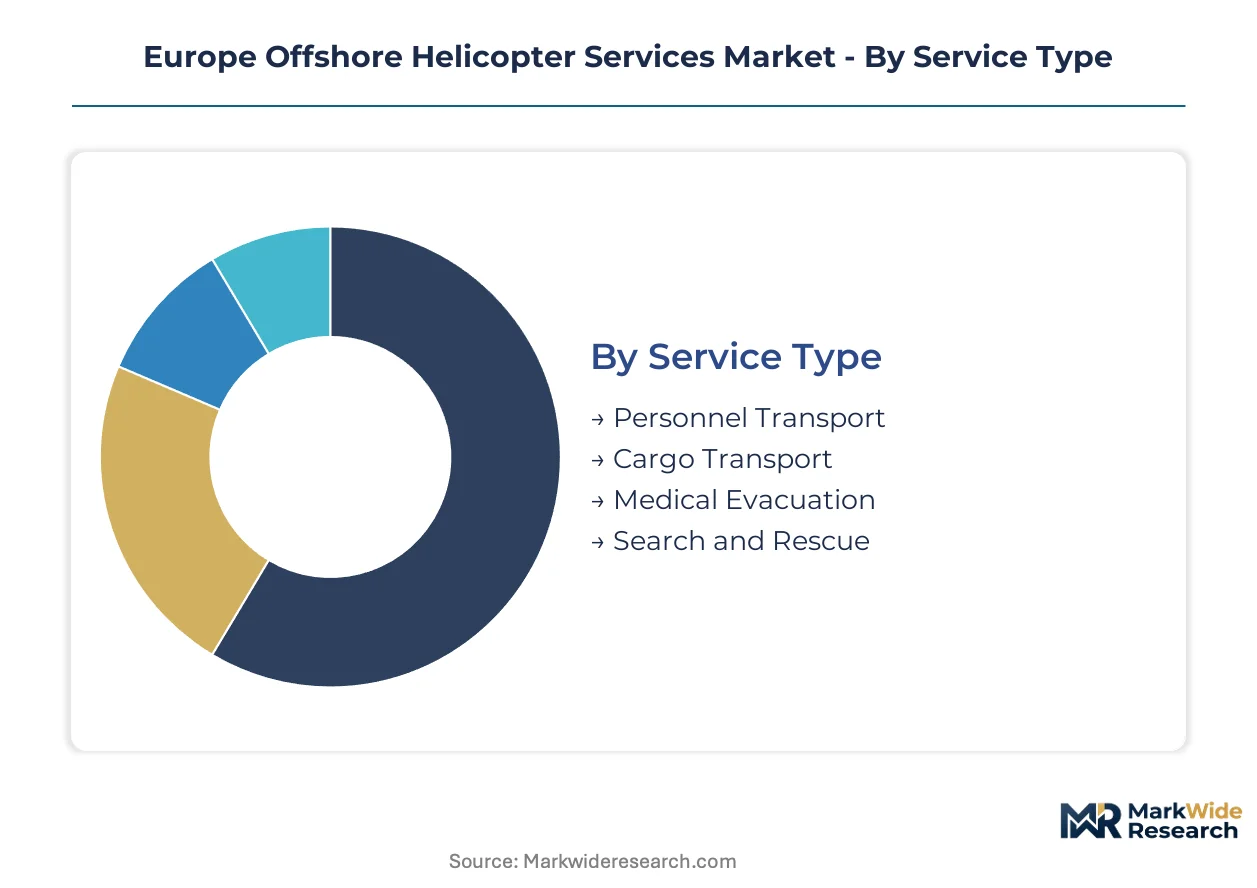
Service differentiation across Europe's offshore helicopter market reflects divergent operational requirements between mature hydrocarbon corridors and emerging wind energy zones. Segment boundaries increasingly blur as multi-mission aircraft configurations gain preference among fleet operators seeking contract flexibility across both legacy and growth end-uses.
Service Type:
Personnel Transport and Cargo Transport dominate revenue generation across UK, Norwegian, and Danish waters, while Medical Evacuation and Search and Rescue concentrate around specific regulatory mandates and geographic risk profiles.
- Personnel Transport:Scheduled crew rotations for oil platforms and wind farms utilize twin-engine helicopters rated for instrument flight rules with flotation systems. UK North Sea operators command the densest route networks, where daily platform changes sustain contract volumes regardless of hydrocarbon price cycles.
- Cargo Transport:External sling loads and internal cabin freight serve turbine component logistics and platform supply runs. German and Scottish floating wind projects are generating new heavy-lift specifications distinct from legacy oil and gas cargo profiles.
- Medical Evacuation:Dedicated air ambulance configurations with intensive care equipment serve isolated offshore installations. Norwegian sector regulations mandate specific response time thresholds that shape fleet positioning.
- Search and Rescue:Military-adjacent contracts require all-weather avionics and winch-equipped aircraft. UK and Irish coastal zones maintain the most intensive SAR coverage requirements.
Personnel Transport commands the established base. The steepest expansion runs through Cargo Transport as floating wind turbine logistics scale.
End User:
Oil and Gas Companies historically anchored fleet investment decisions, though Wind Energy Operators now drive new aircraft specifications and route planning methodologies across North Sea licensing rounds.
- Oil & Gas Companies:Majors operating UK and Norwegian mature fields require predictable crew change logistics for aging platform portfolios. Decommissioning timelines in the UK central North Sea are sustaining personnel mobilization demand through hydrocarbon transition phases.
- Wind Energy Operators:Turbine technicians need transport to fixed and floating structures in weather windows narrower than oil platform tolerances. Danish and German Baltic developments are pioneering new contract structures linking availability guarantees to construction milestone schedules.
- Government Agencies:Coast guard and maritime safety authorities procure SAR and surveillance services through multi-year framework agreements.
- Medical Facilities:Regional hospital networks contract for offshore emergency response capabilities in remote coastal catchments.
Oil and Gas Companies retain the largest contract value. Wind Energy Operators are gaining share fastest as installation pipelines accelerate.
Aircraft Type:
Twin-Engine Helicopters constitute the volume core across European offshore corridors, while Heavy Lift variants capture premium positioning for wind farm construction and Single-Engine configurations face regulatory displacement.
- Twin-Engine Helicopters:Redundant powerplants satisfy EASA instrument flight rules and UK CAA North Sea certification requirements. Aberdeen and Bergen maintenance hubs support the densest operational concentrations of these aircraft.
- Heavy Lift Helicopters:External load capacity exceeding five tonnes enables turbine nacelle transport and platform module installation. Scottish floating wind demonstration projects are specifying these aircraft for anchor chain and mooring line deployment.
- Single-Engine Helicopters:Restricted to coastal transit and near-shore operations under evolving safety mandates. Irish Sea wind developments represent residual demand pockets.
- UAVs:Autonomous cargo platforms are entering trial phases for turbine component delivery to fixed structures.
Twin-Engine Helicopters anchor fleet composition. Heavy Lift Helicopters are climbing the fastest as offshore wind component weights increase.
Deployment Model:
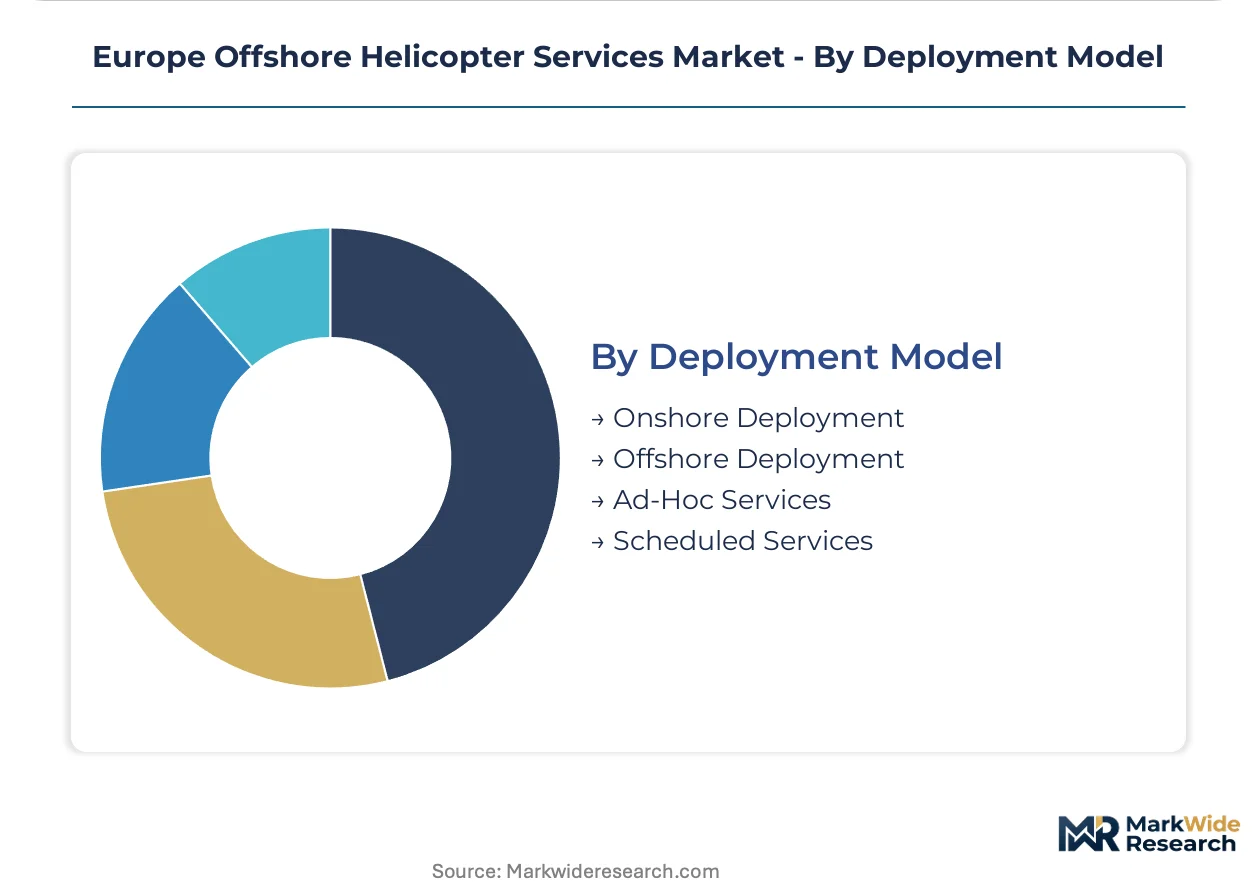
Scheduled Services generate predictable revenue streams for established North Sea operators, while Ad-Hoc Services and Offshore Deployment configurations are adapting to fragmented wind farm construction timelines.
- Scheduled Services:Fixed-rotation contracts with oil majors provide base-load utilization for fleet planning. UK central North Sea routes maintain the highest frequency intervals.
- Offshore Deployment:Platform-based aircraft positioning reduces response times for installations beyond helicopter range from coastal bases. Norwegian deepwater fields require this model exclusively.
- Onshore Deployment:Coastal base operations serve near-field installations with lower fixed cost structures.
- Ad-Hoc Services:Demand-responsive charters address construction spikes and emergency requirements outside scheduled coverage.
Scheduled Services retain contract value leadership. Ad-Hoc Services are expanding most quickly as wind construction schedules fragment traditional rotation patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's offshore helicopter services trade flows predominantly through North Sea corridors, with the United Kingdom and Norway generating substantial service export demand while Denmark and Germany import specialized heavy-lift capacity for emerging wind installations.
United Kingdom
Decommissioning schedules for aging North Sea platforms and floating wind developments in Scottish waters sustain dense crew rotation networks. The UK CAA maintains distinct instrument flight rules certification that shapes pilot training investments and aircraft configuration requirements. Aberdeen anchors the continent's largest offshore aviation cluster, where operators coordinate daily platform changes and emergency response coverage across the central North Sea.
Norway
Deepwater oil fields and electrification mandates for offshore installations drive demand for extended-range twin-engine configurations. Norwegian regulations mandate specific medical evacuation response time thresholds that influence fleet positioning and platform-based deployment models. Bergen serves as the primary operational hub, with maintenance infrastructure supporting harsh-environment missions in the Norwegian Sea and Barents Sea frontier zones.
Germany
Baltic Sea floating wind construction generates new heavy-lift specifications for turbine component installation and anchor chain deployment. The EU's CSRD disclosure requirements pressure energy majors to document Scope 3 emissions, elevating contractor selection criteria toward lower-carbon fleet options. Rostock and Cuxhaven emerge as coastal bases serving construction-phase logistics for the nation's accelerating offshore wind licensing rounds.
Denmark
Fixed and floating wind developments in Danish waters require transport networks distinct from legacy oil and gas rotation patterns, with narrower weather windows for technician access. The F-Gas Regulation compels avionics retrofits for fire suppression systems across existing fleets. Esbjerg concentrates helicopter infrastructure serving the nation's North Sea wind zones, with operators pioneering availability-based contract structures tied to construction milestone schedules.
Netherlands
Declining North Sea gas production and decommissioning obligations sustain personnel mobilization demand through hydrocarbon transition phases. Dutch platforms increasingly require hybrid-electric capable aircraft to satisfy corporate sustainability commitments from international operators. Den Helder maintains residual aviation capacity serving southern North Sea installations, though route density has shifted toward UK and Norwegian corridors over the past decade.
Europe Offshore Helicopter Services Market Competitive Landscape
Concentration sits with integrated service providers possessing redundant aircraft pools and predictive maintenance capabilities. The sector exhibits moderate consolidation, with three to four operators commanding substantial contract share across UK and Norwegian corridors while regional specialists capture niche wind farm logistics. Strategic archetypes include military-adjacent SAR contractors, oil and gas rotation specialists, and emerging wind-focused operators. Competitive moves center on fleet modernization for emissions compliance and availability-based contract structures that transfer operational risk from energy majors to service providers.
Within the integrated service tier, Babcock International and CHC Helicopter exemplify contrasting positioning archetypes. Babcock International occupies a position aligned with government framework agreements and search-and-rescue mandates, leveraging training and maintenance infrastructure for military-adjacent contracts. CHC Helicopter anchors the oil and gas rotation segment through Aberdeen and Bergen operational hubs. Leonardo S.p.A represents the technology supply dimension, with avionics packages increasingly specified for all-weather North Sea missions.
| Leading Market Players |
|---|
| Petroleum Helicopters International Inc |
| Héli-Union |
| CHC Helicopter |
| Airbus SE |
| Babcock International |
| Bristow Group Inc. |
| Omni Helicopters International S.A. |
| Leonardo S.p.A |
| NHV Group |
| Others |
Supply & Pricing Matrix
Hybrid-electric powertrain retrofits replacing conventional turbine configurations simultaneously reshape supply geography toward German and French avionics clusters and compress pricing economics for legacy aircraft residual values. This substitution dynamic concentrates procurement leverage with fleet operators capable of bridging interim compliance windows while OEMs accelerate clean-sheet development timelines.
Pricing Analysis
Industrial OEM buyers anchor contract structures toward availability-based agreements rather than hourly flight rates. Three-tier pricing structure across premium, standard, and economy levels reflects aircraft age, EASA certification tier, and predictive maintenance capability bundling. Cost compression in mid-tier scheduled services is intensifying because wind farm operators are consolidating contract awards with redundant-fleet providers. Price sensitivity peaks among emerging Irish Sea wind developers, while Norwegian deepwater oil majors demonstrate lowest sensitivity due to regulatory-mandated response time requirements.
Supply Chain Analysis
Turbine engine manufacturing chokepoints in the United States, United Kingdom, and France tether fleet expansion timelines to single-source airframe OEM delivery schedules. Critical component dependencies include nickel-based superalloys for hot-section parts, composite rotor blade materials, and avionics fire suppression systems subject to EU F-Gas Regulation restrictions. Single-source vulnerability concentrates in twin-engine offshore-rated airframe supply, where three manufacturers control certification pathways. Distribution runs through Aberdeen and Bergen maintenance hubs serving North Sea operational corridors with platform-based forward positioning for Norwegian deepwater fields.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's CSRD disclosure mandates and F-Gas Regulation compliance curves constitute a dual regulatory inflection accelerating fleet turnover and consolidating contract awards with integrated service providers possessing redundant aircraft pools and emissions documentation capabilities.
For Market Incumbents: Shield core contract positions by deepening predictive maintenance capabilities and securing hybrid-electric retrofit partnerships before OEM clean-sheet aircraft reach market. Vertical integration into pilot training infrastructure addresses EASA instrument rating pipeline constraints that threaten crew availability. Certification investment in UK CAA and EASA dual-jurisdiction compliance protects against regulatory fragmentation overhead.
For New Entrants and Emerging Players: Anchor in Irish Sea wind licensing rounds where established helicopter infrastructure remains underdeveloped and first-mover positioning potential concentrates. Target ad-hoc construction-phase logistics contracts tied to floating wind milestone schedules, where availability guarantees command premium positioning absent incumbent fleet redundancy. Go-to-market execution should emphasize rapid-response capability for weather-window-dependent technician transport.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors integrated operators with documented emissions profiles and redundant fleet pools. Long-term viability rests on capital deployment into hybrid-electric transition pathways and predictive maintenance infrastructure rather than conventional turbine aircraft accumulation. Monitor CSRD Scope 3 disclosure enforcement intensity as the signal indicating acceleration or deceleration of contract specification shifts toward lower-carbon fleet requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Fleet Transition | EU F-Gas Regulation compliance secures airworthiness certification for North Sea operations. |
| Predictive Maintenance Infrastructure | Availability-based contracts with oil majors transfer operational risk to service providers. |
| Pilot Training Pipeline Expansion | EASA instrument rating capacity addresses crew scarcity constraining fleet utilization. |
| Irish Sea Base Establishment | First-mover positioning captures emerging offshore wind licensing round demand. |
| Dual-Jurisdiction Certification Investment | UK CAA and EASA compliance reduces regulatory overhead for cross-border operators. |
Research Methodology
Desk research of EASA operational bulletins, UK CAA certification records, and EU regulatory filings preceded structured interviews with fleet operations directors, offshore wind project logistics managers, and aviation maintenance executives. Secondary validation drew from helicopter OEM delivery disclosures, energy major procurement frameworks, and offshore wind construction databases. Bottom-up crew rotation demand modeling and top-down fleet capacity assessment provided cross-referencing triangulation.
Variance decomposition across service type, end user, aircraft configuration, and deployment model dimensions shaped analytical framework construction over the projection horizon. CAGRs derived from segment-level demand build-ups incorporating North Sea decommissioning schedules and floating wind installation pipelines. Industry-specific forecast inputs included EASA pilot certification pipeline data and EU F-Gas Regulation retrofit compliance timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained North Sea hydrocarbon decommissioning activity and accelerated floating wind licensing; material deviation in either trajectory would warrant model refresh. Practitioners should keep alternative scenarios live as CSRD enforcement intensity and hybrid-electric aircraft certification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
Middle East Airport Operations Market
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Airport Terminal Operations Market
Airport Operations
Aircraft Ground Handling System Market
Airport Operations
UK Airport Operations Market
Airport Operations
Airport Operations Market
Airport Operations
Business Jet Ground Handling Services Market
Airport Operations
Global Air Charter Services Market
Airport Operations
Airport Ground Handling Market
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market
Airport Operations
Canada Airport Operations Market
Airport Operations
Global Airside Services Market
Airport Operations
France Airport Operations Market
Airport Operations
South Korea Airport Operations Market
Airport Operations
Global Non-Aeronautical Market