
 Flight Tracking System Market | 2026-2036
Flight Tracking System Market Size, Share, and Industry Trends Forecast 2026-2036
Flight Tracking System Market Analysis
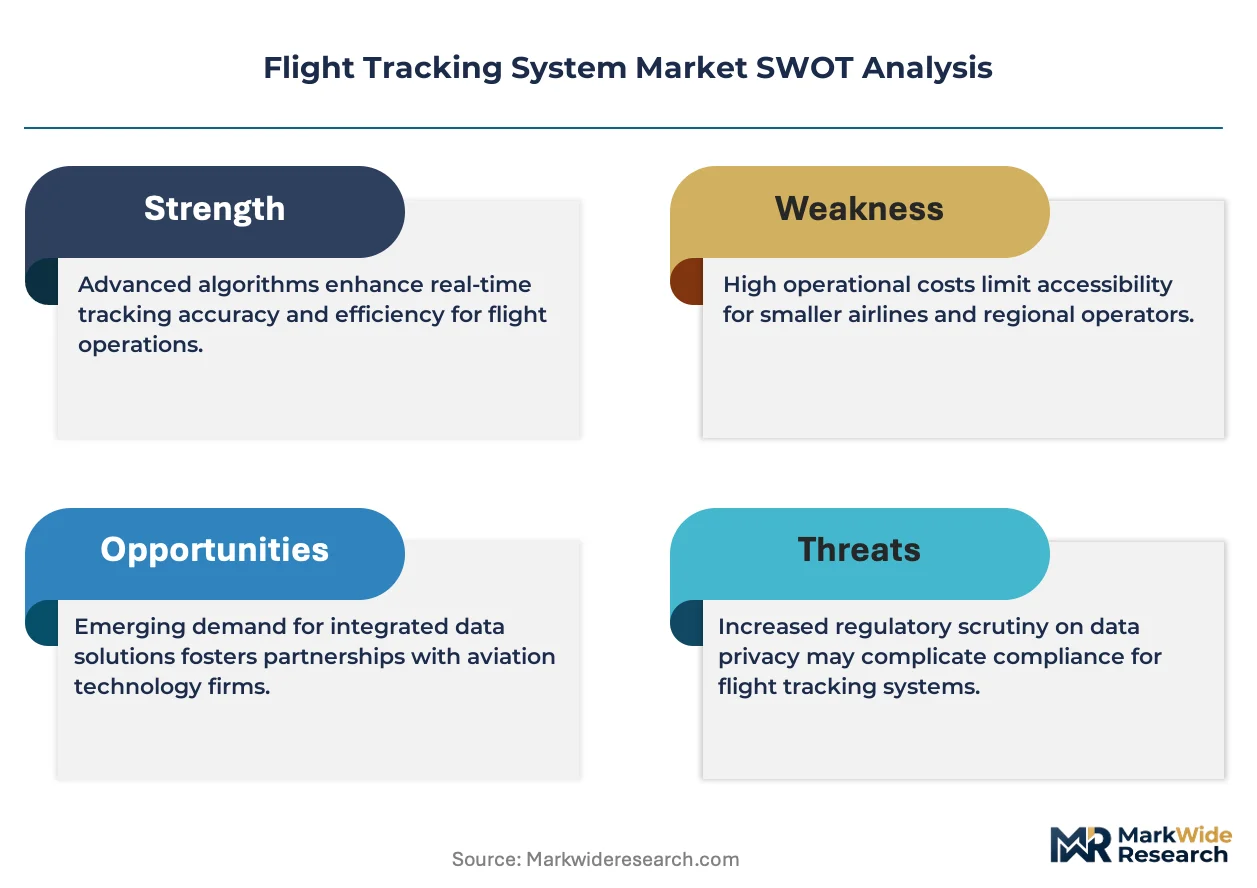
Subscription-based software-defined tracking is shifting how vendors monetize flight surveillance, moving buyers from perpetual hardware licenses toward recurring data-service contracts. Honeywell International Inc. leverages its avionics installed base to bundle connectivity with predictive maintenance portals. Aireon LLC anchors the space-based ADS-B layer through its Iridium NEXT hosted payload constellation. Garmin Ltd. competes in the general aviation segment with portable and panel-mount transponders that integrate with mobile flight planning ecosystems.
Flight tracking systems comprise transponder hardware, ground station networks, and data fusion platforms that aggregate aircraft position, altitude, and velocity from multiple sensor sources including ADS-B broadcasts and satellite relays. These systems achieve position accuracy within meters through multilateration timing synchronization, serving air traffic control separation assurance and airline operational control centers. ADS-B technology leads installed capacity but satellite-based augmentation represents the fastest-expanding segment as oceanic and remote airspace coverage gaps close. Cloud-based deployment models now capture disproportionate growth in airline fleet management, while on-premises installations retain dominance among government agencies with classified operational requirements.
The FAA mandates ADS-B Out equipage under 14 CFR 91.225 across controlled airspace, while EASA enforces equivalent requirements through its ADS-B regulation within the Single European Sky framework. ICAO Global Aeronautical Distress and Safety System standards further shape product roadmaps by requiring autonomous distress tracking capabilities on commercial transport aircraft. Stakeholders must monitor spectrum allocation decisions at WRC proceedings that could reassign frequencies critical to current transponder designs.
Market Dynamics
The transition from ground-based radar to satellite-based ADS-B surveillance is compressing infrastructure deployment timelines while fragmenting vendor competitive positions across hardware, connectivity, and data analytics layers.
Growth Catalysts
- FAA ADS-B Out mandate:The 14 CFR 91.225 requirement across controlled US airspace forces fleet-wide retrofits on aging aircraft, sustaining transponder replacement demand through the forecast period.
- ICAO GADSS distress tracking:Autonomous tracking mandates for commercial transport aircraft expand addressable hardware volume beyond traditional air traffic control applications.
- NextGen airspace modernization:The United States sustains procurement of satellite-based surveillance infrastructure as the FAA replaces legacy radar systems with space-based augmentation networks.
Market Restraints
- Semiconductor supply concentration:Transponder manufacturing depends on specialized RF chipsets sourced from concentrated East Asian foundries, exposing lead times to geopolitical friction.
- Legacy fleet retrofit economics:Aging narrow-body aircraft face retirement timing decisions that render ADS-B Out investments uneconomical for operators with near-term phase-out plans.
- Spectrum reallocation risk:World Radiocommunication Conference proceedings threaten reassignment of L-band frequencies critical to current transponder designs, forcing potential hardware redesign cycles.
Strategic Opportunities
- General aviation penetration:The United States hosts over 200,000 piston aircraft lacking ADS-B Out equipage, representing a latent hardware market as voluntary adoption accelerates.
- Predictive maintenance convergence:Flight tracking data streams merge with engine health monitoring platforms, creating bundled service contracts that capture recurring revenue from airline operational control centers.
- Remote airspace coverage gaps:Oceanic and polar routes lacking ground station infrastructure drive demand for Iridium NEXT hosted payloads and competing satellite relay constellations.
Industry Challenges
- Multilateration synchronization complexity:Ground station networks require nanosecond timing precision across distributed receiver arrays, demanding specialized engineering talent scarce in avionics sectors.
- Cloud migration security certification:Government agencies with classified operational requirements impose lengthy accreditation timelines on cloud-based fleet management platforms, delaying vendor revenue recognition.
- Data fusion platform integration:Airlines struggle to reconcile ADS-B broadcasts with ACARS messages and satellite telemetry into unified operational dashboards, fragmenting procurement decisions across IT and flight operations departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flight Tracking System Market |
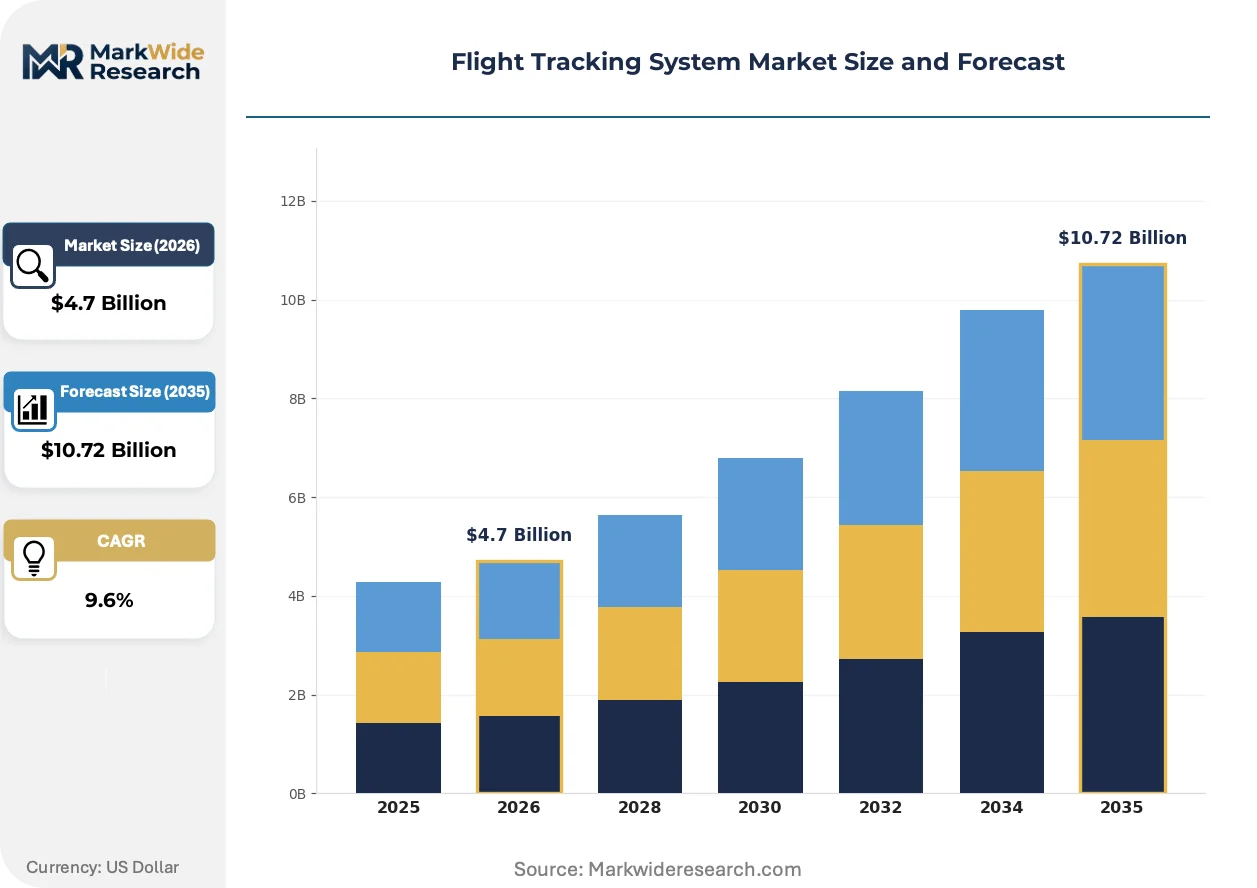
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $10.72 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: ADS-B, GPS, Satellite, Multilateration End User: Airlines, Government Agencies, Private Operators, Heliports Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Service Type: Real-Time Tracking, Data Analytics, Alerting Services, Support Services |
| Companies Covered | Aireon LLC, SKY TRAC SYSTEMS LTD, Honeywell International Inc., BLUE SKY NETWORK, Spider Tracks Limited, Garmin Ltd., FLYHT Aerospace Solutions Ltd., General Electric (GE Aviation), Rockwell Collins (Collins Aerospace), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flight Tracking System Market Emerging Trajectories
Software-defined architectures are displacing fixed-function hardware across the flight surveillance stack, enabling vendors to push capability updates remotely while compressing physical retrofit cycles for end-users.
Space-based ADS-B receiver constellations are electrifying oceanic surveillance coverage by eliminating the ground station infrastructure dependency that has historically constrained aircraft tracking over remote water and polar regions. Maritime patrol operators and long-haul cargo carriers are accelerating procurement of dual-mode transponders compatible with both terrestrial and satellite relay networks. This technology convergence is compressing the competitive advantage of legacy ground-station-centric vendors while elevating payload-hosting satellite operators into critical supply chain positions.
EASA's Single European Sky ADS-B regulation is harmonizing equipage requirements across member states, reducing fragmentation that previously complicated fleet planning for intra-European operators. The framework mandates performance-based navigation compatibility, forcing transponder manufacturers to certify multi-constellation GNSS receivers alongside traditional Mode S functionality. Low-cost carriers with high aircraft utilization rates face compressed installation windows during overnight maintenance rotations, favoring modular retrofit kits over integrated avionics replacements.
Airline operational control centers are unbundling flight tracking from legacy flight planning suites, procuring standalone data services through API-centric platforms rather than integrated software licenses. This purchasing pattern disrupts incumbent avionics vendors with entrenched installed bases, opening procurement decisions to specialized data analytics providers. North American network carriers with complex hub-and-spoke systems demonstrate the most aggressive unbundling behavior, separating position data acquisition from operational decision-support tools.
Flight Tracking System Market Segmentation
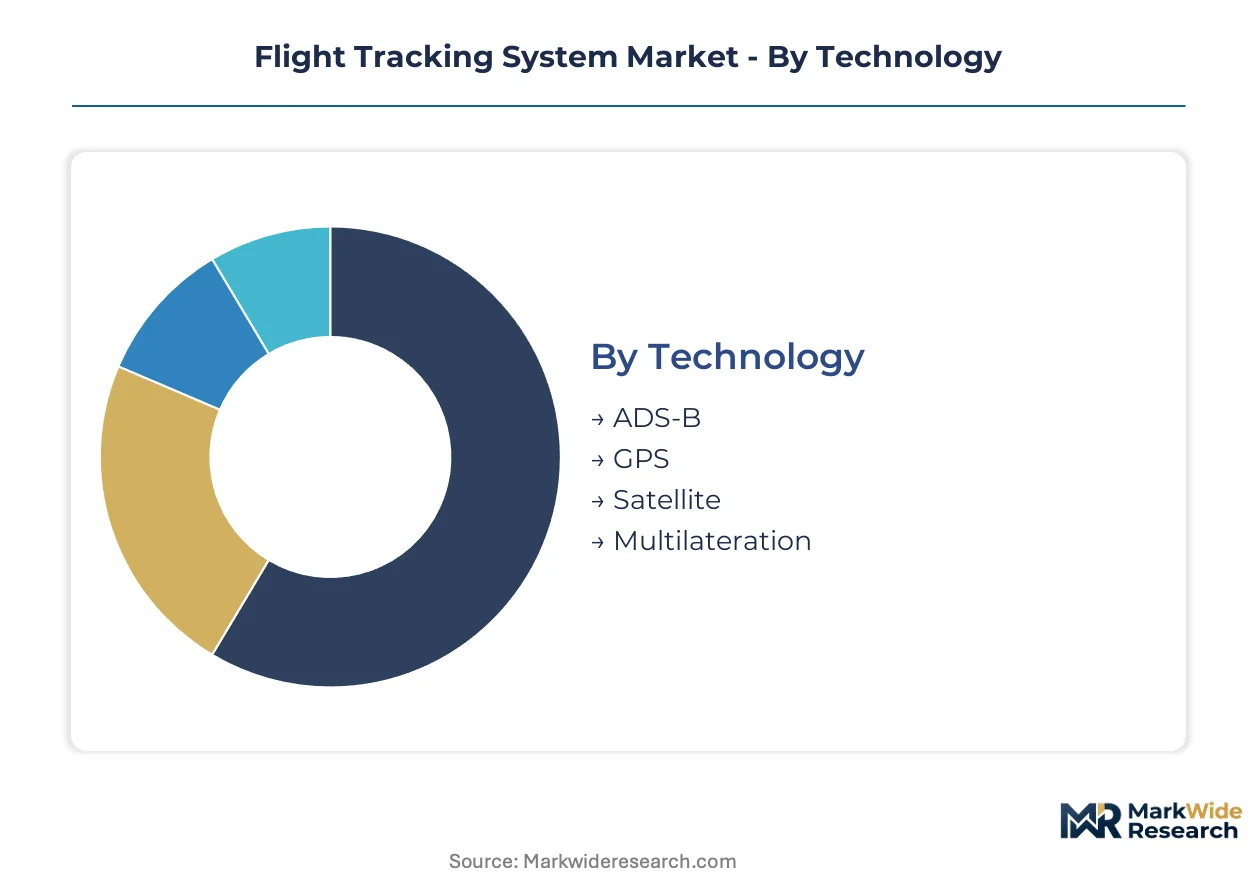
Flight tracking system procurement fragments across four distinct dimensions. Technology choices determine hardware retrofit requirements and infrastructure dependencies. End-user profiles shape compliance urgency and budget cycles. Deployment models separate security-conscious government buyers from cost-optimizing commercial operators.
Technology:
Supply concentration clusters around RF chipset vendors and ground station network operators, with satellite payload hosts emerging as bottleneck suppliers.
- ADS-B:Broadcasts aircraft position, altitude, and velocity via 1090 MHz extended squitter transponders. Demand concentrates in the United States where FAA mandates under 14 CFR 91.225 force fleet-wide retrofits through controlled airspace equipage deadlines.
- Satellite:Space-based ADS-B receivers on low-earth orbit constellations eliminate ground infrastructure gaps over oceanic and polar routes. Long-haul cargo carriers operating transpacific lanes drive procurement as they seek continuous surveillance beyond terrestrial receiver range.
- GPS:Satellite navigation augmentation provides position reference for multilateration timing synchronization. General aviation operators in remote regions depend on GPS-referenced tracking where ground station density proves insufficient.
- Multilateration:Time-difference-of-arrival calculations across distributed receiver arrays achieve meter-level accuracy. European air navigation service providers deploy wide-area multilateration as Mode S radar replacement in high-density terminal areas.
Today's leader: ADS-B. Tomorrow's challenger: Satellite.
End User:
Procurement authority separates between operational control centers seeking fleet visibility and regulatory bodies mandating surveillance infrastructure.
- Airlines:Network carriers unbundle flight tracking from legacy flight planning suites, procuring standalone data services through API-centric platforms. North American hub-and-spoke operators demonstrate the most aggressive separation of position data acquisition from decision-support tools.
- Government Agencies:Classified operational requirements impose lengthy cloud migration security certifications. The FAA sustains procurement of satellite-based surveillance infrastructure as NextGen airspace modernization replaces legacy radar systems.
- Private Operators:Corporate flight departments prioritize discrete tracking solutions that shield aircraft movements from public flight tracking websites.
- Heliports:Urban air mobility infrastructure investments drive demand for precision approach path monitoring in dense metropolitan environments.
Airlines dominate current procurement volume. Government agencies anchor long-term infrastructure commitments.
Deployment:
Margin structures diverge between recurring subscription revenue and perpetual license models.
- Cloud-Based:Airlines with complex fleet management requirements favor software-as-a-service delivery that enables rapid scaling across expanding aircraft portfolios.
- On-Premises:Government agencies retain dominance where classified operational requirements preclude third-party data hosting.
- Hybrid:Operators split sensitive operational data on-premises while pushing non-critical analytics to cloud environments.
- Mobile:General aviation pilots leverage tablet-based applications integrated with portable ADS-B receivers for situational awareness.
Cloud deployment captures disproportionate growth in commercial aviation. On-premises retains structural importance in defense and intelligence applications.
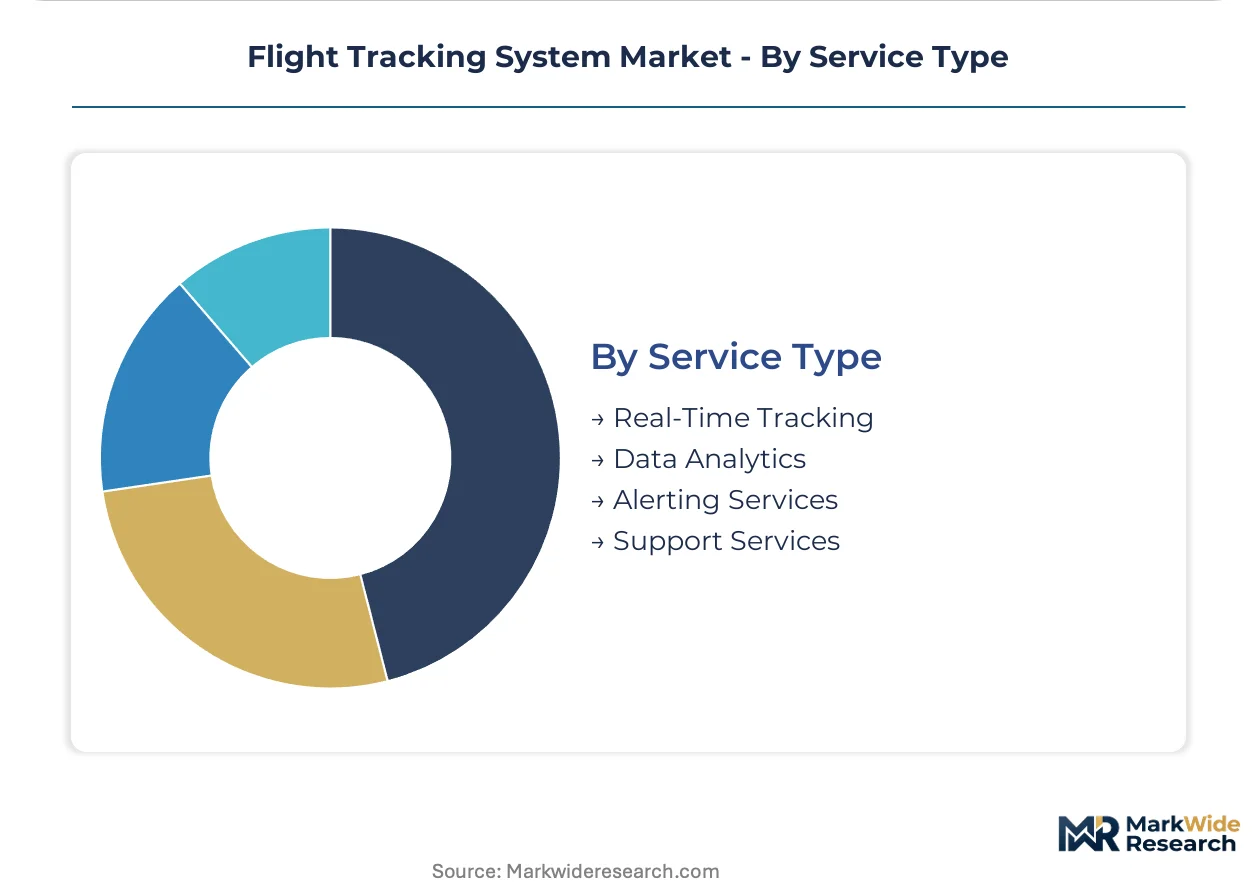
Service Type:
Customer lifetime value expands as vendors migrate buyers from discrete data feeds toward integrated operational platforms.
- Real-Time Tracking:Position updates at sub-minute intervals enable air traffic control separation assurance and airline operational control center dispatch decisions.
- Data Analytics:Predictive maintenance convergence merges flight tracking streams with engine health monitoring platforms, creating bundled service contracts.
- Alerting Services:Automated notifications trigger on geofence breaches, altitude deviations, or distress conditions per ICAO GADSS autonomous tracking requirements.
- Support Services:Installation supervision, regulatory compliance documentation, and ongoing technical assistance accompany hardware procurement.
Real-time tracking anchors current revenue. Data analytics represents the steepest expansion trajectory as airlines operationalize surveillance data beyond mere position awareness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outpaces Germany in satellite-based surveillance infrastructure procurement, while China accelerates domestic ADS-B manufacturing capacity to reduce import dependency. Regulatory mandates and fleet modernization programs create divergent growth trajectories across national aviation authorities.
United States
The FAA sustains NextGen airspace modernization investments while network carriers unbundle flight tracking from legacy suites. The 14 CFR 91.225 ADS-B Out mandate forces retrofits across controlled airspace. Dallas-Fort Worth and Atlanta anchor operational control center consolidation as hub-and-spoke operators centralize fleet visibility platforms.
Germany
EASA's Single European Sky framework harmonizes equipage requirements across member states while Lufthansa Group drives predictive maintenance convergence. The EU Green Deal pressures operators toward fuel-efficient routing enabled by precision tracking. Munich and Hamburg concentrate avionics engineering talent for multilateration ground station deployment.
China
Domestic airlines expand fleet monitoring capabilities under CAAC safety mandates while COMAC indigenous aircraft programs stimulate local transponder demand. The country's national aviation regulator accelerates airspace modernization timelines. The Yangtze River Delta hosts manufacturing clusters producing RF chipsets for next-generation surveillance hardware.
United Kingdom
Heathrow and Gatwick operational demands pressure NATS toward satellite augmentation for oceanic route coverage. The Civil Aviation Authority enforces ICAO GADSS distress tracking timelines for commercial transport. Cranfield and Farnborough anchor aerospace research clusters developing autonomous tracking algorithms for unmanned aerial systems integration.
Japan
ANA and JAL operational control centers prioritize API-centric tracking platforms for complex transpacific networks. METI industrial policy supports domestic satellite payload hosting partnerships. Nagoya and Tokyo Bay manufacturing corridors produce compact transponder modules for regional jet retrofits.
Flight Tracking System Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with satellite payload hosts and ground station operators commanding bottleneck positions. The vendor base concentrates around RF chipset fabricators and constellation operators, while data analytics providers fragment across airline IT procurement. Three archetypes dominate: avionics incumbents leveraging installed bases, satellite operators hosting space-based receivers, and software platforms unbundling tracking from legacy suites. M&A activity targets predictive maintenance convergence capabilities, while strategic partnerships link hardware manufacturers to cloud infrastructure providers.
Among North American avionics specialists, Honeywell International Inc. and Garmin Ltd. exemplify divergent positioning strategies. Honeywell occupies a position bundling connectivity with operational portals, while Garmin anchors the general aviation segment with portable and panel-mount hardware. Aireon LLC represents the satellite-hosted payload archetype through its Iridium NEXT constellation integration, compressing competitive advantage for ground-station-centric vendors.
| Leading Market Players |
|---|
| Aireon LLC |
| SKY TRAC SYSTEMS LTD |
| Honeywell International Inc. |
| BLUE SKY NETWORK |
| Spider Tracks Limited |
| Garmin Ltd. |
| FLYHT Aerospace Solutions Ltd. |
| General Electric (GE Aviation) |
| Rockwell Collins (Collins Aerospace) |
| Others |
Supply Flow & Price Mechanics
RF chipset fabrication costs cascade through three distinct pricing tiers as transponder manufacturers source from concentrated East Asian foundries, with premium-certified units commanding substantial markups over general aviation alternatives.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for ADS-B transponder modules. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified commercial units from experimental-category hardware and portable receivers. Pricing pressure stems from low-cost Chinese manufacturers entering the general aviation segment. Charter operators exhibit highest price sensitivity, while network carriers prioritize certification reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Singapore, Frankfurt, and Dallas-Fort Worth anchor hub-and-spoke patterns for spare transponder logistics. Manufacturing concentrates in Taiwan, China, and Malaysia for RF chipsets, with final assembly in Mexico and Poland. Raw material dependencies include gallium arsenide substrates, precision oscillators, and aerospace-grade aluminum enclosures. Single-source vulnerability concentrates in L-band frequency components. Distribution runs through authorized avionics dealers and direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in predictive maintenance bundling as airlines shift procurement from discrete hardware to recurring data-service contracts.
For Market Incumbents: Hedge against satellite-based payload disruption by deepening partnerships with constellation operators like Iridium NEXT. Acquire predictive maintenance analytics capabilities before specialized software vendors capture airline IT budgets. Prioritize cloud security certifications to accelerate government agency procurement cycles. For New Entrants and Emerging Players: Begin with the general aviation retrofit segment, where over 200,000 piston aircraft lack ADS-B Out equipage. Target voluntary adoption acceleration through mobile-integrated portable transponders. Pursue API-centric platform positioning to bypass incumbent avionics suites. For Investors and Strategic Acquirers: Roll-up economics work for fragmented data analytics specialists because airline unbundling trends fragment procurement decisions across IT and flight operations departments. Five-to-ten year viability hinges on satellite constellation deployment completion. Monitor ICAO GADSS distress tracking compliance deadlines as inflection indicators for hardware replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Satellite Payload Hosting Partnership | Aireon LLC's Iridium NEXT integration compresses ground-station-centric vendor advantages. |
| Predictive Maintenance Platform Acquisition | Honeywell bundles connectivity with operational portals to capture recurring airline revenue. |
| Cloud Security Certification Investment | FedRAMP and equivalent accreditations unlock delayed government agency procurement. |
| General Aviation Channel Expansion | Garmin's portable receiver ecosystem penetrates the 200,000-unit piston aircraft retrofit market. |
| API-Centric Platform Development | North American hub-and-spoke carriers unbundle tracking from legacy flight planning suites. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with avionics engineering directors, airline operational control center managers, FAA certification specialists, and satellite payload program executives informed demand-side assessments. Secondary sources include FAA ADS-B equipage databases, EASA regulatory filings, ICAO GADSS implementation timelines, and customs records for RF chipset trade flows. Bottom-up fleet retrofit projections triangulate against top-down infrastructure spending forecasts.
Rate-of-change decomposition separates transponder hardware replacement cycles from satellite-based augmentation adoption curves across the projection horizon. Segmentation dimensions modeled include technology type, end-user category, deployment architecture, and service tier. CAGRs derive from regression analysis of historical equipage rates against regulatory mandate deadlines. Forecast inputs incorporate semiconductor foundry capacity expansion schedules and WRC spectrum allocation proceedings.
Several conditions sit outside the modeled scope, including unannounced aircraft fleet retirement programs and geopolitical disruptions to East Asian foundry operations. Forecasts reflect assumptions about regulatory timeline adherence and constellation deployment schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
Navigational Inertial Systems Market
Communication Navigation & Surveillance
Drone Transponders Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Tactical Data Link Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Space Situational Awareness Sensor and Tracking Performance Test Systems Market
Communication Navigation & Surveillance
Global Military Communications Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Airborne Laser Obstacle Avoidance Monitoring Systems Market
Communication Navigation & Surveillance
Land-Based Situational Awareness Systems Market
Communication Navigation & Surveillance
Weapon Locating Radar Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
Coherent Radar Market