
 UK Airport Operations Market | 2026-2036
UK Airport Operations Market Size, Share, and Industry Trends Forecast 2026-2036
UK Airport Operations Market Insights
Air traffic controller and ground handling labor shortages is reorganizing how UK airports scale capacity during peak seasons. Heathrow Airport Holdings sustains slot-constrained operations through capital-intensive infrastructure expansion. Manchester Airports Group dominates Northern England connectivity with multi-airport network coordination. Gatwick Airport Limited differentiates through single-runway efficiency optimization that maximizes aircraft movements per hour.
UK airport operations encompass the integrated management of airside and landside activities including runway condition monitoring, passenger processing throughput metrics, and aircraft turnaround time standards, serving the commercial imperative of safe, efficient air transport facilitation. Facility management and security screening segments absorb disproportionate capital allocation due to regulatory compliance intensity and infrastructure renewal cycles. Biometric identification and automated check-in technologies within the technology adoption dimension are capturing investment priority as airports pursue touchless passenger journeys and reduced staffing dependencies.
The UK Civil Aviation Authority enforces safety management system mandates while the Department for Transport coordinates surface access decarbonization requirements that reshape ground fleet procurement decisions. CAA licensing standards for ground handling personnel directly constrain operational scalability and training cost structures across licensed aerodromes. Stakeholders must weigh biometric infrastructure deployment against legacy system interoperability risks and evolving data protection obligations under UK GDPR-derived aviation security protocols.
Market Dynamics
Slot scarcity at Heathrow and Gatwick is forcing capacity expansion through airfield reconfiguration and off-peak scheduling optimization rather than additional runway construction. The UK Civil Aviation Authority's tightening emissions mandates are accelerating fleet turnover decisions among ground handling operators.
Growth Catalysts
- Net-Zero Aviation Strategy:The UK Civil Aviation Authority's operational emissions standards are compelling airports to electrify ground support equipment fleets and secure renewable energy contracts for terminal operations.
- Biometric Passenger Processing:Touchless identification technologies are reducing processing times at security checkpoints and border control, enabling higher passenger throughput without proportional staffing increases.
- London-South East Demand Concentration:Heathrow and Gatwick anchor sustained passenger volume growth that justifies capital-intensive infrastructure automation investments across their operational networks.
Market Restraints
- Air Traffic Controller Shortages:CAA licensing bottlenecks for air traffic control officers constrain operational scalability during peak seasonal demand windows across licensed aerodromes.
- Lithium Supply Concentration:Battery raw material sourcing dependencies for electric ground support equipment create input cost volatility and supply security risks for fleet electrification programs.
- Legacy System Interoperability:Biometric infrastructure deployment faces technical friction against existing passenger service systems, requiring costly middleware development and extended integration timelines.
Strategic Opportunities
- Northern England Connectivity:Manchester Airports Group's multi-airport network coordination creates expansion white space in underserved regional markets outside the London-South East corridor.
- Automated Check-In Convergence:Integration of mobile identity verification with self-service bag drop technologies is enabling fully touchless passenger journeys from curb to gate.
- Surface Access Decarbonization:Department for Transport coordinated requirements are creating procurement tailwinds for zero-emission ground fleet transitions and charging infrastructure deployment.
Industry Challenges
- Ground Handling Personnel Certification:CAA licensing standards for specialized ramp operations create training cost burdens and workforce pipeline constraints that limit operational flexibility during demand surges.
- Data Protection Compliance Complexity:UK GDPR-derived aviation security protocols impose evolving obligations on biometric data collection, storage, and cross-border transfer that complicate technology vendor selection.
- Infrastructure Renewal Cycles:Facility management and security screening segments require disproportionate capital allocation for regulatory compliance, compressing available investment for passenger experience technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Airport Operations Market |
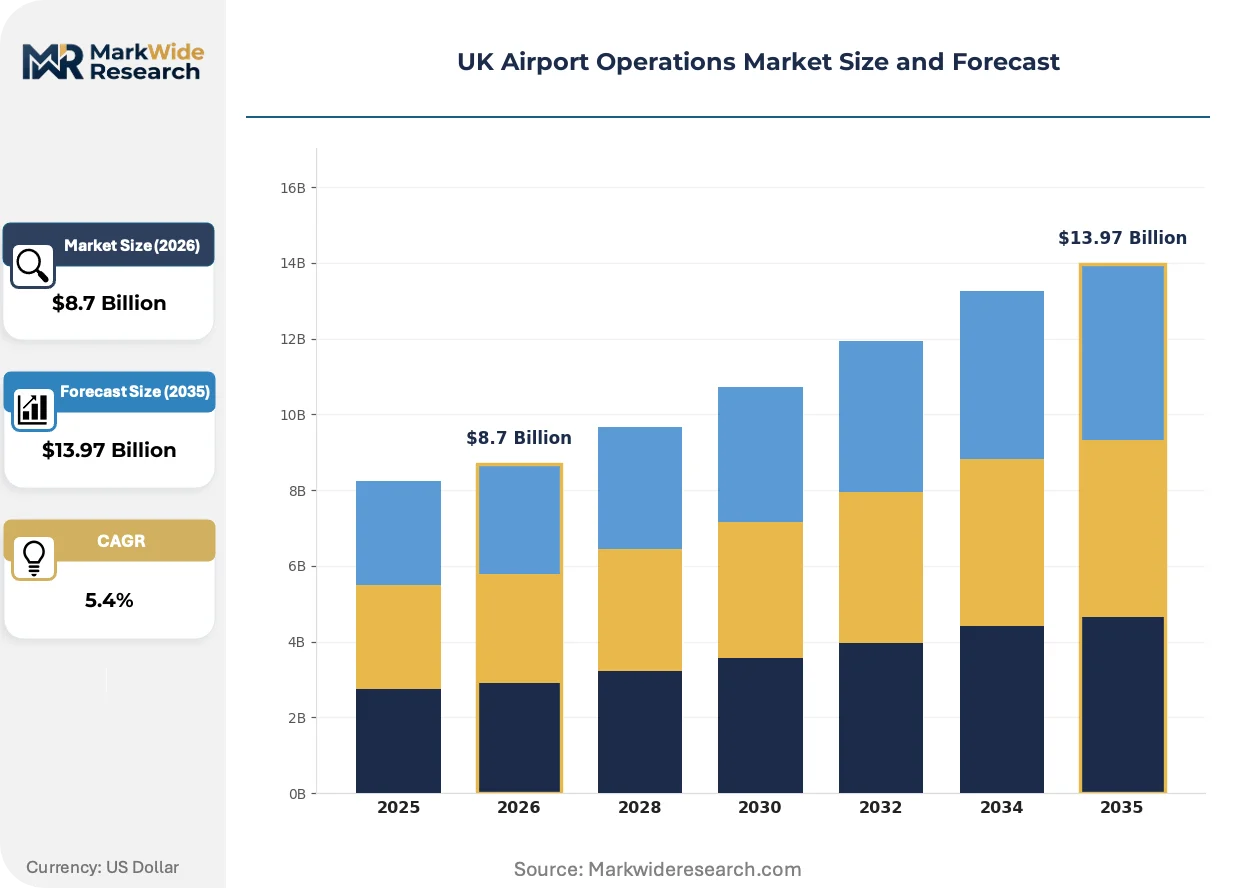
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Runway Maintenance, Passenger Services, Security Screening, Aircraft Handling, Baggage Management, Facility Management Technology Adoption: Biometric Identification, Automated Check-in, IoT Sensors, AI Surveillance, Mobile Boarding Pass, Remote Monitoring Application: Flight Scheduling, Ground Support, Emergency Response, Cargo Handling, Customer Experience, Traffic Control End User: Airlines, Ground Handlers, Security Agencies, Airport Authorities, Catering Providers, Retail Operators |
| Companies Covered | Stansted Airport Limited, Fraport, Heathrow Airport Holdings, Optime Group, Aéroports de Paris, Gatwick Airport Limited, Birmingham Airport, PointrLabs, Manchester Airports Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Airport Operations Market Trends and Innovations
Digital automation is restructuring core operational workflows across UK airports, with particular intensity in passenger processing and airside fleet management. Three interconnected developments are determining competitive positioning and capital allocation priorities.
Biometric facial recognition systems are supplanting traditional document-based identity verification at check-in, security, and boarding gates. British Airways and other major carriers are deploying these technologies at Heathrow and Gatwick terminals to compress passenger processing times. This transition is enabling single-token journeys that eliminate repeated document checks while reducing staffing dependencies at high-throughput checkpoints.
The UK Civil Aviation Authority's safety management system mandates are tightening audit frequencies and documentation requirements for airside operations. Ground handling operators must now demonstrate continuous risk monitoring capabilities through digital reporting platforms rather than periodic compliance submissions. Smaller regional airports lacking integrated safety management infrastructure face disproportionate compliance cost burdens relative to their revenue bases.
Airlines are consolidating ground handling contracts around performance-based service level agreements that penalize aircraft turnaround time overruns. British Airways' procurement team at Heathrow has shifted from unit-rate pricing to outcome-based contracts that tie operator payments to on-time performance metrics. This reconfiguration is most visible at slot-constrained airports where turnaround efficiency directly determines daily aircraft movement capacity.
UK Airport Operations Market Segmentation
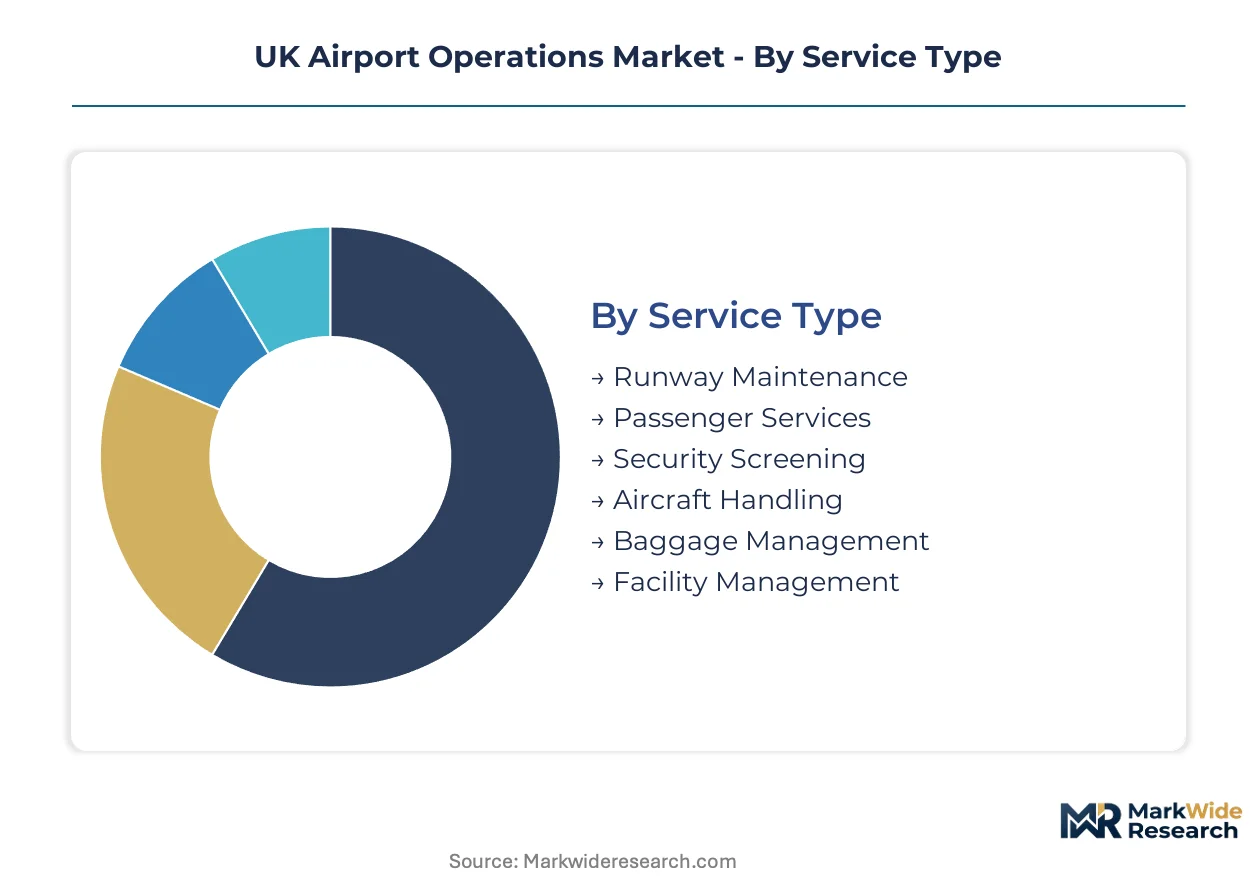
Segmentation reveals where capital allocation concentrates across UK airport operations and which service lines face displacement from automation. Understanding these boundaries clarifies where infrastructure spending outpaces operational budgets and where regulatory compliance reshapes procurement priorities.
Service Type:
Facility Management and Security Screening absorb disproportionate capital due to regulatory compliance intensity, while Passenger Services faces the strongest substitution pressure from biometric automation and self-service technologies.
- Facility Management:Terminal infrastructure upkeep, energy systems management, and regulatory compliance maintenance. Demand concentrates at Heathrow and Gatwick where aging infrastructure renewal cycles coincide with net-zero retrofit mandates from the UK Civil Aviation Authority.
- Security Screening:Passenger and baggage threat detection, checkpoint throughput optimization, and CAA-mandated equipment upgrades. London-South East corridor airports prioritize this segment as biometric integration and automated tray return systems reduce staffing dependencies while maintaining throughput standards.
- Aircraft Handling:Pushback operations, towing services, and ground support equipment coordination.
- Baggage Management:Automated sorting systems, tracking technologies, and mishandled baggage recovery operations.
- Passenger Services:Check-in assistance, wayfinding, and special needs support.
- Runway Maintenance:Pavement condition monitoring, lighting system upkeep, and foreign object debris management.
Facility Management retains volume leadership; Security Screening holds the steepest expansion curve.
Technology Adoption:
Cost tier differentiation separates proven deployments from experimental pilots, with premium-tier biometric systems commanding infrastructure budgets while mobile boarding passes saturate economy-tier operations.
- Biometric Identification:Facial recognition systems for single-token passenger journeys from curb to gate. Heathrow and Gatwick terminals drive demand as British Airways and other major carriers deploy touchless identification to compress processing times and reduce checkpoint staffing.
- Automated Check-in:Self-service kiosks, mobile identity verification, and bag drop automation. Manchester Airports Group coordinates multi-airport network deployment to capture regional efficiency gains outside the London-South East concentration.
- AI Surveillance:Perimeter intrusion detection and behavioral analytics for security operations.
- IoT Sensors:Environmental monitoring, asset tracking, and predictive maintenance for airside equipment.
- Remote Monitoring:Centralized control of distributed airport systems and off-site security oversight.
- Mobile Boarding Pass:Smartphone-based boarding authorization and digital wallet integration.
Biometric Identification captures the premium infrastructure tier; Automated Check-in expands most quickly across regional airport networks.
Application:
Volume concentration in Flight Scheduling and Ground Support reflects slot-constrained operations at Heathrow and Gatwick, while Customer Experience applications gain share through competitive differentiation investments.
- Flight Scheduling:Slot allocation management, off-peak optimization, and airfield reconfiguration planning. Heathrow Airport Holdings sustains constrained capacity through capital-intensive scheduling automation rather than additional runway construction.
- Ground Support:Aircraft turnaround coordination, fueling operations, and electric ground support equipment deployment. The UK Civil Aviation Authority's tightening emissions mandates accelerate fleet turnover decisions among handling operators at licensed aerodromes.
- Traffic Control:Air traffic management, ground movement coordination, and CAA safety system compliance.
- Cargo Handling:Freight processing, cold chain maintenance, and dedicated cargo facility operations.
- Emergency Response:Incident command systems, rescue coordination, and regulatory drill compliance.
- Customer Experience:Wayfinding optimization, retail integration, and passenger satisfaction measurement.
Ground Support retains operational volume leadership; Customer Experience gains share fastest through competitive differentiation mandates.
End User:
Customer type segmentation distinguishes capital-intensive infrastructure owners from service contractors, with Airport Authorities and Airlines driving procurement decisions while Ground Handlers face margin compression from performance-based contracting.
- Airport Authorities:Infrastructure owners responsible for terminal operations, regulatory compliance, and long-term capital planning. Heathrow Airport Holdings and Manchester Airports Group dominate procurement volumes through multi-billion-pound infrastructure automation programs.
- Airlines:Carriers procuring ground handling, passenger processing, and turnaround efficiency services. British Airways' procurement team at Heathrow shifted from unit-rate pricing to outcome-based contracts tying operator payments to on-time performance metrics.
- Ground Handlers:Specialized contractors providing ramp operations, baggage handling, and aircraft servicing.
- Security Agencies:Government and private entities responsible for threat detection and border control.
- Catering Providers:In-flight meal preparation, logistics, and galley loading operations.
- Retail Operators:Duty-free concessionaires, food and beverage vendors, and commercial space management.
Airport Authorities retain procurement volume leadership; Airlines hold the steepest technology adoption curve through direct passenger experience investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The London-South East corridor commands premium infrastructure pricing that northern regions cannot replicate, creating a two-tier investment dynamic across UK airport operations. Heathrow and Gatwick anchor capacity constraints that drive capital-intensive automation, while Manchester and Birmingham pursue network coordination strategies to capture underserved demand.
London and South East
Heathrow Airport Holdings sustains slot-constrained operations through airfield reconfiguration rather than runway expansion, driving demand for biometric passenger processing and automated ground support equipment. The UK Civil Aviation Authority's net-zero aviation strategy mandates electrification of terminal operations and ground fleets across licensed aerodromes. British Airways and major carriers deploy single-token biometric journeys at Heathrow and Gatwick terminals to compress processing times amid chronic capacity pressure.
North England
Manchester Airports Group coordinates multi-airport network operations across Manchester, Stansted, and East Midlands to capture regional connectivity demand outside the London corridor. The Department for Transport's surface access decarbonization requirements reshape ground fleet procurement across northern licensed aerodromes. Manchester Airport anchors Northern England's largest passenger throughput, with network coordination enabling operational scale that justifies infrastructure automation investments.
Midlands
Birmingham Airport pursues capacity expansion through runway extension and terminal reconfiguration to capture transfer traffic bypassing London congestion. CAA safety management system mandates tighten audit frequencies for airside operations across Midlands licensed aerodromes. The Birmingham Airport catchment area serves England's second-largest city region, with surface access improvements connecting to the HS2 corridor driving passenger volume growth projections.
Scotland
Edinburgh and Glasgow airports face seasonal demand volatility that constrains year-round infrastructure automation investments relative to English counterparts. The Scottish Government's transport decarbonization plan imposes accelerated ground fleet electrification timelines on regional airport operators. Edinburgh Airport anchors Scottish passenger throughput, with limited slot constraints enabling operational flexibility that reduces capital intensity for biometric infrastructure deployment.
Wales and Northern Ireland
Cardiff and Belfast airports operate below critical scale thresholds that would justify premium-tier biometric infrastructure investments, concentrating procurement on automated check-in and mobile boarding pass technologies. CAA licensing bottlenecks for air traffic control officers constrain operational scalability during peak seasonal demand windows across smaller licensed aerodromes. Belfast International Airport serves Northern Ireland's primary connectivity node, with post-Brexit border processing requirements driving security screening capital allocation.
UK Airport Operations Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across UK airport operations, creating segmented competitive dynamics. Infrastructure owners with slot-constrained assets at Heathrow and Gatwick deploy capital-intensive automation to maximize throughput, while regional operators prioritize network coordination and operational flexibility. Three archetypes dominate: integrated airport groups with multi-site portfolios, single-site efficiency optimizers, and specialized technology vendors supplying biometric and automation systems. Competitive moves concentrate on strategic partnerships for technology deployment and infrastructure consolidation through group structures that spread fixed costs across multiple licensed aerodromes.
Among integrated infrastructure groups, Heathrow Airport Holdings and Manchester Airports Group occupy positions that exemplify scale-driven operational strategies, with the former representing slot-constrained premium-tier positioning and the latter illustrating network coordination across dispersed geographic footprints. Gatwick Airport Limited sits within the single-site efficiency optimizer tier, demonstrating how runway-constrained operations drive specialized turnaround optimization. Optime Group and PointrLabs represent technology vendor archetypes supplying automation infrastructure to licensed aerodromes without direct operational ownership.
| Leading Market Players |
|---|
| Stansted Airport Limited |
| Fraport |
| Heathrow Airport Holdings |
| Optime Group |
| Aéroports de Paris |
| Gatwick Airport Limited |
| Birmingham Airport |
| PointrLabs |
| Manchester Airports Group |
| Others |
Pricing and Supply Chain Analysis
Heathrow's slot-constrained scale economies concentrate procurement power among a handful of infrastructure groups, compressing price floors for ground handling services while elevating premiums for biometric-integrated facility management contracts. Manchester Airports Group's multi-site coordination spreads fixed costs across northern licensed aerodromes, creating tiered pricing bands that regional operators cannot match.
Pricing Analysis
The customization-premium spread separates configured-to-order biometric infrastructure deployments from standard automated check-in kiosk rollouts. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade for CAA safety management compliance and volume scale of passenger throughput. Pricing pressure stems from lithium supply concentration for electric ground support equipment fleets, compressing margins on electrification contracts. Regional airport authorities exhibit highest price sensitivity due to limited passenger volumes, while Heathrow Airport Holdings demonstrates lowest sensitivity given slot scarcity and captive demand.
Supply Chain Analysis
Inventory lead-times for biometric hardware and electric ground support equipment extend procurement cycles beyond traditional facility management sourcing rhythms. Manufacturing concentrates in China, Germany, and the United States for facial recognition systems and battery components. Supply chains draw from lithium carbonate, cobalt, and advanced sensor arrays as critical inputs. Single-source vulnerability permeates battery cell supply for fleet electrification programs. Distribution runs through specialized aviation technology integrators and OEM-direct channels to licensed aerodromes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric passenger processing penetration sits below critical mass across UK regional airports, positioning the market for early-cycle expansion as CAA emissions mandates accelerate infrastructure replacement decisions.
For Market Incumbents: Secure long-term renewable energy contracts for terminal operations to lock in net-zero compliance costs before grid price volatility intensifies. Deepen backward integration into ground support equipment maintenance capabilities to capture performance-based contract premiums from British Airways and major carriers. The UK Civil Aviation Authority's tightening safety management system audit frequencies threaten smaller competitors with disproportionate compliance burdens. For New Entrants and Emerging Players: Anchor in Northern England connectivity gaps where Manchester Airports Group's network coordination leaves underserved regional markets. Target automated check-in convergence opportunities at Cardiff and Belfast airports operating below critical scale thresholds for premium biometric deployment. Pursue mobile identity verification partnerships with self-service bag drop technology vendors to bypass incumbent infrastructure lock-in. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized automation vendors supplying biometric infrastructure without operational asset ownership. Long-term viability hinges on interoperability middleware development that bridges legacy passenger service systems. Acquisition targets should demonstrate UK GDPR-derived aviation security protocol compliance capabilities. The signal to watch is CAA licensing bottleneck resolution for air traffic control officers, which would unlock capacity expansion capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Infrastructure Deployment | Heathrow and Gatwick compression of passenger processing times reduces checkpoint staffing dependencies. |
| Electric Ground Fleet Transition | UK Civil Aviation Authority emissions mandates accelerate procurement of battery-powered support equipment. |
| Multi-Airport Network Coordination | Manchester Airports Group spreads fixed automation costs across Manchester, Stansted, and East Midlands. |
| Performance-Based Contracting | British Airways ties operator payments to on-time performance metrics rather than unit-rate pricing. |
| Safety Management System Digitization | CAA mandates continuous risk monitoring platforms replacing periodic compliance submissions. |
Research Methodology
Cross-validation between primary interviews with airport operations directors and secondary regulatory filings anchors the qualitative findings. Stakeholder conversations encompassed infrastructure procurement managers at Heathrow Airport Holdings and Manchester Airports Group, CAA licensing officials, ground handling operator executives, and biometric technology vendor account directors. Secondary sources included UK Civil Aviation Authority safety management system mandates, Department for Transport surface access decarbonization requirements, SEC filings from listed airport groups, and UK airport passenger throughput statistics. Bottom-up service line modeling triangulates against top-down regional demand aggregation.
Sensitivity analysis tested forecast robustness across the projection horizon through alternative scenario weighting. Segmentation dimensions encompassed service type, technology adoption tier, application function, and end-user archetype. CAGRs derive from regression-adjusted historical throughput trends and infrastructure investment pipeline tracking. Industry-specific inputs include CAA electrification mandate timelines and biometric deployment schedules at major terminals.
Material uncertainties — regulatory enforcement intensity for emissions standards, lithium supply disruption, and air traffic controller licensing resolution — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology adoption curves and infrastructure replacement cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
Aircraft Ground Handling System Market
Airport Operations
Global Airside Services Market
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
Business Jet Ground Handling Services Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Airport Terminal Operations Market
Airport Operations
Canada Airport Operations Market
Airport Operations
Airport Operations Market
Airport Operations
Airport Ground Handling Market
Airport Operations
Global Air Charter Services Market
Airport Operations
South Korea Airport Operations Market
Airport Operations
France Airport Operations Market
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market
Airport Operations
Europe Airport Operations Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
Middle East Airport Operations Market