
 Aircraft Ground Handling System Market | 2026-2036
Aircraft Ground Handling System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Ground Handling System Market Analysis
SAE ARP 4852B-compliant electric ground support equipment is unwinding legacy diesel-based fleet economics across major hub airports. Swissport International leverages its global station network to standardize turnaround protocols across 300-plus locations. Menzies Aviation anchors European cargo handling through specialized freighter ramp services at Amsterdam Schiphol and Frankfurt. Dnata competes on scale in the Middle East and Asia-Pacific with integrated passenger and ramp service contracts.
An aircraft ground handling system encompasses the equipment, vehicles, and operational protocols required to service aircraft during terminal and remote stand operations, including 400 Hz power units delivering precise voltage for onboard systems, preconditioned air units, and towbarless tractors capable of moving aircraft up to 600,000 pounds. Its primary purpose is minimizing turnaround time between landing and departure while ensuring safety compliance. Ramp services generate the highest equipment utilization rates due to continuous aircraft movement cycles, while automated systems represent the fastest-expanding technology segment as airports pursue labor reduction and precision docking. Cargo handling commands premium pricing per aircraft turn because of specialized containerized loading requirements and temperature-controlled storage integration.
The FAA mandates specific ground support equipment safety standards under 14 CFR Part 139, while OSHA enforces worker exposure limits during aircraft fueling and de-icing operations; both frameworks directly shape equipment specifications and training investments. In Europe, EASA's CS-25 airworthiness requirements and the EU Green Deal's airport decarbonization targets are accelerating electric GSE procurement timelines. Stakeholders must weigh capital intensity against regulatory compliance deadlines as electrification mandates tighten across multiple jurisdictions.
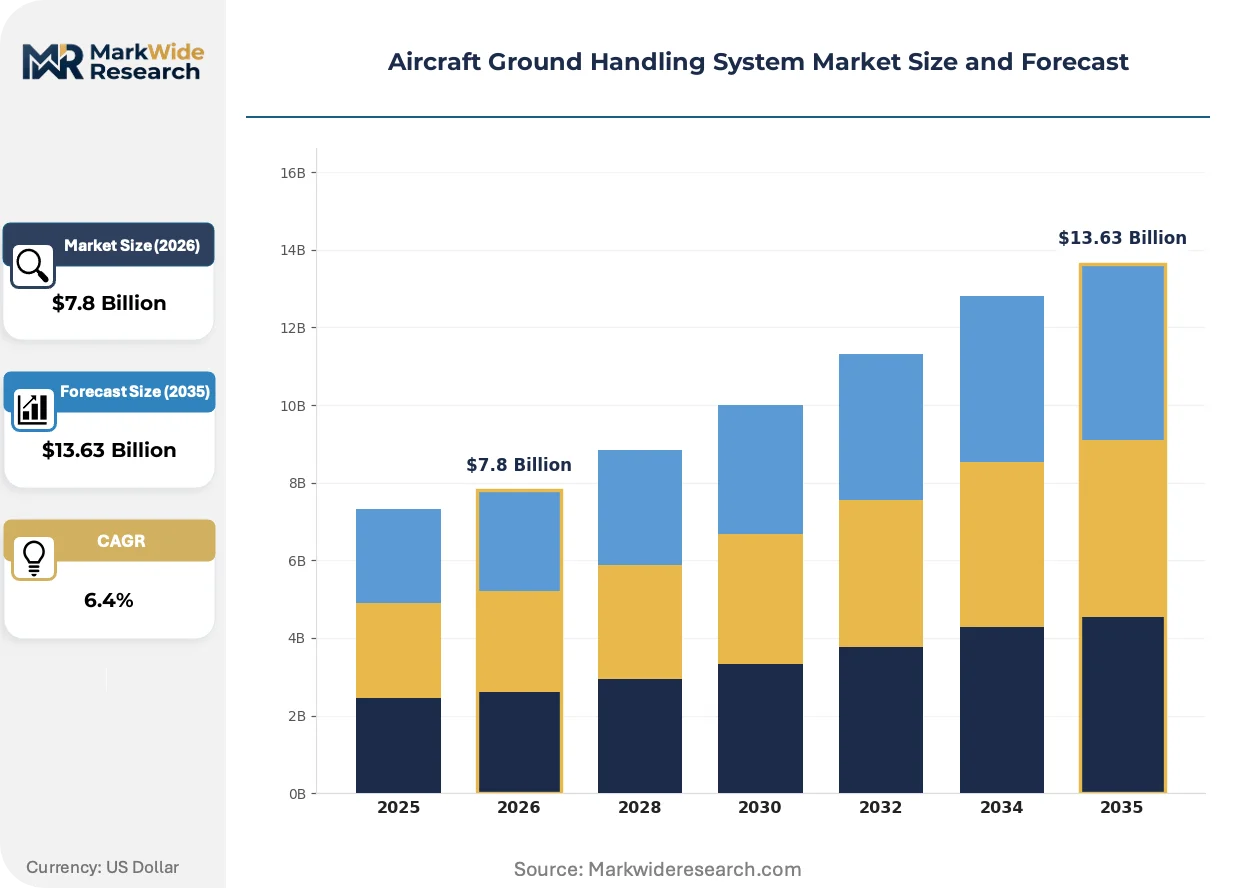
Market Dynamics
SAE ARP 4852B electrification mandates are compressing diesel ground support equipment replacement cycles at major hub airports, forcing simultaneous capital deployment across power infrastructure, fleet procurement, and technician retraining.
Growth Catalysts
- FAA 14 CFR Part 139 mandates:Updated winter de-icing protocols in the United States require equipment upgrades at Category X airports, pulling forward replacement demand for glycol recovery systems and heated containment units.
- India airport privatization:Greenfield terminal construction at Delhi, Mumbai, and Bangalore is creating capacity bottlenecks that only modern handling infrastructure can resolve, concentrating procurement in 2024-2027.
- Towbarless tractor adoption:Pushback equipment capable of moving 600,000-pound aircraft without towbars is reducing turnaround times by eliminating coupling delays and ground crew exposure.
Market Restraints
- Lithium-ion supply concentration:Battery cell production for electric GSE clusters in China and South Korea, exposing procurement to export control volatility and freight cost spikes.
- Airport tenancy structures:Short-term ground handling licenses at privatized terminals prevent 10-15 year capital recovery horizons for electrified fleet investments.
- Legacy 400 Hz infrastructure:Existing solid-state ground power units lack interoperability with next-generation aircraft electrical loads, stranding sunk capital.
Strategic Opportunities
- EU Green Deal airport decarbonization:Binding 2030 targets for Scope 1 emissions at member state hubs are accelerating electric GSE procurement timelines ahead of total cost parity.
- Preconditioned air unit integration:Convergence of thermal storage batteries with PCA systems enables peak-shaving during summer demand surges, opening retrofit markets at slot-constrained airports.
- Cargo handler specialization:Temperature-controlled pharmaceutical ramp services at Amsterdam Schiphol and Frankfurt command premium pricing per aircraft turn.
Industry Challenges
- High-voltage technician certification:OSHA worker exposure limits during electric GSE maintenance require specialized training pipelines that airport authorities lack capacity to staff.
- Interoperability with legacy fleets:Mixed diesel-electric operations during transition periods complicate fueling infrastructure, charging depot placement, and spare parts logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Ground Handling System Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ramp Services, Passenger Services, Cargo Handling, Aircraft Maintenance Technology: Automated Systems, Electric Towbarless Tractors, Mobile Apps, Ground Support Equipment Application: Commercial Aviation, Military Aviation, Cargo Transport, Corporate Jets End User: Airlines, Ground Handling Companies, Airports, Aircraft Operators |
| Companies Covered | Swissport International, Dnata, Menzies Aviation, SATS, TLD Group, John Bean Technologies Corporation, Cavotec SA, Oshkosh AeroTech, Aviapartner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Ground Handling System Market Emerging Trajectories
Electrification is rewriting equipment lifecycle economics while regulatory deadlines compress procurement windows, creating simultaneous pressure on capital allocation and operational continuity.
Autonomous electric tow tractors equipped with precision docking sensors are supplanting manned pushback operations at Category X hubs. Full-service carriers in Southeast Asia are piloting these systems during night curfew windows to validate safety protocols before daytime deployment. The technology is supplanting traditional towbar-based workflows and enabling 90-second coupling intervals that manual crews cannot replicate.
EASA CS-25 airworthiness requirements for ground support equipment interoperability are mandating standardized electrical connectors and communication protocols across European Union member states. Equipment manufacturers must now certify simultaneous compliance with EASA, FAA, and ICAO standards to serve multinational carrier fleets. Narrow-body ramp services face the steepest certification burden due to higher aircraft rotation frequencies and shorter turnaround windows.
Airlines are unbundling ground handling contracts from full-service agreements and awarding standalone ramp, cargo, and passenger service components to specialized providers. Low-cost carriers at secondary airports are driving this fragmentation, seeking unit-cost transparency rather than bundled convenience. The shift is most visible in India, where privatized terminals now host three competing handlers per service category.
Aircraft Ground Handling System Market Segmentation
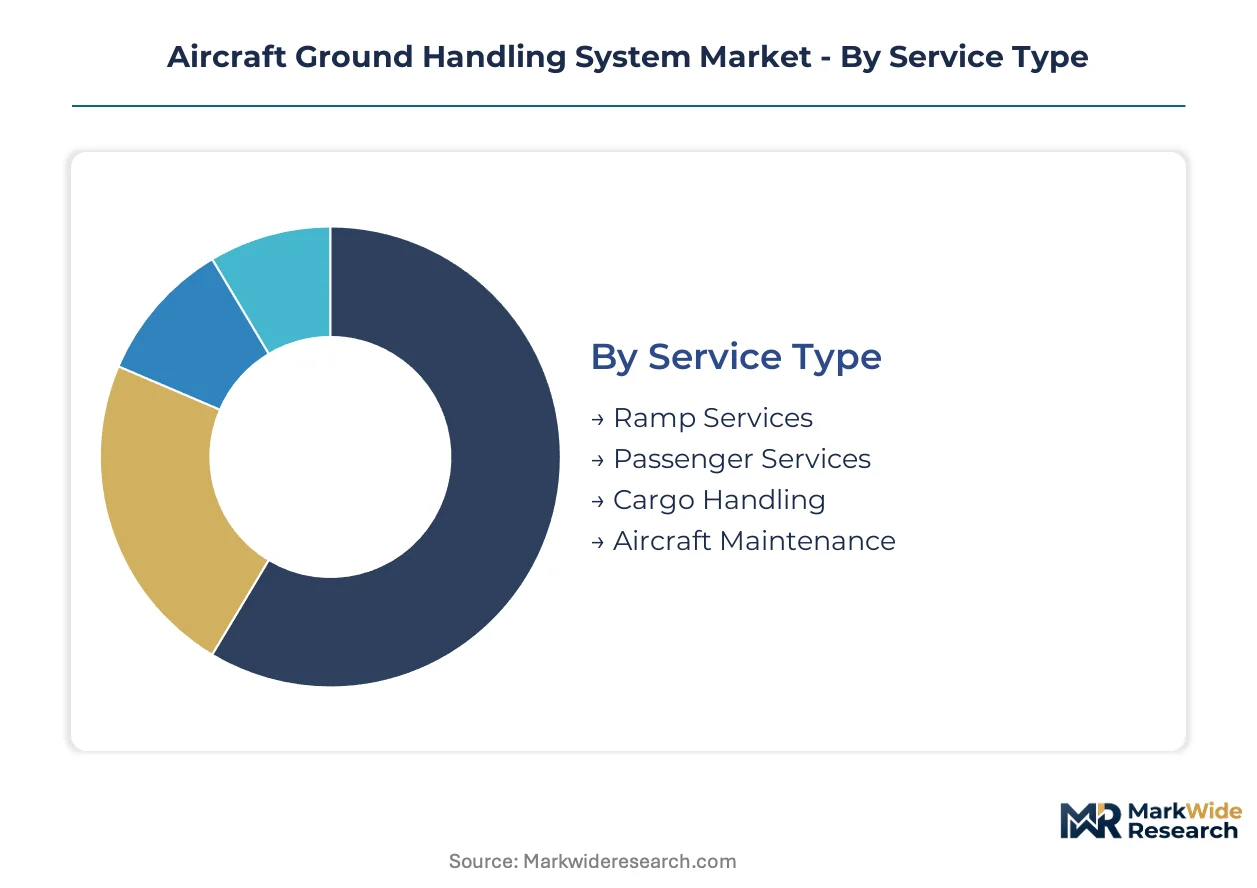
Segmentation in aircraft ground handling systems reveals how procurement channels split between direct airline ownership, ground handler leasing pools, and airport authority concessions. Equipment specifications vary sharply across these channels, with automated systems flowing through integrator partnerships while electric tractors move via fleet financing arrangements.
Service Type:
Ramp services dominate equipment utilization cycles, driving channel concentration through dedicated ground handling contracts at major hubs. Passenger services flow through fragmented airline-direct procurement, while cargo handling concentrates via specialized freight operators.
- Ramp Services:Continuous aircraft movement cycles demand 400 Hz power units, preconditioned air systems, and towbarless tractors operating under 14 CFR Part 139 safety mandates. Demand clusters at Category X airports in the United States where FAA winter de-icing protocols force equipment upgrades. Swissport International standardizes turnaround protocols across 300-plus locations, consolidating procurement scale.
- Cargo Handling:Specialized containerized loading requirements and temperature-controlled storage integration command premium pricing per aircraft turn. Menzies Aviation anchors European volume through freighter ramp services at Amsterdam Schiphol and Frankfurt, while Dnata competes on integrated contracts in the Middle East and Asia-Pacific.
- Passenger Services:Jet bridge operations, passenger boarding stairs, and bussing coordination equipment flow through airline-ground handler split contracts at privatized terminals.
- Aircraft Maintenance:Hangar-based support equipment including maintenance platforms and engine change systems channels through MRO provider networks with longer capital recovery horizons.
By volume, Ramp Services leads. By growth pace, Cargo Handling is ahead.
Technology:
Cost tier stratification separates mature diesel equipment from electrified systems carrying 40-60% capital premiums. Automated systems sit at the top tier with precision docking sensors and autonomous navigation, while mobile apps represent the lowest capital entry point.
- Automated Systems:Autonomous electric tow tractors equipped with precision docking sensors enable 90-second coupling intervals that manual crews cannot replicate. Full-service carriers in Southeast Asia pilot these systems during night curfew windows to validate safety protocols before daytime deployment.
- Electric Towbarless Tractors:Capable of moving 600,000-pound aircraft without towbars, these systems reduce turnaround times by eliminating coupling delays and ground crew exposure. EASA CS-25 airworthiness requirements and EU Green Deal decarbonization targets accelerate procurement timelines ahead of total cost parity.
- Mobile Apps:Digital task allocation and real-time turnaround tracking penetrate fastest at secondary airports where low-cost carriers drive unbundled service contracts.
- Ground Support Equipment:Legacy diesel-based fleet economics unwind as SAE ARP 4852B electrification mandates compress replacement cycles at major hub airports.
By maturity, Ground Support Equipment dominates installed base. By expansion trajectory, Automated Systems is climbing the fastest.
Application:
Customer type determines specification intensity, with commercial aviation demanding highest equipment diversity and military aviation requiring hardened interoperability standards.
- Commercial Aviation:Narrow-body ramp services face the steepest certification burden due to higher aircraft rotation frequencies and shorter turnaround windows. Full-service carriers in Southeast Asia expand outsourced ground operations to cut turnaround times.
- Cargo Transport:Temperature-controlled pharmaceutical ramp services command premium pricing per aircraft turn at major European hubs.
- Military Aviation:Hardened 400 Hz power units and tactical refueling systems must certify to dual civilian-military standards, extending procurement cycles.
- Corporate Jets:Fractional ownership models drive demand for flexible, multi-aircraft compatible handling equipment at executive terminals.
By equipment diversity, Commercial Aviation leads. By margin structure, Cargo Transport is gaining share fastest.
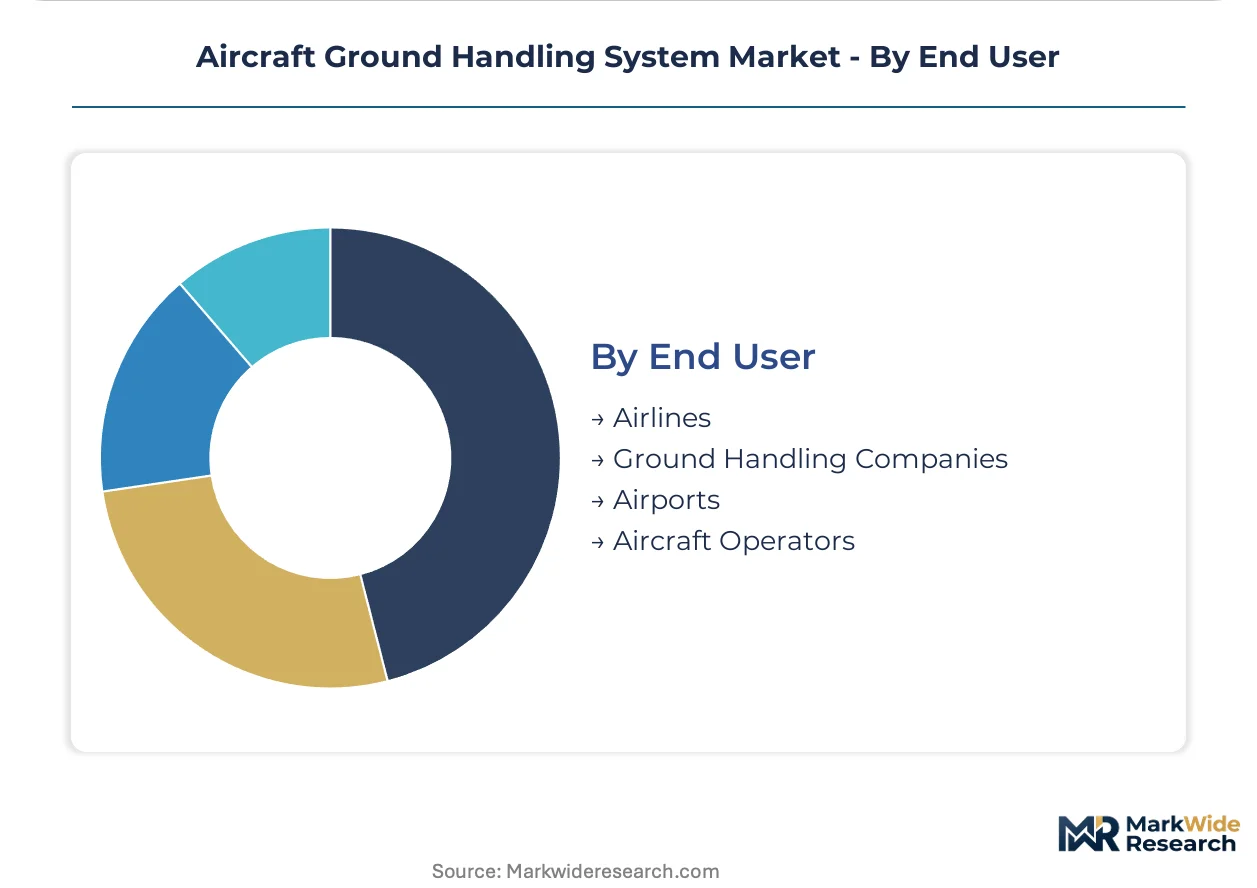
End User:
Supply concentration varies by end user type, with ground handling companies consolidating fleet purchasing power while airports fragment procurement across multiple concessionaires.
- Ground Handling Companies:Swissport International, Menzies Aviation, and Dnata leverage global station networks to standardize equipment specifications across 300-plus locations, capturing volume discounts from manufacturers.
- Airports:Privatized terminals in India now host three competing handlers per service category, fragmenting procurement authority and preventing 10-15 year capital recovery horizons for electrified fleet investments.
- Airlines:Full-service carriers unbundle ground handling contracts from full-service agreements, awarding standalone ramp and cargo components to specialized providers.
- Aircraft Operators:Corporate and charter fleets drive spot-market equipment rentals rather than capital ownership, concentrating demand at fixed-base operators.
By procurement scale, Ground Handling Companies leads. By contract flexibility, Aircraft Operators is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment import dependency shapes procurement timelines across major aviation hubs, with domestic manufacturing capacity determining fleet replacement velocity. Trade balance considerations intensify where electrification mandates accelerate faster than local battery assembly can satisfy.
United States
Category X airports drive concentrated demand for 400 Hz power units and glycol recovery systems under FAA 14 CFR Part 139 winter protocols. OSHA worker exposure limits during fueling and de-icing operations force specialized training investments. Chicago O'Hare and Atlanta Hartsfield-Jackson anchor procurement clusters where legacy diesel fleets face compressed replacement cycles.
Germany
EU Green Deal binding targets for Scope 1 emissions at member state hubs pull forward electric GSE procurement ahead of total cost parity. EASA CS-25 airworthiness requirements mandate standardized electrical connectors across ground support equipment. Frankfurt and Munich airports concentrate specialized freighter ramp services commanding premium pricing per aircraft turn.
India
Greenfield terminal construction at Delhi, Mumbai, and Bangalore creates capacity bottlenecks resolvable only through modern handling infrastructure. Airport privatization fragments procurement authority across three competing handlers per service category. The PLI scheme for manufacturing incentives draws equipment assembly toward Gujarat and Maharashtra industrial corridors.
United Arab Emirates
Dnata leverages integrated passenger and ramp service contracts across Dubai and Abu Dhabi hubs to capture scale advantages. MOHAP safety frameworks align with EASA interoperability standards for ground support equipment certification. Dubai International Airport hosts autonomous electric tow tractor pilots during night curfew windows validating daytime deployment protocols.
Singapore
SATS anchors Southeast Asian outsourced ground operations for full-service carriers seeking reduced turnaround times. The Civil Aviation Authority of Singapore enforces equipment safety standards converging with ICAO protocols for multinational carrier compatibility. Changi Airport's slot constraints drive preconditioned air unit integration with thermal storage batteries for peak-shaving during summer demand surges.
Aircraft Ground Handling System Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and contract flexibility dimensions, creating tiered procurement channels. Swissport International and Cavotec SA represent publicly traded entities with disclosed financials, while Dnata and Menzies Aviation operate under private ownership structures enabling longer strategic horizons. Three archetypes dominate: global station network operators standardizing protocols across 300-plus locations, regional cargo specialists anchoring freighter ramp services at major hubs, and equipment manufacturers integrating precision docking automation. Competitive moves concentrate on fleet electrification partnerships with battery cell suppliers and unbundled service contracts fragmenting traditional full-service agreements.
Among global station network operators, Swissport International and Dnata exemplify scale-driven positioning across 300-plus locations, while Menzies Aviation occupies a specialized freighter-focused niche at Amsterdam Schiphol and Frankfurt. TLD Group represents equipment manufacturer archetypes supplying towbarless tractors capable of 600,000-pound aircraft movement. John Bean Technologies Corporation and Oshkosh AeroTech sit within the ground support equipment fabrication tier where SAE ARP 4852B compliance requirements differentiate procurement eligibility.
| Leading Market Players |
|---|
| Swissport International |
| Dnata |
| Menzies Aviation |
| SATS |
| TLD Group |
| John Bean Technologies Corporation |
| Cavotec SA |
| Oshkosh AeroTech |
| Aviapartner |
| Others |
Supply Flow & Price Mechanics
Twelve-to-sixteen-week lead times for lithium-ion battery packs tether pricing power to cell production geography, compressing margins for electric GSE procurement while amplifying cost premiums for air-cargo handlers seeking rapid fleet conversion.
Pricing Analysis
Ground handling companies anchor contract-based long-term offtake pricing for electric tractor fleets, with price differentiation hinging on SAE ARP 4852B certification grade and after-sales maintenance bundling. Three-tier pricing structure across premium autonomous systems, standard electric towbarless tractors, and economy diesel legacy equipment stratifies procurement channels. Cost compression in the mid-tier electric segment is intensifying because battery cell supply clusters in China and South Korea expose buyers to freight cost volatility. Low-cost carriers at Indian privatized terminals exhibit highest price sensitivity, while integrated Middle Eastern handlers absorbing EU Green Deal compliance costs show lowest.
Supply Chain Analysis
Strategic stockpiling of high-voltage components dominates inventory strategy as ground handlers buffer against lithium-ion supply concentration in China, South Korea, and Japan. Electric GSE manufacturing draws from battery cell assemblies, precision docking sensors, and 400 Hz power electronics as critical inputs. Single-source vulnerability in semiconductor content for autonomous navigation systems threatens production continuity. Distribution runs through manufacturer-direct fleet financing arrangements and ground handler leasing pools at major hub airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft ground handling equipment demand tracks commercial aviation passenger traffic cycles, with recovery momentum building as Southeast Asian full-service carriers expand outsourced operations to reduce turnaround times.
For Market Incumbents: Secure long-term battery supply agreements with cell manufacturers to lock in pricing before EU Green Deal procurement deadlines compress availability. Defend station network density by standardizing turnaround protocols across 300-plus locations, preventing specialized cargo handlers from fragmenting freighter ramp contracts at Amsterdam Schiphol and Frankfurt.
For New Entrants and Emerging Players: Differentiate on autonomous electric tow tractor integration with precision docking sensors, targeting night-curfew validation contracts at Category X hubs as the most penetrable entry point. Pursue standalone ramp service unbundling at Indian privatized terminals where three competing handlers per category create procurement fragmentation ripe for specialized disruption.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated systems sub-segments as precision docking certification requirements extend R&D horizons beyond five-to-ten-year viability windows for pure equipment fabricators. Target acquisition profiles favoring ground handling companies with integrated passenger-ramp service contracts and established EASA-FAA dual certification pathways. Watch lithium-ion export control announcements from China and South Korea as the critical inflection signal for procurement cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion Partnership | Battery supply agreements with Chinese and South Korean cell manufacturers secure pricing ahead of EU Green Deal deadlines. |
| Autonomous System Certification | EASA CS-25 airworthiness compliance enables 90-second coupling intervals at Category X hubs. |
| Freighter Ramp Specialization | Temperature-controlled pharmaceutical services at Amsterdam Schiphol command premium per-turn pricing. |
| Multi-Handler Terminal Positioning | Privatized Indian airports fragment procurement authority, creating entry points for specialized providers. |
| Precision Docking R&D Investment | Sensor integration with towbarless tractors reduces ground crew exposure during pushback operations. |
Methodological Framework
A standing panel of ground handling operations directors, airport authority procurement managers, airline fleet planning executives, and electric GSE maintenance technicians provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against FAA 14 CFR Part 139 enforcement records, EASA CS-25 certification databases, EU Green Deal implementation timelines, and customs data for ground support equipment imports. Bottom-up equipment unit economics and top-down airport capital expenditure trajectories were triangulated to anchor market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including service type, technology tier, application intensity, and end-user procurement channel. CAGRs were derived from equipment replacement cycle compression under SAE ARP 4852B mandates and electrification penetration curves at major hub airports. Forecast inputs incorporated narrow-body rotation frequency data and cargo handler premium pricing differentials at European pharmaceutical hubs.
The analysis sits within stated boundaries; outcomes outside sustained commercial aviation traffic recovery or lithium-ion supply stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and battery cost trajectories. Revision becomes warranted when export control volatility from China or South Korea crosses thresholds affecting equipment procurement lead times.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
Europe Airport Operations Market
Airport Operations
Airport Ground Handling Market
Airport Operations
Airport Operations Market
Airport Operations
France Airport Operations Market
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
Canada Airport Operations Market
Airport Operations
Global Airside Services Market
Airport Operations
Airport Terminal Operations Market
Airport Operations
Middle East Airport Operations Market
Airport Operations
UK Airport Operations Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Business Jet Ground Handling Services Market
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
Global Air Charter Services Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market