
 Rotary Wing Aircraft Rivets Market | 2026-2036
Rotary Wing Aircraft Rivets Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Wing Aircraft Rivets Market Analysis
Distribution through aerospace tier-one integrators is tilting toward consolidated procurement platforms with long-term material agreements. Howmet Aerospace leverages captive titanium forging capacity to anchor its rivet supply position. LISI Aerospace sustains European rotorcraft programs through specialized blind rivet manufacturing. Precision Castparts Corp. dominates superalloy fastener channels for high-temperature turbine-adjacent applications.
Rotary wing aircraft rivets are permanent mechanical fasteners installed in helicopter airframes, typically manufactured from aluminum alloys, titanium, or corrosion-resistant steels with shear strengths ranging from 30 to 160 ksi depending on specification. These components join primary structural elements including rotor hubs, transmission mounts, and fuselage frames under cyclic loading conditions that demand fatigue-resistant joint design. Blind rivet configurations lead product type demand due to their installation accessibility in enclosed helicopter structures where conventional bucking tools cannot reach. Titanium material grades represent the fastest-expanding segment as rotorcraft manufacturers substitute heavier steel fasteners to meet fuel efficiency targets. Airframe assembly applications capture the largest value share given the extensive riveted joint count in helicopter primary structure, while maintenance repair operations present fragmented but steady demand tied to fleet age demographics.
FAA airworthiness standards under Part 29 govern rotorcraft structural fastener performance, while EASA CS-29 imposes parallel certification requirements for European-manufactured helicopters. The EU Green Deal's embodied carbon tracking extends to aerospace supply chains, pressuring mills to document energy intensity in titanium and aluminum extraction. Military procurement through NAVAIR and Army Aviation specifications adds layer-qualified sourcing mandates that restrict vendor eligibility. Stakeholders must monitor evolving fatigue test protocols and dual-use export control alignment as defense and civil helicopter programs diverge in specification stringency.
Market Dynamics
Defense procurement consolidation around Textron and Sikorsky production hubs is compressing supplier qualification timelines while tightening material traceability mandates under FAA Part 29 fatigue life standards.
Growth Catalysts
- NATO Military Procurement:Member state helicopter modernization programs are expanding fastener specifications across multi-national defense supply chains.
- Titanium Substitution:Rotorcraft manufacturers are replacing steel fasteners with titanium grades to achieve fuel efficiency targets.
- FAA Part 29 Updates:Revised airworthiness directives for rotorcraft fatigue life are mandating enhanced material documentation and testing protocols.
Market Restraints
- Titanium Input Volatility:Sponge and mill product pricing fluctuations constrain margin predictability for fastener manufacturers.
- US Defense Supply Chain Concentration:Heavy reliance on NAVAIR and Army Aviation procurement channels creates single-point vulnerability.
- Blind Rivet Technical Limits:Installation torque consistency in enclosed helicopter structures remains difficult to automate.
Strategic Opportunities
- EU Green Deal Alignment:Embodied carbon tracking requirements favor suppliers with documented low-energy titanium extraction processes.
- Maintenance Repair Operations:Aging helicopter fleets in civilian and military service create fragmented but steady aftermarket demand.
- Superalloy Fastener Expansion:High-temperature turbine-adjacent applications represent an emerging specification tier for specialized products.
Industry Challenges
- Dual-Use Export Control Alignment:Defense and civil helicopter programs are diverging in specification stringency, complicating unified production lines.
- Layer-Qualified Sourcing Mandates:Military procurement through NAVAIR restricts vendor eligibility to pre-approved tiers, lengthening qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Wing Aircraft Rivets Market |
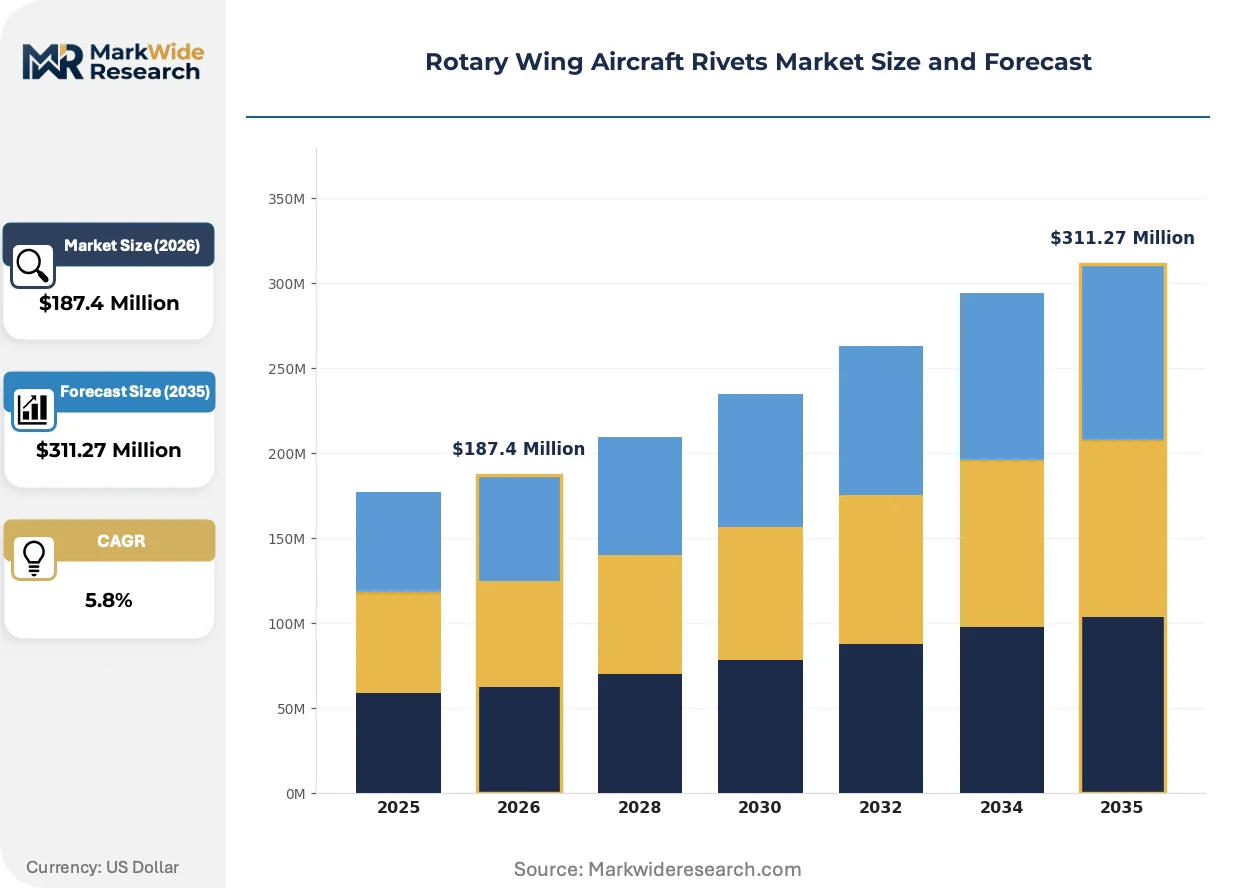
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Rivets, Blind Rivets, Multi-Grip Rivets, Split Rivets Material: Aluminum, Steel, Titanium, Copper Application: Airframe Assembly, Component Repair, Maintenance, Structural Attachment End User: Military, Civil Aviation, Maintenance Repair Operations, Aerospace Manufacturers |
| Companies Covered | Precision Castparts Corp., LISI Aerospace, Arconic Corporation, Howmet Aerospace, TriMas Corporation, Stanley Black & Decker, Cherry Aerospace, Ingersoll Rand, Brown Aviation Tool Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Wing Aircraft Rivets Market Emerging Trajectories
Fastener engineering is converging with advanced materials science and digital traceability systems, reshaping how rotorcraft manufacturers specify, source, and validate structural joining components.
Automated blind rivet installation systems are hybridizing robotics with real-time torque feedback to address accessibility constraints in enclosed helicopter structures. Sikorsky and Bell assembly lines are piloting these configurations for transmission mount applications. This convergence is hybridizing quality assurance workflows, compressing inspection cycles from batch sampling to 100% in-process verification.
EASA CS-29 certification requirements are tightening fastener fatigue test protocols for European-manufactured helicopters. The regulation mandates expanded environmental exposure testing and extended cycle counts. Superalloy fastener suppliers serving turbine-adjacent applications face the steepest compliance cost increases.
Consolidated procurement platforms with long-term material agreements are displacing spot-market purchasing among aerospace tier-one integrators. Howmet Aerospace and LISI Aerospace are anchoring multi-year supply contracts with rotorcraft OEMs. This pattern concentrates most visibly in United States defense supply chains around major production hubs.
Rotary Wing Aircraft Rivets Market Segmentation
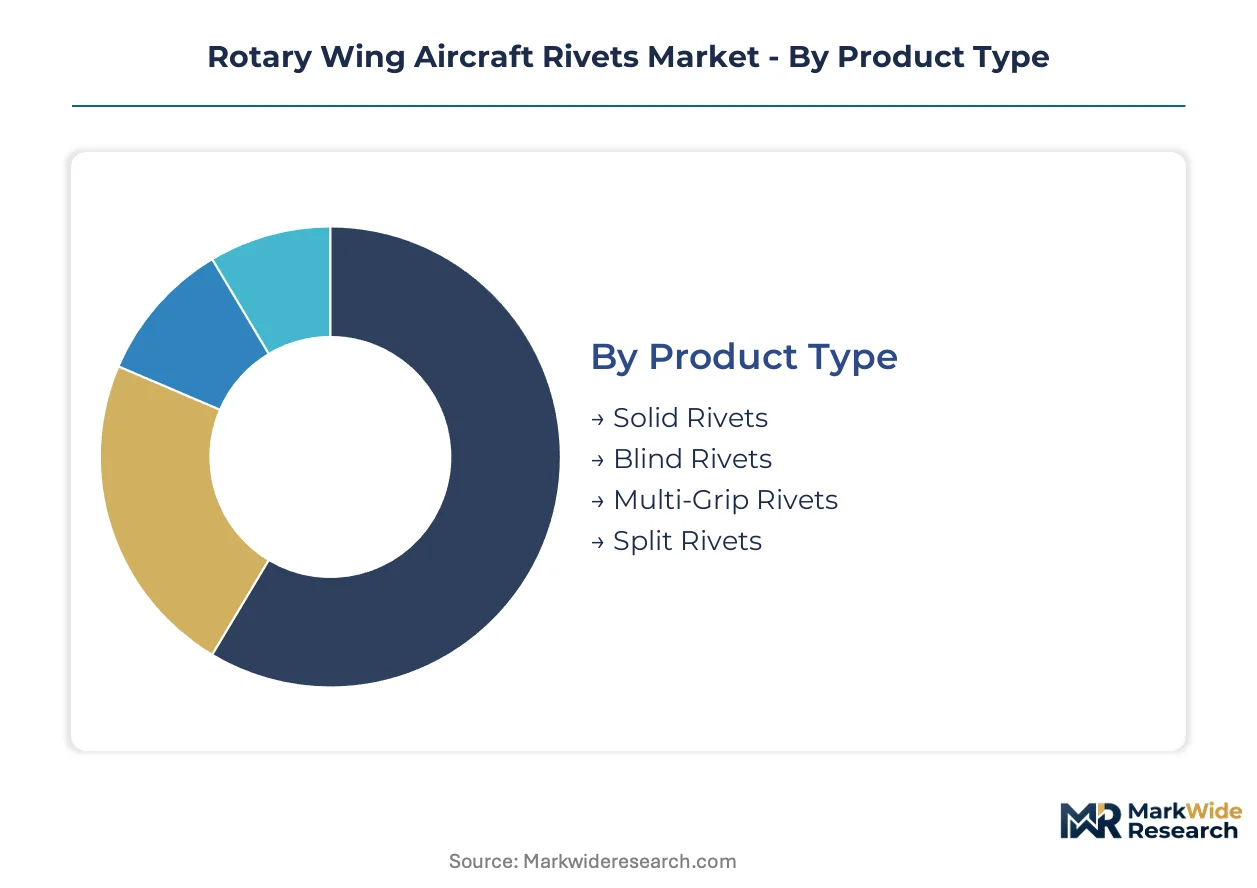
Rotary wing aircraft rivets segment across four critical dimensions that shape procurement patterns and supplier positioning. Product type determines installation accessibility in enclosed helicopter structures. Material selection drives weight reduction imperatives and fatigue performance under cyclic loading.
Product Type:
Installation constraints in helicopter airframes create divergent demand profiles across rivet configurations.
- Blind Rivets:These fasteners install from one side without bucking bar access, essential for transmission mounts and rotor hub enclosures. Demand concentrates around Sikorsky and Bell assembly lines where enclosed structures dominate. FAA Part 29 fatigue life standards mandate torque consistency that automated installation systems now address.
- Solid Rivets:Traditional bucked rivets deliver maximum shear strength for primary fuselage frames and external skin panels. Military helicopter programs through NAVAIR specifications favor these for structural attachment points requiring documented material traceability.
- Multi-Grip Rivets:Adjustable grip range accommodates variable material thickness in component repair scenarios.
- Split Rivets:Bifurcated shank designs serve specialized aerospace applications requiring rapid field installation.
Established volume favors blind rivets; emerging adoption favors multi-grip configurations.
Material:
Weight-performance tradeoffs segment the supply base across metallurgical tiers.
- Titanium:Grades 5 and 6Al-4V deliver strength-to-weight ratios 40% superior to steel alternatives. Rotorcraft manufacturers substitute titanium for fuel efficiency targets at Textron and Airbus Helicopters production hubs. EU Green Deal embodied carbon tracking now pressures mills to document energy intensity in sponge extraction.
- Aluminum:2024-T4 and 7075-T6 alloys dominate legacy airframe assembly with proven corrosion resistance. Civil aviation maintenance operations favor aluminum for cost-sensitive component repair cycles.
- Steel:Corrosion-resistant grades retain position in high-load structural attachment points.
- Copper:Specialized electrical bonding applications in avionics integration.
Procurement gravity centers on titanium; aftermarket stability anchors aluminum.
Application:
Lifecycle position determines specification stringency and documentation requirements.
- Airframe Assembly:Primary structure joining demands riveted joint counts exceeding 50,000 units per helicopter. New production at major OEM facilities drives volume concentration. EASA CS-29 certification tightens fatigue test protocols for European-manufactured platforms.
- Maintenance Repair Operations:Aging military and civilian fleets generate fragmented but steady demand tied to fleet age demographics. Component repair cycles favor blind rivet configurations for field accessibility.
- Structural Attachment:Secondary joining applications in interior fixtures and non-load-bearing assemblies.
- Component Repair:Depot-level maintenance requiring reverse engineering of original fastener specifications.
Production scale favors airframe assembly; margin stability favors maintenance repair operations.
End User:
Procurement channel structure segments demand across defense and commercial hierarchies.
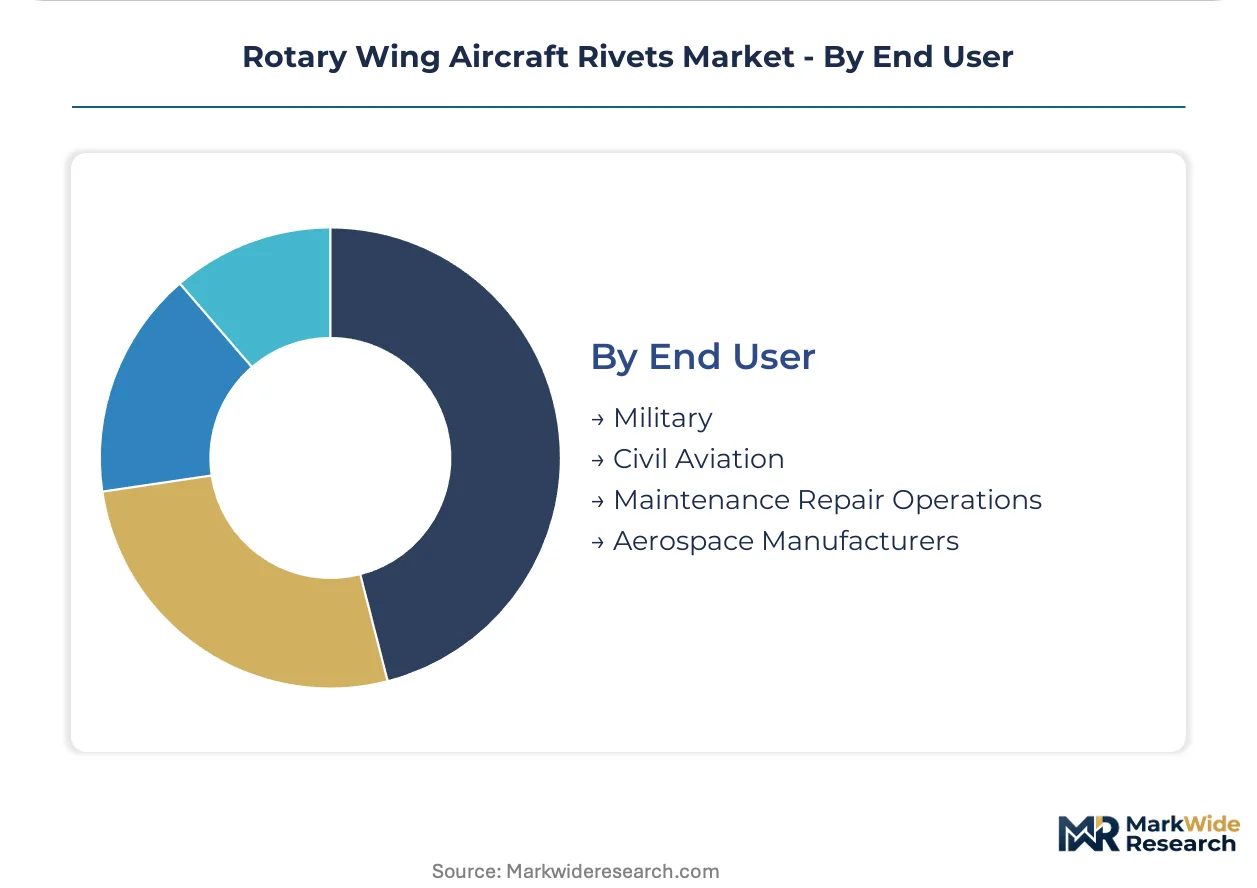
- Military:NAVAIR and Army Aviation specifications impose layer-qualified sourcing mandates restricting vendor eligibility. NATO member state helicopter modernization programs expand fastener specifications across multi-national supply chains. Dual-use export controls complicate unified production lines.
- Aerospace Manufacturers:Tier-one integrators consolidate procurement through long-term material agreements with Howmet Aerospace and LISI Aerospace. United States defense supply chain concentration around Textron and Sikorsky hubs compresses supplier qualification timelines.
- Civil Aviation:Commercial helicopter operators prioritize total cost of ownership in fastener selection.
- Maintenance Repair Operations:Independent service providers face documentation gaps in legacy fleet support.
Contract security favors military; volume predictability favors aerospace manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States defense supply chains while European suppliers absorb compliance cost premiums under EASA CS-29 fatigue protocols. This asymmetry reshapes procurement negotiations across NATO helicopter programs.
United States
NAVAIR and Army Aviation specifications drive layer-qualified sourcing mandates that restrict vendor eligibility to pre-approved tiers. FAA Part 29 airworthiness standards tighten material traceability requirements for rotorcraft fatigue life. Textron and Sikorsky production hubs in Connecticut and Texas compress supplier qualification timelines through consolidated procurement platforms.
France
Airbus Helicopters production in Marignane anchors European demand for titanium-grade fasteners meeting fuel efficiency targets. EASA CS-29 certification requirements impose parallel fatigue test protocols to FAA standards with expanded environmental exposure testing. The EU Green Deal's embodied carbon tracking pressures mills to document energy intensity in titanium sponge extraction.
Germany
NATO helicopter modernization programs expand fastener specifications across multi-national defense supply chains. Bundeswehr procurement through the Federal Office of Bundeswehr Equipment aligns with NAVAIR technical standards for interoperability. Industrial clusters in Bavaria and Baden-Württemberg host specialized blind rivet manufacturing for enclosed rotorcraft structures.
United Kingdom
Ministry of Defence rotorcraft procurement through Defence Equipment & Support channels prioritizes dual-use export control alignment. UK Military Aviation Authority regulations mirror EASA CS-29 fatigue protocols with additional electromagnetic compatibility testing. Aerospace manufacturing concentrates around Broughton and Yeovil assembly facilities serving AgustaWestland and military programs.
Japan
Ministry of Defense helicopter procurement through the Acquisition, Technology and Logistics Agency favors domestic fastener suppliers with documented material pedigree. METI industrial standards govern titanium mill product specifications for aerospace applications. Manufacturing clusters in Aichi Prefecture around Nagoya integrate with Kawasaki Heavy Industries and Subaru Corporation rotorcraft assembly lines.
Rotary Wing Aircraft Rivets Market Vendor Landscape
Integrated titanium processors and specialized fastener manufacturers split the market between captive material control and design-engineering depth. Tier-one aerospace integrators consolidate procurement through multi-year supply agreements that displace spot-market purchasing. Two archetypes dominate: vertically integrated metals processors with forging capacity, and focused fastener specialists with blind-rivet engineering expertise. Competitive moves center on backward integration into titanium sponge sourcing and strategic partnerships with rotorcraft OEMs for qualification co-development.
Within the integrated-processor archetype, Howmet Aerospace and Precision Castparts Corp. occupy positions anchored by captive forging and casting capabilities. LISI Aerospace exemplifies the specialized-engineering tier with European rotorcraft program concentration. These three companies represent the dominant sourcing channels through which tier-one integrators consolidate procurement.
| Leading Market Players |
|---|
| Precision Castparts Corp. |
| LISI Aerospace |
| Arconic Corporation |
| Howmet Aerospace |
| TriMas Corporation |
| Stanley Black & Decker |
| Cherry Aerospace |
| Ingersoll Rand |
| Brown Aviation Tool Company |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific freight corridors from Japanese titanium mills to Connecticut assembly hubs transmit sponge price volatility directly into fastener cost structures, concentrating pricing power among processors with captive forging capacity while fragmenting margin capture for distributors serving spot-market maintenance operations.
Pricing Analysis
The customization-premium spread between NAVAIR-qualified titanium rivets and commercial-grade aluminum alternatives spans three performance tiers driven by fatigue certification grade and material traceability documentation. Three-tier pricing structure across premium, standard, and economy levels separates military-specified products with layer-qualified sourcing from civil aviation alternatives. Cost compression in the aluminum tier is intensifying because of spot-market purchasing consolidation among tier-one integrators. Civil maintenance repair operations exhibit highest price sensitivity, while defense procurement channels prioritize qualification security over unit economics.
Supply Chain Analysis
Tariff exposure between US and Chinese titanium sponge suppliers dominates supply chain risk planning for fastener manufacturers dependent on aerospace-grade mill products. Raw material sourcing draws from Japanese sponge producers, Russian VSMPO-AVISMA mill outputs, and domestic US forging operations. Single-source vulnerability concentrates in specialized superalloy feedstock for turbine-adjacent applications. Distribution runs through aerospace tier-one integrators with multi-year material agreements displacing traditional spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
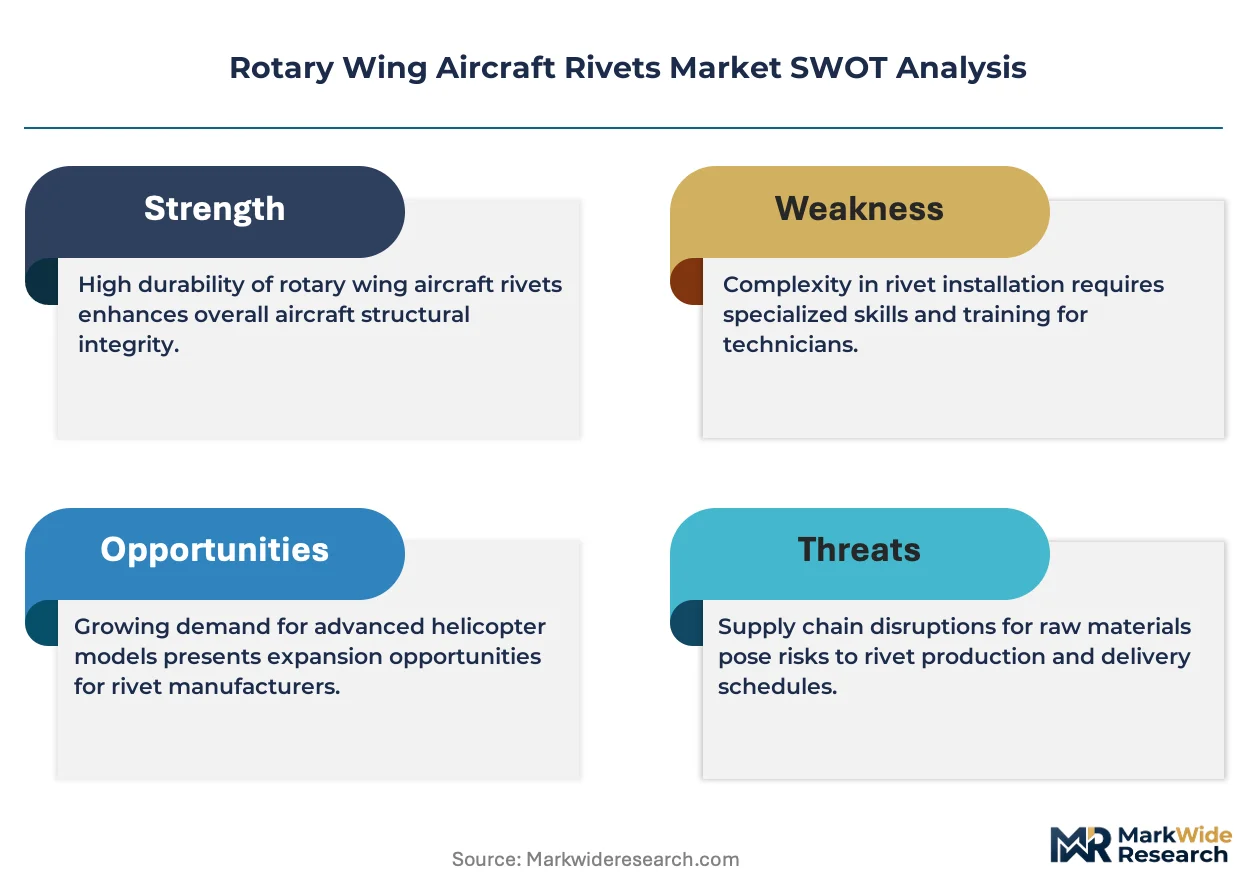
This market functions as a defensive-moat story anchored in regulatory entrenchment: FAA Part 29 and EASA CS-29 certification requirements create decade-long qualification cycles that lock out unapproved competitors regardless of price competitiveness.
For Market Incumbents: Entrench position through backward integration into titanium sponge sourcing and expansion of captive forging capacity in Texas and Connecticut production corridors. Threat from automated installation technology vendors demands co-development partnerships with Sikorsky and Bell assembly lines. Certification investment in expanded environmental exposure testing under revised EASA protocols serves as the priority defensive lever. For New Entrants and Emerging Players: Southeast Asian civil helicopter maintenance hubs present the most penetrable geographic underpenetration for blind rivet specialists lacking defense qualification. Target independent service providers facing documentation gaps in legacy fleet support with digital traceability platforms. Go-to-market execution should emphasize rapid field-installation tooling bundles for enclosed rotorcraft structures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized fastener engineers with blind-rivet automation IP over commodity titanium processors. Long-term viability across the projection horizon rests on qualification co-development relationships with rotorcraft OEMs. The inflection signal to watch is divergence in defense-civil specification stringency that fragments unified production economics.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Titanium Forging Investment | Howmet Aerospace anchors supply security through in-house mill product conversion. |
| Automated Blind Rivet System Deployment | Sikorsky assembly lines pilot robotics with real-time torque feedback for transmission mounts. |
| EASA CS-29 Certification Pre-Positioning | European suppliers absorb compliance premiums ahead of expanded environmental testing mandates. |
| Layer-Qualified Sourcing Alignment | NAVAIR procurement channels restrict vendor eligibility to pre-approved tier-one tiers. |
| EU Green Deal Carbon Documentation | Titanium mills document energy intensity in sponge extraction for Airbus Helicopters supply. |
Methodological Framework
Initial hypotheses were tested against primary input from rotorcraft OEM procurement directors, NAVAIR specification engineers, tier-one integrator supply chain managers, and aftermarket maintenance facility operators and refined through secondary validation against FAA airworthiness directives, EASA CS-29 certification databases, customs trade records for titanium mill products, and SEC filings from aerospace fastener manufacturers. Bottom-up demand modeling across product type, material grade, application lifecycle position, and end-user procurement channel was triangulated with top-down market sizing from production forecasts at Textron, Sikorsky, and Airbus Helicopters facilities.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation modeling spanning blind versus solid rivet configurations, titanium-aluminum-steel material tiers, airframe assembly versus maintenance repair applications, and military versus civil procurement channels. CAGRs were derived from production volume trajectories at major OEM facilities, fleet age demographics driving aftermarket demand, and material substitution rates from steel to titanium grades. Industry-specific forecast inputs incorporated NAVAIR modernization program timelines and EASA fatigue protocol revision schedules.
Practitioners should monitor NATO defense budget allocations, titanium sponge price indices, and rotorcraft OEM automation adoption rates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Global Aerospace Pressure Gauge Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Air Taxi Exterior Component Systems Market
Aircraft and Aerospace Components
South America Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Tube and Duct Assemblies Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Low-Noise Landing Gear Fairing Composite Designs Market
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Europe Passive Electronic Components in Aerospace and Defense Market
Aircraft and Aerospace Components
Solenoid Valves in Aerospace Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market