
 Europe Smart Airport Market | 2026-2036
Europe Smart Airport Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Airport Market Foresight
Biometric authentication hardware is restructuring capital allocation across European airport modernization programs. SITA leverages its established passenger processing platforms to anchor digital identity verification contracts at hub airports. Amadeus IT Group S.A. competes through cloud-native departure control systems that extend operational flexibility to mid-tier carriers. Siemens AG dominates energy-efficient building automation, positioning its smart HVAC and lighting controls as compliance tools for EU Green Deal targets.
A smart airport integrates IoT sensors, AI-driven analytics, biometric identification, and cloud-based operational platforms to automate passenger flow, baggage tracking, security screening, and flight information dissemination. These systems typically operate on sub-second latency requirements for real-time gate allocation and predictive maintenance alerts. AI Systems currently lead technology investment as airports deploy computer vision for queue management and anomaly detection. Passenger Processing captures the largest application spend, though Security Management represents the fastest-expanding segment as EU regulators tighten screening protocols for explosives and unauthorized items.
EMA and EASA standards govern biometric data handling and airside safety equipment certification, while EU Green Deal carbon benchmarks force terminal operators to source renewable-powered smart building systems. REACH compliance adds material traceability costs to IoT device procurement, filtering non-compliant Asian component suppliers from European tender processes. Stakeholders must weigh interoperability commitments against vendor lock-in risks as airports consolidate around single-platform ecosystems.
Market Dynamics
EU Green Deal carbon benchmarks are forcing terminal operators to retrofit legacy infrastructure with renewable-powered building automation systems, creating a structural divergence between compliant and non-compliant airport assets.
Growth Catalysts
- EU Green Deal mandates:Binding emissions reduction targets accelerate airport electrification and smart HVAC deployments across German and French hub terminals.
- Biometric passenger processing:EASA certification frameworks for automated border control gates expand addressable infrastructure spend at Schengen zone airports.
- Airline digitalization:Full-service carriers anchor cloud-native departure control investments, pulling mid-tier operators into platform consolidation.
Market Restraints
- REACH material traceability:Compliance costs filter non-compliant Asian component suppliers from European IoT tender processes, constraining procurement flexibility.
- Legacy system integration debt:Proprietary passenger processing architectures at Frankfurt and Munich airports create vendor lock-in friction for multi-platform environments.
- Sub-second latency requirements:Real-time gate allocation and predictive maintenance alerts demand fiber-optic backbone investments that compress capital deployment timelines.
Strategic Opportunities
- Spanish airport privatization:Aena's terminal modernization program opens smart baggage handling and energy management contracts at Barcelona and Madrid hubs.
- EU AI Act compliance:Risk-based classification of biometric identification systems creates premium positioning for explainable computer vision vendors serving security screening applications.
- Digital twin convergence:Integration of IoT sensor networks with AI-driven analytics enables predictive asset management across airside and landside operations.
Industry Challenges
- Interoperability architecture:Stakeholders must weigh open-platform commitments against single-vendor ecosystem consolidation risks during procurement cycles.
- Specialized talent scarcity:Shortages in aviation cybersecurity and edge computing engineering compress implementation timelines for smart terminal deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Airport Market |
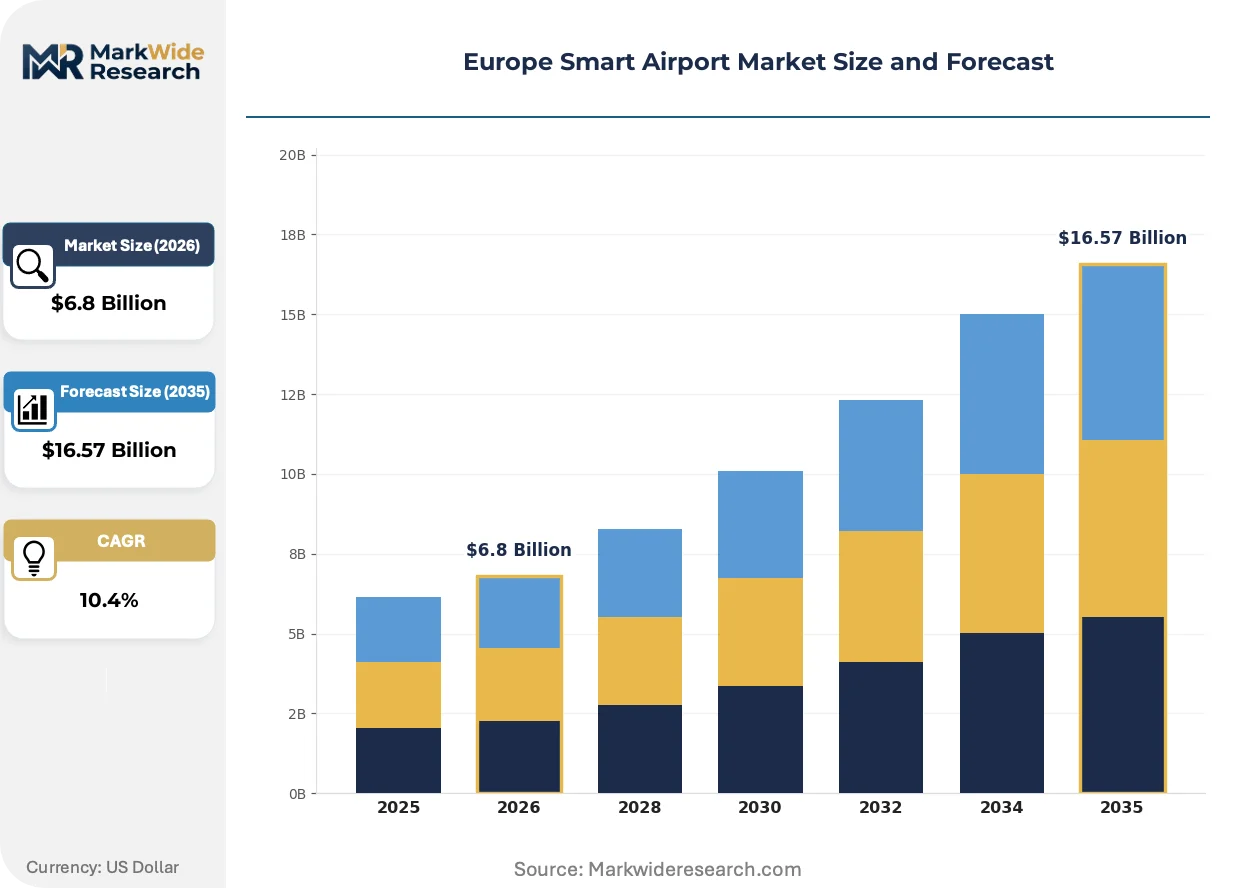
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $16.57 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Devices, AI Systems, Biometrics, Cloud Solutions Application: Passenger Processing, Baggage Handling, Security Management, Flight Information End User: Aeronautical Authorities, Airline Operators, Ground Handlers, Security Personnel Service Type: Consulting Services, Integration Services, Maintenance Services, Support Services |
| Companies Covered | SITA, Amadeus IT Group S.A, Siemens AG, Honeywell International Inc., Thales Group, Indra Sistemas, Vanderlande Industries B.V., Cisco Systems, IBM, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Airport Market Shifts & Advancements
Computer vision systems are restructuring security screening protocols while cloud-native operational platforms compress deployment cycles for mid-tier European carriers.
Electrified ground support equipment is electrifying apron operations as airports replace diesel-powered baggage tractors and pushback tugs with battery-electric alternatives. Amsterdam Schiphol and Paris Charles de Gaulle have mandated fleet conversion timelines aligned with EU Green Deal benchmarks. This transition is electrifying vendor competition for charging infrastructure contracts and thermal management systems.
CSRD sustainability disclosure requirements now mandate granular emissions reporting from airport operators, forcing terminal managers to deploy sub-metered energy monitoring across HVAC and lighting systems. The regulation compresses procurement evaluation criteria toward vendors with certified lifecycle carbon data. German hub airports are responding fastest, embedding building automation specifications with embedded renewable energy sourcing clauses.
Airlines are unbundling traditional IT service contracts in favor of consumption-based pricing for passenger processing platforms. Low-cost carriers at Stansted and Bergamo pioneered this shift, pressuring legacy system integrators to modularize deployment architectures. The model is now penetrating full-service carrier procurement at Scandinavian and Benelux hubs, restructuring vendor revenue recognition patterns.
Europe Smart Airport Market Segmentation
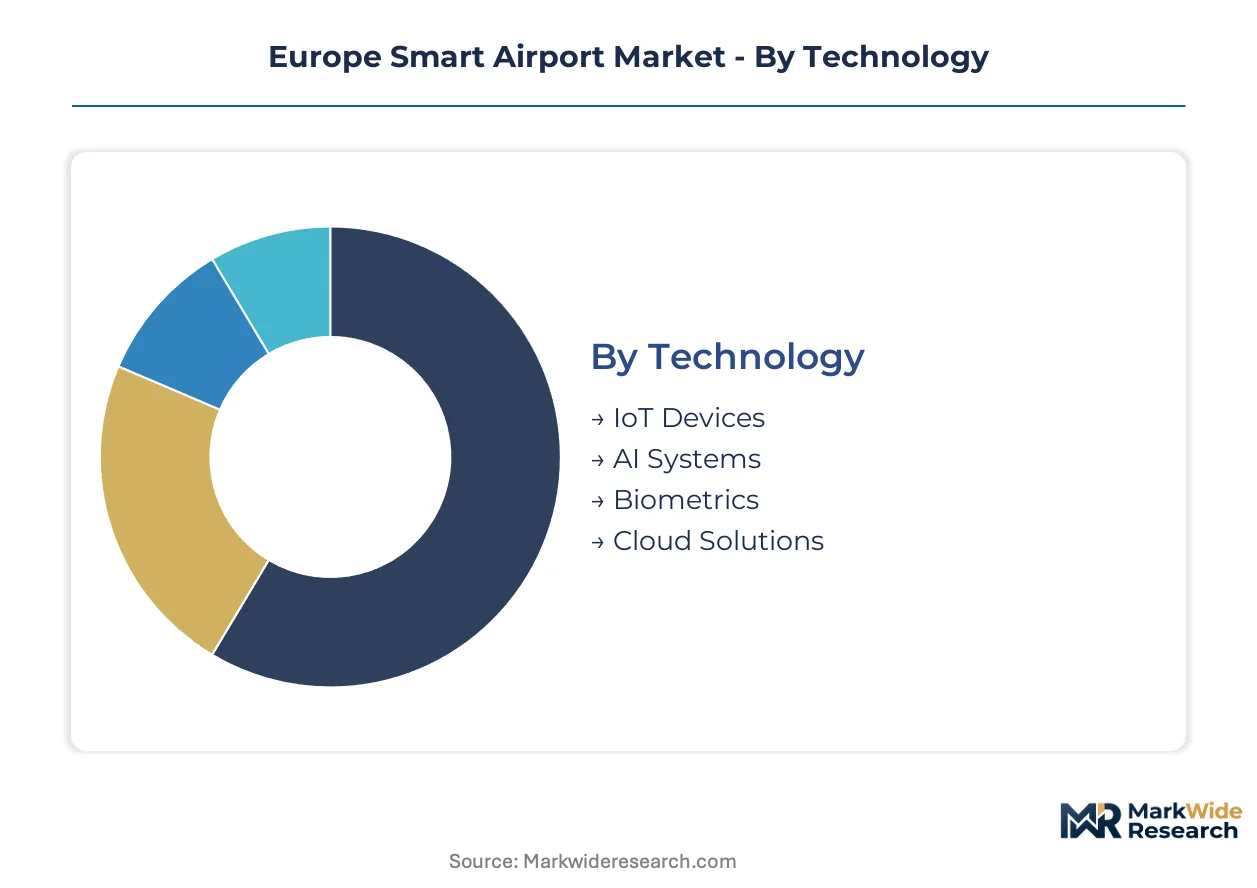
Smart airport procurement in Europe fragments across four intersecting dimensions. Technology selection determines compliance posture under EU AI Act and Green Deal mandates, while application priorities shift with passenger volume recovery patterns at Schengen hubs.
Technology:
Capital allocation decisions hinge on latency requirements and data sovereignty constraints.
- AI Systems:Computer vision platforms process queue analytics and anomaly detection at sub-second thresholds. German and French hub terminals anchor deployment demand as EASA certification frameworks mature for automated decision-making systems.
- Biometrics:Facial recognition and fingerprint authentication hardware automate border control gates. Schengen zone airports concentrate procurement under EMA data handling protocols, with Frankfurt and Munich driving large-scale terminal retrofits.
- IoT Devices:Sensor networks for environmental monitoring and asset tracking operate across airside and landside perimeters.
- Cloud Solutions:Distributed computing architectures host passenger processing and flight information platforms with edge-node redundancy.
Volume sits with AI Systems; growth tilts toward Biometrics.
Application:
Operational pain points at high-traffic terminals reshape spending priorities across functional domains.
- Passenger Processing:Self-service kiosks, automated boarding gates, and digital identity verification streamline check-in to gate flow. Full-service carriers at Amsterdam Schiphol and Paris Charles de Gaulle anchor platform consolidation investments.
- Security Management:Explosive detection systems and unauthorized item screening deploy computer vision for throughput acceleration. EU regulatory tightening on screening protocols drives fastest-expanding segment demand.
- Baggage Handling:RFID tracking and automated sortation systems reduce mishandled luggage rates across hub operations.
- Flight Information:Dynamic display systems and mobile integration platforms synchronize passenger communications during disruption events.
Revenue concentrates in Passenger Processing; expansion accelerates most quickly in Security Management.
End User:
Procurement authority fragmentation creates multi-stakeholder sales cycles with divergent technical specifications.
- Airline Operators:Full-service and low-cost carriers drive cloud-native departure control investments. Scandinavian and Benelux hubs pioneer consumption-based pricing models that restructure vendor contract architectures.
- Aeronautical Authorities:National regulators mandate interoperability standards and certify airside safety equipment under EASA frameworks.
- Ground Handlers:Apron service providers procure electrified ground support equipment and charging infrastructure.
- Security Personnel:Screening staff utilize biometric authentication and threat detection interfaces at passenger checkpoints.
Spending authority clusters with Airline Operators; contract velocity runs highest through Ground Handlers.
Service Type:
Lifecycle service models shift from capital-heavy integration toward recurring revenue maintenance structures.
- Integration Services:System deployment and legacy architecture migration absorb upfront project budgets. Proprietary passenger processing systems at Frankfurt and Munich create vendor lock-in friction for multi-platform environments.
- Maintenance Services:Predictive asset management and sub-metered energy monitoring extend under CSRD disclosure mandates. German hub terminals embed renewable sourcing clauses in building automation service agreements.
- Consulting Services:Digital transformation strategy and compliance roadmap development support procurement decision frameworks.
- Support Services:Help desk and field engineering coverage maintain operational continuity across distributed terminal networks.
Project value pools in Integration Services; margin expansion favors Maintenance Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in German hub terminals where Frankfurt and Munich airports anchor large-scale smart infrastructure deployments. Airline operators across the region are channeling capital toward digital passenger processing and energy-efficient building automation systems. The EU Green Deal's binding emissions benchmarks are forcing terminal operators into accelerated retrofit cycles.
Germany
Frankfurt and Munich airports drive biometric authentication hardware procurement under EASA certification frameworks for automated border control gates. The EU Green Deal mandates renewable-powered smart HVAC and lighting retrofits across hub terminals. Bavaria's Munich Airport anchors Germany's largest smart terminal deployment with integrated IoT sensor networks.
France
Paris Charles de Gaulle mandates fleet conversion timelines for electrified ground support equipment aligned with EU Green Deal carbon benchmarks. The CSRD sustainability disclosure requirements force granular emissions reporting across terminal operations. Île-de-France's airport cluster leads building automation procurement with embedded renewable energy sourcing clauses.
Netherlands
Amsterdam Schiphol pioneers consumption-based pricing models for cloud-native passenger processing platforms among full-service carriers. EMA data handling protocols govern biometric deployment at Schengen zone checkpoints. Randstad's logistics density supports smart baggage handling and automated sortation system investments.
Spain
Aena's terminal modernization program opens smart baggage handling contracts at Barcelona and Madrid hubs under privatization frameworks. The EU AI Act's risk-based classification creates premium positioning for explainable computer vision vendors. Catalonia's Barcelona-El Prat anchors Iberian Peninsula demand for security screening automation.
United Kingdom
Low-cost carriers at Stansted drive unbundling of traditional IT service contracts toward modular deployment architectures. GDPR compliance adds data sovereignty constraints to biometric data handling across passenger processing platforms. London's Heathrow and Gatwick concentrate cloud-native departure control investments among British Airways and competing operators.
Europe Smart Airport Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with system integrators dominating large-scale terminal retrofits while component vendors capture recurring maintenance revenue. The vendor base organizes around three strategic archetypes: aviation IT platforms, building automation conglomerates, and security screening specialists. Consolidation pressures favor single-platform ecosystems despite interoperability risks. M&A activity targets cybersecurity capabilities and edge computing talent, while strategic partnerships secure charging infrastructure contracts for electrified apron operations.
Within the aviation IT platform tier, SITA leverages established passenger processing infrastructure to anchor digital identity verification contracts, while Amadeus IT Group S.A. competes through cloud-native architectures that extend operational flexibility to mid-tier carriers. Siemens AG occupies a position exemplifying the building automation conglomerate archetype, with smart HVAC and lighting controls positioned as compliance tools for EU Green Deal targets. These three entities represent the dominant competitive anchors across European smart airport procurement cycles.
| Leading Market Players |
|---|
| SITA |
| Amadeus IT Group S.A |
| Siemens AG |
| Honeywell International Inc. |
| Thales Group |
| Indra Sistemas |
| Vanderlande Industries B.V. |
| Cisco Systems |
| IBM |
| Others |
Supply & Pricing Matrix
Cloud-native platform migrations at Amsterdam Schiphol and Scandinavian hubs are compressing deployment timelines while simultaneously redistributing vendor margins toward recurring SaaS structures and away from upfront integration fees.
Pricing Analysis
Volume concentrates in project-based integration contracts for legacy system migration, while margin expansion favors consumption-based SaaS tiers for passenger processing platforms. Three-tier pricing structure across premium, standard, and economy levels differentiates by latency guarantees and EASA certification tier. Pricing pressure stems from unbundling of traditional IT service contracts at low-cost carrier hubs. Ground handlers exhibit highest price sensitivity due to thin operating margins, whereas full-service carriers prioritize compliance-grade biometric systems over cost minimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Frankfurt and Munich airports, while systems integrators serve mid-tier terminals through project-based procurement. Component manufacturing concentrates in Germany, the Netherlands, and France for edge computing hardware and sensor assemblies. Supply chains draw from specialized semiconductor foundries for AI accelerators, rare earth processors for IoT magnetics, and certified cable assemblies for fiber-optic backbones. Single-source vulnerability runs through EASA-certified biometric sensor suppliers. Distribution runs through aviation-specialized system integrators with terminal retrofit expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric authentication systems are displacing legacy document-based passenger processing, creating a technology-transition phase where EASA certification timelines determine competitive viability.
For Market Incumbents: Anticipate margin compression from modular SaaS competitors by anchoring long-term maintenance contracts at German hub terminals. Consolidate around single-platform ecosystems to deepen switching costs for Frankfurt and Munich airport operators. Invest in cybersecurity capabilities to defend against specialized talent scarcity threatening implementation timelines. For New Entrants and Emerging Players: Mid-tier Spanish airports under Aena's privatization program represent the most penetrable buyer archetype for cloud-native baggage handling and energy management contracts. Target explainable computer vision vendors serving EU AI Act compliance requirements at Barcelona-El Prat. Pursue strategic partnerships with electrified ground support equipment manufacturers to secure charging infrastructure contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by building automation conglomerates seeking aviation vertical integration. Long-term viability hinges on renewable-powered smart HVAC positioning under tightening EU Green Deal benchmarks. Monitor CSRD disclosure mandate adoption rates as the inflection indicator for sub-metered energy monitoring demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cloud-native departure control systems extend operational flexibility to mid-tier carriers at Benelux hubs. |
| Acquisition of Specialist Firm | Cybersecurity capabilities and edge computing talent compress implementation timelines for smart terminal deployments. |
| Strategic Partnership | Charging infrastructure contracts for electrified apron operations anchor vendor relationships at Amsterdam Schiphol. |
| Geographic Expansion | Spanish airport privatization opens smart baggage handling contracts at Barcelona and Madrid hubs. |
| Product Launch | Explainable computer vision platforms capture premium positioning under EU AI Act risk-based classification frameworks. |
Research Methodology
EU regulatory filings, EASA certification databases, and airport operator procurement disclosures formed the secondary backbone, supplemented by primary interviews with terminal operations directors, aviation cybersecurity engineers, smart building automation procurement leads, and ground handling fleet managers. Bottom-up triangulation across technology deployment records and top-down validation against EU Green Deal investment tracking enabled cross-verification of infrastructure spend patterns.
Historical trendline analysis of biometric hardware procurement and energy retrofit cycles informed the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, application function, end-user authority, and service delivery model, with additional granularity on EASA certification tier and EU AI Act risk classification. CAGRs were derived from compound trajectory analysis of disclosed contract values and announced terminal modernization budgets, incorporating CSRD disclosure mandate adoption curves and electrified ground support equipment conversion timelines as industry-specific forecast inputs.
Revisions become necessary when EU Green Deal enforcement intensity shifts, EASA certification frameworks for automated decision-making systems are delayed, or REACH material traceability requirements expand to additional component categories. Forecasts reflect documented assumptions regarding passenger volume recovery patterns and airline digitalization capex commitments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Smart Airport 2.0 Market
Airport Technologies
Asia-Pacific Smart Airport Market
Airport Technologies
Airport Airside Service Market
Airport Technologies
Helideck Monitoring System Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Smart Airport Market
Airport Technologies
Advanced Airport Technologies Market
Airport Technologies
North America Smart Airport Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Global Remote Towers Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Airport Baggage Tracking Systems Market