
 Middle East Airport Operations Market | 2026-2036
Middle East Airport Operations Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Airport Operations Market Analytics
Project finance tied to long-term airport concession agreements is rewriting competitive dynamics across Middle East aviation infrastructure. Dubai Airports Company leverages its hub position to control passenger flow and retail yield per traveler. King Abdulaziz Airport Company anchors Saudi Arabia's west coast gateway with specialized Hajj and Umrah terminal operations. Abu Dhabi Airports Company differentiates through premium lounge ecosystems and transfer efficiency metrics.
Middle East airport operations encompass the coordinated management of aircraft turnaround, passenger processing, baggage flow, and airside safety systems requiring ICAO-compliant runway lighting, Category III instrument landing capabilities, and real-time baggage tracking infrastructure. The primary purpose is maximizing aircraft utilization rates and passenger throughput while maintaining regulatory safety margins under extreme thermal conditions. Ground handling services occupy the largest revenue pool given labor intensity and equipment depreciation cycles, while automation solutions represent the fastest-expanding technology category as airports deploy autonomous baggage tractors and biometric boarding gates. Security systems maintain mature margins driven by mandatory regulatory refresh cycles rather than discretionary capital.
The General Authority of Civil Aviation in Saudi Arabia and the UAE's General Civil Aviation Authority enforce ICAO Annex 14 standards alongside national safety management system mandates that dictate equipment certification and staffing ratios. GCAA's drone integration rules and GACA's privatization framework are reshaping procurement timelines and operator qualification requirements. Stakeholders must monitor how biometric data governance under national cybersecurity authorities intersects with passenger processing investments.
Market Dynamics
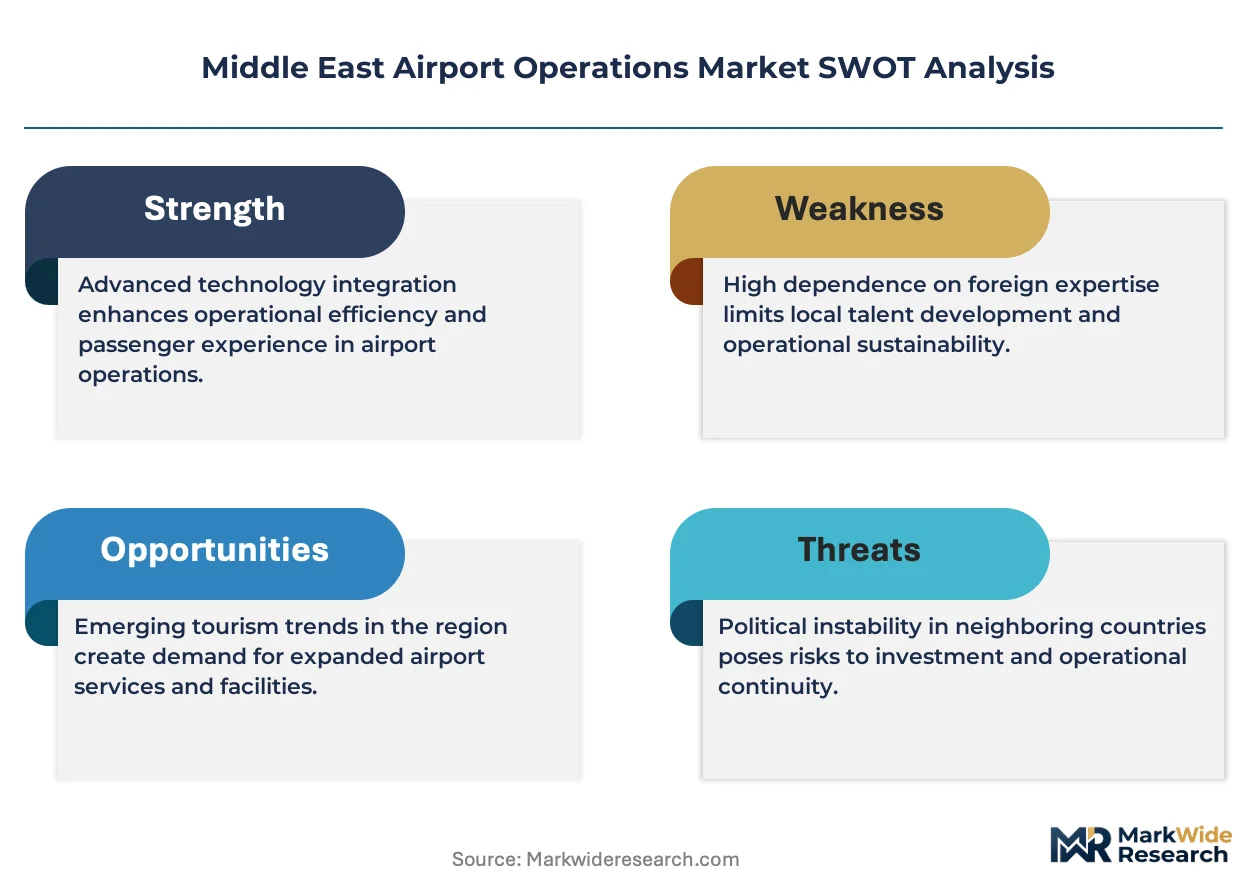
ICAO carbon offsetting mandates are forcing Gulf airports to replace diesel ground support equipment with electric alternatives, triggering wholesale procurement cycles across Saudi Arabia and the UAE while privatization frameworks accelerate operator consolidation.
Growth Catalysts
- Vision 2030 Infrastructure Buildout:Saudi Arabia's General Authority of Civil Aviation is privatizing airport management and constructing new terminals in Riyadh and Jeddah to absorb projected Hajj and Umrah volume expansion.
- Electric GSE Mandates:Carbon offsetting rules under ICAO's CORSIA framework are compelling ground handlers to retire diesel baggage tractors and deploy battery-powered alternatives with dedicated charging infrastructure.
- Biometric Passenger Processing:Touchless boarding gates and facial recognition checkpoints are compressing aircraft turnaround times while reducing terminal labor requirements during peak thermal periods.
Market Restraints
- Lithium Supply Concentration:Battery cell production for electric ground support equipment concentrates in East Asian manufacturing hubs, exposing Gulf operators to shipping cost volatility and extended lead times.
- Extreme Thermal Degradation:Ambient temperatures exceeding 50°C in summer months accelerate battery degradation and cooling system failures, compressing equipment replacement cycles.
- Skilled Technician Scarcity:Local labor pools lack certified avionics and electric drivetrain specialists, forcing operators to import maintenance personnel at premium compensation rates.
Strategic Opportunities
- Secondary Saudi Gateways:Taif and Al-Qassim airports remain underpenetrated for international scheduled service, creating first-mover positioning for low-cost carriers and their ground handling partners.
- Sustainable Aviation Fuel Infrastructure:GACA's planned SAF blending mandates at King Abdulaziz and King Khalid International will require dedicated storage, hydrant, and quality testing installations.
- Drone Integration Corridors:UAE GCAA regulatory frameworks for beyond-visual-line-of-sight cargo drones are opening airspace for automated last-mile delivery between airport perimeters and urban distribution centers.
Industry Challenges
- Legacy System Interoperability:Biometric boarding gates must interface with decades-old departure control systems, requiring expensive middleware development and extended commissioning timelines.
- Certification Bottlenecks:ICAO-compliant Category III instrument landing system upgrades face protracted approval queues from national aviation authorities, delaying operational deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Airport Operations Market |
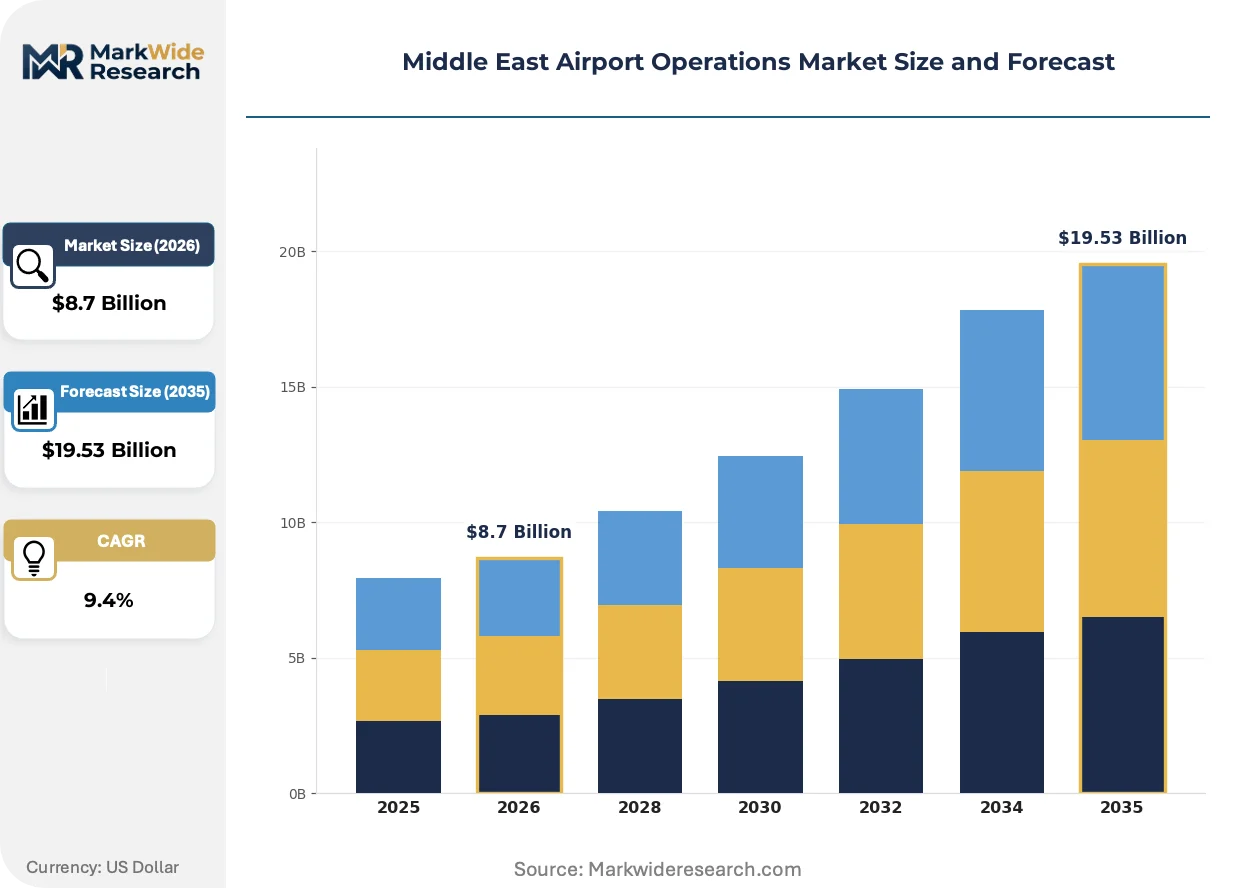
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Handling, Air Traffic Control, Security Systems, Baggage Management Service Type: Passenger Services, Aircraft Maintenance, Cargo Services, Technical Support Technology: Automation Solutions, Intelligent Transportation, Surveillance Systems, Communication Networks End User: Airlines, Airport Operators, Service Providers, Government Authorities |
| Companies Covered | Abu Dhabi Airports Company, Sharjah Airport Authority, Dubai Airports Company, King Khalid International Airport, King Abdulaziz Airport Company, Jeddah Airports Company, Riyadh Airports Company, Queen Alia International Airport, Hamad International Airport, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Airport Operations Market Evolving Landscape
Autonomous ground vehicles and predictive maintenance algorithms are compressing aircraft turnaround windows while biometric identity systems eliminate physical document checks. Thermal management innovations and SAF infrastructure investments are reshaping capital allocation priorities across Gulf airport operators.
Autonomous baggage tractors equipped with lidar navigation and collision avoidance systems are rendering obsolete manually operated diesel tugs in apron operations. Dubai Airports and Abu Dhabi Airports Company are piloting these units during overnight curfew periods to validate reliability metrics. The technology is rendering obsolete traditional ground handling labor models while forcing renegotiation of union staffing agreements.
GACA's privatization framework and concession restructuring rules are transferring operational control from state entities to international airport operators with performance-linked revenue mechanisms. Saudi terminals must now meet ICAO Annex 14 safety benchmarks and passenger throughput guarantees to retain management contracts. King Abdulaziz Airport Company and Riyadh Airports Company are responding by importing terminal management expertise from European hub operators.
Airlines operating from Gulf hubs are unbundling ground handling contracts from fuel supply agreements, creating discrete procurement categories for specialized handlers. Low-cost carriers at Sharjah International and Kuwait International are driving this fragmentation by soliciting standalone bids for passenger boarding bridge operations. Saudi Arabia's domestic route expansion under Vision 2030 targets is accelerating this pattern as new entrant carriers seek operational flexibility without legacy bundled service commitments.
Middle East Airport Operations Market Segmentation
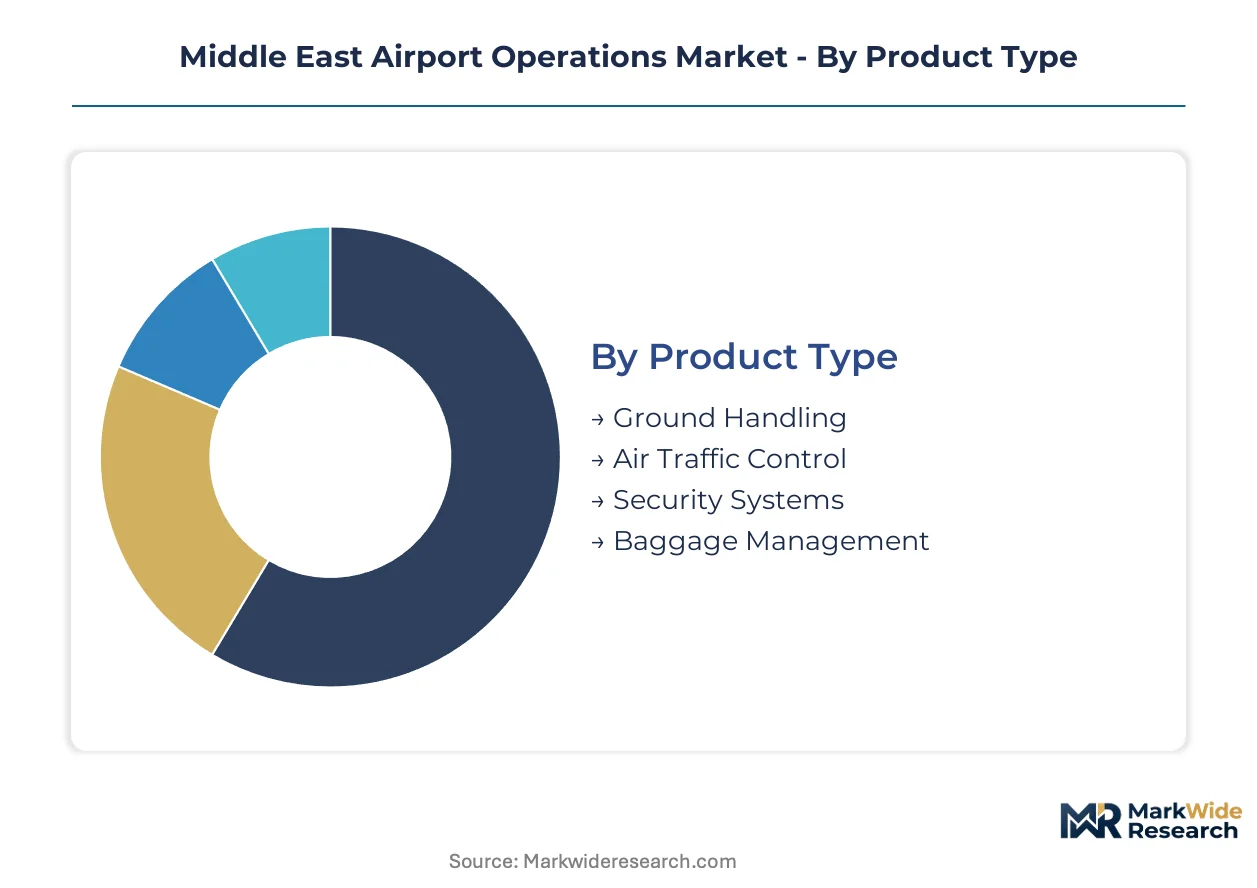
Segmentation in Middle East airport operations reveals how capital allocation priorities diverge across service maturity levels and technology adoption curves. Procurement patterns vary sharply between established ground handling contracts and emerging automation platforms.
Product Type:
Mature operational categories dominate current revenue pools while emerging equipment classes reshape replacement cycles.
- Ground Handling:Aircraft turnaround services including pushback, catering, and cleaning operations require intensive labor deployment and equipment depreciation reserves. Demand concentrates in Saudi Arabia's privatizing terminals where GACA mandates performance-linked concession terms for baggage tractor fleets and passenger boarding bridge operations.
- Air Traffic Control:Radar surveillance, approach sequencing, and tower coordination systems demand ICAO-compliant Category III instrument landing capabilities. The UAE's GCAA and Saudi GACA drive procurement through mandatory safety management system upgrades at Dubai International and King Abdulaziz International.
- Security Systems:Hold baggage screening and access control infrastructure.
- Baggage Management:Automated sorting and real-time tracking installations.
Ground Handling retains volume leadership; Baggage Management holds the steepest expansion curve.
Service Type:
Cost tier stratification separates labor-intensive passenger-facing services from capital-heavy technical functions.
- Passenger Services:Check-in processing, lounge management, and gate coordination functions absorb terminal staffing budgets. Low-cost carriers at Sharjah International and Kuwait International are unbundling these contracts from fuel supply agreements to secure operational flexibility.
- Aircraft Maintenance:Line maintenance, engine inspections, and component repair operations require certified technician pools. Saudi Arabia's domestic route expansion under Vision 2030 targets is concentrating demand at Riyadh's new terminal complexes.
- Cargo Services:Perishable handling and express freight consolidation.
- Technical Support:IT infrastructure and systems integration services.
Passenger Services commands the largest labor allocation; Aircraft Maintenance exhibits the sharpest certification premium escalation.
Technology:
Application focus determines whether procurement prioritizes apron automation or terminal passenger flow optimization.
- Automation Solutions:Autonomous baggage tractors with lidar navigation and biometric boarding gates eliminate manual document checks. Dubai Airports and Abu Dhabi Airports Company pilot these units during overnight curfews to validate reliability before union staffing renegotiations.
- Intelligent Transportation:Automated people movers and apron vehicle routing systems.
- Surveillance Systems:Perimeter intrusion detection and terminal video analytics.
- Communication Networks:Terrestrial and satellite datalink infrastructure for aircraft-ground coordination.
Automation Solutions attracts the steepest capital commitment; Communication Networks maintains the most stable replacement cadence.
End User:
Customer type dictates contract structure, from long-term concession agreements to discrete procurement tenders.
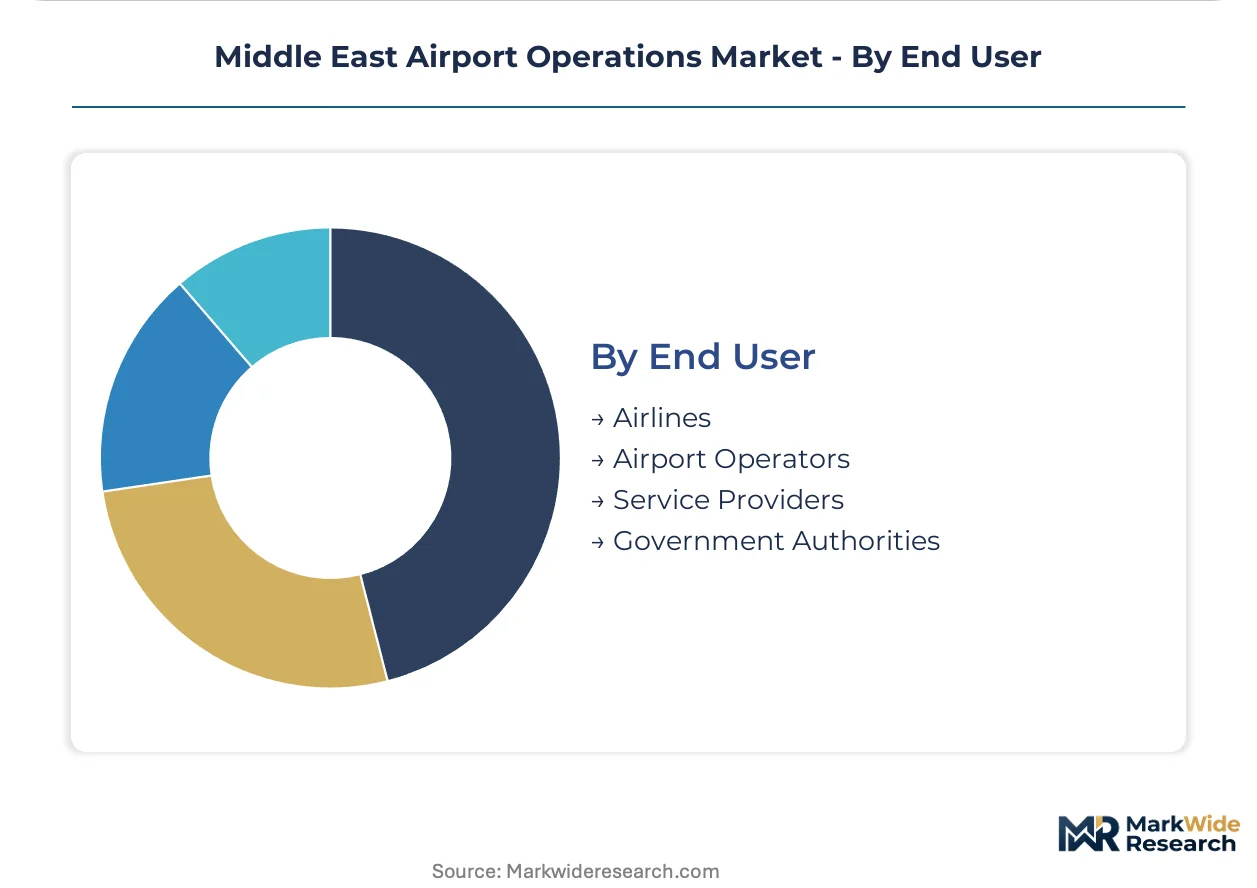
- Airlines:Full-service and low-cost carriers negotiate ground handling and passenger service contracts separately from fuel supply. New entrant carriers in Saudi Arabia's expanding domestic market seek unbundled service arrangements without legacy bundled commitments.
- Airport Operators:Dubai Airports Company, Abu Dhabi Airports Company, and Saudi privatized terminal managers control passenger flow and retail yield optimization.
- Service Providers:Third-party ground handlers and maintenance contractors.
- Government Authorities:GACA and GCAA regulatory oversight and safety enforcement functions.
Airport Operators controls infrastructure access; Airlines drives the fastest contract unbundling momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai commands premium ground handling rates that Jeddah and Riyadh cannot yet match, though Saudi Arabia's terminal privatization is compressing this pricing-power gap. The UAE's established hub infrastructure maintains yield advantages while Saudi Vision 2030 buildouts accelerate competitive convergence.
Saudi Arabia
Riyadh Airports Company and King Abdulaziz Airport Company drive demand through GACA-mandated privatization of terminal operations under performance-linked concession terms. The General Authority of Civil Aviation enforces ICAO Annex 14 safety benchmarks and passenger throughput guarantees that reshape procurement timelines for baggage tractor fleets. Jeddah's west coast gateway anchors specialized Hajj and Umrah terminal capacity expansion.
United Arab Emirates
Dubai Airports Company and Abu Dhabi Airports Company control passenger flow optimization and retail yield per traveler across hub-and-spoke network structures. The General Civil Aviation Authority enforces drone integration rules and Category III instrument landing system mandates that dictate equipment certification requirements. Dubai International's apron automation pilots during overnight curfews validate autonomous baggage tractor reliability metrics.
Qatar
Hamad International Airport concentrates transfer efficiency investments and premium lounge ecosystem differentiation to capture connecting traffic flows. The Qatar Civil Aviation Authority aligns with ICAO carbon offsetting frameworks while accelerating electric ground support equipment procurement cycles. Doha's single-terminal hub design enables compressed aircraft turnaround windows through integrated passenger processing platforms.
Jordan
Queen Alia International Airport serves as a secondary gateway for religious tourism and regional cargo consolidation amid limited domestic carrier presence. The Civil Aviation Regulatory Commission of Jordan implements ICAO safety management system standards that govern ground handler qualification requirements. Amman's airport zone maintains perimeter security and access control infrastructure refresh cycles driven by mandatory regulatory compliance.
Kuwait
Kuwait International Airport experiences contract unbundling pressure as low-cost carriers solicit standalone bids for passenger boarding bridge operations separate from fuel supply agreements. The Directorate General of Civil Aviation oversees national safety protocols while secondary terminal expansions proceed under constrained fiscal frameworks. The airport's ground handling market fragments between incumbent bundled service providers and new entrant specialized operators.
Middle East Airport Operations Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The market structure concentrates around state-affiliated airport operators managing concession-based revenue mechanisms, with limited pure-play ground handling independents. Three archetypes dominate: hub-scale terminal managers with retail yield optimization capabilities, specialized Hajj/Umrah operators with seasonal surge capacity, and technology-integrated handlers deploying biometric passenger processing. Competitive moves center on concession restructuring for performance-linked contracts and procurement of electric ground support equipment fleets.
Among state-affiliated terminal operators, Dubai Airports Company, Abu Dhabi Airports Company, and King Abdulaziz Airport Company exemplify the hub-manager archetype with integrated passenger flow control. These entities occupy positions where privatization frameworks transfer operational control from government authorities to performance-accountable management structures. Riyadh Airports Company and Jeddah Airports Company represent the Saudi expansion vector, anchoring new capacity buildouts under GACA concession terms that mandate ICAO-compliant safety benchmarks.
| Leading Market Players |
|---|
| Abu Dhabi Airports Company |
| Sharjah Airport Authority |
| Dubai Airports Company |
| King Khalid International Airport |
| King Abdulaziz Airport Company |
| Jeddah Airports Company |
| Riyadh Airports Company |
| Queen Alia International Airport |
| Hamad International Airport |
| Others |
Value Network & Pricing Analysis
East Asian battery cell manufacturing concentration for electric ground support equipment feeds directly into margin compression for Gulf airport operators, as procurement teams face extended lead times and shipping cost volatility that erode equipment lifecycle economics.
Pricing Analysis
Configured-to-order pricing for autonomous baggage tractors with lidar navigation and thermal management systems commands a 40-60% premium over standard diesel-equivalent units. Pricing stratifies across premium, standard, and economy tiers based on equipment certification grade and after-sales service bundling. Pricing pressure stems from ICAO carbon offsetting mandates accelerating fleet replacement cycles before depreciation reserves mature. Low-cost carriers at Sharjah International and Kuwait International exhibit highest price sensitivity, while hub operators like Dubai Airports Company absorb premiums for turnaround efficiency gains.
Supply Chain Analysis
Export-control restrictions on lidar sensors and advanced battery management systems from US and EU jurisdictions limit flows to Middle East ground handling equipment integrators. Component sourcing concentrates in China for battery cells, South Korea for power electronics, and Germany for precision hydraulics. Supply chain risk hinges on single-source vulnerability for lithium-ion cell supply, with distribution running through Dubai-based logistics hubs serving Saudi and UAE airport operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric passenger processing platforms are reshaping competitive positioning as interoperability standards force ecosystem consolidation around integrated departure control systems.
For Market Incumbents: Entrench concession control through performance-linked contract renegotiations that embed ICAO Annex 14 compliance benchmarks as non-negotiable terms. Acquire certified electric drivetrain maintenance capabilities in-house to offset skilled technician scarcity premiums. Defend against low-cost carrier unbundling by bundling ground handling with exclusive apron automation pilots. For New Entrants and Emerging Players: Pursue specialized Hajj and Umrah seasonal surge capacity contracts at Taif and Al-Qassim airports where incumbent presence remains thin. Target sustainable aviation fuel infrastructure installations as GACA mandates approach. Lead with drone integration corridor expertise under UAE GCAA beyond-visual-line-of-sight frameworks. For Investors and Strategic Acquirers: Capital is best deployed toward technology-integrated ground handlers with biometric boarding gate deployments and autonomous vehicle pilot credentials. Long-term viability rests on concession restructuring exposure across Saudi Arabia's privatizing terminals. Watch for GACA SAF blending mandate announcements as inflection triggers for storage and hydrant infrastructure capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Electric GSE Fleet Conversion | ICAO CORSIA compliance mandates accelerate diesel equipment retirement across Saudi and UAE hubs. |
| Biometric Boarding Gate Deployment | Dubai Airports and Abu Dhabi Airports Company compress turnaround times while reducing terminal labor. |
| SAF Infrastructure Buildout | GACA blending mandates at King Abdulaziz and King Khalid International require dedicated storage installations. |
| Drone Integration Corridor Development | UAE GCAA beyond-visual-line-of-sight rules open automated last-mile delivery between airport perimeters. |
| Concession Restructuring Negotiation | Saudi privatization transfers operational control to performance-accountable managers with throughput guarantees. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with airport operations directors, ground handling procurement managers, GACA concession officers, and electric GSE maintenance technicians; and secondary validation through ICAO safety management system filings, GACA privatization framework documents, GCAA drone integration regulations, and customs records for ground support equipment imports. Bottom-up equipment procurement forecasts triangulated against top-down airport capacity expansion announcements.
Forecast inputs span the projection horizon across service type segmentation, technology adoption curves, and end-user contract structures. CAGRs derive from equipment replacement cycle modeling and concession term dynamics. Electric ground support equipment penetration rates and biometric passenger processing installation timelines serve as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in oil-export revenues and sovereign infrastructure spending would shift the trajectory. Forecasts reflect assumptions around ICAO mandate enforcement timelines and GACA privatization adherence. Material shifts in lithium supply chain concentration or battery thermal degradation mitigation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
France Airport Operations Market
Airport Operations
Global Air Charter Services Market
Airport Operations
Canada Airport Operations Market
Airport Operations
Global Airside Services Market
Airport Operations
Airport Terminal Operations Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
Business Jet Ground Handling Services Market
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market
Airport Operations
Airport Ground Handling Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
South Korea Airport Operations Market
Airport Operations
Aircraft Ground Handling System Market
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
Airport Operations Market
Airport Operations
Europe Airport Operations Market